Team No Comments

Quilter Investors – Diversify and Conquer

Please see article below from Quilter Investors received yesterday afternoon – 15/04/2021

The need to diversify

Quilter Investors chief investment officer, Bambos Hambi, explains why private investors need to diversify across different asset classes and different geographies.

Over the last 30 years or more, while the ‘average’ retail investor (if there is such a thing) has undoubtedly become more investment savvy, investment markets and the fund strategies that draw upon them have taken a quantum leap in both size and sophistication. Consequently, the chasm between the two has probably never been greater.

Even today, too few private investors really understand the need to diversify their savings across different asset classes and geographies and how this impacts the risks to which their financial futures are subject.

Given the constant media barrage, it’s hardly surprising that investor ‘champions’ such as the ‘FAANG’ stocks – namely Facebook, Apple, Amazon, Netflix and Google (Alphabet) – arise. A previous investor acronym that once attracted similar attention is the ‘BRICS’, which stood for Brazil, Russia, India, China and South Africa.

While both helped attract huge levels of new investment, anyone who plumped solely for these investment areas will have experienced a bumpy ride. By contrast, the essence of diversifying across a range of different risk categories is that it smooths the investment journey, enabling us to make more reliable plans for our financial futures.
Spinning the wheel

Many people still think of diversification in terms of eggs and baskets, but it’s a flawed analogy. In reality, the risk of concentrating your savings into a few leading tech stocks, or a group of ‘hot’ emerging markets, is much more akin to walking into a casino, putting your ‘egg’ on one number and spinning the roulette wheel.

A better analogy is to think of diversification in terms of cooking. Imagine an array of different pots bubbling away. While each one will come to the boil at different points, delivering the desired outcome, each could also boil over, or just go cold, if left unattended.

This is where a multi-asset portfolio manager comes into play. It’s their job to stir each ‘pot’ and see that it receives the right amount of heat, at the right time, to achieve the desired end result.

Over the last 30 years or more, investment markets and fund strategies have taken a quantum leap in both size and sophistication.

Active not reactive

Having a fully resourced portfolio manager at the helm is important because, as the table (see the pdf at the bottom of this page) shows, different asset classes and regions respond to economic events in different ways. Accounting for this requires constant monitoring, analysis and position refinements at the portfolio level.

Take UK property as an example. In terms of investment returns for the 11 asset classes listed in the table, UK property had yo-yoed from last place in 2016, to first place in 2018 and back to last again by 2019.

Meanwhile, UK equities, which have never placed higher than fifth in the last 10 calendar years, proved to be the worst performing asset class of 2020, thanks to the onset of the pandemic and the last thrashes of the Brexit farrago.

By contrast, the pandemic, and the speed with which China was able to deal with its fallout, helped to propel Chinese equities into first place in 2020. They were also the best performing asset class in 2017 (but the worst in 2018).

Creating solutions

Thanks to our scale and reach as an investment business, we begin with a universe of many thousands of different strategies and fund structures and whittle it down to find the ‘best of breed’ in each space.

This means our portfolio managers and investment teams spend the majority of their time researching, analysing and modelling to find those managers who can demonstrate the most consistent returns for the level of risk with which we’ve entrusted them.

As dedicated portfolio managers, we have two key advantages over investors who decide to manage their own investments. The first is the time, expertise and expense required to actively monitor global markets, to decide which asset classes are best suited to the conditions and to identify those managers that consistently do the best job in each asset class.

The other great advantage we have is access. Unlike private investors, we have access to a huge swathe of investment managers and strategies from around the world covering every major equity and bond market. Often we invite proven managers to create dedicated funds (called mandates) that are run especially for us.

We also have access to a whole universe of fund strategies that either aren’t available to UK investors, are too sophisticated for private investors or which require minimum levels of investment that put them far beyond the reach of ordinary investors. This is especially so in the case of so-called ‘alternative investments’.
Alternative thinking…

The term ‘alternative investments’ covers an enormous global investment industry that’s all but closed to private investors. Alternative investment funds cover the widest range of asset classes from commodities like gold and oil to other ‘real assets’ such as commercial property, infrastructure and renewable energy.

They also include hedge funds that invest in all manner of asset classes but which, thanks to the complex derivative strategies they employ, can pursue all manner of different instruments. Many of these focus on generating returns that have a low ‘correlation’ to those of equity or bond markets, others focus on delivering consistent ‘absolute returns’ whatever the investment environment.

Having access to such diversity allows us to reduce the correlation of our holdings both with one another and with major global equity and bond markets. This means that if, say, a global pandemic broke out and sent equity markets into steep decline, as was the case in 2020, other holdings, not correlated to equity markets, could take up the strain.

Unlike private investors, we have access to a huge swathe of investment managers and strategies from around the world covering every major equity and bond market.

Diverse times

Recent months have provided ample illustration of the need to properly diversify portfolios.

The unprecedented events of 2020 ended with one of the greatest relief rallies on record, thanks to news of three viable coronavirus vaccines. Within this, ‘value stocks’ that had been in the shadow of ‘growth stocks’ for almost a decade began to outperform as investors rotated into those areas previously left behind (see the inset box).

Only weeks later, the headlines were dominated by news of rocketing government bond yields and major losses for bond investors as markets began to price-in ‘reflation’ – the period of rising prices and growth that tends to follow a period of ‘deflation’ (falling prices and growth), like the one caused by lockdown.

On the whole, reflation is a welcome sign for long-term investors like us, as it shows that an economic recovery is well underway and that improving economic growth lies ahead. However, bond markets naturally recoil at the prospect of the higher inflation and interest rates that might accompany it.

Not only did lower-risk bond investors feel this in the pocket, but investors at the other end of the risk spectrum, namely, higherrisk ‘growth investors’ in equities, also suffered. The so-called FAANGs and other leading tech companies were among the early casualties.

This is because growth stocks tend to struggle with the risk of higher interest rates and inflation; as a high level of their predicted profits lies in the future, the prospect of higher interest rates reduces their value today.

While all this was going on, smaller companies began to outperform as they tend to enjoy reflation.

These issues (and too many more to mention) have already exposed investors with too little diversification to significant volatility and potential losses so far in 2021. .

This underlines the ‘smoothing’ benefits of a well-diversified, global portfolio. When changes in the economic cycle or the broader tapestry of society take hold, the diversified investor doesn’t need to ‘run out’ and find a solution because it’s already simmering away somewhere in their portfolio.
Understanding ‘value’ and ‘growth’

In general terms, ‘value’ investment approaches target those companies regarded as looking cheap relative to the value of their assets (also known as their ‘intrinsic’ or ‘book’ value). Value stocks tend to be well-established businesses, which often offer high levels of dividend.

Good examples of value stocks include banks, oil and mining, utility and industrial companies although any company whose valuation is below the market average is technically regarded as a ‘value stock’.

Meanwhile, ‘growth investing’ is more focused on capital growth than on collecting dividends. Growth stocks tend to be younger or smaller companies whose earnings are expected to increase faster than those of other companies in their industry sector or the broader market.

They tend to pay limited dividends as they are busy reinvesting their profits in growing their businesses.

Growth stocks are most commonly found in the technology sector with companies like the ‘FAANGs’ the most prominent example of recent years.

Other ‘cyclical’ areas (meaning companies most impacted by the economic cycle) such as consumer goods, leisure and travel or the automobile sector often contain ‘growth’ stocks. The same is true of areas like biotech.

Ultimately, any company with a disruptive business model, ground breaking new technology or an irresistible new line of consumer goods can find itself classified as a ‘growth’ stock if its earnings growth starts to outpace the broader market.

As companies mature and become more established in their industry niche, they naturally evolve from being growth companies into being value companies. That is, until they bring something new to the market, at which point the cycle can begin all over again.

Interesting input from the CIO at Quilters.  A lot of this is what we discuss daily with our clients.  We need diversification by assets, geography, and styles.  Good strong ‘Active’ and ‘Tactical’ fund management helps too, particularly in volatile markets.

As IFAs we use a wide range of investment options for our clients to meet their objectives and risk profiles.  We have a myriad of choice.

Please continue to check back for our latest blog posts and market updates.

Charlotte Ennis

16/04/2021
Team No Comments

The economic outlook improves, but the shadow of COVID lingers

Please see below article received from Invesco yesterday afternoon, which conveys a positive outlook for the global economy despite concerns over a ‘fourth wave’ in countries such as Brazil and India.

IMF upgraded its economic outlook

The International Monetary Fund (IMF) provided a press briefing last week, sharing recent alterations to its global economic outlook for this year. The IMF now expects the global economy to grow 6% in 2021 — the highest level of growth since 1980.1 This is an upward revision from its previous estimate in October of 5.5% growth in 2021 for the global economy.

This is a reflection of the optimism created by the discovery and rollout of effective vaccines as well as significant fiscal stimulus, which is already having a positive impact on some countries such as the United States. It dramatically revised its growth expectations for the US economy in 2021 from 5.1% to 6.4%.1 The IMF modestly upgraded its expectations for economic growth in China in 2021 from 8.1% to 8.4%.1 One key takeaway from the IMF’s press briefing is that the world is on divergent recovery paths. The US and China, the two largest economies in the world, are leading the recovery, but other countries are experiencing a far slower recovery and are not expected to reach pre-pandemic GDP levels until 2023.

Eurozone PMIs point to improvement

The final eurozone composite Purchasing Managers’ Index (PMI) reading for March was 52.5 versus 48.8 for February.2 More importantly was the final services PMI reading for March: 49.6 versus 45.7 in February.2 We saw significant improvement in a number of countries including Ireland, the UK, and Germany. And so while it’s no surprise to me that manufacturing continues to strengthen, led by manufacturing powerhouse Germany, it is surprising — and encouraging — to see the services sector improving in some countries despite rising COVID-19 infections and lockdowns.

Chris Williamson of IHS Markit explained what is happening in the euro area: “The survey therefore indicates that the economy has weathered recent lockdowns far better than many had expected, thanks to resurgent manufacturing growth and signs that social distancing and mobility restrictions are having far less of an impact on service sector businesses than seen this time last year. This resilience suggests not only that companies and their customers are looking ahead to better times, but have also increasingly adapted to life with the virus.”2

This is good news, given that the vaccine rollout in the eurozone has been disappointing. While I don’t expect a robust recovery until COVID-19 is well controlled, the PMI readings suggest the economy can still recover in an environment of slow vaccinations and higher stringency.

FOMC minutes represent a ‘have your cake and eat it too’ moment

The Federal Reserve upgraded its economic outlook — but that didn’t change its stance on accommodative monetary policy. The minutes from the March meeting of the Federal Open Market Committee (FOMC) were released last week, showing that its growth expectations for the US economy in 2021 were — similar to the IMF — upwardly revised to 6.5% from 4.2%, while unemployment expectations were revised down to 4.5% for 2021 from 5%.3 The Fed’s optimism was driven by the economic re-opening and increased fiscal stimulus. The Fed also upwardly revised its expectations for inflation, forecasting 2021 core personal consumption expenditures to increase by 2.2% — this is a substantial increase from its previous forecast of 1.8%.3

In my view, these minutes represent a “have your cake and eat it too” moment — a Fed that expects the economy to experience strong growth — but will not pre-emptively tighten as it has often done in the past. The Fed is expecting a brighter economic outlook, but wants to remain very accommodative. The minutes stated that it will be “some time before the conditions are met for scaling back the asset purchase program” — and the Fed still expects rates to remain zero through 2023.3 In these minutes, the Fed once again reiterated its plans to sit on its hands well beyond 2021, anticipating that the spike in inflation it expects this year will be transitory. Investors couldn’t ask for a nicer Fed.

We heard lots of ‘Fedspeak’

We didn’t just get the minutes from the March FOMC meeting last week. We also heard from various Fed officials. Here are the highlights:

  • Last week Fed Chair Jay Powell suggested that COVID-19 infections are the biggest risk to the economy. He shared a cautionary message about the pandemic last week despite growing optimism about the economy: “Cases are moving back up here, so I would just urge that people do get vaccinated and continue socially distancing. We don’t want to get another outbreak; even if it might have less economic damage and kill fewer people, it’ll slow down the recovery.”4
  • St. Louis Fed President James Bullard shared his view that the Fed should not even consider any changes to its monetary policy until we have certainty that the pandemic is over. In my view, this could further delay monetary policy normalization given that it could tether future Fed considerations to health-related accomplishments.
  • Then, last night, Powell appeared on an American TV news show, “60 Minutes.” He reiterated that the principal risk to the economy is a resurgence of the pandemic. Powell stated that the US is “at an inflection point,” and he expects growth to be very strong in the back half of 2021. One important line from his interview, “The Fed will do everything we can to support the economy for as long as it takes to complete the recovery.”5

Signs of inflation in PPIs

The US Producer Price Index (PPI) rose substantially in March, exceeding expectations. However, markets barely flinched. And this rise in PPI is not specific to the US; China also experienced a big rise in producer prices. My view is that these data points are to be expected, a combination of base effects and short-term supply disruptions. However, that doesn’t mean we won’t want to follow future inflation data closely, including US Consumer Price Index this week.

Fears of a ‘fourth wave’ continue

The Fed’s concerns about COVID-19 are well-founded. COVID-19 cases are on the rise in a number of countries, most notably Brazil and India. Bruce Aylward, a World Health Organization official, described the situation in Brazil in stark terms, “What you are dealing with here is a raging inferno of an outbreak.”6 I believe concerns about infections, especially a rise in the spread of more contagious variants, will continue to be an intermittent cause of concern for markets.

So what happened in markets?

The big news is that the yield on the 10-year US Treasury backed down materially last week. This came as a surprise to many, given that the outlook for the economy continues to improve — as have expectations for inflation.

I think there are several possible reasons for this.  First of all, it could be a reaction to rising COVID-19 infections in parts of the world, which could be causing investors to actually lower expectations for growth. Similarly, all this talk of rising taxes in the US could also be dampening expectations about a very strong economic recovery. Or perhaps investors are finally starting to believe the Fed when it says it will not be tightening any time soon.

Not surprisingly, because yields backed down, there was a rotation within stocks. Stocks in general made gains last week, but technology stocks and other more growth-oriented stocks — as well as larger-cap stocks — assumed positions of leadership. Going forward, I would expect a continuation of this trend: rotations in leadership tied to changes in the 10-year yield. But make no mistake — I am in the camp that expects yields to rise this year. Despite last week’s downward moves, I expect the yield on the 10-year US Treasury to reach 2% or higher this year.

Looking ahead

There is a lot to look forward to in the coming week, from US retail sales to UK gross domestic product (GDP) to the business outlook survey from the Bank of Canada. Here are a few items I am focused on:

  • Eurozone retail sales. The services PMIs mentioned previously suggest that the pandemic and lockdowns don’t seem to be having as big an effect on the service sector of the economy. This data should help confirm that theory.
  • Beige Book. The Fed’s “Beige Book” is chock full of anecdotal information from businesses in the different Fed districts across the country. It gives you a real sense of what they are experiencing — and thinking about.
  • China GDP. China has clearly helped lead the economic recovery in the early innings. This will give us a sense of how strong that leadership has been in the last quarter, and what parts of the economy it has come from.
  • Earnings season. Earnings season begins this week. Many companies abandoned guidance in the midst of the pandemic, but I am hopeful we will get more guidance this quarter. Any kind of outlook will be valuable.
  • Global vaccination levels. As always, I remain most concerned about our ability to control the pandemic, and the speed with which we vaccinate populations plays a critical role. As Fed Chair Powell has made clear, he believes the pandemic is the greatest risk to the economy this year. When I went to receive my second COVID-19 vaccine yesterday, the physician’s assistant who inoculated me ominously warned me against laminating my vaccination card. She matter-of-factly explained, “You will be back periodically for boosters. This is not over.” That’s because variants are spreading, especially where COVID-19 hasn’t been controlled, and will likely make it quickly to other parts of the world. There is a funny expression in the US about the city perhaps best known for gambling and general fun that is arguably more decadent: “What happens in Vegas, stays in Vegas.” But there is no such thing when it comes to a pandemic. What happens in Sao Paolo (or New Delhi or Paris or Amsterdam or Los Angeles) doesn’t stay there. It can happen everywhere. So we need to care about vaccinations everywhere.

Please check in again with us soon for further market updates and news.

Stay safe.

Chloe

15/04/2021

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see below this week’s Markets in a Minute update from Brewin Dolphin – received late yesterday afternoon – 13/04/2021

Equities hit new highs on hopes of sustained economic recovery

Numerous share markets hit all-time highs last week, with the S&P500 bursting further past the 4,000 mark, finishing the week comfortably in record territory at 4,129. European markets also performed strongly, as investors bet on continental economies reopening later this year despite problems with the vaccination programme. The European Stoxx600 hit a record high of 437.23 on Friday.

In the UK, confidence in the continued easing of restrictions helped the FTSE100 rally by more than 2.6%, to levels not seen since before the pandemic. Meanwhile, the more domestically focused FTSE250 surged through its previous record of 22,000.

The tech-heavy Nasdaq also recouped some of its recent losses last week, rising more than 3%, helped by a pause in rebounding bond yields. Asia was more subdued, however. Chinese policymakers are reportedly considering tightening monetary and fiscal policy to prevent the economy overheating and inflation rising too high, leading to a pullback in share prices.

Last week’s market performance*

  • FTSE 100: +2.64%
  • Dow Jones +1.95%
  • S&P 500: +2.70%
  • Nasdaq: +3.11%
  • Dax: +0.84%
  • Hang Seng: -0.82%
  • Shanghai Composite: -0.45%
  • Nikkei: +1.29%

*Data from close of business on Thursday 1st April to close of business Friday 9th April.

Shares start week on cautious note

Markets edged back from their record highs on Monday, as investors digested last week’s surge in equity markets, and looked ahead to key US inflation data out later today. It is the start of first-quarter earnings season in the US this week.

In the UK, the FTSE100 closed down 0.39% at 6,889, despite the feelgood factor accompanying the reopening of non-essential shops and pubs.

In the US, the Dow fell 0.16% at 33,745.40, while the S&P500 fell slightly, losing 0.02% to close at 4,127.99 and snapping a three-week winning run in the process. The Nasdaq fell by 0.36%. In Europe, the Stoxx600 index dropped by 0.25%, although markets in France and Germany edged up.

Bond yields take a breather

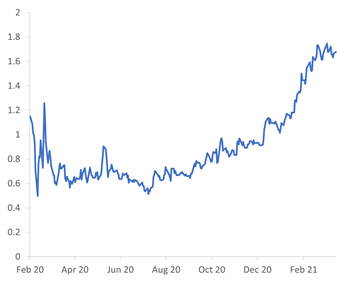
The yield on 10yr US treasuries started the year below 1%, but surged in the first quarter to hit 1.67%. Rising treasury yields are usually a sign of increasing investor confidence since yields move inversely to bond prices. When investors sell bonds and invest more of their portfolios in risk assets such as equities, yields rise.

However, there can come a point at which higher yields can tempt investors back into bonds to enjoy a risk-free return on their money, or to search for sectors with more upside potential, especially if yields rise too fast.

Hence, we have seen a large-scale rotation out of growth stocks and into more value-orientated, cyclical sectors during the first quarter, as evidenced by the recent correction in big tech in the US.

The pause in rising yields last week was a key factor in the strong performance in share markets over the past few days, particularly on the Nasdaq.

While yields will likely continue to rise, with 10yr treasury yields expected to hit 2% by the end of 2021, the increase is expected to be more gradual, which equity markets should find easier to digest.

US 10yr Treasury yield

Source: Refinitiv Datastream

Global growth set for record year

The International Monetary Fund (IMF) said last week that it expects the global economy to grow by 6% this year, up from the 5.5% it forecast in January.

If true it will be the fastest expansion on records going back to 1980, despite large parts of the world still being mired in the pandemic.

Also supporting the bullish outlook are the trillions in excess savings waiting to be spent around the world, an improving employment picture in the US, and the Federal Reserve’s insistence that it will not be rushed into raising rates until there is solid evidence of a sustained recovery. Minutes from the last Federal Reserve meeting suggest that there is no intention to raise interest rates until at least 2024, and even then would require firm evidence of a sustained economic recovery and inflation at or above its 2% target.

All this should support further growth in equities as long as we don’t get a nasty overshoot in inflation, and bond yields remain relatively stable.

UK economic recovery appears on track

Last week we saw a slew of positive economic data that suggests the UK economy is enjoying a healthy rebound. The ISM/Markit Purchasing Managers’ Index for the key UK services sector, which accounts for around 80% of GDP, showed business levels improving for the first time since last October, with 56.3% of respondents reporting higher business volumes in March than in February. The UK construction industry is also recovering strongly, with the construction activity index hitting a reading of 61.7, its highest level in seven years.

Another quick update from Brewin Dolphin, these updates are a good way of keeping up to speed with developments in the markets.

Please continue to check back for our latest blog posts and market updates.

Charlotte Ennis

14/04/2021

Team No Comments

The Changing of The Weather

Please see the below article from Legal and General’s Asset Allocation team received late yesterday afternoon:

With some of the lockdown rules easing in England today, and following some recent warm and sunny weather, it feels like change is in the air. In this week’s Key Beliefs, we look at three areas of the market where change may also be on the way.

A deluge of EU doses?

We try not to talk too much about the vaccines and virus now, as it’s increasingly important we focus on other factors. That said, vaccines have featured more heavily in our recent debates and in the market’s commentary.

In the UK, about 60% of adults have had their first jab. In the US, it’s nearly 50% and 25% of adults are fully vaccinated. While there are still risks to reopening in both cases, the likelihood is that the vaccinations will win out in the race against another viral wave.

Inevitably then, there’s a lot of attention on the European Union, where only about 25% of adults have received their initial vaccine dose. It was inevitable that the more infectious variant that was first identified in the UK would become the dominant strain across the continent, and unfortunately that’s led to further lockdowns, so the question is when Europe will be able to reopen.

The good news is that despite the disappointing progress so far, the EU is poised to accelerate rapidly and will likely be two months or fewer behind on its journey. Alongside some more surprising stories, like Bavaria buying the Sputnik V vaccine, the past fortnight has brought the highest vaccination rates yet at 1.5-2% a week. Germany has now outlined its potential to vaccinate 12.5% of its population a week once the supplies are available; Martin Dietz estimates German deliveries at 16.6 million doses in April across four different vaccine providers.

To catch the US up over two months, the EU would need to vaccinate about 4.5% of the population a week. Given the diversified sources of supply Europe is employing, that looks very achievable. So, on balance, Europe could be another source of positive surprises this quarter. We believe this is supportive of both our travel and leisure equity position and broader positive equity view.

High and dry

Market activity tends to be low in the week following Easter, and similarly there was just one view change from our team last week. That came in US Treasuries, where we removed the tactical short position that was designed to help protect us from the risk of a bumper employment number on Good Friday.

After nearly a million US jobs were added in March, we expect further good news as the country reopens. While that supports our medium-term positive equity view, we’re not convinced it implies higher bond yields. There are two main reasons why.

First, with a 10-year yield around 1.65%, we think valuations are towards the upper end of a fair range and that markets will struggle to price in a much higher path, with almost four rate hikes implied in the market consensus by the end of 2023.

Second, we know being short US Treasuries is a very popular position; we try to avoid such crowds, so we prefer to keep our powder dry.

The biggest risk to yields in the coming months may be the upcoming inflation numbers. Starting from depressed levels this time last year, economists already expect temporarily high prints in the second quarter.

However, with so many unusual factors – including the large build-up of household savings – there is a chance that there are big surprises. Last week, we saw the Producer Price Index rise 1% against a consensus expectation of 0.5%. While it’s a noisy series, it could be the first of many.

That said, for the longer term we don’t buy into the idea that there’ll be sustained inflation and are prepared to look through the short-term noise.

The calm after the storm

Uncertainty is high this year, which makes our mantra of ‘prepare, don’t predict’ all the more important. To take one example, sentiment towards equities has been positive for most of the year, but not stretched to levels where it becomes a worrying sign.

However, one of the indicators that Lars Kreckel finds most reliable, the AAII Bull-Bear Spread, has now jumped to 36.5 and is close to the 40+ level that he considers a warning signal. The most recent Goldman Sachs QuickPoll suggests sentiment is a lot less elevated, though.

Against the improving backdrop, we’ve also seen implied volatility in equities drop markedly over the past couple of weeks, with the VIX at its lowest level since February 2020 and broadly in line with average levels from 2018-2019.

So with some evidence that investors are becoming more bullish, we retain our positive equity view, although following strong performance we rebalance to avoid weights drifting up further. Some portfolios have also been selling volatility at elevated levels as a source of return, but we expect those opportunities will be increasingly hard to find.

Please keep checking back for our regularly updated blog content covering a range of market updates and insights from a number of great fund managers, as well as topical issues such as ESG and our own thoughts and input.

Andrew Lloyd

13/04/2021

Team No Comments

Investment Intelligence Update – Weekly Market Performance

Please see below commentary received from Invesco this morning, which analyses market performance over the past week – as the IMF predicts strong economic recovery this year.

The IMF’s latest World Economic Outlook, published last week, reaffirmed the forecasting community’s expectation of a strong economic recovery in 2021. The rollout of multiple vaccines, better than expected adaption to pandemic life, additional fiscal support in some countries, particularly the US, and continuing monetary accommodation (the Fed reaffirmed during the week that the bar for tapering asset purchases, the first stage in tightening policy, remains high) underpinned the IMF’s 50bp upgrade to 2021 forecasts, from an already strong 5.5% to 6%. However, the IMF continues to expect that differences in the pace of the vaccine rollout, the extent of policy support and structural factors, such as the reliance on tourism, will ensure any recovery will be a multi-speed one. The US leads the way among advanced economies (see chart of the week) and is forecast to surpass its pre-Covid GDP levels this year, while many others (including the UK) won’t do so until 2022. It’s a similar picture in emerging economies, where China already returned to pre-Covid levels in 2020, but many others are not expected to do so until 2023.

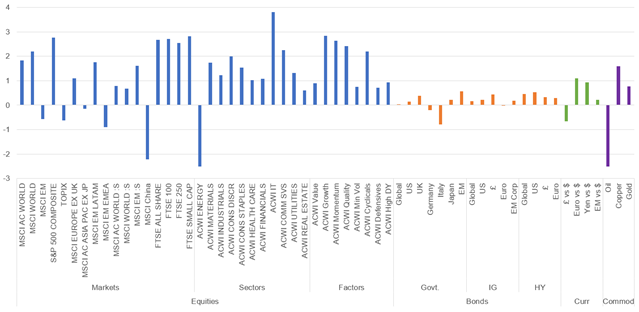
While global equities had a good week overall (MSCI ACWI 1.8%), hitting a new all-time high, not all markets made gains. While DM were up 2.2%, EM continued to struggle, falling 0.6%, led lower by Asia (EM Asia -0.8%). EM are now over 7% below their 12.5% YTD high and are around 4.5% behind DM. As markets have rallied, expectations of future volatility have declined, with the VIX dropping to below 17 for the first time since pre-pandemic, but that remains well above the historical lows (<10) of the late 2010s.  DM performance was led by US equities, with the S&P 500 up just under 3% and hitting a new all-time high. Europe also made gains and is the strongest DM region YTD (MSCI Europe ex UK 10.4%). While Small Caps underperformed (0.8%) they remain well ahead of the overall market YTD. EM and DM small caps have risen broadly in-line. At a sector level, tech-related sectors dominated performance, with IT (3.8%) and Communication Services (2.3%) leading the way. Energy (-2.5%) struggled against a weaker oil price, although remains the best performing sector YTD. In a risk-on environment, defensive sectors underperformed and remain the market laggards. Consumer Staples and HealthCare are only up 2-3% YTD. It was a rare week of Growth (2.8%) outperformance against Value (0.9%). Momentum (2.6%) and Quality (2.4%) also performed well. UK equities outperformed (All Share +2.8%), with both mid and small caps hitting new all-time highs. A weaker £ and an easing of lockdown measures underpinned the market.

Government bond yields were relatively stable, with 10yr USTs, Gilts and JGBs seeing 1-2bp declines. There was modest upward pressure in EZ yields with the 10yr Bund and BTP up 3bp and 11bp respectively. Overall global government bonds are still down YTD (-2.9%), with Gilts and USTs the main laggards. Credit yields and spreads edged lower in both IG and HY, with the latter outperforming (0.5% vs 0.2%). HY is comfortably ahead YTD (1.3% vs -2.7%) with the EZ the best of the regional markets in both IG and HY.

The US$ gave up some of its recent gains with the US Dollar Index down 0.9%, its worst week since December, as both the Euro (1.1%) and Yen (0.9%) appreciated. £ was an outlier, declining 0.7% and back close to its YTD lows at just over $1.37.

After a strong start to the year (up 34% at one point), oil prices have struggled in recent weeks and gave up 2.5% last week as virus-related demand concerns remained and OPEC+ decided to increase supply between May and June by 2mbd. Although it saw a small gain, Copper has struggled to regain momentum since reaching a 9-year high in February as demand concerns, a stronger US$ and rising inventories have weighed on sentiment. Gold (0.8%) has bounced off its lows as a stabilisation in real yields and a weaker US$ have provided some support. It is still down 8% YTD.

Market performance last week (%)

Past performance is not a guide to future returns. Sources: Datastream as at 11 April 2021. See important information for details of the indices used.

YTD market performance (%)

Past performance is not a guide to future returns. Sources: Datastream as at 11 April 2021. See important information for details of the indices used.

Chart of the week: ISM Services PMI Index and S&P 500 performance

Past performance is not a guide to future returns. Source: Datastream as at 12 April 2021. Price only performance.

  • There have been a series of much stronger than expected US economic data releases since the start of April. These include the ISM Manufacturing PMI, that hit its highest level since December 1983, and Non-Farm Payrolls that at 916k came in much better than expected (albeit seasonal effects probably overstated the degree of the beat). Last Monday we saw the ISM Services PMI hit an all-time high of 63.7, rising from 55.3 and well ahead of consensus expectations of 59 (remember here that PMIs are diffusion indices, so tell us the percentage of firms that are experiencing an uptick in business and do not give a sense of the magnitude). While the Services PMI has a much shorter history (since 1997) than the Manufacturing PMI (since 1948), it remains a key guide to business sentiment in what is, of course, the dominant sector in the US economy.
  • And as the chart highlights there has historically been a close relationship between equity market performance and the Services PMI. The correlation is a high 64%, only marginally lower than the 67% correlation with the Manufacturing PMI over the same time period. Given this relationship and the strength of the Services (and Manufacturing) recovery from the pandemic lows, its hardly a surprise that the equity market performance has been so strong.
  • Clearly there is a big surge in activity under way as the weather improves. Alongside that, although new cases have picked up recently, the substantial drop in virus case numbers from the second wave peak and the successful rollout of the vaccination programme (34% have received their first shot) has allowed lockdown restrictions to be lifted at the same time as Biden’s $1.9trn in additional fiscal stimulus boosts incomes. And the improvement in the PMI has been broad-based, with all eighteen industries reporting growth. Among the key sub-components of the index the largest gains were seen in Business Expectations (+13.9pts to 69.4) and New Orders (+15.3pts to 67.2), both at record levels. Employment also saw an improvement, reflecting the strong Non-Farm Payrolls numbers, and at 57.2 is back at pre-pandemic levels.
  • For those concerned about a potential lift-off in inflation, there were further signs that inflation pressures continue to rise. The Prices index rose to 74, its highest level since 2008, a similar picture to what we saw with Manufacturing (85.6). Time will tell whether that turns into a sustained and/or substantial rise in inflation, forcing a change in policy stance from the Federal Reserve. For now, the Federal Reserve thinks not. The risk is that they are wrong.

Key economic data in the week ahead

  • A relatively quiet week ahead with China’s Q1 GDP and US inflation the main features.
  • In the US March’s Inflation data is out on Tuesday. Headline and Core are expected to rise 0.5%mom and 0.2%mom respectively. This would take them to 2.5%yoy and 1.6%yoy, the former the highest it has been since before the pandemic. Initial Jobless Claims posted a surprise uptick last week to 744k. It is expected to drop to 700k on Thursday – still elevated given the strength of the economic recovery. On the same day Retail Sales for March are also forecast to jump thanks to the latest round of stimulus cheques and improved weather. An increase of 5.5%mom is pencilled in following the 3% drop in February. Following the recent batch of positive economic data, the University of Michigan Consumer Sentiment index for April on Friday is expected to rise to 89 from 84.9, the highest reading since March of last year.
  • The only data point of note in the UK is February’s monthly GDP published on Tuesday. Although economic activity is expected to have picked up, increasing 0.5%mom after January’s 2.9% contraction, the rolling 3m number is expected to remain negative at -1.9%. Improvement in services is the key driver here, with February forecast at 0.5%mom after the 3.5%mom fall in January.
  • In the EZ Retail Sales data for February is released on Monday. A small 1.3%mom gain is forecast, but still leaving a -5.4%yoy shortfall. February’s Industrial Production numbers are released on Wednesday. A -1%mom decline is expected, leaving it at -1%yoy.
  • In China Q1 GDP is published on Friday. A quarterly gain of 1.4%qoq is forecast, leaving the economy higher by 18.3%yoy. The increase in economic activity is expected to be broad based, with Industrial Production, Retail Sales and Exports forecast to rise 27.6%yoy, 28%yoy and 28%yoy respectively.
  • There is no data release of significance from Japan this week.

We will continue to publish relevant market analysis and news as we enter the 10-week countdown to the end of the UK’s national lockdown.

Stay safe.

Chloe

12/04/2021

Team No Comments

Carl Eccles

‘I have known Steve as a friend for a long time, and a few years back I started dealing with Steve on a professional front to look after my personal finances. Working within the financial services sector myself I hand on heart would recommend Steve & his team to anybody. The personal service and professionalism is second to none. I 100% trust and take Steve’s professional advice without hesitation as he takes the time to understand and gets to know you as a person, your business objectives so he can advise for your best interests.

By working closely with Steve I am also more knowledgeable about the markets and how to best to plan for my future. Regardless of how busy Steve is he always makes time to help, advise and support you as a client and a friend.

A great guy, a great company… Thanks for all your advice and support so far.’

Carl Eccles – Director, Just Protect

10/04/2021

Team No Comments

Will ‘peak pension freedoms season’ return after pandemic-induced withdrawals slump in 2020?

This email was received yesterday, 11/04/2021, and this article was written by Tom Selby, a Senior Analyst at A. J. Bell.

Until 2020, the beginning of a new tax year has traditionally been peak pension withdrawal season, with UK savers taking advantage of a fresh set of tax allowances to access larger amounts from their retirement pots.

In fact, before the pandemic hit withdrawals in the first three months of the financial year had been between 10% and 33% higher than in subsequent quarters.

That all changed last year, when retirement income investors spooked by the uncertainty of lockdown – not to mention double-digit market falls – tightened their belts, with year-on-year withdrawals dropping 17%.

This likely reflected people choosing to either delay accessing their pension, pause withdrawals or reduce the amount they were taking as income in the face of profound uncertainty.

While most of us still have fewer things to spend our money on at the moment – particularly given restrictions on foreign travel – the success of the coronavirus vaccine and more stable market conditions mean we should expect to see a significant jump in withdrawals in the coming quarter.

For those accessing their retirement pot during this period, there are various pitfalls and bear traps to watch out for.

Source: HMRC

1. Taking taxable income flexibly from your pension will trigger an irreversible £36,000 cut in your annual allowance

Anyone considering taking taxable income from their retirement pot for the first time needs to be aware of the severe impact it will have on their ability to save tax efficiently in a pension in the future.

Taking even £1 of taxable income will trigger the money purchase annual allowance (MPAA), reducing the amount most people can save in a pension each year from £40,000 to just £4,000.

Furthermore, if you trigger the MPAA you will lose the ability to ‘carry forward’ unused pensions allowances from up to 3 previous tax years, meaning in some cases the impact will be a £156,000 reduction in the potential annual allowance in the current tax year, from £160,000 to £4,000.

To avoid an annual allowance cut, savers who have the option should consider using money held in vehicles such as ISAs or cash savings accounts first. For those who only have their pension, just taking your 25% tax-free cash will also allow you to retain the £40,000 annual allowance.

2. Your first taxable withdrawal will be subject to emergency ‘Month 1’ taxation

Since the pension freedoms launched in April 2015, around £700 million has been repaid to savers who were overtaxed on taxable withdrawals.

When you first take a flexible payment from your pension, HMRC will automatically tax it on an emergency ‘Month 1’ basis. This means that the usual tax allowances are divided by 12 and then applied to that first withdrawal.

For example, if someone made a £12,500 taxable withdrawal in 2020/21 and had no other taxable income, they might expect to be charged 0% income tax as the withdrawal is within their personal allowance.

However, because it is their first taxable withdrawal only £1,042 (£12,500 personal allowance divided by 12) is taxed at 0%. The next £3,125 (£37,500 basic-rate tax band divided by 12) is taxed at 20%, with the remaining £8,333 taxed at 40%.

In total, rather than paying zero tax they would face an initial – potentially shocking – bill of £3,958.

For those taking a regular income this shouldn’t be a problem, as any overpaid tax in the first month will be ironed out via your tax code. However, where it is a single payment over the tax year there are two options – wait until the end of the tax year for HMRC to hopefully sort it out, or sort it out yourself by filling out one of three forms.

Once you’ve filled out and sent off the relevant form, HMRC says you should receive a refund of your overpaid tax within 30 days.

View the tax refund form

  • If the withdrawal used up your entire pension pot and you have no other income in the tax year, use form P50Z;
  • If the withdrawal used up your entire pension pot and you have other taxable income, use form P53Z;
  • If the withdrawal didn’t use up your pension pot and you’re not taking regular payments, use form P55.

3. Think about the sustainability of your retirement plan – and beware big withdrawals during falling markets

Last year saw the first bear market – characterised by falls in stocks of more than 20% – since the pension freedoms launched in 2015. The pandemic and global economic shutdown brought into sharp focus the importance of understanding the investment risks you are taking and managing withdrawals sustainably.

This is particularly the case where large withdrawals come at the same time as big falls in markets, a phenomenon often referred to as ‘pound-cost ravaging’.

As an example, someone taking a 5% inflation-adjusted income from their fund who suffered a 20% hit in their first year of drawdown and 4% growth thereafter could see their pot run out after 18 years – three years sooner than if they suffered the hit 10 years into retirement.

To put this into context, whilst on average life expectancy at 65 is 18.6 years for men and 21 years for women, a man has a 1 in 4 chance of living another 27 years, while a woman has a 1 in 4 chance of living another 29 years.

Savers wanting to manage withdrawals sustainably and avoid selling down their capital at a low point in the market could use other cash resources – such as ISAs, savings or their 25% tax-free cash – in order to keep their underlying pension intact.

Taking a natural income has also been a good strategy previously, although finding companies paying the dividends needed has been a real challenge over the past 12 months.

For those who do take capital withdrawals from their pension, the key is to have a plan in place and review your income strategy regularly, ideally with the help of a regulated adviser, to ensure you aren’t risking running out of money early in retirement.

4. If you’re just taking your tax-free cash, don’t forget about the remaining 75% of your fund

The vast majority of savers cite accessing their 25% tax-free cash as the main reason for entering drawdown*. This is understandable given this is one of the main tax benefits of saving in a pension.

Although accessing your tax-free cash won’t necessarily mean a change in your underlying investments, it is worth using this as an opportunity to review your retirement plans and ultimate goals.

For example, someone planning to take a regular income after accessing their tax-free cash will likely have a different asset allocation to someone who doesn’t plan to touch the remaining money for 15 years.

While many will understandably be spooked at the prospect of investing at the moment, it is worth remembering that short-term volatility has historically been the price you pay to enjoy longer-term growth.

Investors also need to be aware of and comfortable with the risks they are taking.

Although investments can go down in value as well as up, the value of cash will be eaten away by inflation over time.

5. Do you want to spend your pension or leave it to loved ones after you die?

Pensions are no longer just about providing an income in retirement. Since 2016, savers have been able to pass on leftover pensions tax-free if they die before age 75.

Where the pension holder dies after age 75, the remaining funds will be taxed at their recipient’s marginal rate when they make a withdrawal.

For those who want to leave assets to loved ones, it therefore often makes sense to leave as much of your pension untouched as possible in order to minimise your tax bill.

This means when you come to flexibly access your pension for the first time, you should think not just of your retirement income strategy but also your IHT plans.

It’s also important to ensure your nominated beneficiaries are up-to-date so the right people inherit your pot.

Useful input from Tom at A. J. Bell.  There is nothing new here, since the new ‘Pension Freedoms’ were introduced in April 2015 we have had the freedom to withdraw capital and/or income from age 55 from our fund value based pension pots with greater flexibility.

However, we have had some form of Pension ‘Drawdown’ legislation in place since 1995.

This is a key area for independent financial advice.  The pitfalls are substantial if you don’t fully understand what you are doing.

In general terms, it’s probably better for the majority of the population not to access their pension funds until they retire or at least semi retire.  There are exceptions to this.

My focus as an IFA is in the following areas:

  1. Overall tax efficiency, holistically and with your partner if applicable
  2. Sustaining your pension assets for potentially a long-term retirement.  We are living longer on average
  3. Retaining your ability to fund pensions at a good level if at all possible
  4. Building your assets for your eventual full retirement, a variety of assets to aid tax efficiency and risk control

Retirement planning is not a ‘one size fits all’ approach.  We need to carefully take into account our client’s circumstances, plans and objectives.

The earlier you start planning for retirement the better.  We can do a lot more with a 15 year term to retirement than we can with a few months.  However, even if you are coming to this ‘Pension Freedom’ late, near drawing benefits, please do take advice.

Steve Speed

12/04/2021

Team No Comments

The Silicon Valley of Green Tech?

Please see the below article from Invesco:

The health crisis of 2020 created a synchronised economic depression requiring equally radical policy responses.

Europe’s response was the creation of a €750bn European Recovery Fund. However, rather than just deploy the capital, member states chose to focus on a Green Recovery and hence use the funds to address the existential threat of climate change. In practice this means the European Commission spending is being guided by the newly developed sustainable finance taxonomy. Promoting activities supportive of the environmental objectives of climate change mitigation and adaption:

  • Sustainable use and protection of water and marine resources
  • Transition to a circular economy
  • Pollution prevention and protection of biodiversity and ecosystems
  • It also contains criteria that ensure activities ‘do no significant harm’

European environmental legislation is not new. For years Europe has been a first mover in safety standards and best practices that become global standards, however, the European Green Deal marks a more dynamic approach. Taxonomy is the means by which the market will administer the carrot or the stick to companies. Winners will be those seen to solve the environmental crisis and losers will be those thought to be the cause.

This comes at a time of other changes to the investment landscape. Savers now demand their asset managers embed sustainability into allocation decisions. Fund regulation is playing its role too, through the deployment of SFDR this year, funds will be classified dependant on embedding ESG principles thereby making it easier for savers to pick compliant funds and avoid others. Lastly, the pandemic has created the political cover to deploy the significant European Recovery Fund to sustainable companies.

Combined these elements create the foundations for success. European companies that comply with taxonomy will see their cost of capital fall vs those that don’t.

The EU Recovery Plan is interlocked with the Commissions’ 2019-24 priorities that included the realisation that “Europe needs a new growth strategy that will transform the Union into a modern, resource efficient and competitive economy”. This is an inclusive plan with The Just Transmission Mechanism’s goal that ‘no person or place left behind’. At least E150bn is being made available to address socio-economic effects of the transition out to 2027 – a topic we discuss in greater detail in another piece (link to The Just Transition article). However, the real prize isn’t intra-Europe it’s global.

The goal of climate neutrality requires significant investment and innovation. If the transition is effective through taxonomy rewarding companies in the transition phase, we will grant our existing enterprises a competitive advantage though access to the cheapest capital. This will create more dynamism through more innovation and the creation of products, services and refreshed skilled jobs to achieve all the EU goals. Brown companies can become Green.

This idea of creating a pathway isn’t new. Europe has 2030 targets not just 2050, including transition plans for hybrid ahead of full electric vehicles, coal to gas electricity generation and developing blue hydrogen ahead of green hydrogen being viable. Through this approach we can incentivise European companies to allocate their existing cashflow towards green innovation as opposed to being forced into ever larger dividend yields.

Silicon Valley is perhaps the best example of the prize on offer. The birth of Silicon Valley was a confluence of skilled science-based research, education, venture capital and defence spending, particularly through the creation of NASA and the space race. The success and longevity of which is a function of being the first and with it a sustainable multiplier effect.

We are already starting to see the positive effects from this focus on transition. European oil companies lead the way in reallocating hydrocarbon cashflows towards greener alternatives (Total, Repsol, BP). In renewable energy, Europe is home to the leading wind turbine manufactures (Vestas, Nordex and Siemens Gamesa) and our power generators are world leaders in green production (Enel, EDP, Acciona). In technology, European semiconductor companies have leadership in Auto electrification (Infineon and STMicro). We also have expertise in building materials and renovation focused on reducing energy consumption (SaintGobain, Wienerberger, Kingspan). Europe’s paper companies are transitioning to sustainable packaging and biofuels (UPM) and Europe is home to worldwide leaders in the circular economy (Veolia and Suez). All are stocks that are held in portfolios across the team, to a varying degree.

Europe has grand ambitions and a once in a generational opportunity to steal a march on other continents through early adoption of regulation and technology. Through incentivising companies to innovate and embrace climate change Europe can become a global exporter of Greentech products and services to the rest of the world and enjoy the multiplier effect. Europe has the potential to achieve net zero and in doing so become the Silicon Valley of Green Tech including the vibrancy, jobs and sustainability that comes with it.

Please continue to check back for a range of blog content and regular updates from us.

09/04/2021

Andrew Lloyd

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see below this weeks update on markets from Brewin Dolphin. This update was received late yesterday afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

08/04/2021

Team No Comments

Invesco Insights: Israel’s economic data starts to show the impact of vaccines

Please see below for one of the latest Invesco Insight articles written by Kristina Hooper, Chief Global Market Strategist at Invesco Ltd. This article was received by us today 07/04/2021:

A month ago, I wrote about the great progress Israel was making in terms of inoculating its citizens against COVID-19. At the time, I said that we would want to follow economic data in Israel closely for indications of what the US and UK could expect in the near future — as they are making swift progress in vaccinating their respective populations — as well as what any country can expect once it successfully vaccinates a significant portion of its population. Therefore, I think it’s worth re-visiting Israel to see the impact that widespread immunization has had on its economy. It’s clear that Israel’s vaccination program is not only having a substantial impact on consumer confidence, but also on spending.

Israel’s data shows the impact of vaccines

While vaccinations only began in December, they ramped up quickly. As of April 4, Israel has given at least one dose of a COVID-19 vaccine to 59% of its population, with 54% fully vaccinated.1 The economic impact was seen relatively early on. As morbidity moderated, restrictions eased and the third lockdown was rolled back — and the Bank of Israel’s Composite State of the Economy Index for February increased by 0.4%.2

Mobility, which we have found to be a helpful indicator of economic activity, has increased substantially. By the end of March 2021, retail and recreation mobility (restaurants, cafes, shopping centers, movie theaters, etc.) was off by only 6% from January 2020 levels, while grocery and pharmacy mobility is actually higher than those early 2020 levels.3 And, not surprisingly, economic activity accelerated in March. Daily credit card data shows that the value of transactions for the week ending March 22 was actually 15% higher than it was in January 2020.4 By comparison, back in April 2020, the value of transactions was more than 40% below its level in January of 2020.4 The rebound in spending has been strongest in some of the areas hardest hit by the pandemic, especially leisure and tourism.

Why is this time different?

What makes this time different than past economic re-openings, like we saw in spring 2020? Before broad vaccinations, the re-opening of an economy was a double-edged sword. Typically, a re-opening would often be followed, after a lag, with an increase in COVID-19 infections. In addition, the increase in economic activity would typically be tempered because some consumers would be reluctant to go out and spend despite the re-opening because of health safety concerns.

I believe this time is different because vaccinated consumers will be more likely to re-engage in pre-pandemic economic activity and, according to medical research, should be well protected against COVID-19 — so spending should not be tempered as in past re-openings. Israel’s re-opening is already proving that vaccinations are leading to an uptick in consumer activity, and they haven’t seen another wave of COVID-19 infections.

A preview of what’s to come in the US and UK?

In my view, Israel’s current state illustrates what we can soon expect in countries such as the United States and then the United Kingdom — and in any country once it has achieved broad vaccination of its population. In the United States, 31% of the population has received at least one dose of a vaccine, and 18% have been fully vaccinated.1 In the United Kingdom, 47% of the population has received at least one dose of a COVID-19 vaccine, although only 7.8% of the population is fully vaccinated.1

The US economy is already seeing significant improvement, further helped by fiscal stimulus. For example, the March employment situation report saw a far-better-than-expected increase in non-farm payrolls at 916,000.5 And we just got the ISM Services PMI for March, which was also far better than expected, clocking in at 63.7 with all 18 services industries reported growth.6 The only problem is that COVID-19 infections are on the rise in some states in the US, so vaccinations will need to maintain momentum in order to slow and ultimately stop the rise in infections.

The UK is a bit more complicated and hasn’t shown as much improvement yet because it remains at a relatively strict level of pandemic-related lockdown, although stringency is being eased gradually.

Investment implications

I expect that rising vaccinations and improving economic data are likely to lead to a continued rise in bond yields and outperformance of smaller-cap and cyclical stocks, especially in countries that are leading the recovery.

I should add that in the US, there are a few clouds on the horizon in the form of growing fears of rising taxes. And that is likely to be the case for a number of countries burdened with higher debt levels created by the pandemic. While far from a reality at the moment, if an increase in taxes becomes more likely — especially a large increase in corporate taxes – we could see some shift in leadership, albeit modest, to larger-cap and more defensive names. However, it’s important to stress I don’t believe this would end the stock market recovery, but could just cause some rotation in leadership.

But right now, the focus is on the virus and vaccinations. As the Brookings-FT Tracking Index for the Global Economic Recovery has indicated, the ability to control COVID-19 is likely to be the main determinant of economic success in 2021.7 That is why the index shows major economies such as China and the US leading the global recovery. The index suggests that there may not be a coordinated global economic rebound, but that instead there may be a time lag for some countries, especially Europe and Latin America, given their lack of progress in vaccine rollout and general difficulties in controlling the virus. This isn’t surprising — and it’s something we anticipated last year when putting together our 2021 outlook. In other words, we believe an economic recovery is in the future for all parts of the world, but its timing and strength will be dictated by control of the virus and vaccine rollout progress, and so we will want to follow this data closely.

Key takeaways

Recent data has been positive

Mobility, which we have found to be a helpful indicator of economic activity, has increased substantially in Israel.

A preview of what’s to come?

In my view, Israel’s current state illustrates what we can expect in countries that achieve broad vaccination of their populations.

What might this mean for stocks?

I expect this economic recovery to be very robust, which may lead to outperformance by smaller-cap stocks and cyclical stocks.

Please continue to utilise these blogs and expert insights to keep your own holistic view markets up to date.

Keep safe and well.

Paul Green DipFA

07/04/2021