Team No Comments

Brooks Macdonald – The Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their discussions on the US inflation report. Received this morning 15/10/2026.

What has happened?

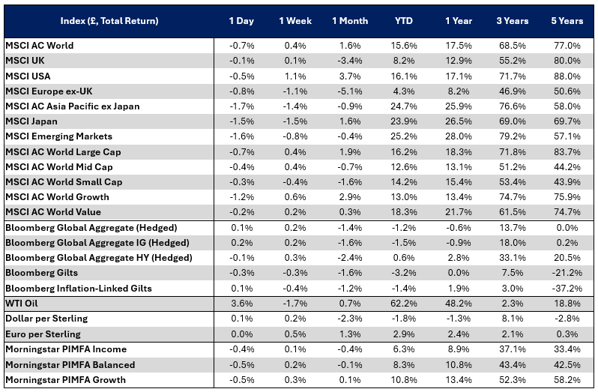
A stronger-than-expected US inflation report initially pushed Treasury yields sharply higher and reignited fears of further Federal Reserve tightening. The 10-year Treasury yield briefly reached 5.33% before reversing to close at 5.19%, and has fallen a further 8bps overnight to around 5.10%. Despite lower yields by the end of the session, risk appetite weakened, with the S&P 500 falling -1.11%, its worst day since July. European markets was more resilient, with the STOXX 600 rising +0.43% and the FTSE 100 +0.70%.

US inflation above expectations

Headline CPI rose +0.65% m-o-m, lifting the annual rate to +3.7%, while core CPI increased +0.34%, pushing the y-o-y measure to +2.6%. Importantly, the upside surprise extended beyond energy prices, suggesting inflationary pressures were broad-based across the economy. Markets initially responded by sharply increasing the perceived likelihood of another Federal Reserve rate hike, with October hike expectations briefly rising above 50%. However, those moves largely reversed as investors shifted their attention to growing concerns around economic growth and tighter financial conditions. High-yield credit spreads widened to their highest level since March, highlighting a more cautious backdrop beneath the surface.

The AI trade faces a reality check

The sell-off in AI-related assets accelerated yesterday as investors scrutinised the sector’s heavy capital spending requirements and reliance on financing. The Philadelphia Semiconductor Index declined -4.30%, marking its sixth consecutive daily loss and leaving it down more than -11% over that period. The sell-off has continued into Asian trading this morning, with the KOSPI (-7.04%) and Nikkei (-5.08%) among the hardest-hit markets, while semiconductor leaders such as SK Hynix and Samsung also recorded sharp declines.

What does Brooks Macdonald think?

Yesterday’s market moves highlight the competing forces currently driving investor sentiment. On one hand, the inflation data suggests central banks may have less scope to ease policy than markets had hoped. On the other, growing concerns around the AI sector and broader financial conditions are raising questions about the strength of future economic growth. The sharp fall in Treasury yields after their initial post-CPI surge suggests investors are becoming increasingly focused on the economic consequences of tighter conditions, rather than inflation alone. Looking ahead, today’s US PPI inflation release and UK GDP data will provide further insight into the balance between inflationary pressures and economic momentum.

Bloomberg as at 15/10/2026.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

15/10/2026

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 13/10/2026

What could U.S. midterms mean for investors?

The Democrats are expected to win seats in the upcoming elections, which could affect economic priorities.

Key highlights

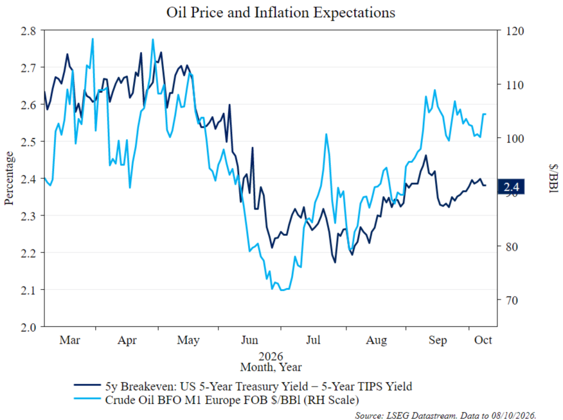
  • Oil and geopolitics: Brent crude pushed back above $103 per barrel as energy prices remain the dominant cross-asset driver, keeping inflation pressure alive in bond markets.
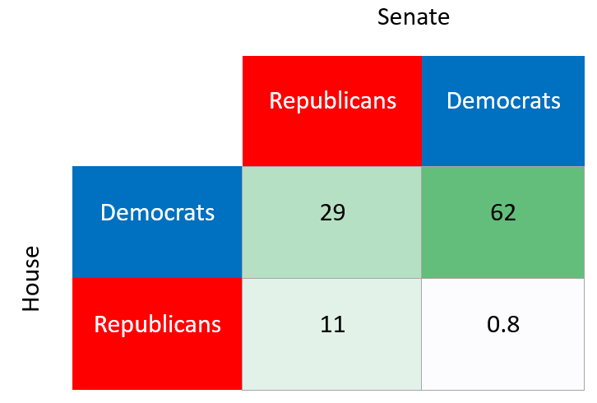
  • U.S. midterm elections: Prediction markets give Democrats near-certainty of taking the House of Representatives and a 65% chance of the Senate, signalling legislative gridlock ahead.
  • Labour market: Employers are holding onto staff while employees aren’t moving – a signal of job insecurity rather than weakness, which is helpful for the inflation outlook.

Oil still calls the shots

Energy and geopolitics continue to set the tone across every asset class and last week offered a textbook illustration.

Brent crude pushed back above $103 a barrel after reports that the White House asked the Pentagon to draw up strike options against Iran that could be implemented before the midterms. With energy prices anchored at these levels, inflation remains the dominant cross-asset driver and the pressure has been felt in bond markets, where yields have reached multi-decade highs.

The conflict has also widened. Houthi attacks have reached Saudi airports, including strikes on Riyadh’s main international airport, which killed three people and injured dozens more. Iranian attacks on shipping have stepped up, even as flows through the Strait of Hormuz have shown some signs of improvement.

None of this is accidental. With the midterms less than a month away, the political pressure on the Trump administration from that quarter is at or around its peak, so it’s entirely rational for Iran to be as antagonistic as it can be while its leverage lasts.

That calculation cuts both ways, and by the close of the week it had produced something closer to a thaw. By the end of the week President Trump confirmed he won’t conduct further military action ahead of the midterms and that productive discussions are ongoing.

It’s fair to say that the administration’s commentary on the state of negotiations should be met with a degree of scepticism, but they’re signalling to Iran that they do not consider that they will accept heavier losses in the midterms rather than softening their negotiating stance. Once the votes are counted, Iran’s perceived leverage diminishes, which could prompt either side to re-evaluate their position. Oil prices are modestly lower as a result, which is where last week left us – a little relief, no resolution.

Midterms

Looking in more detail at the U.S. midterms, there are a few things to observe. It’s normal for a sitting president’s party to lose seats. The president is not on the ballot, but his popularity affects the 435 races in the House and the 35 in the Senate.

Prediction markets now give the Democrats a virtual certainty of taking the House and a 65% chance of winning the Senate as well. The bottom line is that once the new Congress is sworn in on 3 January, there will be major constraints on the president’s ability to guide domestic policy.

The prediction market implied chances of each party winning each chamber of Congress

Source: Kalshi

Three consequences follow. Legislative gridlock is the first: given how far apart the two parties have become ideologically, little of consequence will pass beyond what is strictly necessary.

The second is fiscal. Brinkmanship becomes a feature of divided power in the U.S. Last year’s reconciliation bill lifted the debt ceiling from $36tn to $41tn, and over half that additional capacity has already been used. The limit is expected to be reached in the spring of 2027, after which accounting measures could extend it for roughly six to nine months.

Shutdowns and debt ceiling negotiations have tended not to have a big impact on markets but chip away at the global investors’ ebbing willingness to finance the U.S. More immediately the Trump administration will need a budget and will want more military spending, but the Democrats will have a voice in those negotiations and are likely to demand more healthcare funding. That should eventually be good for the healthcare sector, which already benefits from longevity and from AI’s ability to reduce costs. It is unlikely to address the issue of America’s rising debt-to-GDP.

In 2011, a standoff was resolved two days before the deadline and contributed to a downgrade of the U.S. credit rating; in 2023, Republicans extracted substantial spending concessions while controlling only one chamber.

The third consequence is investigations: committee control, subpoena power and the ability to sue in court would all shift to the Democrats. Two areas are largely untouched. Foreign policy remains the president’s to direct, including command of the military and trade negotiations.

Appointments are the live question.

Jerome Powell has not vacated his seat on the Federal Reserve’s (Fed) board, having said he would stay until the investigation into the renovation cost overruns was well and truly over. The Fed’s internal watchdog found mismanagement but no criminal violations, and the Justice Department won’t reopen a criminal case, though the attorney general hasn’t closed the door entirely. That falls short of Powell’s test, so he will most likely stay for now. If the Democrats took the Senate, they would be able to block his eventual replacement, which most observers would regard as good news for Fed independence.

Equity returns in the year after a midterm has historically been the strongest of the presidential cycle, however the same logic would suggest we’re currently in one of the weaker years of the cycle, so it seems like the normal pattern hasn’t been in place this year. Furthermore, we’re always conscious that a six-foot man can still drown in a river that’s five feet deep on average.

Low hire, low fire

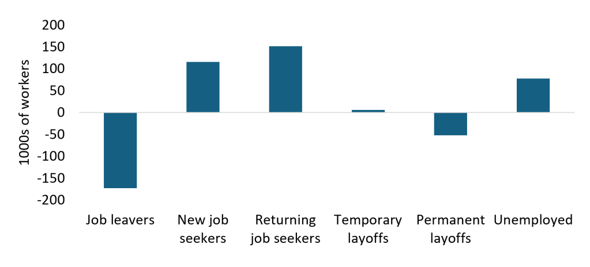
Unemployment rose during September because more people looked for work despite

fewer people quitting or being laid off

Source: LSEG Datastream

The American labour market is sending a consistent and rather particular signal: employers are content to hold onto staff and employees are not looking to move. The payroll report showed job growth below the pace needed to keep unemployment stable and the rate duly ticked up to 4.2%. But the rise came mostly from people entering or re-entering the workforce, not from layoffs – which barely show up in the data. Voluntary departures, meanwhile, fell sharply.

Jobless claims last week were similarly benign. What that describes is a prevailing sense of job insecurity, not outright weakness.

For inflation, this is helpful. Wage growth has continued to slow, which has taken the heat out of inflation expectations – a process that has been running since the end of April, interrupted only recently by higher energy costs.

Growth is cooling gently rather than stalling: the Atlanta Fed’s running estimate of consumption growth has slipped from 2.8% to 2.2%, and the September services surveys showed the global sector still expanding, with Europe accelerating and the UK expanding more slowly. The U.S. picture is muddier, with the ISM manufacturing index reading more sedate than the S&P version. On this occasion we’d lean towards the ISM, since a sharp jump in American activity last month looks implausible.

Three hikes priced, one forecast

The minutes of the latest Fed meeting showed a committee that agreed on the destination, but not the route. Members voted unanimously to raise rates, yet gave clearly different reasons for doing so, which does nothing to clarify where policy goes next. The Fed chair’s reluctance to offer forward guidance leaves markets to work it out for themselves, and they’ve taken a hawkish view.

From a base rate of 4%, markets now discount up to three further increases. Professional forecasters, weighted towards the most recent estimates, expect just one, unwound towards the end of next year. That’s a wide gap and one of the more consequential disagreements in markets today.

The cost of money is also being allocated with more discrimination. Sovereign bond markets have been weak but bifurcated, with strong credits holding up and weaker ones punished. France stands out as the weakest of them all, with French government bonds underperforming the broader market and the euro soft.

Emmanuel Moulin, France’s representative on the European Central Bank’s (ECB) governing council, described the situation as complicated and serious while making clear it doesn’t warrant intervention from Frankfurt. History suggests the ECB has found reasons to step in before and has shown some ingenuity in explaining why such action isn’t a fiscal measure. More stress would usually be needed to trigger such a move, but Christine Lagarde confirmed late last week that the ECB has the tools ready if needed.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

14/10/2026

Team No Comments

WH Ireland – The Daily Update | The Confidence Gap

Please see the below article from WH Ireland discussing weak US consumer confidence despite resilient growth and the potential midterm impact, received today – 13/10/2026.

With the US midterms only three weeks away, the economy is becoming a defining political issue. The University of Michigan’s preliminary October survey puts consumer sentiment at 46.3, down 3.7%mom and 13.6%yoy. More strikingly, its Current Economic Conditions Index plunged 12.2% to 44.7, a record low. The headline reading is also approaching May’s all-time low of 44.8. The figures capture a widening disconnect between economic activity and how households experience it.

The deterioration is not simply about slower growth. It reflects the cumulative burden of higher prices, expensive borrowing and renewed energy costs. Inflation may rise or fall from month to month, but lower inflation does not mean prices return to previous levels. Households are still paying more for everyday essentials, while elevated mortgage rates and housing costs make financial progress harder. Recent US data suggest real wage growth has weakened, compounding the squeeze on purchasing power.

There is also a growing divide between those benefiting from rising asset prices and those relying primarily on earned income. Strong equity markets and technology investment have supported aggregate wealth and consumer spending, but those gains are unevenly distributed. Households with substantial investments may feel more secure; those with limited savings have less protection against higher fuel bills, food prices and borrowing costs. This helps explain how spending can remain resilient even as consumer confidence approaches historic lows.

Inflation expectations add another complication. One-year expectations rose from 4.6% to 4.7%, while five-year expectations increased from 3.4% to 3.5%. Both are above their respective ranges in 2024. These are survey expectations, not forecasts of actual inflation, but persistently elevated readings matter because they can influence spending decisions and complicate the Fed’s task. With energy costs rising amid the Iran conflict, policymakers face the risk of renewed inflation pressure just as households are expressing deep dissatisfaction with current conditions.

The political implications are significant, particularly as independent voters become an increasingly important force in US politics. Gallup found that a record 45% of US adults identified as political independents in 2025, making them the largest group by political affiliation. Their influence is especially pronounced in closely contested races, where relatively small shifts in support or turnout can prove decisive. The latest University of Michigan survey adds to the challenge for incumbents: sentiment among independents deteriorated further in October, even as it improved among Republicans and Democrats. While this does not necessarily translate into a change in voting intentions, it suggests that economic dissatisfaction is extending beyond traditional party loyalties.

More concerning is the possibility that weak sentiment reflects a deeper and more persistent erosion of confidence, rather than a temporary reaction to one month’s data. If household purchasing power remains under pressure while asset price gains disproportionately benefit wealthier Americans, robust headline growth may do little to improve how the economy feels for many voters. As the midterms approach, the question is no longer simply whether the US economy is growing, but who is benefiting from that growth, and whether the gains are reaching the households whose votes could prove decisive.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

13th October 2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing how high bond yields are pressuring AI markets, non-AI businesses and French fiscal policy, received this morning – 12/10/2026.

Bond yields put the AI trade on notice
US tech stocks still dominate and lead higher as we start this week, having ended last week’s choppiness positively. Developments involving conflicts in Ukraine and the Middle East are much in the news but the net effects may have offset each other. Oil prices and bond yields are unchanged from the Friday closing level.

Chip manufacturers were rattled by an apparent misreading of OpenAI’s revenue but quickly recovered once the story’s source intervened. The recovery was encouraging, but it’s a reminder that much of investors’ AI optimism rests on poorly understood, industry-specific ‘compute’ metrics.

The fragile mood is partly because equity investors are looking nervously at high bond yields. Investors aren’t yet tempted to swap stocks for bonds, but we might be approaching the ‘hurdle rate’ that changes the equation: 10-year US inflation-linked bonds now yield a government-guaranteed 3.2% above inflation. Anecdotally, we hear that short-term credit instruments are struggling to compete with that offering.

That’s not hitting share prices yet and it might never – considering that the AI growth story promises to deliver much greater returns. But high yields hurt companies in other ways too, most notably now in credit spreads. They’ve risen sharply amid the AI borrowing spree, exacerbated by SpaceX’s $40bn bond issuance. Investors don’t like that AI firms keep borrowing even as costs rise, and there’s a risk that those fears spiral.

Still, underlying credit metrics are healthy: default rates are rising but only mildly. Credit spreads also spiked after 2025’s “Liberation Day” tariffs and the US-Iran war, but quickly recovered. Higher credit spreads put pressure on equity valuations, but we shouldn’t overstate it.

Liquidity conditions are key, and those are influenced by investor sentiment. Geopolitical risks make that sentiment fragile, but the mood should be bolstered by strong expected Q3 earnings. The billions AI firms have borrowed but not yet spent should support liquidity too.

Earnings have outpaced share prices this year, meaning lower valuations. Arguably, markets have already priced in some slowdown. If they’re right, yields should fall. But the tug-of-war over growth and yields means equities need to deliver strong earnings – or stall.

AI crowds out investment
AI stocks keep climbing even as bonds and non-AI equities struggle. Tech firms’ insatiable capital appetite is powering markets and the economy, but it’s also pushing up borrowing costs for everyone else. Some commentators call this ‘crowding out’. Crowding out is typically a charge levelled at governments – the theory that higher government borrowing and spending raises interest rates and prevents private sector firms from investing in their own growth.

Goldman Sachs and Absolute Strategy Research (ASR) downplay the AI crowding-out story. ASR point out that yield rises have been uniform – rather than concentrated on areas with high tech issuance. Instead, ASR blame resilient growth in the face of high energy prices.

We think that misses the point; growth is resilient because of the AI investment boom. The benefits of that growth have been mainly concentrated on tech firms, but the drawbacks (higher rates) are felt everywhere. Outside the US, where AI investment is lower, growth has been much weaker. Even within the US, non-AI businesses are feeling the strain: McDonald’s shares are down more than 30% from February’s peak. The fast-food giant’s consumers are struggling just as its financing costs for new equipment are rising.

This is really just last year’s ‘K-shaped economy’ story wearing a new name: tech does fine, everything else has a harder time. Crowding out is only a problem for those being crowded out, so AI firms and their investors won’t complain yet. But the risk is that this comes back to bite the winners themselves.

AI firms’ borrowing costs jumped last week, suggesting they’re not as rate-proof as assumed. They may therefore have to slow their issuance. That’s normal, but markets’ heavy concentration in a handful of AI names makes any slowdown more dangerous than it should be.

High French bond yields force fiscal discipline
Protestors in France are angry about state underfunding. At the same time, the government wants tighter fiscal policy. That’s about the harsh conditions that high bond yields impose.

France’s fiscal position remains fragile: debt-to-GDP is close to 120%, and the deficit-to-GDP was 5.4% last year. Yields on French government bonds (OATs) have risen sharply, and our measure of fiscal risk (yields compared to bank swaps) is higher for France than other G7 nations. The French public is clearly unhappy with the current tax-and-spend mix, but OAT investors think it’s already too generous. As the FT put it, France is caught “between the bond markets and the barricades” ahead of next April’s presidential election.

We argued before that it’s difficult for French leaders to push for fiscal discipline, so it was interesting to see Marine Le Pen argue for exactly that. She wants a 3% deficit by 2030 and a “golden rule” capping debt at 60% of GDP. Those savings are unrealistic: she’s opposed pension reforms before (the single biggest spend) and her plan for cutting EU payments would likely hurt French farmers. But the pitch itself is significant, signalling a break from the high-spending brand of right-wing populism she’s campaigned on in the past.

We think there’s a shift to fiscal discipline happening across the political spectrum, and not just in France. This doesn’t have to mean spending cuts; tax rises could also close the funding gap. The shift isn’t because Le Pen or others suddenly had a change of heart, but because bond yields are so high. As we see in the UK, the primary impact of fiscal expansion now is to simply raise debt costs, wiping out the benefit of extra borrowing.

Bond investors haven’t had much good news lately, but the effectiveness of bond vigilantes themselves lowers the fiscal risk.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

12th October 2026


Team No Comments

Brooks Macdonald | Daily Bulletin

Please see below, Brooks Macdonald’s Daily Investment Bulletin which provides a brief analysis of the key factors currenting affecting global investment markets. Received today – 09/10/2026

What has happened?

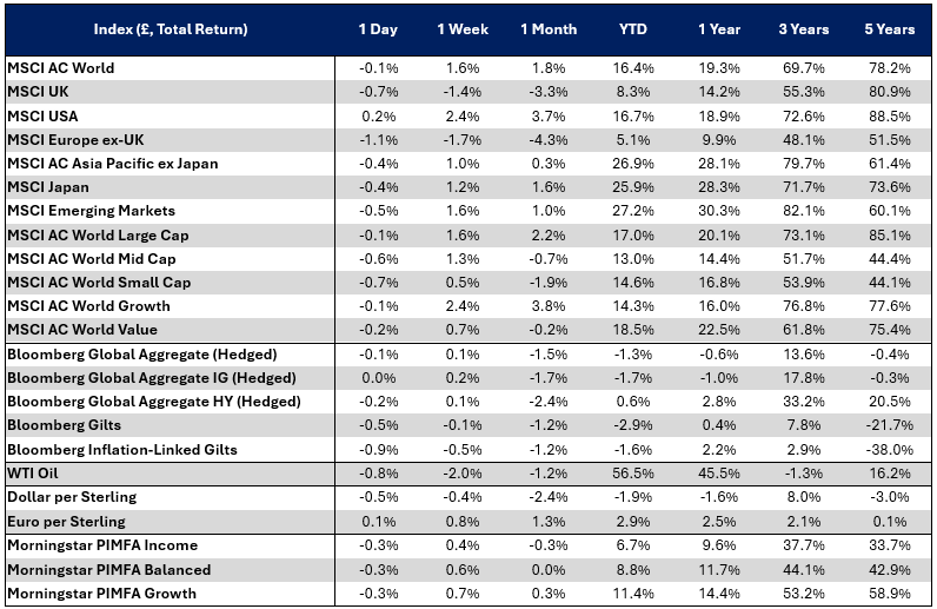
Markets remained under pressure as higher oil prices renewed concerns about inflation and interest rates. Brent crude briefly approached $106/bbl amid ongoing disruption to shipping through the Strait of Hormuz and escalating Middle East tensions, before easing back after President Trump stated that the US would not attack Iran before November’s midterm elections and described discussions with Tehran as productive. Nevertheless, investors continued to price in the possibility of a more prolonged period of elevated energy costs. European assets bore the brunt of the move. The STOXX 600 fell to its lowest level since June, while bond markets remained sensitive to inflation concerns and fiscal risks, particularly in France. UK gilt yields reached fresh post-2007 highs, reflecting a global repricing of inflation and policy expectations. In the US, Treasury markets stabilised following strong auction demand and softer oil prices late in the session, with the 10-year Treasury yield ending lower despite earlier testing multi-decade highs. Economic data continued to point to labour-market resilience, with US jobless claims falling to 197,000, reinforcing expectations that central banks still have room to prioritise inflation.

Oil Shock Meets Tight Monetary Policy

The latest market volatility highlights a familiar but important tension; financial conditions are tightening while energy-driven inflation risks are re-emerging. While bond markets have periodically rallied on concerns that higher yields or market stress could slow growth, policymakers continue to stress that inflation remains the primary challenge. Recent comments from Federal Reserve officials, alongside ECB and Bank of England communications, suggest that further tightening remains possible even as markets digest higher borrowing costs. The interaction between energy prices, inflation expectations and policy rates remains one of the key drivers of cross-asset market performance. 

What does Brooks Macdonald think?

The market reaction reflects a growing recognition that inflation risks have not disappeared. While oil prices have retreated from recent highs and diplomacy may limit near-term escalation with Iran, disruptions to global energy flows continue to warrant close monitoring. Importantly, resilient economic data reduces the urgency for central banks to pivot towards easier policy. For investors, the key question is whether higher energy prices prove temporary or become embedded in inflation expectations. While elevated yields are creating a more attractive opportunity set within fixed income, they also raise the hurdle rate for equity valuations. We continue to see broadly resilient economic growth and healthy labour markets as supportive for risk assets, but the combination of geopolitical uncertainty, elevated oil prices and restrictive monetary policy is likely to keep market volatility elevated in the near term.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

9th October 2026

Team No Comments

Brooks Macdonald – The Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their discussions on French fiscal market pressures. Received this morning 08/10/2026.

What has happened?

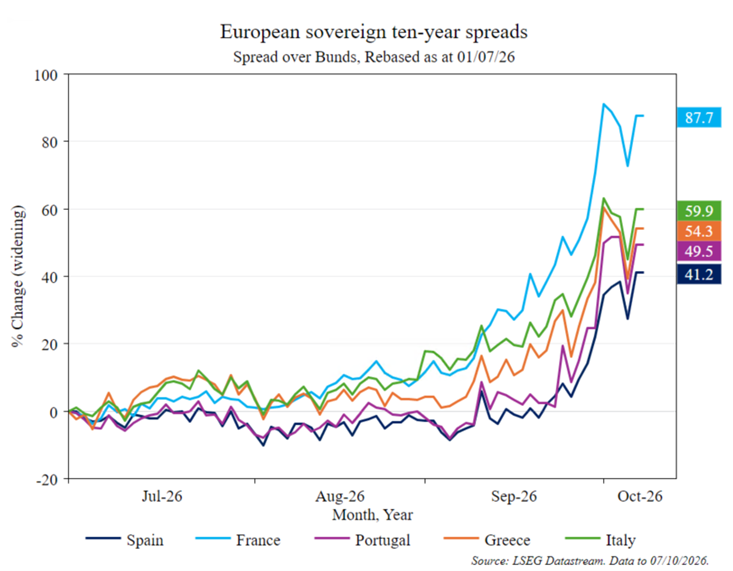
Global markets weakened as renewed French fiscal concerns and rising energy prices pushed government bond yields higher. France’s 10-year yield rose to 4.86%, widening its spread over German Bunds by 12 basis points, while selling extended to Italian debt and UK gilts, where the 10-year yield reached a post-2007 high. European equities fell sharply, led by banks, while the euro weakened against the US dollar. US equities retreated modestly from record highs, although weak market breadth and a four-month low for smaller companies indicated greater pressure beneath the headline indices. US Treasuries stabilised following a strong 10-year auction, but longer-dated yields remained elevated. Oil prices also rose overnight as tensions involving Iran and the Strait of Hormuz intensified.

Fiscal and energy risks collide

The combination of sovereign-debt concerns and higher energy costs presents a difficult policy trade-off for Europe. France’s deteriorating fiscal position has increased the risk premium demanded by investors, while contagion into Italian and Spanish bonds suggests that markets are testing the credibility of the wider euro-area framework. At the same time, Brent crude above $100 a barrel and rising European gas and diesel prices are adding to inflation expectations. This leaves the European Central Bank balancing persistent inflation against tightening financial conditions and weaker risk appetite. Although direct intervention remains unlikely while the disruption is viewed as primarily country-specific, a broader deterioration in market functioning could alter the policy response.

What does Brooks Macdonald think?

The latest moves reinforce the importance of balancing economic resilience against a less supportive valuation and interest-rate backdrop. Elevated bond yields and geopolitical risks may continue to challenge highly leveraged companies, rate-sensitive sectors and governments with limited fiscal flexibility. However, stronger starting yields also improve the prospective income available from high-quality fixed income, while robust corporate earnings should provide some support for equities. We therefore favour maintaining diversified exposure rather than reacting to short-term volatility, with an emphasis on balance-sheet quality, sustainable earnings and selective duration. Key risks include further escalation in the Middle East, a broader spread of French bond-market stress and evidence that higher energy costs are becoming embedded in inflation expectations.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

08/10/2026

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 06/10/2026

Will the Federal Reserve raise rates?

Softer U.S. economic data may have lowered the probability of a rate hike to 20%, but the inflation debate is far from over.

Key highlights

  • The shadow of the Iran war: Energy prices and bond markets moved on signs Tehran may allow nuclear inspectors back.
  • French fiscals: A 2027 budget deficit of 5.4% of GDP tests EU limits amid contentious spending cuts.
  • U.S. labour data: The September jobs report came in below expectations, easing interest rate hike fears.

Europe’s bonds buffeted by foreign affairs

The U.S.-Iran war continues to cast a long shadow over European markets, and it’s increasingly dictating economic policy rather than merely disturbing it.

High energy prices have pushed inflation up and growth down across the continent, which makes the arithmetic of already strained public finances considerably harder. Chancellors and finance ministers are drafting budgets around a variable none of them control.

The news continues to ebb and flow as Iran appears to have offered to allow nuclear inspectors back into the country. This is a genuine concession rather than a repackaged proposal, like the one President Donald Trump dismissed at the start of last week – and perhaps the first hint that Tehran’s position is weaker than its rhetoric.

Energy prices fell on the news and bond markets rallied modestly. The U.S. has also deployed another carrier group to the region, though it won’t arrive until after the midterms – so whether it represents a potential military escalation or an idle threat is a matter of pure speculation.

The electoral clock is the live variable. Prediction markets now give the Democrats roughly a 62% chance of taking both chambers – the Senate and the House of Representatives – of the U.S. Congress.

A president who could get petrol flowing again at a sensible price would materially improve the Republicans’ chances, but it would need to happen very soon to reach household budgets in time. That’s precisely why the Iranians may judge their leverage to be at its peak right now.

For portfolios, energy remains the swing factor behind inflation and, therefore, interest rates.

The British Retail Consortium’s shop price index came in below expectations, a tentative sign of easing pressure. But with a backlog of energy increases still to pass through, the likely direction for UK inflation over the coming months is up until second-round effects wash out.

The circle France cannot square

The French government presented its 2027 budget last week, the last under President Emmanuel Macron, with the deficit running at around 5.4% of gross domestic product (GDP) for 2026. That sits above the previous plan’s 5% target, the International Monetary Fund’s 5.2% projection, and the 3% permitted under the European Union (EU)’s excessive deficit procedure.

Brussels is expected to show leniency, largely because it has no credible means of imposing anything on a member state that represents the ‘core’ of the euro area. The cuts being proposed fall on the most contentious ground available: pensions, welfare, public sector wages and state-funded sick leave.

France’s difficulty isn’t simply that cutting is politically hard, though with the highest public spending in the G7, there’s plenty to cut. It’s that cuts large enough to matter risk reducing GDP by as much as they reduce the deficit. When calculating the debt-to-GDP ratio, this is known as a ‘denominator trap’ (where cuts shrink the economy faster than the deficit).

It adds to a vicious cycle: weak growth widens the deficit, the deficit demands cuts, the cuts meet resistance in the Assembly and then on the streets, and investors price the resulting uncertainty into yields that make growth weaker still. The spread of French 10-year yields over German equivalents is out at levels last seen during the euro debt crisis that occurred from 2009 to 2018.

Some countries can let inflation erode their debt quietly instead, running the economy a little hot and keeping real returns on savings slightly negative. The UK and U.S. did this after both world wars and Japan has done so more recently. Inside a currency union, where monetary policy is delegated to the European Central Bank, that door is largely closed.

Westminster plays for time

The above is an option for the UK if the fiscal position continues to deteriorate. For now, spreads against other major markets have narrowed, yet gilt yields are still the highest in the G7, and the external environment has been every bit as unkind here as in Paris.

However, the UK’s fiscal framework means it does start from a better position than France. With four weeks until the Budget, Chancellor John Healey’s leeway against his predecessor’s fiscal rules has been eroded again by expectations of higher interest rates.

The Labour conference responded to the fiscal challenges by deferring the toughest issues. Prime Minister Andy Burnham has signalled openness to tax rises to fund social care but ruled out acting within this Parliament. The genuinely contentious items – electoral reform, a possible path back into the EU and softening the triple lock – are being lined up for the 2029 manifesto. The triple lock change is the substantive one. Each year, the state pension has risen by whichever is the highest of earnings growth, the consumer price index or 2.5% – a ratchet that lifts both cost (to the taxpayer) and benefit (to the recipient) as a share of the economy over time.

From 2030, all three measures will survive, but the earnings leg would restore pensions only to the level earnings growth implies, rather than compounding on top of it. The Institute for Fiscal Studies greeted it as a distinctly less-bad policy than the present one, which is about the warmest reception such reforms receive.

The prime minister appears to have a reformer’s instinct but a saint’s patience. Or he’s road testing these policies before he has to commit to them. If they land well, perhaps he could be tempted into an early election given that Labour is leading in the polls, and has planned an unprecedented fiscal tightening over the remaining years of the parliament.
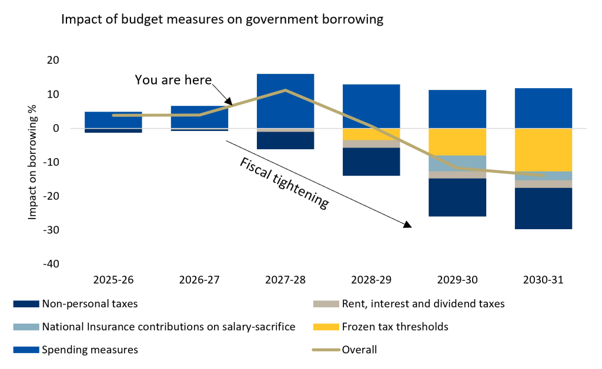
Source: Office for Budget Responsibility

One policy does arrive immediately. The ‘Your First Home’ scheme was announced at the Labour conference, with details to follow in the Autumn Budget. It’s essentially Help to Buy mark two: a government-backed equity loan of around 20% against a buyer deposit of roughly 2.5%, limited to new builds, with income and price caps still to be set. Housebuilder shares rose 10% to 15% on the news.

Goldilocks returns to the U.S. labour market

In a week full of labour market data, the general tone was one of moderate warmth. Thursday’s Challenger U.S. job cuts report generally indicated labour demand was stronger this year than last (even after stripping out government employment, which was distorted by the Department of Government Efficiency campaign).

The more interesting shift was in why companies say they’re cutting jobs. For the past five months, AI has been the single most commonly cited reason for layoffs, accounting for around a fifth of all announcements. In September, it fell to fifth place, overtaken by “economic and market conditions,” business closings, “downturn” and restructuring – all of which carry a distinctly cyclical rather than technological flavour.

It’s a small reversal, and the data only captures the slice of the jobs market covered by formal hiring and layoff announcements, but it suggests that whatever job losses are occurring right now are more about softening demand than automation.

The rest of last week’s data points were more straightforwardly reassuring. Initial jobless claims fell on Thursday. The ISM (Institute for Supply Management) manufacturing survey showed employment still expanding, albeit less enthusiastically than the PMI (Purchasing Managers’ Index) surveys had suggested. And globally, manufacturing has been expanding at its fastest pace in several years.

The JOLTs (Job Openings and Labor Turnover Survey) report added to the picture of a cooling – rather than cracking – U.S. labour market, with job openings slipping and the ratio of vacancies to unemployed workers easing further. When the September non-farm payroll jobs report itself landed, it came in below expectations, with downward revisions to prior months and softer wage growth than forecast.

For markets, whose principal anxiety has been that the Federal Reserve might hike interest rates more than expected, this was a welcome signal: a labour market losing a little momentum, without falling off a cliff, is close to the Goldilocks outcome (a market that’s not too hot and not too cool) investors want the most.

That dose of reassurance, combined with softer energy prices, took some of the pressure off bond yields and helped spark a rally across global sovereign markets. France, however, was a conspicuous underperformer.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

07/10/2026

Team No Comments

WH Ireland: The Daily Update | Saudi’s Resilient Cushion

Please see the below article from WH Ireland discussing how Saudi Arabia has emerged as an unexpected financial beneficiary of the conflict with Iran through elevated oil revenues. Received today – 06/10/2026.

While conflict in the Middle East is often framed as supply vulnerability and strategic paralysis, the economic realities tell a rather different story. As the conflict with Iran drags on, Saudi Arabia has emerged as an unexpected financial beneficiary; highlighting the strategic value of the Kingdom’s infrastructure and its position in the global oil market.

According to recent analysis by Brookings Institution economist Robin Brooks, Saudi Arabia’s annualised oil revenues have risen from a pre-war baseline of around $150 billion to approximately $210 billion. The additional $60 billion represents more than 6% of nominal GDP. Even when exports fell below 4 million barrels per day (mbpd) during the height of the conflict, Brent prices around $110pb more than offset the lost volumes. With exports now recovering towards 5.5mbpd and Brent still over $100pb the revenue uplift has become even more pronounced.


Infrastructure has been central to this resilience. Saudi Arabia’s East-West pipeline provides an alternative route to the Strait of Hormuz, while substantial storage, refining and Red Sea export capacity provide flexibility. Crucially, the Kingdom also has the financial capacity to mobilise resources and adapt infrastructure at pace; a flexibility that can be harder to replicate across many major economies, where planning, procurement and regulatory processes can extend timelines. The IMF’s latest assessment reinforces this point, describing the Saudi economy as demonstrating “agility and resilience” and highlighting the authorities’ ability to rapidly reroute oil, maximise pipeline capacity and repair damaged facilities. It also points to the Kingdom’s ample fiscal and external buffers, strong banking-sector capital and liquidity and diversified energy and logistics infrastructure.


This resilience is reflected more broadly in the sovereign credit assessment. Rated Aa3/A+, the major rating agencies continue to recognise Saudi Arabia’s substantial fiscal and external buffers and its capacity to absorb shocks. Together with the IMF’s assessment, this suggests that the Kingdom’s strength lies not simply in its ability to benefit from higher oil prices, but in its capacity to deploy capital, adapt infrastructure and absorb disruption while continuing to pursue its longer-term economic transformation.


This does not make prolonged conflict unambiguously positive for Saudi Arabia: infrastructure attacks, higher freight costs and regional instability carry clear risks. But financially, the equation is unusually favourable. Until crude prices fall significantly or a diplomatic resolution removes the geopolitical risk premium, elevated oil revenues provide Riyadh with a powerful fiscal cushion.


Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alexander James Roberts

06/10/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing bond pressures, AI-driven markets and the US midterms, received this morning – 05/10/2026.

Bonds cast shadow over equities

Global equities struggled last week. Tech stocks held, but the rest of the market dropped, on fears that AI-fuelled growth is overheating the economy. A softer-than-expected US jobs report on Friday eased those worries, and we think strong earnings growth should keep stock markets supported.

Lower oil prices would also help. Over the weekend, Saudi Arabia cut crude oil contract prices to Asia while US partners in the G7 agreed to release 100 million barrels of crude oil reserves in return for the US not banning diesel exports. Nevertheless, oil and refined product prices are slightly higher this morning after the Saudi-backed Yemeni government intensified attacks on the Houthis.

UK commentators were sceptical about by the Chancellor and Prime Minister’s conference speeches, with little sign of a positive growth agenda but at least markets aren’t worried about short-term fiscal discipline. That was enough to keep sterling firm against the rising dollar.

Financing pressures came back to bite the AI leaders themselves. Oracle’s bonds sold off after its ‘force majeure’ notice on its Project Jupiter lease – raising broader tech credit spreads. This was markets struggling to digest the sheer debt issuance, rather than actual credit stress. But credit spreads are still a problem for equity valuations: given rising real yields and credit spreads, equity valuations should probably be cheaper. That doesn’t mean stocks will sell off, but it puts more pressure on AI firms to deliver strong earnings.

Weaker US core inflation would have been expected to allow real yields to edge lower but they moved higher, continuing the trend begun early in September. Strong US growth (2.4% annualised) raises the odds the Fed has to act, although a soft labour market could dampen consumer demand.

European political unrest is back in the news. Growth is being weighed down by energy prices and, particularly in France, rapidly rising financing costs. PM Lescure budget proposal on Thursday estimated a deficit fall from 5.4% of GDP to 5% but unrest among 6th form students (lycéens) has caused some investors concern that there is no political appetite for fiscal discipline. Meanwhile, the Sanchez minority government in Spain has failed to pass its housing plan after widespread protest and has therefore called an election for Sunday November 29th. The Euro slipped markedly last week and has gone further down in early Monday trading.

Higher input and interest costs appear to be causing global growth to soften, so why are yields still rising? Market strategist Ed Yardeni puts it down to the unwind of the yen carry trade – hedge funds have lost their source of cheap financing. That’s one factor, alongside AI capital demand, fiscal risk and historic bond volatility.

Hopefully, a strong Q3 earnings season will drown out the worries.

September asset returns review

September was mixed for markets. Global equities rose 0.9% in sterling terms, but bonds lost 1.7%. The aggregate equity gain hides disparities too: tech stocks powered the gains while most other indices fell. September is typically a weak month for returns, as investors return from holiday and reposition portfolios, so perhaps the volatility should be little surprise.

Government bond yields climbed to multi-decade highs, led by the US, where the 10-year treasury reached 5.3%. UK gilt yields rose more slowly than US yields for once, though that is a hollow victory as long as gilt yields keep rising in absolute terms.

Investors typically blame bond trouble on oil prices – and Middle East tensions certainly didn’t help. Iran’s ceasefire proposal eased things into the end of the month, but oil still finished 10.6% higher.

More significant than energy, though, was growth. Business surveys were strong almost everywhere, but remarkably so in the US. AI-related investment continues to power the world’s largest economy, seemingly unaffected by interest rates and energy. That mix of strong growth and sticky inflation pushed the Fed, ECB and BoJ to raise rates – and the BoE to signal a hike next month.

AI’s thirst for capital pushed up borrowing costs for everyone else, hurting UK, European and smaller US companies, as well as government bonds themselves – a kind of reverse ‘crowding out’.

China stocks lost ground yet again. High oil prices and weak Chinese demand hurt broader emerging markets, but the EM index still gained 1.5% from its dominant chipmakers.

How long can markets keep rising on the back of a narrow, AI-driven rally? The narrowing of hyperscaler credit spreads into the month end hinted that their borrowing binge may be slowing. If so, the growth and inflation outlook could look less worrisome as we head into year-end.

Do markets care about the US Midterm Elections?

Trump’s Republicans face a tough battle in November’s midterm elections. High oil prices from the president’s unpopular war (and particularly in rural Republican states, high diesel prices) have frayed the MAGA base and delivered Trump’s lowest ever approval rating. Democrats are all but certain to retake the House, while forecasters give them a slightly-better-than-even chance of winning the Senate too. Betting markets and renowned forecaster Nate Silver put the Democrats’ Senate chances even higher.

The market impacts of a Democrat victory would be marginal, but potentially meaningful. Trump would be forced to rely even more heavily on executive orders – putting him more at risk of conflict with the Supreme Court. The court already ruled against his original tariffs, and Washington’s replacement tariffs now require lengthy investigation to be implemented, rather than the president’s whim. We would not expect a repeat of last year’s ‘Liberation Day’ tariff mayhem, though impeachment or forced policy reversals remain unlikely, given Senate arithmetic.

There are risks at the extreme: if Trump attempted to cancel or overturn the election, US bonds and the dollar would likely get hit – even if he failed. We can’t rule that out, but it’s less likely than it once looked. Combative figures like Stephen Miller have lost influence, cabinet members Rubio and Vance are already positioning for a post-Trump era, and Republican lawmakers look more willing than ever before to challenge their figurehead (if only rhetorically).

The important thing for markets in the long-term is what this means for fiscal policy. Trump’s fiscal indiscipline continues to worry bond investors, but a Republican return to pre-Trump fiscal discipline after a midterm defeat could offer markets some reassurance. Don’t expect the midterms to move markets much themselves, but what comes next – a more constrained White House, and a possible fiscal rethink – could matter more.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

5th October 2026

Team No Comments

Brooks Macdonald – The Daily Update

Please see the below daily update from Brooks Macdonald detailing their thoughts on investment markets currently, received this morning 02/10/2026:

What has happened?

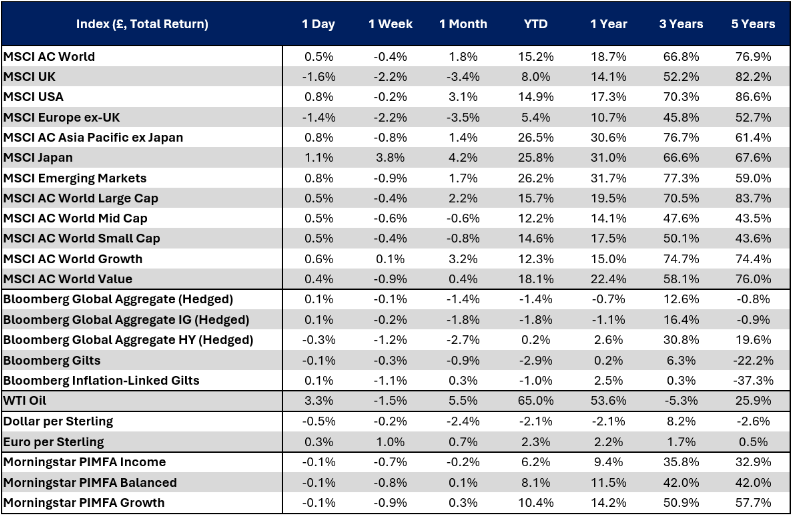
Markets endured a volatile start to the fourth quarter as concerns over European sovereign debt sustainability triggered a broad risk-off move. French and Italian government bond spreads widened sharply versus German bunds, with the Franco-German 10-year spread recording its largest daily jump since March 2020. The sell-off spread across European assets, with the STOXX Banks index falling almost 4%, European high yield credit spreads widening materially and the euro posting its weakest session against the US dollar since June. At the same time, Brent crude rose above $102/bbl amid renewed Middle East tensions and concerns over disruptions to shipping through the Strait of Hormuz, adding to inflation worries and tightening financial conditions. The US market proved more resilient. Although the 10-year Treasury yield briefly reached 5.34%, its highest intraday level since 2002, yields retraced lower as investors reassessed the likelihood of further Federal Reserve tightening. Dovish comments from several Fed officials helped offset another strong set of economic data, with jobless claims falling to a 10-week low and manufacturing surveys continuing to signal economic expansion. The S&P 500 ended higher on the day, with investors increasingly focused on today’s payrolls report as the next major test of the growth, inflation and policy outlook.

Europe’s Bond Market Stress Returns

Recent market moves highlight that concerns around fiscal sustainability are becoming an increasingly important driver of global asset prices. While higher energy prices initially pushed bond yields higher, investor attention quickly shifted towards France, where concerns over budget deficits and debt dynamics have driven a sharp repricing of sovereign risk. The widening in French spreads has begun to spill into other European bond markets, evoking memories of previous periods of euro area stress and weighing on banks, credit markets and the euro. Rising sovereign borrowing requirements across developed markets, combined with heavy corporate issuance linked to infrastructure, AI investment and energy security, are increasing the supply of long-dated bonds. This is contributing to steeper yield curves and tighter financial conditions. Paradoxically, if higher market rates perform some of the tightening normally delivered by central banks, policymakers may feel less need to raise policy rates further.

What does Brooks Macdonald think?

While market sentiment has deteriorated, we believe the message from bond markets is more nuanced than fears of an imminent crisis. Financial conditions have tightened meaningfully, particularly in Europe, and this may reduce the need for central banks to continue raising rates aggressively. We see scope for policymakers, especially the Federal Reserve, to underdeliver relative to current market expectations as inflation gradually moderates over the coming quarters. At the same time, resilient US labour market and manufacturing data suggest growth remains on a firmer footing than market sentiment currently implies. That said, we remain cautious on longer-dated government bonds given persistent fiscal deficits, rising issuance requirements and structurally higher term premia. Higher long-term yields are increasingly being felt across risk assets, although resilient earnings and economic momentum continue to provide support for US equities. In our view, volatility is likely to remain elevated into year-end, particularly around inflation and labour market data, but periods of stress should also create opportunities for active investors to exploit market dislocations.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Andrew Lloyd

02/10/2026