Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing global market volatility, Nvidia’s challenges and how stronger economic growth is supporting equities despite higher interest rate expectations, received this morning – 16/11/2026

Bumpy ride towards a better place

Given the leadership turmoil engulfing Nvidia, wider global stocks put in a decent performance through last week. Nvidia’s tumbling share price has had a relatively minor impact on overall portfolios. Chip stocks fared badly but other sectors did reasonably well amid improving expectations for economic growth and company earnings.

The UK economy grew 0.7% in the three months to September, the fastest quarterly expansion since 2024, and JP Morgan’s nowcasts imply annualised growth of around 3%. Yet again, UK growth is much better than the dour media narrative suggests. It was powered by business investment, particularly AI-related, rather than the usual consumer spending. That’s a good sign, as we might finally see growth led by service exports rather than a widening current account deficit. Stronger growth will mean higher inflation and interest rates, but high rates are manageable with growth to back them up.

Earnings are rising across most major markets, and this time it’s driven by higher revenues rather than profit margins. Companies aren’t just taking bigger slices of the pie; the pie itself is growing. Growth is the best fuel for stocks, but the accompanying rise in real government bond yields makes equity valuations less attractive by comparison. We don’t expect yields to go much higher, and higher borrowing costs should stop sentiment running too hot.

Tighter financial conditions do mean a bumpier ride. Real yields have climbed and central banks are more hawkish, leaving markets less liquid in the short term. Investors are also more prone to being spooked by geopolitics, and the Middle East limbo hasn’t gone away, with rumours of an Israeli strike on Iran. European gas prices haven’t fallen with oil either, which could mean a tough winter. Next week’s Anthropic IPO (expected Thursday) and Nvidia’s results (Tuesday night) will test sentiment, and hopefully show it remains healthy.

From Silicon Valley, with love

It doesn’t get much juicier than the Jensen Huang affair. The centibillionaire CEO of Nvidia resigned this week after admitting to two affairs, one with an alleged Chinese spy, Alice Huang (no relation), whose former company (Megaspeed) is being investigated for illegally smuggling Nvidia chips into China.

Nvidia has launched an independent investigation. The FBI is looking into it too although US intelligence has reportedly known for a while. The sticking point seems to be less about sensitive information reaching China, and more about Megaspeed: the Singapore-based cloud firm where Alice Huang once served as executive, and which is under investigation for breaching sanctions on US chip sales to China.

Nvidia shares have lost nearly 30% this month, but its troubles aren’t all about Huang’s personal life. US tech companies have struggled since early October as investors have grown more sceptical of AI’s seemingly constant earnings growth. Other big tech stocks recovered last week, but Nvidia’s fall continued.

The story isn’t terminal for Nvidia, and certainly not for the AI investment boom, but it’s clearly a headwind as Google and others try to muscle in on its core business. For broader tech companies, the bigger concern is Nvidia’s central role in financing the AI buildout. It is one of the firms earmarked for investing an extra $26bn in Anthropic at the Claude-maker’s IPO.

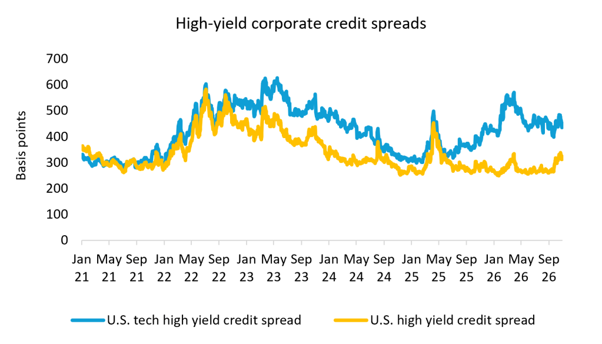
The good news there is that Nvidia’s credit spread has been remarkably stable over the week, unlike its share price. Basically, investors think Nvidia has an image problem, but not one that will stop it from paying its debts. Its borrowing costs are still cheap, well below its expected earnings growth, and it has no plans to raise equity. The Huang affair might be an embarrassment, but it’s only a disaster for Jensen Huang, not for the AI buildout.

Rate expectations pushed up by growth, not inflation

Global inflation is running hot. US consumer price inflation came in above expectations for October, just after a Federal Reserve governor warned that persistently high inflation could force a half-point rate hike next month. In the UK, NIESR predicts inflation will stay above the Bank of England’s 2% target for another four years. Commentators blame energy prices, but that doesn’t match how bond markets have moved.

NIESR forecasts UK inflation will peak at 4.4% in February 2027 and won’t fall below target until 2030, blaming “the double whammy of higher energy prices and rising global borrowing costs”. Bond markets’ implied UK inflation expectations are lower than NIESR’s, though. One reason is the sharp fall in oil prices this month.

The other reason is that NIESR expects just one BoE hike in 2027, versus more hawkish market expectations. NIESR’s dissenting opinion is odd, considering it thinks rates should be higher. Since early October, bond traders have effectively priced in hawkish central bank reactions to any growth or inflation data, dampening the longer-term inflation impacts. That goes for the US as well as the UK, which is why both US and UK breakeven yields have fallen.

Markets still see inflation above central banks’ 2% target, because they’re pricing in strong growth. A stronger-than-expected US jobs report suggests that the employment stasis we’ve noted over the last year (no hiring, no firing) has ended. Meanwhile, UK growth has consistently beaten forecasts in 2026, driven by government and business investment, mostly in AI.

That’s less positive for bonds than it looked a few weeks ago, but it’s a good mix for stocks. Capital markets can cope with higher rates as long as the global economy is strong enough to justify investment. For now, rate expectations are being held up by growth, not inflation.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

16th November 2026
Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, the ‘Daily Investment Bulletin’ from Brooks Macdonald, covering the tech-led market rebound, AI investment and upcoming economic data – 12/11/2026

What has happened?

Markets rebounded over the past 24 hours, led once again by technology stocks. Strong results from CoreWeave (+24.71%) helped lift sentiment across the AI trade, with the Philadelphia Semiconductor Index (+5.66%) driving the S&P 500 (+1.31%) higher. European equities also participated in the rally, with the STOXX 600 (+0.72%) and Germany’s DAX (+1.20%) reaching fresh records. However, volatility in the technology sector has continued this morning following reports that Nvidia’s board is considering removing CEO Jensen Huang, sending shares -8.6% lower in after-hours trading. Oil prices also recovered after two consecutive declines, with Brent crude finishing +1.2% higher despite no obvious catalyst.

Investors are still hungry for AI

Anthropic’s bankers are reportedly considering a valuation of around $1.5tn for its upcoming IPO following robust investor demand, potentially allowing the company to raise more than $100bn. Meanwhile, OpenAI reportedly generated $10bn of quarterly revenue in the three months to September, up 50% from the previous quarter and taking annualised revenue to around $50bn. Taken together, the developments illustrate both the rapid commercial growth of leading AI businesses and the increasingly ambitious valuations investors are willing to support.

What does Brooks Macdonald think?

With the US holiday limiting fresh economic data and Federal Reserve commentary yesterday, investor attention is likely to shift back towards the macroeconomic backdrop. Today’s UK Q3 GDP release will provide an update on the health of the domestic economy, while tomorrow’s US producer price inflation report could prove more consequential for global markets. Expectations for interest rates remain an important influence on equity valuations, particularly in the technology sector where recent price swings have highlighted the sensitivity of markets to changes in sentiment.


Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alexander James Roberts

12/11/2026

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 10/11/2026

Will AI stocks weather the political storm?

With U.S. midterm results reshaping the regulatory outlook, we look at whether the AI sell-off is justified.

Key highlights

  • U.S. midterm results reshape the outlook: The Democrats’ sweeping victory raises concerns over tougher AI regulation, though President Trump’s veto could mean policy gridlock.
  • AI stocks faced a sharp correction: Concerns over regulation, spending and valuations have triggered widespread selling, despite strong underlying demand.
  • The Bank of England raises rates: Interest rates increased to 4%, but falling oil prices could ease inflation pressures and limit further tightening.

Political uncertainty meets a fragile AI trade

The Democrats’ decisive victory in the U.S. midterm elections was not entirely unexpected, but the scale of the party’s success surprised markets. Taking control of both chambers of Congress – the Senate and the House of Representatives – raises the prospect of greater scrutiny of businesses, particularly AI and data centre development.

Markets initially welcomed the removal of election uncertainty, but relief quickly gave way to renewed selling of technology shares. Investors are concerned that tougher regulation could slow the extraordinary expansion of AI infrastructure.

However, President Trump retains veto power, making sweeping legislative changes difficult without bipartisan support. The result could be policy gridlock, with both sides struggling to advance their agendas.

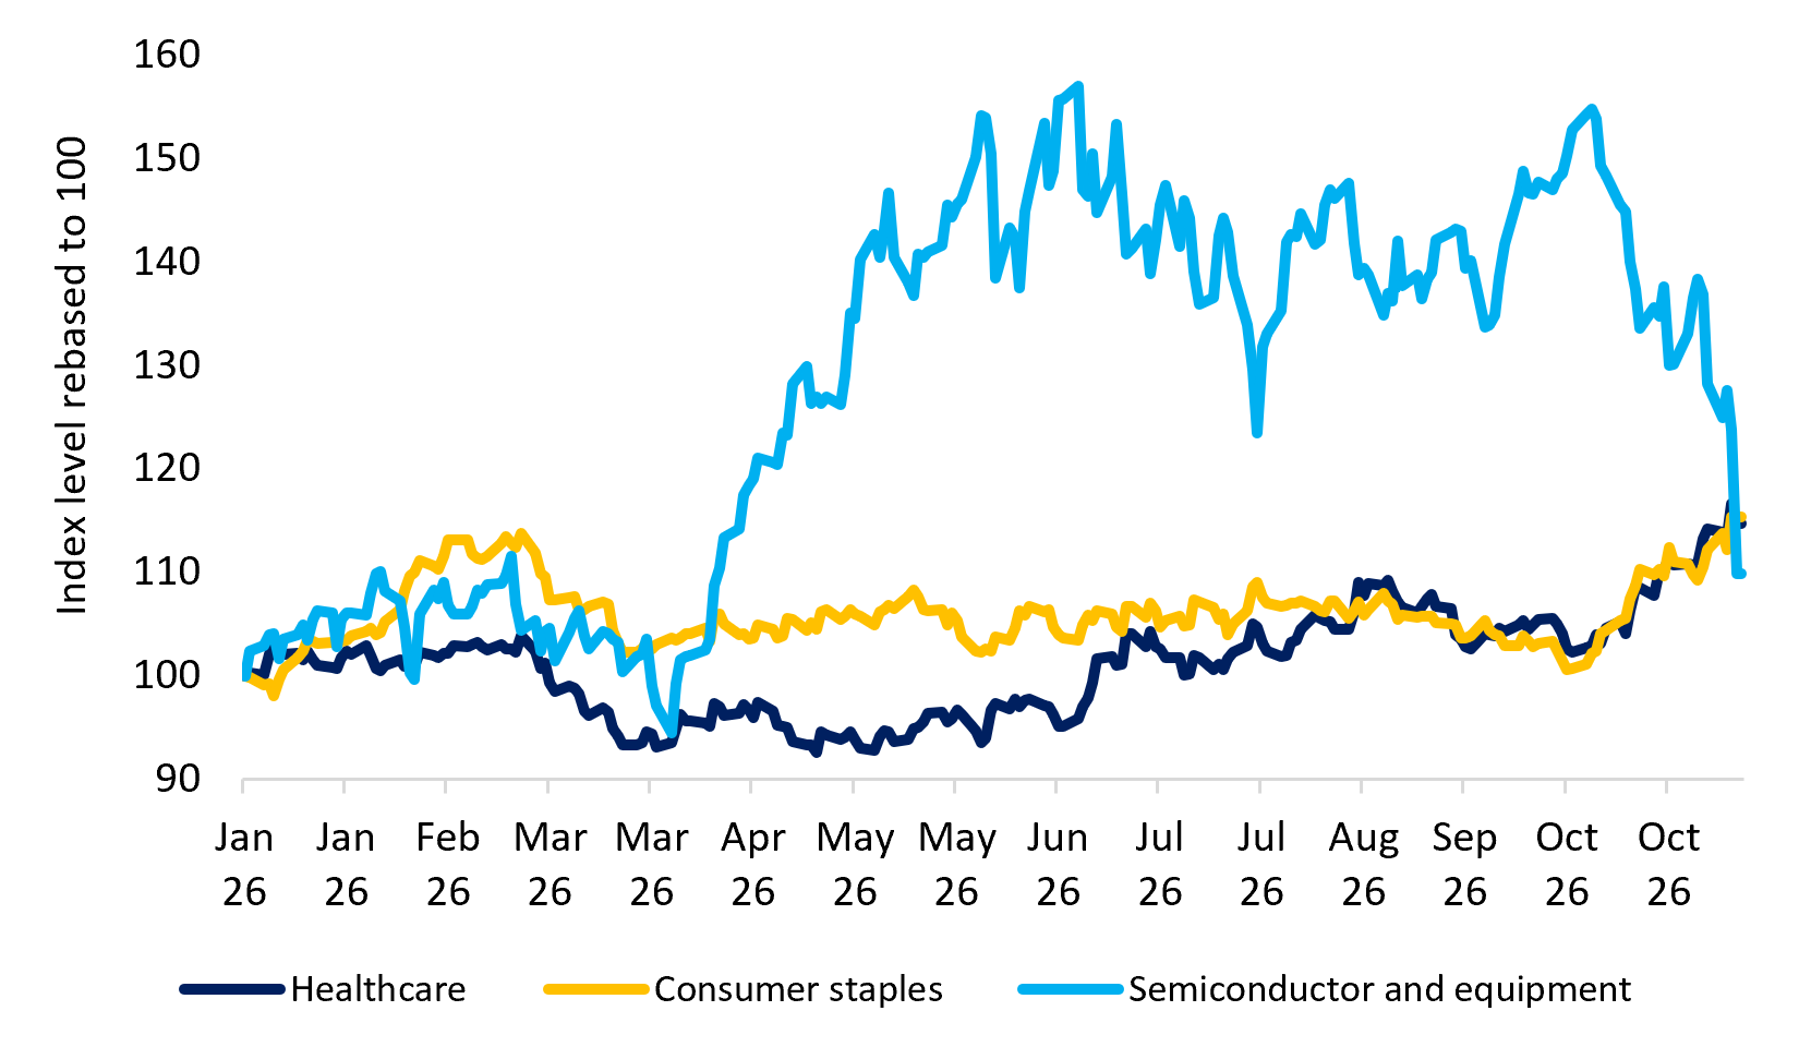
Technology shares had already been under pressure amid concerns about elevated valuations and the returns on AI spending. The subsequent sell-off spread across semiconductor manufacturers, memory suppliers and other companies supporting AI infrastructure.

MSCI World Price Index performance by sector

Source: Bloomberg

We believe the scale of selling reflects more than deteriorating fundamentals. Investors had built substantial exposure to the AI trade, and hedge funds have been reducing crowded positions. Such selling can become self-reinforcing, pushing share prices further than the underlying news might justify.

This creates considerable near-term uncertainty but does not necessarily signal the end of the AI investment cycle.

AI: Strong demand, but tougher questions

Underlying demand for AI computing power remains impressive.

Global cloud infrastructure spending reached $168 billion in the third quarter, growing 55% annually. Major providers’ order backlogs exceed $2 trillion according to contracted future revenue estimates released alongside earnings results.

The largest technology companies regard AI investment as strategically essential, and their strong balance sheets provide considerable financial flexibility.

Nevertheless, investors are increasingly questioning the returns on this extraordinary spending.

Five major technology companies have doubled their combined capital expenditure to more than $550 billion. In the first nine months of this year, they returned just 9.3% of operating cashflow to shareholders, the lowest proportion in at least 15 years.

The longer-term arithmetic is challenging. Research and advisory firm Gartner estimates cumulative AI infrastructure spending will hit $7 trillion by 2030. Generating an adequate return could require around $8.5 trillion in revenue, considerably above current forecasts.

Our assessment remains balanced. We retain a modest overweight in global equities, supported by resilient corporate earnings and strong AI demand. However, the investment environment has become more fragile, and further volatility is possible.

History suggests that positioning-driven sell-offs can overshoot. Some of the strongest market recoveries occur close to periods of greatest pessimism, making it difficult to time an exit and re-entry.

We therefore favour staying invested while making deliberate adjustments rather than reacting to every market swing. Our exposure to European equities, cash and government bonds provides valuable diversification against technology-related volatility.

Government bonds find support amid uncertainty

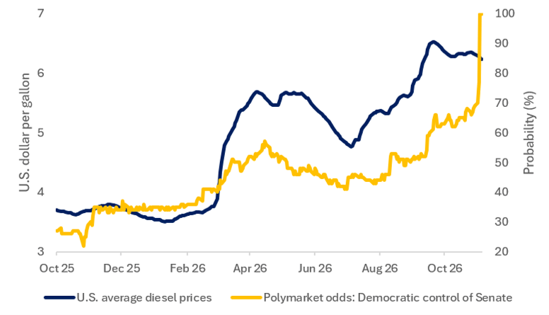
Government bonds have benefited from safe-haven demand amid equity market volatility, falling oil prices and expectations that a Democrat-controlled Congress could constrain further fiscal expansion.

Democrats’ chances have surged with the price of diesel

Source: Bloomberg

The 10-year U.S. Treasury yield has retreated from around 5.3% a few weeks ago to approximately 4.85%, supporting bond prices. Gold has also recovered to above $4,100 an ounce, helped by a weaker dollar and defensive demand.

However, political uncertainty remains. While Congress may constrain President Trump’s domestic legislative agenda, he retains substantial authority over foreign policy, particularly regarding Iran.

Diplomatic efforts continue, but the conflict remains unresolved and the risk of renewed escalation persists.

Oil prices have fallen further from their recent peak of above $117 per barrel to below $100, reflecting hopes of diplomatic progress. This offers welcome relief for inflation expectations and borrowing costs.

Nevertheless, the trajectory of energy prices remains crucial. A sustained decline would improve the inflation outlook, while renewed escalation could quickly reverse recent gains.

Central banks face a delicate balancing act

Last week, the Bank of England (BoE) raised interest rates by 25 basis points to 4%, the first increase in more than three years.

Governor Andrew Bailey explicitly linked the outlook for further tightening to the Iran conflict and energy prices. The BoE expects inflation to peak close to 5% next year, although the recent decline in oil offers some encouragement.

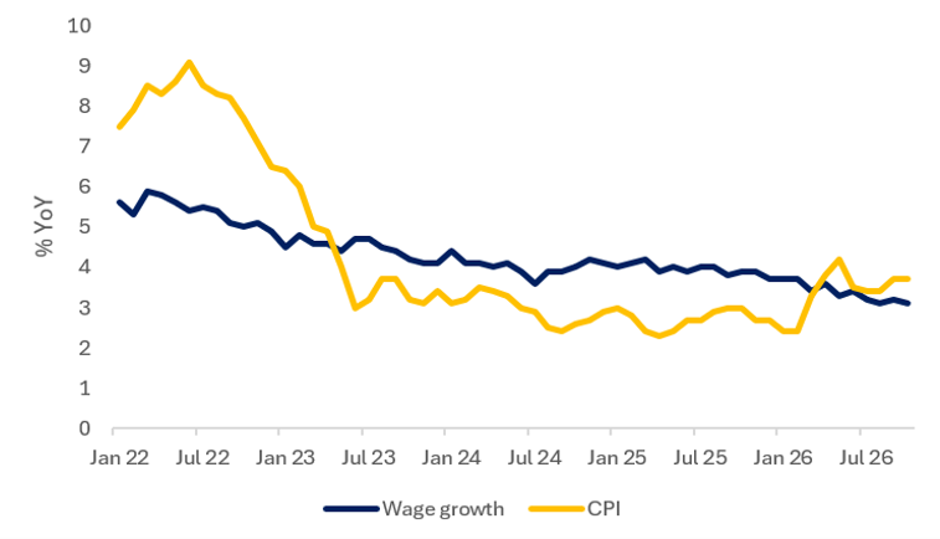
Markets anticipate three further rate hikes in 2027, but the eventual path could be less aggressive if energy prices remain lower and wage growth stays contained. So far, there’s limited evidence of a wage-price spiral.

In the U.S., October employment data showed continued economic resilience. 165,000 new jobs were added over the month, comfortably exceeding expectations of 65,000, while unemployment fell to 4.1%.

The stronger labour market marginally supports the case for further Federal Reserve tightening, though soft wage growth and the recent fall in oil prices may provide some waiting space.

U.S wage growth has not kept up with inflation recently

Source: Bloomberg

For both central banks, the key question is whether the energy shock proves temporary or feeds into more persistent inflation.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

11/11/2026

Team No Comments

WH Ireland – The Daily Update: Mind the Crack

Please see the below article from WH Ireland detailing their discussions on oil prices, notably the Diesel markets. Received this morning 10/11/2026.

Crude oil has fallen sharply since the end of October as expectations of a further escalation in the Iran conflict have eased. Yet the retreat in oil prices does not necessarily signal an end to the energy shock. Diesel markets tell a more complicated story, with refining margins remaining elevated despite the recent decline. The divergence highlights why crude prices alone can provide an incomplete picture of inflationary pressures.

The diesel crack spread measures the difference between the price of diesel and crude oil, providing an indication of refining margins and the relative balance between supply and demand for refined products. When the spread widens, diesel is becoming more expensive relative to crude, potentially signalling tightening supplies, stronger demand or constraints in refining capacity.

The scale of the recent move is significant. Before the outbreak of the Iran conflict on 28 February, the European diesel crack spread averaged approximately $31 per barrel, against Brent crude at around $69. This averaged around $45 in June, rising to approximately $72 in July and $81 in August, before approaching $98 in early September. Although margins have since retreated, they remain considerably above their earlier levels. The recent decline in crude prices has also contributed to some narrowing in refining margins, but this does not necessarily indicate that underlying supply pressures have been resolved.

Diesel is particularly important because it underpins global economic activity, powering freight transport, shipping, agriculture, construction and heavy industry. Geopolitical disruption reduced Russian and Middle Eastern exports, refinery constraints and depleted inventories have all contributed to tighter middle-distillate markets. The International Energy Agency estimates that global diesel exports in September were 700,000 barrels per day lower year-on-year, while it expects supply constraints to persist into 2027.

For the wider economy, sustained increases in diesel prices can feed into transportation, manufacturing and food production costs, extending inflationary pressures beyond the energy sector. Lower crude prices should provide some relief to headline inflation, but elevated refined-product costs could prove more persistent, particularly if businesses pass higher operating costs on to consumers.

Ultimately, the outlook will depend on whether the recent decline in crude marks a lasting easing of geopolitical risk or simply a temporary repricing, while refined-product supply remains constrained. Although inflationary pressures have not disappeared, lower energy prices offer a potential counterbalance. The balance between these competing forces will be important in determining the path of inflation, interest rates and the wider economic outlook.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

10/11/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing market volatility following the US midterm elections, October’s asset returns and why concerns over an AI bubble may be overstated, received this morning – 09/11/2026.

Sentiment rollercoaster
Thursday saw a rout in global tech stocks, on fears that Democrat victories in the US midterm elections will slow datacentre building. Indeed, US equities had their worst day since 2025’s “Liberation Day” but then recovered somewhat on Friday – helped by a stronger-than-expected US employment report. Investors are clearly anxious about the durability of AI growth, but we think the ‘AI bubble bursting imminently’ narrative is overdone.

Markets were initially positive on the midterms. Stock and bond prices gained, while oil dropped below $100pb for the first time since September. Markets were relieved that Trump didn’t challenge the results – having been more nervous about election chicanery than we realised. A ‘lame duck’ president is less able to disrupt markets, but there are still risks. Lame ducks tend to focus on foreign policy, which doesn’t bode well for the oil crisis, and an opposition Congress makes government shutdowns more likely.

Panic then spread over Democratic governors elected on anti-datacentre platforms in Texas, Georgia and Ohio. But a datacentre slowdown might not actually be all that bad for AI firms. It’s arguably what investors want: they have punished debt-fuelled spending plan announcements recently and rewarded near-term cashflow. A moratorium on new approvals would leave existing projects intact but make ‘compute’ scarcer and reduce the building costs – which would be supportive for hyperscalers’ bottom lines, but likely slow US growth.

The Bank of England raised interest rates by 0.25 percentage points and signalled more hikes ahead. Governor Bailey made it clear that global factors are dictating policy – even though those global factors (lower oil prices and US bond yields) have helped gilts recently. The fact French yields fell despite another budget failure in parliament shows that it’s often global sentiment, rather than local factors, that drives bond markets. The crucial factor is a lower risk that the AI infrastructure splurge overheats the global economy – a relief, we think, once volatility subsides.

October asset returns review
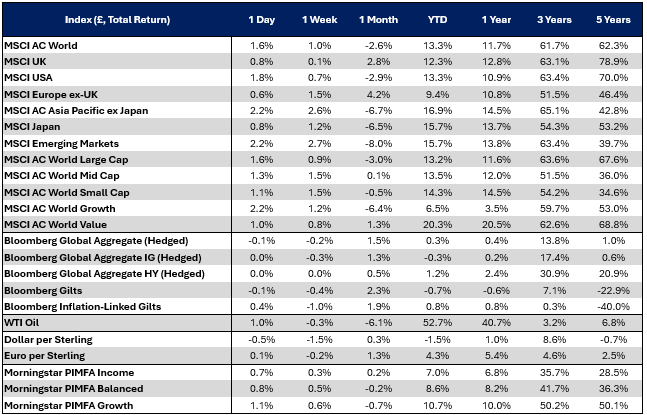
October brought a setback for equity investors, but relief for bondholders: global stocks shed 2.5% in sterling terms, while global bonds gained 1.7%. Investors finally changed their minds about the relative attractiveness of historically high government bond yields versus stocks. The strange part is that it happened despite strengthening corporate earnings and a decisive moderation in yields.

Yields had been rising since March, and we wondered when ‘risk free’ returns would be attractive enough to lure investors. The turning point came in mid-October, when a surprisingly strong US inflation report convinced bond investors that growth would tail off as the Federal Reserve was forced to raise rates. Gilt yields also fell ahead of an autumn budget that contained little new spending or revenue raising.

Investors were also moved by doubts over whether the boom in AI earnings growth can carry on. Stories about slowing demand for AI computing power spooked markets, even though other indicators show the opposite, alongside fears of debt-financed AI spending and a spike in tech credit default swaps (CDS). Higher CDS raises borrowing costs and makes tech valuations less attractive. US tech stocks lost 6.1%, Japanese shares fell 5% and emerging markets (concentrated on a handful of East Asian chipmakers) dropped 8.8%. China dropped 7.5%, though that was also about weak domestic growth.

Tech-lite equity regions fared better: European stocks fell just 1% and the UK even gained 1.3%, helped by the FTSE 100’s energy exposure. Oil prices rose 14.7% on expectations of a post-midterm US attack on Iran.

The timing of AI anxiety seemed somewhat irrational, considering the continued strength of tech earnings. We got the sense that investors were waiting until the US midterm results – and how Trump might react to them – before making any firm decisions. When Trump quickly accepted defeat at the start of November, global stocks, initially, rebounded.

Dispelling the doom
We’re increasingly fielding inquiries from clients nervous about apparently impending global disaster or collapsing share prices. Scare stories abound about global conflict, hacked supermarket fridges and a supposed ‘AI bubble waiting to burst’. We should treat these stories separately.

Downing Street’s advice to stock up on food and water was never going to calm the nerves, but it doesn’t mean war is imminent for the UK. Advanced AI models make national infrastructure attacks a greater threat, but the same frontier models that are exposing security gaps are also plugging them. AI supercharges the cybersecurity race, but doesn’t necessarily favour one side in the long-term.

Meanwhile, fears of a post-midterm election attack by the US on Iran eased this week – though Trump retains foreign policy control even after losing the majority in Congress.

Geopolitics are often the cause of investors’ concerns, but the object of them is often tech share prices. AI stocks sold off on Thursday, following Democrat victories on anti-datacentre platforms in the US midterms.

It is also worth noting that AI isn’t a bubble in the classic valuation sense at least: valuations in terms of share prices relative to corporate profits have actually fallen as earnings growth has outpaced share prices. Moreover, the proposed datacentre moratorium cuts against the previous AI earnings anxiety of (supposedly) slowing demand for ‘compute’. GPU rental prices show an undersupply in compute, and paused datacentre building would only prolong the undersupply and keep prices elevated. It would be brave to bet against AI earnings growth in that environment.

We think the fears about tech firms’ negative cashflows are also overdone. AI firms are borrowing to fund investment, as companies do, and the big names still have far less debt than most. We’re not underplaying the concerns around opaque financing agreements, but we also suspect that debt-fuelled spending will slow – precisely because investors are punishing firms for capital raising. Market collapses usually happen when undue optimism quickly reverses but, right now, there’s not enough optimism to undo.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

9th November 2026

Team No Comments

WH Ireland: The Daily Update | The Vanishing Worker

Please see below, an article from WH Ireland which discusses the upcoming US employment data and the implication for markets. Received today – 06/11/2026

The US publishes its October employment report later today, with unemployment expected to hold at 4.2 per cent. That headline has long helped guide the Federal Reserve’s assessment of pressure in the labour market. But the unemployment rate can fall because people stop looking for work, rather than because more people find employment.

Economists expect 65,000 additional jobs in the separate payroll survey. Yet jobs and workers are different things. Over the year to September, the number of jobs rose by almost half a million while the household survey recorded roughly half a million fewer people in work. How reassuring is low unemployment when fewer people are working?

The distinction starts with the arithmetic. The unemployment rate measures people without work who are actively seeking it as a share of the labour force. Retire, or abandon the search, and you disappear from both its numerator and denominator. The rate can improve without anyone finding a job. It counts unemployment among those still in the labour force, rather than measuring the proportion of Americans employed.

The annual comparisons illustrate the problem. Over the year to September, unemployment fell from 4.4 to 4.2 per cent, even as the household survey recorded fewer people in work. Both labour-force participation and the proportion of the population employed declined. The unemployment rate improved; the share of Americans working did not.

The surveys are not interchangeable. They cover different populations, household employment is volatile and population adjustments complicate annual comparisons. Someone holding two jobs can appear twice in payrolls but only once in the household employment count. That does not establish why the surveys have diverged. It does explain why additional jobs cannot automatically be equated with additional people working. Neither survey alone settles the question.

Retirement helps explain the divergence. Baby-boomer retirements and reduced immigration are slowing workforce growth, lowering the number of additional jobs needed to keep unemployment steady. Estimates vary with assumptions about immigration and participation. Nevertheless, payroll gains that once looked inadequate may now prevent unemployment from rising. Clearing that lower hurdle says less about economic strength than investors might assume.

Slower employment growth alone does not establish that demand is weakening. An economy adding fewer workers should create fewer jobs, while productivity gains can sustain output. Falling participation caused by retirement is different from workers abandoning unsuccessful searches. The question is whether recruitment is adjusting to labour supply or businesses are becoming less willing to employ available workers.

A low-hire, low-fire market makes the distinction harder to observe. Employers can retain staff while reducing recruitment, keeping unemployment subdued even as opportunities dwindle. Existing employees enjoy relative security; graduates, new entrants and job changers face a less forgiving market. Weakness appears first in the difficulty of getting hired, before it becomes visible in redundancies.

Pay growth also deserves attention. Economists expect annual hourly earnings growth to ease to 2.9 per cent. Alongside weak recruitment and any reduction in working hours, that would strengthen the case that labour demand is cooling. It would offer less reassurance about inflation driven by energy, tariffs or other supply constraints.

Higher interest rates cannot reverse retirement or replenish immigration. They can restrain spending, investment and hiring. The Fed risks applying further pressure if it mistakes labour scarcity for vigorous demand. Today’s report therefore deserves scrutiny beyond its headlines, particularly revisions, hours and participation among prime-age workers, which helps distinguish ageing from broader weakness. Low unemployment remains relevant. But when the proportion of Americans working is falling, it offers less reassurance than the headline suggests.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

6th November 2026

Alex Kitteringham

Team No Comments

WH Ireland – The Daily Update

Please see the below article from WH Ireland detailing their discussions on the US Mid Terms and the roll out of data centres within the US. Received this morning 05/11/2026.

The sweeping gains by the Democrats in both the House and the Senate look likely to slow down, if not derail, the roll out of Data Centres in a number of highly significant States.

Developers in Texas (which accounts for over one quarter of the national capacity due to come online in 2028) were already facing a suspension of approvals under Republican Governor Greg Abbott. Gina Hinojosa, elected on Tuesday as the first Democratic Governor of Texas in more than a quarter of a century, had consistently called for a moratorium during her campaign. Some 13 gigawatts of data centre capacity (enough to power around 10 million homes according to GLJ Research) is immediately exposed by Hinojosa’s victory.

Jefferies’ analyst Jonathan Petersen noted in a recent research piece that regardless of the election outcome the likelihood is tighter rules around who pays for grid infrastructure, water use and the oversight of tax incentives.

It is not just Texas. In Ohio Democrat Amy Acton defeated billionaire entrepreneur Vivek Ramaswamy and has called for an immediate conditional moratorium that requires developers to meet a series of requirements to be cleared for construction. Meanwhile Democrat Keisha Lance Bottoms, elected as Governor of Georgia, called for a moratorium on new construction of data centre sites during her campaign. Georgia has historically encouraged data centre development and is the third largest state in terms of data centre development.

Down the line this may have significant implications for the Asian tech trio of TSMC, Samsung Electronics and SK Hynix and their supply chains although one suspects that data centre developments elsewhere (India, China, ASEAN to name just a few) will offset any decline in US data centre demand.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

05/11/2026

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 03/11/2026

Are we seeing a repeat of the dotcom bubble?

The recent sell-off in AI stocks may be reminiscent of the 90s dotcom bubble, but there are important differences.

Key highlights

  • AI faces a big test: Strong tech earnings growth continues to underpin the positive view on AI-related investments, but the extraordinary capital spending and financing requirements leave little room for disappointment.
  • Credit markets are flashing caution: Widening corporate bond spreads and growing scrutiny of AI-related borrowing hurt market sentiment.
  • Central banks remain vigilant: The Federal Reserve, European Central Bank and Bank of Japan all held interest rates in October, but inflation pressures mean further rate rises remain possible.

The ghost of 1999

With the largest AI companies reporting earnings last week, we ask a common question amongst our clients: is today’s AI-driven rally a rerun of the late 1990s technology bubble? Our answer is that the comparison is useful but not decisive. Some indicators look healthier than they did then. Others look much the same, and a few look more stretched.

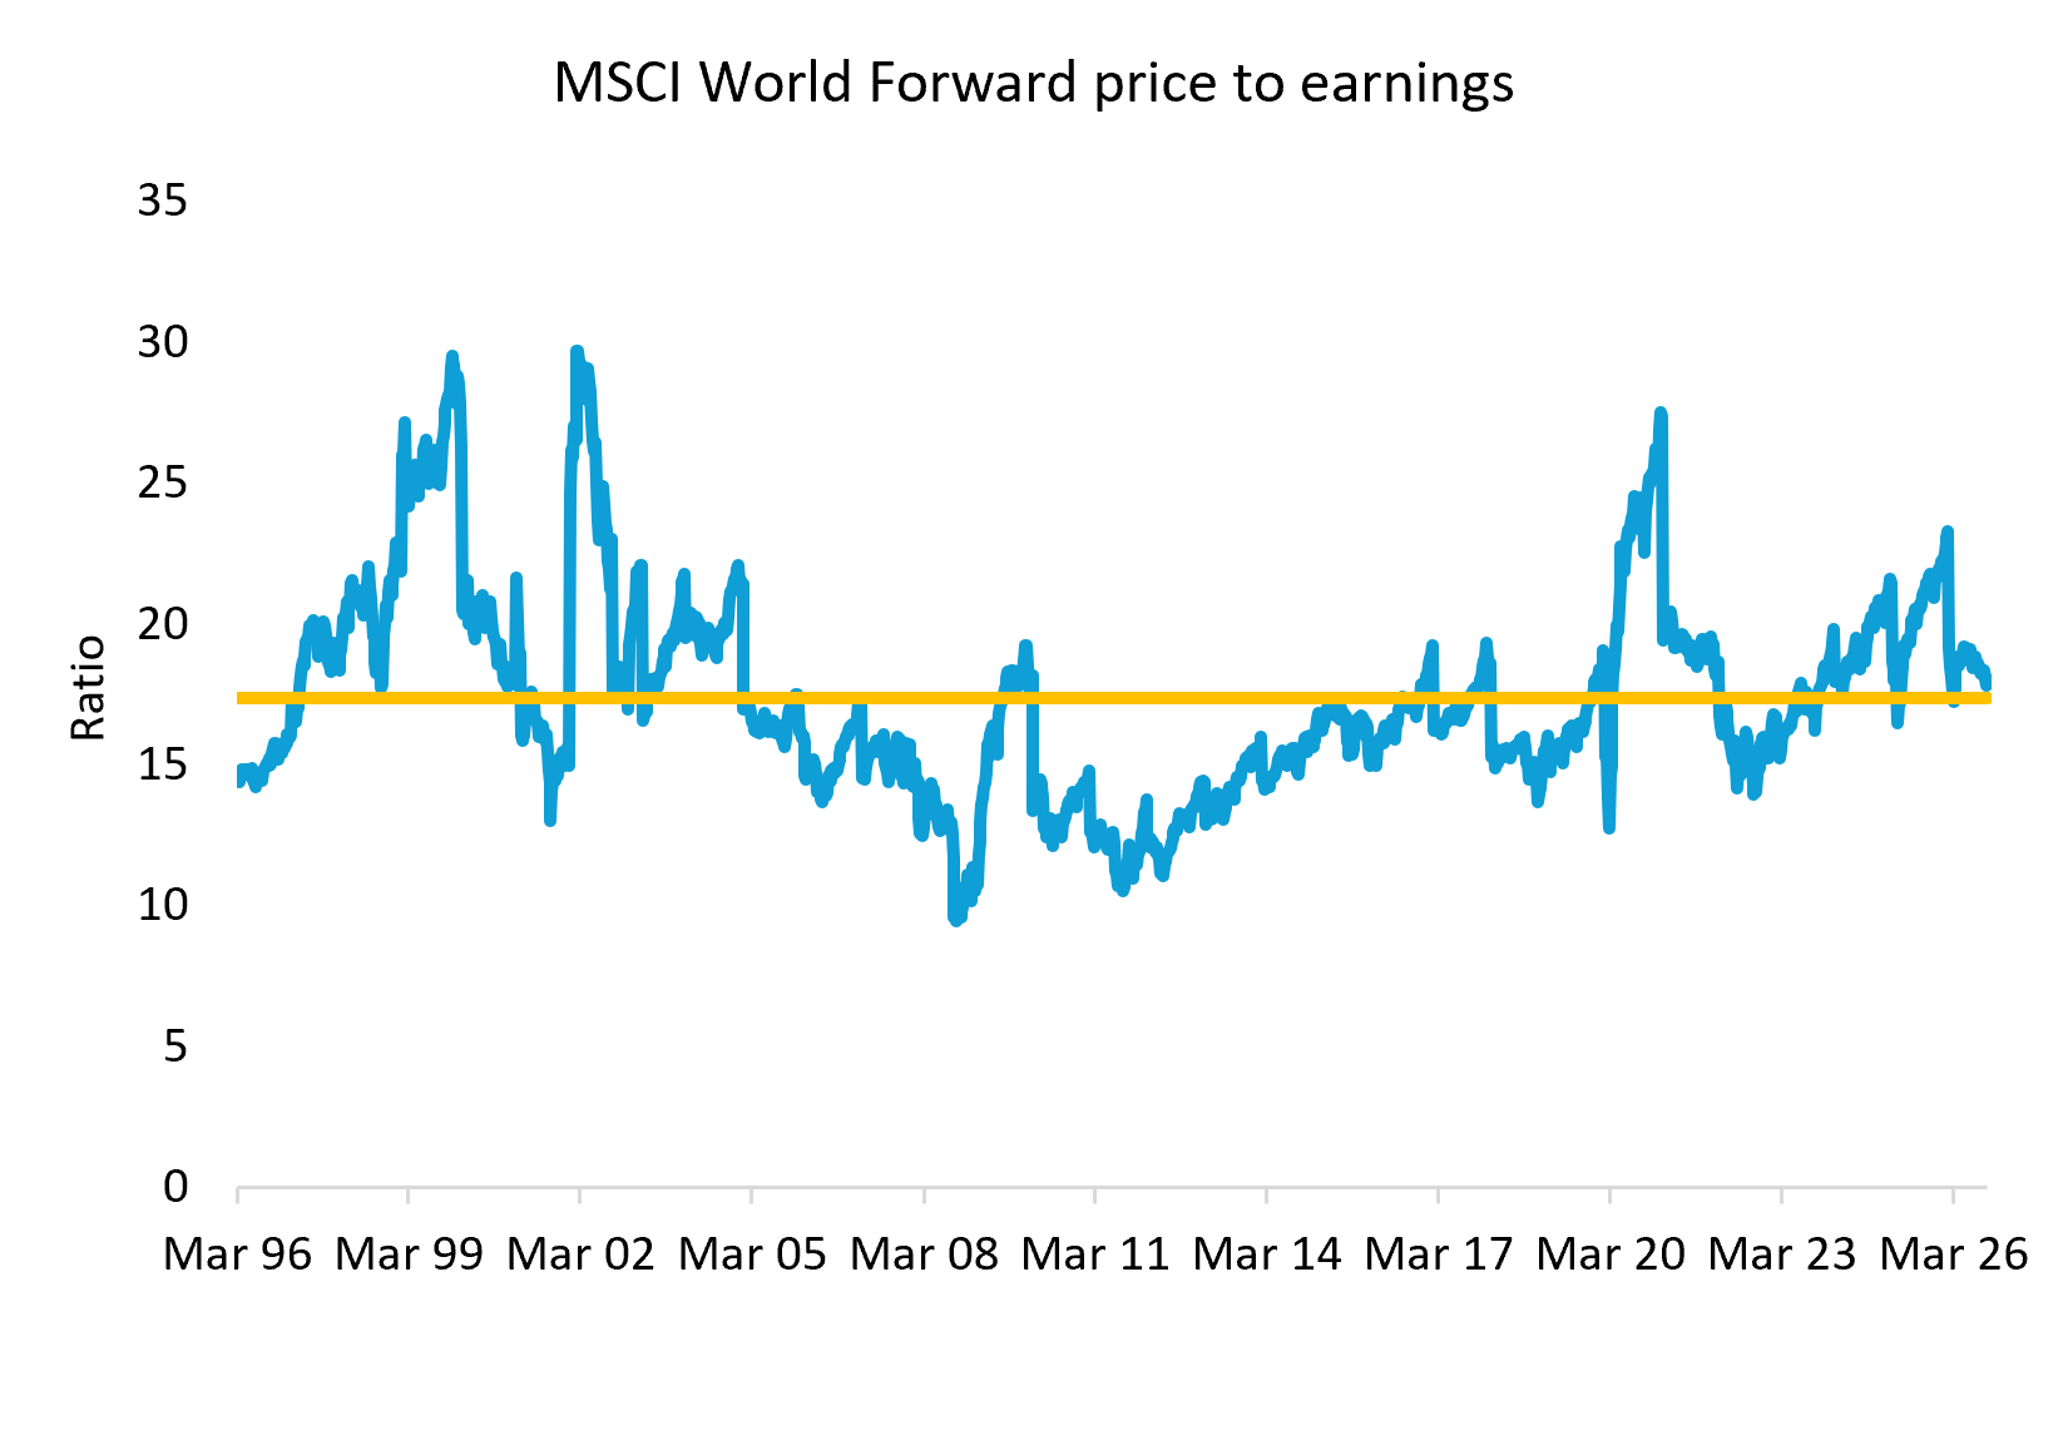
The reassuring evidence is substantial. Global shares trade on 16 times expected earnings, close to their long-run average. In 1999, the same measure ran from 21 to 24 times. Profits, rather than enthusiasm alone, have done more of the lifting this cycle, and company balance sheets are in better shape: U.S. corporate debt is growing by around 2% a year after inflation, against low double-digit growth in the late 1990s. The rally is broader, too. This year, between 50% and 70% of S&P 500 companies have typically traded above their 200-day average price, against around 30% at the end of 1999.

Source: Bloomberg

The less comforting evidence sits mostly in the U.S. On traditional yardsticks such as price-to-book and dividend yield, American shares are more expensive than at any point before the 2000 peak, although the rest of the world is far less stretched.

Concentration is starker still. AI-related companies now make up 49% of the S&P 500’s value, more than the 41% that technology, media and telecoms reached at their peak. Only the railway mania of the 1880s was more concentrated. The scale of investment is also extraordinary: a recent Brookings study estimates the AI build-out will absorb around 3.6% of U.S. gross domestic product (GDP) between 2025 and 2032, more than three times the late-1990s fibre and telecoms boom.

None of this proves AI is a bubble. It does mean AI has to deliver. In data going back to the late 1980s, corporate profit growth has never been further ahead of economic growth, and analysts are more optimistic than they were near the last peak.

Investors also seem calmer: the VIX (CBOE Volatility Index), Wall Street’s ‘fear gauge’, has typically sat around 17 over the past two years, against nearly 24 in the run-up to March 2000. That leaves little room for disappointment, which made last week’s results from the hyperscalers (the giant cloud computing companies) far more than routine.

Demand isn’t the question

On this season’s evidence, demand for computing power is not the problem. Microsoft’s Azure cloud business grew 48%, while its capital spending came in below expectations. That combination points to better returns on the money being spent. Amazon Web Services posted its fastest growth in 18 quarters. Its order backlog is up 190% and management describes capacity for 2027 and 2028 as essentially sold out. Further down the supply chain, Amphenol, which makes the connectors and cabling that wire data centres together, saw orders double. Rising rental prices for the most advanced chips suggest demand is still running ahead of supply.

The harder question is whether the spending earns its keep, and the market is keeping a tight rein.

Microsoft’s shares had already rallied hard recently, and despite strong results they fell with the broader market. Amazon’s shares dropped sharply as cloud growth came in just short of hopes, though we think it presents a buying opportunity. Alphabet’s cloud business more than doubled, but search revenue missed forecasts because AI-generated answers earn less than traditional adverts, for now. Its shares saw the largest daily percentage fall on record. New formats have historically been under-monetised at first, so at below 20 times next year’s earnings we find Alphabet attractive.

Pricing power is the longer-run test. The leading Chinese model has closed the gap from 38% behind the best U.S. model in May last year to just 5%, and it is cheaper to run. The hyperscalers that once kept to their own lanes now compete head-to-head. Booming demand never made airlines reliably profitable, and AI will need its moats.

Credit blinks first

The markets for borrowed money are asking the same question, and this is the signal we take most seriously.

Credit spreads are the extra yield investors demand to lend to companies rather than governments. Since 1998, they consistently started widening before U.S. equities peaked, with a median rise of about 0.14 percentage points beforehand. Spreads on global investment-grade corporate bonds have risen from a low of 0.73 percentage points in January to around 0.95.

Source: Bloomberg

Over the past year, the cost of insuring Oracle’s debt against default has more than quadrupled. There have been false alarms before, and this may simply be a healthy repricing of AI build-out risk, but given credit’s track record we aren’t dismissing it lightly.

Those funding the boom at its riskier edges are also becoming choosier. Data centre company Firmus scrapped what would have been Australia’s largest-ever listing. UK-based developer Nscale met investor pushback on its roughly $30 billion valuation, and OpenAI is reported to have trimmed the valuation target for its latest funding round.

The market must also absorb a wave of new shares, including Meta’s plan to raise close to $100 billion. None of this inspires much confidence, even if it stops well short of a verdict.

Why, not when

The late 1990s offer one more parallel that’s hard to ignore. Back then, the Federal Reserve (the Fed) began raising rates again in June 1999 after a run of cuts, and the S&P 500 peaked nine months later. Today’s Fed cut rates in 2024 and 2025, restarted hiking last month and held steady at last week’s meeting, as expected. If the old template were followed exactly, the market would peak next June.

We think the more useful question is why the Fed raises rates and by how much: hikes that respond to a strong economy are manageable, but hikes forced by inflation from outside the economy are a bigger problem.

Oil is the obvious candidate. Brent crude has climbed quickly to around $116 per barrel. RBC Capital Markets and BCA Research both flag the risk that escalation with Iran may push it higher still, which would put pressure on central banks.

Perspective helps, though. In today’s money, oil passed $200 in 2008, and the global economy now uses less oil for each unit of output than ever before. Stronger household and company balance sheets also make the private sector less sensitive to higher bond yields than in the past, but higher yields still reduce what future profits are worth today and make bonds a stiffer competitor for shares.

Spending the headroom

Bond yields matter at home, too, and gilt investors watched last week’s UK Budget closely, even though its content was fairly uneventful.

The Office for Budget Responsibility revised up its borrowing projections. The government appears willing to run down a little of its fiscal headroom (the cushion it keeps against its own borrowing rules) while restating its commitment to fiscal discipline.

The more interesting question is political: what does the Budget imply for the prospect of a general election in the new year?

Weighing a step back

For equity investors, the most pressing question remains the one we began with: is today’s AI-driven rally a rerun of the late 1990s technology bubble?

We have held a modest overweight in global equities, deliberately small given the risks, because the balance of evidence has supported the rally running further. That evidence is now genuinely mixed.

AI adoption is still at an early stage and chip rental prices are rising. Against that, widening credit spreads, cooler appetites for new listings and productivity growth of 2.7% a year (still short of the 3.5% achieved in the late 1990s) argue for caution.

We’re debating whether to bring our equity position back to neutral and will share our decision next week, because the ghost of 1999 is a guide to what can go wrong, not a script for what will.

Central banks pause, but further hikes remain possible

Away from AI, the Fed, European Central Bank (ECB) and Bank of Japan all kept interest rates unchanged last week, although further tightening remains on the table.

The Fed struck a slightly more hawkish tone, acknowledging stronger economic growth, while two policymakers voted for another rate hike.

The ECB also signalled that another hike could come in December, although tighter financial conditions and limited signs of wage-driven inflation may reduce the need for further tightening beyond that.

Meanwhile, the Bank of Japan kept rates on hold but indicated that further increases remain likely as underlying inflation approaches a sustainable 2%.

Overall, central banks remain cautious about inflation, particularly with energy prices still elevated, but are taking time to assess the impact of previous rate increases.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

04/11/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing market uncertainty ahead of the US midterm elections, the UK budget, Anthropic’s planned IPO and the market reaction to Lula’s re-election in Brazil, received this morning – 02/11/2026

Overloaded with unknowns
Stock markets recovered early last week, and government bond yields fell – until Google owner Alphabet’s earnings unsettled investors, sending its shares down 13% on Thursday. Sentiment is still brittle. Investors feel there are too many unknowns, not least this week’s US midterm elections.

Chancellor John Healey’s budget contained plenty of measures, but their average value was tiny. There were small revenue raisers, like a higher surcharge on banks, and good news for mainstream savers: the cash ISA allowance will stay at £20,000; for larger amounts there will be a tax surcharge. Otherwise, this was finally a budget worthy of the ‘mini’ moniker.

Fiscal headroom fell, which isn’t bad per se, but it leaves UK finances more precarious. If rumours of a post-midterm US strike on Iran are true and yields climb again, higher interest payments would likely remove any remaining headroom. Hamstrung by Labour’s 2024 manifesto and his own MPs, Healey couldn’t make sweeping changes. That’s why many suspect Andy Burnham might call another election next year.

Back to Alphabet’s results, it was its search revenue growth that disappointed – tellingly losing out to Google’s own AI query segment. Investors also disliked Alphabet’s negative cashflow, as the company is no longer able to fund its AI infrastructure investments entirely just from ongoing income. With Microsoft beating free cashflow estimates by $10bn (and faring better than Alphabet for it) investors are now clearly prioritising cashflow over AI spending. The bigger test will be Anthropic’s IPO in mid-November. A $1.5tn-$2tn valuation looks outlandish, but no more so than SpaceX’s IPO in June.

The Fed’s interest rate pause was expected but markets predict a hike in December, and possibly two more next year. Inflation remains above target, US growth is strong and American consumers feel surprisingly confident.

That still won’t help Trump’s Republicans in the midterms. Markets fear Trump might try to overturn election results – which is a bigger risk if Senate results are close. Investors also fear a post-midterm attack on Iran, pushing oil prices to $113pb. Hopefully, those uncertainties will clear this week.

Anthropic’s blockbuster IPO will test AI investors
AI firm Anthropic is set for perhaps the largest ever IPO next month. The Claude maker filed its S-1 share prospectus form last Monday and will reportedly float $100bn of shares at a target valuation of $1.5tn-$2tn. Anthropic hasn’t confirmed those numbers but, if they’re right, the issuance would eclipse SpaceX’s record $85.7bn raised in June.

The filing did reveal an $81bn loss in the first half of 2026 – though $72bn came from convertible notes (loans that become shares upon IPO) revalued alongside the company. Still, operating losses were $693mn, and it has promised to spend $800bn on datacentres in commitments running until 2045. However, against these challenging financials sits exceptional revenue growth: $33bn from the start of the year until September, up 633% from just $4.5bn a year earlier, plus net revenue retention at 900%.

Coming into a multi-trillion IPO with $693mn in operating losses strains belief. But, as the FT’s Lex column argued, it’s misguided to seek a ‘fair’ valuation from historical numbers. Anthropic isn’t pitching investors the past; it’s pitching a slice of a new industrial revolution.

It’s an atypical proposition: the prospectus lists risks from legal troubles with the US government to AI’s potential to destroy humanity. The founders’ 50.1% ironclad voting share also means investors get no say. We’ve been cynical about CEO Dario Amodei’s existential AI warnings before (a government-enforced slowdown might be a convenient excuse to stop borrowing so much) but that doesn’t make those warnings wrong. At least the pitch is more down to earth than SpaceX’s, as Claude is already a tool many businesses find extremely useful and are willing to pay good money for.

The timing, however, isn’t ideal, with confidence in the AI boom waning again, just like a year ago around the same time. Analysts look evenly split. There will be demand – from retail investors and Nasdaq-linked funds – but whether it meets Anthropic’s lofty targets is hard to say. Anything near the target would show there’s still life in the AI trade.

Brazil’s Lula shock
President Lula da Silva’s surprise re-election rocked Brazil’s capital markets last week. Far-right Senator Flavio Bolsonaro was expected to win after topping the first round, but Lula surged in the second to claim an historic fourth term. Markets expected a Bolsonaro victory, and the Brazilian stock market fell a very considerable 13.9% on Monday. Long-term bond yields spiked, and Brazil’s currency, the Real, suffered its worst daily loss against the dollar since 1999.

On the other hand, the sell-off was a mirror image of the rise that came before. Bolsonaro pledged market-friendly reforms and deep spending cuts to tackle a deficit worth 9.5% of GDP, and Brazilian stocks rose practically in lockstep with his chances. Lula’s win undid those expectations. The bond and currency moves followed more or less the same pattern – though US investment banks Morgan Stanley and Goldman Sachs do see some additional fiscal risks if Lula enacts campaign spending policies.

Prolonged effects on emerging market (EM) assets are unlikely. Broader EM indices are mostly dominated by East Asian chipmakers. Even for Latin American equities, this was a sudden adjustment in the policy outlook, reversing an opposite adjustment weeks ago. Once the Bolsonaro trade fully reverses, there’s no inherent reason to expect Brazilian stocks to underperform other EM stocks. And while extra spending commitments might worsen the bond outlook, it’s doubtful how many Lula can implement, given Brazil’s congress swung to the right. The veteran Lula has a history of compromising with opposition politicians too.

Lula’s relationship with the Trump administration is also less antagonistic than sometimes assumed – in policy terms that is, if not rhetoric. Trump will reportedly not back Bolsonaro’s claim that he is Brazil’s rightful ruler, and Trump has rescinded tariff threats against Brazil before. The strategic importance of Brazil to the US (South America’s largest oil producer with ample reserves of rare earth minerals) suggests that Washington will adjust to Lula’s fourth term – just as markets will.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

2nd November 2026

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, the ‘Daily Investment Bulletin’ from Brooks Macdonald which analyses the key factors currently affecting global investment markets. Received today – 30/10/2026

Big Tech spending tests investor patience

Alphabet’s record -12.64% fall reflected growing investor scrutiny of the enormous sums being committed to AI. The company’s results were not uniformly weak, but investors were disappointed by the balance between heavy investment and the near-term returns being generated. Similar concerns weighed on Amazon after the closing bell. Its cloud business continued to grow strongly, but quarterly spending on property and equipment jumped to $77bn, contributing to a roughly -7% fall in the shares in extended trading. The common thread is that expectations for the largest technology companies are exceptionally high.

The ECB keeps December in play

The ECB left rates unchanged at 2.50%, as expected, while signalling it could afford to wait for more data before its next move. Although the accompanying statement struck a slightly dovish tone, President Christine Lagarde indicated that a December rate increase remains the likely next step unless the economic outlook changes materially. Markets continue to price around an 84% chance of a December hike, but reduced expectations for further tightening thereafter, with around 64bps of additional increases priced by next September, 10bps less than before the meeting. Lagarde also announced plans to step down by 7 February, although we do not expect the leadership transition to materially alter the near-term direction of monetary policy.

What does Brooks Macdonald think?

Weakness in the major US indices has been driven disproportionately by a small number of tech companies, while the broader US market and European equities have remained more resilient. That does not signal the end of the AI investment theme, but it does suggest investors are becoming more discerning about whether exceptionally high levels of spending will ultimately translate into stronger earnings. Elsewhere, monetary policy remains an important counterweight. The ECB appears to be approaching the later stages of its tightening cycle, while the Bank of Japan left rates unchanged at 1.25% overnight. Attention now turns back to the inflation outlook, with preliminary October figures from France, Spain, Germany and Italy due today ahead of next week’s euro-area release.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

30th October 2026