Team No Comments

Brooks Macdonald Investment Bulletin

Please see the below market commentary from Brooks Macdonald received today:

What has happened

The Collins dictionary defines a deadline as ‘a time or date before which a particular task must be finished or a particular thing must be done.’ With US Fiscal Stimulus and Brexit talks both hurtling through yet another pair of ‘deadlines’ at the end of last week one can’t help feeling the 2021 edition needs some updating.

Brexit

Yesterday UK PM Johnson and EC President von der Leyen held a call followed by a joint statement confirming that the negotiating teams would continue to talk over the coming weeks. There were no new deadlines set but frankly with 2 ½ weeks to go until the end of the transition period there really isn’t a need for manufactured urgency. The tone at a leader level is very much that both sides remain far apart but even if a deal is close this will be the language until the last moment. After a torrid week for sterling and UK domestic equities we are seeing both bounce today but remaining below levels seen a few weeks ago when more hope was baked into UK sensitive valuations.

Central Banks and Stimulus

This week we see the final meetings of the Federal Reserve and Bank of England rate setting committees. The markets are not expecting any meaningful change in the US but for the language around quantitative easing to be ‘enhanced’ as the bank releases its latest Summary of Economic Projections. In the UK a similar meeting is expected, especially after the additional QE announced in the November meeting. The big question this week will be whether the US can get a fiscal package over the line ahead of Christmas. In an attempt to break the deadlock, there are two bills going to Congress today, a $748bn package which contains the less contentious areas and a separate c. $160bn bill with the thorny topics such as state and local aid. House Speaker Pelosi and Treasury Secretary Mnuchin are set to talk yet again to try to reach a compromise position.

What does Brooks Macdonald think

Despite Christmas being just around the corner there are some major macroeconomic events for investors to navigate through this week. Optimism has grown today around both US stimulus and Brexit although this is from the low base set last Friday. The second half of December is traditionally a lower volume period for equities however with COVID restrictions changing working norms and the macro diary packed, the wind down will likely be delayed a further week.

It is definitely a more interesting time of the year than usual with the Pandemic and Brexit negotiations.

Please keep checking back for more blog content and investment outlooks from us.

Andrew Lloyd

14/12/2020

Team No Comments

AJ Bell – What is the yield curve telling advisers and clients?

Please see below investment weekly article from AJ Bell received 13/12/2020.

No investment indicator is infallible – if it were, none of us would be working and all of us would be playing the markets (only to find, ultimately, that there would be nothing in which to invest except each other’s investments).

“The curve in the UK stands at its steepest since August 2019, while in the US, the yield premium offered by ten-year US Treasuries relative to two-year paper is at its highest since October 2017.”

However, one which is generally held to stand the test of time is the yield curve, so advisers and clients may be intrigued to learn that the curve in the UK stands at its steepest since August 2019, while in the US, the yield premium offered by ten-year US Treasuries relative to two-year paper is at its highest since October 2017.

In theory, this is the bond markets’ way of saying that an economic upturn, and possibly inflation, are coming. This is a view which has considerable implications for financial markets and asset allocation strategies overall, as well as fund and specific stock selection strategies.

Big switch

In general terms, there are four types of yield curve, using the difference in yield between two- and ten-year Government bonds as a benchmark.

  • Normal. Here, yield on the ten-year paper is higher than that of the two-year. Advisers and clients demand compensation for the additional eight years to maturity, as this means there is more time for things to go wrong, with inflation, interest rate increases or default being the main three dangers.
  • Steep. In this case, long-term yields rise more quickly than near-term ones as investors look to price in an acceleration in economic growth and interest rate increases. Advisers and clients fear being locked into low rates and demand greater compensation for owning longer-dated paper.
  • Flat. This is where the bond market is unsure how to proceed. Yields on two- and ten-year paper are the same as the economy transitions from downturn to upturn or upturn to downturn.
  • Inverted. Here, bond markets fear an economic slowdown or recession and the yield on longer-dated bonds drops below that of shorter-term papers. This happens because advisers and clients price in future interest rate cuts in response to the slowdown and a drop in coupons on bonds issued by Governments in the future.

12-to-18 months ago, all of the talk was of how yield curves were inverting and how that could have been warning of trouble ahead (though no-one would pretend that fixed-income markets saw the pandemic or subsequent recession coming).

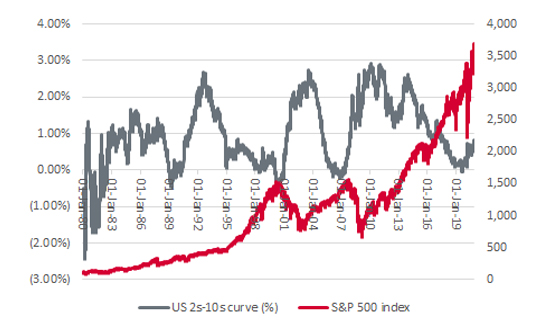
“The yield curve is now steepening in the US, a trend which characterised the early stages of the bull equity markets that began in 1982, 1990, 2002 and 2009.”

The picture is quite different now. Buoyed by further momentum, the race for a COVID-19 vaccine and further fiscal stimulus from Congress, combined with further monetary largesse from the US Federal Reserve, the yield curve is now steepening in the US, a trend which characterised the early stages of the bull equity markets that began in 1982, 1990, 2002 and 2009.

The yield curve stands at its steepest in over three years

Source: Refinitiv data

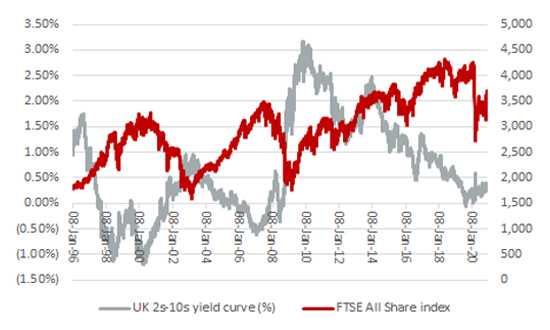
Admittedly, Japan’s experiences since 1990 suggest the yield curve can be a poor predictor of economic activity but the yield curve has had its uses in the UK. Inverted yield curves in 2000 and 2007 helped to call the top for the FTSE All-Share index but a clear steepening marked the beginning of bull runs in 1998, 2003 and in the early stages of the last decade.

The UK yield curve is also steepening

Source: Refinitiv data

Style council

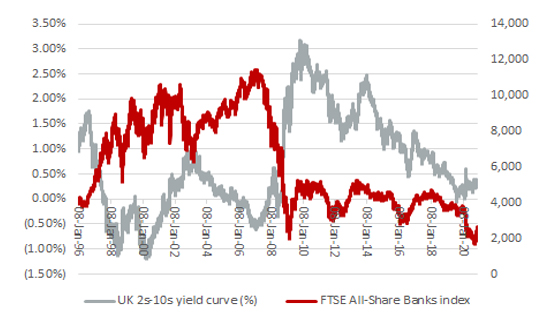
There may be further implications below the level of headline indices. Banking stocks, for example, have been crushed by central banks’ efforts to keep yields low (and, by implication, yield curves flat) as they try to help governments fund their burgeoning debts. A steeper curve could boost banks’ net interest margins, earnings power, share prices and ability to pay dividends. This could be influential in the UK market, for example, where the FTSE 100’s Big Five banks are so integral to earnings and dividend growth forecasts.

Banking stocks could well benefit from a steeper yield curve

Source: Refinitiv data

“A steeper yield curve, hinting as it does at a stronger economy and inflation, seems to favour cyclical earnings growth over secular earnings growth – or, to put it more crudely, ‘value’ as a style over ‘growth’ – at least if history is any guide.”

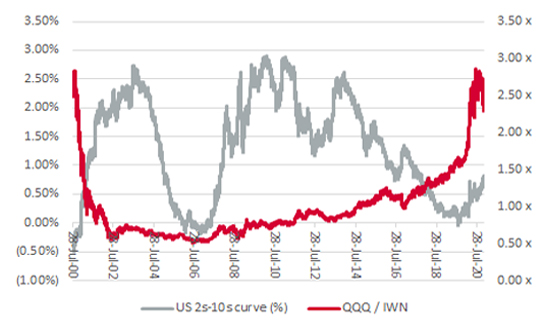
Even more intriguingly, a steeper yield curve, hinting as it does at a stronger economy and inflation, seems to favour cyclical earnings growth over secular earnings growth – or, to put it more crudely, ‘value’ as a style over ‘growth’ – at least if history is any guide.

As this column has noted (30 October 2020), value has tried to forge a recovery relative to growth, using the ratio of the price of the Invesco QQQ Trust, an exchange-traded fund (ETF) designed to track and deliver the performance of the heavyweight NASDAQ 100 index (minus its running costs), relative to the iShares Russell 2000 Value ETF, as a benchmark.

‘Value’ seems to be taking its lead from a steeper curve too

Source: Refinitiv data

Some are wondering if this trade is already exhausted. Looking back at 2000, you could argue that it has hardly begun, such was the violence of the switch from growth to value as the former began to falter under the twin weights of lofty valuations and earnings disappointment.

Russ Mould, AJ Bell Investment Director.

Please continue to check back for our latest updates and blog posts.

Charlotte Ennis

14/12/2020

Team No Comments

A.J. Bell: A year to forget but also one to remember

Please see below an article published late yesterday by A.J. Bell, which looks back on the initial outlook for 2020, in contrast to what was experienced and what we might see in 2021:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

11/12/2020

Team No Comments

Jupiter – Investing for a post-Covid world

Please see below an article recently published by Jason Pidcock, who is Head of Strategy on Asian Income at Jupiter, which outlines his thoughts on potential investment opportunities in a post-Covid world:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

10/12/2020

Team No Comments

Daily Investment Bulletin

Please see below update received from Brooks Macdonald this afternoon, which comments on the markets’ reaction to political developments in the US as well as ongoing Brexit negotiations in the UK.

What has happened

After starting somewhat moodily, markets gradually recovered ultimately ending in positive territory with the US close. Whilst US Fiscal Stimulus pre-Christmas is still up for debate, constructive comments from the Republican Senate leadership helped support risk appetite.

US Stimulus

Senate Majority Leader McConnell urged both sides to set aside their top priority demands which had generated sticking points earlier in the year. Both parties are acknowledging that this is stage one of the negotiations with another package inevitable when the new administration enters the White House. It’s within that context that the narrative has shifted to ‘pass those things that we can agree on’ in the words of Mnuchin. Treasury Secretary Mnuchin presented a $918bn bill to House Speaker Pelosi so there is a suggestion that we are getting closer to a headline figure on the package. Below the surface there are quite a few differences however, including unemployment insurance where the bipartisan bill backed by Pelosi allocates $180bn with Mnuchin’s White House bill containing just $40bn. Markets have taken the language of compromise, backed by actions, positively however and this has been enough to shrug off the European risk with Brexit.

Brexit

The contentious provisions in the Internal Market Bill were withdrawn by the UK Government yesterday after an agreement in principle was reached around the Northern Ireland arrangements. This draft agreement is yet to be published but these talks, led on the UK side by Michael Gove, have been running in tandem to the main trade talks. This has removed a key point of contention between the EU and UK with the former suggesting that the provisions meant the UK could not be trusted. This improved backdrop is the context for UK PM Johnson to meet EC President von der Leyen over dinner tonight to discuss the Brexit impasse.

What does Brooks Macdonald think

Both sides have played down the odds of a deal and have sounded cautious without entirely snuffing out hope. Is this theatrics or managing expectations ahead of a dinner that shows ‘both sides tried’ – who knows. That said, yesterday was a positive day for Brexit developments as the dropping of the Internal Market Bill provisions (and promise not to include similar measures in the Taxation Bill) does suggest a continued softening of the UK’s position ahead of the crunch dinner tonight.

We will continue to monitor the markets’ performance as we edge closer to the end of the Brexit transition period on the 31st December. Please therefore, check in again with us soon.

Stay safe.

Chloe

09/12/2020

Team No Comments

Legal and General Asset Allocation team’s key beliefs

Please see below for the latest key beliefs article from Legal and General’s Asset Allocation team, received by us late afternoon 07/12/2020:

Festive spirits

Markets don’t seem to be taking a holiday break yet. Last week, equities rose, the US dollar weakened, and rates and inflation climbed higher. It doesn’t look like we will be able to relax any time soon, either; the coming weeks could see the start of vaccine distributions, the Trump administration transferring power, the conclusion of Brexit’s game of ‘deal or no deal’, and potentially a fiscal deal in the US.

As with all Key Beliefs emails, this email represents solely the investment views of LGIM’s Asset Allocation team.

Could the last bull please switch off the lights?

Recent news on COVID-19 vaccines has generally been positive, but the immediate economic outlook remains challenging. Europe is already in a renewed contraction, following a significant increase in restrictions to get the virus under control. US economic data have held up well so far because restrictions had been relatively limited, but stricter measures are starting to be deployed amid a surge in cases.

Then there are the fading hopes for fiscal stimulus. US households are beginning to run out of savings from the income transfers received during the spring lockdown, while more unemployment benefits are set to expire at the end of this month. There are signs Congress is beginning to recognise this danger, and Friday’s weaker payrolls report was a clear warning as talks have resumed on passing some targeted measures in the $500-900 billion range. It is not clear a compromise can be reached in time for Christmas; failure to achieve one risks an outright contraction in activity over the festive period and a negative GDP print for the first quarter.

Does it matter? The outlook for 2021 is bullish and markets might be able to look through any weakness as temporary. The main headwind for markets at the moment is the very broad positive sentiment. Next year’s consensus outlooks are bullish and our sentiment indicators are exuberant. What could possibly go wrong?

We remain cautiously bullish for the medium term but tactically neutral. We will not chase the rally at this point, preferring to take our risk in relative-value trades.

Every hero needs a crisis

Central banks had no choice in either 2008 or March this year. The world needed to be saved from a financial meltdown and so they flushed liquidity into the world.

However, today’s monetary policy can contribute to tomorrow’s meltdown. Keeping interest rates low to provide a safety net for markets can induce corporations and households to take on more debt and more risk. This dynamic has also tended to stoke inequality, as asset prices have been boosted even though unemployment has spiked. Managed stability creates instability.

Global leverage has increased significantly this year, undoing much if not all of the deleveraging of recent years. In a normal world, increased leverage is often resolved by a credit crisis, massive defaults, forced liquidations, or massive inflation. But apparently this isn’t a normal world.

Most of the increase in debt during the pandemic has been in the public sector, and a large part of this has been absorbed by central banks via quantitative easing. This debt sits with central banks and is perpetually rolled over, effectively debt monetisation. Central banks could commit to never selling it or just write it off, which would improve debt-to-GDP ratios. Cancelling public debt like this is prohibited in some countries, due to the moral hazard it could create for politicians. For others, the only constraint is ultimately inflation.

But ballooning debt is also a symptom of other problems like weak productivity and inequality (encompassing poor health, low wage growth, and poor education). This could result in further political tensions and anti-globalisation, similar to the experience of the 1930s.

Given the current economic output gaps, we don’t see runaway inflation as a likely scenario but our head of economics does expect mildly higher inflation in the years to come. This would change if we saw continued broad global fiscal support financed by central banks.

Do you feel lucky?

Bitcoin reached a new all-time high last week. The crypto-currency has mostly seemed a private-investor phenomenon, but we have seen increased interest from institutions. There are many things for them to like: past returns have been stellar (an annualised return above 100% over the past five years); it has offered some diversifying properties with only a slight positive correlation with risk; and, contrary to many currencies, it has the attraction of limited supply at a time when central banks are printing money.

However, there are also plenty of downsides. Bitcoins have no intrinsic value (at least tulip bulbs could yield a beautiful flower); they are not widely recognised or regulated; it takes the energy of a medium-sized nation to mine a bitcoin so it isn’t very environmentally friendly; and it is very expensive and slow to use in day-to-day transactions.

The first is perhaps the most existential risk: at some point bitcoins could become worthless if a more popular or efficient alternative is found. Central banks could well develop their own crypto-currencies, especially if bitcoins and others become too big and interfere with efficient monetary policy.

It could easily be years before the next bitcoin selloff but we know how this story is likely to end. At the peak of the 17th century tulip trade in Amsterdam, those paying fortunes for a single bulb were surely speculators who understood that tulip prices had no link to bulbs’ intrinsic value and just hoped to sell them to someone else at an even higher price. Many were successful in the year before the crash in 1637; their quick gains were what drew in others and excited pundits. Does that sound familiar?

These articles provide concise well-informed views that cover the whole of the market and are useful to maintain your up to date view of the markets globally.

Please keep reading our blogs regularly to give yourself a holistic and up to date view of the markets.

Keep safe and well,

Paul Green

08/12/2020

Team No Comments

Jupiter: Views from the House

Please see the below look back at 2020 from Jupiter Asset Management’s Chief Investment Officer:

Jupiter’s Chief Investment Officer reflects on the longer-term implications of a year most unlike any other.

In a year overwhelmingly dominated by the pandemic, it could be tempting to dwell on the challenges that have been presented to businesses and to global society.

Long before any of us had heard – let alone uttered – the words “COVID-19,” there was a trend towards more flexible working in many sectors of the economy, including in asset management. Some in our industry were embracing growing requests for more flexible working arrangements, while others may have viewed them with a certain degree of scepticism, pondering whether fund management was the kind of industry that could accommodate such arrangements at scale.

As much of the world went into lockdown, personal opinions on the merits and disadvantages of remote working became largely irrelevant; a significant policy decision that would, historically, have been the preserve of individual businesses was essentially taken for them.

Simultaneously, the important question as to whether a firm like ours could operate effectively with virtually all employees working remotely for a prolonged and potentially open-ended period was answered; we could, and we did. Indeed, a recent conversation with our head of dealing, Jason McAleer indicated that our industry as a whole has not only coped with the challenges presented, but has seen no perceptible increase in operational errors or issues.

In my view, the changes we have seen have the potential to make asset management a fundamentally more inclusive industry. Put simply, it now feels reasonable to hope that many of those who – for oft-cited reasons, including perceptions of long hours, punishing travel schedules and reconciling the demands of a challenging career with family life – might never have considered a career in fund management, will feel newly emboldened to take a closer look.

If, like me, you believe that more diverse investment teams are better performing ones, then this can only be a welcome development from the perspective of our clients.

Inclusivity leads to diversity

The pandemic and associated changes to working patterns and practices have also reminded us of the value of the office environment, as evidenced by numerous requests from colleagues for permission – which was generally denied, in line with the official guidance at the time – to continue to work from the office as the second UK-wide lockdown came into force.

This all begs a question: how quickly will the potential benefits of changes to working patterns in our sector filter through into the reality of the make-up of our workforce? Naturally, in a profession like fund management, hiring cycles are relatively lengthy. For this, there can be no apologies; the business of taking fiduciary responsibility of other people’s money is a serious one, and it is right that those charged with this duty should first have to prove their aptitude.

Of course, recruitment decisions are largely devolved to hiring managers; while this makes it difficult to “force” change in hiring practices from above, as CIO I am committed to continuing to challenge ourselves.

Changing behaviours: impact on markets and innovation

For a business like Jupiter, one of the more testing trends to emerge over the last year has been a tangible increase in direct participation in financial markets by retail investors. The exact cause of this change in behaviour is difficult to pinpoint, but we can reasonably speculate that it may have much to do with a combination of increased market volatility creating perceptions of attractive entry points, and the simple reality of the increase in available time many people have found in lockdown.

Whatever the cause, there is no doubt that such a sharp increase in activity in stock markets among individual retail investors has had an impact not only on stock prices, but also on liquidity and on sources of liquidity.

For asset managers, this potentially disruptive trend should act as something of a wake-up call; as retail investors in growing numbers show signs of exploring different ways to put their money to work, we must remain relevant, and continue to demonstrate that our products offer value.

As a firm, we place great emphasis on the importance of fostering innovation. A particularly exciting development for us in this regard was the formalisation earlier in the year of our strategic partnership with US-based NZS Capital, LLC (“NZS”), a highly innovative investment boutique which itself focuses on identifying disruptive businesses with the potential to generate favourable outcomes simultaneously for investors, customers, employees, society, and the global environment.

2020: when ESG became truly “mainstream”

Our partnership with NZS also serves as a timely reminder of our commitment to innovation and leadership in the field of ESG investing, a topic that has enjoyed a meteoric rise in prominence over the course of the last year. Indeed, I would be unsurprised if, in the future, social anthropologists looked back on 2020 as the year ESG investing became truly “mainstream.” This is an overwhelmingly positive development, and one to be embraced.

From a fund management perspective, I believe that ESG in the years ahead will be a refinement, evolution and re-categorisation of many of the assessments managers already make when looking at an investment case. How is a company run? Do its activities and/or products cause detriment to the environment? Are its employees mistreated or endangered? Does it mistreat its customers in a way that is detrimental to them and unlikely to build long-term loyalty? Has it taken on excessive leverage in pursuit of short-term shareholder returns that might undermine its longer-term viability? For us, these are not new questions, but they are being asked of us by a broader range of clients and other stakeholders, and with a frequency and determination not before seen.

Such focus on these issues is having a marked effect on markets, and on the way in which capital is being allocated to investment managers. This, in turn is undeniably changing and disrupting perceptions of the characteristics of a business most prized by investors.

The “what” and the “how” of asset management

I believe that the single most important thing we can do as a business is to generate strong and sustainable investment returns for our clients. As the end of every year approaches, we take the time to reflect on our performance; for a year that is likely to stand out in the collective memory for many of the “wrong” reasons, in this particular regard, 2020 has been a year much like any other.

The change, challenges and uncertainties we have all faced notwithstanding, it is pleasing to see that many of our strategies have performed very well throughout this period. Meanwhile, the new colleagues who joined Jupiter through our acquisition of Merian Global Investors have already made a significant contribution to Jupiter, bringing fresh energy, ideas, and perspectives to our debates.

But investment and performance are not the only things about which we hear from clients, who increasingly want to know how a firm like Jupiter manages its money managers. This is perhaps the most important part of the role of the CIO office, and it has been a privilege to speak with so many clients over the course of the year about how we seek to hold our fund managers to account. Put another way, it might be said that in 2020, what we seek to do (generate strong, sustainable investment performance), and how we go about it have become first among equals in the pecking order of clients’ priorities.

In truth, nobody knows how 2021 will play out. With the promise that vaccine programmes may be imminently deployed, a final end to the next chapter of Britain’s exit from the EU in sight, and a the potential for a more stable geopolitical scenario, it is tempting to look forward to the coming year with a great sense of optimism. At the same time, none of us must be under any illusion over the scale of the challenges facing the global economy as the world emerges from the pandemic. Whatever happens, our focus in the CIO office will be on seeking to ensure we deliver the best performance we can, in the most sustainable way we can; it is this pursuit, I believe, that gives us our real licence to operate.

As the end of every year approaches, reflections on the year we are about to leave behind tend to come naturally to everyone.

Look backs at the financial world and investment markets pour out from fund managers followed by outlooks, predictions, and goals for the year ahead.

2020 was a year that nobody could have predicted, and a year I’m sure nobody will look back fondly on.

One of the (positive) key points that can be taken away from this year (as demonstrated in the article above) is something we have been talking about for a while now, ESG is now mainstream.

It’s real, it’s important and it’s here to stay.

From firms and fund managers beginning their ESG journey, to the ones talking about how they already factor in a strong ESG process within their operations.

Whatever our industry takes away from this year, one thing is for sure, ESG is now firmly on everyone’s radar.

Andrew Lloyd

08/12/2020

Team No Comments

Blackfinch Investments – Monday Market Update

Please see below this week’s Monday Market Update from Blackfinch Investments – received today 07/12/2020.

Blackfinch Group – Monday Market Update

Issue 20 | 7th December, 2020

UK COMMENTARY

• The COVID-19 vaccine developed by Pfizer in conjunction with BioNTech was granted authorisation for use in the UK by regulators, with the first doses expected to be rolled out imminently
• The FTSE 100 hit its highest level since March thanks to a solid performance in pharma, mining and energy stocks
• House purchase mortgage approvals increased to 97,532 in October, from 92,091 in September, beating the forecast of 84,000, helped by the stamp duty holiday which has turbocharged the housing market
• Nationwide house price index rose 0.9% in November from October. The year-on-year increased quickened to 6.5% from October’s 5.8%.
• The UK was lifted out of ‘lockdown 2.0’ leading to many UK department stores experiencing a mini boom as shoppers rushed back through their doors. Meanwhile Arcadia group fell into administration, putting 13,000 jobs at risk.
• Tesco surprised markets by deciding not to accept its £585m of business rates relief from the government. Many of its peers followed suit providing a c.£2bn saving to the public purse.
• The manufacturing Purchasing Managers’ Index (PMI) rose to a 35-month high of 55.6 in November (revised up from the ‘flash’ reading of 55.2), up from 53.7 in October. PMI has now signalled expansion (i.e. above the 50.0 level) for six successive months.
• PMI appears to have been boosted by the stockpiling of critical inputs and increased demand from the EU ahead of the UK-EU transition arrangement deadline on 31st December
• Private new car registrations in November were 32.2% lower than in November 2019 caused by the second lockdown. They were up 0.6% year-on-year in October.

US COMMENTARY

• Both the Dow and S&P posted their best November returns since 1928 as hopes around vaccines and a stimulus package assisted sentiment
• US jobless claims fell from 787,000 to 712,000 undershooting the 775,000 consensus estimate. Continuing claims also fell to 5.52m from 6.09m, lower than forecasts of 5.8m. However, 245,000 jobs were added in November compared 638,000 on the previous month and it was the fifth month in a row employment has fallen in the US.
• This mixed jobs report added weight to the argument that further financial assistance and stimulus is needed to help the US economy
• A bipartisan $900 billion relief package bill has been put forward but is it unlikely to get much support as too many discrepancies exist
• Moderna has applied to the US Food and Drug Administration for emergency use authorisation for its COVID-19 vaccine

ASIA / AUSTRALIA COMMENTARY

• China’s Caixin manufacturing purchasing managers’ index (PMI) jumped to 54.9 in November, from 53.6 in October; the consensus forecast was for a reading of 53.5
• Australia’s economy expanded 3.3% quarter-on-quarter in September after a 7% quarter-on-quarter contraction in the June quarter

GLOBAL COMMENTARY

• The Organisation for Economic Cooperation and Development (OECD) now predicts that global Gross Domestic Product (GDP) will contract by 4.2% this year, which is an improvement on the previous forecast of -4.5%. At the same time, it lowered its 2021 forecast to 4.2% from 5%.
• OPEC+ ministers agreed to withdraw previous output cuts by no more than 500,000 barrels a day each month, starting in January, with production hikes subject to review each month helping to push up oil prices

COVID-19 COMMENTARY

• In the UK, cases and hospitalisations continue to fall, with some of the hardest-hit parts of the country reporting a halving in new cases since the second national lockdown began on November 5th
• The US reported 100,000 COVID-19 hospitalisations for the first time

Please continue to check back for our latest blog posts and updates.

Charlotte Ennis

07/12/2020

Team No Comments

Invesco Weekly Market Performance Update

Please see below an article received from Invesco this morning providing their latest market update:

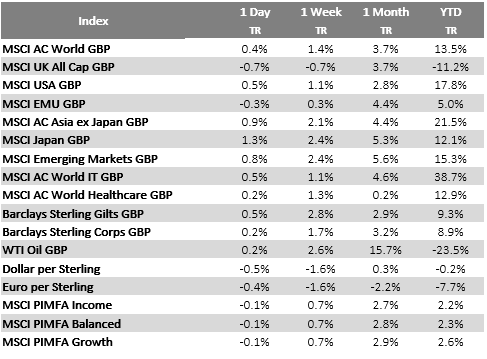
As you can see from the above, many sectors had a positive week last week in terms of investment returns. The main losers appeared to be Government Bonds and some Investment Grade Bonds. Thursday could be a day to watch, with the U.S. Jobless report, the ECB meeting and UK economic activity indicators are all released.

We will continue to provide details on any announcements made on a deal or no deal scenario and what impact this could have on markets and investments.

It is important to remember, whatever happens, it is important to remain invested and focus on your long-term objectives.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

07/12/2020

Team No Comments

What the dollar’s decline may mean for markets

Please see below AJ Bell article received yesterday morning which provides a market commentary relating to the dollar’s 9% fall since Donald Trump’s inauguration on the 20th January 2017.

It wasn’t always easy to understand what US president Donald Trump wanted, but at least he was consistent about the dollar. He spent much of his four-year tenure in the White House complaining about how the greenback was too high and ultimately he got his way, even if he may have finally come around to the view in 2020 that a rising currency was a back-handed compliment from markets about the relative strength of the US economy.

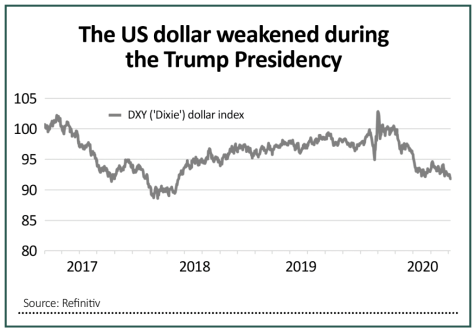
The dollar has fallen 9% since his inauguration on 20 January 2017, using the trade-weighted basket of currencies that makes up the DXY (or ‘Dixie’) index as a guide, and now trades at a two-and-a-half-year low.

A loss of value in the globe’s reserve currency, and a major haven asset, has potential implications for a range of markets, and not just foreign exchange.

Gloomy greenback

There are multiple possible reasons for the buck’s case of the blues. First, the president regularly railed against the US Federal Reserve’s monetary policy, arguing that chair Jay Powell and the Federal Open Markets Committee were running it too tight.

Whether they listened to the president, heeded stress in the financial markets in autumn 2019 or took other data on board, Powell and colleagues had begun to push through interest rate cuts even before the global pandemic pulled the rug from under the US economy in 2020.

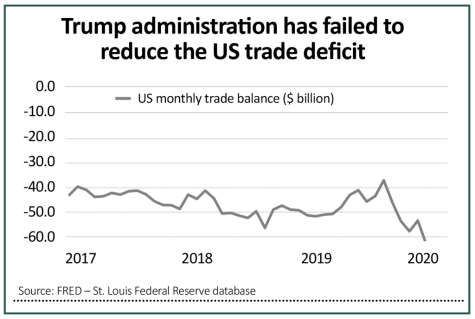
Second, the president’s trade war with China unsettled markets and seemed to bring no great economic benefit. The US trade deficit has surged back toward its all-time high, with the result that dollars are flowing out of America to pay for the overseas-produced goods that consumers are sucking into the country.

In some ways this can be seen as a good sign. In 1960, economist Robert Triffin argued that America would always have to run a trade deficit, and hand out more than dollars than it received, to ensure the world had enough of the reserve currency to go around.

The alternative would be a painful liquidity squeeze on the globe’s economy and financial markets alike as dollars flooded home.

Third, the markets’ latest round of optimism that the pandemic may soon be over and a global economic recovery underway, following the vaccine announcements from Pfizer-BioNTech, Moderna, and AstraZeneca and the University of Oxford, means that perceived havens such as the dollar are less in demand.

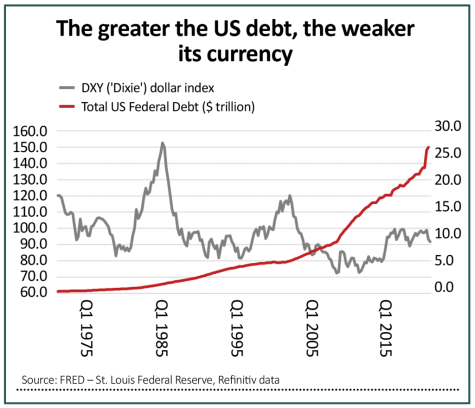
Finally, and perhaps most fundamentally, Trump oversaw a huge increase in the Federal deficit. When he took office America’s national debt was $18.9 trillion. It began to surge even before the pandemic and has soared in its wake to $27 trillion. Although Republicans and Democrats have failed to agree upon another round fiscal stimulus, the debate centres on the degree of further borrowing, not whether there should be further debt creation or not.

This argument is not unique to America – something which may be sparing the dollar a few more blushes – but it will surely continue a trend of ever-higher government debt ceilings.

That dates to the early 1970s, when Richard Nixon took America off the gold standard so he could pay for welfare programmes and the Vietnam War, but the trend is clearly accelerating.

Remember that Moody’s downgrade of America’s credit rating, and summer of turmoil in financial markets, came after 2013’s debt ceiling suspension, when the limit was $16.7 trillion. It had taken America 237 years to get there but Uncle Sam has taken just seven years to overspend by a further $9.3 trillion.

Road to ruin

Anyone who takes the view that American debt is not a sustainable path will be wary of the dollar.

Anyone who feels that Covid-19 can be contained, and the world builds a reliable recovery, will also fight shy of the buck. Triffin’s theories imply that a weak dollar is the natural result of a strong US economy and robust global trade flows – both of which would logically benefit emerging markets and commodities, asset classes that traditionally do well when the dollar is weak.

The dollar is likely to hang tough for a while yet, not least as suitable candidates to replace it as the world’s reserve currency are in short supply.

China’s renminbi is not fully convertible, a return to gold will impose disciplines which no politician or central banker will accept (or can afford) and cryptocurrencies do not have universal acceptance.

But any attempt to reset currencies and debts could yet be spearheaded by central bank-backed digital currencies, a trend which must be closely watched.

We will keep an eye out for updates on the value of currency as the new President-elect, Joe Biden, takes office in January 2021. Please check in again with us soon.

Stay safe.

Chloe

07/12/2020