Investment Management House Janus Henderson recently published some thought pieces on ESG and Socially Responsible Investing. Please see the key takeaways from these pieces below:
Sustainable equities: the future is green and digital
The pandemic has accelerated investment into digitalisation, which we consider to be a key enabler of sustainability.
We expect support for sustainable development to gain momentum as countries embrace the need to be low carbon and as Joe Biden takes his seat in the White House.
Investment into electric vehicles is expected to surge in 2021 as innovators ‘race’ to the top.
Sustainable design in consumer products
The apparel sector is well known for its detrimental effects on the environment. However, as consumers become more aware of their own environmental footprints, there has been a surge in demand for sustainable goods.
A circular economy is based on the principles of designing out waste and pollution, keeping products and materials in use, and regenerating natural systems.
Companies including Nike, Adidas and DS Smith have incorporated a circular approach to the design and production of their goods, creating durable and long-lasting products with a reduced environmental footprint.
Investing in Diversity: analysing the investment risks and opportunities
Companies are increasingly being held accountable by consumers who reward brands aligned with their values.
For many global businesses, matters of diversity and inclusion go beyond the workplace, and efforts are made to address discrimination in the countries in which they operate.
Investors should be wary of companies that fail to futureproof themselves in terms of diversity. Socially conscious brands that make inclusivity a central part of their business strategy and brand ethos are more likely to succeed.
What gets measured, gets improved. Investors should focus on company disclosure, diversity-related targets, and meaningful initiatives in place. A list of suggested investor questions can be found at the end of this paper.
Janus Henderson are ahead of the game with ESG policies and started factoring this in back in 1991 shortly following the 1987 United Nations Report, ‘Our Common Future’ which I mentioned recently in an ESG blog. Their philosophy is below;
‘We believe there is a strong link between sustainable development, innovation and long term compounding growth.
Our investment framework seeks to invest in companies that have a positive impact on the environment and society, while at the same time helping us stay on the right side of disruption.
We believe this approach will provide clients with a persistent return source, deliver future compound growth and help mitigate downside risk.’
As I wrote about in our blog, as a firm we undertake regular due diligence with regards to the investments we recommend to our clients. This an ongoing process and we are constantly monitoring the market, and this year ESG has become a key factor in what we look for in the due diligence process.
Of course, many businesses may have a broad and generic ESG statement, but having a strong and well defined ESG process embedded into a businesses culture and investment process is definitely one of our key determining factors in the companies we choose to recommend.
We start off with an investment houses ESG statement, but then we dig deeper, to make sure these investments do exactly what they say they do, in terms of ESG, then factor this into the rest of our research i.e. investment returns, track records, cost etc.
It’s good to see so many investment houses now openly talking about and promoting ESG and demonstrating their views and philosophies.
Now could be a great time to invest whilst asset prices are still generally low, all whilst taking a responsible approach to investing!
As always, keep checking back for a variety of blog content from a wide range of investment houses, fund managers and our own original pieces.
Please see the below 2021 Outlook from Legal & General:
Foreword: A fresh start
Despite the ongoing challenges, we see next year as a time for healing – for the economy, environment and society.
After contending with the terrible human and economic toll of a pandemic, as well as market volatility reminiscent of the financial crisis, investors could well be forgiven for wondering anxiously: what could 2021 possibly have in store for us?
We cannot, of course, predict the outcome of risk events already on the horizon, let alone identify any black swans fluttering menacingly. But based on our research and the available information, we can sketch out the contours of next year’s macro and market landscape. Pleasingly, we believe it is one in which investors can thrive, albeit with the right approach.
In this outlook, we offer views from across LGIM that inform this optimism, grounded in our assessment that even though the world economy’s immediate prospects may have darkened, 2021 could still be a strong year for growth. Other key points include:
• The bull case for equities at this point in the cycle
• How a Biden administration could create ripples in the bond market
• The role of cashflow-driven investing in tackling market gyrations
• Why 2021 could be a pivotal year for battery technology and renewable power
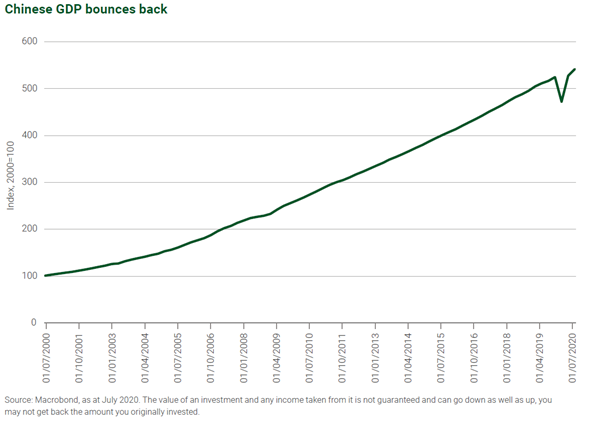
• How China’s financial sector is opening up potential opportunities for investors
As we noted in our autumn update, COVID-19 has accelerated a number of long-term investment themes that were previously underway. The global energy transition is an obvious example, as the shock of coronavirus has focused attention on the looming threat of climate change just as it has shaken up carbonintensive industries.
At the same time, environmental regulations are likely to tighten under the incoming US administration, whose climate policies will have a worldwide impact. The changing of the guard in Washington, meanwhile, brings us to another long-term trend: populism.
While Donald Trump lost the 2020 US election, the result was not a repudiation of everything he stood for. We will need to continue monitoring the way our politics have changed forever as a result of the forces that propelled the outgoing president, and other populists around the world, to power and sustained them in office.
It’s also clear that many Americans continue to view China unfavourably, despite the election result, with the uneasy relationship between the world’s two largest economies likely to be a key driver of geopolitics for the foreseeable future.
In Europe, even though a UK-EU trade deal now looks probable, much else remains to be decided after the Brexit transition period ends. Expect the UK’s long divorce from the bloc never to stray too far from the headlines, or the radar of investors, next year.
And while we look forward to a post-pandemic world, we are still living with coronavirus and the dramatic steps taken to contain it. As such, expect further debates over fresh monetary and fiscal stimulus to be a prominent feature of the coming months – even as we contemplate the ultimate cost of such measures.
Despite these challenges, we see next year as a time for healing – for the economy, environment and society – in which we can play an important role on our clients’ behalf, by seeking to create a better future through responsible investing.
Sonja Laud
Chief Investment Officer
Economics: Unlocking growth
The immediate economic outlook may have darkened, but there are reasons to believe 2021 could be a strong year for global growth.
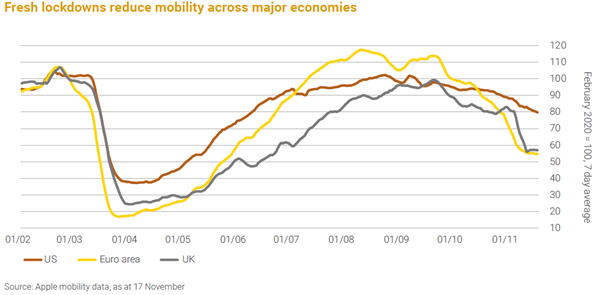
The primary downside risk we saw for the economy – further waves of COVID-19 leading to renewed lockdowns – has sadly materialised across many parts of the northern hemisphere. While we don’t expect the impact on the economy to be as severe as it was during the spring, the measures taken by European governments during the autumn and winter are likely to lead to another significant fall in output following the strong summer rebound.
The US has been slower to respond and, as pressures build on hospitals, the approach taken to tackle the virus across different states is likely to toughen.
The US probably has sufficient momentum into November to avoid an outright contraction in the fourth quarter, but the holiday season will now be far from normal.
After rapid progress to reduce unemployment, the improvement in the labour market could stall or even reverse heading into 2021. The US election outcome, discussed by Jason on page 8, has reduced the chance of a radical shift to sustained fiscal expansion, but we still expect some additional support to emerge in the coming months in response to the deteriorating virus news.
Vaccine change
Offsetting the gloom are several positive developments. First, China has largely eradicated the virus and so has a much greater chance of successfully deploying track, trace and testing programmes to prevent future outbreaks. Second, we have seen how quickly activity can recover once restrictions are eased. But most crucially, progress on developing safe and effective vaccines has continued, bringing forward a potential return to normality – or something approaching that condition – by one or two quarters.
We still await more comprehensive data, and there will be logistical and public-relations battles ahead before the world can reach herd immunity – or at least reduce the threat of the virus – to allow most people to resume normal activity.
Yet although the precise timeline remains uncertain, we expect more widespread distribution of vaccines to begin in the spring. As restrictions ease from the winter and confidence builds that the end is in sight, activity could rebound strongly through the course of 2021.
Aiding the recovery will be exceptionally loose monetary policy as central banks focus on preventing inflation from dipping further below target. There is also an understanding from fiscal authorities that next year is not the time to address the large budget deficits caused by the response to the pandemic.
Bringing all this together, our central view expects global GDP to finish 2021 around 3% below its pre-virus trend, but there remains huge uncertainty around this outcome, with risks skewed to the downside should a vaccine be delayed.
Beyond this horizon, there is a concern the pandemic is causing lasting economic damage through capital stock obsolescence and belief scarring, which leads to increased saving and caution around future investment. However, it is also possible to see the potential for creative destruction and increased dynamism, accelerating change and boosting productivity.
Tim Drayson Head of Economics
Asset allocation: The year of hope
We believe the economic outlook is positive for equities, but investors will probably need to think carefully about their allocations to fixed income.
My takeaway from Tim’s economic outlook is that 2021 will be the year of hope. The fundamental backdrop he describes should boost equity markets in particular as investors start to see a potential end to the economic and social hardship of the past year.
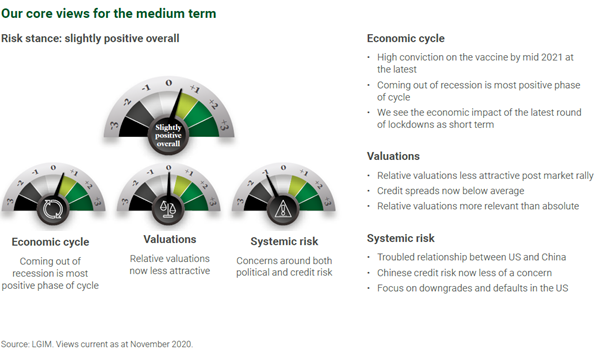
But this isn’t just about optimism. We are only early in the economic cycle, with a meaningful output gap that can still be closed, while recession risk is low and there are limited inflationary pressures. Risk-adjusted equity returns from this point in the cycle have historically been strong.
Valuations are not a troubling headwind either. Equities may look expensive in absolute terms, but on a relative basis the equity risk premium – the equity earnings yield minus bond yields – remains attractive, in our view.
All things considered, our base case would therefore be that equities are among the best-performing asset class in 2021; we would not be surprised to see double-digit returns.
One point to note is that we are obviously not alone in this view. Sentiment has turned bullish for the first time since the pandemic, and at some point in 2021 it is very likely that markets will price in too much optimism. For now, though, we think this is too early to be a dominant factor.
We continue to believe in our ‘lower for longer’ theme in fixed income, seeing limited upside potential for bond yields from their current levels. We expect inflation dynamics will become more important than growth dynamics in determining bond yields once we get past the recession phase. That has been true for the past four cycles, but should be even more important now that the Federal Reserve (Fed) has indicated it will not react pre-emptively.
That should mean positive news on the vaccine rollout is unlikely to be enough to put sustained upward pressure on bond yields. We will also need evidence that inflation is moving sustainably above 2%, which is very unlikely to happen in 2021 with unemployment still extremely high.
On the corporate side, investment-grade credit is in our view less attractive than other risky assets like equities, given the compression in spreads seen since March. Today’s tight spreads are partly a reflection of subdued corporate bond defaults thanks to fiscal support, cheap financing and the prospect of a vaccine in 2021.
Returns from credit do not typically accrue evenly; instead, and perhaps understandably, they tend to be higher when starting spreads are wider. That suggests to us there is potential value in having space in portfolios to add significantly to credit in extreme selloffs. Admittedly, that comes at a cost – namely the returns given up by patiently waiting for a better entry point – but we believe it’s the right framework for thinking dynamically about credit for the medium term.
A low yield environment provides challenges for investors both from a return and a risk mitigation perspective. Though there is no single panacea, one of the measures we believe investors can take is to look at smaller, non-traditional fixed income markets to find better risk-off hedges. Smaller rates markets with higher yields that could still fall become more interesting and important, for example. At the time of writing in mid- November, these include South Korea 10-year bonds yielding over 1.5% and Australian 30-year yields over 1.8%.
Emiel van den Heiligenberg Head of Asset Allocation
US politics and policy: Biden, bonds and the limits of presidential power
Despite its limited room for manoeuvre, we expect the Biden administration to make some ripples in the fixed income market.
Somewhat lost in all of the noise surrounding the 2020 presidential election is the fact that control of the Senate remains undecided: in order to reclaim the upper chamber of Congress, the Democrats need to win both Georgia seats in a runoff election on 5 January.
Betting markets imply about a 30% chance of this happening, as at the time of writing. Yet even if the Democrats do succeed in Georgia, it would be difficult to characterise this victory as looking anything like the ‘Blue Wave’ outcome expected before the November election.
Democrats look to have lost about 10 seats in the House of Representatives, which means Speaker Nancy Pelosi will operate with the slimmest margin in that body for 20 years. A 50-50 split in the Senate could be even more difficult to navigate, particularly as Senator Joe Manchin (D-WV) has expressed opposition to ending the filibuster – a tool to delay legislation and appointees. As such, President-elect Joe Biden’s agenda will likely need to be scaled back significantly.
That said, the last two years of the current administration have demonstrated the power of executive orders to circumvent Congress. A newly elected President Biden will probably use the same tools to tackle immigration, trade, energy and housing policy.
And yet there are likely to be legal setbacks along the way, much as President Trump encountered. Consider energy: while rejoining the Paris Climate Accord should be relatively straightforward, the President-elect’s plans for a green energy policy could hit considerable resistance in courts, where the previous administration was able to appoint more conservative judges.
Biden’s signature agenda items – taxes, healthcare and infrastructure – will face even longer odds. Without being able to circumvent the Senate filibuster, it will be nearly impossible to reverse the Trump tax cuts. As a result, corporate and personal tax rates will stay at current levels at least until 2022, which will in turn lower the likelihood of an expansive infrastructure deal.
Lower for even longer
Meanwhile, it is quite likely that components of the Affordable Care Act (ACA) will be found unconstitutional by the Supreme Court and require legislative fixes. Rather than expanding the ACA as he would like, the new president may find himself fighting to preserve the existing platform.
For bond markets, the failure of the Blue Wave to materialise decreases the likelihood of an imminent shift away from the theme of lower for longer, as less expansive fiscal policy implies there will be less upward pressure on interest rates.
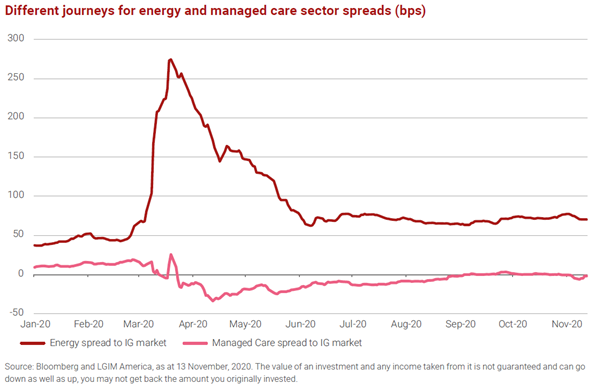
There are equally important implications at the sector level for corporate credit. While US energy companies will remain in focus as investors increasingly consider ESG themes, the pressure on the industry is likely to be less acute with the control of government more divided.
The risks around a wholesale change to the healthcare reimbursement ecosystem seem to have waned, meanwhile, but the managed care and pharmaceutical sectors could yet face headwinds even if they are less severe than previously anticipated.
In short, we believe 2021 is shaping up to be a year of opportunities for fixed income investors, where the policy backdrop will probably remain supportive and the Biden administration will make some ripples in the market – despite the President-elect’s limited room for manoeuvre.
Jason Shoup Head of Global Credit Strategy, LGIMA Fixed Income
Energy: Batteries charge up the renewable agenda
We believe battery technology is the key to unlocking the potential of renewable power, and 2021 could be a pivotal year for this market.
220 years have passed since Alessandro Volta paired copper and zinc discs separated by a layer of cardboard and salted water. Now, thanks to some recent breakthroughs, the battery technology market is again in an early growth phase, ready to power the next technological revolution in 2021 and beyond.
Of course, battery technology has not been static through those two centuries, as is evident from how electronic devices have become ever smaller and able to go for longer without charging.
But two events late in 2020 really electrified the industry: Tesla’s admission to the S&P 500, and the UK’s plan to ban the sale of new cars fuelled solely by petrol or diesel from 2030.
Epitomised by the rise of Tesla, a company that we believe should be recognised as much for its battery innovation as its car design, these welcome steps illustrate how investors can focus on batteries principally as an element of the electric-vehicle revolution.
That market, however, is only part of the role batteries will play in helping the world move to a less carbon-intensive economy. We believe they will also be vital in harnessing the potential of renewable energy.
Charging at windmills
Fossil fuels have accounted for most of the world’s mix of power generation since the 1970s, but according to BloombergNEF, renewables are now poised to take the lead. Wind and solar technologies alone are expected to provide 48% of all our electricity by 2050.
This progress is both exciting and essential, but the utility of clean energy will be limited without better and more extensive battery storage. Improved energy storage can help overcome the short-term intermittency – due to daylight hours or fluctuating weather – of renewable sources. Without an upgraded storage infrastructure, much of the electricity that could potentially be generated by renewables will be lost, and coal and gas-fired power stations will remain necessary to cover supply shortfalls.
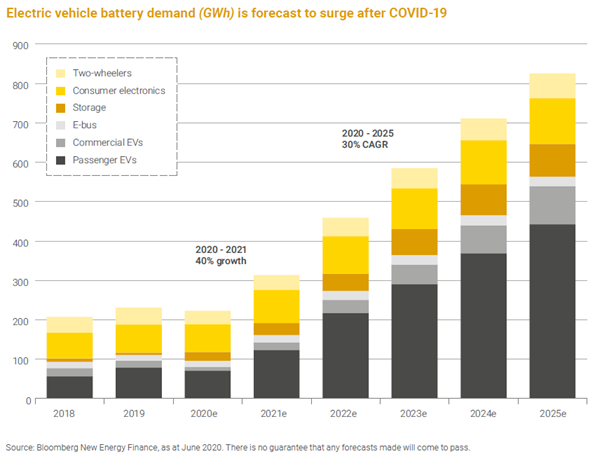
Electric vehicle battery demand (GWh) is forecast to surge after COVID-19 Encouragingly, 2021 should be a marquee year for storage capacity. The world’s largest new battery installation was completed near San Diego in August, and we expect that record to be broken again next year. For example, the new San Diego plant has a capacity of 250 megawatts (each megawatt can serve an estimated 750 homes). Another new project just south of San Francisco will provide 400 megawatts of storage when completed in 2021.
Maintaining this trajectory of progress, underpinned by the advances made in battery technology, will be critical in achieving the energy transition necessary to avert the climate emergency.
Aanand Venkatramanan Head of ETF Investment Strategies
Letter from Hong Kong: Meanwhile, in China…
China’s financial sector is clearly growing more dynamic, opening up significant opportunities for international investors, in our view.
While global investors have understandably focused on the US election, virus waves and a potential vaccine, seismic events have also been occurring in the world’s second largest economy with similarly significant implications.
First, it’s easy to underplay just how successful the country has been at controlling the virus and returning to pre-pandemic economic output. The benefits of an efficient track-and-trace system are obvious. And by getting back on its feet quickly, China has avoided much of the sustained unemployment and defaults that will scar Western economies for years to come.
The cost is government control of private data. But for now, economic practicalities dominate such concerns and, in our view, China is well placed to be a relative winner from this crisis.
The technology sector has been another pandemic winner, but the second key event in China has been the regulatory focus on its domestic players. Clearly, the country has some extremely successful technology companies, with Alibaba recently announcing that Singles Day sales totalled 498.2 billion yuan, an increase of 26% versus last year.
But Alibaba’s founder Jack Ma publicly criticised Chinese regulators for holding back technological innovation, with an investigation and suspension of Ant Group’s impending IPO quickly following, ultimately causing the roughly $35 billion capital raise to be postponed. This doesn’t look like an isolated incident, with China announcing a set of draft rules against the broader monopolistic behaviour of its technology sector. A motivation for such intervention is to protect consumers and nip fintech systemic risks in the bud.
Constrained expansion
Does this spell the end for the Chinese technology boom? Certainly not if you believe the latest plenum of China’s Communist Party, which declared that self-reliance in science and technology is a strategic pillar of national development.
Perhaps the unconstrained expansion is over. But even constrained growth is attractive in a country expanding much faster than Western economies, so many investors could see recent market volatility as potentially an opportunity to add exposure.
The final key event is actually more of an ongoing trend, arguably even more important than the first two. This is the opening up of domestic Chinese financial markets; the internationalisation of the renminbi; and the introduction of risk into previously ‘bullet-proof’ investments, such as dominant property developers and bonds issued by state-controlled entities.
The direction is clearly towards a more dynamic financial sector, with significant opportunities for international investors. Here, the result of the US election will be influential, as the new administration will have to decide how much to push against China’s globalisation and how much to embrace it.
Once a COVID-19 vaccine has been successfully deployed, perhaps we can also remember 2020 for this hugely important development, which will be the topic of future Letters from Hong Kong.
Ben Bennett Head of Investment Strategy and Research
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
The 2021 forecasts are all starting to be released now – expect more to follow.
This year has been an interesting year (to say the least), now we just have to hold onto our seats and see what next year will bring!
Please see below an article received from Invesco yesterday afternoon providing their views on the ongoing Brexit negotiations:
As you can see from the above, negotiations remain on a knifes edge, however, a deal would be more beneficial for both sides and as suggested above, it could be that a deal is agreed in the 11th hour.
If a deal was to be agreed, we would expect this to have a positive impact on markets and the opposite would also be true.
We will continue to provide details on any announcements made on a deal or no deal scenario and what impact this could have on markets and investments.
It is important to remember, whatever the outcome may be, it is important to remain invested and focus on your long-term objectives.
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
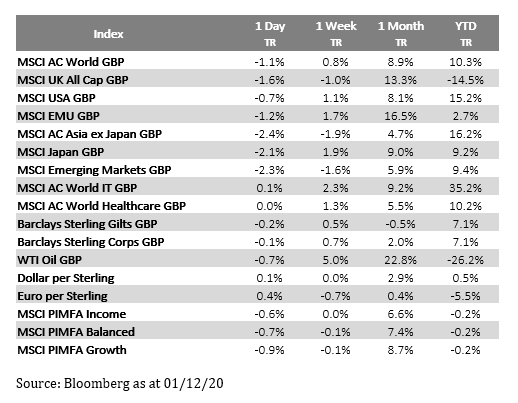
Please below the latest ‘Markets in a Minute’ update from Brewin Dolphin – received last night 01/12/2020 Markets in a minute: Equity rally pushes global markets to record highs
01 . 12 . 2020
It’s been an historic week for equity markets as numerous indices hit all-time highs. In the US, the Dow passed the 30,000 level for the first time and the Russell 2000 index of small cap firms also hit a new record. Japan’s Nikkei hit a 29-year high and the MSCI Global Index hit its highest level ever. Here in the UK, the FTSE100 enjoyed its best month since 1989, rising by 12.4%. The rally has been prompted by positive vaccine news and high hopes of a return to normal in 2021, plus Donald Trump finally appeared to accept his defeat.
Last week’s markets performance*
FTSE100: +0.25%
S&P500: +2.27%
Dow: +2.12%
Nasdaq: +2.95%
Dax: +0.46%
Hang Seng: +1.67%
Shanghai Composite: +0.90%
Nikkei: +4.37%
*Data for week to close of business on Friday 27 November.
Stocks fall as investors take some profits
Global markets were largely down at the start of the week, with US indices retreating from their highs. The Dow fell by 0.91% while the Nasdaq closed down just 0.06%.
Here in the UK, the FTSE100 fell by 1.59% with most of that fall occurring in the last hour of trading.
This is a classic sign of profit taking; when investors look at their portfolios at the end of the month and see big gains in equities and relatively lacklustre performance from other assets such as bonds and cash, it is typical for many investors to cash in some profits, leading to a downturn in prices. The next question is whether we will see a classic ‘Santa’s rally’, the phenomenon that sees shares rise in most years in the run-up to Christmas.
Black Friday sees online sales surge
Digital sales rose by almost 22% on Friday compared with last year, with Covid-19 leading shoppers to spend around $9bn online instead of going into physical stores. Another interesting aspect is that 40% of those sales were booked over smartphones, highlighting two secular trends that we think are here to stay, even as the pandemic fades over the next couple of years.
Property boom
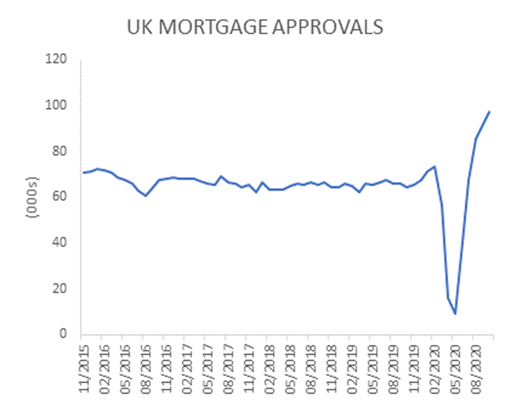
UK mortgage approvals hit a record high in October, reaching their highest levels since 2007 as buyers rush to complete purchases before the government’s temporary stamp duty holiday ends next Spring. The news comes despite rising unemployment and falling economic activity.
There were 97,500 mortgages for home purchases approved in October, up by a third compared to February, before the pandemic started. Economists expect the mini boom to continue until the stamp-duty break ends in March, as new working habits prompt more people to trade up or move out of towns as they envisage working from home more often, even after the pandemic.
After that point, the consensus is for activity to begin reflecting the economic fundamentals, as rising unemployment and mortgage rates take their toll and the cautious attitude being exhibited by consumers on the high street spreads to the housing market.
Source: Bank of England Data: 30/11/2015-31/10/2020
Households repay credit and loans
Data from the Bank of England showed signs of a slowdown in consumer spending, with households repaying a net £600m of consumer credit in October. That means consumers are repaying more in loans and credit cards than they are borrowing. In contrast, consumers were borrowing roughly £1bn a month before the pandemic.
This is important because consumer borrowing tends to form the basis for most economic recoveries. This time, however, a vaccine and return to the office may do the trick instead, helping bolster spending in suffering town centres.
Interest rates
There is an expectation that interest rates will stay close to zero for some time, but beyond the next few months, rates in the UK and US could begin to diverge.
For the immediate future the outlook looks like it should improve for the UK as it emerges from lockdown, while the US remains vulnerable to further tightening measures. The US economy has remained resilient so far, even according to high frequency data, but the latest initial jobless claims showed rising claims for the last two weeks, while consumer sentiment exhibited worries over the outlook for the employment, which may keep rates low in the US and help push the case for more monetary and fiscal stimulus.
This week’s ‘Markets in a Minute’ from Brewin Dolphin focuses on this week’s market rally which has been prompted by positive vaccine news and the hopes of a return to normality during 2021.
Please continue to check back for our regular blog posts and updates.
Please see below update received from Brooks Macdonald this morning. It explains where the markets stood by the end of November, as the world continues to wait for vital vaccine efficacy results in the fight against Covid-19.
What has happened
With yesterday’s close November capped off one of the best months of performance for global assets. The quid pro quo was weakness in safe havens such as the US dollar and gold, but sovereign bonds were remarkably resilient as monetary accommodation outweighed the changing vaccine winds.
OPEC+ delayed
The OPEC+ meeting that was planned for today has been pushed back to Thursday as members needed to have further discussions ahead of the summit. The main items on the agenda is whether or not to keep to a planned easing of supply cuts from the start of January. The oil price is walking a tightrope at the moment, with vaccine hopes for a faster recovery on one side, against continued COVID risks during the winter months on the other. As well as trying to judge the likely pace and scale of the nascent global economic recovery, OPEC+ members also have the challenge of keeping production discipline intact. Should OPEC+ members break ranks on production, this risks a lot more volatility for the oil price as well as uncertainty for the energy sensitive parts of the market.
COVID update
Whilst we didn’t, as expected, see any new vaccine efficacy results yesterday the incremental vaccine news continued. Moderna announced that it would request emergency authorisation from both the US and EU regulator and Novavax said that its UK study was expecting results soon. Meanwhile cases continue to fall in Europe with the UK seeeing its 7-day average move to early October levels and France seeing its lowest daily case rise since August. Of course, the UK partial lockdown is about to ease so there will be a knock-on impact on cases down the line, but this will all occur with a familiar lag. In the US we have seen cases continue to rise particularly in the original hot spot, New York, and the summer hot spot of California.
What does Brooks Macdonald think
Whilst November was an exceptionally strong month for equity returns the relative outperformance of cyclical equities over defensives was the main story. Selectivity remains key within the cyclical sectors as there are some areas, such as bricks and mortar retail, that have likely seen their decline accelerated by the pandemic. For others, such as airlines, it’s too early to say whether COVID-19 will cause a permanent reduction in business travel for example. This may prevent some sectors from rallying to their start of year levels for some time.
We will continue to publish relevant content and market updates as we enter the final month of a challenging year. Please check in again with us soon.
Please see the below market update from Brooks Macdonald:
US and Global markets hit all-time highs as vaccine euphoria continues
European COVID-19 cases fall as US numbers continue to mount
Brexit talks enter yet another key week as one month of transition period remains
US and Global markets hit all-time highs as vaccine euphoria continues
US and Global markets hit another all-time high on Friday as the vaccine tide lifted all ships. Signs of a smoother transition from the Trump Presidency to Biden also spurred a regional outperformance of the US over Europe despite the former having more of a growth skew within its mega caps.
European COVID-19 cases fall as US numbers continue to mount
This may be the first Monday in a month that does not have a vaccine efficacy trial linked to it. Over the weekend, there were several reports suggesting that the UK could be the first country to approve the Pfizer vaccine, while the US Surgeon General is expecting Pfizer to seek authorisation for emergency use on 10 December. This means the first round of vaccinations may occur in the UK and US ahead of Christmas. This may increase the palatability of shorter-term restrictions that are the source of a Conservative MP revolt in the UK currently. More generally, the weekend continued the narrative of slowing infections in Europe but cases that continue to grow in the US. The state level restrictions in the US are more piecemeal, meaning the response, as we saw over the summer surge, tends to be slower and less uniform.
Brexit talks enter yet another key week as one month of transition period remains
Another ‘key’ week for Brexit passed uneventfully though; with only four weeks left until the end of the year, the key one must surely be approaching. This week, face-to-face meetings continue and comments over the weekend suggest that a deal is getting closer. On the level playing field, UK Foreign Secretary Dominic Raab said that he could see ‘a landing zone’, similar to words used by the EU a few weeks ago. This implies that the main issue is now fisheries, which remains a sticking point despite the small contribution that the industry provides to GDP. The UK Government is concerned that giving too much ground on fisheries will mean that the UK has not ‘taken back control’ of its borders. While the next UK election is a long way away, there is undoubtedly a political angle to the optics of any deal. With the three developed world vaccine front runners having reported their early stage efficacy, this week may be less dramatic in terms of stock rotations. The US jobs report on Friday may be a source of volatility, however. Initial Jobless Claims have risen for the last few weeks, so investors will be watching closely to see if this is sufficient to stop the improvement in headline employment numbers.
Please keep checking back for our regular blog updates.
Please see below for the latest Blackfinch Group Monday Market Update received by us today 30/11/2020:
UK COMMENTARY
Prime Minister Boris Johnson announced an end to the second national lockdown, with the country moving to a three-tier system after 2nd December. Additional rules governing the Christmas period were also announced, with three households allowed to form a ‘bubble’ between 23rd and 27th December.
The Composite UK Purchasing Managers’ Index (PMI) fell to a six-month low of 47.4 in November, from 52.1 in October, indicating a contraction in business activity. The services sector PMI contracted from 51.4 to 45.8, while there was expansion in manufacturing from 53.7 to 55.2.
Rishi Sunak announced the Government’s latest spending review. He confirmed that £55bn of COVID-related spending is in place for the next fiscal year, in addition to the £280bn allocated for 2020.
The Office for Budget Responsibility released its forecasts, showing its central case. This is where vaccines are widely available from mid-2021, leading to the economy being approximately 3% smaller in 2024/25 than if the pandemic hadn’t happened.
US COMMENTARY
The General Services Administration announced that it would begin the formal transition process to the president-elect Joe Biden. This will allow Biden and his team access to both funding and government agency officials. It’s the first sign that a smooth transition of power may take place.
Initial jobless claims came in ahead of expectations at a five-week high of 778,000
The Federal Reserve meeting minutes from early November showed that policymakers will consider further stimulus via asset purchase mechanisms
ASIA COMMENTARY
China’s industrial profits rose for the sixth consecutive month, posting an increase of 28.2% year on year according to the country’s National Bureau of Statistics
COVID-19 COMMENTARY
Results from clinical trials of the COVID-19 vaccine in joint development by Astrazeneca and Oxford University showed 70% effectiveness across all dosing regimens tested. One regimen showed efficacy of 90%.
These articles provide concise well-informed views that cover the whole of the market and are useful to maintain your up to date view of the markets globally.
Please keep reading our blogs regularly to give yourself a holistic and up to date view of the markets.
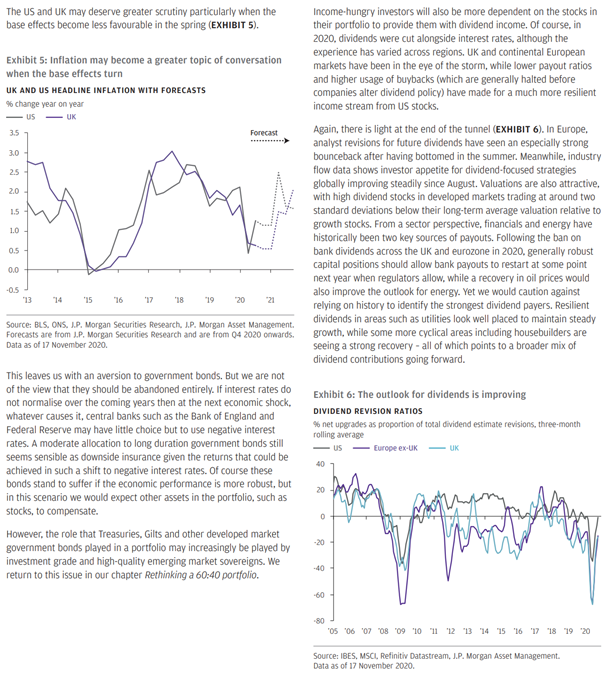
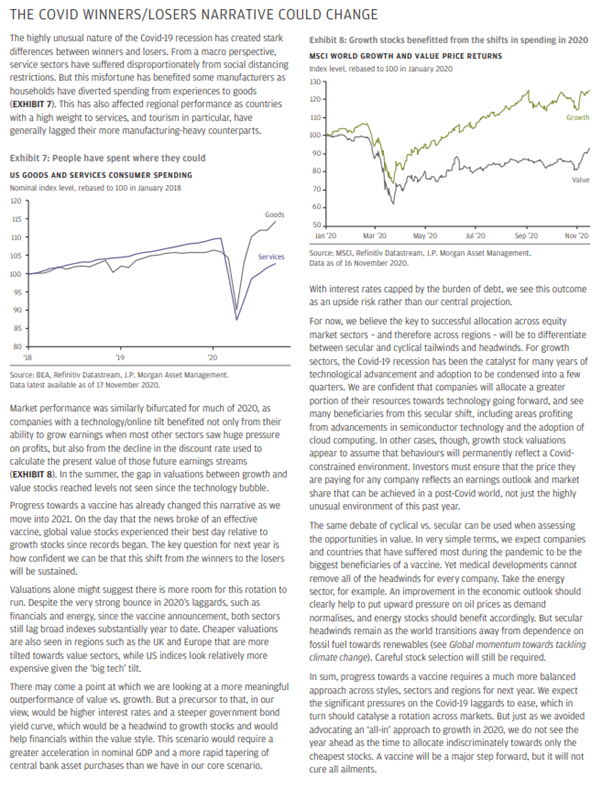
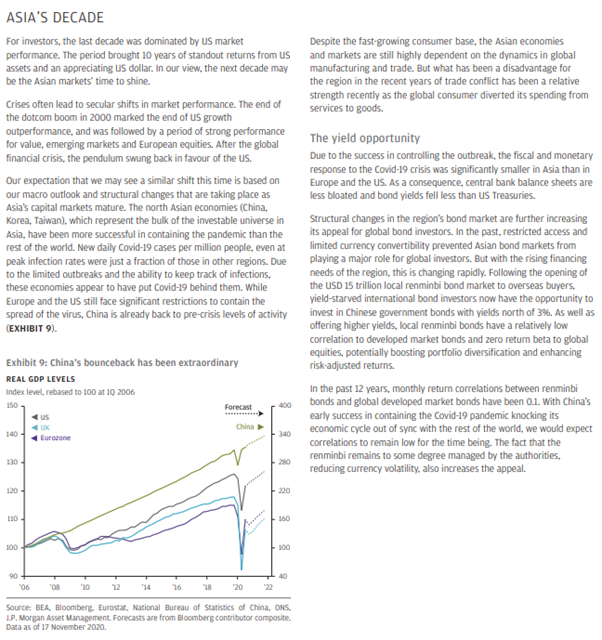
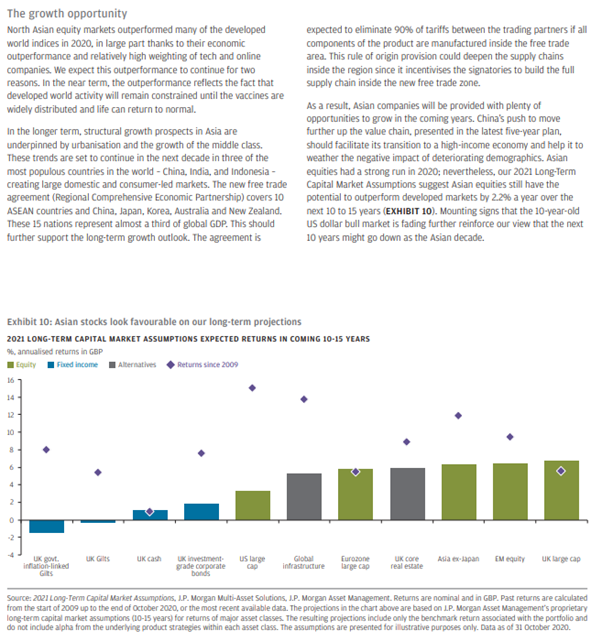
Please find below an article from J.P. Morgan which was received late on Friday and outlines their outlook for investments for 2021:
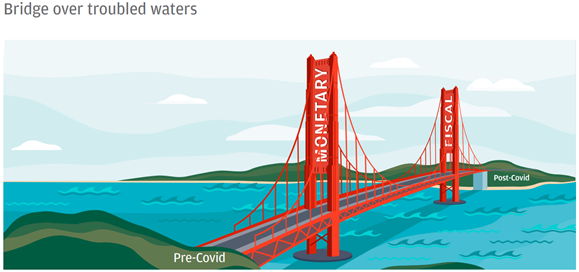
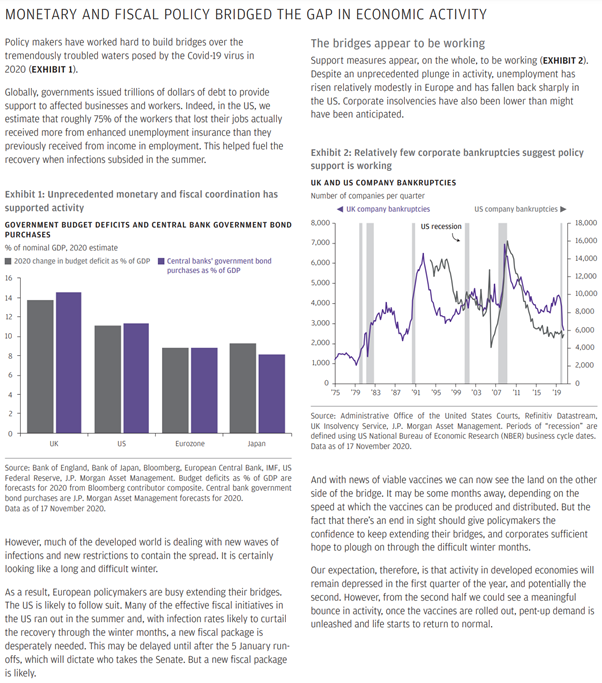
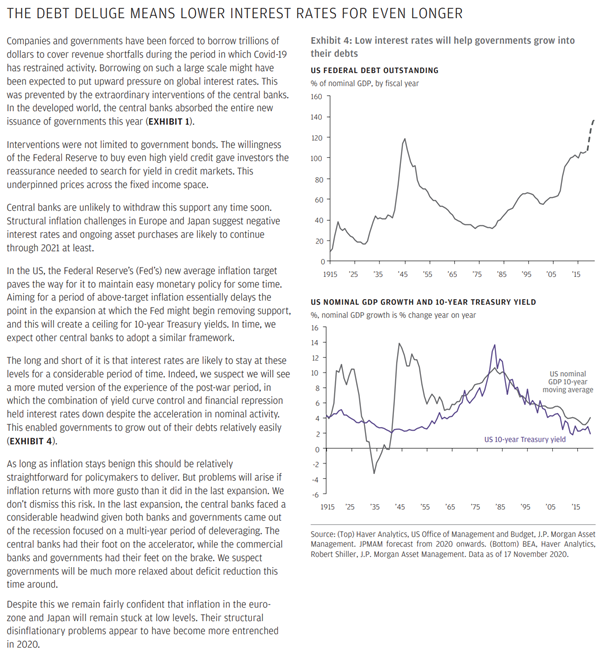
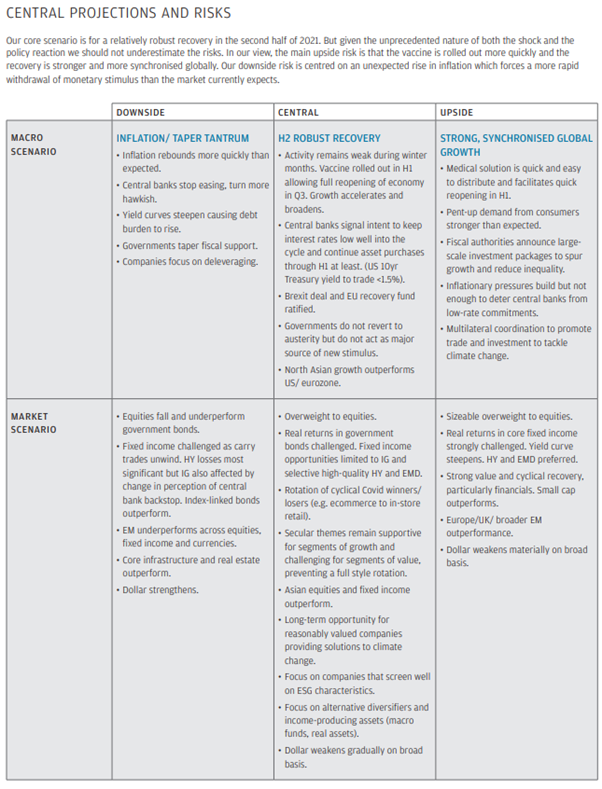
As you can from the above, the action taken from central banks has really helped economies get through these hard times.
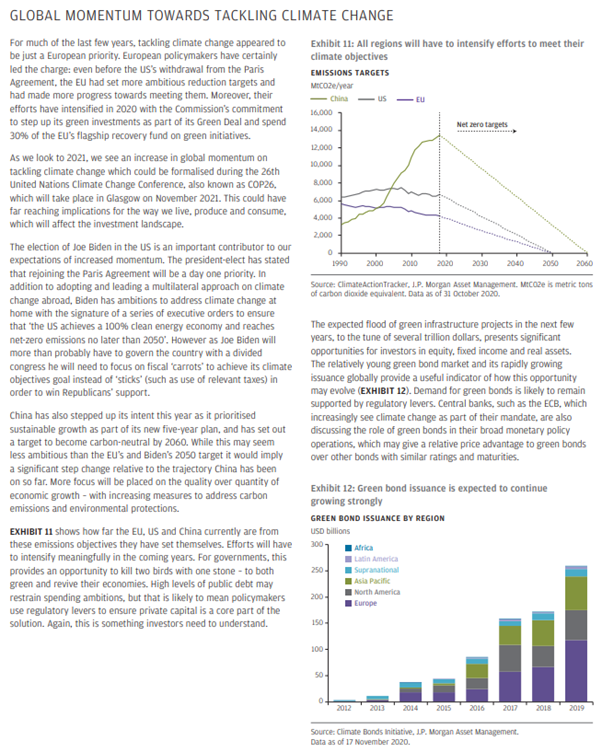
There will be more of a focus on investing in investments/companies that have a positive effect on the environment, also known as, Environmental, Social and (Corporate) Governance (ESG) as the world attempts to work together to reduce the impact of global warming.
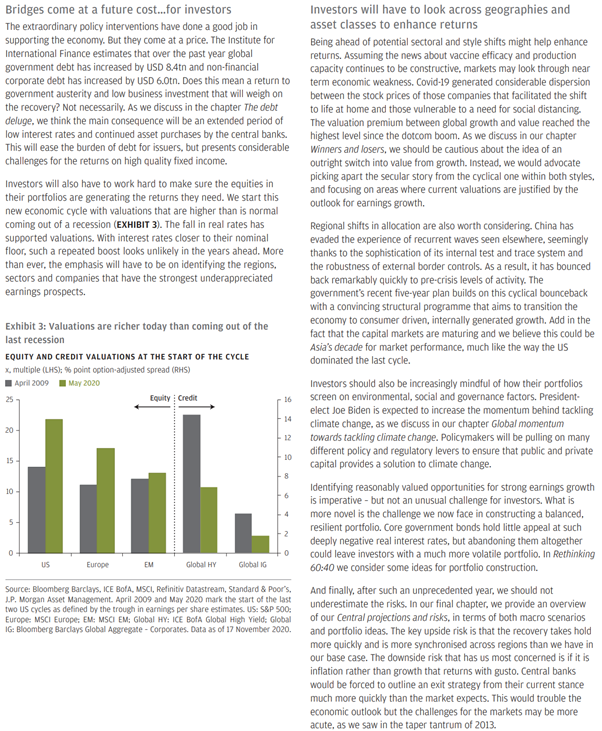
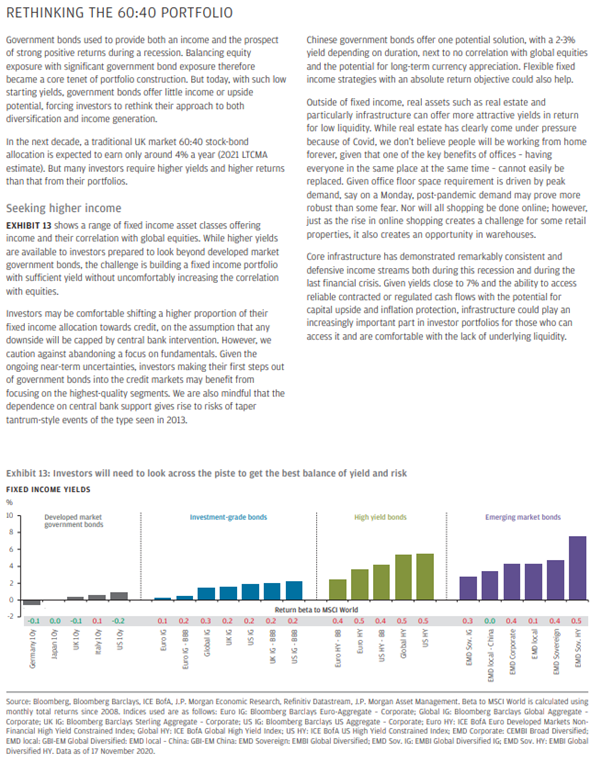
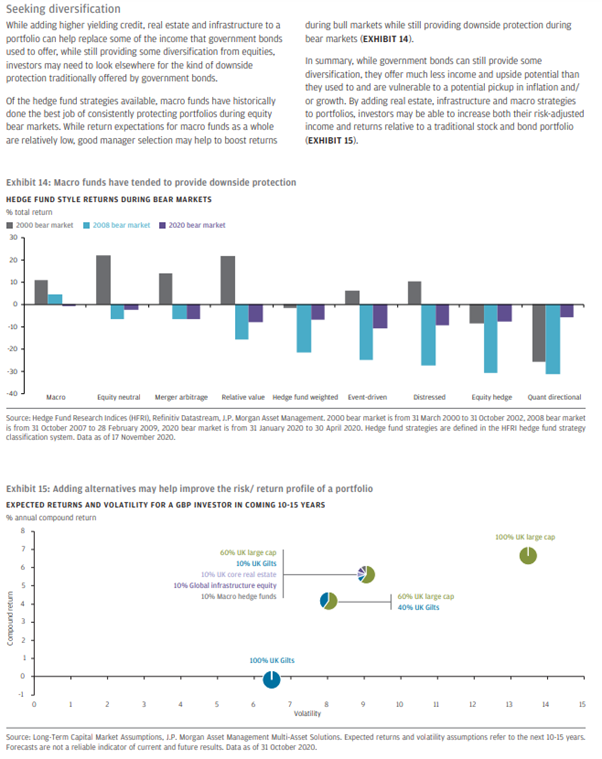
Overall, Diversification across geographies and assets classes will be important now more than ever, as investors seek real (post inflation) investment returns.
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
This is the first of our 2021 forecasts – expect more to follow.
I’ve just cut and paste this from an article received from A J Bell yesterday, Sunday 29/11/2020. It’s a little late into the pandemic but I agree with most of the content.
1. Can you use other income sources to tide you over?
If you take taxable income from your pension, your annual allowance will reduce from £40,000 to just £4,000 (the ‘money purchase annual allowance’ or MPAA). This is one of the main reasons why you might avoid taking taxable income from your retirement pot. If you have money saved in an ISA, for example, you could consider taking this out tax-free, while also keeping your full pensions allowance intact.
2. Take your tax-free cash first
Note that the MPAA only kicks in if you take taxable income from your pension pot. So if you have no other options open to you, taking only your tax-free cash will at least leave you more flexibility to rebuild your retirement fund later on.
3. Do you have a plan?
If you have been forced to access your pension early – or are planning to in the coming months – spend some time thinking about how you can rebuild your fund once your income bounces back. It might be that you need to pay more in as a result to get back on track, or consider working a bit longer. But whatever you do, don’t stick your head in the sand.
4. Sustainability is the key
For those who have already stopped working and are taking a retirement income via drawdown, it is vital to review withdrawals regularly to make sure they remain sustainable. These reviews should happen at least annually, and you should be prepared to potentially reduce your income if your investments suffer significant short-term falls (as we saw in March and April).
5. Consider a ‘natural income’ route
A ‘natural income’ retirement strategy involves living off the dividends your investments produce, thereby preserving the capital value of your underlying fund, allowing it more time to grow. While a natural income strategy has been particularly difficult in 2020 as swathes of companies have cut dividends, positive vaccine news could mean it is more viable in 2021 and beyond.
Summary
I struggle with the last point on a ‘natural income.’ If this were for your main source of income, you would have to be able to manage significant variation in income yields, particularly at the moment. This would work for a secondary income, a top up income from, for example, a Stocks & Shares ISA portfolio.
From my point of view, I advise all clients to build at least three different assets to help manage risk and aid tax efficiency in retirement; cash deposits, Stocks & Shares ISA portfolios and pension funds.
If markets drop as they did in March and your pension fund values follow, you can then switch your Drawdown pension income off, start to draw on your cash deposits to cover living costs and wait for the market to recover. This will help you protect your pension assets for the long term. As the markets recover, you can start your Drawdown pension income, perhaps at a lower level initially.
When markets fully recover, you can use your Stocks & Shares ISAs to top up your cash deposits. Your Stocks & Shares ISAs and pension funds remain invested and recover in value so that you are fully prepared for the next shock to markets – hopefully, a good long time away.
Any guaranteed income you have, for example State Pensions, will help through volatile periods.
Please see article below from Jupiter Asset Management which provides their latest market views – received today 27/11/2020
Active Minds – 26 November 2020
James Moir – Analyst, UK Growth
The normalisation of UK politics has begun
James Moir, Equities Analyst, UK Growth, gave an update on how the UK market has reacted to news flow in November. The Covid crisis has had a particularly severe impact on the UK market, given the relatively high weighting to oil & gas, financials and miners. As such, it has rebounded more than most developed markets this month on the back of the positive vaccine developments.
Although the bounce back has been strong, James pointed out that sectors such as oil & gas and banks are still significantly down year-to-date. James gets the sense that there has been a bottoming out of assumptions for the energy stocks, while the absolute bear case for bank credit losses might be avoided now that vaccines are imminent.
In terms of style, it has undeniably been a good month for Value, but Growth stocks in the UK have nevertheless delivered absolute gains this month. In any case, the winners and losers from Covid haven’t neatly aligned with the Value/Growth divide, with James and the team identifying many companies they consider long-term Growth stocks that have been adversely impacted by Covid and have had a strong November.
Company news is fairly thin, given that this isn’t reporting season, but there have been a couple of M&A deals that are notable for being domestic-focused UK companies that are being acquired ahead of Brexit.
Turning to Brexit, James sees it as significant that a normalisation of UK politics appears to be underway. In the past month, the UK government has announced a 10-point plan on the environment, and increased the defence budget by almost 10%. Leaving the detail of this spending aside, James said it is important that the UK government is now being more active on priorities beyond Brexit, with many issues long overdue for being addressed, and that should be encouraging to all investors in the UK market.
Ivan Kralj – Assistant Fund Manager, Absolute Return
Is this the start of a prolonged rotation back into Value?
Ivan Kralj, Assistant Fund Manager, Absolute Return, shared his thoughts on the ‘Growth to Value’ rotation narrative. Although some of the daily moves over the past few weeks have been extraordinary, in magnitude and in the context of any longer timeframe, those moves were mere blips, said Ivan. He continues to see huge gaps between share price and valuation, and massive spreads between companies that are perceived as being ‘fit for the future’ which are trading on triple-digit P/E ratios and price-sale ratios above 30x, and those that are viewed as ‘boring’, asset-heavy companies which are trading on historically low single-digit P/Es and offering around 10% dividend yields.
So, why is this happening? As Value investors are facing large redemptions and are forced to liquidate positions, prices are being driven down. Ivan noted a recent academic paper that found how surprisingly price inelastic the stock market is, and that flows in and out of the market are having a significant effect on price – this seems to confirm that it’s liquidity rather than fundamentals that is driving many of today’s moves, said Ivan. However, he thinks it’s wise to assume that valuations will one day matter once again. Market experience over the past decade doesn’t mean that anything has fundamentally changed, even though valuations have been poor predictors of share prices over that period. There’s a century’s worth of quantitative and behavioural evidence that suggests investors tend to under-price stocks with the poorest prospects and over-price those with the most promising prospects.
While it’s too early to tell if a prolonged rotation back into Value stocks has begun, Ivan thinks Russell Napier’s recent essays provide the most compelling narrative in terms of potential catalysts. Napier argues we’re transitioning from a new era where governments are seizing the money creation mechanism from central banks, and they’re incentivising commercial banks to lend to businesses and consumers in the real economy, through various government-backed lending programmes. That should create money, potentially leading to inflation and nominal economic growth. In that scenario, said Ivan, if inflationary expectations were to change then Value stocks should do really well.
Patty Cao – Assistant Fund Manager, Emerging Markets Debt
Goldilocks scenario supports emerging market debt in 2021
The election of Joe Biden as US president has been positive for emerging markets (EM) in that it potentially reduces trade tensions and brings a more conciliatory foreign policy, and the vaccine news has also provided a boost, said Patty Cao, Assistant Fund Manager, Fixed Income. Inflows have reached a three-month high in emerging market debt, and net flows have turned positive for the year. Last week saw inflows of $3.2 billion into the asset class, split evenly between local currency and hard currency, Patty said, citing JPMorgan data.
These trends should continue next year, in her view. The team is expecting a Goldilocks scenario (not too hot, not too cold) for EM, a year of repair and renewal. Economic growth should improve sharply, with China and India each forecast to expand by around 9%, and rebounds elsewhere as vaccines roll out and markets and economies come back to life.
There is a cyclical upswing in growth, and there is plenty of support from central banks across the globe, Patty said. This should keep the US dollar relatively weak and inflows into the asset class robust, which is supportive of asset prices. In her view it makes sense to stay bullish on EM credit, and local currency and sovereign debt.
Colin Croft – Fund Manager, Emerging Markets
Low cost, simpler vaccines are great news for emerging markets
As you would expect, the positive news flow around vaccines has been positive for Emerging Market (EM) equities, said Colin Croft, Fund Manager, Emerging Markets. The data from the Oxford University vaccine has been especially impactful, he said, as the relatively low cost and simpler logistics (the vaccine is stable at normal fridge temperatures) compared to the earlier announced results should help wider distribution across emerging markets.
This moves us towards a recovery scenario which ought, over the next 6-12 months, to drive outperformance of the most beaten down and economically sensitive sectors such as airlines and banks, said Colin. Some of the banks in emerging markets have been relatively resilient anyway, he highlighted, without having to raise equity and making significant upfront provisions early in the pandemic. This means that several of them are already showing a rapid rebound in earnings as provisions come down. Colin also touched on the US election. As we inch towards a Biden presidency, Putin is one of only three major foreign leaders yet to congratulate him. There have been some worries that Russia might face the risk of more sanctions once Trump is gone, so last week Colin joined a call with a former US Ambassador, who is close to the Biden team and designed the current Russia sanctions regime back in 2014. His view was that Russia doesn’t face an immediate threat of new economic sanctions – while Biden was sceptical of Obama’s reset and is unlikely to try something similar, he is also unlikely to escalate sanctions without a fresh reason to do so.
So, a Biden presidency might not be as bad as feared for Russian assets – but the caveat is that this will depend on what Russia does – if they do cross certain lines again, then there would be a greater likelihood of better-targeted US action, that is better coordinated with allies, than under Trump. So Colin’s view is that if something does happen he’d be more inclined to turn bearish on Russia, but for the time being Biden shouldn’t necessarily be seen as a negative for Russian equities.
Please note: Market and exchange rate movements can cause the value of an investment to fall as well as rise, and you may get back less than originally invested. The views expressed are those of the individuals mentioned at the time of writing, are not necessarily those of Jupiter as a whole, and may be subject to change. This is particularly true during periods of rapidly changing market circumstances.
A good update from Jupiter Asset Management’s fund managers, providing a useful insight into the markets.
Please continue to check back for our latest blog posts and updates