Team No Comments

Where are we now? (Part 1)

I had the privilege of listening to a webinar on Wednesday afternoon, which was hosted by Karen Ward from J. P. Morgan and also featured Dr. Gertjan Vlieghe.  Karen is JPM’s Chief Market Strategist for EMEA (Europe, Middle East and Africa) and Dr. Gertjan Vlieghe is a voting member of the Bank of England’s MPC (Monetary Policy Committee). 

The interview covered a wide range of important topics and I took notes in order to interpret the speakers’ key points.  Please note: Gertjan did point out that the opinions expressed where his views and not necessarily those of the Bank of England’s MPC.

Karen on the topic of the Pfizer vaccine:

‘A 90% efficacy rate is a ‘Game Changer.’  The timing is excellent (of the vaccine against the current backdrop of a high second wave of the virus).  How quickly will we get to that important point of herd immunity?’

Karen went on to ask Gertjan, ‘If the vaccine is distributed, could we be looking at a very strong bounce back in the second half of 2021?’

Gertjan replied, ‘Only if the vaccine works. In a way, the vaccine is already in the forecast. That is precisely what our central forecast is.’

Karen then asked, ‘What will you be tracking to assess the degree of long-term scarring?’

Gertjan’s response was ‘Unemployment dynamics – it’s difficult to all get back into a job.  There is still some slack in the economy and levels of unemployment will not come back down for a long time.  We will need stimulus.’

In relation to Brexit, Karen asked, ‘How is it going and what are the changes that will affect Q1 2021 and the longer term?’

Gertjan responded, ‘This is a longer-term issue. There is a trade-off between sovereignty and smooth and open trade.  It will have a purely economic consequence. We will have less trade, less competition and less technological diffusion.  This is very important for the country, but not for monetary policy.  It has also dampened investment (in UK businesses).  To what extent are UK firms ready?  How much disruption will there be in the short term?  How will financial markets react?  This will impact on monetary policy; it’s about how smoothly we transition.’

Karen on Central Banks, ‘Have Central Banks been monetarily financing governments?’

Gertjan replied, ‘On ‘Co-ordinated action’, I’m not entirely happy with it.’  Fiscal policy is doing the heavy lifting and monetary policy is helping. 

He continued to remark on QE (Quantitative Easing), ‘We expand reserves beyond what banks really need.  The macro-economic impact is very small and expansion in reserves does not lead to a proportionate response in lending.  In 2008/2009, re QE, we had no high inflation.  If inflation does come back, we know what to do; there is no constraint.’

Karen’s next question was, ‘Could a government less focused on austerity contribute to a higher velocity of money?’

Gertjan responded, ‘Completely, absolutely.  Timing is crucial in relation to the government flipping back into debt reduction mode.’

Karen then asked, ‘What can the Bank of England do to support the economy?’

Gertjan replied, ‘The impact of QE on the economy is state-contingent.  When market functioning is impaired, QE can have a big impact.  Expectations of future real interest rates are really very low.  The stimulus power (of QE) now is very low.  With regards to technical constraints, it’s important to understand that they are self-imposed – we can change the rules.’

Comment

This update is based on my interpretation and notes from the first half of the webinar’s discussion and I have tried to stay faithful to the content.

From my point of view, I was happy with the Dr.’s input as he obviously understood everything in detail and had no problem with any of the questions put to him by Karen.  He also gave me confidence (based on his views), that these people on the Bank of England MPC really do know what they are doing and are a great aid to the recovery of our economy in the UK.

Summary

Over the next few days, I will work on a precis for Part 2 of the webinar for you, which starts with a discussion on negative interest rates.

If you have any topics that you think we should cover on markets, advice or planning issues, please let me know.

Steve Speed

13/11/2020

Team No Comments

Vaccine Update

Please see the below updates from AJ Bell regarding this week’s news on the Pfizer vaccine:

Is the vaccine news a game-changer or just a good start?

There are high expectations for Pfizer and BioNTech to win with their Covid-19 vaccine following the latest trial update which triggered a global stock market rally and installed hope in people around the world.

The two companies will collate data until the third week of November before submitting to the regulators for approval. Safety is very important given the scale of deployment with potentially billions of perfectly healthy people being given the vaccine.

Assuming more data confirms the 90% effectiveness of the vaccine there are other considerations as more news arrives over the coming weeks.

The first big question is for how long the vaccine will provide immunity because there is no guarantee that vaccine-induced immunity will be any better than that afforded by infection.

Second, the science behind this vaccine is known as mRNA and it has never been commercialised which means no one knows for sure how to manufacture it at scale. The technology involves injecting a blueprint of the vaccine into the cells of the body so that they can make copies of the vaccine.

The vaccine needs a cold storage supply-chain because it has to be stored at minus 80 degrees centigrade. The lack of available cold refrigeration infrastructure, especially in poorer areas of the globe, may hinder distribution of the vaccine.

According to Shore Capital it is unclear at this point whether the study included patients with severe symptoms which is very important because if it didn’t it would mean the vaccine can so far only make mild cases more mild and not prevent hospitalisations.

Pfizer has targeted production of around 50 million doses for 2020 and 1.3 billion next year.  Various countries have already secured agreements with Pfizer including the UK with 30 million doses. Shore Capital points out that because two doses are required and assuming wastage this would only cover around 12 million patients. It takes 28 days from the first injection to attain immunity.

The broker notes that the world will need more than one vaccine because a range of sub-groups are likely to respond differently to vaccines. Mark Brewer, analyst at FinnCap, argues that global herd immunity requires 60% to 70% of the population to become immune which given the huge numbers involved could take years to achieve.

In short, don’t expect the economy to open up quickly even if a vaccine is approved.

Two late-stage trials with results expected in the next few weeks are University of Oxford’s and AstraZeneca’s (AZN) study of compound AZD1222 and Moderna’s vaccine candidate mRNA-1273.

Both these studies include patients with severe Covid-19 symptoms and so a positive result may be more meaningful in terms of reducing hospitalisations.

Where we stand after markets’ vaccine boost

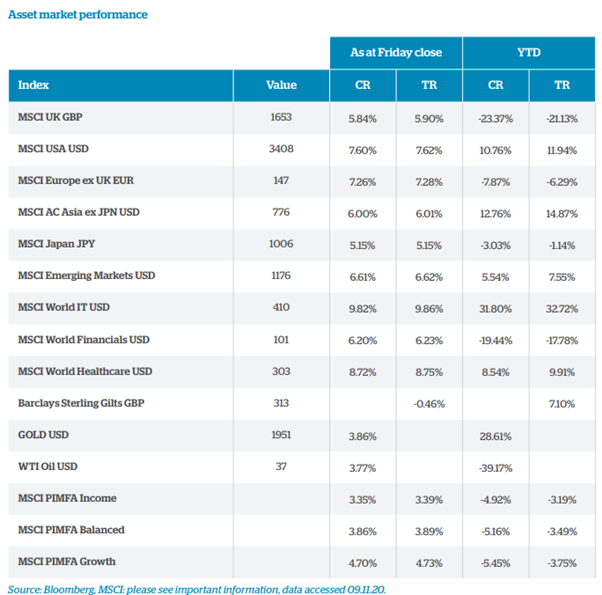
he near-5% gain for the FTSE 100 on 9 November reflected news of extremely positive results for the vaccine being developed by Pfizer and BioNTech.

This was the biggest gain since the index surged 9.1% on 24 March when investors reacted to a rescue mission by central banks during the wild trading seen at the outset of the global pandemic. Even this, more modest, November movement ranks among the 10 highest one-day percentage gains for the index.

In the spring there was considerable uncertainty on the path out of the coronavirus crisis and just how damaging it might be. Now the situation on both these variables is a little clearer and that helps explain why market rallied so strongly. Although it is not quite true to say the market has come full circle.

Has the ftse fully recovered?

As we write the FTSE 100 is still 15% below its pre-Covid levels – we take 20 February as being when investors really began to price in a material impact from the pandemic.

In contrast, the S&P 500 which, thanks to a combination of the US presidential outcome and the vaccine news, broke new record highs this week.

The gains across the Atlantic were less substantial than those enjoyed by the FTSE 100 and that hints at the changes in stock market leadership we are seeing in the wake of Pfizer’s big announcement.

Losers become winners and vice versa

While Wall Street is dominated by the big technology companies, the UK market has plenty of the old-world economy in its ranks, many of which have seen their valuations smashed on the rocks of the Covid crisis.

These beaten down ‘value’ stocks were suddenly in fashion and we saw some quite spectacular moves, while tech, which sits very much in the ‘growth’ category, and traditional safe havens like government bonds and gold were sold off.

Tech has been one of the few places to find earnings growth in 2020 and so investors have been happy to pay high prices in this area. Many investors now look to be taking the view that some of the worst-performing stocks this year now have a greater chance of earnings recovery, which means they can find growth at a cheaper price and so tech becomes less appealing as valuations start to become more important.


Travel Rebound

Drilling down to specific sectors, travel was clearly a big winner including British Airways owner International Airlines Group (IAG) which enjoyed intra-day gains of 40%.

Aircraft engine maker Rolls-Royce (RR.) continued the dizzying ascent it has enjoyed since addressing its own financial problems with a recent £2 billion rights issue. Hotels, as well as leisure and hospitality businesses, also soared on hopes they might be able to return to more normal levels of business in the not too distant future.

However, as the graphic shows many stocks remain some way below the levels they were trading at before the pandemic erupted, demonstrating just how far they have fallen in 2020.

Other Sectors Rising

Oil majors BP (BP.) and Royal Dutch Shell (RDSB) were also in demand as oil prices spiked, though again both their share prices and the Brent crude benchmark remain way below pre-Covid levels.

Housebuilders were fired by hopes of an improved economic picture as well as surprisingly punchy guidance from Taylor Wimpey (TW.) that 2021 would be materially ahead of expectations – confidence underpinned by an order book up from £2.7 billion a year earlier to £3 billion. Real estate investment companies, particularly those with exposure to shops and offices, also soared.

Left Behind In The Rally

Perceived lockdown winners like Just Eat Takeaway (JET) and DIY-firm Kingfisher (KGF) were losers on the day. The biggest faller in the FTSE 100 was online groceries firm Ocado (OCDO) which fell 16.1% to £22.83.

Consumer goods giant Reckitt Benckiser (RB.), which had done well earlier this year after receiving a boost from demand for health and hygiene products, also gave up some of its recent gains.

What Happens Next?

Let’s assume the most bullish assumptions are true and there will be a return to some normality by the spring. With very loose monetary policy in play and a possible spending splurge by those consumers which still enjoy a disposable income, there is the possibility of inflation increasing fairly rapidly.

This might see central banks execute a handbrake turn as they look to gain control of rising prices and begin withdrawing stimulus or even increasing ultra-low rates. In this article we talk about the investments which could do well if inflation returns.

Conversely, if there are unexpected delays in the development and distribution of the Pfizer vaccine and others potential vaccines, will investors be patient, or will they look to sell Covid-impaired names once more?

One must also consider the unresolved risks which persist around Brexit and the transfer of power in the US.

This week’s vaccine news is positive news, however it’s by no means the end of the road, its just a step in the right direction.

We may see further drops in the market and setbacks in terms of the Pandemic, but this is a very good start.

Stay posted for further market updates and blog content from us.

Andrew Lloyd

13/11/2020

Team No Comments

US elections: As the dust settles

Please see below commentary received from Fidelity International yesterday afternoon, which discusses how the US election result will likely impact the US economy as well as global trade. The article suggests that there may not be substantive changes in these areas and explains why.

As the dust settles on the US elections, a couple of uncertainties remain. Control of the Senate will not be resolved until runoffs are conducted in January 2021, to name one example. But investors weighing how much has changed should also consider the broader trends that remain in place. When it comes to key elements around geopolitics and economic strategy, will it be much more a case of style over substance?

Focus on the US

First, against a backdrop of a rolling pandemic crisis, both the near-term response and the medium-term consequences will mean an inevitable focus on the domestic economy. This implies an ongoing use of both fiscal and monetary policy to support the demand side of the economy, and additional investment in infrastructure to stimulate economic activity. The possibility of a split Congress means that higher-end estimates for fiscal stimulus, such as those anticipated under ‘blue wave’ scenarios of Democratic control of both houses, will probably fail to materialise. Once again, the Fed will be expected to carry more of the weight. Still, as we go through the coming quarters, the imperative for the White House and Congress will be to iron out the particular targets of spending (albeit at the lower end of the range of estimates), with areas such as infrastructure or healthcare likely to be beneficiaries.

Geopolitics unmoved?

Second, again discounting the issue of partisan approach, it is hard to see a meaningful near-term change in the geopolitical landscape, with key areas such as US-China relations potentially remaining fragile if we look at rhetoric from all sides of the US political spectrum over the course of this year. In many ways the narrative of competitive threat and security risk will just act to reinforce a need for investment closer to home. And while recent months have highlighted that global trade flows continue despite tariffs and other bilateral barriers, these flows are also likely to grow more regional over time as shorter supply chains become a priority in the wake of Covid.

The view from Asia

Third, I expect the direction of US economic strategy outlined above will continue to act as a drag on the US dollar in relative terms. Despite what is likely to be a more limited scale in a split Congress scenario, US stimulus measures and their impact on currency markets should, at the margin, ease conditions for Asia and developing markets globally. This, combined with a greater success in containing the spread of Covid-19 across large parts of Asia, will see a scope for not only a broader-based recovery in the region, but for Asia to increasingly decouple from what is being experienced elsewhere in the world.

Market implications

Turning to markets and how investors should be positioned as we head into 2021, clearly the points above speak to the attraction of non-dollar denominated assets. With the prospect of increased volatility, this suggests a good risk-reward balance in Asian fixed income markets, and in particular Chinese government bonds and Asian high yield bonds. On the equity side, we see value in markets such as India and across South East Asia, which have lagged much of the rest of the region over the course of 2020, and also for Japan, given the ongoing focus on corporate reform combined with attractive valuations. As the dust settles on the 2020 US elections, these are some of the broad global trends to watch.

We will continue to provide market analysis and relevant content from the world’s leading investment experts, so please check in again with us soon.

Stay safe.

Chloe

11/11/2020

Team No Comments

Daily Investment Bulletin

Please see below the latest bulletin received from Brooks MacDonald this afternoon, which provides a refreshing update on the continuous rise in the markets following the US election result and the Pfizer vaccine news.

What has happened

The news from Pfizer/BioNTech catalysed a broad market rally across Europe although the momentum did fade at the latter end of the US session and coming into Asian markets. The rally had a decidedly cyclical skew with the unloved hospitality and leisure sectors seeing a sizeable boost.

The Pfizer vaccine

Given the squeezed timescales for a coronavirus vaccine, there were always many fears about the chances of a successful vaccine. One of the key determinants of ‘success’ is efficacy, and the Pfizer candidate is reporting over 90% which, for comparison, is hugely above that of the average flu vaccine which is around 50%. Politicians globally welcomed the news but advised caution that this would provide a quick win given the need to ramp up production and raised concerns around logistics given the vaccine needs to be deep frozen until the day of use. It is too early to say whether this vaccine news is a genuine game changer, but it is a salient reminder of how aggressively the under owned value and cyclical areas can snap back. Whilst the post pandemic world is likely to continue to be dominated by low growth, low inflation and low interest rates, favouring growth sectors, some balance is required given how cheap the cyclical/value areas of the market are.

Internal Market Bill falters

The House of Lords voted to remove the clauses from the internal market bill that would allow ministers to disallow elements of the EU withdrawal agreement. Despite this the government said it would progress with the provisions and add them back to the bill when it returns to Commons debate in December. The House of Lords defeat puts more pressure on PM Johnson as EU/UK trade talks reach their conclusions and President-Elect Biden’s victory swings the balance of power towards a multilateral approach to negotiation. Biden has previously warned that any destabilisation of the Northern Ireland peace process would make a US/UK trade deal very unlikely. 

What does Brooks Macdonald think

Whilst a Biden win is not a surprise for markets, many of the existing risks and opportunities in the world need to be revisited with a fresh lens. Brexit is a particularly interesting case as the EU may feel emboldened by the prospect of closer US relations, possibly encouraging a more aggressive position with the UK. This risks an impasse with the UK at exactly the time when Sterling will need clarity over the state of EU/UK talks.

Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World GBP 1.4%5.7%1.8%8.8%
MSCI UK All Cap GBP 5.2%9.8%3.4%-16.2%
MSCI USA GBP 0.9%5.3%1.0%13.9%
MSCI EMU GBP 4.9%11.0%2.6%-0.3%
MSCI AC Asia ex Japan GBP 0.9%3.8%4.8%16.7%
MSCI Japan GBP -0.4%2.3%1.9%4.4%
MSCI Emerging Markets GBP 1.5%5.1%5.3%10.0%
MSCI AC World IT GBP -0.6%6.4%-0.7%32.5%
MSCI AC World Healthcare GBP0.3%5.2%0.4%12.0%
Barclays Sterling Gilts GBP -1.3%-2.2%-1.5%5.7%
Barclays Sterling Corps GBP -0.4%-0.3%0.1%4.9%
WTI Oil GBP 8.6%7.5%-1.7%-33.4%
Dollar per Sterling 0.1%1.9%1.0%-0.7%
Euro per Sterling 0.7%0.4%1.1%-5.7%
MSCI PIMFA Income 1.7%4.3%1.4%-1.6%
MSCI PIMFA Balanced 1.9%4.9%1.6%-1.6%
MSCI PIMFA Growth 2.3%6.0%1.9%-1.6%

Although this appears to be the light at the end of the tunnel, we are likely to see more volatility as the markets recover. Please check in again with us soon for further market data and news.

Stay safe.

Chloe

10/11/2020

Team No Comments

Vulnerable Clients

The FCA have always had a focus on Vulnerable Clients – in particular, how firms manage and deal with Vulnerable Clients.

Following Covid-19, this focus was heightened given the significant impact of Covid-19 on people’s health (both physical and mental) and finances (stock market drops or possible furlough/job loss).

A key element of the FCA’s focus is on the importance of protecting vulnerable clients at this time and firms should expect to receive continued and increased scrutiny on what they are doing to identify and deliver good outcomes for their vulnerable consumers.

What is a ‘Vulnerable Client’?

FCA Definition: A vulnerable person is someone who, due to their personal circumstances, is especially susceptible to detriment, particularly when a firm is not acting with appropriate levels of care.

In 2018 the FCA Estimated that 50% of adults display 1 or more characteristics that show potential vulnerability. This means that 24m adults in the UK showed signs of vulnerability.

Following COVID-19, it is now estimated that 1 in every 6 adults show signs of vulnerability.

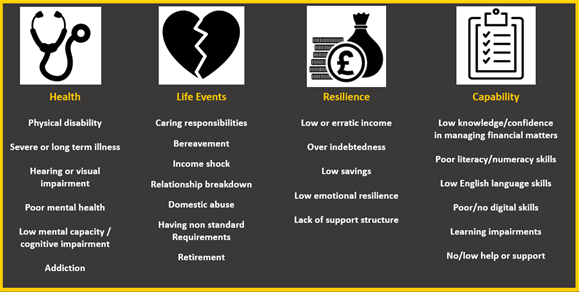
What are the 4 key drivers?

Given the broad scope of the drivers, it’s likely that most people will experience one or more of these drivers at some point in their life.

How do we support Vulnerable Clients?

We have implemented a Vulnerable Client Policy which details how we spot the signs of vulnerability and how we manage and support our client’s needs.

In addition to our policy, we regularly provide training to all staff regarding Vulnerable Clients to highlight our requirements as a firm, the drivers and impact of vulnerability and how to spot and manage vulnerability.

We have a Vulnerable Client Champion (that’s me!), to help make sure that we support clients in the best possible ways and to constantly review and challenge our own internal processes to make sure we are strong in our focus in delivering the right outcomes.

We make it our goal to make sure the fair treatment of Vulnerable Clients is properly embedded into our culture, policies and processes to make sure that we can provide clients with any additional support needs that may be required which helps us deliver the best outcomes for our clients.

Ensuring that this as embedded into our firm’s culture helps us support our clients during periods of vulnerability which is the time when they need it most.

This year has been challenging in many ways and we have recently reviewed our internal training and policies to ensure that we take the potential impact of Covid-19 in how we help provide the best advice and support for our clients.

As a firm, we don’t just look at helping our Vulnerable Clients as a regulatory issue, we do it because we support our clients at all times, no matter what life may throw at them.

We are all likely to be more vulnerable now following the pandemic and its important to remember, we are all in this together!

Andrew Lloyd

Vulnerable Client Champion

09/11/2020

Team No Comments

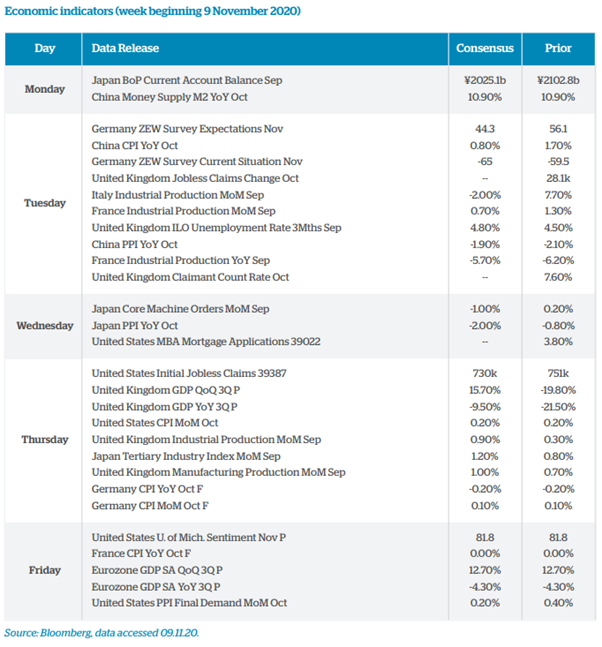
Brooks Macdonald – Weekly Market Commentary

Please see below the latest bulletin from Brooks Macdonald, which has just been received and provides their weekly market commentary:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

09/11/2020

Team No Comments

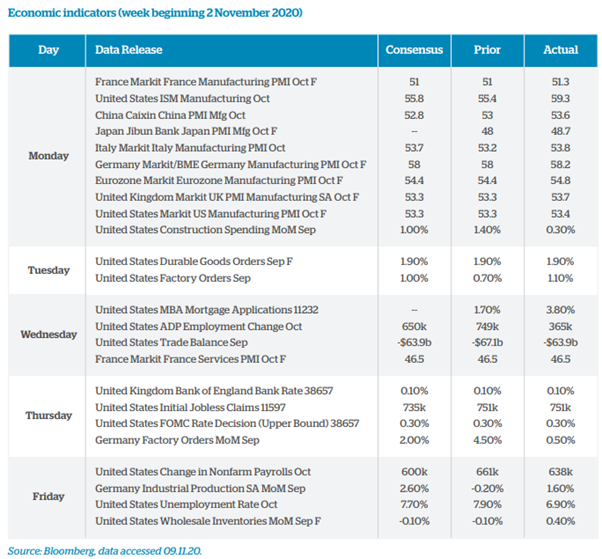
Blackfinch Investments – Monday Market Update

Please see below this week’s Monday Market Update from Blackfinch investments – received today 09/11/2020.

Blackfinch Group Monday Market Update – Issue 16 – 9th November 2020

UK COMMENTARY

• Boris Johnson placed England in a second national lockdown. Although the rules are not quite as strict as the first time round, the public is under specific guidance on movement until 2nd December at least.

• The UK Manufacturing Purchasing Managers’ Index (PMI) for October was revised up to 53.7 from the flash estimate of 53.3. This was below September’s level, with the main drag attributed to a contraction in the consumer goods industry, blamed in part on regional lockdowns.

• The IHS Markit/CIPS UK Services PMI Business Activity Index was reported as 51.4 in October, down from 56.1 in September. However, a value above 50 still indicates an increase in activity.

• The Office for National Statistics reported that the UK’s headline measure of labour productivity fell by 1.8% year on year in the second quarter

• The Bank of England voted unanimously to implement a £150bn bond-buying exercise, ahead of market expectations for a repeat of the current £100bn. The gilt purchases will begin in January when the existing programme expires and will last throughout 2021.

US COMMENTARY

• All focus was on the presidential election. Donald Trump fared better than anticipated in the polls, but by close of business on Friday it appeared Joe Biden had the lead. Over the weekend he was confirmed as victor. Whether the current President will concede the election is another matter entirely.

• The Senate appears likely to remain Republican, creating a divided government in the US. This also continues the trend seen so regularly in the past ten years, including in the second half of President Trump’s term.

• Initial jobless claims fell to 751,000, however economists had predicted a figure of 735,000

• The total unemployment rate fell to 6.9% from 7.9%

ASIA COMMENTARY

• The Caixin/Markit PMI came in at 53.6 for October, marking the sixth straight month of manufacturing expansion in China

• Japan’s benchmark equity index, the Nikkei, reached a near thirty-year high at the close of business on Friday

A good update from Blackfinch Investments, providing a short summary of events from around the world over the past week.

Please continue to check back for our latest blog posts and updates.

Charlotte Ennis

09/11/2020

Team No Comments

US Election 2020

Please see below article received from T. Rowe Price this morning following the US election results. The commentary includes predictions on Biden’s priorities and policy proposals and the effects of this on the global markets. 

Democrat Joe Biden’s policy proposals as the next US president (pending the outcome of potential legal challenges) could have mixed implications for investors if implemented, according to T. Rowe Price investment professionals. On the positive side, many see Biden as likely to prioritize additional major fiscal stimulus to help the economy continue to recover from the steep downturn caused by the coronavirus pandemic. However, Biden also supports corporate tax increases that would be used to fund some of the additional spending. It is far from certain that they would be enacted given Republican opposition.

Spending and Taxes

Mark Vaselkiv, T. Rowe Price’s chief investment officer (CIO) for Fixed Income, believes that Biden is likely to seek additional funding for states and municipalities. “The economy is weakest at the state and local level, where governments need help to mitigate cuts in essential services amid quickly declining revenues,” Vaselkiv asserts. This push for funds for localities could help stabilize and support the credit quality of municipal debt for years to come as the economy recovers from the pandemic, he says.

Biden has proposed raising corporate taxes to halve the tax cut enacted by the Tax Cuts and Jobs Act (TCJA) of 2017. Biden’s plan involves increasing the corporate income tax rate—currently a flat 21%—to 28%. That would still leave the rate meaningfully lower than the pre‑TCJA rate of 35%. President‑elect Biden would also likely try to boost taxes on the foreign income of US companies and institute a form of alternative minimum tax for corporations. However, Republican opposition could limit or prevent some of these measures to increase taxes.

Short-Term Effect on Corporate Earnings

Biden’s outlined tax hikes, if implemented, could reduce after‑tax corporate earnings. David Giroux, T. Rowe Price CIO of Equity and Multi‑Asset and head of Investment Strategy, says that the tax rate increases proposed by Biden could collectively reduce after‑tax profits for companies in the S&P 500 Index. However, some industries could benefit from increased spending. Global Focused Growth Equity Strategy Portfolio Manager David Eiswert agrees that US companies would experience an “earnings reset” if the Biden tax plan passes, although he also believes that the effects would be “manageable and likely offset, in part, by fiscal stimulus.”

Looking at corporate bonds, Vaselkiv asserts that “Biden’s tax increases would impact equities more directly than corporate credit, probably hitting the wildly profitable giant tech stocks the hardest.” A tax hike would not necessarily hold back growth, Vaselkiv adds, noting that US corporate earnings and the broader US economy both continued to grow after tax hikes during the Clinton and Obama administrations.

According to T. Rowe Price Chief US Economist Alan Levenson, the first order of fiscal business for Biden will likely be a debt‑financed coronavirus response and economic rescue package. Biden will probably wait until later in 2021 to try to implement his broader vision for economic renewal, with roughly half of the 10‑year cost expected to be offset by tax and other revenue increases. “The implied addition to debt is manageable because borrowing rates are low relative to the economy’s potential growth,” he explains.

Tensions with China seem to resonate across the political divide.

– Quentin Fitzsimmons, International Fixed Income Portfolio Manager

Pressure on China to Continue

All signs suggest that, as president, Biden will take a tough stance toward China on market practices and human rights issues, though he will likely seek multilateral partnerships and engage levers beyond trade in any renegotiation of the US‑China relationship.

“Tensions with China seem to resonate across the political divide,” says Quentin Fitzsimmons, a London‑based T. Rowe Price International Fixed Income portfolio manager. He believes Biden will maintain pressure on China to address concerns about intellectual property rights in the technology sector. “It’s tough to say how US‑China relations will evolve in a Biden presidency,” Science & Technology Equity Strategy Portfolio Manager Ken Allen states, “but if volatility were to lessen, that could be a positive for technology companies that are perceived as having some exposure to trade tensions between the two countries.”

However, according to Levenson, Biden may face tensions between reengaging more constructively with allies on trade while seeking to re‑shore critical supply lines and manufacturing jobs in general.

Industrials Could Benefit from Push Toward Energy Efficiency

Biden has indicated that he will seek higher levels of federal procurement spending and tax incentives to create jobs and drive economic development by rebuilding critical infrastructure. This push would focus on reducing carbon emissions and investing in clean‑energy technologies, although it could face opposition from Republicans in Congress.

Jason Adams, portfolio manager of the Global Industrials Equity Strategy, believes that, if implemented, Biden’s ambitious plans could accelerate advances in energy efficiency and emissions reductions. “Many industrial companies are part of the solution in this regard,” he says. Potential beneficiaries, he adds, could include companies specializing in air compressors, rail transport, commercial aircraft, electric vehicles, and industrial gases.

Conversely, US defense spending “faces the prospect of several years of a modest downward trajectory after a seven‑year upcycle, which would have been likely regardless of who was elected as the next president,” Adams asserts.

We don’t think there’s anything Biden will do that would change our view that…oil will remain in a long‑term bear market….

– Shawn Driscoll, Global Natural Resources Equity Strategy Portfolio Manager

Health Care Policies May Expand Market for Medicare-Focused Firms

Expanding access to health insurance also appears to be a priority for Biden, who has proposed lowering the age requirement for Medicare eligibility to 60 years from 65 and creating a new Medicare‑administered public option that would automatically enroll low‑income Americans who aren’t eligible for Medicaid. Health Services Analyst Rouven Wool‑Lewis believes that, if implemented, these policies could expand the market for Medicare‑focused managed care organizations while potentially siphoning away some customers from private health insurance providers.

President‑elect Biden and President Trump advocated different solutions to curb drug costs. Pharmaceuticals Analyst Jeff Holford says such proposals are more likely to be enacted in the Biden administration, which could negatively impact pharmaceutical stocks. Holford also notes, however, that the politics of health care legislation are complicated given the strong relationships that politicians across the political divide have with the pharmaceutical industry.

Potential for Heightened Bank Regulation

The Biden administration might seek to impose stricter rules and enforcement policies for banks. These potential measures could include additional limits on bank dividends and share buybacks as the U.S. recovers from the pandemic and its fallout. However, Gabriel Solomon, portfolio manager of the Financial Services Equity Strategy, believes that the regulatory environment may prove “less adversarial” than during the Obama administration, after lax bank regulation was widely viewed as contributing to the global financial crisis of 2008–2009.

Regulatory Moves Likely to Have Little Impact on Oil Market

Biden’s platform, as well as his comments on the campaign trail, suggests that he will try to tighten regulation of the fossil fuels industry, which would likely result in higher compliance costs for oil and gas companies. Biden has also voiced support for a moratorium on new oil and gas lease sales on federal lands and potentially halting the issuance of new drilling permits in these areas.

Shawn Driscoll, portfolio manager of the Global Natural Resources Equity Strategy, contends that conditions in the global oil market, not the regulatory implications of Biden’s election, are likely to have more influence on energy company earnings. “We don’t think there’s anything Biden will do that would change our view that, outside of the occasional countercyclical rally, oil will remain in a long‑term bear market because of rising productivity and falling output costs.”

Once Biden has been inaugurated, he will be faced with an ongoing pandemic, a struggling economy, and a divided country. It will be interesting to see how he tackles these challenges during his first few months in Office.  Please check in again with us soon for further up to date content.

Stay safe.

Chloe

09/11/2020

Team No Comments

Biden presidency faces potential battles ahead

Please see the below article from BNY Mellon:

Democrats have taken control of the Presidency under Joe Biden but control of the Senate is still in question. Managers from BNY Mellon Investment Management outline how they expect the result to impact markets and sectors over the coming months should results hold

Joe Biden has won the US presidential election, but it is still unclear if Republicans have retained control of the Senate. The latter could hinder implementation of the Democratic Party’s future policy program.

It was against the backdrop of a global pandemic that an often bitter election campaign played out: now, the question for investors is how different asset classes are likely to respond and what political power a Biden White House can realistically assert if Congress remains split.

Regardless of a favorable outcome for Biden’s team, the prospects of a Democratic-sponsored hike in corporate taxes, a focus on a ‘green’ agenda and the potential for increased cooperation in the international sphere could possibly face Republican opposition.

Despite Biden’s win – and beyond party politics – Newton Investment Management global equity portfolio manager Paul Markham believes it could be a tough challenge for his party to satisfy its political base for new social policies, given the US’s poor governmental financial position – on account of its efforts to tackle the Covid-19 pandemic.

“Higher taxation or further increases in government spending could cause headaches for the Democrats – the forthcoming four years will be very difficult– and what has been pledged by the party in terms of social and health care may prove hugely challenging to actually deliver. Democratic pledges on social and healthcare changes could be especially difficult to deliver, given the currently challenging government financial predicament,” he says.

April LaRusse, Insight Investment’s head of investment specialists, believes key government policies are likely to remain unchanged under Biden, though she adds that the Presidential change and a wider mood shift could benefit risk markets.

“In our view, if the Senate does remain in Republican control, this outcome could mean key policies like corporate taxes will  be unchanged. That said, we would expect to see government bond yields move somewhat higher and risk assets rally, though not to the extent seen in 2016 given existing Fed policy. While an infrastructure deal might be less likely, so is further trade escalation, and so we may see trade-exposed names benefit from that.”

In contrast, Alcentra co-chief investment officer Leland Hart is more concerned by the election outcome, in light of the potential market uncertainty it could generate.

“We view the latest election outcome as a fairly negative result given the political uncertainty that may ensue. Ultimately, it means we could soon start to lose clarity on whether there will be decisive action by government and continued strong support for the economy,” he says.

Hart says decisions on where and how support to sectors of the economy is delivered could become more complex and subject to political division between Republicans and Democrats. “In the recent past both sides have tended to politicize decision marking, often with a negative impact on markets, including private credit markets.”

Newton Investment Management global strategist and member of the Real Return Team, Brendan Mulhern supports the view that potential bi-partisan conflict risks slowing economic progress and could dent market confidence.

“The lack of action a split House and Senate might bring about has been on display this year with the Republicans and Democrats unable to agree on another fiscal package to support the economy. It’s difficult to say how much of this is down to the two parties playing politics ahead of the election but if the House and Senate is still split there may be concerns that policymakers in Washington will not be able to act decisively to counter the impact of the Covid-19 pandemic on the economy. This may come to weigh on market sentiment and expectations,” he says.

John Bailer, lead portfolio manager of US dividend-oriented and large cap strategies at Mellon, also feels the Biden administration could adopt a moderate approach. On a more optimistic note he adds that, ahead of the election, the market was pricing in a Democratic sweep, so some sectors – such as financials, energy and defense which performed poorly before the election – might now rally.

He adds: “The most meaningful change would happen with executive orders and appointees to Government agencies.”

“I would expect more international cooperation, therefore helping companies hurt by the trade wars. Mergers & acquisitions could slow with a more consumer focused Department of Justice. Since 1933, a divided government with a Democratic President has led to 13.60% returns in the S&P 500, which has been better than average.”

Newton head of fixed income Paul Brain is also optimistic government spending could continue to support the US economy and hopes international trade relations might also thaw under Biden. Separately, he also expects to see a rise in US Treasury yields following the latest election.

“We would expect to see a new stimulus package put in place and global trade relationships improve a little, even if some US trade pressure remains on China. The US dollar could bounce back now that election uncertainty has been removed, but the trend is still likely to be lower against Asia in particular.

“In bond markets, we would expect yields in the US Treasury market to rise faced with the prospect of more government spending, with the curve steepening. Investors in risk assets such as credit may be concerned about the potential for increased corporate taxes later, though initially, government spending plans look set to dominate and improve the outlook. We would expect the US dollar to weaken over time as domestic spending increases and sucks in imports and emerging markets outperform.”

For Jeff Burger, senior portfolio manager, Mellon, one asset class that may benefit is municipal bonds. “Under a Biden Presidency infrastructure spend may actually pick up – funded largely by the sale of municipal bonds. Here, we believe there could be an emphasis on ‘green’ and environmentally sensitive projects as a way of providing economic stimulus,” he says.

Burger also raises the prospect of a push by Democrats to raise corporate taxes. If successful, this could also spark inflows into municipal bonds, given the tax exemptions they offer investors, he says.

Meanwhile, Insight fixed income fund manager Gautam Khanna believes  the Senate staying Republican under a Biden presidency means game-changing policies are less likely. In his view, markets will take comfort that further trade flare-ups are less likely (a positive for emerging markets and trade-exposed names), while possible Senate resistance to tax hikes will also be viewed positively.

However, the Senate could also look to curtail Democrats’ fiscal spending ambitions, with pandemic relief packages and renewed infrastructure spend likely to face deadlock. The potential deregulation roll-back may also hurt sectors such as energy and autos, he adds.

“If the pandemic continues to deteriorate and anarrow Republican Senate majority is a roadblock to a larger fiscal stimulus package, this ‘stimulus disappointment’ could cause increased volatility, offsetting the positive certainty on the tax front,” he says. “Nonetheless, markets are often comfortable with a lack of real policy change – so, for now, we see that result as positive for risk.”

Global equities: The long term view

For the Walter Scott investment team, the outcome could represent a change of direction in US policy with the prospect of higher taxation (albeit with more fiscal stimulus), wider health care benefits, a higher minimum wage and a re-engagement on climate changes issues. Even so, just how much of that agenda will actually be enacted depends on the extent to which a Republican Senate might counter some of these policies, aside from the question of government finances. They add: “Markets have increasingly anticipated policy shifts, but whatever the political landscape, we’re confident the US will remain a haven for enterprise and innovation. We’ve found that long-term growth patterns for businesses able to adapt and innovate are rarely significantly altered, whatever the political twists and turns.

Please keep checking back for updates on the US Election aftermath, the ongoing Pandemic and a range of investment commentary from some of the world’s leading investment houses.

Andrew Lloyd

09/11/2020

Team No Comments

Legal & General Investment Management Blog

Please see below an article received early this afternoon from Legal & General Investment Managers which provides their latest views on the U.S. Election:

It looks like the end could be in sight, and all signs are pointing towards a Biden victory, despite Trump’s delaying tactics. Once the election is settled, investment houses will have a clearer picture for the future and will be able to position themselves accordingly.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

06/11/2020