Please see below an article from FT Adviser, which was received late yesterday afternoon and details how financial advice is ‘intrinsically linked’ to good mental health:
As you can see from the above article, receiving financial advice putting a plan in place, especially for retirement accompanied with regular reviews can have a positive impact on an individual’s mental health.
It’s easy to understand why this is the case as by firstly receiving financial advice, we (as IFAs) can help you identify and prioritise your needs and objectives. Then, by reviewing these plans on a regular basis and knowing where you are in terms of achieving your desired goals should help give people peace of mind knowing what they need to do (if anything) in order to achieve their objectives.
The cost/benefit issue is not necessarily understood by prospective clients. As a client you can understand the value of advice. Research in this area has indicated that the ongoing advice and guidance is good value for money.
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see below this week’s Markets in a Minute update from Brewin Dolphin – received late yesterday afternoon – 23/11/2021
Stocks mixed as UK inflation hits ten-year high
Stock markets were mixed last week as UK inflation hit its highest level in nearly ten years amid surging energy prices.
The FTSE 100 fell 1.7% with high inflation and an increase in employment fuelling speculation that the Bank of England will raise interest rates next month.
The pan-European STOXX 600 slipped 0.1% as an increase in the number of Covid-19 infections prompted several countries to reintroduce restrictions to curb the spread of the virus.
US indices fared better, with the Nasdaq hitting a new intraday high on Friday and ending the week up 1.2%, powered by technology stocks. The S&P 500 also rose, whereas the Dow recorded its second-consecutive weekly loss, finishing down 1.4%, as banking, energy and airline stocks slumped on fears of full lockdowns across Europe.
Japan’s Nikkei 225 managed a 0.5% gain after the government approved a larger-than-expected spending package to cushion the economic blow of the pandemic.
Powell to chair Fed for second term
Major indices were mixed on Monday (22 November) as investors digested the news that US President Joe Biden had nominated Jerome Powell as chair of the Federal Reserve for a second term. Biden cited the ‘decisive action’ Powell took during the early stages of the pandemic as a reason for the reappointment.
Bank stocks and Treasury yields rose following the decision but concerns about increasing Covid-19 infections in Europe weighed on investor sentiment. The Dow edged up 0.1% whereas the S&P 500 and the Nasdaq lost 0.3% and 1.3%, respectively. The FTSE 100 managed a 0.4% gain as telecom stocks rose following private equity firm KKR’s $12bn takeover bid for Telecom Italia. The STOXX 600 was 0.1% softer as investors feared Germany would follow Austria in imposing a full lockdown.
The FTSE 100 was 0.6% lower at the start of trading on Tuesday, while the STOXX 600 looked to be on track for its worst day in nearly two months, amid ongoing fears about Covid-19 restrictions.
UK inflation hits 4.2% in October
Consumer prices in the UK rose at their fastest pace in nearly a decade in October, hitting 4.2% on an annual basis. The Office for National Statistics (ONS) said this was mainly because of higher fuel and energy prices, although the cost of second-hand cars and eating out also increased. The figure was far higher than the 3.1% annual rise seen in September and more than double the Bank of England’s 2% target.
Speculation that the Bank of England will raise interest rates in December intensified further after figures showed the number of payrolled employees increased by 160,000 to 29.3m between September and October. Huw Pill, the Bank’s chief economist, was quoted in the Financial Times as saying the ‘burden of proof’ had shifted and that policymakers would have more explaining to do if they left interest rates unchanged than if they raised them. “I’m looking perhaps for reasons not to hike rates,” he said.
Despite soaring prices, GfK’s consumer confidence index rose three points in November to -14, better than the -18 forecast by economists. There was a seven-point jump in the sub-index of whether people think this is the right time to make big purchases. Meanwhile, the latest UK retail sales figures from the ONS showed sales rose 0.8% in October from the previous month, following no growth in September, as people shopped earlier than usual for Christmas presents.
US retail sales record biggest jump since March
Retail sales in the US also rose in October for the third consecutive month in a row. The 1.7% month-on-month increase was the largest gain since March and topped economists’ expectations for a 1.4% rise.
Sales were up by 16.3% from a year ago and are now 21.4% above their pre-pandemic level. Several retailers noted there had been an earlier start to Christmas shopping. The data suggests the recent surge in US inflation – it hit its highest level in three decades in October – hasn’t yet dampened spending, despite consumer sentiment falling to a ten-year low earlier in the month.
Europe tackles surge in infections
Austria has become the first western European country to reimpose a full national lockdown since vaccines became widely available. As of 22 November, people will only be able to leave their homes for specified reasons, such as buying essential groceries and going to the doctor. The lockdown is expected to last for a maximum of 20 days and comes amid a spike in infections to 15,809 on Friday.
Several other European countries have introduced measures that aim to stem the spread of the virus, ranging from a partial lockdown in the Netherlands to restrictions for the unvaccinated in Germany and mandatory face masks in Spain and Poland. It comes after the World Health Organization warned that Europe could see 500,000 more Covid-19 deaths by February unless measures were tightened. The restrictions led to protests in Belgium, the Netherlands, Austria, Croatia and Italy over the weekend.
Please continue to check back for our latest blog posts and updates.
Please see below article written by Legal & General’s Asset Allocation team, whose research suggests that the current rise of inflation is due to a mixture of positive demand shocks as well as negative supply shocks. Please read on for full details.
The unwinding of negative supply shocks should temporarily lower inflation next year, while some rotation away from goods back to services might help reduce inflation too – but not as much as central banks expect, in our view, as we see less labour market slack.
Some of the demand shocks are expected to prove longer-lasting as well, aided by excess saving and wealth, easy financial conditions and stronger wage growth and pricing power. So, despite uncertainty around the output gap, we see the risks as skewed towards inflation being positive in 2022 – which will be inflationary in itself.
Icarus’ flight may go higher this time
If the above thesis holds, the Federal Reserve (Fed) is behind the curve. Rates should be at neutral as the economy reaches full capacity, but it is still doing quantitative easing (QE).
The Fed will need to move faster, we believe, and to a higher peak than the market expects. The ultimate peak will be a function of how neutral rates have changed since the last cycle. The market seems confident that they have not risen much – and may have even fallen since 2019. Given the change in fiscal policy, we’re less convinced that will prove to be the case.
Of course, the market is likely to price in a lower path because of the asymmetry of the Fed’s reaction function: a negative demand shock could be met by sharp rate cuts (back to zero), while the Fed will likely be slow to react to further negative supply shocks, arguing they are temporary. In the medium term, we expect the Fed to learn from its mistakes and raise rates sufficiently to prevent a prolonged and serious inflation outbreak.
This implies we want to keep a negative duration bias, but with positioning still short, we don’t think it’s sensible to be holding short tactical views during periods in which there is no catalyst for repricing.
Clash between currency titans
In currency markets, the US dollar and the euro are the titans. Movements in their exchange rate are important, as the euro and dollar are the centres of gravity for the euro-bloc and dollar-bloc currencies.
The US dollar has been strengthening across the board in 2021 (the DXY dollar index is up 6.6%), with many market observers expecting further appreciation. With US inflation on the rise, rate hikes by the Fed are likely to be brought forward into 2022. That’s reflected in the short end of the interest rate curve, while in the long end, the gap with the Eurozone is widening too. Purely looking at nominal rates, US dollar strength seems obvious.
Today, not many investors are worried about a lack of inflation anywhere – not even in the Eurozone – so without much inflation, differentiation between nominal rates is in the driving seat. Over shorter time periods, we agree that nominal rates are a better predictor for currencies than real rates, at least for developed currencies, but over longer time periods this is not true and real rates form the better anchor.
With expectations for rate hikes by the Fed brought forward, while rate hikes by the European Central Bank remain much more conservatively priced, we believe the bar for surprises has been lowered. This will make it harder for nominal rates to continue pushing the US dollar stronger, while it gives more confidence that currencies cannot de-anchor from real rate moves much longer.
Given this outlook, recent euro weakness appears overdone, in our view. We’re turning more positive on the euro versus the US dollar and are ideally looking for negative sentiment and positioning as a potential opportunity.
We’re not there yet, but as the pandemic rears its ugly head again in Europe with the Austrian lockdown, it may not take long. A period of speculation about who is next feels inevitable. Given how unpredictable COVID-19’s trajectory has been, we have no idea where a new round of lockdowns might end, but rates and currency markets have proven to be quite sensitive to coronavirus waves over the last 12 months.
Minotaur’s labyrinth
There is a light election calendar in emerging markets for 2022, with fewer pivotal votes than we will see the year after. There are general elections in Hungary and Poland early next year, followed by a presidential election in South Korea, and then general and presidential elections in the Philippines, Colombia and Brazil.
Will we see an end to Orban’s rule in Hungary? Despite a competitive opposition candidate putting Fidesz on the back foot, an Orban victory remains the base case. In Poland, the Law and Justice party might try to rebuild its majority with a snap election. The outcome depends on the opposition uniting. The task is hard, but not impossible. This matters more broadly as the current government’s spat with the EU is getting more serious.
In South Korea we could see a conservative turn in politics that would result in closer relations with the US and Japan against China, and could lead to a greater risk of miscalculation with North Korea or China. The geopolitical consequences will be the most significant for markets. A generationally divided electorate in South Korea could signal instability and political turbulence in the years ahead.
In the Philippines, the election will be a test for dynastic political machines and the winning president will get substantial powers. This is important for the relationship with China and the US in the Pacific, but we only see limited market impact as most candidates favour broad policy continuity. In Colombia, fiscal constraints are starting to bite, so if the new president is uninterested in fiscal discipline or economic reform, markets are likely to panic.
In Brazil, the current right-wing president Bolsonaro is under strain, increasing the likelihood of a turn to the left with the return of former president Lula. Either way, the constitutionally enforced spending gap, the country’s only fiscal anchor, is under threat. That’s keeping financial markets on their toes. Another key threat comes from the potential inflating away of outstanding public sector debt. Volatility is likely to be high in the runup to the election, and potentially afterwards if institutions are tested. This will be reflected principally in the real, in our view, but also in domestic bond yields and equities.
Please check in again with us soon for further relevant content and market updates as we approach the final month of 2021.
Please see the below article from AJ Bell received over the weekend:
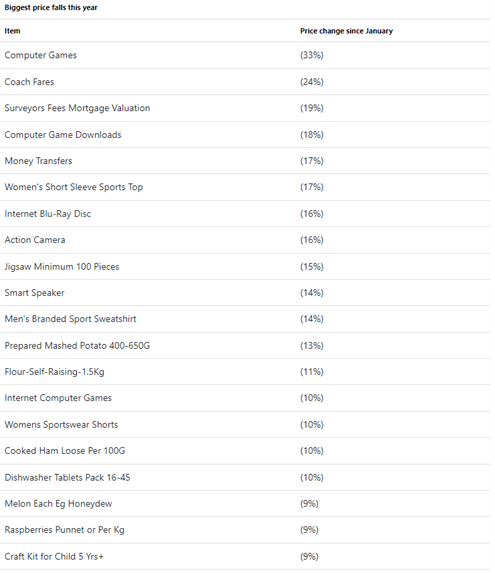
Inflation has soared to a 10-year high and everyone is feeling the pinch, whether it’s in their weekly shop, their energy bills or when they’re heading out to buy a new car. But not everything has risen in price and some areas of our lives are getting pricier than others.
“The single biggest price rise of the year will dismay DIY fans or anyone working on a home renovation: MDF (or Medium-density fibreboard). The man-made wood has got 63% more expensive since the start of the year, as supply chain issues and a surge of people doing up their homes has put it in strong demand. And the biggest faller of the year? Computer games, which are a third cheaper than the start of the year, following a boom in demand during the pandemic that has died away now.”
Travel and transport
Car hire has soared in price, rising by 30% this year, shortly followed by air fares which have risen by 28% as more people hopped on a plane to get some sun. And anyone thinking of going on a jaunt to France will be shocked that EuroTunnel prices have risen 21% this year.
But if you’re willing to travel in the UK you’ll find costs haven’t risen that much, with coach fares actually falling by 24% and rail fares only rising by 3%, meaning a UK holiday could be much more affordable than setting your sights abroad.
Everyone knows that second-hand cars have been among the biggest risers this year, increasing by by almost 25% since January. But electric or hybrid cars haven’t seen the same increases, staying the same price across the year, meaning now could be a good time to go green. Adding literal fuel to this argument is that petrol prices have risen by more than 18% this year, while diesel prices have risen 17%.
Clothing
Now is not the time to be buying formal clothing and workwear, as it’s shot up in price after everyone realised they needed to upgrade their work wardrobes for the return to the office. If you’re pondering a new coat for Christmas you’ll need to dig deeper as a men’s coat has risen in price by more than a third, while a woman’s coat has risen by a more modest 15%.
But those still working from home and who didn’t max out on comfy clothing in the pandemic will find their clothes shopping is less pricey, as men’s jogging bottoms are 5% cheaper than at the start of the year, while women’s exercise leggings are 2% cheaper.
The food shop
The biggest price rise of all food items is fruit drink bottles, so things like Fruit Shoots, which are a staple in many parents’ weekly shop. A pack of them has risen 32% this year. The other biggest risers are a pack of yogurts, which is up 19%, and low-fat spread, which has risen 18%. It’s going to cost more to make a spag bol now, as tinned tomatoes have risen in price by 17%. As it’s not summer people might not be too disappointed that Magnums and other ‘chocolate-covered ice creams’ have risen by 13% in the year.
And the food item that’s fallen the most in price? Prepared mashed potato, which is down 13% on the year, followed by self-raising flour, which was hugely in demand during the pandemic, but people have now ditched their home-baking causing it to be more than 10% cheaper than the start of the year.
As for booze, wine drinkers have found the cost of their tipple increase, with new world red wine and European white wine up by 5% on the year, while a glass of plonk in the pub is up 4%. Beer drinkers haven’t been spared, with a pint of draught bitter or lager both up by 4%. But if you’re willing to ditch the pub for a beer at home, you’ll find a pack of lager has actually dropped in price by around 2%.
Christmas presents
Anyone wanting to buy the bookworm in their life some new material will find costs have shot up, with ebooks costing 23% more than last Christmas and hard-cover books rising by more than 20%. Even children’s books have shot up in price, up by 12%.
If you’re thinking of getting a new TV to watch the Christmas specials you’ll find they cost around 10% more than the start of the year, while the family Christmas board game is around 5% more expensive. But jigsaw fans can rejoice as they are 15% cheaper – once the hot ticket item to have in lockdown it appears their favour has waned a little. The same is true for smart speakers, which are 14% cheaper than the start of the year.
And sports fans will have found their weekly golf trip has got pricier, with golf balls getting 3% more expensive while green fees have shot up 19% in the year. But football players have fared better, with football boots staying the same price and the cost of an actual football rising by around 3%. But those wanting to get the new kit for Christmas will find prices have shot up, with official shirts being 19% more expensive than the start of the year.
Our Comment
These views should be taken in context. Please look at our other blogs that cover inflation as this is a topic we have been regularly posting about.
Rising inflation is currently a global trend due to high demand and issues with supply chains. These supply and demand issues along with rising energy prices are pushing prices up globally.
It may continue to rise in the short term before falling back but it is important to note that inflation is still viewed as transitory by Central Banks.
Please keep checking back for more updates on the current inflation situation, along with our regular content, including our ESG related content and economic updates from some of the world’s leading investment houses.
We don’t normally do two blogs in a day but this one came in this morning from Invesco and I thought it was an important one for you to understand on Inflation
Everywhere I go, every channel I turn to — it seems all I hear is the “i” word. Yes, inflation. And the data is ugly right now:
The headline US Consumer Price Index (CPI) rose 0.9% for October, while core CPI (which excludes food and energy) rose 0.6% for the month. For the first 10 months of the year, headline CPI was up 6.2% versus the same 2020 period — well over expectations of 5.8% — and core CPI was up 4.6%.
China’s Producer Price Index (PPI) for October rose 13.5% year over year, which is well above expectations. This is up from 10.7% year over year in September and represents the fastest pace in 26 years. (China’s PPI measures the cost of goods as they leave the factory gate, before transportation or other costs are factored in.)
The data and the media attention around inflation has altered market-based inflation expectations:
The 5-year breakeven inflation rate finished the week above 3% for the first time in more than 10 years.
Even the 10-year breakeven inflation rate has been impacted. As of Nov.12, it was 2.73%. That’s up from 2.33% two months ago (as of Sept. 14).
It is also having an impact on shorter-term consumer inflation expectations:
Last week, the Federal Reserve Bank of New York released its Survey of Consumer Inflation Expectations for October. Median inflation expectations increased to 5.7% for one year ahead, which is a series high (although keep in mind the inception of the survey only goes back to June 2013) and the 12th consecutive increase. The survey had some positive takeaways: After increasing for three consecutive months, median inflation expectations for three years ahead stayed the same for October (4.2%).
The University of Michigan released its preliminary survey results for November on Nov. 12, and the findings are very similar to that of the New York Fed. US inflation expectations for the year ahead edged up to 4.9% in early November of 2021 from 4.8% in October, the highest since July 2008.However, five-year inflation expectations are unchanged since the previous reading at 2.9%.
Reasons to remain calm about inflation
Most of the questions we are receiving from clients are on the topic of inflation. Financial advisors are sharing with me that most questions they are receiving from clients are on the topic of inflation. Older clients in particular are fearful that this is the 1970s all over again.
So why shouldn’t investors be fearful of inflation? I see five reasons to remain calm.
Inflation is a necessary evil as countries emerge from the pandemic, especially for the many countries, such as the United States, that provided adequate fiscal stimulus this time around (as opposed to during the Global Financial Crisis). Household savings is elevated, there is pent-up demand, there are labour shortages and there are supply chain disruptions. We’re facing a perfect storm — but it’s better than still being in the depths of the pandemic. As I say each birthday, as I grimace about the growing candles on my cake, “This is better than the alternative.” And so it is with high inflation.
While the tunnel may be a bit longer than first expected, I do see light at the end of it. The public has come to realize that inflation likely won’t be over in a few months — but I believe it is likely to peak in mid-2022 and then start to recede. There are multiple reasons for elevated inflation, and some factors, such as pent-up demand, will dissipate sooner than others, but the general trend should improve in the back half of 2022.
Tolerant central banks. The Federal Reserve will not overreact to the inflation data, in my view. The Fed recognizes that the factors causing high inflation will not easily be remedied through aggressive rate hikes. Raising the fed funds rate will not force more people back into the workforce or get ships unloaded in the port of Long Beach any faster. Under the leadership of Chair Jay Powell, the Fed seems hyper-aware of not making a policy error. And I think the Fed would only get more dovish if Lael Brainerd were appointed the new Fed Chair. (Brainerd, a member of the Federal Reserve Board of Governors, recently interviewed for the post.) While other developed central banks may feel more pressure to tighten, I don’t expect overly aggressive tightening. It is also worth noting that the People’s Bank of China is actually in easing mode. And so, all in all, the environment should remain supportive of risk assets given positive economic fundamentals
Longer-term inflation expectations remain relatively well-anchored. Consumers seem to understand that while inflation might be very elevated in the shorter term, it will come down. We saw this in both the Michigan and New York Fed surveys released last week. This helps provide the rationale the Fed needs to avoid a hastening of its rate hikes.
Inflation is not making much of a dent in profit margins. Yes, companies are talking a lot about inflation on their earnings calls, but it hasn’t had much of an impact on earnings. The earnings season in Europe has been better than expected. And thus far, the net profit margin for S&P 500 Index companies in the third quarter is 12.9%, which is near a record-high. And the fourth quarter net profit margin is estimated to be 11.8%, which is still robust.In this quarter’s earnings calls, a number of companies reported being able to pass increased costs onto customers, which helps explain the very healthy profit margins. And while this is not positive for consumers, it should be positive for equity investors.
So what’s the bottom line? I believe we need to expect inflation to remain high — and likely move higher — as we head into 2022. However, I am confident that inflation will peak by mid-2022 and that the Fed will not make a policy error — and that’s the real fear for investors with regard to inflation. I believe investors should remain well-diversified and focused on longer-term goals. I favour maintaining exposure to equities, including dividend-paying equities, inflation-protected securities, and other asset classes that have historically performed well during inflationary periods, including real estate and commodities.
I have just been listening to Brooks Macdonald on Inflation too, amongst other market input. Wage inflation is an area of concern and to precis, Brooks Macdonald say that whilst we might have some Job Movers inflation, for example HGV Drivers, we don’t see much inflation on Job Stayers, the majority of the working population in the UK.
Please find below, an update on markets received from AJ Bell yesterday afternoon – 18/11/2021
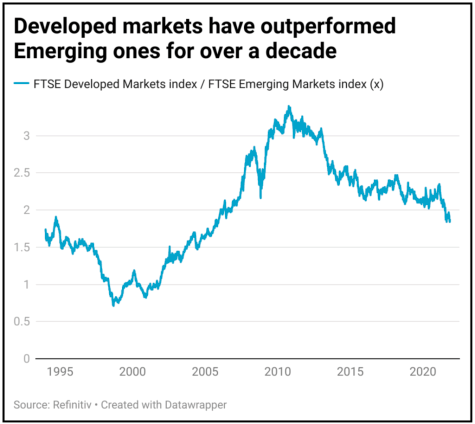
The factors which could knock a 10-year trend of developed markets outpacing emerging markets off course.
Gordon Gekko, the insider-trading corporate raider of 1987’s Oliver Stone film Wall Street, may have been a villain but that did not stop him talking a degree of sense. Quite what he would have made of Rivian’s $100 billion-plus market value after its first day of trading we will never know, but we can probably guess, given his comment that: ‘The mother of all evil is speculation.’
After all, that price tag values Rivian more highly than rival (and backer) Ford, even though Ford is forecast by analysts to generate more than $120 billion in sales and $6 billion in net profits. By contrast, Rivian is going to be in loss this year, not least as it only began to ship its first vehicles in September.
Whatever you think of Rivian’s potential, its valuation now prices in an awful lot of good news and not much bad. This is not to say anything bad will happen. But if it does, well, watch out as the valuation offers little or no downside protection.
By contrast, investors can protect their downside, and leave scope for upside, by looking at assets which may be out of favour and could therefore be undervalued as a result. The danger is that something is underperforming and cheap for a perfectly good reason, so careful research is needed. But one trend which catches this author’s eye is the 10-year underperformance of emerging equity markets relative to developed ones.
CLEAR TREND
This can be seen by simply dividing the value of the FTSE Emerging index by that of the FTSE Developed index. If the line rises, emerging markets are outperforming and if it falls then developed arenas are doing better.
Developed markets ended the 1990s on a high as the Asian and Russian currency and debt crises hammered emerging markets, only for them to recover just in time for the technology bubble bust to hobble the developed ones for the best part of a decade. It has been one-way traffic since 2010, however, as developed markets have proved to be the better portfolio pick by far.
The questions to ask now, therefore are ‘why?’ and ‘what could change’?
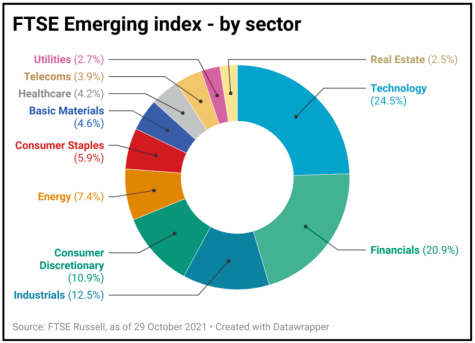
One good guess as to the reason for the performance disparity would be the sector mix of the indices. But they are not as different as you might think. There is a similar representation in technology and the percentage weighting toward cyclical sectors such as financials, industrials and consumer discretionary. Emerging markets’ greater weighting toward financials in a margin-crushing, zero-interest-rate environment may not help, and nor may the higher weighting toward energy and basic materials (mining) during a low-growth, low-inflation decade, but neither looks conclusive.
NEW YORK, NEW YORK
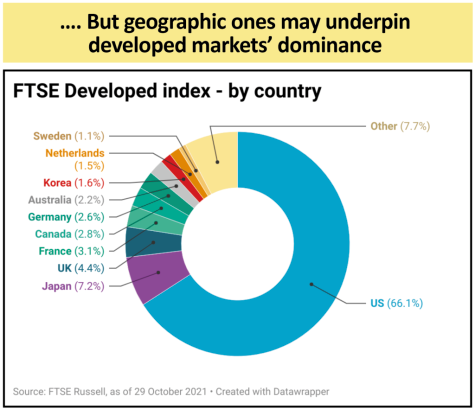
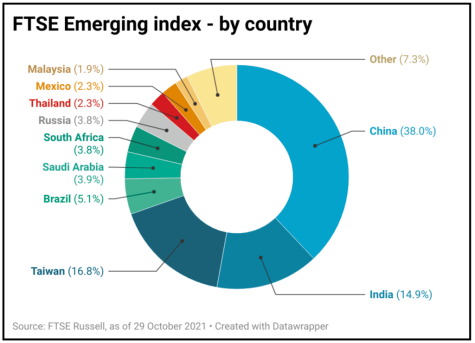
A more convincing explanation comes in the form of geographic exposures. The runaway US equity market represents two-thirds of developed market capitalisation and China more than one third of emerging markets.
This is not the only reason – China’s weightings have increased over time as overseas listings and the domestically-traded stocks have entered global indices – but the S&P 500 is up by more than 300% since January 2010 and the Shanghai Composite by just 7%.
After a long and loud clamour for their inclusion, index compilers are now busily excluding Chinese stocks owing to US sanctions, governance issues and more besides. That may appeal to contrarians, who will also baulk at the valuation attributed to US stocks.
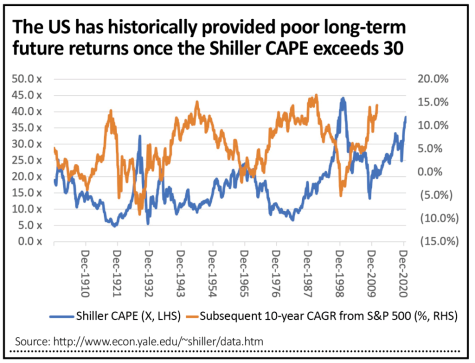
The Case-Shiller cyclically adjusted price earnings ratio – also known as CAPE – is no use at all as a near-term timing tool. But the two previous occasions when the CAPE exceeded 30 times, and the four prior times when 10-year historic compound returns from the S&P 500 have exceeded double-digits in percentage terms, have all seen the next decade’s returns from US equities tail off very badly indeed.
FRIEND OR FOE
Some investors will be happy to stick to the maxim that ‘the trend is your friend’ and row in with the US and developed markets over China and their emerging counterparts. Others will keep the combination of Gekko and Shiller’s CAPE in mind.
China is trying to support its economy while managing a huge debt mountain and attempting to stop financial speculation from derailing its economy through poor capital allocation. But you can argue the US faces the same challenge, even if it comes with far superior corporate governance and investor protection.
China is acting and could be running monetary policy that is too tight as a result. That leaves it room to loosen. The Federal Reserve might just be ducking the challenge and running policy that is too loose, with the result it will have to tighten in time whether it likes it or not in a reversal of fortune that could, one day, break a 10-year-plus trend in relative share price performance.
Please continue to check back for a range of blog content from us and from some of the world’s leading fund management houses.
Please see the below article from Invesco, received yesterday – 17/11/2021.
The challenge of preventing climate change is a matter of life and death, and thus, gets likened to a war. In a war, there are often multiple battles being fought at the same time. The fight to transition our energy dependence away from fossil fuels and towards renewables energy is a key focus, but there are other battle lines being drawn out.
Global food chains need to become more sustainable if we want to avoid climate change. This theme has, so far, remained in the shadow of the energy transition. Herein lies the opportunity. In this blog, we’ll frame how global food supply chains can become more sustainable and highlight the companies we own that are enabling this.
The dual problem – unsustainable practices compounded by a growing population
The food industry faces various sustainability issues. It relies heavily on cheap labour, tolerates an enormous amount of food waste and produces a lot of food with low nutritional value. But we’re going to focus specifically on the environmental concerns here, which are set to intensify as global food demand increases.
The world’s population is expected to reach 9.7 billion by 2050 – that’s nearly 2 billion more mouths to feed relative to today1. Bearing in mind that over 700 million people are currently undernourished2 and around 1.9 billion adults are overweight or obese3, this increase in population size means we’ll have to produce around 50% more calories than we do now to provide everyone with a nutritious diet.
Using today’s agricultural practices, we would need to find an area twice the size of India to do so, which would greatly amplify the food industry’s environmental impact.
Environmental concerns
Whilst on its journey from farm to fork, the food industry releases emissions across the value chain. It accounts for a quarter of global greenhouse emissions, which includes a material contribution to global Co2 emissions and approximately 50% of global methane emissions. Research from Poore and Nemecek showed that, on a global level, more than 50% of emissions generated by the food system was related to livestock – either through land use, animal feed, land conversions or methane production. Nearly 20% of emissions were generated by activities after the production phase, including processing, transport, packaging and retail.
The food industry needs to decarbonise, if global warming is to be held below 1.5°C. Industrial agriculture also poses significant risks to biodiversity and is a large contributor to the consumption of single-use plastic.
The solution – and how our funds are exposed
To reduce the impact of western food chains we need to either drastically change what food we consume or how we produce and distribute it. We believe that innovation can facilitate this change and our investment strategies own some of the companies that are innovating across the three components of the food chain: production, processing and distribution. Interestingly, many of the solutions are coming from enterprises outside of the food value chain.
Food Production – adopting more sustainable techniques
All global food chains start with crop production. The amount of global acreage used for farming and the extensive use of agricultural chemicals are threatening natural carbon sinks and biodiversity. To become more sustainable, farmers need to change farming practises.
Agriculture relies on fertilisers to enhance yields. Without them, we would run the risk of insufficient food production. However, commodity fertiliser can wash off fields into rivers when it rains. This has negatively impacted natural fish populations.
Yara, a leading fertiliser company, produce premium, targeted fertilisers that do not leach into water systems, thus reducing the biodiversity risks linked to fertiliser application. It has also developed digital farming technology, which enables smart application of the optimal amount of fertiliser, creating a better effect with less waste.
As well as reducing the amount of fertiliser applied, farmers can also adopt new techniques to reduce their Co2 emissions. The popularity of ‘no-till’ methods, where farmers do not plough the land, is growing. These methods produce lower yields, and therefore less profit, but sequestrate much more Co2 out of the atmosphere. Yara has launched a program that helps farmers monetise any additional carbon sequestration achieved. This programme incentivises farmers to look at lower carbon practices and is fuelling the growth of ‘no-till’ acreage.
Another innovation is soilless vertical farming. This is when plants are fed nutrients through water systems with the plants’ roots suspended in air, water or non-soil mediums such as sand and gravel. Whilst in its infancy, vertical farming is gaining traction as it uses less land, less water, no pesticides, delivers more nutrients and can be carbon neutral when using renewable electricity. The reduction in acreage required for food production is also a positive for biodiversity. Signify, held across our large and smaller company portfolios, is a worldwide lighting manufacturer with a leading position in vertical farming lighting solutions.
Food Processing – reformulating and repackaging food
Food processors need to offer more sustainable products. Plant-based alternatives to dairy and meat have a significantly lower environmental impact. Plant-based food product innovation will help shift consumption habits and lower the impact of global food chains, but food processors need to gain scale by growing capacity.
GEA is an equipment supplier to the food processing industry and has a strong position in plant-based food. They are a key enabler for food processors to innovate into plant-based food alternatives. This company should also help traditional food production become ‘greener’, as their product innovation allows customers to improve energy efficiency, reduce waste, including water, and leverage alternative packaging solutions.
The food industry makes up 30% of the packaging market, and thus, is a large consumer of single-use plastic. UPM and Stora Enso, two global leaders within the pulp and paper sector, offer plastic-free packaging options for food processors. Using today’s technologies, 25% of plastic packaging could be switched to paper-based packaging. In addition, UPM and Stora are investing in biochemical capabilities where they aim to make wood-based bioplastic, a solution that reduces the demand for hydrocarbons. UPM has recently signed an agreement with Coca-Cola for bio-based PET bottles.
Food Distribution – reshaping the length and shape of global food supply chains
A revolution in the food industry requires the involvement of supermarket chains. The food retail names we own, Ahold and Carrefour, has committed to offering healthier options, improving product transparency, eliminating waste and reducing emissions. Large scale food retailers have the power to force change at the food production and food processing stages, and they will also be instrumental in reducing the carbon intensity of food chain logistics.
The emissions from food transport can be overlooked but are significant. Reducing the miles travelled from farm to fork and the decarbonisation of road and sea freight will reduce the impact of global food supply chains. Yara is leading in the development of green ammonia, a type of ammonia created from hydrogen rather than natural gas.
In future, green ammonia could be used as fuel by the maritime industry to reduce sea freight emissions. Volvo and Daimler are developing their product range of electric trucks. Road freight emissions will fall as logistics companies electrify their truck fleets.
Conclusion
The energy transition, understandably, is a huge topic within the investment community. This needs to be a success if we are to combat climate change, but this is not the only challenge. As mentioned above, global food chains need to innovate for the world to mitigate climate change. Over time, the equity market will reward those companies that can facilitate these changes. However, today’s investors can already build exposure to this multi-decade theme.
What we’ve analysed here are the sustainability concerns linked to getting food from farm to fork. There are other companies trying to solve issues that relate to the next stage of the journey: once food has left the plate. The theme of reducing waste and the circular economy is another battle that needs to be fought in our war against climate change. And we’ll address this in a future blog.
Please check back in again soon for a range of blog content from us and from some of the world’s leading fund management houses.
Please see below this week’s Markets in a Minute update from Brewin Dolphin – received late yesterday afternoon – 16/11/2021
Markets mixed as investors mull spike in US inflation
Stock markets were mixed last week as investors weighed a rise in US inflation against the EU’s more optimistic economic growth forecasts.
The S&P 500, Dow and Nasdaq fell 0.3%, 0.6% and 0.7%, respectively, after the headline consumer price index (CPI) increased at its fastest annual pace since 1990. This overshadowed news that weekly jobless claims had reached a new pandemic-era low.
In contrast, the pan-European STOXX 600 added 0.7% as the EU raised its economic growth forecast for the eurozone and industrial production fell less than expected. The UK’s FTSE 100 gained 0.6% as investors digested the latest gross domestic product (GDP) data.
Over in Asia, the Shanghai Composite added 1.4% following reports that Beijing is considering easing rules to let struggling property developers sell off assets to avoid defaults.
European stocks hit new all-time highs
European indices rose on Monday (15 November) following encouraging economic data from China. The STOXX 600, Dax and CAC 40 all closed at fresh record highs after China’s industrial output rose 3.5% in October from a year ago, beating expectations of a 3.0% increase. Chinese retail sales rose 4.9% year-on-year, significantly higher than forecasts of 3.5% growth.
The FTSE 100 was little changed after Bank of England governor Andrew Bailey said he was ‘very uneasy’ about rising inflation and had come to close to voting for an increase in interest rates when policymakers met earlier this month. US stocks were also flat ahead of this week’s retail sales, construction starts and building permits reports.
At the start of trading on Tuesday, the FTSE 100 was 0.2% weaker as investors considered the latest employment data from the Office for National Statistics (ONS). The number of payrolled employees rose by 160,000 to 29.3m between September and October despite the ending of the furlough scheme. The unemployment rate fell by a bigger-thanexpected 0.5 percentage points to 4.3%. The figures are likely to fuel speculation that the Bank of England will increase the base interest rate when it meets in December.
US inflation highest in three decades
Last week’s economic headlines were dominated by the latest inflation figures from the US, which revealed the headline CPI rose to 6.2% in October from a year ago, the fastest pace for three decades, largely because of faster-than-expected rises in the cost of fuel and food.
Compared with a month ago, prices surged by 0.9%, well above the 0.6% rise forecast by economists. Core inflation, which excludes energy and food, also rose more than expected by 0.6% from the previous month.
The data came a week after Federal Reserve chair Jerome Powell admitted that high inflation was lasting longer than anticipated and it was difficult to predict the persistence of supply constraints.
Concerns about rising prices saw US consumer sentiment decline to its lowest level in a decade. The University of Michigan’s consumer sentiment index fell to 66.8 in November, down from 71.7 in October and well below the expected 72.4. Richard Curtin, chief economist of the university’s consumer surveys, said the decline was driven by “an escalating inflation rate and the growing belief among consumers that no effective policies have yet been developed to reduce the damage from surging inflation.”
Supply issues hit UK GDP growth
Here in the UK, data from the ONS showed the impact that supply chain problems are having on UK economic growth. GDP grew by an estimated 1.3% in the third quarter (July to September), a marked slowdown from the 5.5% growth seen in the second quarter when there was an easing in many coronavirus restrictions. The growth rate was below the 1.5% forecast by the Bank of England, with shortages of goods, labour and components weighing on activity.
The monthly figures showed GDP grew by 0.6% in September but remained 0.6% below the pre-pandemic level. Services output grew by 0.7% as the number of face-to-face appointments at GP surgeries grew, whereas production output declined by 0.4% following two consecutive months of growth.
EU hikes growth forecast
More encouragingly, the European Commission increased its 2021 GDP growth forecast for the eurozone to 5.0% from 4.8%. The commission’s vice president Valdis Dombrovskis said measures to cushion the blow of the pandemic and ramp up vaccinations had “clearly contributed to this success”. GDP growth is forecast to be 4.3% in 2022 and 2.4% in 2023.
The commission also said inflation would reach 2.4% this year, before slowing to 2.2% next year and 1.4% in 2023. The eurozone’s budget deficit is expected to decline to 7.1% of GDP this year from 7.2% in 2020, and then fall to 3.9% and 2.4% in 2022 and 2023.
Elsewhere, data from Eurostat showed supply chain constraints held back manufacturing in September, with industrial production declining by 0.2% from the previous month. However, this was better than the 0.7% decrease predicted by economists in a Wall Street Journal poll.
Another quick update from Brewin Dolphin, these updates are a good way of keeping up to speed with developments in the markets.
Please continue to check back for our latest blog posts and updates.
Please see below article received from Legal & General yesterday afternoon, which provides an update on China’s high-yield bond market and Chinese equities, and how they may affect currency, commodity, and Western equity markets.
Four is the magic number
Throughout the rout, our emerging-market economists have maintained a very consistent line of argument: the consensus is underestimating the likely hit to growth associated with this squeeze on property developers, and the government’s threshold for intervention is further away than the market thinks.
That changed last week. The consensus seems to have finally capitulated, with a number of high-profile downgrades to growth outlooks. We think that we are now nearing the 4% line in the sand for the government: growth below that level puts long-term prosperity goals at risk, and is not consistent with the need to maintain a robust jobs market.
With the market having finally adjusted enough, we are also seeing the first signs of a policy response in relaxed restrictions for homebuyers’ access to mortgage finance and a dilution of the “three red lines” policy that has constrained highly leveraged developers.
On Wednesday, the People’s Bank of China took the unusual step of publishing monthly mortgage lending data for the first time, seemingly to highlight the nascent recovery at the start of the fourth quarter. The state-owned Securities Times opined that “for real-estate developers, the feeling of the recovery of the financing environment will become more and more obvious” going forwards.
For us, that all adds up to a signal that we are hitting a policy inflection point. That encourages us to dial up exposure to the theme: either directly through China’s high-yield bond market, or indirectly through Chinese equities. We might find the intentions of the authorities hard to understand at times, but we don’t think it’s sensible to doubt their ability to underwrite the near-term growth outlook when they see fit.
At sixes and sevens over US inflation
We learnt last week that US inflation hit 6.2% in October. That’s the highest rate since November 1990, the month “Home Alone” was released in cinemas. However you choose to slice and dice the data (core, median, trimmed mean, etc), inflation pressures look to be broadening.
On the Atlanta Fed’s underlying inflation dashboard, there are now a lot of red lights flashing and there are growing warnings of a peak at or above 7% in the months ahead.
But the bond market has been a fickle friend to the vigilantes this year. Anyone who sold out of the longest-maturity bonds in the spring in anticipation of the string of upside inflation surprises has been disappointed, with 30-year futures rallying over 10% since March. The financial media have been full of anecdotes in recent weeks of storied macro hedge funds suffering gut-wrenching losses on bond trades gone awry. Recent price action suggests that, in the wake of those losses, there has been considerable forced liquidation of positions.
For us, that “cleaning up” of the market makes it interesting to sell duration again. Last week, we did exactly that in both the US and Europe across dynamically managed portfolios.
When Kevin McCallister was busy defending his home against the Wet Bandits in 1990, 10-year US Treasury yields were above 8.5%. The contrast with today could barely be more different, with yields now at the dizzy heights of 1.5%.
In the US, we think that some sterner words from the Federal Reserve await in the weeks ahead. In Europe, bond scarcity has driven the short end of the German curve below money-market rates. Risks are never entirely one-sided, but we’re happy to run with tactical duration shorts against that backdrop.
Can a stitch in time save nine?
The University of Michigan survey of consumer sentiment has tumbled to levels rarely seen outside recessions. The survey’s chief economist noted: “Consumer sentiment fell in early November to its lowest level in a decade due to an escalating inflation rate and the growing belief among consumers that no effective policies have yet been developed to reduce the damage from surging inflation.”
And it’s not just US consumers feeling the pinch. In the face of tumbling approval ratings, Joe Biden has suddenly propelled inflation-fighting to the top of his economic agenda, arguing that “reversing this trend is a top priority for me”.
It’s unclear what that means. Throwing federal money around like confetti is a strange way to fight inflation, but the administration continues to insist that the recently signed Infrastructure Bill and the larger “Build Back Better” agenda have nothing to do with the price pressures in the economy. They even have the chutzpah to argue that these programmes – aimed at tackling a host of other pressing challenges – will help pull down inflation by bolstering the supply side of the economy.
Perhaps the most obvious inflation-fighting tools in the administration’s arsenal are releasing oil from the Strategic Petroleum Reserve (SPR) and cutting tariffs on Chinese imports. The SPR contains the equivalent of 600 million barrels of oil in underground tanks in Louisiana and Texas. It was used to lean against oil prices in 2011 under the Obama administration (with Joe Biden in the Vice President’s office) and has been under discussion by the administration over the past month. This obviously wouldn’t be a long-term fix to cool oil prices, but it would represent a short-term supply boost of up to 4.5 million barrels per day.
Tariffs have been frozen since the Trump presidency at an average rate of just above 19% (up from 3% before the trade war started). It would have seemed unthinkable a few months ago that Biden would consider rolling back tariffs given the political danger of being outflanked by the Republicans on this issue.
However, maybe that calculus is changing with the growing inflation concerns. Tariff reduction would offer marginal relief on the outlook for both US inflation and Chinese growth. It would be very warmly welcomed by financial markets as a result. A virtual summit between Presidents Xi and Biden is scheduled for this week. We’ll be watching closely for any hints of a thaw in relations.
Please check in again with us soon for more relevant content and news.
Please see the below article from JP Morgan received this morning:
The global leaders from around 200 countries that convened for the COP26 summit had a stark warning from scientists ringing in their ears. If limiting global warming to less than 1.5 °C versus pre-industrial levels was to remain within reach, swift and decisive action at COP26 was required. While several new announcements were made in areas including coal, deforestation and methane emissions, progress fell short of the scale and specificity required to give us confidence that disruptive climate outcomes can be avoided.
What have we learned?
As the practicalities of reaching net zero become clear, governments are finding the short-term economic costs unpalatable. Massive change is required to reach net zero emissions, which in the short term is likely to involve considerable economic cost. Finding new jobs for many of the roughly 30 million people involved globally in the fossil fuel sector is one clear example. The short-term costs are making governments hesitant in committing to ambitious targets. This was evident in statements from leaders in the emerging world, who stressed that climate ambitions must be balanced against economic goals.
The summit did see some new commitments: of particular note was India’s pledge to reach net zero by 2070 and to triple the usage of renewable energy by 2030, while the announcement that the US and China will cooperate on emission cuts was also encouraging. Yet the reluctance of both China and India (among others) to join global commitments on coal power and methane emissions sent a clear message: the energy transition will not be prioritised above economic progress, unless wealthier nations are willing to take into account their high cumulative emissions since the beginning of the industrial revolution and ramp up their support to help with the economic costs. In the developed world, several countries have upgraded their climate targets this year but current levels of emissions when judged on a per capita basis often compare much less favourably to emerging markets, especially for the US.
In addition, analysis from Climate Action Tracker highlights that the UK is the only major developed nation to have policies and targets deemed “almost sufficient” to limit warming to below 1.5 °C, with no wealthy nation’s plans currently being ranked as sufficient.
Developed markets will provide more financial support to the emerging world, but it’s not coming quickly. In 2009, wealthy countries committed to make USD 100 billion a year available from public and private sector sources to the developing world by 2020. But this target was not met. While accelerating the available levels of financing was a key priority of the conference, it still looks like the USD 100 billion target will only be reached in 2023.
The onus will fall on the private sector to drive change. Our other key takeaway is that governments are reluctant to be the ones inflicting the economic pain. The lack of agreement on the future of a global carbon market and carbon price was a major disappointment. In the absence of clear government solutions to drive change, the focus – and indeed the key breakthrough – was the agreement to ensure the financial system will deploy capital in a manner consistent with climate objectives. The Glasgow Financial Alliance for Net Zero, an initiative tabled by Mark Carney, saw over 450 financial institutions commit more than USD 130 trillion of private capital to support the net zero transition. Yet governments will still have a key role to play here: a combination of policy incentives and clearer guidance on future regulation will be necessary to enable the financial sector to effectively put its capital to work.
Investors will need to pay more attention to the climate risks in their portfolio. Even when assuming that current pledges are implemented in full and on time, restricting global warming to 1.5 °C still appears unlikely based on analysis from across the scientific community. The potential for macroeconomic disruption, not just in carbon-intensive industries but extending across the economy, will increasingly need to be factored in by long-term investors. Physical climate risks, most acute in the emerging markets, will sadly also warrant careful consideration.
Please continue to check back for a range of blog content from us and from some of the world’s leading fund management houses.