Team No Comments

Can ethical investing help narrow the gender investment gap?

Please see below article received from AJ Bell yesterday, whose research team have found that women are more inclined to invest in green policies when looking for investment opportunities.

Women invest less than men, that’s a fact. A new study* commissioned by AJ Bell suggests the average level of savings and investments held by women is less than half the amount held by their male counterparts.

To put a number on it, if you extrapolate the average difference in savings and investments between the men and women questioned and factor in the UK population then the gender investment gap comes in at a staggering £1.65 trillion.

There are many reasons for the gap from pay differences to maternity leave and the fact women simply think differently to men, but there could be one change that might start to make a difference.

SEEKING POSITIVE CHANGE

Chatting to two first time investors during research for our new Money Matters campaign it emerged that while both women had different reasons for starting their investment journeys both had really focused on the ability to have their money work for positive change.

31-year-old Dee told me: ‘When I first started investing… I was just happy to give it a go to see if it was for me. As I got more experienced it very much became a conscious decision of what company I invested in and any organisations that I would like to support.

‘I started reading an organisation’s green policies… and it actually did become an emotional decision and it still is. Now I will only invest in a company that I believe will do good for the planet or at least has a green initiative.’

Similarly, Georgia, who is 28, said, ‘I think the first time I looked at (investing) I was getting a sense of how it worked. I invested a small amount, but I got to grips with what all the different words meant. Now I’ve been able to use that information to make more ethical decisions about where I put money and decide the best options for me that fit my values as well.’

RESPONSIBLE INVESTING ON THE RISE AMONG MEN AND WOMEN

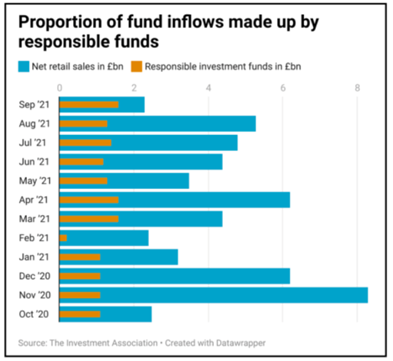
That’s not to say women are the only ones putting their money where their ethics are. Two thirds of fund inflows in September went into products that invest specifically according to ESG (environmental, social and governance) principles and over the past year most months saw around £1 billion of funds being invested in ‘responsible’ funds.

But as Dee says, at least among her friends, investing means different things to different people. ‘I’ve got a small circle of friends that invest. Some are female, some are male. Most of my female friends only invest in companies they believe in. Most of my male friends, in fact all of them, invest in the company they think will get them the most money or most reward. In return they very rarely look at the company as a whole.’

Ethics isn’t a barrier to rewards and when you look at AJ Bell’s most traded lists for this year and compare it with five years ago you can see change is coming, albeit slowly.

INVESTMENT APPETITES ARE CHANGING

Several high carbon emitters have slipped out of the top 10 most traded stocks, but BPremains a popular choice and its ESG credentials come with great big caveats.

Pre-packaged funds which tell investors exactly what’s ‘in the tin’ have become more popular, and making sure that investors have easy access to clear information might be the most significant thing to emerge from COP26, the Glasgow-based climate change summit of world leaders.

From April next year over 1,000 of the largest UK registered businesses will be required to disclose mandated climate-related financial information, and investment products will also come under the spotlight with the FCA, the financial regulator, due to consult on criteria for ESG labels.

It’s often said knowledge is power but there have been many complaints that ESG reporting has lacked clarity and a mechanism for judging whether all those net-zero promises are more than just lip service.

In this case the knowledge might make a double impact, helping make the UK and the world a cleaner, greener place and giving more women the impetus and the confidence to seek out investing for the first time. Helping the planet and helping themselves.

Please check in again with us soon for more relevant content and news as we approach the festive season.

Stay safe.

Chloe

12/11/2021

Team No Comments

Daily Investment Bulletin – Brooks Macdonald.

Please find below, a “Daily Investment Bulletin” received from Brooks Macdonald yesterday afternoon – 10/11/2021.

What has happened

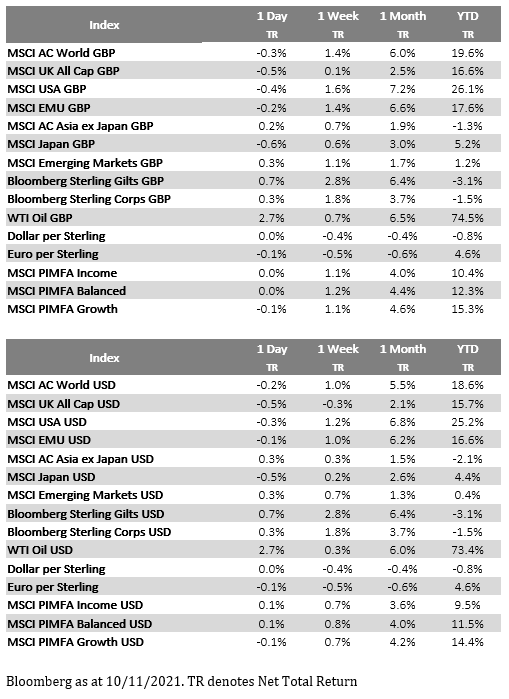
Equities finally broke their winning streak yesterday with the US market down a third of a percent. Tesla dragged discretionary stocks lower as fallout continue from founder Elon Musk’s twitter poll proposing a partial sale of his Tesla stake.

Inflation

Today sees the long-awaited publication of the latest US CPI number. Whilst the headline number will drive the news flow, the true devil will be in the detail with the subcomponents scrutinised for signs of transitory versus persistent forces. Supply shock areas such as used cars and new cars are expected to show inflationary pressure given the ongoing global issues over semiconductor shortages. COVID reopening areas such as travel and hotel accommodation continue to be skewed by base effects from the pandemic last year and as such can be volatile. Finally, housing subcomponents will be a test of whether inflation is broadening. Housing, like all the sub-indices will be distorted by last year’s readings but given its importance in the basket it will be closely watched. Earlier today China’s Producer Price Inflation came in at 13.5%, the highest level in over 25 years which acts as a good indicator that upstream supply side issues are still rife. In better news for the transitory inflation camp, natural gas prices fell by over 8% in both the US and Europe yesterday.

Interest rates

Yesterday saw yields fall in the US and Europe and the yield curve flatten. One of the drivers of this is the expectation that any change at the Federal Reserve would likely favour a more dovish position. Fed Governor Brainard is being considered for the Fed Chair position alongside incumbent Powell, Brainard is considered to be more dovish so this offers the choice to markets of either the status quo or lower for longer. With additional Fed seats now vacant there is also more scope for the White House to propose more dovish candidates for the vacancies.

What does Brooks Macdonald think

Whilst the US market ended its extensive winning streak there was no clear catalyst to the change in mood so this likely reflects some gain fatigue rather than anything more concerning.

Please check back in again soon for a range of blog content from us and from some of the world’s leading fund management houses.

Alex Kitteringham

10th November 2021.

Team No Comments

Stocks rally as central banks maintain dovish stance

Please find below, a ‘Markets in a Minute’ update received from Brewin Dolphin late Tuesday afternoon – 09/11/2021

Global equities rose last week as major central banks struck a dovish tone on interest rates and US jobs data proved far stronger than expected.

 The FTSE 100 added 0.9% after the Bank of England surprised the markets by voting to keep interest rates unchanged. Germany’s Dax also rallied 2.3% as the European Central Bank (ECB) indicated that interest rates would stay low for some time.

In the US, the S&P 500, Dow and Nasdaq added 2.0%, 1.4% and 3.1%, respectively, as the Federal Reserve stuck to its view that high inflation would prove transitory and would not necessitate an immediate rise in interest rates.

Over in Asia, the Liberal Democratic Party’s solid win in Japan’s general election boosted the Nikkei 225 by 2.5%. In contrast, China’s Shanghai Composite lost 1.6% amid renewed Covid-19 restrictions and ongoing concerns about the country’s property sector.

Last week’s market performance*

• FTSE 100: +0.92%

• S&P 500: +2.00%

• Dow: +1.42%

• Nasdaq: +3.05%

• Dax: +2.33%

• Hang Seng: -2.00%

• Shanghai Composite: -1.57%

• Nikkei: +2.49%

* Data from close on Friday 29 October to close of business on Friday 5 November.

US stocks rise on passing of infrastructure bill

Wall Street stocks started this week on a strong footing, with Congress’ approval of President Joe Biden’s infrastructure spending package leading to gains across the industrial and material sectors on Monday (8 November). The $1trn package, which was passed by the House of Representatives late on Friday, will provide new funding for transport, utilities and broadband, among other infrastructure projects.

UK and European equities started the week on a more subdued note following a mixed session in Asia overnight. The FTSE 100 slipped 0.1% on Monday after a survey showed UK consumer confidence in October fell to its lowest level since March. However, the upbeat mood in the US boosted sentiment at the start of trading on Tuesday, with the blue-chip index managing a 0.1% gain.

 BoE holds rates at record low

The Bank of England surprised investors last week by voting to hold the base interest rate at its historic low of 0.1% despite surging inflation.

Andrew Bailey, the Bank’s governor, said he was ‘very sorry’ that households were feeling the impact of rising prices, but that the Bank wanted to see what impact domestic and global issues were having on the cost of living before deciding on whether to raise rates. He told the BBC that current conditions were different because inflation was being driven by global supply shocks rather than demand pressure in the UK economy.

The Bank signalled that the base rate could rise in the coming months amid forecasts that inflation is likely to hit 5% next year. Nevertheless, the pound fell against the dollar by 1.5% following the decision.

ECB rate hike ‘very unlikely’ in 2022

Investors were also speculating that the ECB would raise interest rates next year amid a 13-year high in the rate of inflation. However, ECB president Christine Lagarde said a rate increase would be ‘very unlikely’ to take place in 2022. She was quoted by Reuters as saying that despite the current surge in prices, the outlook for inflation over the medium term remains subdued, and therefore the ECB’s three conditions for a rate hike are unlikely to be satisfied next year.

Lagarde also pushed back on expectations of a tightening in monetary policy, saying the ECB would continue to use emergency asset purchases to keep borrowing costs down. “An undue tightening of financing conditions is not desirable at a time when purchasing power is already being squeezed by higher energy and fuel bills, and it would represent an unwarranted headwind for the recovery,” she stated.

Fed holds rates near zero

The Federal Reserve also announced it would keep its main policy rate near zero for now, but said it would begin scaling back its $120bn monthly bond-buying programme this month. The Federal Open Market Committee said it could start withdrawing stimulus because it had achieved ‘substantial further progress’ towards its twin goals of maximum employment and inflation that averages 2%. Fed chair Jerome Powell added that the bar for raising interest rates was higher than that for tapering.

“It is time to taper, we think, because the economy has achieved substantial further progress toward our goals,” Powell was quoted by the FT as saying. “We don’t think it’s time yet to raise interest rates. There is still ground to cover to reach maximum employment, both in terms of employment and in terms of participation.”

Economic data stronger than expected

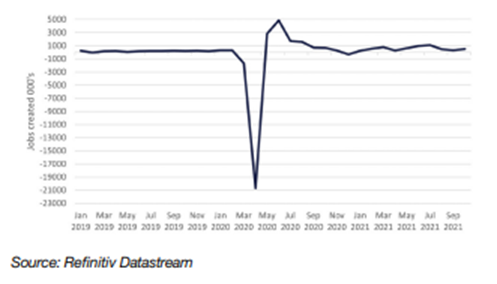
The policy meeting came a couple of days before the latest US nonfarm payrolls report showed the jobs market bounced back in October. Nonfarm payrolls increased by 531,000 from the previous month, according to the Labor Department, compared with the Dow Jones estimate of 450,000.

US non-farm payrolls

Private payrolls showed even stronger growth, rising by 604,000. This was far higher than 312,000 gain seen in September – a figure that was revised up from the Labor Department’s previous estimate of 194,000. Leisure and hospitality drove gains as the number of Covid-19 infections declined. Meanwhile, the unemployment rate fell to 4.6%, marking a new pandemic low. Elsewhere, figures showed US factory orders unexpectedly rose in September by 0.2% from the previous month. Economists polled by Reuters had forecast orders to remain unchanged. On a year-on-year basis, orders were up by 17.6%. However, manufacturing is still constrained by shortages of labour and materials, with manufacturing activity slowing in October, according to the latest survey from the Institute for Supply Management.

Please continue to check back for a range of blog content from us and from some of the world’s leading fund management houses.

David Purcell

10th November 2021

Team No Comments

Legal and General Asset Allocation Team Update

Please see the below update from Legal and General Investment Management’s (LGIM) Asset Allocation Team:

Investors often think that whatever happens in financial markets is the most important thing in everyone’s lives. Last week, with COP26, it was easy to wake up from that distortion. World leaders and captains of industry, including our own CEO, Michelle Scrimgeour, gathered for the United Nations climate change conference. It looks like they made good progress, though much still needs to be made concrete.

Back in the world of macro minutiae, central bankers mostly indicated that monetary tightening will take longer than investors expect. Both equities and bonds liked that message.

As with all Key Beliefs emails, this represents solely the investment views of LGIM’s Asset Allocation team.

It might be a COP out, but…

We use a cyclical framework (a sort of investment clock) to drive our medium-term risk taking. Our confidence in our assessment of the current position of the cycle is lower than normal — due to the pandemic, the extraordinary policy response and the unique nature of the supply disruptions.

We see the risk that the US and some other economies are later in the cycle than realised, and that the currently high rate of inflation will act as a catalyst for more persistent inflation.

Even though uncertainty is increasing, our research shows that even a late-cycle view isn’t necessarily bad for risk assets as long as the recession risk remains low. We think the 12-month recession risk is increasing, but from a low base. We are wary of taking risk off too soon, especially as we see the majority of possible outcomes for now as equity-positive with above-trend growth. So, despite the challenges to our framework, we are sticking to our bullish medium-term view and remaining long equities.

VIX and MOVE: Good COP bad COP

There’s a growing gap between bond and equity volatility. While the VIX index – a summary measure of US equity implied volatility – has revisited post-Covid lows, the MOVE index – a roughly equivalent measure for US Treasury bond implied volatility – was busy making new post-Covid highs.

Bond volatility has broadly risen in line with yields over the past year. The positive correlation between the two makes sense: assuming the existence of some implied lower bound to interest rates, large yield movements are less likely to occur at low levels. As yields rise, so too then should market-implied volatility.

The relatively gradual increase in the MOVE index masks a pretty dramatic increase in volatility at the shorter end of that spectrum over the past month. One-month two-year swaption volatility rose threefold from mid-October to the start of last week, as short-term rates reflected a more hawkish Fed.

While the low level of equity implied volatility may be an attractive entry point for a long position – in strategies that allow it, we currently hold VIX calendar spread positions to take advantage of the sort of short-term spikes in volatility that become more likely as we move from mid- to late-cycle – we don’t see the rise in bond implied volatility as an opportunity to go short. To the contrary: with rising yields and uncertainty around inflation expectations, two-way risk is ever more present, so we are holding on to our long interest rate volatility positions for now.

Calling the COPs on the currency manipulators

In the easing cycle, we saw some central banks resorting to currency intervention as the zero-bound in interest rates kept them from cutting rates further. We believe that with the tide turning, the first thing those central banks will do is step away from currency intervention and allow their currencies to strengthen. It could be argued that currency strength is more effective than rate hikes in managing inflationary pressures resulting from supply-side constraints.

Switzerland and Israel are clear examples where central banks had intervened to stop their currencies from appreciating, but now the franc and shekel have resumed strengthening. Some central banks are more explicit about their goals than others, but our emerging market economists have done some interesting work to unmask the “currency manipulators” by scrutinising foreign exchange reserves.

This is important, as we believe we may see more strength from such currencies. Based on this work, we have increased our exposure to the Indian rupee. In the latest US Treasury Department’s semi-annual report, India is on the list of countries that merit close attention to their currency practices and macroeconomic policies.

If it’s not inflationary pressure that convinces India’s central bank to stop currency intervention and let the rupee appreciate, political pressure may do the trick.

Please continue to check back for a range of blog content from us and from some of the world’s leading fund management houses.

Andrew Lloyd DipPFS

09/11/2021

Team No Comments

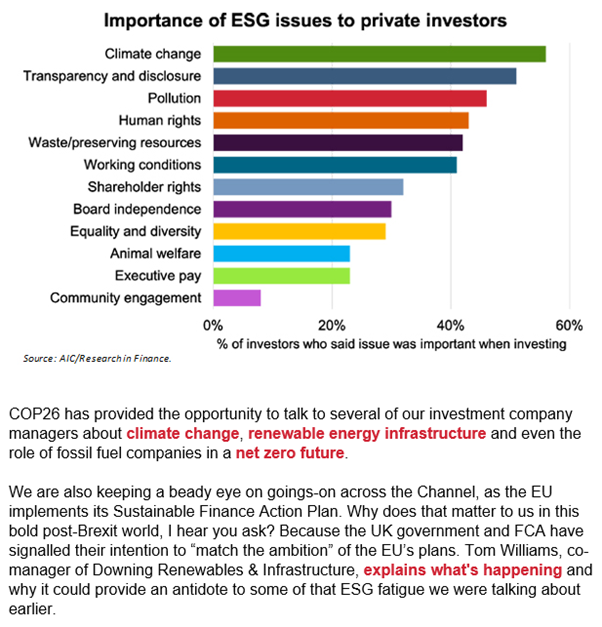
The AIC – Facing up to the ESG fatigue

Please see below an article from The AIC, which was received yesterday (04/11/2021) covering their views on ESG discussions:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

Independent Financial Adviser

05/11/2021

Team No Comments

Daily Investment Bulletin

Please see below article received from Brooks Macdonald yesterday, which provides an update on the markets as world leaders reconvene for a fifth day at the United Nations Climate Change Conference in Glasgow.

What has happened

Global equities continued their series of fresh highs yesterday with mild gains across the US and Europe. Earnings continue to be a driver of these gains, even if they look slightly less bountiful than at the start of the season, with c. 90% of US companies reporting yesterday beating their earnings estimates.

Central Banks

After the RBA decision yesterday we saw a rally in sovereign bonds as bond markets priced in the possibility of central banks’ bark being worse than their bite. The major event today will be the Federal Reserve decision which is widely expected to contain a reduction in the monthly asset purchases by the US central bank. It’s worth noting that this is tapering the pandemic quantitative programme i.e. until the middle of next year there is still pandemic era net stimulus being provided by the Fed, just every month it’s slightly less. The distinction between a withdrawal of pandemic era stimulus narrative versus the beginning of a tightening cycle will be a tightrope all central banks will need to walk. Meanwhile President Biden yesterday said that we would make an announcement ‘fairly quickly’ on whether Fed Chair Powell would continue in his post for another term.

US Politics

Voters have gone to the polls in Virginia and New Jersey to elect their new governors. Several news outlets have called Virginia for the Republicans and rumours are abound that New Jersey will follow the same path. Virginia saw a 10 point margin of victory for Biden in the Presidential Election so a defeat here will be politically difficult for the President and bode badly for the mid-terms next year. Whilst a year is a long time, the probability of legislative gridlock in the US after the midterms seems to be increasing.

What does Brooks Macdonald think

A tapering announcement at the Fed’s meeting today is very much in line with the market’s expectation, however what will be of more interest is whether the Fed push back against the interest rate pricing for 2022. The difficulty for Fed Chair Powell is the highly uncertain path of near term inflation, should the inflation issues prove transitory a 2023 rate rise is probably still the base case, should pressures continue into the middle of next year a 2022 rate hike (or two?) is on the cards.

The Fed did as expected yesterday and reduced asset purchases. It will be interesting to see what the Bank of England do today on interest rates.

Please check in again with us soon for further relevant news and content.

Stay safe.

Chloe

04/11/2021

Team No Comments

Prudential – Common misconceptions about investing for good

Please see article below from Prudential, which covers the common misconceptions about investing for good, received yesterday afternoon – 02/11/2021

Common misconceptions about investing for good

Mythbusters

In today’s world of social media and the web, it’s often hard to separate the facts from the fiction. Just because we hear something often doesn’t necessarily make it true. For example, have you ever heard a goldfish only has a 3-second memory span or that lightning never strikes twice? Both these things have been scientifically proven as untrue and yet people still believe them.

When it comes to investing, there are many misconceptions out there. One of the areas that are often misunderstood is investing to help people and the planet. There are ways to give your money a chance to work harder whilst also helping to create a better world. We want to address some of the common questions and confusion about this. It may be for you, it may not, but to make that decision – it’s important to know the facts.

Does investing for good only help the environment?

While the environment plays a huge part in ‘investing for good’ it is not the only focus. Firstly when we say environment it covers a wide spectrum from climate change, finding environmental solutions to tackling the huge amount of waste in today’s world with a circular economy. Secondly investing for good aims to tackle some of the most pressing issues facing society. This ranges from diversity and inclusion within society and workplaces, better work and education and better health which saves lives.

Investing for good looks to invest in companies proactively finding solutions to these challenges whether that is advancements in medical treatments or bringing education to smaller communities in remote locations.

It goes way beyond ‘just the environment’.

Does investing for good give poorer returns?

A survey by the Global Impact Investing Network (GIIN)* shows that an overwhelming majority of people who took part reported their impact investments as meeting or exceeding their financial expectations.

The same survey also goes on to show that over half of the impact investments looked at resulted in competitive returns.

The idea that you can’t make money whilst doing good is simply wrong.

Of course, as with any investment, it can go down as well as up and you might not get back what you put in. It’s also important to know that past performance Is not a guide to the future.

Is it too risky? 

All investments have a level of risk, but there’s no reason why investing to help create a better world would mean your money was at greater risk than investing in something else. A common misconception could for example be that all companies with big dreams about saving the world are risky startups with no profits. This simply isn’t true. In fact to the contrary often it can be large industry-leading companies – that can have positive outcomes on society and the planet.

An adviser will always talk to you about the level of risk you are willing and comfortable taking as well as how much money you can afford to lose.

Is ‘investing for good’ a fad?

The ideas behind investing for good are not new, but there has been a surge in demand for funds that invest to help the planet. Based on data from the Global Sustainable Investment Alliance, the amount invested in sustainable investments globally is more than US$30 trillion.

Sustainable investing is becoming more popular with societal shifts such as the mass rejection of single-use plastic and climate change warnings.

The importance of looking after our planet and society is becoming a movement with the younger generation and is only set to continue.

*GIIN Annual Impact Investor Survey, 2020

Please continue to check back for more ESG related insights along with our usual market updates and blog posts.

Charlotte Clarke

03/11/2021

Team No Comments

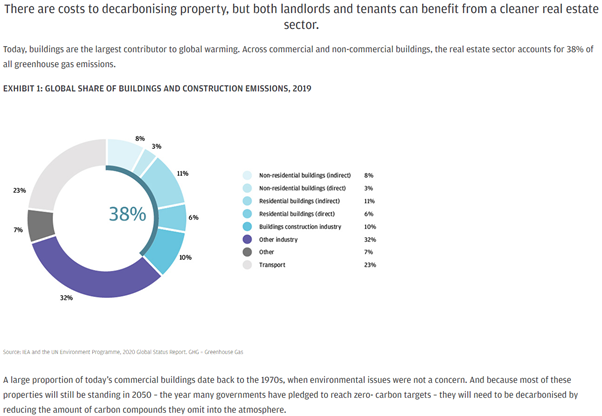
J.P. Morgan – Buildings reimagined: Why carbon neutral property is the future of real estate

Please see below an article from J.P. Morgan which was received yesterday (01/11) and covers their views on the Property sector and going carbon neutral:

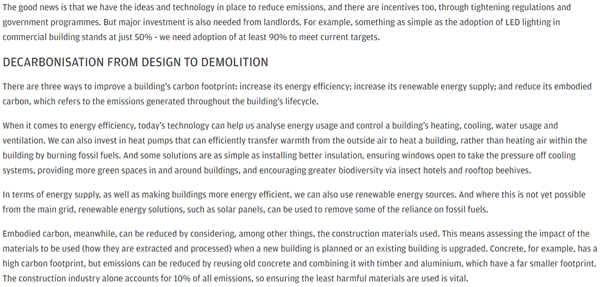
As you can see from the above, Property, both Commercial and Residential, account for a high proportion of total green house gases. This means that a lot of investment is needed in this sector in an effort to move towards becoming carbon neutral.

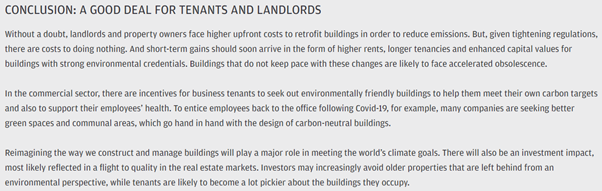
There also seems to be a focus on trying to get employees back into the office, which could help a full recovery on Commercial Property investment.

Property is a key focus of COP 26 and we believe it still has a vital role to play in an investors portfolio. It is a great diversifier and normally provides some inflation proofing as it is backed by a real asset that generally has upward only rent reviews in the commercial sector.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

Independent Financial Adviser

02/11/2021

Team No Comments

COP26: For market support the world needs its leaders to lead

Please see the below blog article taken from this weeks Tatton Weekly, a weekly update from Tatton Investment Management:

The 2021 United Nations Climate Change Conference, known as COP26, begins on Sunday. Current weather forecasts for Glasgow are perhaps a little too literal, with visitors to the city braced for torrential rain and flooding. Along with the precipitation there is also an air of – if not downright pessimism – ahead of the summit. Last month, Boris Johnson told world leaders at the UN that “it is easy being green” and referenced Kermit the Frog to reinforce his point. But on Monday, he was downplaying expectations by telling schoolchildren and reporters in Downing Street that it was “touch and go” whether COP26 would deliver any sort of climate change breakthrough.

The mood darkened further this during the week after it was announced that the $100 billion of climate finance promised by developed countries in 2005 – pledged to help developing countries adapt to climate change – had not been met by the original deadline of 2020, and would most likely not be reached until 2023.

Next came another stark warning from the UN, ratcheting up the pressure on COP26 attendees. It declared climate goals are off track and emissions rise could lead to 2.7°C warming. Some countries, notably China and India, have not updated their emissions reduction pledges ahead of the summit. Other nations, including Brazil, have submitted weaker pledges than were outlined in their original commitments. As one of the UN delegates succinctly put it: “Unless more progress is made in the next fortnight, we will all be in trouble.”

We don’t have a crystal ball of course, so it’s impossible to make any predictions of what progress will indeed be made over the next couple of weeks, if any. That said, news flow this week has presented a few ideas on what to look out for.

For example, COP26 could deliver what’s being labelled a “methane moment”, after another 25 countries joined the US and EU-led initiative to drastically cut global methane emissions by 30% from their 2020 levels by 2030. That takes the total number of countries backing the pledge to 34, although again, Brazil, India and China are conspicuous by their absence. This is a positive development. While carbon dioxide (CO2 ) is the biggest contributor towards human-made global warming, methane runs a significant second. According to the International Panel on Climate Change, methane contributed to about 0.5°C of warming between 2010 and 2019 relative to 1850- 1900 levels, whereas carbon dioxide produced about 0.7°C of warming over the same period/

Although carbon dioxide gas stays in the atmosphere for longer, methane is considered some 28 times more potent in global warming terms, as its properties trap more heat.

Another initiative to look out for over the next fortnight could be further developments made on carbon pricing. Carbon pricing programmes usually involve countries taxing polluters’ carbon emissions, or ‘cap and trade’ systems that effectively limit a company’s level of emissions before costs become prohibitive.

International business groups are pushing for an international carbon price strategy to be unveiled at COP26, to prevent the bewildering patchwork collection of local policies they are struggling to contend with now. The World Bank recently identified 64 different carbon pricing initiatives across 45 countries. Disappointingly, the World Bank says these initiatives cover less than 22% of global carbon emissions, and most schemes use carbon prices too low to incentivise heavy emitters to change their business models.

Carbon trading schemes rely on private market mechanisms to attach a price to a tonne of CO2. Usually, governments set an economy-wide allowance (or per sector) and issue permits. If a company needs more permits, it has to purchase them in the CO2 market. It is a highly effective set-up (first applied in the early 1990s to reduce US sulphur emissions in the most cost-effective way), provided it comes equipped with a functioning framework. Recurring issues are that too many permits are issued, and hence the trading price drops close to zero. Remedies to this include issuing fewer permits or, as California has decided, introducing a floor, which is then a carbon tax that the government levies. Besides poorly set-up trading mechanisms, control and enforcement mechanisms also tend to be too weak. What really seems to be lacking, on top of it, is international co-ordination on such schemes, which renders them currently to be somewhat akin (and globally ineffective) as domestic stock markets that operate under capital controls.

Getting a majority of countries to agree to some sort of carbon pricing framework looks like a tall order. A carbon price that is high enough to limit rising temperatures to no more than 2°C from pre-industrial times is considered unworkable by the likes of the US, China and India. The EU, however, has been more forward-thinking, adopting its own ‘carbon-border adjustment mechanism’. This would mean companies importing goods – such as steel, aluminium, fertiliser, cement or electricity – into the EU would have to buy carbon certificates that reflect the same carbon prices faced by European producers under the EU’s emissions trading system. However, even this scheme has been criticised, with detractors suggesting it could lead producers from developing nations to sell into other markets with lower standards, hindering climate action.

The UK is not a member of the EU’s mechanism, which is perhaps another example of the somewhat muddled response from the UK government. At COP26, Boris Johnson will plead with the international community to make significant pledges to cut carbon emissions. Yet on Thursday, Rishi Sunak’s Autumn Budget drew criticism for measures that would make it cheaper to take domestic flights. Sunak also continued the time-honoured practice of freezing fuel duty (a freeze that has remained firmly in place since 2010), which has the net result of making car travel less expensive than more environmentally sustainable alternatives. According to the Office for Budget Responsibility, this year’s fuel duty freeze alone will mean an additional 450 million litres of fossil fuels purchased over the next five years. Such mixed messages certainly make alignment difficult.

When it comes to tackling climate change, every action has a reaction, and risks creating losers as well as winners. Which leads us to another key theme that has emerged this week: divestment. On Tuesday, Europe’s biggest pension fund, ABP of the Netherlands, announced plans to divest €15 billion worth of fossil fuel assets by early 2023. The fund said it doesn’t expect the decision to hurt long-term returns and added that the move will allow it to unveil a more ambitious CO2 reduction goal next year. Also on Tuesday, several UK faith institutions, announced an en masse $4.2 billion divestment from coal, oil and gas companies. Six cities, including host city Glasgow, have also said they will sign formal commitments to dispose of their fossil fuel assets in the future. According to the DivestInvest lobby group, that helps to bring the totals committed to be divested by asset managers on behalf of their investors to a stunning £39 trillion in the next few years.

Unsurprisingly, fossil fuel producers have spoken out against the hidden dangers of divestment. Coal producer Glencore argued that the movement was counterproductive, as it would force them to dispose of their assets and place them in the hands of less responsible owners (‘brownwashing’). Other producers have pointed out that it is better to allow these assets to run down, and that companies that demonstrate engagement on addressing the climate agenda should still be deemed worthy of investment. They do have a point. After all, divestment arguably just means gains are being pushed elsewhere and perhaps towards investors without CO2 reduction aims at all, and that will most likely have unforeseen and unintended consequences. Unceremoniously dumping fossil fuels might well be a ‘quick win’ for funds that are keen to decarbonise their portfolios – although whether this has a net positive effect on the environment – as discussed above – is another matter entirely. It changes the dynamics of capital markets, certainly, but without addressing the underlying problem. After all, selling the stocks themselves doesn’t reduce the demand – or use – of fossil fuels. Instead, it’s likely to just make stocks more volatile, and therefore tradeable. Without government action, and policy on a global scale, that discourages the use of fossil fuels, there will always be a demand for ‘dirty fuels’ to be met by someone.

The markets will always look towards global leaders to provide them with the framework in which they can successfully operate. If we think green investment is still the missing piece of the puzzle, and we want the market to help solve this problem, we need a framework that is clear, transparent and can be relied on to be here to stay to provide the planning certainty that is so crucial for successful longer-term investments. At the same time, from an investment point of view, it’s important to recognise that climate change is not a sector-by-sector issue. The whole of the economy has to ‘green up’, while accepting the risk of stranded assets and that there will be losers as well as winners.

Climate change is a global problem that requires a truly global approach. The key point regarding COP26 is that big events like these can – and must – be used to create common frameworks. So far, governments have been walking a political tightrope in terms of making the right noises about dealing with climate change, but without making the hard choices that a genuine commitment demands, or without being honest about what a fully transitioned global economy would look like – for better or worse. We can’t keep having it both ways.

What is COP26 and why is it happening?

COP 26 is the 2021 United Nations Climate Change Conference which is currently being held in Glasgow from 31st October – 12th November.

The world is warming because of fossil fuel emissions caused by humans.

Extreme weather events linked to climate change – including heatwaves, floods and forest fires – are intensifying. The past decade was the warmest on record, and governments agree urgent collective action is needed.

For this conference, 200 countries are being asked for their plans to cut emissions by 2030.

They all agreed in 2015 to make changes to keep global warming “well below” 2°C above pre-industrial levels – and to try aim for 1.5°C – so that we avoid a climate catastrophe.

This is what’s known as the Paris Agreement, and it means countries have to keep making bigger emissions cuts until reaching net zero in 2050.

Keep checking back, we will be posted regular updates and articles as the conference takes place and announcements are made.

Andrew Lloyd DipPFS

01/11/2021

Information Source: Tatton Weekly and BBC News

Team No Comments

Market impact of company updates more obvious than economic data

Please see below article received from AJ Bell yesterday afternoon, which seeks to explain how economic set-pieces and corporate releases influence stocks.

You don’t need a degree in finance to understand that both company earnings reports and major economic indicators and events both influence the investing landscape.

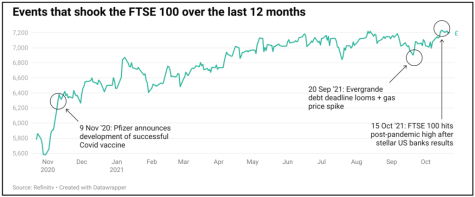
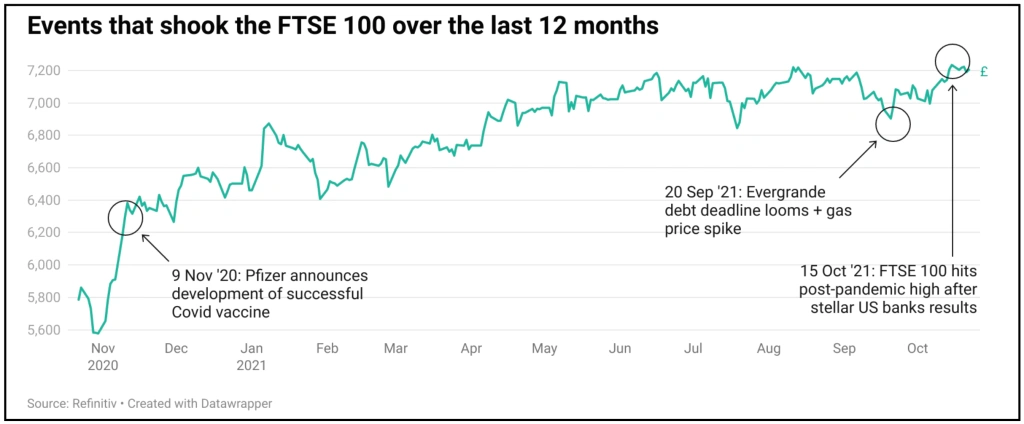
However, looking at how London markets have performed over the last, complicated, 12 months it’s interesting to dig into those peaks and troughs and explore trends.  Just weeks ago, at the start of the latest round of company earnings, the FTSE 100 surged to a pandemic high despite ongoing concerns about supply snarl ups and rising prices.

US banks in particular exceeded expectations, but it wasn’t just banks and it wasn’t just US companies reporting forecast busting figures. It’s not surprising that stellar results whet investor appetites.

They’re straightforward and immediate. If profits and earnings are up there’s an instant catalyst to buy and vice versa when the numbers disappoint.

The X-factor is surprise. Investors are pretty good at picking up cues and pricing them in, so often its more about how a company does relative to expectations rather than how it makes out in absolute terms. Sometimes just meeting expectations will disappoint investors.

Updates from individual firms may have a significant impact on their own share price but a limited one on the wider market in isolation. However, in combination a results season can set the tone for the markets.

MARKETS DON’T LIKE SURPRISES

Economic data typically acts more like a drip, drip of incremental news which gradually shifts investor sentiment in different directions. Often individual releases like GDP figures don’t tend to make big ripples unless there’s a major upset.

For example, China’s latest growth numbers unsettled many people but that’s because any slowdown seems unusual, and they came off the back of events which have already impacted sentiment towards China, from the tech crackdown in May to the Evergrande debacle which came to a head in September.

Both of those events in singularity took time to permeate through to big market movements, primarily because it was hard to know immediately what the situations might mean, it can take days or even weeks for the ramifications to really permeate.  It buys investors time, gives them breathing space to make adjustments in their portfolios and get comfortable with the winds of change.

It’s why the anticipated interest rate hike from the Bank of England which has received so many column inches has seemingly had a modest influence on markets so far.

Even when it comes it’s unlikely to merit much of a move, unless the MPC (Monetary Policy Committee) go bonkers and shoot for a whole 1% all in one go, but that’s about as likely as the UK experiencing a white Christmas in June.

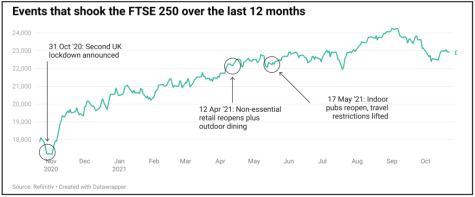
The more UK-facing FTSE 250 index has endured a year of uncertainty. Covid hasn’t run in a smooth line, lockdowns have had to be re-implemented, ‘Freedom Days’ have had to be shifted and sometimes the expected benefits are undone by crises like the ‘pingdemic’ which saw many businesses scrabbling to find the staff they needed just to keep operations going.

When the economy has enjoyed a smooth run, when the recovery juggernaut ploughed through, the FTSE 250 soared; its domestic companies expected to benefit from a return to something like business as usual.

RISING PRICES NOT THE ONLY TROUBLE AHEAD

Gas prices on the other hand, they nestle between the two extremes. On the one hand rising prices and the impact they were having on energy providers could be clearly seen for some time. The energy cap was going up, small providers were dropping like flies.

But this impact was crystallised in a single day, a day of extremes, that made waves. After a 37% jump in 24 hours the gas price cooled as the Russian president stepped forward and seemed to imply more supply would be forthcoming to Europe.  

Forget the next 12 months, the next six months is shaping up to bring more of those heart stopping, unexpected moments that markets hate to love and many more of those priced in economic set pieces.

And the next quarterly results, the judgement is still out on that one… even among companies which have beaten analysts’ estimates, there have been warnings that margins are set to be eroded, that supply issues and inflation will take their toll.  Investors love certainty, but in the unexpected there are opportunities as well as potholes.

Please check in again with us soon for further relevant content and news as we approach the festive season.

Stay safe.

Chloe

29/10/2021