Team No Comments

Budget notes from Brewin Dolphin

Received last night, 27/10/2021.  Our thoughts added.

Chancellor Rishi Sunak has delivered his autumn budget, in which he announced a series of measures that aim to strike a balance between “preparing for a new economy post-Covid” and ensuring household wallets are not unduly squeezed by rising prices.

The budget came against a backdrop of unprecedented government borrowing, supply chain disruption, rising energy prices, and surging inflation that is forecast to reach 4.4%1 next year. Yet with economic growth forecasts more optimistic than six months ago, Sunak moved away from the March budget’s focus on protecting people’s jobs and livelihoods to one of investing in public services and infrastructure. 

After already freezing tax thresholds and increasing national insurance and dividend tax rates, the chancellor spared investors and pensioners from further tax hikes. At the same time, he proposed new fiscal rules that would commit the government to balance the books and reduce national debt. 

Here, we look at the main announcements and what they might mean for investors and the economy.

The economy 

The lifting of lockdown restrictions over the summer provided a much-needed boost to activity, with the latest figures from the Office for Budget Responsibility (OBR) providing a somewhat rosier picture of the economy. 

The OBR expects the economy to return to its pre-pandemic level by the turn of the year, six months earlier than previously thought, with gross domestic product (GDP) growing by 6.5% this year compared with the March forecast of around 4% growth. The OBR also revised down its estimate of long-term scarring to the economy from the pandemic to 2% from 3% previously. Meanwhile, unemployment is expected to peak at 5.25%, compared with the March forecast of 6.5%, suggesting the end of furlough will have a smaller impact than previously thought. 

At the same time, higher tax receipts mean government borrowing in 2021/22 is expected to be £183bn, some £51bn lower than the previous forecast of £234bn. However, with interest payments on borrowing revised up by £15bn, and the GDP growth forecast for 2022 lowered from 7.3% to 6%, the challenge of balancing the public finances is far from simple. Sunak proposed new fiscal rules whereby net debt as a percentage of GDP should be falling, and the government should only borrow to fund investment, with everyday spending funded by taxation. 

P and B comment:

This is a really difficult balancing act, with a lot to be taken into consideration.  For example, if interest rates increase too quickly the impact on the economy could be dramatic. Consumers are spending less, and the State is having to pay a lot more to service the interest on the covid debt in addition to other debt. Total debt in the UK c £2.2 trillion.

Investment in services and the economy 

A key area of focus was the announcement of additional investment in public services and infrastructure. This will include an extra £5.9bn to help the NHS tackle the backlog of non-emergency procedures and modernise digital technology; £5.7bn to transform transport networks outside London; £4.7bn for schools; £1.8bn for new housing; a £1.4bn fund to attract overseas investment into the UK; and increased spending on sports and youth clubs, support for families and children, and crime prevention. The government will also increase its investment into research and development to £20bn by 2024/25 as part of its goal to “drive economic growth and create the jobs of the future”.

P and B comment:

A very welcome investment into research and development for economic growth and future jobs.  Unfortunately the NHS and social care will need a lot more funding.

National living wage 

In an effort to help families who are struggling with rising prices, Sunak confirmed the national living wage would rise from £8.91 to £9.50 per hour for workers aged 23 and over from April 2022. This represents an increase of 6.6%, which is double the September inflation rate of 3.1%. 

Sunak also ended the public sector pay freeze introduced last November, cancelled the planned rise in fuel duty, and reduced the universal credit earnings taper rate from 63p to 55p in the pound.

P and B comment:

All of the above points are welcome but lower earners will need every penny as they combat inflation generally and in particular energy prices this winter.

Business rates 

The chancellor froze the business rates multiplier for a further year, which he said would be equivalent to a tax cut worth £4.6bn over the next five years, with bills 3% lower than without the freeze. He also announced plans to temporarily halve business rates for the retail, hospitality and leisure sectors, overhaul alcohol duties and reduce taxes on draught beer and cider.

P and B comment:

The business rates system in the UK is now out of date and doesn’t take into account the move to online shopping.  This system needs a complete overhaul but the problem is it’s worth c £25 billion a year to the Treasury.

Personal allowances

The chancellor previously announced in March that the personal tax allowance and higher-rate tax threshold would be frozen for five years from April 2021. The personal allowance, which is the amount you can earn each year before you start paying income tax, therefore remains at £12,570, while the higher-rate tax threshold remains at £50,270. By freezing these thresholds, more people could drift into higher and additional-rate income tax bands, and potentially see their personal allowance tapered once adjusted net income exceeds £100,000. 

The national insurance (NI) threshold was also frozen at £9,568. However, as announced in September, the rate of NI for employees and the self-employed will increase by 1.25 percentage points from April 2022 to help fund health and social care costs. Working pensioners will pay 1.25% on their earned income for the first time from April 2023.

P and B comment:

Effectively no real change from previous announcements.  As we get squeezed for more tax in all areas, it makes tax planning more important.

Dividend tax

As announced in September, the rate of dividend tax will also rise by 1.25 percentage points from April 2022 to 8.75% for basic-rate taxpayers, 33.7% for higher-rate taxpayers, and 39.35% for additional-rate taxpayers. The annual dividend allowance – the amount of dividend income you do not have to pay tax on – will remain at £2,000. The changes are expected to raise around £600m for the Treasury. 

Looking for ways to mitigate dividend tax, including investing through ISAs and pensions and taking a ‘total return’ approach to investments, could therefore become even more important when the tax hike comes into effect.

P and B comment:

As above.  Tax planning is more important.  Use the right products and allowances, plan ahead.

ISA allowance

Fortunately, for savers and investors, there were no changes to ISA allowances. The main ISA limit for 2022/23 will remain at £20,000, meaning a couple could invest up to £40,000 a year into ISAs to benefit from tax-free income and growth. The limit for Junior ISAs remains at £9,000. 

P and B comment:

ISAs still remain a very useful planning product alongside other assets.

Capital gains tax

There was some speculation that the chancellor would scrap existing rates of capital gains tax (CGT) and align them more closely with income tax rates. This was recommended by the Office of Tax Simplification in November 2020 and, if implemented, would have resulted in higher-rate taxpayers paying CGT at 40% on profits or gains exceeding the annual CGT exemption. 

Fortunately for investors, this did not come to fruition. CGT rates remain at 10% and 20%, or 18% and 28% on properties that are not a main home. The annual CGT exemption remains at £12,300 after being frozen in the March budget until 2026. 

P and B comment:

This is good news.  Any ‘simplification’ would have been penal.

Pensions tax relief

It was rumoured that the chancellor would look at overhauling pensions tax relief by, for example, moving to a flat rate of 25%. In the end, Sunak chose to leave current rates untouched, meaning higher-rate and additional-rate taxpayers can continue to benefit from tax relief of up to 40% and 45%, respectively. The pension annual allowance also remains at up to 100% of taxable earnings or £40,000, whichever is lower (this may be tapered for those with high incomes). 

As more people drift into higher tax bands due to the personal allowance and higher-rate tax threshold being frozen, these tax reliefs could make pensions an even more valuable financial planning tool.

P and B comment:

Pension tax relief rumours of change have been around for years.  Thankfully, no change here.  We need to maximise our pension funding whilst we have this tax relief available to us.

Pension lifetime allowance

The chancellor announced in March that the pension lifetime allowance, which is the total amount you can save into your pension before incurring tax charges, would be frozen until 2026. The allowance will therefore remain at £1,073,100 in the 2022/23 tax year. Any money withdrawn as a lump sum above this level will incur a 55% tax charge, while money withdrawn as income will incur a 25% charge, with the remainder then subject to income tax at the individual’s marginal rate. 

While the lifetime allowance might seem generous, pension contributions, tax relief and investment growth over several decades could mean those with seemingly modest pension portfolios could be at risk of exceeding the threshold. It is therefore crucial that savers seek expert advice on the best course of action for their individual circumstances. 

P and B comment:

As more people breach the Lifetime Allowance, I think it’s perceived as a target by some, an achievement. Having more pension than the Lifetime Allowance is not necessarily an issue, it means you have good pension assets and should be able to sustain a reasonable level of retirement income over the long-term.

Other tax planning vehicles are also available if you have good levels of pension provision in place.

Inheritance tax

The inheritance tax (IHT) thresholds remain the same and will be frozen until April 2026. Everyone is entitled to pass on assets of up to £325,000 on their death, free from IHT. This may be boosted by the residence nil-rate band, for passing on a property to a direct descendant – which remains at £175,000 per person. 

This means a married couple with children will be able to pass on a maximum of £1m in total without having to pay IHT – two lots of £325,000 (£650,000) and two lots of £175,000 (£350,000).

Although IHT thresholds have been frozen, there is still uncertainty around how the tax could be treated in the future following several reports from the Office of Tax Simplification and an All-Party Parliamentary Group. Seeking advice on IHT as early as possible, when there are more potential options to mitigate the tax, could therefore prove especially important in the years ahead.

P and B comment:

If you have an inheritance tax problem, start your planning now. This type of planning is a journey and can take many years to do. 

Budget – general comment from P and B:

An interesting Budget from Rishi Sunak as he tries to balance increasing tax receipts to pay for the NHS, social care, investment in the economy and servicing the massive debt we have in the UK, whilst getting the economy back to full growth following Covid and the impact of Brexit.

It’s a very delicate balance. We need the consumer to continue spending as c 60% of the UK economy is based on consumption, and too many tax rises and increases in the cost of living could reduce consumption as we become more cautious.

The last c 19 months has been difficult but this transition phase as we try to exit the pandemic and return to normal is very tricky too. Central Banks need to maintain the status quo and not raise interest rates too quickly and governments globally need to remain supportive.

Hopefully our government and the Bank of England will make the right decisions – we will see.

Steve Speed

28/10/2021

1 Source: CPI inflation. Office for Budget Responsibility: ‘Economic and fiscal outlook – October 2021’

Team No Comments

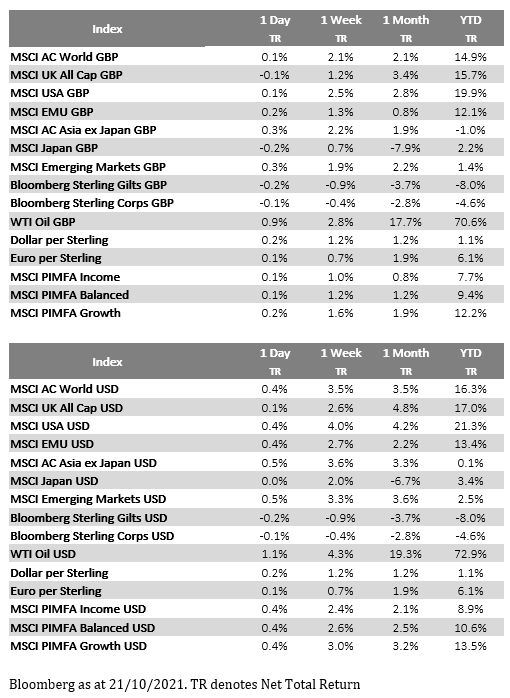
Brewin Dolphin – Markets in a Minute

Please see below Brewin Dolphin’s latest market summary, which was received late yesterday (26/10/2021) afternoon:

Please continue to check back for a range of blog content from us and from some of the world’s leading fund management houses.

Andrew Lloyd DipPFS

27/10/2021

Team No Comments

Barbara T – Hale

‘I’ve known Steve  for  over  10  years.  As  a  Financial  Adviser,  he  is  second  to  none, but  its  more  than  that,  it’s  the friendliness  that  goes  with  his  professionalism.

When  we  have  our  meetings,  I  always  feel  comfortable  and  at  ease.

Steve  explains  things  and  makes  sure  I’ve  understood  them, nothing  is too much  trouble.

Steve’s  done  a  great  job  for  me  with  my  portfolio  and  I  would  have  no  hesitation  in recommending  Steve  and  his  staff  to  anyone.’

Team No Comments

Brooks Macdonald – Weekly Market Commentary

Please see below this week’s market commentary from Brooks Macdonald received yesterday afternoon – 25/10/2021

Weekly Market Commentary | Equities perform well ahead of bumper week for US earnings

25 October 2021

Read detailed economic and market news from our in-house research team.

By Edward Park

  • US earnings season continues to show strong momentum with a bumper week ahead
  • Inflation expectations surged last week which set a rocky backdrop for the sovereign bond market
  • The UK Budget and Spending Review is likely to contain few carrots, given the outdated fiscal data the government has chosen to use

US earnings season continues to show strong momentum with a bumper week ahead

Last week saw inflation expectations surge across the US and Europe but this was counterbalanced by continued strength in US earnings numbers. Spurred by the earnings season, equities performed strongly with around one quarter of US companies having now reported and another bumper week, which includes many of the heavyweight US technology companies, ahead.

Inflation expectations surged last week which set a rocky backdrop for the sovereign bond market

Last week saw US 5-year inflation breakevens (a proxy for inflation expectations) increase to 2.9% and 10-year breakevens move to 2.64%, setting post financial crisis records1. European expectations also rose with the ‘5-year, 5-year’ inflation expectations (5-year inflation starting in 5 years’ time, used to assess medium term expectations), rising to 2% for the euro area2. 2% may seem mild but against the context of an European Central Bank that has struggled to reach 2% in recent history, despite negative interest rates, this is impressive movement. With higher inflation expectations now incorporated into the medium-term figures, this suggests a bond market that is moving away from its pure focus on the transitory inflation narrative to a more balanced position.

The UK Budget and Spending Review is likely to contain few carrots, given the outdated fiscal data the government has chosen to use

Next week sees the Bank of England’s November policy meeting and it is widely expected that it will contain the first hike since the summer of 2018. Whilest the Bank of England have made it clear that they want to reduce some of their monetary support, there are many question marks over the future for UK fiscal impulse. This week’s 2021 Spending Review will be the Chancellor’s opportunity to set the path of government spending for this parliament and perhaps more importantly for markets, determine the balance between near-term fiscal restraint and promised spending. This week’s budget is likely to focus on the updated economic forecasts as well as the pre-announced national insurance increase and dividend tax rate hike. There are a few areas that the Chancellor could consider in order to increase the government’s tax take but most of them, such as pension reform or Capital Gains Tax hikes, would have political ramifications.

It is likely that this will be a UK budget with few sweeteners given the Chancellor has chosen to use September fiscal numbers which paint a slightly weaker picture for the UK economy. This serves three purposes, political validation for what is expected to be a tighter budget, justification for setting new fiscal rules to achieve fiscal balance, but also setting a lower bar for future performance.

Please continue to check back for our latest blog posts and updates.

Charlotte Clarke

26/10/2021

Team No Comments

Invesco – Understanding inflation expectations and why they matter

Please see below an article from Invesco which was received late Friday (22/10) afternoon and covers their views on inflation in the US:

As you can see from the above, inflation remains a hot topic. Although market consensus states that inflation is transitory, Invesco’s view is that this ‘transitory inflation’ could last for up to 3 years or more. This is something we will continue to keep an eye on and also see how this translates to UK inflationary pressures. Many of the supply chain issues are global.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

Independent Financial Adviser

25/10/2021

Team No Comments

Brooks MacDonald Daily Investment Bulletin 21/10/2021

Please see below for Brooks MacDonald’s Daily Investment Bulletin, received by us late yesterday 21/10/2021:

What has happened

 US and European equities continued their recent run of positive days with a small gain in the US leaving the index only a fraction away from its all-time high set in September. US earnings were, again, the driver of this upswing with around two-thirds of companies reporting yesterday beating expectations.

 COVID-19

 With the recent pickup in cases, headlines filtered through yesterday from across the globe. In Russia, President Putin has mandated a ‘non-working’ firebreak between the 31st October and 7th November whilst the Czech Republic has mandated the wearing of masks in indoor spaces. In New York City, municipal workers will need to show proof of vaccination to continue in their roles with the option of showing a negative test no longer available. Global governments appear to be taking one of two paths as cases increase in the northern hemisphere, either enacting restrictions now or doubling down on their vaccination/booster strategy. In the UK, weekly average cases have now risen to 45k per day with the Health Secretary yesterday urging citizens to register for vaccinations and for booster jabs ahead of the winter period.

 Inflationary pressures

 Whilst equities recorded another strong day yesterday, sovereign bonds remained under siege due to inflationary concerns. Oil prices hit another high for the year after reports from the US EIA pointed to falling inventories of both crude oil and gasoline. US 10 year inflation breakevens are now sitting at 2.6%, their highest level since 2012. Fed Speakers have been keen to push back against market expectations for interest rates, which are now running far ahead of the latest Fed dot plot from September. Fed Governor Quarles said yesterday that whilst he sees ‘significant upside risks’ to inflation, that his base case sees US inflation heading towards 2% next year. Quarles also addressed the elephant in the central bank room, saying that a demand/supply imbalance is not best addressed by curtailing demand via tighter monetary policy, describing such an approach as ‘premature’.

 What does Brooks Macdonald think  The market has fully priced in one rate hike in the US in 2022 with a second hike three-quarters priced in. The first step on the Fed’s monetary normalisation process will be the tapering of pandemic quantitative easing programmes so this will buy some time for the Fed to settle on the exact timing and pace of rate hikers, in the interim the Fed wants to avoid the market pricing in too rapid a tightening.

Please continue to utilise these blogs and expert insights to keep your own holistic view of the market up to date.

Keep safe and well

Paul Green DipFA

22/10/2021

Team No Comments

Stocks soar as US consumers splash the cash

Please see below Brewin Dolphin’s latest market summary, which was received late yesterday (20/10/2021) afternoon:

Global equities rose last week on the back of better-than[1]expected US retail sales and encouraging employment figures.

The S&P 500 and the Dow gained 1.8% and 1.6%, respectively, following a 0.7% jump in US retail sales in September and a decline in weekly jobless claims.

In Europe, the STOXX 600 surged 2.7% amid an encouraging start to the US earnings season. The FTSE 100 added 2.0% with airlines among the strongest performers after the US announced it would ease travel restrictions from 8 November.

Japan’s Nikkei 225 clawed back losses from the previous week to finish up 3.6%, as investors took comfort from new prime minister Fumio Kishida’s comments that he would not increase capital gains tax for the time being.

Last week’s market performance*

• FTSE 100: +1.95%

• S&P 500: +1.82%

• Dow: +1.58%

• Nasdaq: +2.18%

• Dax: +2.51%

• Hang Seng: +1.99%

• Shanghai Composite: -0.55%

• Nikkei: +3.64%

* Data from close on Friday 8 October to close of business on Friday 15 October.

Wall Street mixed as China GDP disappoints

Wall Street stocks gave a mixed performance on Monday (18 October) following disappointing gross domestic product (GDP) figures from China. The Dow slipped 0.1% whereas the S&P 500 and the Nasdaq gained 0.3% and 0.8%, respectively, as bond yields rose and data showed China GDP grew by 4.9% in the third quarter from a year ago, below the 5.3% growth expected by economists.

The sombre mood continued in London, where the FTSE 100 fell 0.4%. Figures from Rightmove showed average UK house prices jumped by 1.8% in October from the previous month – the biggest rise at this time of the year since 2015. On an annual basis, the average asking price is up 6.5% to £344,445. Meanwhile, the two-year gilt yield soared to its highest level since May 2019 – a sign that traders expect UK interest rates to rise soon.

The FTSE 100 was flat at the start of trading on Tuesday as investors awaited more earnings reports from the US.

US retail sales surge as prices rise

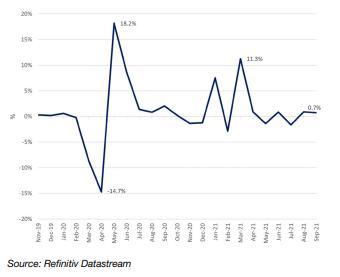
 Figures released by the Census Bureau last week showed US retail sales jumped by 0.7% in September, far better than the 0.2% decline expected by economists. Compared with a year ago, sales were up by 13.9%.

US retail sales – MoM change

 The increase came as the government ended the enhanced benefits it had been providing during the pandemic. It was thought this would depress sales, but instead spending accelerated as workers and students returned to offices and schools.

Much of the increase was driven by higher prices, as US retail sales figures are calculated according to receipts as opposed to volume. Indeed, separate data showed inflation, as measured by the consumer price index (CPI), rose by 5.4% in September from a year ago, slightly higher than the 5.3% increase expected by analysts. On a monthly basis, prices increased by 0.4%, following a 0.3% rise in August. Core CPI, which excludes food and energy, rose by 4.0% from a year ago – well above the Federal Reserve’s 2.0% target.

Meanwhile, the University of Michigan’s consumer sentiment index slipped in early October to 71.4 from a final reading of 72.8 in September, suggesting consumers remain anxious despite spending more.

UK GDP rises by 0.4%

Here in the UK, figures showed GDP grew by 0.4% in August from the previous month, as the hospitality industry benefitted from the first full month of coronavirus restrictions being lifted in England. Accommodation and food service activities were the main contributor to growth in the services sector, rising by 10.3%. This was followed by arts, entertainment and recreation, up 8.5%. Despite the increase, the Office for National Statistics (ONS) said GDP remains 0.8% below its pre-pandemic level, while consumer-facing services are 4.7% below their pre-pandemic level.

Investors were also cheered by data that showed UK employers added 207,000 staff to their payrolls last month, shortly before the end of the furlough scheme. This meant the number of payrolled employees surged to 29.2 million – the highest level since records began in 2001. However, the unemployment rate for June to August was an estimated 4.5%, higher than the 4.0% rate seen before the pandemic.

Germany’s GDP forecast slashed

Over in Europe, Germany’s GDP forecast for 2021 was slashed last week by a group of economic research institutes. The group’s biannual report said the German economy would grow by 2.4% this year, down from its previous forecast of 3.7% growth. The researchers said the reduction was driven by the ongoing impact of Covid-19 on the service sector, and continuing supply chain issues. GDP is expected to grow by 4.8% in 2022, assuming the pandemic and supply chain disruptions are resolved.

Supply chain issues are affecting the eurozone more broadly, with industrial production falling in August by 1.6% from the previous month. Eurostat said one of the steepest declines was in Germany, where output dropped by 4.1%

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

David Purcell

21st October 2021

Team No Comments

MPS Monthly Market Commentary

Please see below article received from Brooks Macdonald yesterday afternoon, which provides a succinct update on current market behaviour.

Global equities fell in September as inflationary pressures remained elevated and on further signs of a global economic slowdown. Continued anxiety about a possible bond default by Chinese property group China Evergrande also rattled markets. Major central banks, particularly the US Federal Reserve (Fed), drew closer to the point of tightening monetary policy. The news boosted the US dollar while yields on government bonds generally rose. Supply disruptions and drops in US crude stocks helped oil prices hit the highest levels in almost three years.

UK stocks declined as increasing energy costs, supply chain issues, (which led to motor fuel shortages) and worries about an economic slowdown dampened sentiment. Increasing pricing pressures – the annual inflation rate leapt to 3.2% in August from 2.0% in July – added further gloom. The Bank of England signalled that it could bring forward its plans to increase interest rates as it raised its inflation target. The UK’s second-quarter GDP growth was revised up to 5.5% from 4.8% previously, although the economy expanded by just 0.1% month on month in July.

US equities dropped on concerns about a weakening economy and moves by Democrats to raise corporate taxes. Inflation remained relatively high – consumer prices rose by 5.3% year on year in August, down slightly from 5.4% in July – further dampening the mood. The Fed turned more hawkish, with Chairman Jerome Powell hinting that the process of winding back the central bank’s asset purchases, known as ‘tapering’, could begin as early as November.

European markets were lower as worries about the economic recovery, the debt problems at Evergrande and high inflation unsettled investors. The European Central Bank said it would slow bond buying under its pandemic emergency purchasing programme over the rest of 2021. It insisted the move did not amount to tapering as it warned that the economic recovery remained nascent. The eurozone’s GDP growth over the second quarter was revised up to 2.2% from 2.0% previously.

Japanese stocks strengthened as the resignation of Prime Minister Yoshihide Suga sparked hopes that his successor would implement new fiscal stimulus measures. Former foreign minister Fumio Kishida was, by month end, expected to become the country’s new leader after winning a Liberal Democratic Party leadership contest. The continued roll-out of COVID-19 vaccinations, after a slow start compared with other developed countries, further boosted the market. Japan’s second-quarter GDP growth was revised up to 1.9%, on annualised basis, from 1.3% previously6.

Asia-Pacific equities (excluding Japan) weakened on concerns about a global economic slowdown. In China, worries about a weakening economy and Evergrande’s debt problems and power shortages (which shut a number of factories) dragged down stocks. The prospect of a slowdown in China also hurt Taiwan’s market. South Korean stocks declined as technology companies faced the threat of tightening regulations, sparking a sell-off in the economically important sector. Rises in COVID-19 infections hurt investor confidence in Australia and Singapore.

Emerging markets were down, overall, as the strengthening US dollar weighed on sentiment. India’s market remained strong, however, as the continued roll-out of COVID-19 vaccinations underpinned confidence in the economy’s recovery. Increased buying by foreign equity investors added further support. Brazilian shares fell sharply as disaffection over the leadership of President Jair Bolsonaro – and his defiance in the face of a number of scandals – increased political tensions. Russia’s market made gains as it benefitted from increases in energy commodity prices, while Turkish stocks slumped as the central bank surprised investors with an interest rate cut, despite concerns about soaring inflation. South African equities came under pressure from the stronger US dollar.

Yields on core government bond markets generally increased. The yield on US benchmark 10-year Treasuries rose (prices fell, reflecting their inverse relationship) as the Fed moved closer to tightening monetary policy, sparking a sell-off towards month end. The yields on UK 10-year gilts and German 10-year bunds also gained, although the latter remained in negative territory. In the corporate debt market, US investment-grade and high-yield spreads tightened.

We will continue to publish relevant content as we approach Halloween and edge nearer to the festive season.

Stay safe.

Chloe

20/10/2021

Team No Comments

Quid Game – Legal & General’s Asset Allocation team’s key beliefs

Please see the below article received by Legal & General late yesterday afternoon:

Quid Game

The Bank of England has signalled it’s getting ready to move, although battle lines were drawn last week as Silvana Tenreyro and Catherine Mann, both members of the MPC, voiced opinions against a rate hike. Nonetheless, there is an overall hawkish tone coming from Threadneedle Street. That has clearly been reflected in rates, with gilt yields moving higher even more aggressively than their international counterparts – both at the short end and further out.

The same cannot be said for the pound. Although interest-rate differentials are low today, such changes in expectations usually drive some currency movement, too. But the energy crisis, rising inflation and a lower growth outlook have kept sterling at bay; across the pond, rising yields and a risk-off environment have helped the US dollar dominate virtually all other currencies. The enthusiasm for dollars is also reflected in various measures of investor sentiment and positioning.

With supportive valuations, we think the combination of market dynamics and valuation warrants a trade, so we are moving to a more preferential view on the pound against the dollar. To diversify the idiosyncratic risks from picking one currency, we also have positive views on the Australian dollar and euro against the US dollar. Even though the fundamentals for each currency look a little different, they share the common factor of light positioning versus the greenback.

The Fed’s Gambit

Last week’s US CPI print of 0.2% confirms our view that we’re reaching the middle-game for the current inflationary spike. With the initial spike from the reopening of the economy potentially winding down, the Federal Reserve (Fed) is much more focused on the breadth of the current shock. In that regard, the 0.5% jump in median CPI is concerning. Some broader measures are already elevated and, if the others follow suit, that could bring forward Fed action. Our economists and the markets expect the first rate hike in late 2022, though there’s a strong consensus that the risks are skewed heavily towards an earlier lift-off, rather than a delay.

The Fed is gambling that labour market participation will pick up, providing a release valve for wage pressure and limiting the risk that consumers’ rising inflation expectations lead to higher pay and ultimately into an ugly endgame where rate hikes are needed to stop price rises from spiralling out of control. The growing risk is that there has been a negative structural shock to labour supply through a combination of retirements and people re-evaluating their work/life balance. With unemployment down to 4.8%, despite disappointing payroll data, we would need to see a rapid return of workers to alleviate this concern.

Considering the above, we are moving back to a negative view on US rates after a few weeks on the sidelines. A challenge to this position is that investor sentiment indicators point to a widespread consensus short view on rates, though not an extreme one.

As regular readers know, we don’t like to join the herd too often. We lean against another widely held position by taking a short US inflation view against the market’s overall long predisposition; if necessary, then we’d expect the Fed to act, reducing the risk of a prolonged spike in inflation pricing 5-10 years in the future. Higher today, lower tomorrow.

Peso Blinders

There are several currencies known as the peso in the Americas, and we are revisiting our stance on Chile’s versus its Colombian counterpart. We are bullish on the Chilean peso and, where possible in portfolios, short the Colombian peso.

The recent performance of the Chilean peso has been poor, but with reason in our view; the Chilean economy is overheating. Loose fiscal and monetary policy has caused the current account to deteriorate, inflation to rise, and the peso to underperform. Chile’s recent central-bank action to hike the policy rate by 1.25% is an important signal that it is keen not to see further currency weakness. Politics in Chile is messy, but it’s the same in Colombia and the whole continent has been leaning left in recent years.

Finally, while not a driver of the trade, Chile is massive exporter of copper, which could see a tailwind in case the metal’s price rises on the back of the global decarbonisation drive.

Combining these factors gives us confidence to take a position. The Chilean peso adds risk to our portfolios but, combined with a trade against Colombia, we believe it becomes more of a diversifier.

Please continue to check back for a range of blog content from us and from some of the world’s leading fund management houses.

Andrew Lloyd DipPFS

19/10/2021

Team No Comments

A.J. Bell – Sustainable investment trends – performance, flows and greenwashing

Please see below an article from A.J. Bell which was received yesterday (17/10) and covers their views on Environmental, Social and (Corporate) Governance investing:

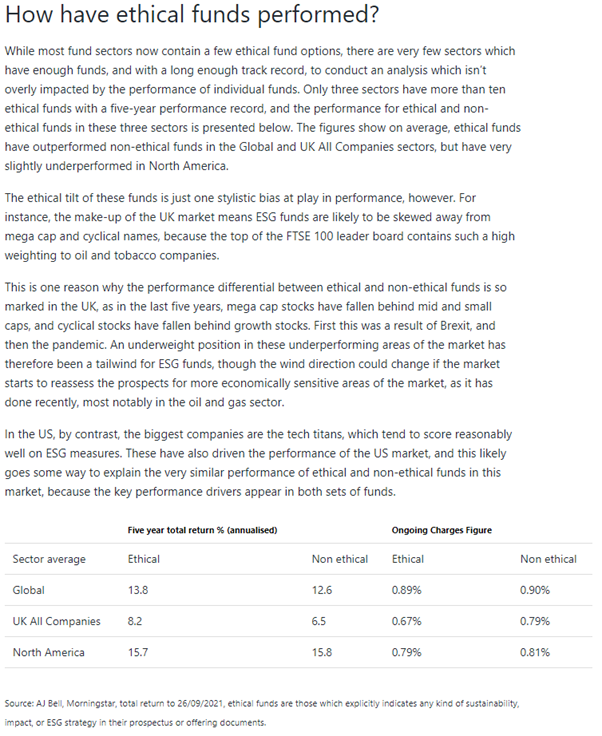
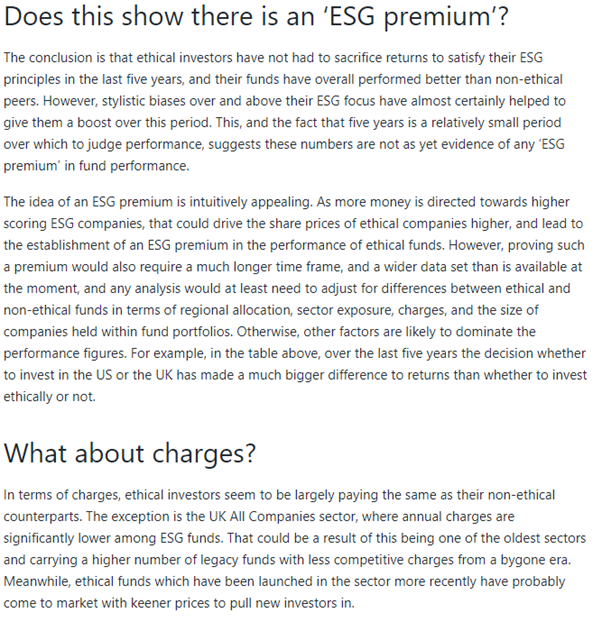
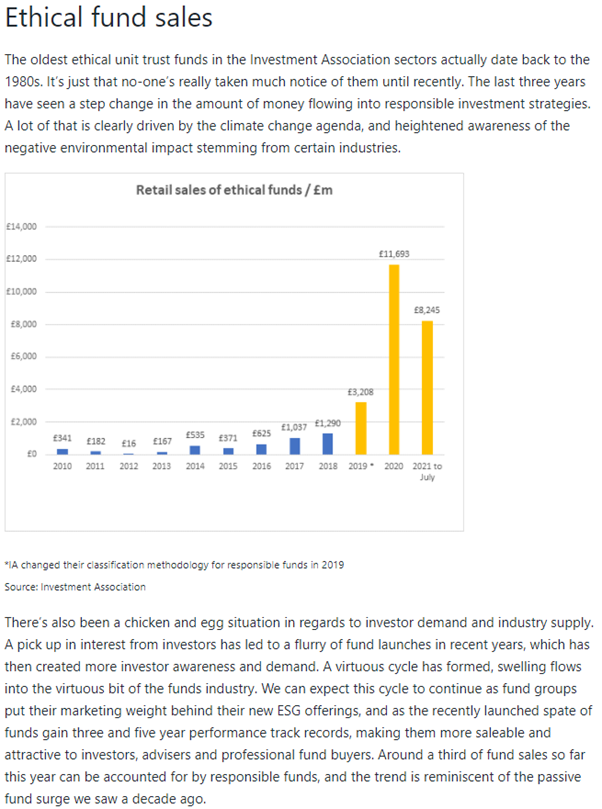
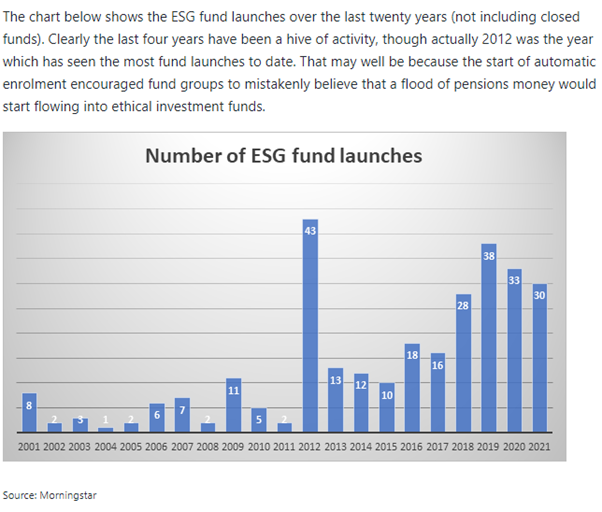
As you can see from the above article, ESG investing is certainly becoming more mainstream, and this theme ties into what we are seeing and hearing from other fund management companies too.

One question I am most typically asked by my clients when we discuss ESG investing is, ‘Will I have to compromise on investment returns to be an ethical investor?’ and I believe the above article demonstrates that this is not the case.

It has been suggested that in the future, ESG investing may actually become the default investment offering with investors specifically having to ‘opt out’ of this type of investment strategy.

ESG investing is certainly an area to keep an eye on in the future. We believe it is a great option.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

Independent Financial Adviser

18/10/2021