Please see below, Tatton’s ‘Monday Digest’ providing their analysis on market movements and economic events during the last week. Received today – 31/07/2023.
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see below, the ‘Daily Update’ from EPIC Investment Partners for a brief analysis of the key news from markets and economies across the world. Received today – 28/07/2023
Earlier this week, we heard that eurozone banks reported a sharp fall in corporate loan demand, which has fallen to its lowest level on record (since the survey started in 2003). The ECB’s quarterly survey of banks also showed a striking fall in household loan demand and tightening financial conditions, which highlight the impact increasing borrowing costs have had on the eurozone economy. Despite this, the ECB continued on its tightening path, with inflation being the main priority.
As was well priced in, the ECB increased rates by 25bps, to 3.75% on the deposit rate, and left the door open for further hikes. In a statement, the central bank noted that although inflation has been declining, it will likely remain “too high for too long”. Headline eurozone inflation fell to 5.5% in June, from 6.1% previously, however, remains way above the 2% target. There was no forward guidance given, the ECB will maintain its data dependence approach in “determining the appropriate level and duration of restriction”. The statement also highlighted the effects of past tightening as increasingly dampening demand across the region.
In a surprise move, the ECB “set the remuneration of minimum reserves at 0%,” to ensure “the full pass-through of interest rate decisions to money markets”. Adding that “it will improve the efficiency of monetary policy by reducing the overall amount of interest that needs to be paid on reserves in order to implement the appropriate stance.”
Later, ECB President Lagarde repeated: “We want to break the back of inflation”. She also reiterated the data dependence approach, adding that the ECB is unlikely to give forward guidance. She said the ECB has an “open mind” going into the September meeting, adding “We might hike, we might hold.” She came across slightly dovish as she discussed the bloc’s economic outlook and the changing drivers of inflation; namely wage growth and profit margins.
As with the Fed, the ECB’s next meeting is in September, which will allow it a natural pause and lots of data to plan its next steps. Unlike the US, however, inflation in the eurozone is falling much slower, with some calling for a 2% target to be hit at the earliest in 2025. Moreover, the economy is not holding up as well; business activity (measured by the S&P Global PMIs) shrank more than expected, with only services in expansion in July. Prelim. S&P Global PMI readings in key economies (e.g., France) are well in contraction, and the manufacturing gauge in Germany fell to 38.8, with the composite reading dropping into contraction.
The eurozone’s official Q2’23 growth and inflation figures are due on Monday, expected at 0.1%qoq and 5.2%yoy (prelim. for July), respectively. Earlier this week, the IMF said it expected the eurozone could grow by 0.9% this year. However, this factors in a recession in Germany, where the GDP is expected to contract by 0.3%. The Fund noted that Italy will grow at a faster rate than the bloc’s two largest economies, Germany and France.
Lastly, it would be remiss of us to not highlight the new Governor of the BoJ, Kazuo Ueda’s surprise tweak to yield curve control (YCC) flexibility. The central bank will allow 10-year benchmark yields to have a 50bp tolerance, as reference points rather than “rigid limits”. Thus, the central bank will buy the 10-year at 1% each day instead of 0.5%. The BoJ upgraded its forecasts for inflation for this year, to 2.5% (from 1.8%), then falling to 1.9% (from 2%). Having held short-term interest rates at -0.1%, Japan is the only country left with negative interest rates.
Please continue to check our blog content for advice and planning news from us and leading investment management houses.
Please see below an article received from Evelyn Partners earlier this morning (27/07/2023), which details their thoughts on yesterday’s interest rate decision that was announced by the Fed:
What happened?
After pausing in June, the FOMC raised its upper bound interest rate by 25bps to 5.50%, which is broadly in line with what the market had expected, and is at its highest level for 22 years.
In the following press conference, Fed Chair Powell did leave open the possibility of further hikes to return inflation to its 2% goal. This means the next FOMC on 20 September is a “live” meeting. As of today, the Fed Futures market is not expecting a full 25bps rate hike in September.
What does it mean?
Unless there is a material rebound in inflation, the Fed is set to pause on interest rates from here, with the next move likely to be down sometime in 2024. Importantly, favourable macro data over the last few months should leave the hawks at the FOMC in the minority, reducing the risk that the Fed goes on to overtighten on interest rates.
First, the June CPI inflation report showed that underlying price pressures continue to subside. All three of the main core inflation categories that the Fed is focusing on, such as housing, core services ex shelter and core goods, are all trending down on an annual basis. Consumer surveys of inflation expectations are also coming down, which will be encouraging for the Fed in its efforts to prevent inflation becoming entrenched in the economy.
Second, the jobs market is cooling. At the headline level, June non-farm payrolls came in at 209k, its lowest increase since the recovery from the pandemic. Importantly, firms are cutting back on job vacancies and this is reducing the number of workers willing to quit jobs to seek higher paying opportunities. In effect, the Fed appears to have reduced the risk of a price-wage spiral that would make its job to bring down inflation more difficult. The next key data point to determine the whether wage rates have indeed peaked is the second quarter Employment Cost Index (a comprehensive measure of wages and benefits) due on the 28 July.
Third, the FOMC will be cognizant of the impact of monetary tightening on the financial system. Back in March, the failure of Silicon Valley Bank (SVB), the 16th largest bank in the US, raised concerns of systemic problems appearing, like those suffered during the Global Financial Crisis (GFC) in 2008. However, those fears proved to be unfounded as SVB was more of a manageable idiosyncratic risk. Nevertheless, further monetary tightening could potentially lead to rising debt default rates in the private sector that leads to material financial and banking sector stress.
Bottom Line
With the Fed set to pause on interest rates, it provides an opportunity for equities to continue to broaden out from the Artificial Intelligence-led rally.
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see the below article from Brewin Dolphin commenting on the latest stock market movements. Received late yesterday 25/07/2023.
Stocks rise as UK inflation eases
Most US and European indices rose last week as slowing inflation raised hopes that interest rate hikes could be nearing an end.
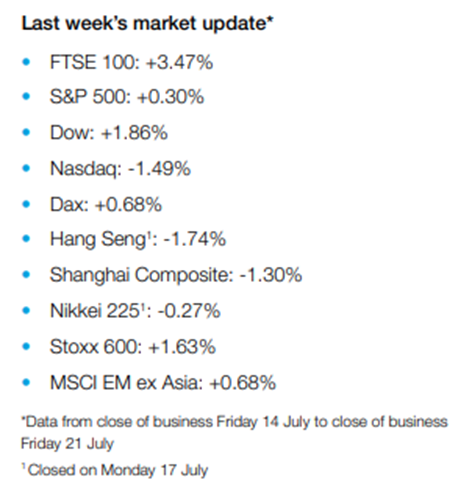
The FTSE 100 surged 3.5% as UK inflation eased more than expected, triggering a decline in the pound versus the dollar (around 70% of FTSE 100 company revenues come from overseas). The Stoxx 600 and Germany’s Dax climbed 1.6% and 0.7%, respectively, after two hawkish European central bankers appeared to moderate their stance on future rate hikes.
In the US, the Dow enjoyed its tenth consecutive day of gains on Friday – its longest winning streak since August 2017. The Dow ended the week up 1.9%, boosted by comments from Treasury secretary Janet Yellen that the risk of a US recession had fallen. Disappointing technology sector earnings weighed on the Nasdaq, which lost 1.5%. In Asia, the Shanghai Composite and the Hang Seng fell 1.3% and 1.7%, respectively, after figures showed China’s gross domestic product (GDP) grew by just 0.8% in the second quarter, down from the first quarter’s 2.2% expansion.
Investors shrug off weak PMIs
Stocks made small gains on Monday (24 July) as investors digested the latest purchasing managers’ indices (PMIs) for the US, eurozone and UK. The Dow extended its winning streak, advancing 0.5%, while the S&P 500 and the Nasdaq gained 0.4% and 0.2%, respectively. S&P Global’s flash PMI for the US showed business activity slowed to a five-month low in July, dragged down by weaker services sector growth. Manufacturing remained in contraction territory, but rose from 46.3 in June to a forecast-beating 49.0 in July (a reading below 50.0 indicates a contraction).
The Stoxx 600 and the FTSE 100 managed to shrug off weak PMIs to edge up 0.1% and 0.2%, respectively, on Monday. S&P Global’s flash PMI for the eurozone showed business output fell at the fastest rate for eight months in July. The services sub-index fell to 51.1, its lowest in six months, while the manufacturing output index plummeted to 42.9, the lowest in more than three years. S&P Global’s PMI for the UK was also disappointing, with manufacturing and services sector readings both coming in below expectations at 45.0 and 51.5, respectively.
Investors will now be looking ahead to the Federal Reserve’s two-day policy meeting on 25-26 July and the European Central Bank’s policy meeting on 27 July.
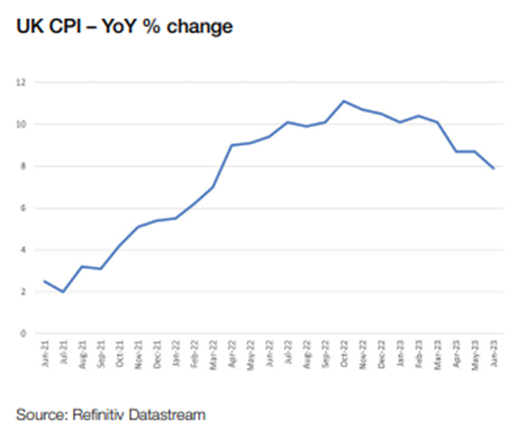
UK inflation rate falls to 7.9%
Last week saw the UK’s Office for National Statistics publish the closely watched consumer price index (CPI) report. The headline rate of inflation eased to 7.9% year[1]on-year in June, down from 8.7% in May and lower than expected. This was mainly driven by a 22.7% year-on[1]year decline in motor fuel prices. Food and drink inflation eased to 17.4% in June from 18.4% in May. Core inflation, which excludes energy, food, alcohol and tobacco, slowed to 6.9% in June after hitting a 30-year high of 7.1% in May.
The report has raised hopes that the Bank of England will be less aggressive when raising interest rates over the coming months. Markets now expect rates to peak at 5.8% this cycle, down from previous forecasts of 6.5%. The peak is expected to be reached in February 2024.
US retail sales rise modestly
In the US, retail sales rose by 0.2% in June from the previous month, while data for May was revised higher to show a 0.5% increase in sales. The data suggests sales have remained resilient despite interest rate hikes, although the rise was lower than the 0.5% increase forecast by economists in a Reuters poll. Online sales surged by 1.9%, the most in six months, whereas receipts at service stations and building material stores declined.
Core retail sales, which exclude automobiles, gasoline, building materials and food services, rose by a healthy 0.6% in June following an upwardly revised 0.5% increase in May. Core retail sales are an important indicator of consumer spending, which accounts for more than two[1]thirds of US GDP
Japan raises inflation forecast
Over in Japan, the government raised its inflation forecast for the current fiscal year to 2.6%, up from its January prediction of 1.7%. The announcement came a week before the Bank of Japan’s (BoJ) policy meeting on 27 July. Markets will be keen to see whether the revised forecast will result in the bank raising its own forecast and, in turn, tweaking its ultra-loose monetary policy. Latest figures show headline and core inflation both rose to 3.3% in June from 3.2% in May. Despite inflation persistently exceeding the 2% target, the BoJ has so far defended its stance. At the beginning of last week, governor Kazuo Ueda told a news conference that the BoJ would only change its yield curve control policy if there was a change in its inflation expectations.
Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.
Please see below article received from Brooks Macdonald this morning, which reminds readers to remain invested for long-term growth.
Cash savers are currently enjoying the highest returns in nearly two decades, with some popular savings accounts offering fixed-term deposit rates over 5% p.a. After a prolonged period of virtually zero return on cash, rates today are multiple times higher compared to previous years, and investors are naturally keen to put more into cash than they have done so previously. So, are investors right to prioritise cash? To answer this question, we examine the role of cash in the context of inflation, investment horizon and opportunity cost of reinvestment. Despite the current attractiveness of cash deposit rates, cash may not be the best place to be for long-term investors.
Cash is not inflation-proof
Cash offers certainty only in its nominal value but not its real value, which is measured by the resilience of its purchasing power over time. Inflation erodes the purchasing power of any asset. While cash may retain its real value to some extent during periods of low inflation, its purchasing power rapidly diminishes during times of high inflation. In fact, in the past two decades, there were only three isolated years where cash managed to outperform inflation and retain its purchasing power. Even during the era of subdued inflation that preceded the COVID pandemic, deposit rates languished at levels even lower. Despite the recent surge in cash rates, they still fall short of the prevailing higher inflation rates. Consequently, relying solely on cash rates often proves inadequate in terms of providing comprehensive real value protection.
A diversified portfolio could be a better option for long-term investors
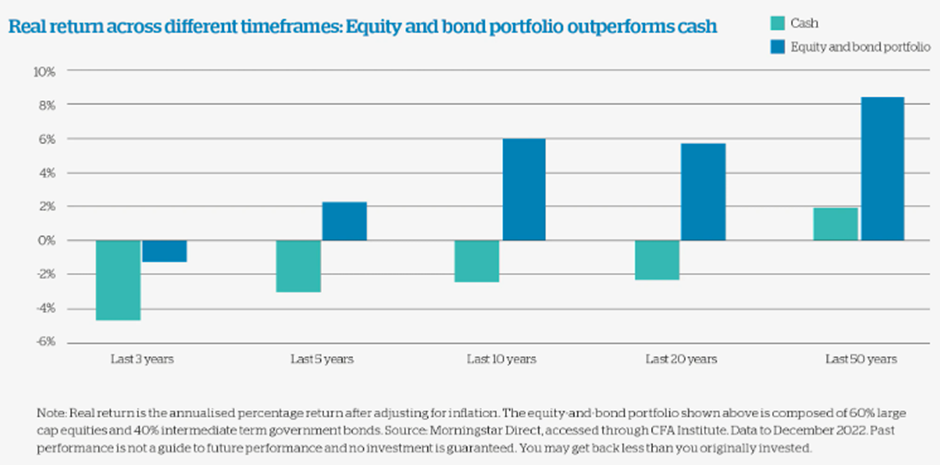
It is important to examine the case for cash in comparison to other investment instruments such as equities and bonds. For investors with long-term goals, a diversified 60% equities and 40% bonds portfolio can hold greater potential for generating real returns. If we examine the excess returns of cash vs. an equities and bonds portfolio across varying time horizons, we see that over the past 3, 5, 10 and 20 years, cash savings have delivered negative real returns, thereby diminishing the purchasing power of depositors. While cash managed to retain a level of real value over a 50-year period which will incorporate many different economic cycles, it is still lower than the returns generated by the equities and bonds portfolio. By contrast, the equities and bonds portfolio has consistently delivered returns that outpaced inflation across timeframes of 5 to 50 years, regardless of the prevailing macroeconomic conditions.
Hidden costs of fixed-term deposits
Investors attracted by the higher rates offered by fixed-term deposits are often locked in for a period of time. One key consideration for depositors in these situations is reinvestment risk, which is the risk of earning lower returns when choosing a new investment after their original fixed-term investment has expired. Once the fixed rate reaches its end, they must either renew at potentially lower rates or explore alternative investment options. However, the financial landscape at that time could differ significantly, and the investor could have missed attractive entry points in equity and bond markets. Historical analysis also reveals that high deposit rates rarely persist over an extended period. Looking at past patterns, in the five previous hiking cycles, the Bank of England typically maintained peak interest rates for an average of 9 months between its last hike and its first rate cut. It is unlikely for higher rates to endure, and investors risk sacrificing long-term opportunities for the allure of short-term ‘guaranteed’ gains.
What does it mean for investors?
While current cash deposit rates may be attractive, investors should carefully evaluate the role of cash in light of inflation, investment horizon, and reinvestment risks. So, whilst holding cash can be a useful tool for investors with a very short investment horizon, a diversified investment portfolio could provide better returns for investors seeking to preserve and grow their wealth over the long term.
Please check in again with us soon for further relevant content and news.
Please find below the Tatton ‘Monday Digest’ which provides an overview of global economic news from the past week. Received this morning – 24/07/2023
Another inflation driver turns over
Last week, markets yet again revolved around inflation, wages and profit margins. In the UK, we finally received some of the positive inflation news that has been stoking US markets. June’s consumer price index (CPI) decline to 7.9% year-on-year could be a watershed moment, giving the Bank of England (BoE) the green light to raise interest rates only by another 0.25% in August. To put this into context, last Tuesday markets were still pricing in a 0.50% hike.
The better-than-expected inflation news helped UK equity markets to storm higher on the week, egged-on by sharp falls in medium-term gilt yields (and parallel gilts price rises!). Sterling retreated from its recent highs against the US dollar, but UK stocks closed the week leading the rest of the world higher, even in UK sterling-based terms.
On the other side of the Atlantic, the US second quarter earnings season has showed that margins are finally coming under pressure across the board. Tesla withdrew its previous statement that margins would “remain among the highest in the industry,” and a cautious commentary left the door open for another round of price cuts soon. It’s not just Tesla, however, and margins have weakened substantially in other integral areas like trucking and freight (which we discuss in greater detail below). We have become used to the UK headlines about strikes, but if the US turns out to have a more entrenched inflation path because labour relations have worsened it may face the same worries as we have faced in the UK.
As the earnings season progresses, we appear to be in a new phase, where companies have lost pricing power but sales should hold up because they are not cutting labour aggressively. We will be listening very closely to what the US Federal Reserve tells us after this Wednesday’s Federal Open Market Committee meeting.
Chinese property developers are on their own
Since property giant Evergrande defaulted on its debt two years ago, the world’s most leveraged property developer has been in a lengthy restructuring process which, for the most part, has looked like artificial life support rather than a cure. Its slow-motion collapse has been a major part of China’s property crisis, and is a substantial drag on growth for the world’s second-largest economy. None of the property developer’s problems should surprise us anymore, and yet, its latest announcements cannot help but make collective eyes water. In just two years, Evergrande made losses of $81 billion. The incredible losses are driven mostly by asset depreciation, thanks to sinking values in China’s building industry. Analysts have suggested that the fact such dire figures are now being released shows an acceptance the hoped-for improvement is not coming anytime soon.
The Chinese government has seemed surprisingly uninterested in arresting the decline. The last few months have been horrendous for the ailing property sector, but policy support has been minimal. If Beijing does let large developers go bankrupt, equity and foreign bondholders will be the least protected. The distress also has big implications for China’s banks – which are among the largest financial institutions in the world. Developers’ financial struggles seriously impact banks, which will inevitably mean tighter lending conditions for everyone. That could well dampen any help that comes from the authorities.
China’s hopes of a post-Covid boom have well and truly evaporated, pushing down asset values which rallied into the start of this year. The property developers’ financial problems are proving contagious as they are weighing down on consumer and business sentiment. As such, they have been at the heart of the weak post-lockdown rebound in Chinese consumption and that has led to rising savings rates and even weaker private sector activity. This is not to say that Beijing is against growth – both words and actions suggest the opposite. However, it wants growth in productive areas and property has become unproductive. Developers may already be resigned to being given nothing more than life support.
Freight not great
There are serious questions over the health of the US freight industry at the moment. Relations between companies, drivers and other workers have become highly antagonistic, just as revenues have been falling. UPS, the world’s biggest courier, has been in the spotlight due to its negotiations with the Teamsters Union, with the two sides failing to agree wage increases for part-time workers, who make up roughly half of UPS’s unionised workforce in the US. UPS isn’t the only company under pressure. Yellow Corporation, the parent company of Holland and Yellow Freight, announced it is $50 million short of the pension contributions it owes, and remains in severe financial distress.
Yellow’s likely demise is a symbol of America’s freight recession. Early in the pandemic, the surge in transport demand created huge capacity expansion in trucking, only for companies to find themselves short of drivers. Workers’ increased pricing power meant significantly higher wage bills, eating into profit margins and worsening financial metrics. When the post-Covid boom dwindled, revenues fell sharply and firms were caught out.
Some of the bad news for freight companies is good news for US consumers. The ongoing freight recession means lower costs, while the inventory situation could also mean the easing of goods prices. This would help inflation-bruised consumers and support demand but, as ever, this has to be balanced against the increased risk of defaults. A wave of defaults hurts everyone, making finances tighter than they already are. This is not happening yet, but is very much a live possibility for the freight sector.
Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
This has been cut and pasted from Invesco’s mid-year investment outlook received this morning, 21/07/2023:
In an effort to curtail the worst inflation in decades, Western developed central banks have moved aggressively to tighten monetary policy. This has helped exert downward pressure on inflation but has also brought about a meaningful slowdown in global growth and some financial accidents, including several US regional bank failures.
However, against this backdrop, we see resilient domestic demand in many economies, especially in services. Our base case anticipates a relatively brief and shallow economic slowdown as inflation continues to moderate and monetary policy tightening nears an end, followed by a recovery.
We call this a bumpy landing because there will continue to be some economic damage in this scenario. We believe there is the possibility of a downside scenario – a “hard landing” – in which global growth is hit harder, with a recession first in the US, which then cascades into other economies.
We also believe there is the possibility of an upside scenario – a “smooth landing” – in which monetary policy impacts growth less than expected and the global economy is relatively unscathed. In the US, we believe rate hikes are ending, and US inflation will continue to fall significantly, albeit imperfectly.
While discussion of a recession in the US is now commonplace, we continue to believe the US is likely to avoid a substantial broadbased recession. Instead, we expect some weakness in the second half of this year as policymakers accomplish a bumpy landing, but we anticipate activity will nevertheless remain relatively resilient.
As we enter 2024, we expect a more positive growth outlook to unfold as the economy recovers. In our view, the eurozone and UK are likely to follow a pattern similar to the US, but with a lag.
A variety of forces have helped sustain European economic momentum so far in 2023, but we expect tightening financial conditions to weigh on credit growth over time, helping to reduce inflationary pressures but also causing a significant economic slowdown.
In contrast with many major developed market economies, China is in a markedly different place in its cycle. The relaxation of COVID-19 restrictions has driven a meaningful though uneven recovery. The reopening is largely benefiting the services component of the economy while slowing growth momentum globally has meant weaker-than-hoped manufacturing activity.
Nevertheless, China remains a bright spot with subdued inflation and a robust growth outlook. We expect continued accommodation from the People’s Bank of China (PBoC) through the rest of 2023.
In short, we believe we are at a policy peak, that disinflation is underway, and that a relatively brief global economic slowdown is occurring, but markets are likely to soon look past this episode and begin to discount a future economic recovery.
Comment
For circa 40 months conditions have been challenging with volatility ongoing, and for the last couple of years markets have really just traded sideways.
It will be good to see inflation coming under control in the US, and an economic recovery. China should help too, lifting the Asia region, and in turn, both the US and China aiding the economic recovery globally.
2024 will hopefully be a better year for invested assets.
Please see the below technical update article from LV:
Over the years, increasing attention has been given to the fact that men historically earn more than women – the ‘gender pay gap’ and how to close or narrow this gap.
Today, public and private sector employers with 250 or more employees are required to annually publish data on the gender pay gap within their organisations.
Over time, the gender pay gap has been shrinking. In fact, recent data shows little difference in median hourly pay for male and female full-time employees aged in their 20s and 30s, but a more substantial gap emerges among full-time employees aged 40 and over.
The reasons for the gender pay gap are complicated. However, parenthood is a major factor – the gap between male and female hourly earnings grows gradually but steadily in the years after parents have their first child.
This difference in earnings across working life has also lead to a ‘gender pensions gap’. With lower earnings, more gaps in work history and the pay gap being more pronounced in the past, many women retiring today have significantly less pension wealth than their male counterparts.
On 5 June 2023, the Government published its first report on the gender pensions gap. This confirmed a 35% gap in private pension wealth between men and women who are at or approaching normal minimum pension age, albeit the gap is smaller at 32% for those who are eligible for Automatic Enrolment.
Potential pitfalls and planning points
There are a number of steps that can help protect the future pensions of those who are working part time or have taken time out of paid work to care for others.
Maternity leave – When maternity leave (or shared parental leave) is taken, it’s important to understand what will happen to pension contributions and consider whether there is any scope to top these up.
Employee contributions are normally deducted as a percentage of pay. As pay will usually be reduced, any employee contributions will be paid at the same percentage as before, but based on the lower income. However, employer pension contributions are based on the employee’s normal salary which he or she would have been paid when they were still at work.
Note that where salary sacrifice is used, the member’s salary has been exchanged for equivalent employer contributions. This means that for a salary sacrifice arrangement, all contributions are technically employer contributions and therefore should normally remain at their prior level during the leave period and should not be reduced at all.
Contributions for a lower earning partner – Where one partner in a couple stops working or earns less, the higher earner can make tax relievable pension contributions on their behalf. This may offer tax advantages in retirement, especially where the lower earner has less overall pension wealth and is likely to be a lower tax payer in retirement.
Tax relievable pension contributions can be made up to the higher of £3,600 (£2,880 net) and a scheme members relevant UK earnings each year. However, other factors such as the amount of tax relief available to each partner and availability of matching employer contributions will need to be taken into account.
Incorrect NI records – Where someone claimed Child Benefit before May 2000 and did not provide their National Insurance Number on the claim, their National Insurance record may not show the correct number of qualifying years for the state pension – Women in their 60s and 70s are most likely to be affected.
The Department for Work and Pensions (DWP) and HM Revenue and Customs (HMRC) are working to find people affected and correct their records so they receive the correct amount of State Pension. Further information for those who may be affected can be found here.
Claiming child benefittoday – For households where one partner earns more than £50,000, the ‘high income child benefit charge’ becomes payable. Once earnings reach £60,000, the tax is equal to any child benefit claimed, so it may seem pointless to claim child benefit.
However, where someone has taken time out of work to look after children, they should still always make a child benefit claim to ensure they get NI credits (35 years’ worth are needed for a full state pension). As part of the application process, it is possible to opt out of actually receiving any payment so as to avoid the tax charge (as highlighted below):
Voluntary NI contributions – Where someone hasn’t a full National Insurance (NI) record, they may not qualify for certain benefits or a full state pension. Where someone has NI gaps within the past 6 tax years, they can make voluntary contributions to make up these gaps.
Furthermore, for men born after 5 April 1951 and women born after 5 April 1953, there is a temporary extended deadline (until 5 April 2025) allowing for voluntary contributions to be made to make up gaps in NI records between tax years April 2006 and April 2016.
Comment
The implications of the gender pension gap affect not just women and can cause financial implications for the whole household as individuals approach retirement.
Having awareness of the factors mentioned above can enable entitlement to a full state pension and help ensure gaps in work history do not lead to financial hardship in retirement.
This is an interesting article as this is a real area of advice that needs addressing and something we come across often.
Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.
Please see the below article from Brewin Dolphin commenting on the latest stock market movements. Received 18/07/2023.
All major indices finished in the green in a week that saw inflation and producer prices falling in the US. The UK’s FTSE 100 and pan-European Stoxx 600 rose by 2.2% and 2.8% respectively on the back of the positive data, while over in the US, the S&P 500 grew 2.2%, the Dow rose by 1.7% and the Nasdaq added 3.1%.
In Asia, the Shanghai Composite added 1.0% as China extended policies to help bolster its struggling property market. The measures encourage financial institutions to extend loans and adjust repayment arrangements for real estate companies in order to promote completion and delivery of pre-sold housing projects.
Hong Kong’s Hang Seng added 5.1% while Japan’s Nikkei 225 added a more modest 0.6% amid speculation the Bank of Japan may raise its ten-year yield ceiling to 1% later this month.
Last week’s market update*
• FTSE 100: +2.21%
• S&P 500: +2.17%
• Dow: +1.66%
• Nasdaq: +3.13%
• Dax: +2.76%
• Hang Seng: +5.05%
• Shanghai Composite: +1.06%
• Nikkei 225: +0.63%
• Stoxx 600: +2.75%
• MSCI EM ex Asia: +3.15%
*Data from close of business Friday 7 July to close of business Friday 14 July
Markets dampened by Chinese data
Markets in the UK and China ended in the red on Monday (17 July) following disappointing economic data, including lower-than-expected second quarter GDP growth. China’s GDP grew to 6.3% year-on-year in Q2, compared to a forecasted 7.3%. The FTSE 100 lost 0.4% while the Shanghai Composite dropped 0.9%. Japan’s Nikkei 225 was closed Monday due to a public holiday, and Hong Kong’s Hang Seng was closed due to a typhoon.
Over in the US, indices closed in the green, as the anticipation of US earnings reports and retail sales data this week boosted investor sentiment. The Dow Jones added 0.2% for its sixth consecutive day, while the S&P 500 grew 0.4% and tech-heavy Nasdaq increased 0.9%.
The average UK property price has fallen by an average 0.2% (£905) this month to £371,907, Rightmove’s House Price Index shows. The decline is attributed to rising mortgage costs and buyer affordability constraints. The average interest rate on Rightmove’s mortgage tracker is now 5.69% for an 85% loan-to-value five-year-fixed mortgage. However, demand is still resilient and 3% higher than in 2019, despite the number of properties for sale being 12% lower than four years ago.
US inflation cools
US inflation rose by an annualised 3% in June, the smallest 12-month increase in over two years, according to figures from the US Bureau of Labor Statistics. This is an improvement from the 4% measured in May, and slightly below the market’s expected 3.1%.
On a monthly basis, the US headline Consumer Price Index (CPI) rose by 0.2% in June, up from 0.1% in May. The rise was driven primarily by the index for shelter, which contributed over 70% of the increase.
Core CPI, which includes all items except food and energy, rose 0.2% in June, the smallest monthly increase since August 2021. On an annualised basis, core CPI rose by 4.8%, driven largely by the shelter index, which accounted for two thirds of the total increase.
In another sign of cooling inflation, the US Producer Price Index (PPI) for final demand rose by a better[1]than-expected 0.1% in June, according to the Labor Department. Economists had predicted a 0.2% increase. The increase was primarily driven by a 0.2% rise in the final demand services index, while prices for final demand goods were unchanged. On an annualised basis, the index advanced 0.1%.
Core PPI – excluding food, energy, and trade services – rose by 0.1% in June after remaining flat in May. On an annualised basis, prices rose 2.6%.
Although inflation has eased, many economists still expect the Federal Reserve to raise interest rates by 25 basis points on 26 July. The Fed held rates last month, but policymakers have indicated there may be a further rise of up to 0.5 percentage points before the end of the year.
UK economy shrinks
UK gross domestic product (GDP) is estimated to have fallen by 0.1% in May, after growth of 0.2% in April, according to the Office of National Statistics.
Production output and the construction sector fell by 0.6% and 0.2% respectively in May, while services output remained flat.
The additional bank holiday in early May for the coronation of King Charles III was cited as a reason for reduced output in manufacturing and construction. The bank holiday benefitted industries in the arts, entertainment and recreation, while sentiment in accommodation and the food services sector was mixed, with reports of both increased and reduced output.
Strikes in healthcare, the rail network, education and the civil service were also reported to have had an impact on results.
The market is expecting the Bank of England to raise interest rates again next month in an effort to stifle inflation.
The pound reached a new 15-month high following last week’s GDP report, rising to $1.30 against the dollar for the first time since April 2022. The pound has gained almost 8% on the dollar so far this year.
Germany reduces dependence on China
Germany announced it will reduce its dependence on China for supply chains and export markets. Sectors impacted include medicine, lithium batteries used in electric cars, and elements used in chipmaking. China continues to be Germany’s main trading partner, with goods worth almost €300 billion exchanged between the countries in 2022.
Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.