Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management detailing their views on global economic news from the past week.

Overview: Summer markets lukewarm on good news

On the face of it, last week contained many of the positive headlines  market optimists had been waiting for, but the response to those headlines received was tepid at best. On Thursday, the US Bureau of Labor Statistics released its consumer price index (CPI) inflation data for July, and it was relatively benign. In particular, the core CPI measure (with food and energy taken out) was +0.16% for the month, the same as in June. For the two months, annualised core CPI is now running below 2%, at +1.92%. Commentators reiterated the June narrative: that the US Federal Reserve (Fed) will be able to stop raising rates and then begin cutting next year. In the bond market, the 10-year yield went from 3.95% as the CPI data was published to 4.10% by the close on Thursday. Meanwhile, the S&P500 was pretty much unchanged. So, for equities and bonds, what was once a bullish driver has become less so now, and corroborative data is not new information.

Back at home, the Royal Institute of Chartered Surveyor’s report on the housing market continued to flag the prospect of further house price falls which, in earlier years, would be a harbinger of very difficult economic times. Yet the UK economy put in yet another quarter of growth, albeit anaemic, at +0.2%. The really surprising aspect was that July manufacturing and construction output was very strong at +2.4% and +1.6% month-on-month, respectively. That echoed the construction purchasing managers’ index (PMI) from last week, which showed a totally surprising shift into growth territory at 51.7 (50 marks the divide between contraction and expansion). Perhaps unsurprisingly, bond yields shifted sharply higher on Friday after the data, with the 10-year testing 4.5% and the two-year back at 5%. Neither has yet broken beyond the highs of the past month, however.

August is generally a quiet month, with holidays the priority for many. In recent years, it has felt more like business-as-usual, but market liquidity can still be somewhat reduced and, if news is really important, can lead to sharp dislocations. So far this month, the stories are not unimportant, but neither are they earth shattering, and while volatility has picked up, remains way down from last year and even the first half of this year.

China’s growing pains continue

China’s economy has sputtered again. CPI inflation fell 0.3% year-on-year in July. Producer prices were even lower, falling 4.4%. That might sound like a strange thing to complain about, given the West’s ongoing battle with high inflation; but China did not experience the same wave of post-pandemic inflation, and now deflation is a bad sign for the world’s second-largest economy. It shows weakness in consumer demand, which will likely mean slower growth down the line. Moreover, businesses competing with Chinese exporters are losing pricing power, while suppliers of commodities to China are experiencing a sharp slackening in demand. Thus, weak growth in China may be transferring to the rest of the world.

As we wrote recently about China, its economic problems have never been about lacking potential. The question is whether the government is willing or able to unlock it, and as yet that question remains unanswered. At the end of July, Beijing called for strong countercyclical measures to arrest a recent decline, but as (by now) usual, the details on what this means are lacking. Policymakers want to boost short-term growth, but are unwilling to loosen their grip on the private sector to do so.

China still has potential for a near-term rebound. But for foreign investors, the longer term returns on Chinese assets are hard to assess. Even though economic growth will come through, there is no guarantee this will translate into enough profit to justify investment, thanks to the unpredictability of central government. There are growth opportunities in China; Beijing only needs to decide if they are in its interest.

Is US earnings supremacy on the wane?

American companies are leading the way again this year, with 12.8% year-to-date returns as of the end of July. With the benefit of hindsight going back a decade, there are few better bets any international investor could have made than the US and its tech giants. Over the 20 years from 1989 to 2019, the S&P delivered an average real (inflation-adjusted) return of 5.5% a year excluding dividends.

However, a June discussion paper written by US central bank staff for the Federal Reserve Board of Governors in Washington argues that much of the growth in the value of US investments is explainable by different, more straightforward factors. The paper posits that exceptional US stock market performance over the last three decades was a consequence of changes to tax and interest rates. Moreover, it is very hard to see either of these trends continuing into the next decade or beyond. Short-term government interest rates have already increased from around 0% at the start of 2022 to above 5%, and markets expect these to come down over the next year or so. But as we have noted before, the economic environment – and particularly labour relations – mean we should not expect a quick return to the pre-pandemic norm of low inflation and growth.

Tax rates are a similar story. Effective taxation is already as low as it has been since corporate taxes were introduced, and the historically high levels of government debt are coinciding with an historically small tax base.

Equity prices change because of earnings growth and the rate investors are willing to pay for those expected earnings. Essentially, long-term US performance from here could be capped given that valuations are no lower than the average, an average based on net income growth which has had exceptional factors since 1989. It is possible that investors could show an even stronger bias for American assets, and accept a lower return because they feel US equities are less risky than other countries. This is not unthinkable but, in the current environment, it is hard to see the US outperforming to the level it has before.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

14/08/2023
Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, the ‘Daily Investment Bulletin’ from Brooks Macdonald providing a brief summary of the key factors currently affecting global markets and economies. Received this morning – 11/08/2023

What has happened

US equities were unmoved yesterday after US CPI came in line with market expectations but the US 30-year Treasury auction struggled. Over in Europe, equities rose more than three-quarters of a percent as the market closed before the later US sell-off. Travel and luxury goods companies did particularly well after China announced that it would be ending its ban on outbound international group tours.

US CPI

The monthly July US CPI print came in line with market expectations but taking the readings to two decimal places there was even better news. Headline CPI expanded by just 0.17% month-on-month with core CPI expanding by just 0.16% over the same period. These very low monthly figures brought headline annual inflation to 3.2% whereas core stayed at 4.7%, reflecting the stickiness of monthly core CPI earlier in the year. The monthly numbers will receive the most attention with both the core and headline readings now near the 2% Fed target for a second month in a row. In terms of contributors to this, airfares were down 8% over the month, building on a similarly sized decline the month prior.

Bond market reaction

We have a while until the next Fed meeting therefore there were Fed speakers immediately available to comment on the CPI. President Daly welcomed the numbers but said that the monthly reading was ‘not a data point that says victory is ours’. In terms of timing of any interest rate cuts, Daly said that she expected those conversations to wait until 2024, pushing back against market hopes for a December 2023 cut. The major bond market news came with the 30-year Treasury auction however as strong demand failed to materialise, causing the bonds to be issued at 4.189%, this then catalysed further concern over the sheer size of the US deficit and its linked funding needs.

What does Brooks Macdonald think?

Stripping out some of the more volatile disinflationary contributors, such as airfares, we still see a stickier inflation backdrop in the US. That said, these volatile components can be lead indicators of wider moves within the inflation basket, just as we saw in 2021 and 2022 when inflation was on its ascendency. The overall reading will support the case for a pause in US interest rates when the Federal Reserve meet in September.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

11th August 2023

Team No Comments

Stocks fall on US credit rating downgrade

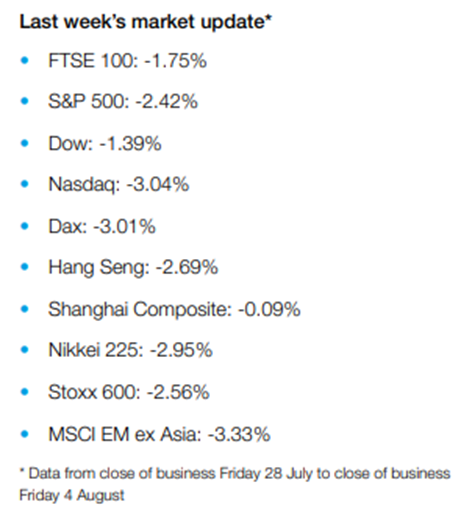
Please see below article received from Brewin Dolphin yesterday afternoon, which provides an update on global market performance.

Most major stock markets fell last week after rating agency Fitch downgraded the US government’s credit rating.

This marked the second time in history that a leading credit agency has downgraded US debt. Fitch cut its rating from AAA to AA+, citing concerns about the state of the country’s finances and its debt burden. The announcement weighed on stocks, with the S&P 500, Dow and Nasdaq finishing the week down 2.4%, 1.4% and 3.0%, respectively.

The UK’s FTSE 100 lost 1.8% after the Bank of England (BoE) indicated that interest rates were likely to stay higher for longer. The pan-European Stoxx 600 and Germany’s Dax fell 2.6% and 3.0%, respectively, following disappointing European corporate earnings reports.

In China, the Shanghai Composite was flat as investors weighed measures that aim to boost consumption and support the real estate market against a 33.1% year-on[1]year slump in new home sales in July.

Investors await US inflation report

US indices rose on Monday (7 August) ahead of the release of US inflation numbers later in the week. The Dow rallied 1.2% and the S&P 500 gained 0.9%. Investors will be scrutinising the report for any clues as to the Federal Reserve’s next interest rate decision in September.

UK and European indices were mixed on Monday and then fell at the start of trading on Tuesday, after data showed exports from China fell by 14.5% year-on-year in July, the biggest drop since the start of the pandemic. Closer to home, the value of UK retail sales grew by just 1.5% year-on-year in July, much lower than the 12-month average of 3.9%, according to the British Retail Consortium and KPMG. The slowdown was partly due to easing inflation (the figures are not adjusted for inflation) as well as wet weather.

BoE raises base rate to 5.25%

Last week saw the Bank of England lift the UK’s base interest rate by a quarter of a percentage point to 5.25%, a new 15-year high. In its statement, the BoE said that some key indicators, notably wage growth, “suggest that some of the risks from more persistent inflationary pressures may have begun to crystallise”.

The BoE hinted that interest rates were likely to stay high for some time, saying it would “ensure the bank rate is sufficiently restrictive for sufficiently long to return inflation to the 2% target”. The bank expects inflation to fall to 4.9% by the end of the year. Although the BoE does not forecast a recession in the coming years, gross domestic product (GDP) is expected to remain below pre-pandemic levels as a result of high interest rates.

UK house prices plummet

UK house prices fell in July at their fastest annual rate since 2009, according to Nationwide. House prices fell by 0.2% from the previous month and by 3.8% from a year ago, worse than the 3.5% annual decline seen in June. The price of a typical home is now 4.5% below the August 2022 peak.

Robert Gardner, Nationwide’s chief economist, said housing affordability remains stretched for those looking to buy a home with a mortgage. For example, a first-time buyer with a 20% deposit who earns the average wage would see monthly mortgage payments account for 43% of their take-home pay (assuming a 6% mortgage rate). This is up from 32% a year ago and well above the long[1]run average of 29%.

Separate data from the BoE showed the value of net mortgage lending fell in the second quarter compared to the first quarter, marking the first quarterly contraction since records began in 1987.

US labour market cools

Over in the US, Friday’s closely watched nonfarm payrolls report showed the labour market cooled slightly in July. The economy added 187,000 new jobs, slightly below expectations of 200,000. The figure for June was revised lower to 185,000 from 209,000, while May’s number was reduced by 25,000 to 281,000. The report from the Labor Department also showed the unemployment rate fell back down to 3.5% from 3.6% the previous month, showing continued tightness in the labour market. Average hourly earnings rose by 0.4% month-on-month, which is above what is considered consistent with the Federal Reserve hitting its inflation target.

Japan’s services sector softens

Japan’s services sector activity grew at a slower pace in July as new business growth eased and cost pressures remained high. The final au Jibun Bank purchasing managers’ index (PMI) showed the headline services index fell slightly to 53.8 in July from 54.0 in June. This was the slowest pace of growth since January. Average cost burdens faced by service providers accelerated for the first time since April amid reports of higher electricity, fuel, raw material and labour costs. Business confidence remained strong in July, but the degree of optimism slipped to a five-month low.

Meanwhile, the manufacturing PMI slipped further into contraction territory to 49.6 in July from 49.8 in June. Firms attributed the decline to weak customer demand for manufactured goods in both domestic and international markets. More positively, input price inflation eased to the softest level since February 2021, and business confidence was the second highest in 18 months.

Please check in again soon for further relevant content and market news.

Chloe

09/08/2023

Team No Comments

The Daily Update: Moody’s Downgrades Banks / Fed Polar Opposites / Food Price Pain

Please see the below market update from EPIC Investment Partners:

Moody’s cut the credit rating for 10 midsize and small US banks yesterday whilst warning that it may also downgrade some of the nation’s biggest lenders, believing that they are being squeezed by funding risks, possible regulatory capital weaknesses and increased risk exposure to commercial real estate loans.

The banks that had their ratings cut included Old National Bancorp, Fulton Financial Corp, M&T Bank Corp, BOK Financial Corp, Pinnacle Financial Partners Inc, and Webster Financial Corp with bigger lenders like State Street Corp, U.S. Bancorp, Truist Financial Corp, and Bank of New York Mellon Corp on review.

In the statement following the downgrades, the rating agency said: “Many banks’ second-quarter results showed growing profitability pressures that will reduce their ability to generate internal capital”. Adding, “This comes as a mild U.S. recession is on the horizon for early 2024 and asset quality looks set to decline, with particular risks in some banks’ commercial real estate (CRE) portfolios.”

Overnight we also had a couple of Fed speakers hit the wires, Bowman and Bostic, who are at opposite ends of the hawk/dove spectrum, and true to form, they did not deviate.

Bowman repeated her view that the Fed may need to raise rates further to fully restore price stability, although it will still depend on incoming data. Bostic said that rates are in a restrictive stance, employment gains are slowing, and that there is no need to hike rates further. He added that he expects the Fed to be in restrictive territory well into 2024.

On this side of the pond, we heard from the Old Lady’s Chief Economist, Huw Pill, warning that while “substantial” falls on global food markets will eventually filter their way down to shoppers, it will only slow the rate of price increases rather than result in an actual fall.

“Unfortunately, the days of seeing food prices fall — that does seem to be something that we may not be seeing for a little while yet, if in the future at all. Our expectation at the moment is that food price inflation will fall back towards about 10% by the end of this year and then further next year”, he said. Adding, “That’s still not a very comfortable level.”

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

8th August 2023

Team No Comments

Tatton Investment Management: Monday Digest

Please see below the Tatton ‘Monday Digest’, which was received this morning (07/08/2023) and provides their views on global economic news from the past week:

Overview: Expecting the unexpected

Stock and bond markets started August with something of a wobble last week. When bond yields suddenly ticked up over the week, for reasons that were not immediately obvious, equity valuations reacted with a mild correction. Only after Friday’s US jobs data signalled a cooling of underlying inflation drivers from the tight labour markets did equity markets begin to relax again. The catalyst for bond yields rising (which means prices fell) was not immediately obvious. It may have been Fitch’s downgrade of the US long-term foreign currency credit rating to AA+ but, since US Treasuries are NOT issued in a foreign currency, this shouldn’t matter greatly. Also, the much more influential Standard & Poor’s has had its US rating at AA+ since 2011.

It is more likely that the price falls were simply due ‘more sellers than buyers’. The US Treasury surprised markets by selling substantially more new long-term bonds than expected, just as corporate borrowers have been shifting from high-cost short-term borrowing to longer-term financing (as we noted last week) and therefore – like the US government – also looked for more buyers of long-term bonds.

The bond sell-off may not have much further to go, but investors are still wary after the huge capital losses of 2022. Here in the UK, we are no stranger to bond price falls since last autumn’s mini-budget disaster. Last Thursday, the Bank of England’s Monetary Policy Committee (MPC) voted by a majority to raise rates by another 0.25% and reiterated that “further tightening in monetary policy would be required”. Although the MPC sees inflation as hard to shift, investors see the risks as no longer heavily skewed. Growth here and in Europe (extremely important for the UK) seem to be on a slower path than the US, especially recently. Although the UK government bond yield curve is inverted, UK (and Euro) bonds look cheaper than those in the US. All areas have seen some price falls but, when comparing bonds of similar maturity, UK Gilts and Euro government bonds have been relatively stable. 

The previously-mentioned US non-farm payroll data of new jobs created over the month (being slightly weaker and below 200,000 new employees) helped alleviate some of the pressure on US yields. Nevertheless, we suspect the incentive to issue around the 10 year maturity because of the currently lower yield cost compared to short term debt could still have some further follow-through – pushing this maturity band’s yield up further. It’s not the end of the world, but equities could lose momentum. So, while we welcomed July’s upbeat investor sentiment, August so far has again demonstrated the fragility of optimism-driven valuations. We expect market fortunes to remain finely balanced and therefore sensitive to anything with the potential to sway investors one way or the other.

European energy update: safer but not safe

Europe has come an incredible way from a year ago. Last August, European natural gas prices peaked at around €340 per megawatt hour, but currently prices are under €30. Far from shortages, current industry talk is of weak demand and storage capacity being close to full. Prices for futures contracts point to a sharp oversupply, leading benchmark contract prices to fall 24% in July, according to Bloomberg.

However, due to recent problems with production in Norway, and lower-than-expected cargoes of liquified natural gas (LNG), there has been a sharp drop in Europe’s projected supply recently. That pushed back analyst predictions of the date when storage will hit 100% of capacity. Bloomberg went from mid-September to the end of October. A year ago, this would have been the kind of news that sent commodity markets rocketing and policymakers spinning, but this time the news was shrugged off by traders, with storage levels currently at 86%.

Traders are now much more focused on weak demand prospects than supply side concerns. Despite Eurozone growth pulling out of a dip in the last quarter, manufacturing output has proven weak on the continent, lowering energy demand. The near future also looks difficult, with business sentiment surveys weakening further and unexpectedly. Last week, Bloomberg lowered its forecast for European gas demand for the 2023-24 winter; they expect it to be 27 billion cubic metres below the 2016-2020 average, if the weather is within the normal range.

Should the weather stay within a normal range, Europe will start its gas drawdown from a strong position and have comfortably enough energy supplies to provide for a sluggish economy. Given there are no great harsh winter fears (indeed policymakers’ attention is currently on the punishingly hot summer in southern Europe) it therefore makes sense that futures pricing for gas has come down, which should help European consumers down the line. On the negative side, however, the continent is still vulnerable to events entirely beyond its control, and despite the pressing need for energy security and the close-to-full gas supplies, Europe’s gas storage capacity has not significantly improved over the last two years. If the supply-demand balance did unexpectedly shift, the storage situation could mean prices change rapidly.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

07/08/2023

Team No Comments

Evelyn Partners Update – August Bank of England MPC decision

Please see below, an article from Evelyn Partners discussing the recent Monetary Policy Committee interest rate decision and the implications for markets and the economy. Received yesterday evening – 03/08/2023

What happened?

The Bank of England delivered on the expectations of economists and markets with an increase of 25bps to the base rate at their meeting today. This represents the Bank’s 14th consecutive increase and takes the base rate to 5.25%, its highest in 15 years.  The committee was split 3 ways on the vote, with 1-6-2 members voting for 0-25-50bps increases respectively. 

What does it mean?

Today’s decision by the Bank of England was always likely to be close, if markets are our guide. Prior to the meeting, Overnight Index Swap markets had priced around a 1/3 chance that the Bank would go further and increase by 50bps.  In the end the MPC’s hawks, who would have preferred such a move, were outvoted by the majority, including governor Andrew Bailey.

A key reason the bank will have decided against the larger increase will have been June’s inflation numbers, which finally revealed a downside surprise in headline inflation and, perhaps more importantly, the core (excluding volatile food and energy) print.  The core figure came in at 6.9%, which will still high, was lower than July’s figure of 7.1%.  The expectation is for inflation to continue to fall as lower energy prices continue to feed through to the bottom lines of balance sheets, both for businesses and individuals.  This was reflected in the MPC’s own inflation forecasts, which fell from 5.1% to 4.9% in the fourth quarter of this year, although this was allied with an increase in its inflation expectations over the medium term.

The monetary policy report also included growth forecasts, which continued to make for pretty bleak reading, revealing a cut to forecasts to 0.5% per year for 2023 and 2024.  On the upside, the Bank agrees with the consensus of economists in no longer forecasting a recession in the UK, but it does highlight the risk of one in 2024 and early 2025. 

Previous guidance in the minutes released today was maintained: “if there were to be evidence of more persistent pressures, then further tightening in monetary policy would be required,”. There was an Important addition about rates being “sufficiently restrictive for sufficiently long” for inflation to get back to the Bank’s 2% target.  That implies that interest rate cuts are perhaps further away than some had imagined. 

The Bank provided no clues to the market today on its plans for reducing the size of its balance sheet, saying it will lay out these plans at its next meeting in September. 

Bottom Line

Reaction to today’s 25bps increase by markets was dovish, as expectations of where rates will peak moved slightly lower, from 5.85% before the meeting to 5.75% afterwards, at the end of this year or beginning of next.  This will be welcomed by mortgage holders, in the hope that increasing rate expectations may have peaked, along with the cost of mortgage deals in the market. The yield on the 10 year government gilt remained broadly unchanged on the announcement and looks attractive in our view, at 4.4%, as the Bank gets closer to the top.

Please continue to check our blog content for advice and planning news from us and leading investment management houses.

Alex Kitteringham

4th August 2023

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see the below article from Brooks Macdonald providing their commentary on global markets. Received this morning – 03/08/2023.

What has happened

Equities fell sharply yesterday as concerns around the US debt downgrade focused investor attention on the funding needs of the US government. The US equity market fell by over 1%, recording its worst daily return since April of this year.

US debt financing

Concerns over the quantity of US Treasury issuance over the coming months filtered through risk assets yesterday with the near-term borrowing needs being formalised yesterday. Adding concern was the comment from the Treasury that this increase in borrowing was likely to continue, saying that ‘further gradual increases will likely be necessary in future quarters.’ Treasury issuance raises yields as the price adjusts for additional supply. At the same time, this issuance draws liquidity from other areas of the market (such as equities and corporate bonds), decreasing the prices of risk assets. All of this puts the US budget deficit back into the spotlight with the Fitch downgrade effectively just highlighting the funding concerns, recent political impasses and ongoing fiscal spending.

UK

Today the market’s focus will switch to the Bank of England which is unveiling its latest policy change at midday. The consensus expects a 25bp interest rate hike, with economists reducing the chance of a 50bp move given the downside miss to UK CPI last month. The market is only now apportioning around a quarter chance of a 50bp move after it being the most likely outcome a few weeks ago. The political pressure continues in the interim with Prime Minister Sunak saying that inflation was not falling as fast as he would like and stressing the policy importance of a further reduction in price pressure.

What does Brooks Macdonald think

The shift in market expectations towards a 25bp hike at today’s meeting does not mean that the UK will have necessarily reached its peak interest rate after the move. The market is expecting the Bank of England to need to raise interest rates further over the coming months to guide inflation lower. A strong UK labour market is a particular concern to the Bank of England, therefore one should expect the central bank to continue with their hawkish rhetoric alongside the smaller hike.

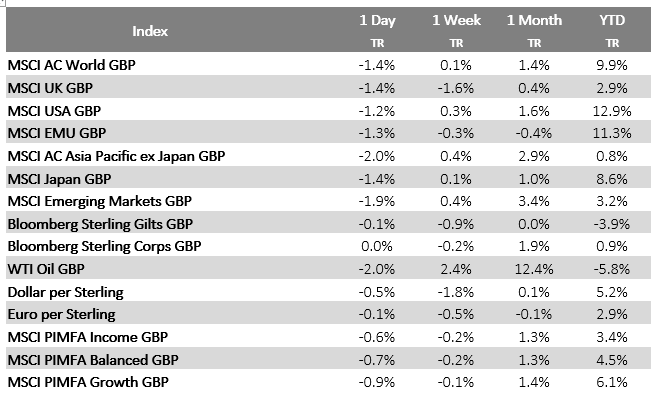
Bloomberg as at 03/08/2023. TR denotes Net Total Return

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

03/08/2023

Team No Comments

Brewin Dolphin – Markets in a Minute

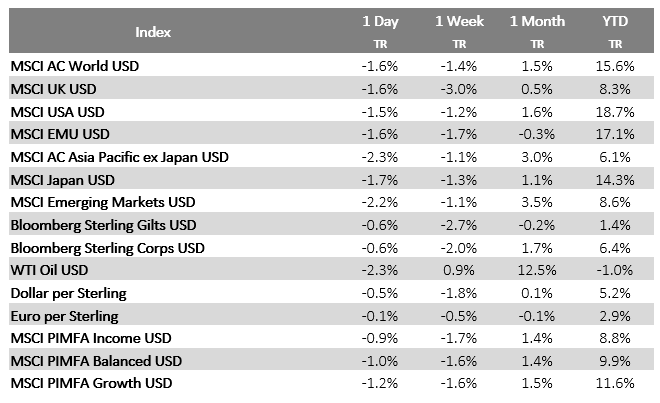
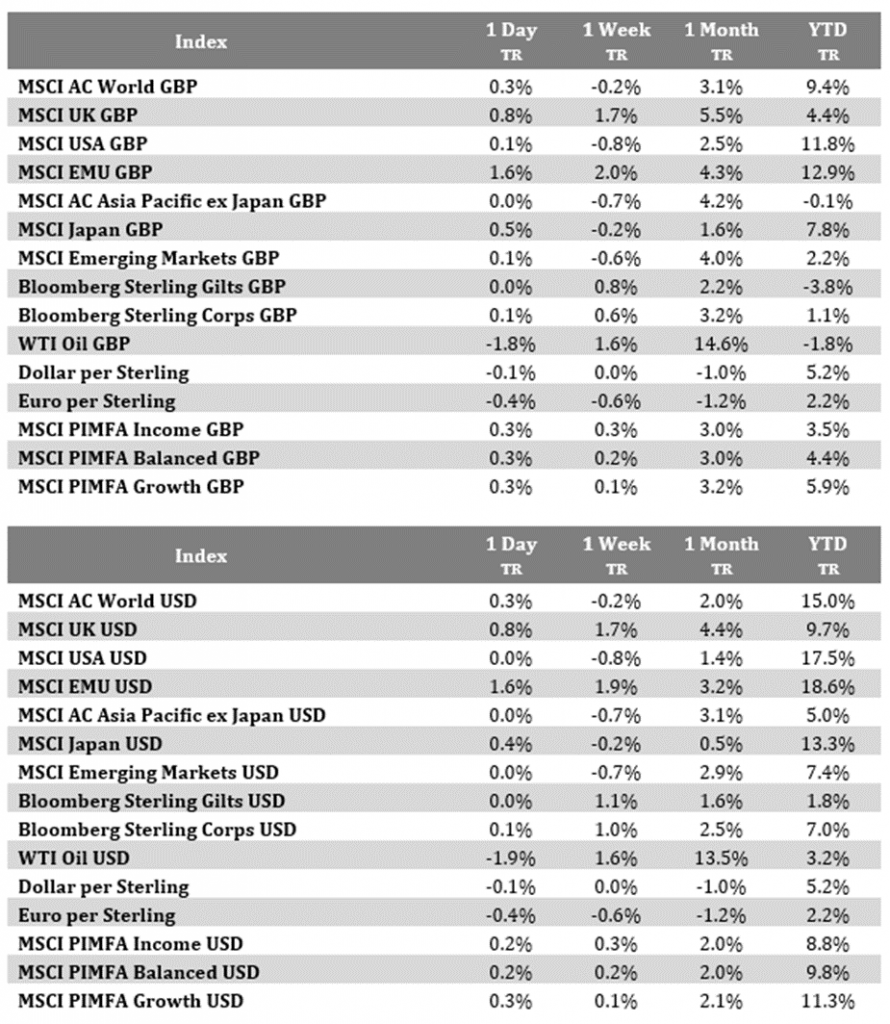
Please see below, Brewin Dolphin’s ‘Markets in a Minute’ update, providing a brief analysis of the key news from markets around the world, which was received late yesterday (01/08/2023) afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

02/08/2023

Team No Comments

Markets in positive mood following better US inflation data

Please see below article received from Brooks Macdonald yesterday afternoon, which provides a detailed market commentary as we head into August.

  • Better inflation data buoys hopes that the US economy might be able to pull-off a soft landing
  • Bank of Japan intervenes to dampen government bond yield moves
  • Company Q2 earnings reports reach the half-way point, so far so good
  • Another interest rate hike expected from the Bank of England later this week

Better inflation data buoys hopes that the US economy might be able to pull-off a soft landing

Markets finished last week in positive mood, as softer US inflation data increasingly suggested the economy might be able to pull-off a so-called ‘soft’ landing (where economic growth slows but avoids recession). Buoying sentiment, both US personal consumption prices and employment costs saw annual gains come in a shade weaker than expected. Looking forward, this week is a relatively busy one for data. It starts with Eurozone consumer inflation later this morning, followed by the US Federal Reserve’s (Fed) latest Senior Loan Officer Opinion Survey on bank lending out later today. Central bank decisions are due from the Reserve Bank of Australia on Tuesday and the Bank of England (BoE) on Thursday. Elsewhere, after last week’s better US Gross Domestic Product (GDP) Q2 print, this week we get some US purchasing manager survey data on manufacturing and services on Tuesday and Thursday respectively. Wrapping up the week, the US monthly non-farm jobs report is out on Friday, where the consensus is looking for 200,000 jobs added in July.

Bank of Japan intervenes to dampen government bond yield moves

After the Bank of Japan (BoJ) surprised markets last Friday by effectively loosening its grip on its yield-curve-control monetary policy, this morning we have been reminded that there still limits to how far the BoJ wants to travel for now. Earlier today the BoJ announced an unscheduled Japanese Government Bond (JGB) purchase operation, spending 300bn yen (around $2.1bn) to buy 5-to-10-year bonds at market yields. This looks consistent with BoJ Governor Kazuo Ueda’s comments last week that the BoJ was ‘not ready’ to allow yields to move freely. It is also interesting that in last week’s latest BoJ forecasts, while it raised its median estimate for fiscal 2023 core consumer inflation (Consumer Price Index (CPI) all items less fresh food and energy) to 3.2% from 2.5% previously, there was no change to fiscal 2024 at 1.7% or fiscal 2025 at 1.8%, which both sit below the BoJ’s 2% inflation target.

Company Q2 earnings reports reach the half-way point, so far so good

We are now half-way through the US company results season, with 51% of US large-market-capitalised companies having reported Q2 results. According to the latest Factset ‘earnings insight’ report, 80% have reported Earnings Per Share (EPS) above consensus, which is above the 10-year average of 73%. Revenues are also so far proving resilient, with 64% of companies reporting revenues above consensus, just about better than the 10-year average of 63%. Meanwhile the longer-term earnings outlook appears to continue to push-back against wider recession fears, with calendar year-on-year earnings growth expected to rise from a flat +0.4% this year, to +12.6% in 2024. Markets are discounting machines, calibrating expected future outcomes into asset prices today. With a strong year-on-year pickup in earnings growth expected next year, that is helping to give oxygen to markets currently.

Another interest rate hike expected from the Bank of England later this week

After hikes from both the Fed and the European Central Bank last week, the BoE is expected to follow suit on Thursday. It is still a bit of a close call however between a 25 basis points (bp) or 50bp hike, The BoE will be weighing up strong wage data on the one hand, but against this, there was the better-than-expected consumer inflation data. On balance, markets expect the BoE to hike by 25bps (which would take interest rates up from 5.00% currently, to 5.25%, which would be the BoE’s 14th consecutive hike in this cycle) but reiterate data-dependency for its forward guidance.

Please check in again with us soon for further relevant content and market news.

Chloe

01/08/2023