Team No Comments

Brooks Macdonald Weekly Market Commentary: Global equities rose, spurred by softer-than-expected US inflation

Please see the below article from Brooks Macdonald detailing the latest update and economic news from the US. Received 17/07/2023.

Global equities surged last week, spurred by softer-than-expected US inflation

Equities fell marginally on Friday but the week in aggregate saw strong gains in equities and bonds as a softer Consumer Price Index (CPI) report reignited hopes of a US soft landing. This week will see a series of US economic data releases, alongside the first full week of the earnings season, which will help investors gauge whether growth has been impacted yet by the restrictive US monetary policy.

US earnings season is underway with major technology and banking names reporting this week

Last Friday saw the start of the US earnings season and the releases from some of the major US banks. Those banks reporting strong results saw rallies in their share prices, mirroring the anecdotal evidence that global asset allocators are underweight equities and are implying that there is still plenty of cash on the sidelines to enter stocks when there is good news. This week sees Tesla, Netflix and IBM alongside other major US banks such as Bank of America, Morgan Stanley and Goldman Sachs. The earnings season takes some time to get going so we will only see c. 10% of the large US companies reporting this week, though by the end of the week we will have a good idea of how earnings for many sectors are likely to play out.

The latest compendium of Chinese data shows an economy struggling to regain momentum

This morning saw the latest compendium of monthly Chinese data. The data showed an economy still struggling to grow despite the exit of pandemic era restrictions. Gross Domestic Product (GDP) expanded by 6.3% in Q2 on a year-on-year basis but this was well below the 7.3% expected by analysts. Given the comparable quarter in 2022 is a period that saw the Shanghai COVID outbreak, investors had hoped to see a more sizeable rebound. Importantly the quarter-on-quarter GDP growth rate was just 0.8%. Retail sales also marginally disappointed as momentum slowed.

After the market’s strongly positive reaction to the trifecta of slower CPI, Producer Price Index (PPI) and used car prices last week, European investors will be keeping a close eye on the UK CPI report on Wednesday. With the UK experiencing inflation due to domestic issues (such a lack of labour supply) and international factors (food prices), it is likely that any global disinflation will take some time to filter through. That said, expectations around UK inflation are very high at the moment, so a small glimmer of disinflation could be enough to reverse the rapid rise in UK interest rate expectations since the upside surprise to UK CPI a few months ago.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

18/07/2023
Team No Comments

Tatton Monday Digest

Please see below this week’s Tatton Monday Digest which was received earlier this morning:

Overview: Core inflation slowdown equals upbeat equity markets

We wrote at the end of last week that markets were still absorbing the prospect of another round of significant interest rate rises from central banks, and that equities would therefore come under further pressure. But by the end of last week equity markets had risen sharply, with most more than reversing their losses of the previous week. The catalyst for the US stock market rally was the release of the latest consumer price index (CPI) figures, which showed that core inflation (with energy and food stripped out) cooled to 3% in June, the lowest rate of growth in two years.

Greedflation or wage-price spiral?

Probably not since the 1970s has inflation been such an all-consuming topic in public discourse. This is because, of course, for decades there was very little of it. Things could hardly be more different now. People are clearly worried about rising prices for goods and services, and what might happen to their individual or collective spending power. But beyond that, there is a deep argument raging about what causes inflation. Opinions remain divided across two major camps: those who think corporate ‘profiteering’ is to blame for runaway prices, and those who think wages are the main cause. As you might imagine, the dividing line is highly political. Here in the UK, the Bank of England (BoE) is adamant wages are the biggest inflationary concern, whereas in Europe, policymakers are much more concerned about corporate profits. Last week, BoE Governor Andrew Bailey joined Chancellor Jeremy Hunt in calling on Britons to show restraint in their wage demands. This is his second intervention, having called for similar restraint back in March. At the same time, Hunt reportedly asked the BoE to scrutinise profits in the UK food industry, following accusations of ‘price gouging’ (the British Retail Consortium recently revealed food prices increased 14.6% in the year to June).

Unfortunately, it is almost impossible to objectively say whether profits or wages are the bigger inflationary force, because they are two sides of the same economic coin. There has been a lot of talk recently about the return of labour pricing power – particularly after two years of widespread industrial action. In this sense, the sensitivity of inflation to employment has increased, which the BoE clearly sees as its main way of impacting the economy. But one could just as well argue there has been a return of corporate pricing power, following a long period of consolidation across nearly every major industry. This has led to wages and profits feeding off each other without either backing down – what should perhaps be called the ‘wage-profit spiral’. Who should ‘give in’ first is a political issue but, unless somebody does give in, we will keep talking about inflation for some time to come.

Banking sector pressure appears far from over

Last Wednesday, BoE Governor Bailey called on UK banks to pass along higher interest rates to savers. Over the past year-and-a-half, interest rates have seen the sharpest spike in a generation, going from near zero at the end of 2021 to 5% now, with further hikes set to come. But deposit interest rates from the big retail banks remain at little over 1% in many cases. UK retail banking suffers from a notable lack of competition, being largely dominated by older, established players and building societies. This means savers have few options and have to take whatever rate is offered, as regulators point out, however, both the government and the BoE have been complicit in reducing the number of British banks, leading to the concentrated environment we see today.

The situation is notably different in the US and Europe, where smaller regional banks are much more prominent. But the prominence of regional banks in the US has been much discussed this year after many of them collapsed, most notably Silicon Valley Bank (SVB), bringing to light deeper structural problems. Having many smaller players increases competition and should benefit customers. But for the banks themselves, the lack of scale and the fact their lending and borrowing all happen in relatively small regions, substantially decreases the potential for diversification. As investors know, a lack of diversification can mean losses piling up quickly. That is exactly what happened to SVB, and these problems have not gone away for the regional banks.

A difficult financial and economic climate is toughest for smaller businesses. For banks specifically, tightening financial conditions can boost profitability if it means higher long-term lending rates over short-term deposits (as seen in the UK), but it can also threaten liquidity, something smaller players inevitably have less of. The incentive for mergers or acquisitions is therefore large. We suspect this is less likely to play out in Europe, where the structural barriers to cross-border mergers are higher. European banks tend to be well capitalised, so stormy conditions might not be a problem at first. But the combination of high interest rates for longer and smaller corporates suffering under the higher cost of borrowing could lead to banking stress and even defaults if the Eurozone economy takes a turn for the worse. Here in the UK, we seem not to have these problems, but a highly concentrated banking system has its drawbacks too. Political pressure is now being exerted on British banks, both by politicians and the BoE. If consolidation increases in the US, we should expect the same political problems to play out, and if the US is more active in its antitrust policies – as has often been the case historically – some of that pressure might make it over here too

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

17/07/2023

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below today’s Brooks Macdonald Daily Investment Bulletin, which was received earlier this morning (14/07/2023):

What has happened

Equities and bonds continued their surge yesterday as investors contemplated the likelihood of a US ‘soft landing’ where inflation falls sufficiently to allow the US economy to avoid a recession. US equity markets have now recovered a significant portion of last year’s sell-off and are back to levels last seen in April 2022.

Market narrative shifts

It was only one week ago that the market narrative was decisively behind a sticky inflation, high interest rate backdrop however the CPI release (and yesterday’s PPI release) has catalysed a rapid shift towards hope for a sudden cooling in US inflation pressures. Those cooling inflation expectations are then feeding a growing chance of multiple interest rate cuts in 2024. The Producer Price Inflation numbers released yesterday painted a similarly rosy outlook for consumer inflation. Producer Inflation, which will ultimately filter into consumer prices, rose at just 0.1% year-on-year, below expectations and very close to outright deflation territory. The core PPI release also missed expectations and is growing by just 2.4% year-on-year. With the CPI and PPI releases impacting bond market thinking, investors are becoming more confident that the July meeting will be the final rate hike for this cycle.

Fed reaction

The ‘pivot’ towards US rate cuts occurred despite Fed speakers stressing that they could not yet gain confidence that inflation was under control from one reading. President Daly said it was ‘really too early to say that we’ve declared victory on inflation’ with Governor Waller saying that two more hikes this year remained his base case. Waller did show the Fed’s data dependency however, saying that if inflation readings continued in line with this week’s release, a pause may be warranted by September. Today is the last day before the Fed moves into communication blackout ahead of their next monetary policy meeting.

What does Brooks Macdonald think

Markets have been taking strong US economic news as bad news given economic strength is likely to booster consumer demand and therefore inflation. Should inflation show further signs of falling, despite robust economic growth, then this narrative too will change and good news for the economy will become good news for markets.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

14/07/2023

Team No Comments

Evelyn Partners Update – June US CPI Inflation

Please see below an article received from Evelyn Partners yesterday (12/07/2023) afternoon, which details their thoughts on yesterday’s US CPI Inflation announcement:

What happened?

US June annual headline CPI inflation rose 3.0% (consensus: +3.1%), its lowest level since March 2021, and compares to 4.0% in May. In monthly terms, CPI rose 0.2% (consensus: +0.3%), compared to a gain of 0.1% in May.

June annual core inflation (excluding food and energy) rose 4.8% (consensus: +5.0%), versus 5.3% in May. In monthly terms, core CPI rose 0.2% (consensus: +0.3%), compared to a gain of 0.4% in May.

What does it mean?

The Fed should take some comfort in the fact that monetary tightening appears to be working to bring down inflation ahead of the FOMC meeting on the 26 July. Annual headline CPI inflation is heading back towards pre-pandemic rates and core (ex-food/energy) price rises are now below 5%. There are three reasons to expect underlying inflation to slow further from here.

First, supply chain disruption from the pandemic has lessened significantly. One way to observe this is through used car prices, which are now falling on an annual basis as production normalises. This puts downward pressure on a past key driver of core CPI inflation during the early stages of Covid from 2020.

Second, rental inflation continues to slow. Using data from timely online residential platforms, recent research from Goldman Sachs shows that average annualised rental inflation has eased to just +1% over the last 8 months to June from 20% plus in mid-2021. It will take time for lower rental prices to feed through to inflation, but there is evidence it is starting to happen. For instance, June shelter CPI inflation slowed to 7.8% from a peak of 8.2% in March. CPI inflation (ex-shelter) in June was up just 0.8% from a year ago. 

Third, lead indicators point to lower core inflation in the months ahead. Selling prices from the National Federation of Independent Business, or better known as the small business survey, have fallen to a level last seen when core CPI inflation was roughly 4%. The annual change in job openings is another lead indicator with a decent track record of leading inflation and this too points to lower pace of price gains ahead. 

Bottom Line

Regardless of whether the FOMC (the US Central Bank’s interest-rate setting body) raises interest rates later this week or not (markets’ expectation is current for a 25bps increase), the Fed is likely coming to the end of its interest rate hiking cycle. This reduces the risk that the FOMC overtightens on interest rates and creates downward pressure to the economy and financial markets. Moreover, as a countercyclical currency, we expect the dollar to depreciate against other major currencies, since the risk of a so-called economic hard landing is reduced. Dollar depreciation should provide additional liquidity, which will help equities to continue their bull run.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

13/07/2023

Team No Comments

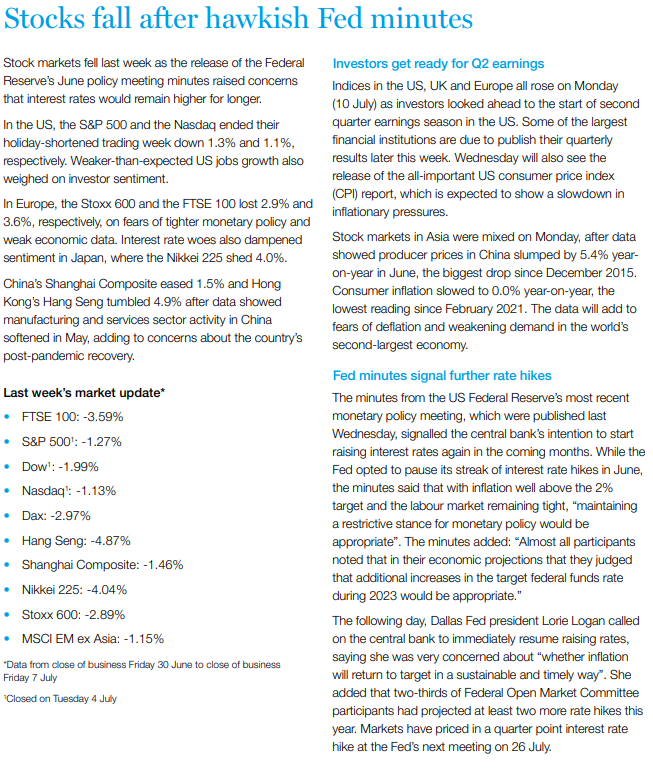
Brewin Dolphin: Markets in a Minute

Please see below ‘Markets in a Minute’ article from Brewin Dolphin commenting on the latest stock market movements. Received late yesterday afternoon – 11/07/2023.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Adam Waugh

12/07/2023

Team No Comments

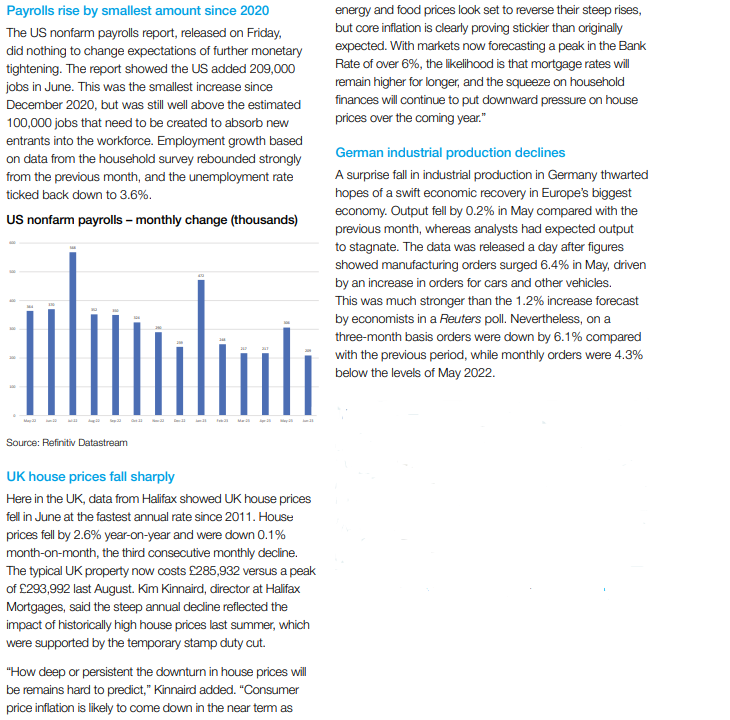
Brooks Macdonald Weekly Market Commentary – US Employment report delivers positives and negatives for investors

Please see the below article from Brooks Macdonald detailing the latest update and economic news from the US. Received 10/07/2023.

The number of new US jobs in June missed market expectations however wage inflation remains high

The headline miss in the US employment report on Friday was not taken as good news by equity markets who instead focused on some of the stickier labour market metrics. Equities closed lower on the day, with the US down just over 1% for the week and Europe underperforming, down a sizeable 3% over the same period.

The US employment report had positives and negatives for investors worried about labour market driven US inflation. The headline number of new jobs created in June came in below market expectations which is the first miss versus expectations in over a year. The unemployment rate grinded lower however, hitting 3.6% while the average number of hours worked in a week climbed versus expectations. The average hourly earnings also rose more than the market expected, coming in at 4.4% year-on-year. In aggregate, there may be some initial signs that labour market strength may soften in the coming months however the tick up in earnings and hours worked suggest that the inflationary wage pressures are still capable of fuelling consumption demand.

The market expects US headline CPI to fall dramatically on Wednesday but for core inflation to be sticky

This focus on inflation brings us to this week’s latest US CPI print which is released on Wednesday. The release comes amidst a series of US Federal Reserve (Fed) speakers so there will be a live commentary on the inflation results for the markets to consider. The headline US CPI reading is expected to plummet from 4% to 3.1% year-on-year while the US core CPI (excluding food and energy) is expected to fall more gradually, from 5.3% to 5%. The bond market, and Fed, will focus far more on this stickier core CPI target which remains well ahead of the central bank’s target range.

Falling consumer inflation expectations remain critical to avoiding an inflationary spiral

The Fed will be looking closely at the core CPI number when it is released however arguably consumers (and the media) are more likely to focus on the headline number. This is important as later in the week we see the University of Michigan release their consumer sentiment survey which includes inflation expectations. Should the headline US CPI continue to fall, this could quickly filter through to lower consumer inflation expectations which in turn may moderate wage growth demands.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

11/07/2023

Team No Comments

Tatton Investment Management: Monday Digest

Please see below, the ‘Monday Digest’ from Tatton Investment Management which covers the key news from global markets and economies. Received this morning – 10/07/2023

Markets sour on news of resilient economy

The second quarter’s positive stock market returns were driven by a somewhat surprising improvement in investor sentiment. At the end of March the fear was that the US regional banks crisis would create a more pronounced slowdown than previously anticipated, which it did not and also while bond yields rose, analyst forecasts of corporate profits did not anticipate anything more serious than a period of stagnant growth.

Markets look to have abandoned this narrative. Positive US job growth figures have been blamed for a reversal in sentiment, with equity and bond markets having fallen and bond yields having risen. So why have investors shifted their views so suddenly to the downside?

The change we experienced over this week was one of sentiment towards the future cost of capital. Up until the end of June, there was a growing expectation that at least the US central bank, the Federal Reserve, was at least close to ending their rate hiking cycle and that cost of capital as a result would not rise further and indeed was likely to start to fall over the coming 6-12 months.

Particularly hawkish statements from the Fed began to challenge these expectations. This week’s data flow of continued tightness of the US labour markets provided more evidence that the Fed may not be done with raising rates, meaning that the other central banks who were expected to be following the Fed, would end their rate rises even later.

So, in summary not particularly much has changed on the hard data front over the past few days, but a surprisingly strong US labour market report disturbed the fragile market balance. Whether this return of ‘good economic news is bad news for market valuations’ is enough to sour sentiment more permanently, remains to be seen. A second set of labour market data on Friday presented much less of an upward outlier, however, confirmed that the US labour market shows no signs of imminent turning.

A higher cost of capital can more easily be absorbed and carried by the economy when accompanied by decent growth and good levels of monetary liquidity – both of which remain broadly in place at the moment. This means markets should continue to carry a higher probability of trading sideways than down over the summer. However, if the other effect of this economic resilience is a slowing or reversal of the recent steady decline in inflationary pressure from the input cost side then the central banks raise rates ever higher. For the time being positive sentiment may well prevail, but for markets to remain that way, this week’s data flow needs to show an environment, where services gradually start to follow the manufacturing sector into an economic soft patch.

Global Inflation Update

Last month’s Federal Reserve meeting was perplexing. Due to persistent inflationary pressures, the Fed intimated that it will likely need to raise rates two more times over the coming months, despite pausing for the time being. Markets had previously hoped for just one more hike, after which financial conditions might ease – but any easing in rates will not come until 2024 at the earliest.

The Fed defended this stance on the basis that the US economy and financial system will need time to settle, and that inflationary pressures persist. This makes some sense given the upheaval witnessed in US markets over the last year  – major US regional banks collapsing sent shockwaves across the financial system. While these considerations counsel against tightening too hard – and causing an unnecessarily painful recession – they do not negate the fact that the world’s largest economy is still running hot.

The Fed also published updated forecasts for core inflation, showing prices are expected to remain stubbornly high for some time. Officials now think core US inflation – currently at 4.7% – will fall to 3.9% by the end of this year. This is a much slower decline than forecast back in March and implies the Fed does not expect to reach its 2% target for another two years, or it expects other factors – like input prices – to offset core price rises over that period.

However, some capital market research institutions believe that the US inflation rate could fall faster than the Fed’s predictions, and there is also a clear downward trajectory in real consumer spending and shortages seen in the US labour market look set to find a balance. 

Over the past year, central banks have been extremely concerned about the impact of input-cost inflation. The most prominent is the dreaded wage-price spiral, but in the US – as in Europe- we are seeing tentative signs of wage moderation.

A year ago, persistently high inflation was causing people to demand higher pay, signals which fed back through into price setting in a worrisome loop. Now, with more stable longer-term horizons, wage pressure has eased, helped by a dramatic easing of supply chain problems, but we should not get ahead of ourselves. Inflation is steadily falling around the world but it is dangerous to assume this trend can continue unchallenged. External supply shocks, a fact of life over the past few years, are always possible. 

This was the lesson learnt from the period of stagflation seen in the 1970s: what might seem like simple supply-side shocks can have lasting consequences on how people react to changes in supply in the future. Central banks seem keenly aware of this prospect. The ECB’s latest inflation forecasts are above target until 2025, with core inflation being similarly long-lasting.

While supply chain issues have certainly eased, we are already in a phase of supply contraction. Crucially, this is happening both at the source of production and further along the supply chain in the stocks of intermediaries.

A leaner supply chain and a run-down of inventories is perhaps the natural reaction to weak global demand, but it makes the global economy more vulnerable to supply shocks. It could also mean that the fallback seen in input prices could soon be coming to an end. If global growth stays steady, we may see renewed input price pressures before too long. Headline inflation is still falling thankfully, but we should be cautious about how long this can last.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

10th July 2023

Team No Comments

Brewin Dolphin: Quarterly Review: Q2 2023

Please see the below economic review of Q2 from Brewin Dolphin received last night:

Please continue to check out Blog content for advice and planning issues and the latest investment markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

07/07/2023

Team No Comments

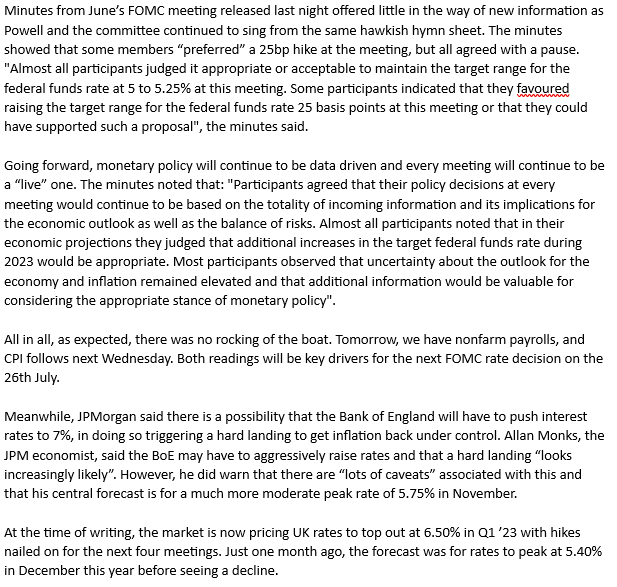
EPIC Investment Partners: The Daily Update

Please see below, mintues of the June 2023 Federal Open Market Committee (FOMC) meeting and comment on the UK interest rates. Received today – 06/07/2023 – via EPIC Investment Partners Daily Update.

Please continue to check out Blog content for advice and planning issues and the latest investment markets and economic updates from leading investment houses.

Adam Waugh

6th July 2023

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see below, Brewin Dolphin’s ‘Markets in a Minute’ update, providing a brief analysis of the key news from markets around the world. Received today – 05/07/2023

Stocks rise on positive economic data

Stock markets rose last week as a slew of positive economic data and signs of easing inflation boosted investor sentiment.

In the US, the S&P 500 surged 2.4% and the Nasdaq added 2.2% to post its best first half since 1983. Investors were cheered by a slowdown in the Federal Reserve’s preferred inflation gauge and further signs of a resilient US economy. Last week also saw Apple become the first public company to achieve a market capitalisation of $3trn.

In Europe, the pan-European Stoxx 600 added 1.9% after eurozone inflation slowed for a third consecutive month. The FTSE 100 climbed 0.9%, despite comments from Bank of England governor Andrew Bailey that UK interest rates are likely to stay higher for longer than markets expect.

In China, the Shanghai Composite edged up 0.1% as hopes of economic support measures were offset by weak data.

Manufacturing downturn deepens

Stock markets started this week on a lacklustre note. The FTSE 100 and Stoxx 600 fell 0.1% and 0.2%, respectively, at the close of trading on Monday (3 July), whereas the S&P 500 registered a small gain of 0.1%. This came after manufacturing purchasing managers’ indices (PMIs) for the UK, US and eurozone all showed a steeper contraction in activity in June.

S&P Global’s manufacturing PMI for the UK fell to a six-month low of 46.5, while the index for the eurozone dropped to 43.4, the lowest since the height of the pandemic. The readings were well below the 50.0 mark that separates growth from contraction. In the US, economists had been expecting a slight improvement in manufacturing activity, but the Institute for Supply Management’s index slipped to 46.0 from 46.9 in May. In China, meanwhile, the manufacturing sector registered slower growth, with the Caixin / S&P Global PMI falling to 50.5 from 50.9.

Fed’s preferred inflation gauge falls to 4.6%

Last week saw the release of the US personal consumption expenditures (PCE) price index, which measures the prices consumers pay for goods and services. The core PCE, which excludes food and energy and is the Federal Reserve’s preferred inflation gauge, showed prices rose by just 0.3% in May from the previous month. This took the year-on-year rate to 4.6%, down from 4.7% in April. When including food and energy, inflation was even lower with prices up just 0.1% monthon-month and 3.8% year-on-year. This was the lowest annual rate since April 2021.

While the data suggests inflation is moving in the right direction, Fed chair Jerome Powell said the central bank’s 2% target wouldn’t be achieved for a few years. Speaking at the European Central Bank’s (ECB) annual conference in Sintra, Powell said inflation was being kept high by the very strong labour market and that further interest rate increases were on the cards.

US new home sales beat forecasts

Sales of new US single-family homes rose to the highest level in nearly 18 months in May, boosted by a very low inventory of existing homes for sale. New home sales jumped by 12.2% to a seasonally adjusted annual rate of 763,000 units. Sales were 20% higher than a year ago, according to the US Census Bureau and the Department of Housing and Urban Development.

Existing home sales also improved in May. However, pending home sales (where the contract has been signed but the sale has not yet closed) shrank 2.7% in May from the previous month and by 22.2% year-on-year, according to the National Association of Realtors. This could be reflected in declining existing home sales when June’s data is published.

Weekly jobless claims plummet

In another sign of economic strength, US weekly jobless claims fell by 26,000 to 239,000 in the week ending 24 June, the steepest drop for 20 months. This reversed a recent jump, which saw claims hit levels last seen in October 2021 and led economists to speculate that layoffs could be increasing.

A separate report from The Conference Board showed consumers’ perception of the labour market was upbeat in June. More people viewed jobs as ‘plentiful’ relative to May, and there was a slight decline in the proportion who believed jobs were hard to get. Consumer confidence increased to the highest level in nearly 18 months to 109.7 from 102.5 in May. Nevertheless, the expectations gauge continued to signal that consumers anticipate a recession at some point over the next six to 12 months.

Eurozone inflation eases to 5.5%

Over in Europe, an initial estimate from the European Union’s statistics office showed annual inflation in the eurozone slowed for the third month in a row in June. Headline inflation measured 5.5%, down from 6.1% in May and lower than forecasts. This was driven by a 5.6% yearon-year decline in energy prices.

However, core inflation (excluding food and energy) rose to 5.4% year-on-year in June, up from 5.3% in May. At the conference in Sintra, ECB president Christine Lagarde said the bank could not declare victory yet in the fight to tame inflation. “We will face several years of rising nominal wages, with unit labour cost pressures exacerbated by subdued productivity growth,” Lagarde said.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

5th July 2023