Team No Comments

Weekly Market Commentary: This week’s focus will be on US employment data release

Please see below article received from Brooks Macdonald this morning, which concentrates on economic developments in the US and the consequent effects on markets.

  • We now enter the second half of the calendar year after a strong Q1 and more mixed Q2 2023.
  • Soft PCE data along with consumer spending data suggest price pressures may be fading which helped catalyse the week end rally in markets.
  • All eyes on US employment data at the end of the week which will provide further insight to the inflationary outlook. 

We now enter the second half of the calendar year after a strong Q1 and more mixed Q2 2023.

The first half of the year, proved to be a strong half for financial markets however it is fairer to say that Q1 was strong and Q2 somewhat more mixed. In terms of the 2023 leader boards, the US technology sector has surged ahead, driven by the mega-cap names and hopes of a generative Artificial Intelligence (AI) revolution. The half-year was capped off by a strong week for equities, with the rally particularly strong on Friday after Friday’s personal spending and Personal Consumption Expenditures (PCE) data suggested that inflation may be moderating in the United States.

Soft PCE data along with consumer spending data suggest price pressures may be fading which helped catalyse the week end rally in markets.

The PCE inflation index for May came in line with market expectations, at 3.8% year-on-year however the core inflation number missed a 4.7% estimate, coming in at 4.6%. The month-on-month increase in US core services inflation was the smallest since June 2022 which helped catalyse the week end rally in markets. Lastly, consumer spending was softer than the market expected which may suggest that some of the demand-side impetus behind the uptick in prices may be fading.

All eyes on US employment data at the end of the week which will provide further insight to the inflationary outlook.

This week’s focus will be on the non-farm payroll report which will give insights into the US employment picture. The headline number of new jobs created is expected to have slowed from 339k in May to 215k in June with average hourly earnings and the length of the workweek expected to be unchanged. While the headline number is expected to ease from the last reading, we are still some way off a level that would imply an imminent recession. A resilient employment report sits in contrast to some of the other lead indicators which are pointing to a slowdown however the outsized strength of the labour market has been a key driver of market inflation expectations so far this year. The Institute of Supply Management (ISM) manufacturing data is out today and is expected to show the US manufacturing sector still in contraction after turning negative in November last year.

With core inflation easing slightly in the US, and the manufacturing sector in clear contraction, the market is awaiting a change in the US employment situation that will bring some of the inflation readings down more decisively. If we see a smaller-than-expected number of new jobs created last month, there will be an expectation that this will filter into weaker hourly earnings in future months which will weigh on consumption as the second half of the year develops.

Please check in again with us soon for further relevant content and market news.

Chloe

04/07/2023

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management discussing the key economic news from the past week. Received this morning – 03/07/2023.

Overview: A glass half-full half year

The second quarter ended with positive sentiment towards global risk assets (Although UK assets have fared less well), a surprising turnaround given the black clouds that gathered back in March amid the  US regional bank crisis. Markets have responded well to more earnings positivity from analysts, but the biggest change has been in their reaction to valuations. Developed world equity indices have doubled up on rising underlying profit expectations with rises in the price-to-earnings multiples applied on top of those earnings. This sign of increased investor optimism may perhaps be lack of pessimism, a sense that the downside is protected, following the experience of renewed central bank support in the aftermath of the US banking crisis.

Somewhat contradictory, manufacturing sentiment (the outlook from businesses rather than the analysts covering them), has continued to show looming recession. This has been particularly evident in Europe, despite the easing of energy price pressures. Furthermore, June’s purchasing managers’ index (PMI) data saw the service side of the economy also gradually turning less positive and manufacturing more negative. Europe was notable for quite a sharp decline across the board, while China’s June reading is estimated to slide back to about 52.8 which would probably mean a World Composite PMI reading of about 52.7.

The European Central Bank (ECB) held its annual symposium in Singa, Portugal last week and leading central bankers from across the world spoke. The tone ranged from mild to bloody-clawed hawkishness, and convinced money markets to factor in more short-term rate rises. Bond yields duly reacted and moved higher, yet equities gave the event a ‘whatever’ shrug. Perhaps investors believe that the impacts of inflation may be less problematic for the financial and economic system than previously feared. Perhaps the central banks also think so. They certainly have not been as hawkish as their rhetoric.

The other intriguing aspect of the past quarter was the lack of corporate bankruptcies and default. In the US, following Silicon Valley Bank’s demise, investors were on the lookout for signs of default contagion. Although there were a few, most would say that it did not become a problem. In the UK, the same could have been said right up until the news concerning Thames Water. The 2021 Bulb bankruptcy was an example of how a utility company can be caught between costs, competition and price caps. Thames Water is potentially of a different magnitude. Perhaps most important will be the impacts on current equity holders, generally pension funds. In itself, the Thames Water situation is not likely to precipitate a crisis. Nevertheless, large debtors with problems are things we should watch closely, as much perhaps as hitherto deemed ultra-safe infrastructure investments.

The heat of June is forecast to give way to a cooler July in Europe. We hope the relative calm experienced by equity markets in June will carry on regardless of the weather.

Markets don’t listen to Wagner

After Yevgeny Prigozhin launched (and quickly retracted) his Wagner rebellion, global stocks and bonds did not budge. The biggest geopolitical event since the Ukraine war began was not even a blip for investors. This is understandable as far as equities go. Russian assets were removed from westerners’ investment universe as soon as Putin launched his invasion, and the remaining trade links between companies have been almost entirely dismantled since then. What is perhaps more surprising is that oil and gas markets were similarly unmoved.

This is a far cry from a year ago, when Russia’s military and political exploits felt like the dominant driver of global – and particularly European – energy prices. Brent crude nearly doubled in price during the build-up to Russia’s war, while Dutch TTF, the European natural gas futures index, more than doubled in just the last two weeks of February 2022. The spikes were even greater when Russia cut the European Union (EU) off from pipeline imports. Still, markets hate instability, and a Russian civil war could destabilise energy supplies again. And, while Europe is far less reliant on Russian gas than it was, it would be a big overstatement to say the continent is unaffected by Russia’s supply situation. 12.9% of the EU’s imports is no insignificant amount in absolute terms. Moreover, the fact that Russian supply is no longer going to the west does not mean it is unimportant for global energy markets. It is now clear that Russian oil and gas has made its way to Asia, whose imports from elsewhere have adjusted downward.

Saudi Arabia recently signalled it would further cut its oil production in response to weak global demand. This is believed to be in large part down to overproduction in Russia, as it tries to pump out supply for much-needed funding. With the ongoing slowdown in the global economy – and even looming recessions in many parts of the world – the biggest swing factor in energy markets is the lack of demand, rather than supply. This puts big suppliers like Russia in a much weaker position than they were a year ago.

Much has been written about perceived Putin weakness following the botched rebellion – backed up by Ukrainian peace discussions with a host of developing nations, including China. But we should not assume that either his grip on domestic power or desire to take Ukraine has been diminished by this. What all this does suggest, however, is that Russia can only afford to keep fighting for so long. That, together with Ukraine’s dwindling counteroffensive, increases the likelihood of a ceasefire in the medium term.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

03/07/2023

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below, Brooks Macdonald’s ‘Daily Investment Bulletin’ providing an analysis of the key events from the financial markets – received late this afternoon, 30/06/2023.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Adam Waugh

30/06/2023

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see below, Brewin Dolphin’s ‘Markets in a Minute’ update, providing a brief analysis of the key news from markets around the world. Received yesterday – 27/06/2023

Stocks fall as Bank of England hikes rates

Stock markets fell last week as the Bank of England (BoE) hiked UK interest rates by a larger-than-expected 0.5 percentage points.

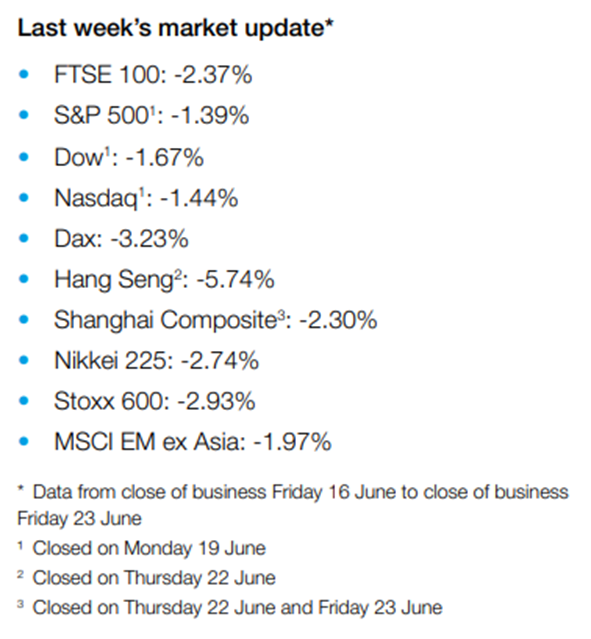
The FTSE 100, Stoxx 600 and Dax declined 2.4%, 2.9% and 3.2%, respectively, on concerns that interest rate hikes could lead to a recession in the UK and eurozone. Norway’s central bank also announced a 0.5 percentage point increase in its key interest rate, while the Swiss National Bank raised rates by a quarter of a percentage point.

Interest rate fears also weighed on US indices. The S&P 500 suffered its first drop in six weeks, finishing the week down 1.4%, while the Nasdaq recorded its first decline in two months, also down 1.4%. This came after Federal Reserve chair Jerome Powell indicated that further rate hikes could be on the cards this year.

Over in Asia, the Shanghai Composite finished its holiday-shortened trading week down 2.3% amid ongoing concerns about China’s post-pandemic economic recovery. Hong Kong’s Hang Seng slid 5.7%, its biggest drop in three months.

Failed Russia coup weighs on markets

Stock markets started this week in the red as geopolitical concerns dented investor sentiment. The S&P 500 lost 0.5% on Monday (26 June), while the FTSE 100 and the Stoxx 600 both edged down 0.1%. Russian mercenary leader Yevgeny Prigozhin embarked on an armed rebellion over the weekend, but called it off after 24 hours.

In economic news, German business sentiment deteriorated for the second consecutive month in June. The Ifo institute’s index fell to 88.5 from 91.5 in May, a steeper drop than had been expected. In the manufacturing sector, business expectations fell to their lowest level since November 2022.

BoE surprises markets with 0.5pp rate hike

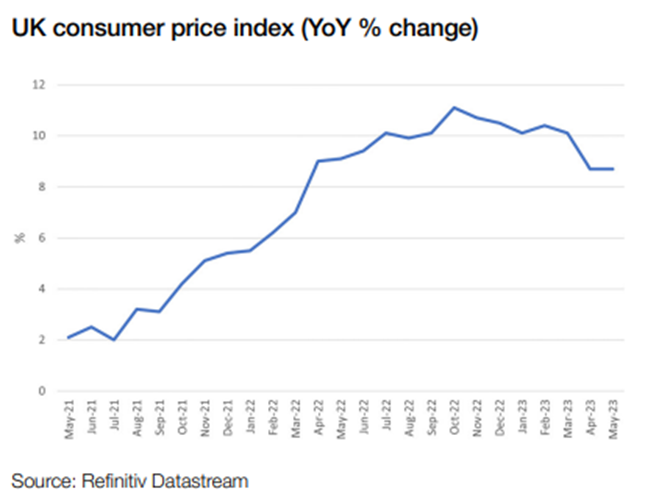
Last week saw the Bank of England announce a surprise 0.5 percentage point (pp) increase in the UK base interest rate. This was bigger than the 0.25pp hike that markets and economists were expecting. The increase takes the base rate to 5.0%, the highest level in 15 years. Andrew Bailey, governor of the BoE, said inflation was still too high and “we’ve got to deal with it”. He added: “If we don’t raise rates now, it could be worse later.” The announcement came after figures from the Office for National Statistics (ONS) showed the UK headline inflation rate remained stubbornly high at 8.7% year-on-year in May. It was the fourth month in a row that the consumer price index (CPI) exceeded forecasts. On a monthly basis, the CPI rose by 0.7%, driven by particularly strong increases in prices for air travel, recreational and cultural goods and services, and second-hand cars.

Even more concerning was the rise in core inflation, which excludes volatile food and energy prices. The core CPI rose from 6.8% in April to 7.1% in May, the highest rate since 1992.

Markets now expect the BoE to increase the base rate to 6.0% by the end of the year to try to combat inflation.

Eurozone business output weakens

In the eurozone, business output growth came close to stalling in June, according to the HCOB flash purchasing managers’ index (PMI) from S&P Global. The index declined from 52.8 in May to 50.3 in June, its lowest since January and just above the 50.0 mark that separates growth from contraction. “Although recording an expansion of output for a sixth consecutive month in June, the latest increase was only marginal and far weaker than the gains seen in the previous four months to signal a considerable loss of growth momentum,” S&P Global said.

Factory output fell for a third straight month and at the fastest rate since last October. Services sector output growth slowed sharply as the recent resurgence in spending on services lost momentum. Expectations for the year ahead deteriorated markedly in manufacturing, down to a seven-month low in June, but also sunk to a six-month low in the services sector.

US manufacturing activity falls

Data painted a similarly sombre picture of the US manufacturing sector. S&P Global’s flash manufacturing PMI fell from 48.4 in May to 46.3 in June, a six-month low and well below estimates. The decline was the most severe in 2023 to date and stemmed from a marked reduction in new orders. The report also showed that cost pressures eased, as suppliers sought to boost their sales and offer reduced prices. The pace at which input prices fell was the quickest since the pandemic lockdown in May 2020.

Japan core CPI rises to 3.2%

In Japan, consumer inflation rose by more than expected in May. The core CPI, which excludes fresh food prices, rose by 3.2% in May from a year ago. This was lower than the previous month, but was above forecasts and well above the Bank of Japan’s 2.0% target. The ‘core-core’ index, which strips out fresh food and fuel, rose to 4.3% in May, the highest reading since 1981. The data has increased expectations that the Bank of Japan will increase its inflation forecasts at its quarterly review in July. The jury is out on whether it will tweak its yield curve control policy.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

28th June 2023

Team No Comments

Brooks Macdonald – Weekly Market Commentary

Please see this week’s Weekly Market Commentary from Brooks Macdonald detailing the latest economic and market news:

This weekend’s mutiny in Russia is likely to create further regional instability over the short and medium term

After a poorer week for equity performance, market attention quickly shifted to events in Russia over the weekend which will likely herald further political instability in Russia over the medium term. In terms of near term implications, this could either lead to President Putin escalating the Ukraine war to re-establish authority or leave a void which Ukraine may be able to utilise.

Friday’s US PCE inflation release will be watched for signs of a further easing in US price pressures

This Friday sees the release of the US Personal Consumption Expenditure (PCE) inflation which is released alongside a broader set of personal income and consumption data. The PCE data is preferred to the Consumer Price Index (CPI) data by the US Federal Reserve (the Fed), in part because it assumes a degree of substitution if one good or service surges in price. The core PCE reading (excluding food and energy) is expected to stay flat at 4.7% while the headline PCE reading is expected to fall from 4.4% to 3.8%. Given the importance of inflation expectations to the path of US interest rates, this will be closely watched as will the personal income and consumption components which will guide markets as to how long the current pace of US consumption can continue.

Eurozone core CPI is expected to rise on Friday however the headline CPI rate should see significant falls

This week also sees the European CPI releases, with Italy starting the country-level releases on Wednesday before Friday’s Eurozone data. In terms of the Eurozone data, the market expects Core CPI to rise from 5.3% to 5.5% and for the headline to fall from 6.1% to 5.6%. With this the last CPI number ahead of the July European Central Bank (ECB) meeting, this report will have significant implications for Eurozone interest rate policy.

The annual US bank stress test results are also due on Wednesday and will be of interest to the market given the regional banking crisis earlier in the year. The tests will include a ‘severely adverse scenario’ which will model a severe global recession combined with a sell-off in real estate and corporate debt markets. While the regulator will be keen to avoid further lack of confidence in the banking sector through banks failing the stress tests, the tests will need to be sufficiently tough to retain credibility.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

27/06/2023

Team No Comments

Tatton Investment Management: Monday digest

Please see the below article from Tatton Investment Management providing their regular Monday update on the financial markets. Received today – 26/06/2023.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment firms.

Adam Waugh

26/06/2023

Team No Comments

Global central bank decisions reflect distinct differences in their economies

Please see the below article from Invesco regarding the weeks Central Bank news:

Last week was a big one for monetary policy, with four major central banks rendering policy decisions. Their decisions reflect the fact that their respective economies are in very different places.

The Federal Reserve holds steady for now

The week started with the US Federal Reserve (Fed) holding rates at current levels. But it was a decidedly hawkish pause, with the Fed suggesting more rate hikes could be coming soon. The Summary of Economic Projections – known as the “dot plot” – showed that the Fed anticipates two more rate hikes this year. This is borne of concerns that core inflation is too sticky – the Fed revised up its projection for core inflation and revised down its projection for unemployment for the end of the year. Now the dot plot is just each member’s policy prescription — it can be very wrong at times, and it can change significantly over time. You may recall that the dot plot released in December 2021 forecast a median fed funds rate of 0.90% by the end of 2022. The Fed couldn’t have been more wrong, as the fed funds rate ended 2022 in the 4.25% – 4.50% range.

And so markets seemed to shrug off this development, even though Fed Chair Jay Powell shared during his press conference that “nearly all” committee members expected further rate tightening in 2023 would be necessary to bring down inflation. My read on this hawkish dot plot and Powell’s hawkish words is that they’re intended to stop the market from assuming there will be any rate cuts this year and keep financial conditions from easing. The Fed wants to keep inflation falling – and prevent any reacceleration.

The Fed is faced with a resilient US economy, one that seems to be handling the aggressive tightening cycle very well. The labor market remains surprisingly tight, which could mean that inflation remains stubbornly high. And so the Fed is comfortable with a hawkish pause and the ability to hold further tightening — that “sword of Damocles” — over markets.

Having said that, if the Fed does tighten two more times this year, I believe it really risks overkill – sending the economy into a significant recession. I’m sounding like a broken record, but I’ll say it again: There is a lengthy lag between when monetary policy is implemented and when it actually shows up in the real economy data, which Powell acknowledged in the press conference. We haven’t seen much of an impact yet because of that lag. That’s why we have to worry so much about overkill. I believe today’s Federal Open Market Committee (FOMC) should heed the words of then-San Francisco Fed President Janet Yellen, who shared the following thoughts during the May 2006 FOMC meeting:

“I strongly favor a pause in our campaign in order to evaluate the effect of our policy actions to date, unless incoming data after this meeting contain large upside surprises….I do certainly understand the urge to continue raising rates at every meeting until we’re sure the economy is slowing. I still remember very well the 1994 tightening episode, and then, as now, there was a sense of great momentum in the economy, posing significant upside risks to inflation. In circumstances like that, the urge to continue tightening is natural. It is instinctual. Unfortunately, with policy lags such a strategy is a sure recipe for overshooting. If we’re lucky enough to stop at exactly the right point this time, as I believe we actually did in ‘95, we can be sure that it will feel risky at the moment we stop and wise only in retrospect. The risks for policy, in my view, are now two-sided…”

The European Central Bank continues to hike

The European Central Bank (ECB) hiked rates last week with more to come, which I believe is appropriate. The eurozone economy is in a different place than the US economy. The ECB started hiking rates later and has not been as aggressive. In particular, the ECB stuck with the transitory inflation philosophy even longer than the Fed or Bank of England.

It turned out demand was very strong on reopening in the eurozone. Plus, European governments, such as the UK, in effect supported both household and business spending by insulating their economies from the energy price shock with price controls and budgetary subsidies. The result was that eurozone (and UK) consumption and business spending have been stronger than expected, and inflation has been higher than expected. Hence it is no surprise that ECB President Christine Lagarde made it clear that there is more work to be done.

The Bank of Japan stays patient

The Bank of Japan (BOJ) maintained its ultra-accommodative monetary policy at its meeting last week and said it would continue to “patiently” maintain this policy. This surprised some given that Japan has experienced higher-than-expected inflation in the past year and that the BOJ upwardly revised its expectations for employment and household income.

Japan is an outlier among major developed economies. It’s experiencing its strongest economic growth in decades, and the BOJ may not want to prematurely extinguish it. Not surprisingly, the Japanese yen fell in response. I suspect the BOJ will need to implement some tweaks to its yield curve control policy in coming months or quarters, but it seems willing to keep its key policy rate lower for longer, tolerating the risks of elevated inflation since it is something of a welcome curiosity for an economy that has been in the doldrums for multiple decades.

The People’s Bank of China seeks to enable economic growth

Then there is the People’s Bank of China, which actually increased monetary policy accommodation while much of the world is tightening. This makes sense. I believe the economic recovery has long legs. But I also recognize that disappointment with recent economic data has triggered a growing view that China may not have provided enough stimulus during the pandemic relative to other major economies and that its economy could benefit from more stimulus now. The People’s Bank of China is lowering policy rates to help goose the nascent economic recovery.

Up next: The Bank of England

Another major monetary policy decision — from the Bank of England (BOE) — is coming this week. The BOE is between a rock and a hard place as the UK experiences a weak economy plagued by high inflation – though it has to be said that UK growth has proven more resilient than most everyone expected (including the BOE itself).

I expect the BOE to hike rates even though that would hurt UK households who are already suffering from higher mortgage rates. With Prime Minister Rishi Sunak’s government saying it will not provide fiscal help to these households, the BOE — similar to the Bank of Canada, which hiked rates earlier this month — risks hurting the economy more than it helps in its attempts to combat inflation.

Having said that, the BOE probably has the strongest case of any of the major developed market central banks to tighten more aggressively and for longer than had been expected. Inflation is high, and the UK needs the BOE to get a grip on it. This is likely better for gilts and sterling than for UK equities in the shorter term, as UK consumers may well feel the pinch on both real incomes and mortgage payments from high inflation and interest rates.

Investors react to these developments

Taking a step back, the general mood among US investors is becoming more positive. There is a realization that the US is at or very close to the end of its tightening cycle, and the economy has remained resilient – especially the labor market.

US high yield credit spreads have narrowed in recent months, suggesting a greater likelihood of a softer landing for the US economy, which should be positive for the global economy. And, reflecting a growing sense of investment FOMO — the fear of missing out — the most recent American Association of Individual Investors survey shows the widest bullish-bearish spread since November 2021. Monetary policy matters, and it’s generally becoming more supportive of risk assets.

Other investors are not as positive. For example, the Eurozone Sentix Investor Confidence reading has been pessimistic for some time, clocking lower in the last two weeks. A contributing factor is likely the ECB’s hawkish monetary policy stance. In addition, a lot of negative sentiment is likely priced into Chinese equities already, and they are trading at the low end of their historical valuation range, despite more monetary and fiscal stimulus in the offing.

Negative sentiment presents opportunities. There should be a growing realization that it is not just the US – that other major Western developed central banks are at or nearing the end of their tightening cycles while the Bank of Japan and the People’s Bank of China are maintaining or increasing their accommodative monetary policies. I believe this is a time to be looking for attractively valued assets with upside potential for the next year and beyond.

Comment

We now know the Bank of England’s MPC decision to increase the base by 0.50% to 5%. The UK is in a difficult position with inflation holding steady at a higher than anticipated level.

The focus will remain on Central Bank policy decisions and the data that will influence these.

Steve Speed Dip PFS

23/06/2023

Team No Comments

Evelyn Partners Update – June Bank of England MPC decision

Please see the below article from Evelyn Partners commenting on The Bank of England’s decision to raise the base level of interest rates by 50 basis points to 5.0%. Just received – 22/06/2023.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Adam Waugh

22/06/2023

Team No Comments

EPIC Investment Partners – Daily Update: UK Inflation Shock

Please see the below article from EPIC Investment Partners providing their Daily Update on the UK Inflation Shock. Received yesterday 21/06/2023.

UK inflation surprised to the upside for the fourth month in a row this morning, increasing the pressure on the Old Lady to accelerate interest rate hikes. CPI rose 8.7%yoy last month, the same as April and well above the 8.4%yoy eyed, with the month-on-month printing 0.7%, again above the eyed 0.5%, although this was lower than the previous of 1.2%.

However, core inflation, which strips out food and energy prices, accelerated to 7.1%yoy, again well above economists’ expectations of 6.8%yoy, to the highest level since the year Basic Instinct was released. This will be of particular concern to the BoE, as core inflation, one of the measures closely watched by the committee, continues to soar as other countries start to see it fall.  

The Office for National Statistics said in its statement following the release: “Rising prices for air travel, recreational and cultural goods and services, and second-hand cars resulted in the largest upward contributions to the monthly change in both the CPIH and CPI annual rates”. It went on to add: “Live music events and computer games also contributed to inflation remaining high. These were offset by a fall in the cost of petrol. Food price inflation also remains high, but the rate has eased slightly.”

We got the obligatory two-pennies-worth from the Chancellor, who said: “If you look at what’s happening in other countries, you can see that rises in interest rates do bring down inflation over time. That will happen here, but we need to be patient, we need to stick to the course and then we’ll get to the other side”.

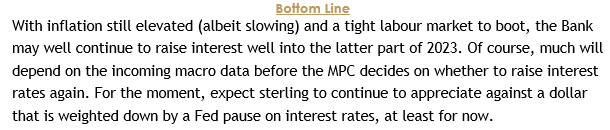
So, now attention turns to the BoE tomorrow. After 12 consecutive hikes, a 25bp rise is already nailed on. However, the market is now pricing in a 50% chance of a 50bp hike, and currently pricing an interest rate peak of 6% by December.

In a separate report, the ONS revealed that the government debt has now exceeded 100% of the GDP, marking the first time this has occurred since 1961. The government borrowed GBP20bn in May, beating forecasts. The deficit for the month, the second highest since modern records began in 1993, rose from GBP9.4bn last year. The increase was driven by cost-of-living payments, including energy subsidies and higher staff costs.

Rishi Sunak’s promise to restore health to public finances and cut inflation looks increasingly like a pipe dream.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

22/06/2023

Team No Comments

Stocks rise after Fed skips rate hike in June

Please see below ‘Markets in a Minute’ article received from Brewin Dolphin yesterday afternoon, which provides a succinct but detailed global market and economic update.

Most major stock markets rose last week after the US Federal Reserve refrained from raising interest rates in June.

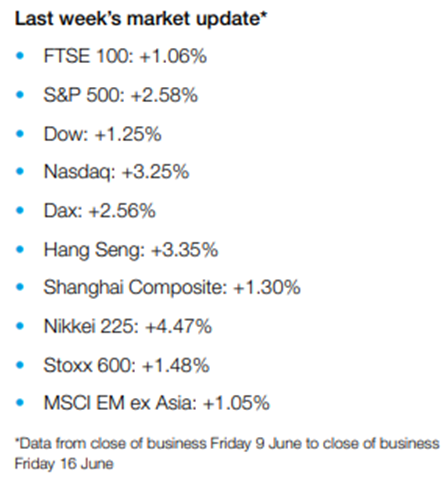
In the US, the S&P 500 enjoyed its longest stretch of daily gains since November 2021 and finished the week up 2.6%. The Nasdaq and the Dow added 3.3% and 1.3%, respectively, after a notable easing of US inflation also helped to boost investor sentiment.

Stock markets in Europe also rallied, with the Stoxx 600 and Germany’s Dax up 1.5% and 2.6%, respectively. The FTSE 100 gained 1.1% following a rebound in UK gross domestic product (GDP) in April.

In Asia, the Nikkei 225 surged 4.5% to its highest level in over three decades after the Bank of Japan chose to leave its ultra-loose monetary policy unchanged. The Shanghai Composite and the Hang Seng rallied 1.3% and 3.4%, respectively, after the People’s Bank of China cut a key policy rate for the first time in ten months.

UK house prices cool

Stock markets finished in the red on Monday (19 June) as investors took profits following last week’s rally. The FTSE 100 fell 0.7% and the Stoxx 600 lost 1.0% in a quiet day for trading. US indices were closed on Monday to mark the Juneteenth national holiday.

In economic news, Rightmove’s house price index showed average new seller asking prices slipped by £82 in June from the previous month. While this was a very small decrease (house prices were flat in percentage terms), it was notable in that it was the first monthly decline so far this year, and the first for this time of year since 2017. Rightmove said the recent significant increases in mortgage rates hadn’t affected buyer demand yet, but were creating “renewed disruption and uncertainty among movers trying to calculate how much they can afford to borrow and repay”. In the last four weeks, the average mortgage rate for a five-year fixed 85% loan-to-value mortgage has jumped from 4.56% to 5.20%.

Fed leaves interest rates unchanged

Last week saw the US Federal Reserve vote unanimously to skip an interest rate increase in June and instead hold the federal funds rate at the target range of between 5.00% and 5.25%. This was the first time the Fed had kept rates unchanged since March 2022. Fed chair Jerome Powell said it was a prudent move given “how far and how fast we’ve moved”.

However, Powell also signalled that further rate hikes are on the cards this year. He said the meeting next month would be a “live” one, which has been interpreted as meaning the Fed is likely to raise rates by 0.25 percentage points on 26 July.

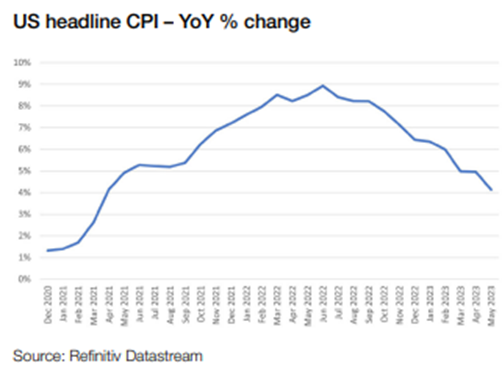
The Fed’s decision came a day after the Labor Department issued its latest consumer price index (CPI) report. Headline inflation eased to 4.0% year-on-year in May, down from 4.9% in April and the slowest annual pace since March 2021.

On a monthly basis, prices rose by just 0.1% after increasing by 0.4% in April. However, core CPI – which excludes food and energy – rose by 0.4% for the third consecutive month.

ECB increases rates to highest level in 22 years

The European Central Bank (ECB) also met last week and decided to increase its key deposit rate by a quarter of a percentage point to 3.5%, the highest in 22 years. ECB president Christine Lagarde said another rate hike in July was “very likely” and that the ECB was “not thinking about pausing”. In a statement, the ECB said that while inflation was coming down, it is projected to remain “too high for too long”.

Despite seeing an easing in inflation, the ECB increased its forecast for core inflation for 2023 to 5.1%, up from 4.6% previously. This was mainly due to wage increases – average wages grew by 5.2% in the first quarter compared with a year ago. Meanwhile, the eurozone economy is expected to grow by 0.9% this year and 1.5% in 2024, down from the ECB’s previous estimates of 1.0% and 1.6%, respectively.

Bank of Japan sticks to ultra-low rates

The week ended with another major central bank meeting – this time at the Bank of Japan (BoJ). Although inflation in Japan has proved stronger than expected, the BoJ chose to maintain its -0.1% short-term interest rate target and a 0% cap on the ten-year bond yield set under its yield curve control policy. The bank reiterated its view that inflation will slow later this year.

“The bank will patiently continue with monetary easing while nimbly responding to developments in economic activity and prices as well as financial conditions,” it said. “By doing so, it will aim to achieve the price stability target of 2% in a sustainable and stable manner, accompanied by wage increases.”

UK economy returns to growth in April

The UK economy returned to growth in April, with GDP expanding by 0.2% month-on-month after contracting by 0.3% in March, according to the Office for National Statistics. This was driven by an increase in car sales and customer spending in pubs and bars. The rise in activity was partly offset by junior doctors’ strikes, which held back health sector output.

The return to growth has added to expectations that the Bank of England will raise interest rates for the 13th time in a row when it meets on Thursday. It has also raised hopes that the UK will avoid a recession this year. Earlier this month, the OECD upgraded its economic growth forecasts for the UK. It expects GDP to grow by 0.3% this year and 1.0% in 2024, much better than its previous forecasts of a 0.2% decline in 2023 and a 0.9% rise in 2024. Nevertheless, all the other economies in the G7 apart from Germany are expected to grow at faster rates this year.

Please check in again with us soon for further relevant content and market news.

Chloe

21/06/2023