Team No Comments

EPIC Investment Partners – The Daily Update – BoJ Rate Hike? / Fed Members Tow The Party Line

Please see today’s daily update from EPIC Investment Partners below:

Bank of Japan Board Member, Hajime Takata, has signalled there is a growing case to end Japan’s negative interest rate policy, with the BoJ’s goal of achieving 2% inflation “finally in sight”. “With monetary easing continuing, I believe we have reached a point where attainment of the 2% price stability target is finally in sight, despite uncertainty over the Japanese economy”, Takata said, adding “It is necessary to consider shifting gears from extremely powerful monetary easing, and how we should respond nimbly and flexibly toward an exit. 

Takata’s remarks, who is seen as a neutral on the nine-member board, will fuel speculation that the Bank of Japan may be preparing for its first rate rise in 17 years. However, Takata did not provide specific timing for any such increase, meaning the next BoJ meeting in March will be even more closely watched. 

 After Takata’s remarks, the yield on the policy-sensitive 2-year notes rose 1.5bps to 0.175%, the highest level since the War Horse film was released. 

We also heard from a number of Fed members overnight, all of which continued to tow the party line, leaning towards hawkish patience.   

Collins said that January’s CPI was an example of uneven inflation progress and that she wants to see more evidence of inflation stability. However, she did say that it’s unlikely the inflation decline can be sustained without slower growth. Bostic said that he expects inflation to continue its trajectory to 2%, although he is comfortable being patient on policy.  

Lastly, Williams said that he expects this afternoon’s PCE inflation number, the Fed’s favoured inflation indicator, to be around 2-2.25% in 2024 and at 2% by 2025. He said that the Fed could think about cutting rates later this year and that three rate cuts in 2024 is a “reasonable starting point”.     

Happy 29th February. 

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Charlotte Clarke

29/02/2024

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below today’s ‘Daily Investment Bulletin’ from Brooks Macdonald, which was received this morning – 29/02/2024:

What has happened

Both Equity markets and Bond markets were relatively quiet yesterday, with the focus being on the  US inflation data due to be released later today. It was also a relatively light day in terms of data releases with the main data being the very modest downgrade to US GDP growth in Q4, with the second estimate coming in at an annualised +3.2% (vs. +3.3% first estimate).

Markets very much focussing on the PCE Inflation release today

Recent US CPI and PPI data releases have surprised marginally to the upside, and some of the components of these that filter into the Fed’s preferred measure of inflation mean expectations exist for a slight increase for today’s data. Bloomberg states survey data showing a month on month increase of 0.4% for Core PCE. This would be the largest monthly increase since Feb of last year. Ahead of this data, we have seen expectations of rates cut from the Fed being pared back and comments yesterday from a couple of Fed members alluded to the higher for longer approach. Boston Fed President Collins said that it “will likely become appropriate to begin easing policy later this year”, but also that “I want to see more evidence of a sustained trajectory to price stability”. Separately, New York Fed President Williams said that they still had “a ways to go on the journey to sustained 2% inflation”.

What does Brooks Macdonald think

Coming into 2024 at our January AA meeting we felt markets were probably over-pricing Fed easing and during the first 2 months this has been reflected in a shift to a more realistic pricing for the trajectory for US interest rates. Whilst we do believe we have likely seen peak rates in the US, we remain cognisant the path to target inflation may be bumpy and not in a straight line. As such, and along with a resilient economy (despite the small revision to q4 GDP),  there remains scope for periods where inflation may surprise to the upside, but these should not derail the view that the next move from the Fed will be to lower headline rates.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

29/02/2024

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update from Brewin Dolphin, which was received late yesterday afternoon:

Guy Foster, Chief Strategist, discusses earnings results from the Magnificent Seven and how these microeconomic factors are affecting the markets.

One topic dominated markets last week: Nvidia’s earnings announcement. It was one of the most anticipated and celebrated events in the market this year.

The shares, which were cyclically depressed at the start of 2023, went to triple in value by the end of the year and have risen another 50% since then. In the week before announcing its profits, Nvidia’s shares slid by nearly 9% as some investors feared that others were expecting too much. Memories of the technology stock market bubble of a quarter of a century ago loom large.

But Nvidia is far from the profitless companies offering jam tomorrow in the late 1990s. Nvidia’s results revealed revenues rising 22% over the preceding quarter, and 200% from the same period last year, with profits up 8x.

As with all stocks, the controversy surrounds what will happen in the future. The pipeline for artificial intelligence-related sales remains very attractive, but unlike the technology bubble, those expectations are grounded in exceptional growth happening right now.

We believe semiconductors are in a cyclical upswing that forms part of a secular uptrend. Individual companies can be volatile, but the supply chain comprises a number of different types of company serving different parts of the value chain, whose long-term trajectory should be positive, even while different factors move them in the shorter term.

Last week felt like Nvidia was singlehandedly pulling the market around, but what else was going on?

Back in the real world…

The purchasing managers indices (PMIs) offered an early snapshot of economic activity in February, painting a mixed picture.

In keeping with other data released so far this year, the US continues to look economically firm. The manufacturing and services sectors both seemed to expand at an accelerating pace. It makes sense to be a little wary of extrapolating the current trend too far. With unemployment so low there is limited room to expand employment, driving increased household income and spending. However, there still seems to be at least some scope because initial jobless claims for the last week declined. This leaves them very low, at levels consistent with a strong economy, although things can change fast.

Outside the US, PMIs were more mixed. European manufacturing remains in a slump and while France showed signs of early stages of recovery, Germany seemed to regress. Outside of these core economies, the peripheral eurozone members performed better – we just won’t know how much better until the end of the month as they don’t release provisional reports like the core countries.

Inflation benign?

Perhaps worryingly, selling price pressures rose during the month. We can take some comfort from the fact that price data from PMIs don’t correlate very well with consumer price indices. However, they suggest that for the services sector at least, the tight labour market is making it difficult to hold wages down. If other data backed these up, it could be difficult to cut interest rates as fast as the market has been hoping.

Interestingly, the price pressures are quite limited to services while disinflation seems to continue within manufactured goods. This is where we would expect to see the impact of higher freight rates emanating from the Red Sea (or, more accurately, from the Cape of Good Hope, around which Red Sea freight has been diverted). The Red Sea is an important transit route for Middle Eastern oil and Southeast Asian goods en route to Europe.

Freight rates are clearly continuing to rise but in Europe’s biggest economies, impact is outweighed by weak demand. This partly reflects the fact that freight is often transported on long-term contracts, which are less vulnerable to movements in spot freight rates.

China stimulus

China and Europe have a substantial bilateral trade balance, but both are currently labouring some.

In China, decades of overinvestment in property, which had become the principal vehicle for the wealthy, has resulted in chronic oversupply. Bursting that bubble became a priority for Xi Jinping’s Chinese Communist Party, but doing so has resulted in a persistent negative wealth effect (declines in the value of property make Chinese consumers feel poorer).

In an attempt to revive fortunes, China cut the loan prime rate for terms of greater than five years. This is essentially the rate which underpins mortgages and therefore serves as a stimulus for Chinese property. This morning’s data from China’s National Bureau of Statistics showed how important that could be, as property prices have continued to decline over the last month.

The slight green shoot of recovery that might be showing is the breadth of price declines may have narrowed. In December, 62 out of 70 cities saw prices for new properties decline, whereas in January that was just 56. Prices of existing properties fell in all 70 cities in December, whereas two saw an increase in January.

There is clearly a long way to go before this becomes a positive trend, and the risk remains that policy will not be able to turn around a sector so distorted by successive stimulus rounds and captive savings over decades. But at least policy is becoming more forceful in its attempt to support the sector.

Tax cuts

Finally, some good news came from UK public finances.

After strong tax receipts, it seems the government will borrow less than had been anticipated by the Office for Budgetary Responsibility. This means we can anticipate the unveiling of tax cuts potentially up to £10bn in the forthcoming budget. This is an enormous number that is difficult to put into context. It would be around half the tax cuts that took place at the beginning of this year after the autumn statement.

Recognising how much ten billion pounds is might also help to appreciate the scale of the market’s response to Nvidia’s earnings announcement. The company’s market value rose by more than 20 times that much on the day ($277bn, which is a record daily change in value for a single company)!

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

28/02/2024

Team No Comments

AJ Bell – Why the sinking Yen is a big market story

Please see the below article from AJ Bell detailing their insights into the depreciation of the Yen and its potential effect on markets. Received 26/02/2024.

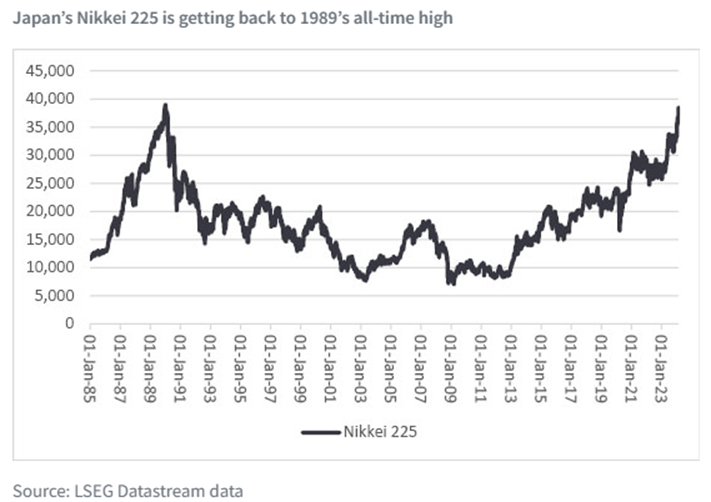
The world’s biggest stock market by market capitalisation, America, is making headlines as it sets new all-time highs and the second-largest arena, China, is making them for the wrong ones, as the Shanghai Composite index is no higher now than it was in 2007, thanks to a soggy economy and a spectacular property bust. But perhaps the biggest surprise to many advisers and clients will be the renaissance of the world’s third most valuable market, Japan, where the Nikkei 225 is on the verge of regaining the all-time high set all the way back in late 1989.

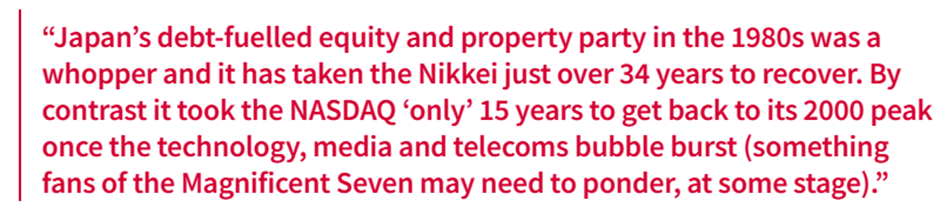
  • The bigger the bubble, the bigger the hangover is likely to be. Japan’s debt-fuelled equity and property party in the 1980s was a whopper and it has taken the Nikkei just over 34 years to recover. By contrast it took the NASDAQ ‘only’ 15 years to get back to its 2000 peak once the technology, media and telecoms bubble burst (something fans of the Magnificent Seven may need to ponder, at some stage).
  • Even the most unloved market can return to favour. Perhaps something to ponder in the context of the UK and emerging markets, which remain out in the cold.
  • Valuation really does matter. Strategists regularly flagged Japan as being extremely cheap, especially on the basis of book value (where a big chunk of the net assets was made up of net cash positions) and eventually that value has attracted buyers as catalysts have emerged to crystallise it, in the shape of the Abenomics reforms, activist investors and improved corporate governance (something the UK should consider as it considers watering down some of its listing requirements).

But there are other factors at work, which may have implications for global markets and not just those in Tokyo, namely the Bank of Japan’s ongoing use of ultra-loose monetary policy and the continued decline in the yen.

With its heavy weightings toward information technology (26%) and industrials (17%), the Nikkei 225 taps into the key themes of artificial intelligence and deglobalisation, and Japanese firms may be primed to benefit from sanctions against China as a valuable alternative source. A low weighting toward financials (3%) is also noteworthy, as banking stocks in the USA and UK continue to flounder.

But Japan also has things in its favour, which may be lacking elsewhere, notably:

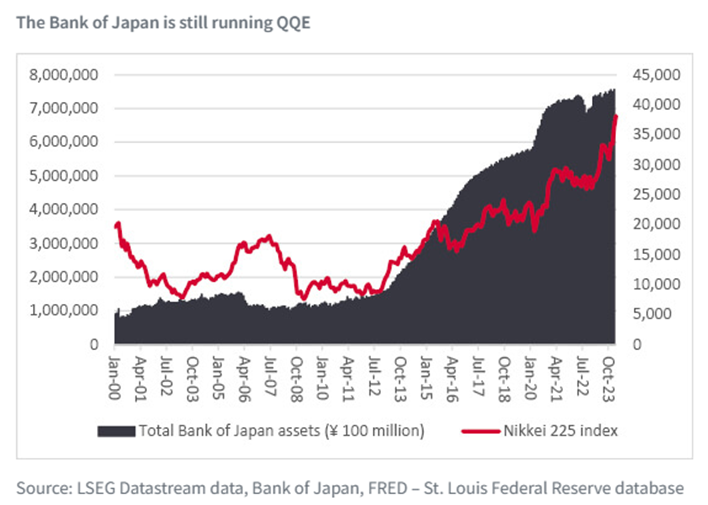
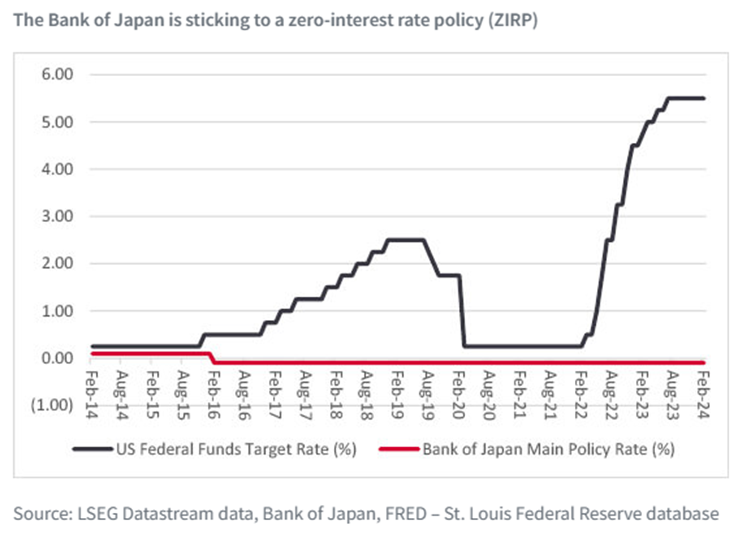
A central bank which remains committed to ultra-loose monetary policy, in contrast to those in the West. While the US Federal Reserve, European Central Bank and Bank of England have jacked up interest rates and started to shrink their balance sheets, the Bank of Japan has stuck with a negative interest rate since 2016 and continued to run a Qualitative and Quantitative Easing (QQE) bond-buying scheme, designed to suppress bond yields and borrowing costs and pump liquidity into Japan’s economy and financial system.

A currency that continues to slide. The yen is back down to ¥150 to the dollar, pretty much an all-time low. This helps to attract overseas buying (as the cheap currency is an added bonus on top of what may be cheap stocks) and boosts exporters at the same time (like those technology and industrial companies in which Japan specialises).

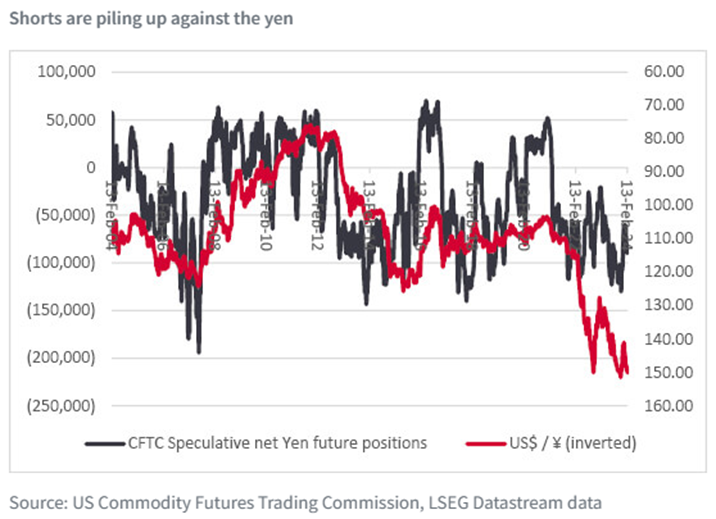
One reason for the yen’s weakness is the interest rate differential between the greenback and the Japanese counter. But another is how international investors (and particularly hedge funds) use the yen as a funding currency for other positions. It costs nothing to short the yen, given the negative interest rate that prevails in Japan, and that cheap cash can be used to generate returns elsewhere (or so the theory goes). Data from America’s Commodity Futures Trading Commission (CFTC) shows that short positions are again piling up against the yen.

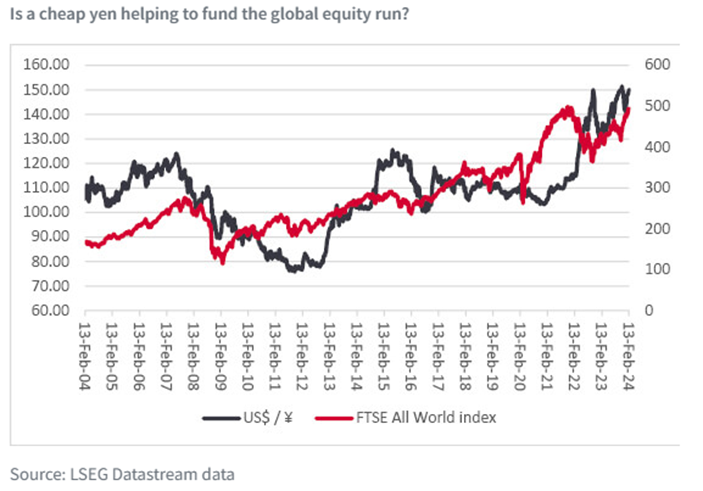
It may therefore not be entirely a coincidence that global equities are surging along, buoyed by the USA, which represents some 60% of the FTSE All-World index. Other factors are helping here, too, notably Bidenomics and free-spending fiscal policy, but a plentiful supply of cheap funding might be helping, too.

This matters because the Bank of Japan is, in theory, inching its way towards a first interest rate hike, just as the western central banks are laying the groundwork for their first cuts. A reduced interest rate differential could spark buying of the yen, prompt a closure of short positions against it and turn off the tap on one important source of global liquidity. Watch this space.

Past performance is not a guide to future performance and some investments need to be held for the long term.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Clare

27/02/2024

Team No Comments

Tatton Investment Management: Monday Digest

Please see below, Tatton Investment Management’s ‘Monday Digest’ providing a brief analysis of global economic news and markets data. Received this morning – 26/02/2024

M&A activity sets growth against value 

Equities moved higher again last week, with gains made across global markets. Even China put in another week of positive returns following the largest ever cut to the five-year housing loan prime rate (admittedly only 0.25%). Government bonds fared less well, with yields rising slightly after a small rebound in general economic growth optimism. Corporate bonds did better, with yields broadly unchanged, on the back of that optimism of credit risks likely to recede even further.

Last week, some of the data releases reinforced the previous week’s pessimism about the potential for near-term UK economic growth, with GfK’s Consumer Confidence Index falling from -19 to -26 in February. And yet… UK business confidence has been picking up. February’s interim ‘flash’ Purchasing Manager Indices (PMIs) estimates showed services doing particularly well, with manufacturing less well but still better than January. The PMIdata is definitely welcome news, with companies getting more positive on their outlooks and therefore on their hiring and business investment intentions. Overall, for the rise in optimism to be maintained, we think rate cuts in relatively short order are still needed on this side of the Atlantic. The good news is that China may well be starting to show more optimism as well. We will get its PMI data at the start of March.

Elsewhere, the talk in markets was all about merger and acquisition (M&A) activity, which tells us about a gradual shift in investment sentiment. In the UK, electricals retailer Currys received a cash bid (ultimately rejected) from activist investor Elliott Partners. Chinese retail internet platform JD.com said it would bid as well, although there are yet to be any details. Meanwhile, in the US, credit card company Capital One announced an all-share agreed offer for Discover Financial Services, another credit card and payment system company. At $35 billion, this deal would easily be the largest of the year so far.

M&A activity has interesting implications for investors. Here at Tatton, we leave the business of picking particular shares to our selected fund managers. Since the start of 2023, ‘quality growth’ companies have been the clear winners, both in revenue and profit performance and in share price valuation terms. Now though, rising M&A activity could mean that investors will start to look for value.

Into the Questverse: Is AI analysis changing market patterns?

According to JP Morgan Research’s February ‘Questverse’ report, the most central investment themes right now are artificial intelligence (AI) and inflation. This will surprise no one, but a notable thing about this observation is that it came from an AI program itself. JPM’s Questverse uses a natural language processing model along with machine learning. It does so in a rather complex way, but the basic premise is that the program tries to recognise patterns in large datasets. The program’s architecture means it is very good at recognising patterns. Therefore, it is no surprise that the Questverse system can detect investment themes and their prominence more consistently than a human.

JPM is far from being the only company applying AI to investment information or decisions. In fact, many of the AI investment programs currently in use are not that different to programs that have been around for many years – high-frequency trading (HFT) for example. But when it comes to using those themes in investment decisions, on their own they give no information about underlying value. Discerning themes and trends might give you some hint about whether an asset’s price is going to go up or down, but they give you no sense of the asset’s fundamental value. We wrote last week about asset bubbles – and ironically the current bubble talk is all about AI stocks – which are defined as instances where an asset’s price systematically deviates from its fundamental value. If everyone is looking for price patterns and not value, bubbles are more likely – and hence, so are sharp unpredictable corrections.

Of course, humans are just as susceptible to feedback loops as machines. But machines are able to process massively more amounts of information several times quicker than any human – meaning the feedback effects can be much larger and sharper. This is exactly the criticism regulators and campaigners have made against HFT programs for years – demanding that regulation be brought in to address growing problems. That brings us tothe question of what should be done. Clearly, the AI genie cannot go back in the bottle, and it would be foolish to try and stop the use of AI investment tools. What we can do – as with any investment strategy – is to better educate ourselves on the risks involved. Ideally, this would be mirrored at the regulatory level too. Without it, ever-bigger feedback loops and sharper price movements will likely be a feature of markets under the influence of AI.

Uranium prices go nuclear

Uranium is in a bull market. Triuranium octoxide – also known as ‘yellowcake’ uranium – cost $87 per pound at the start of this year, but has risen to $103 at the time of writing. If trading carries on like this, we will edge closer to the astonishing peak seen before the Global Financial Crisis of 2008.

As the only source of fuel for nuclear fission reactors, uranium is and has long been a vitalcommodity. Moreover, nuclear power’s inevitable role in the global energy transition away from fossil fuels is clearly acknowledged by politicians and, in many instances, is being backed up by strategy and investment. At last year’s COP28 summit, 22 countries, including the US and UK, pledged to triple nuclear energy capacities by 2050. This global structural push inevitably means more uranium demand, at least in the future. But perhaps there are other factors driving prices in the near term. One reason might be the strategy of ‘fast investors’ capitalising on a flaw in how utility companies structure their contracts. Utility companies often secure supplies with longer-term contracts with producers. These contracts often peg the price to the spot market at the time of delivery, plus a premium. This makes sense when utility companies expect falling – rather than rising – prices going forward. Fast investors have tightened spot market conditions and now a demand surge has put a ‘short squeeze’ on the utility companies.

Fortunately, the potential physical supply of uranium – the amount it is actually possible to mine and enrich – is not a problem in the long term. There are plenty of mines and potential deposits throughout the world. However, near-term supply and demand is tighter, and geopolitics is clearly involved. Crucially, the uranium price squeeze is likely to be short term and will not stop the transition to nuclear energy – or the broader decarbonisation strategy of which it is a part.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

26th February 2024

Team No Comments

The Daily Update | FOMC Minutes and Icelandic Authors

Please see below article received from EPIC Investment Partners this morning, which reviews the FOMC minutes from the January 30/31 meeting.

The FOMC minutes from the January 30-31 meeting revealed little on monetary policy direction. The minutes reiterated the Fed’s intention to wait for “greater confidence” in inflation moving sustainably towards a 2% target and emphasised the need for patience. Only a “couple” of officials seemed inclined to cut rates earlier due to the current restrictive policy stance compared to their colleagues.  

The minutes stated: “Most participants recognised the dangers of easing policy too hastily and stressed the need to carefully evaluate incoming data to determine if inflation is consistently moving towards 2%. However, a couple of participants highlighted the economic risks of maintaining a too restrictive policy for an extended period”. This was echoed in the press conference when Powell was asked about the possibility of a March cut: “that’s probably not the most likely case or what we would call the base case.”  

Furthermore, the minutes highlighted the progress towards the Fed’s dual mandate but cautioned that economic uncertainty could jeopardise this progress. “Members judged the risks to achieving the Committee’s employment and inflation goals were moving into better balance. Members considered the economic outlook uncertain and concurred that they were highly attentive to inflation risks.”  

Regarding inflation, the minutes detailed several risks, noting that the committee “saw inflation’s upside risks as diminished” but observed that inflation remained above the Committee’s longer-term goal. Some participants worried that progress towards price stability might halt, especially if demand increased or the healing of the supply side slowed more than anticipated. However, they also noted downside risks to inflation and economic activity, including geopolitical risks that could significantly reduce demand, potential adverse effects from slower growth in certain foreign economies, the risk of prolonged restrictive financial conditions, or the impact of weaker household balance sheets on consumption deceleration more than expected.   

Lastly, if you have ever thought about writing a book and want to be around like-minded people, then Iceland is your place. About one in 10 Icelanders publishes a book in their lifetime; by comparison, in the US only one in 5,000 have. The average Icelander reads more than two books a month. Remarkably, a blockbuster title can sell as many as 14,000 hardback copies in a country with a population of just 375,000. One reason for the prolific writing could be the country’s ancient storytelling tradition, going back some 800 years to the Icelandic sagas.   

Or it could just be needing something to do during those long 21-hour winter nights.   

Please check in again with us shortly for further relevant content and market news.

Chloe

23/02/2024

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update following Nvidia’s earnings announcement.

What has happened

The market saw a surge of optimism, largely fuelled by Nvidia’s robust earnings report. This positive sentiment propelled the S&P 500, Nasdaq 100, and Dow Jones indices to record new all-time highs. The S&P 500 soared by 2.11%, marking its most significant single-day advance in over a year, with the IT sector leading the charge, gaining 4.35%. Additionally, the lower-than-expected weekly jobless claims in the US bolstered confidence in the economy’s resilience. As a result, the expectations for rate cuts by the Federal Reserve in 2024 dipped to a three-month low of ~80 basis points, less than half of the peak levels observed in mid-January.

Nvidia’s post earnings rally

Nvidia’s stock had a remarkable day, climbing 16.40% after its earnings announcement. This surge augmented Nvidia’s market capitalization by an unprecedented $277 billion, eclipsing the previous record for the largest single-session market cap gain held by Meta, which earlier this month saw a $197 billion increase. This leap propelled Nvidia to the fourth position among the world’s largest companies by market capitalization and to third place within the S&P 500. Nvidia’s year-to-date returns stand at an impressive 58.59%, outperforming all other S&P 500 constituents.

What does Brooks Macdonald think

During a week devoid of major economic data releases, the spotlight has been on Nvidia’s earnings announcement. There were reservations about possibly overstating the significance of Nvidia’s earnings. Nonetheless, the strong market response has confirmed the initial hype, demonstrating the substantial impact that the financial performance of a single company can have on broader market trends.

Please check in again with us soon for further relevant content and market news.

Chloe

23/02/2024

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see today’s Daily Investment Bulletin from Brooks Macdonald received this morning, 22/02/2024.

What has happened

Nvidia’s announcement of strong guidance has positively impacted the markets, with the company’s shares experiencing a gain of 9% in after-hours trading. This surge has contributed to a broader market uplift, a 0.74% rise in S&P 500 futures. Elsewhere, Japan’s Nikkei index has achieved a historic milestone by surpassing its previous all-time intraday high from 1989, marking a continuation of its impressive performance with a 16.5% gain throughout 2024.

Nvidia’s impressive earnings

Nvidia has surpassed expectations for both revenue and earnings in the fourth quarter, with Data Centre revenue notably exceeding projections. The company announced $22.1 billion in Q4 revenue, a substantial 265% increase from the previous year, which was well above the $20.4 billion anticipated by analysts. The company’s guidance for the current quarter’s revenue and gross margin has also surpassed expectations. Nvidia’s management has expressed a confident outlook on Generative AI, highlighting the strong and growing demand that is outpacing supply. The anticipation surrounding Nvidia’s financial results has been evident in the options market, which indicated a significant move in the stock price following the earnings announcement.

What does Brooks Macdonald think

The 2024 earnings revisions are outperforming historical trends, with the market still anticipating low double-digit percentage growth in S&P 500 earnings. However, this growth is primarily driven by the top seven companies, the ‘Magnificent 7,’ while the remaining 493 companies in the index have experienced downward revisions in earnings and margins. This situation certainly exacerbates concerns regarding market concentration.

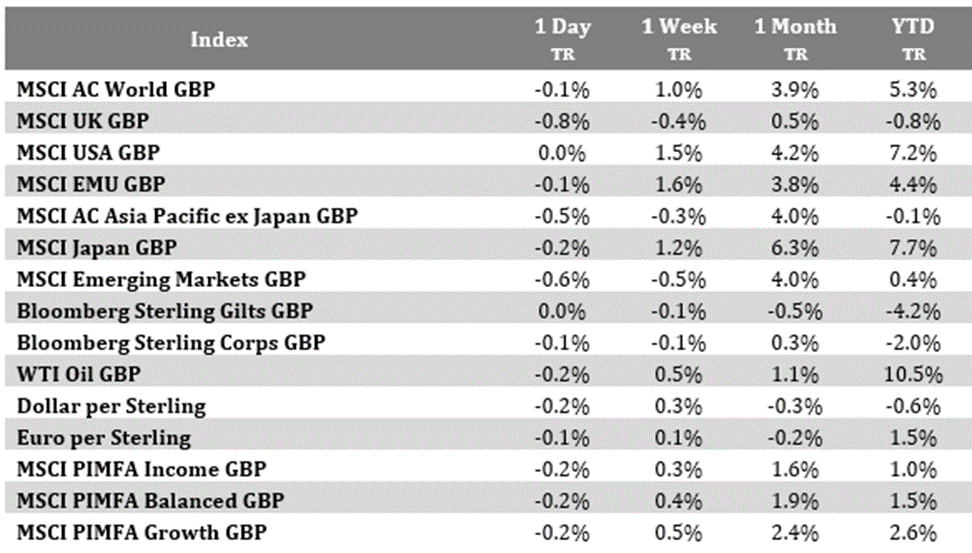
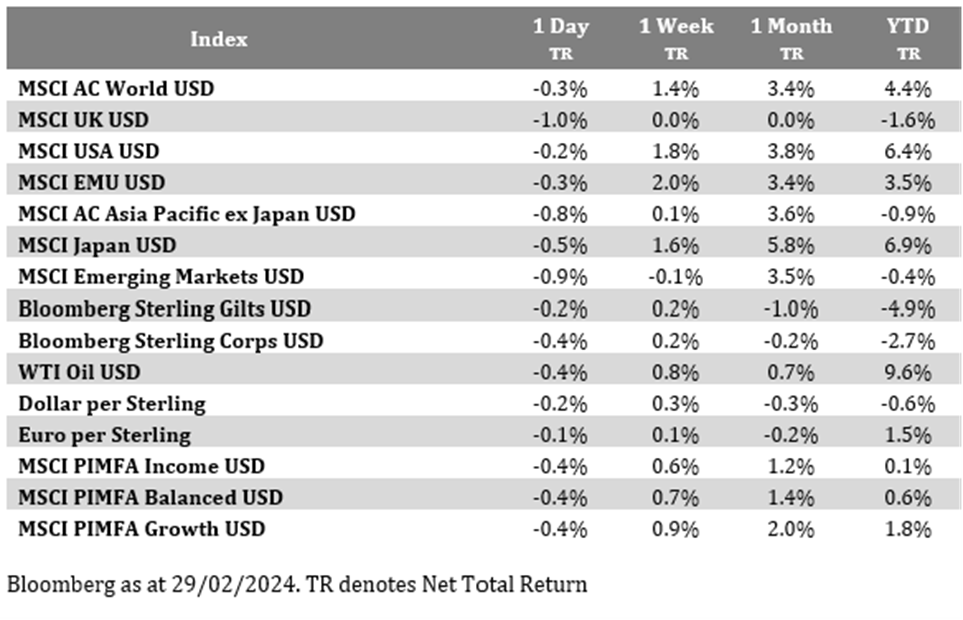
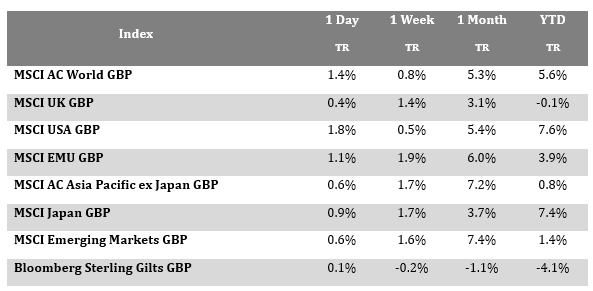
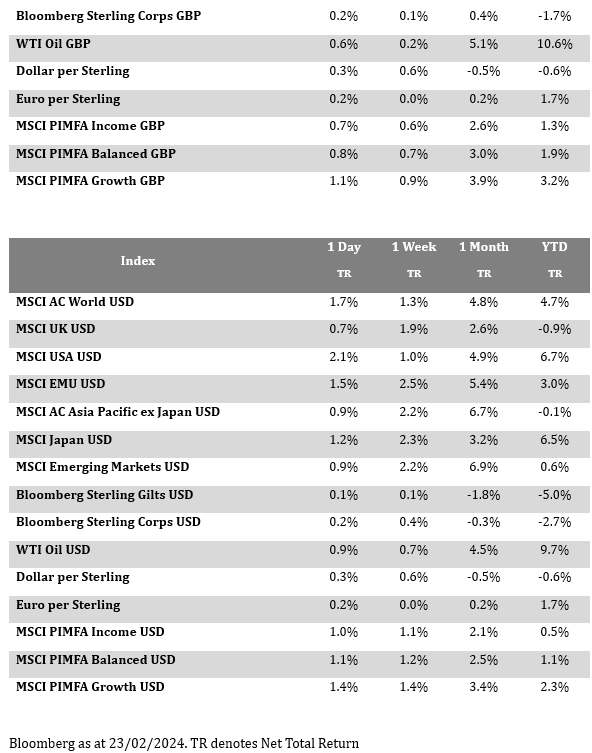
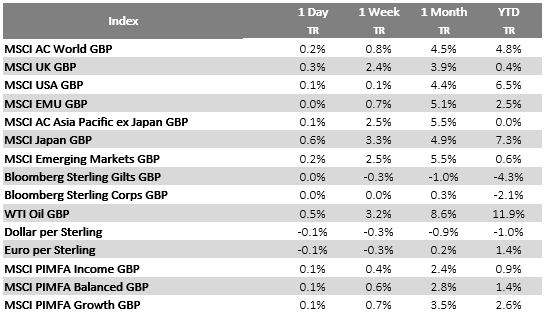
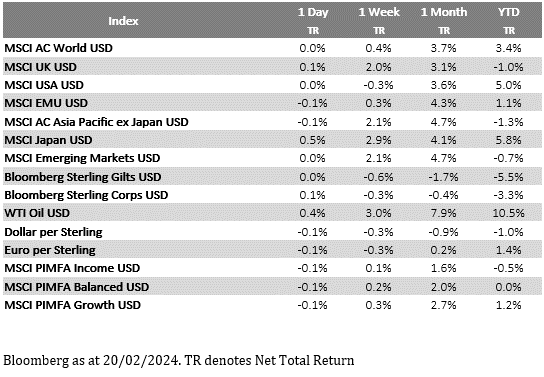
Bloomberg as at 22/02/2024. TR denotes Net Total Return

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Charlotte Clarke

22/02/2024

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see below this yesterday’s global market round-up from Brewin Dolphin, which was received late yesterday afternoon – 20/02/2024:

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

21/02/2024

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see todays Daily Investment Bulletin from Brooks Macdonald providing a brief analysis of markets:

What has happened

Global markets have been rather quiet over the last 24 hours given Presidents’ Day holiday in the US. The STOXX 600 index edged up by 0.16%, continuing its four-week streak of gains and reaching a new two-year high. The index now hovers just shy of its record high from January 2022, suggesting the potential for a new milestone in the near future.

A big week for corporate earnings

Attention is turning to a series of corporate earnings reports. Walmart is anticipated to report at noon London time today, setting the stage for Nvidia’s highly anticipated report after market close tomorrow. Nvidia’s performance is particularly noteworthy as it leads the S&P 500 with an impressive 46.6% surge this year, contributing to the ‘Magnificent 7′ stocks’ collective 10.65% year-to-date advance. In the UK, major banking institutions such as Barclays, HSBC, Lloyds, and Standard Chartered are scheduled to report earnings throughout the week. It’s expected that the UK’s five largest banks will announce a combined record-breaking £50 billion in profits, reaping the benefits of increased borrowing costs. While last year’s results hold importance, the focus is likely to shift towards future outlooks, especially with the Bank of England’s anticipated rate cuts. Despite a positive valuation outlook from analysts, the UK banking sector faces challenges from broader economic concerns and regulatory and political pressures.

What does Brooks Macdonald think

While this week may be characterized by a scarcity of macroeconomic data, it is nonetheless punctuated by a series of critical earnings reports that are likely to capture the attention of investors. We will see the market narrative shift from a macro-level, top-down approach to a micro-level, bottom-up analysis as investors seek to dissect the granular details of company reports. The guidance and forward-looking statements provided by these companies will serve as a barometer for the underlying economic health and could potentially offer insights into future market trends and corporate strategies.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Andrew Lloyd DipPFS

20/02/2024