Team No Comments

Brewin Dolphin: Markets in a Minute

Please see below, Brewin Dolphin’s ‘Markets in a Minute’ which discusses the effect of central bank policy and earnings results on global investment markets. Received yesterday afternoon – 06/02/2024

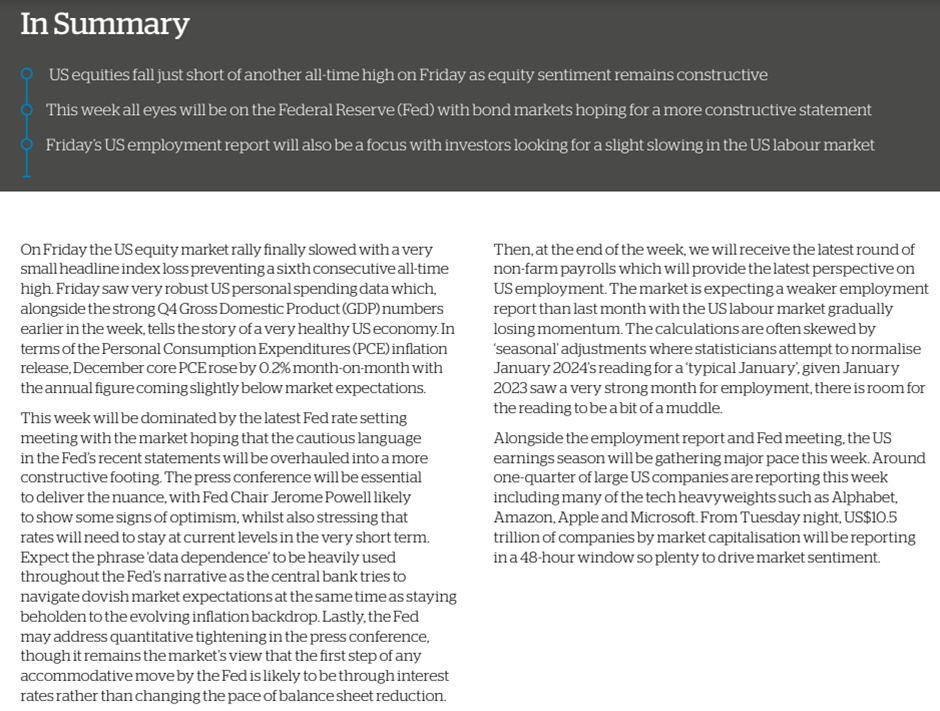
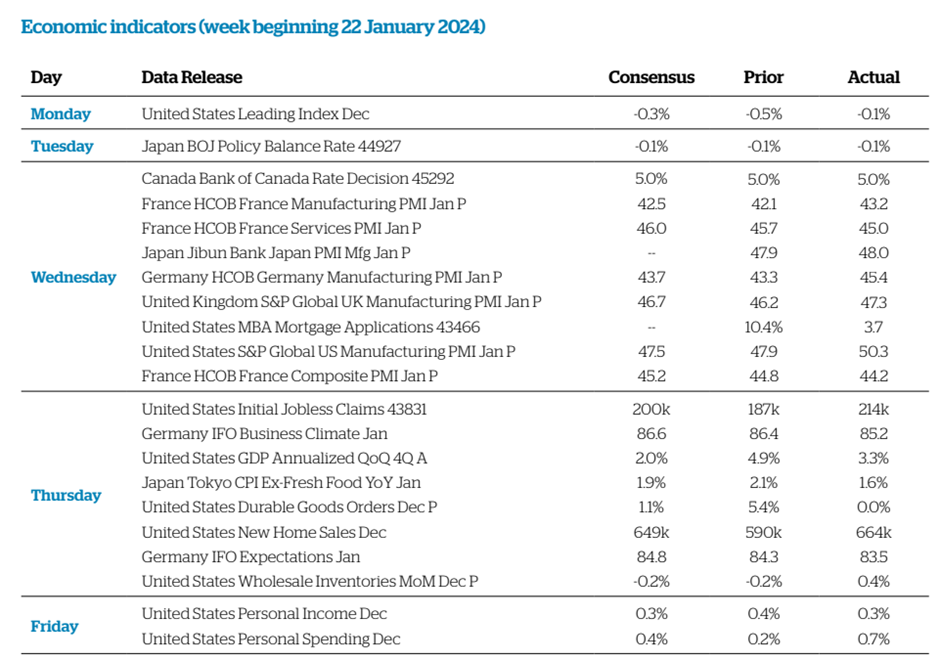
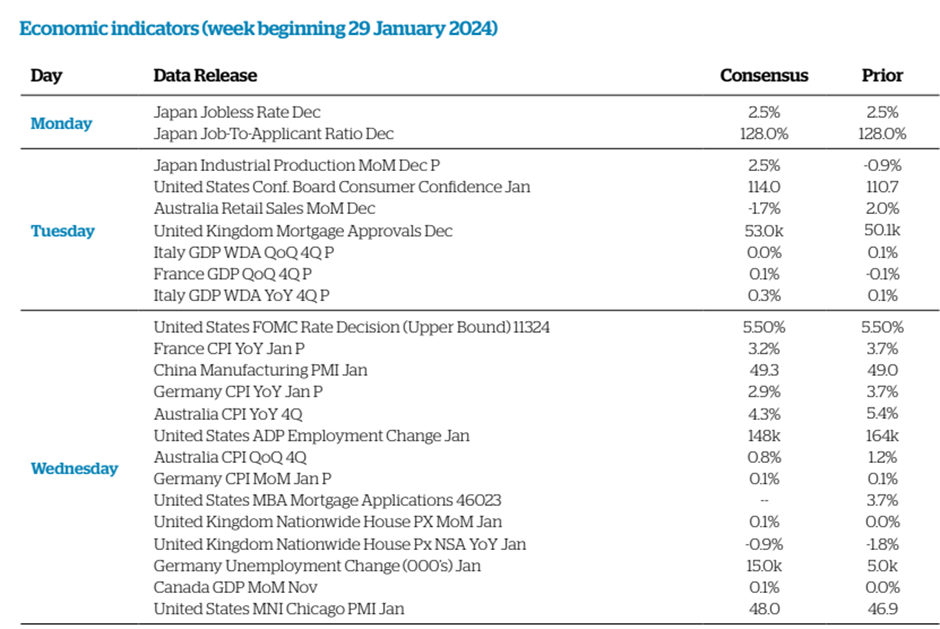
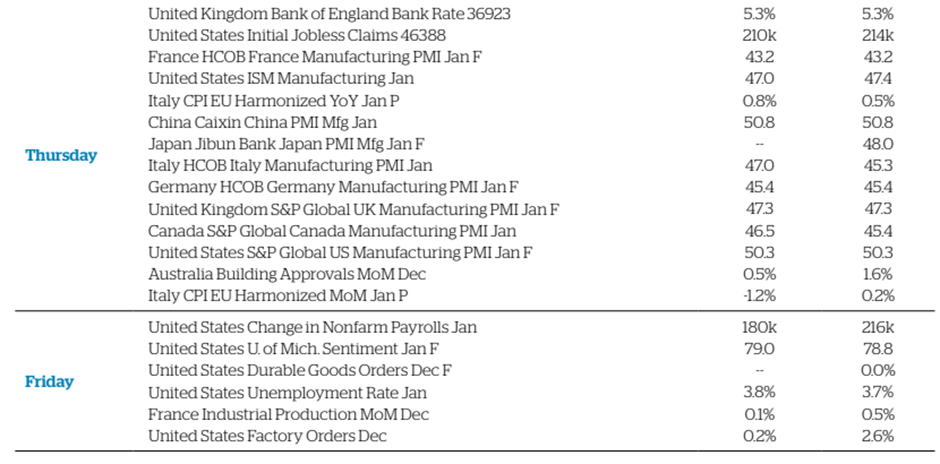
We had two big central bank meetings last week, with the Federal Reserve announcing policy on Wednesday evening and the Bank of England doing so on Thursday lunchtime. As expected, neither made any changes, but it was an opportunity to hear the tone being used and to determine the likelihood of an interest rate cut, possibly as soon as (late) March.

The Federal Reserve chairman, Jay Powell, took the first opportunity to set that tone. Data had been supportive of a continuation of economic growth momentum, alongside weakening inflation. Although job openings increased slightly, suggesting the labour market was tight, fewer people had been quitting their jobs, suggesting diminished confidence amongst workers. That matters because wage growth tends to be faster amongst those switching jobs than those staying within the same job.

Blowout jobs growth

On Friday afternoon, more light was shed on the employment position with the monthly non-farm payroll report, which gets pulses racing across the investment world despite a tendency to be heavily revised in the following months.

The Bureau of Labor Statistics estimates that a huge 353,000 new jobs were taken in January, which was almost double the average forecasted figure, and well above even the highest of those forecasts. Not only that, but previous healthy jobs growth numbers were revised higher. Now, an important caveat here is that the headline jobs growth number comes from surveying companies and asking how many jobs they have filled. An alternative measure of ostensibly the same thing surveys households and asks how many of them are in work. This second measure sometimes (often) conflicts with the first and did so again on Friday. But it is accepted that this household survey is not as reliable as the main non-farm payroll report, so this data suggests the labour market is strong.

The second most shocking part of the report was the wage data. In recent weeks, we have seen some more lagged but better-quality data indicating a slowdown in wage growth, but January’s wage gains seem, provisionally, to have also exceeded any forecaster’s expectations. Wage growth accelerated to 4.5% per annum. Stronger jobs and wage growth is a potent combination which will imply strong growth in consumer spending as well as more money flowing into pensions, and, by implication, into the stock market.

At the same time, though, stronger wage growth will suggest higher costs for firms and therefore higher prices being charged for their goods and services.

Interest rates

This obviously has serious implications for the Federal Reserve. On Wednesday evening, chairman Powell disappointed some investors, saying he doesn’t expect to have sufficient confidence that he could cut interest rates by March.

There was clear disappointment reflected in the equity and bond markets, with investors at some stage thinking there was a 60% chance of a rate cut; this dropped to less than 40% after Powell spoke. And now, following the release of this strong employment report, at the time of writing, the chances of a rate cut seem to have fallen to around 20% (although, chances are still higher than this for subsequent meetings).

Powell’s comments felt like they were designed to calm investors down after he struck a decidedly dovish tone in December. The Bank of England (BoE) was expected to do the opposite.

The BoE has been keen to avoid declaring victory in the battle against inflation. At this meeting, the most obvious relaxation of that stance was evident in the voting. In December, three members had voted for a further increase. In January, that was just two, while one had even started by voting for an interest rate cut.

Economic forecasts for the UK have been downbeat and inflation has been high. The elevated level of inflation has weighed on growth (which tends to be measured after adjusting for price increases). However, consumer confidence has improved, the housing market has stabilised, and business surveys show growing confidence.

Unlike the US, there is clear evidence of the UK labour market weakening, which ought to be enough to keep the two hawks on the BoE’s Monetary Policy Committee in the minority. It doesn’t currently seem sufficient to trigger the cuts the market is expecting.

Earnings season

Earnings season continues with the oh-so-predictable beatsto-misses ratio of 80%. So far, around 40% of companies have reported, but that understates the progression through this earnings season as Tesla, Apple, Alphabet, Microsoft, Amazon and Meta have all reported. So, that just leaves Nvidia to complete the so-called ‘Magnificent Seven’ when it reports on 21 February.

Of these big companies, Amazon and Meta dazzled, Microsoft was mixed, Google and Apple underwhelmed, and Tesla was received particularly badly by the market when the numbers landed last week. Any disgruntled investors may have felt relieved to know that last week, a judge ruled that Musk’s extraordinary record-breaking $56bn compensation should be cancelled.

US stocks seemed set to finish the week little changed overall, after mixed performance from the Magnificent Seven stocks. Despite their size, they contributed an even greater share of the market’s earnings growth. But the rest of the US market, while growing more slowly, did at least seem to surprise analysts more favourably when their earnings were released.

One of the major controversies within the market at the moment is whether, after a strong year of outperformance by the Magnificent Seven, expectations could have become difficult to meet. In the short term some companies showed signs of that, but we still see some of these exceptional stocks as offering tremendous value.

Please continue to check our blog content for advice and planning issues and the latest markets and economic updates from leading investment houses.

Alex Kitteringham

7th February 2024

Team No Comments

EPIC Investment Partners – The Daily Update | Hope For Chinese Equities

Please see below article received from EPIC Investment Partners this morning, which provides an update on Chinese and Hong Kong stock markets.

Chinese stocks bounced aggressively overnight in anticipation of a more forceful response to the ongoing rout, with regulators also planning to brief President Xi Jinping on market conditions. Although it remains uncertain if the upcoming meeting will result in new measures to bolster the market, investors are hopeful for a positive change after many false dawns.  

Since reaching their peak in 2021, Chinese and Hong Kong stock markets have lost approximately USD7tn in value, USD1tn of that in the last 13 days until last night’s rally. The Hang Seng closed over 4% higher, with the CSI 300 up nearly 3.5% and the CSI 1000 gaining 7%.  

Efforts by policymakers to stimulate the economy and stabilise the markets have so far not yet yielded any success in improving investor confidence. With the Lunar New Year holiday approaching, stabilising the stock market has now become a crucial goal for policymakers to prevent further damage to consumer confidence.  

Following the news of President Xi’s meeting, there were a series of statements earlier in the day. One notable statement came from the massive USD11.4tn Central Huijin Investment, a company holding stakes for the Chinese government in major financial institutions, which pledged to increase its purchases of exchange-traded funds. Additionally, the securities regulatory authority emphasised their commitment to ensuring stable market operations in a subsequent remark. 

Authorities have once again tightened trading restrictions, banning some hedge funds from placing sell orders, cracking down on short selling, and stopping investors from cutting stock positions in their leveraged market-neutral funds. On Monday, the securities regulator said it will guide brokerages to adjust their margin call levels and maintain “flexible” liquidation lines to limit forced selling.  

Earlier efforts had already included curbs on short selling, coupled with the state’s share purchases across the nation’s largest banks. However, the measures so far have shown little success in restoring investor confidence, which has been hurt in recent years by an economic slowdown, the implosion in the property sector, as well as Xi’s tightening grip on private enterprise.  

Please check in again with us soon for further relevant content and market news.

Chloe

06/02/2024

Team No Comments

Tatton Investment Management – The Monday Digest

Please see the below article from Tatton Investment Management providing a brief analysis of markets and the key news from global economies over the past week. Received this morning 05/02/2024.

Overview: Central banks challenge goldilocks assumptions

Surprisingly decent monthly returns were soured on the last day of January when the US Federal Reserve dampened the mood by repeating the message that rate cuts will begin later than markets anticipate. That this reiteration led to a sell-off was surprising, because markets seemed to have already grudgingly accepted later rate cuts than hoped at the end of 2023, thanks to surprisingly resilient  US Q4 growth. It is therefore reasonable to assume that last week’s stock and bond market falls were about more than central bank press conferences. We turn to the usual suspects: China, banking fears and uninspiring corporate earnings reports.

The liquidation of faltering Chinese property giant Evergrande could spell further short-term trouble for the property-heavy Chinese economy, even if it may spur the Chinese regime to properly address the property crisis. Beijing’s procrastination is an issue we need to watch. More pressing is the return of American banking woes, following New York Community Bancorp’s 40% share price drop. This was compounded by uninspiring corporate earnings outlooks at the start of the week.

Much better than expected results from US mega tech companies and international oil majors changed the tone, as did a report on Friday showing that the US added 353,000 extra jobs in December. Markets initially only traded sideways on the news, bringing us back to the Fed. The strength of the US labour market means there is little incentive to cut rates in the near-term, but renewed banking pressures challenge the narrative that economic strength will overcome high rates. This could mean less vibrant markets and a longer wait for interest rate normalization, which will put pressure on valuations and corporate financing costs. Until the timing of rate cuts is clear, we have to expect more of the same: China is out, US powers ahead, with its Mega Tech market darlings in focus, while the rest of the economy is hoping for more sympathetic central bank rates sooner rather than later.

January asset returns review

After the hangover from December’s Santa Rally, January turned into a half-decent month for investors. Coming into the new year, capital markets were anxious that they had got ahead of themselves, but these fears dissipated as the month went on. Global stocks gained 0.7% in sterling terms, which is much more impressive when considering the rally that came the month before. US stocks gained 1.8%, thanks to expectations of a goldilocks environment – with earnings remaining strong but rates lowering nonetheless. Returns would have been higher if not for the Fed pouring cold water on a March rate cut on the last day of the month. American stocks still rose to all-time highs, making valuations look stretched.

Japan’s stock market was the best regional performer, gaining 4.7% in sterling terms. Short-term factors like continued negative interest rates and a weaker yen (boosting exports) were the immediate factors behind the rally, but improvements in Japan’s corporate structure means there is still plenty room to grow. UK stocks were negative by contrast, losing 1.3%, while eurozone equities gained a mild 0.3%.

These mild returns mean that both regions held on to most of the gains seen in November and December, and are up over the last three months. Europe stands to gain from rate cuts, expected in the spring, and any pickup in global demand. Lower valuations than in the US could help on that front.

Emerging markets lagged other major regions, losing 4.5% in sterling terms. The biggest drag on EM assets remains China, whose economic weakness is still being felt. The support measures being pursued now are significant, but the lack of private sector confidence runs deep. For wider EMs, they should at least be able to look forward to looser Fed policy and, eventually, a pickup in global demand. Overall, January turned out better than expected for global investors. Gains from November and December were not just solidified, but in most instances extended.

Central banks confirm ‘lower, slower’

The Fed, the BoE and the ECB all held monetary policy meetings in the last couple of weeks, and all three left interest rates unchanged. Virtually all acknowledge that rate cuts are a question of when not if – but the when is complicated by central bankers’ fear of once again being caught out by inflation. The Fed exemplifies this push and pull. Earlier this month, a senior official said the central bank was within “striking distance” of its 2% inflation mandate, but at its meeting last week, Fed chair Powell poured cold water on the idea of a March rate cut.

As a result, markets expect rates to be 0.5% lower by June. That is extraordinary, considering the enduring strength of the US economy and its resultant inflation pressures. Core US inflation (removing volatile elements like food and energy) has eased but is still around 4%, and the labour market remains extremely strong. The US economy added 353,000 new jobs in January – when only 170,000 had been widely expected. There is no immediate need for support, hence the Fed forgoing a March rate cut. This is also true for the Fed’s balance sheet reduction, which some observers thought would slow in response to banking troubles. The bank’s recent increase in its repo rate for the extraordinary liquidity facility (which was set up in March last year to facilitate and ease regional bank funding pressures) is signalling the opposite.

The BoE, meanwhile, remains planted on the fence. At its meeting last Thursday, the Monetary Policy Committee was split three ways for a hike, on hold, and a cut. Structural supply-side problems mean wages and core inflation are still too high, despite continued weakness in the UK economy. The ECB is similarly cautious. The Eurozone economy is stagnant and contracting in some areas but its central bank left rates unchanged and urged for patience in cutting rates, because of labour market tightness and continued inflation in services. Economic realities should mean European rate cuts come sooner than American ones, but policymakers seem to have different preferences either side of the Atlantic.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

05/02/2024

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a market update with specific reference to the US and the UK.

What has happened

The US stock market experienced a notable rebound, with the S&P 500 climbing 1.25% and largely offsetting the previous day’s 1.61% drop. Despite a second consecutive day of losses for US regional banks, which saw a 2.28% decline, and ongoing concerns about New York Community Bancorp, the broader market appeared to recover.

Big tech earnings continue

After the market closed, tech giants Apple, Amazon, and Meta reported earnings that surpassed expectations. Meta’s shares soared approximately 15% after hours, buoyed by higher-than-anticipated revenue forecasts for the first quarter and the announcement of further share repurchases and its inaugural dividend. Amazon’s shares rose 7%, reflecting a robust profit forecast for the first quarter, despite its sales guidance falling slightly short of expectations. Apple’s shares, however, dipped nearly 3% after hours due to a significant sales decline in China, which overshadowed an otherwise modest earnings beat.

Bank of England

In the UK, the Bank of England maintained its interest rates, in line with market expectations. The Monetary Policy Committee (MPC) was divided, with the majority opting to keep rates steady, two members advocating for a 25 basis point hike, and one member favouring a 25 basis point reduction. Governor Bailey emphasized the need for more evidence of inflation trending towards the 2% target before considering rate cutes. Similar to the Federal Reserve, the MPC’s stance appeared to be gradually shifting towards the possibility of rate cuts, as indicated by the removal of the previous explicit tightening bias and the statement that the MPC is prepared to adjust policy as necessary. Market expectations for a rate cut by May decreased, but the likelihood of significant rate reductions by the end of 2024 remained high.

What does Brooks Macdonald think

Looking forward, the focus will be on the US jobs report for January, which will provide early data for 2024 and could influence the Federal Reserve’s rate cut decisions, with March’s outcome still uncertain despite recent comments from Fed Chair Powell. Recent macroeconomic indicators suggest the possibility of a ‘soft landing’ for the US economy. However, historical patterns remind us that the effects of a rate hike cycle can be delayed and unpredictable, often culminating in significant economic impacts.

Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World GBP 0.5%0.0%1.5%1.5%
MSCI UK GBP -0.1%1.3%-1.3%-1.3%
MSCI USA GBP 1.1%-0.1%3.0%3.0%
MSCI EMU GBP -0.4%0.7%0.2%0.2%
MSCI AC Asia Pacific ex Japan GBP -0.1%-1.3%-4.5%-4.5%
MSCI Japan GBP -1.0%0.6%4.0%4.0%
MSCI Emerging Markets GBP 0.5%-1.0%-3.9%-3.9%
Bloomberg Sterling Gilts GBP 0.5%1.9%-1.9%-1.9%
Bloomberg Sterling Corps GBP 0.3%1.6%-0.8%-0.8%
WTI Oil GBP -2.8%-4.9%3.2%3.2%
Dollar per Sterling 0.1%0.4%0.0%0.0%
Euro per Sterling -0.1%0.0%1.8%1.8%
MSCI PIMFA Income GBP 0.4%0.9%0.1%0.1%
MSCI PIMFA Balanced GBP 0.5%0.8%0.2%0.2%
MSCI PIMFA Growth GBP 0.6%0.7%0.7%0.7%
Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World USD 0.7%0.4%1.2%1.2%
MSCI UK USD 0.1%1.7%-1.5%-1.5%
MSCI USA USD 1.3%0.3%2.8%2.8%
MSCI EMU USD -0.2%1.1%0.0%0.0%
MSCI AC Asia Pacific ex Japan USD 0.1%-0.9%-4.7%-4.7%
MSCI Japan USD -0.8%0.9%3.8%3.8%
MSCI Emerging Markets USD 0.6%-0.6%-4.1%-4.1%
Bloomberg Sterling Gilts USD 0.1%1.7%-2.4%-2.4%
Bloomberg Sterling Corps USD -0.1%1.5%-1.3%-1.3%
WTI Oil USD -2.7%-4.6%3.0%3.0%
Dollar per Sterling 0.1%0.4%0.0%0.0%
Euro per Sterling -0.1%0.0%1.8%1.8%
MSCI PIMFA Income USD 0.6%1.3%-0.1%-0.1%
MSCI PIMFA Balanced USD 0.6%1.2%0.0%0.0%
MSCI PIMFA Growth USD 0.7%1.0%0.4%0.4%

Bloomberg as at 02/02/2024. TR denotes Net Total Return

Please check in again with us soon for further relevant content and market news.

Chloe

02/02/2024

Team No Comments

Evelyn Partners Update – Bank of England MPC decision

Please see the below update from Evelyn Partners Investment Strategy team on today’s Bank of England MPC decision to continue to hold interest rates at 5.25%:

What happened?

The Bank of England (BoE) held the base rate at 5.25% at their meeting today. This was consistent with market expectations and marks the fourth consecutive meeting where rates have been held at this level.

Interestingly, the committee vote was split three ways, with two members voting for a hike, six voting to hold, and Swati Dhingra voting for a 25 basis point cut.

What does it mean?

As expected, the BoE held interest rates at 5.25%. Markets are now focused on when the Bank will cut interest rates and how far they will go. And perhaps Swati Dhingra’s vote to cut the base rate signals that the tide is set to turn. This was the first vote for a cut since the pandemic started almost four years ago. Although clearly this will continue to depend on the incoming data, which has been favourable since the Monetary Policy Committee (MPC) last met in December.

December CPI came in at 4.0% year-on-year, which was well below the Bank’s forecast of 4.6%. The headline figure was helped by services inflation, which was 0.5% percentage points below the Bank’s November forecast of 6.9% year-on-year. Similarly, the latest wage data shows further deceleration. The direction of travel seems encouraging, so much so, that the consensus forecast is that CPI will be 2.1% by the second quarter of this year.

The guidance published today by the MPC provided more hints on how they see the economic outlook. Compared to December’s guidance, the MPC dropped the language mentioning the risk of further interest rate tightening, signalling they are less concerned about inflation remaining stubbornly high. We also received the Bank’s latest forecasts. It expects GDP growth of 0.25% in 2024 and 0.75% in 2025. Similar to the consensus view provided in the Bloomberg survey of economists, the Bank sees inflation decelerating to 2% in Q2 2024, before it picks up again in the second half of the year.

This should give the Bank the ammunition it needs to cut rates around the middle of the year. Money markets are split on whether the base rate will be cut in May, but they have more conviction that we will see at least one cut by June. They are also pricing 100 basis points of cuts by the end of 2024.

Bottom Line

The BoE held interest rates at 5.25%. We expect to see the first rate cut around the middle of the year as inflation decelerates to the 2% mark.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

01/02/2024

Team No Comments

EPIC Investment Partners: Daily Update – FOMC / US Banking Concerns

Please see the below update from EPIC Investment Partners about the current movements with the US Economy received earlier today:

As expected, the Fed left its policy rate unchanged at the 23-year high range of 5.25%-5.5%. However, the accompanying statement did acknowledge the more balanced risks to inflation, and the suggestion that whilst further rate hikes are off the table, the committee was not ready to cut yet. The statement said that the FOMC “does not expect it will be appropriate to reduce the target range until it has gained greater confidence that inflation is moving sustainably toward 2%”. 

Fed Chair Jerome Powell acknowledged that whilst progress has been made in reducing inflation, a March cut is unlikely. “Based on the meeting today, I would tell you that I don’t think it’s likely that the committee will reach a level of confidence by the time of the March meeting to identify March as the time to do that. But that’s to be seen,” Powell said. He added: “We believe that our policy rate is likely at its peak for this tightening cycle and that, if the economy evolves broadly as expected, it will likely be appropriate to begin dialling back policy restraint at some point this year”. “We are prepared to maintain the current target range for the federal funds rate for longer, if appropriate”, he said. 

However, the FOMC’s rate decision was overshadowed by renewed concerns in the US banking system. New York Community Bancorp, one of the big winners after the collapse of Silicon Valley Bank and First Republic Bank last year, saw its stock fall a record 46% after it cut its dividend, and massively increased its provision for loan losses to over USD550m due to its exposure to US commercial real estate.

Within hours a second lender announced huge losses due to its exposure to the sector.  Aozora Bank Ltd, Japan’s 16th biggest bank by market value, said it expects to post a net loss of USD191m for the fiscal year, compared with its previous forecast of profit. Shares sank more than 20% (limit down) in Tokyo.

According to a report from the University of Southern California, Northwestern University, Columbia University and Stanford University, as of Q3 last year, US banks alone held about USD2.7tn in commercial real estate debt. Green Street, a real estate analytics company reported commercial property values have fallen over 20% since Q1 2022, with office prices down a massive 35% as demand for desk space weakened following the wide adoption of remote working. 

So, the question now is whether New York Community Bancorp and Aozora Bank are canaries in the coalmine?

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

01/02/2024

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this weeks Markets in Minute update from Brewin Dolphin below, received late yesterday afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

01/02/2024

Team No Comments

EPIC Investment Partners: The Daily Update | Qatar’s Upgrade

Please see below, an article from EPIC Investment Partners which focuses on the economic strength of Qatar and the potential investment opportunities. Received this morning – 31/01/2024

 We have often mentioned to clients that we believe the rating agencies are behind the curve, so we were pleased to hear that Moody’s Investor Service recently upgraded its long-term rating for Qatar by one notch, from Aa3 to Aa2, its first upgrade since 2007. The already high rating for the wealthy nation now sits on par with the UAE, South Korea and France, and is now in-line with S&P Global’s AA rating. Fitch rates Qatar one notch lower, at AA-, with a positive outlook, signalling a potential upgrade.   

Moody’s analysts attribute the upgrade to Qatar’s improved fiscal metrics, which have been “achieved during 2021-2023”, and are expected to be “sustained in the medium term”. The government’s commitment to fiscal prudence (the IMF estimates the nation’s debt to GDP is ~40%, from 73% in 2022), including the gradual reduction of infrastructure spending (linked to preparations for the 2022 FIFA World Cup), is seen as a contributing factor to the upgrade.  

The rating agency further recognises Qatar’s major investments in liquefied natural gas (LNG) production capacity as credit positive. Qatar, the world’s third-largest LNG exporter, is investing substantially to boost its output by about 60% over the next three years, in a move to meet rising global demand growth, particularly given the significant role the fuel plays in the transition to cleaner, more sustainable power sources.   

Given the rising frictions in the Red Sea and Qatar’s dependence on the export route, S&P Global recently commented that diverting LNG carriers away from the Red Sea would minimally affect Qatari oil and gas entities, since most of their customers are located in Asia. The agency went on to add that barring risks of regional war, the impact of tensions on rated Qatari energy firms like Nakilat, and QatarEnergy’s LNG project is manageable. 

Away from hydrocarbons, Qatar has made impressive strides in diversifying its economy, driven by the Vision 2030. Thanks to sustained investments and policy support, Qatar’s non-oil sectors now comprise over 50% of real GDP. Thriving industries such as financial services, tourism, and manufacturing are fast emerging as new engines of economic growth. Qatar is also expanding output in high value sectors like chemicals and technology, which leverage its natural gas resources. With huge investments allocated to transport infrastructure and private sector stimulation, Qatar’s economic base is rapidly broadening. Prudent economic management has translated this diversification into solid GDP growth rates despite hydrocarbon price volatility. 

We also remain cognisant of Qatar’s diplomatic mediation initiatives. Driven by a desire to establish itself as an independent and progressive player on the world stage, Qatar has embraced diplomatic mediation as a cornerstone of its foreign policy. 

We have long favoured Qatar’s sovereign and quasi-sovereign bonds. Through our investment process, we have identified Qatar as having a 7-star NFA score, defined as a “wealthy nation”. Then, using our proprietary relative value model, we have identified undervalued bonds issued by the government and government-owned entities. A good example of a bond we favour is the Qatar 6.4% 2040s. This bond is currently trading ~45 bps wider than similarly rated bonds with a ~10-year duration and offers a risk-adjusted return and yield of ~10%.   

Qatar has not issued international bonds in around four years, simply because it does not need to. So, its first green bond offering, which is coming “soon” according to the nation’s finance minister, Ali Al-Kuwari, will attract much attention, and will further demonstrate its commitment to sustainability funding.  

We continue to believe Qatar’s economy will maintain its positive trajectory, supported by rising LNG exports and diversification efforts, and through its mediation efforts will continue to bring it to the fore as a global ally. Therefore, as long as the bonds offer attractive risk-adjusted returns, or alpha, Qatar will remain a high conviction investment in our Next Generation Bond Strategy.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

31st January 2024

Team No Comments

Brooks Macdonald – Weekly Market Commentary

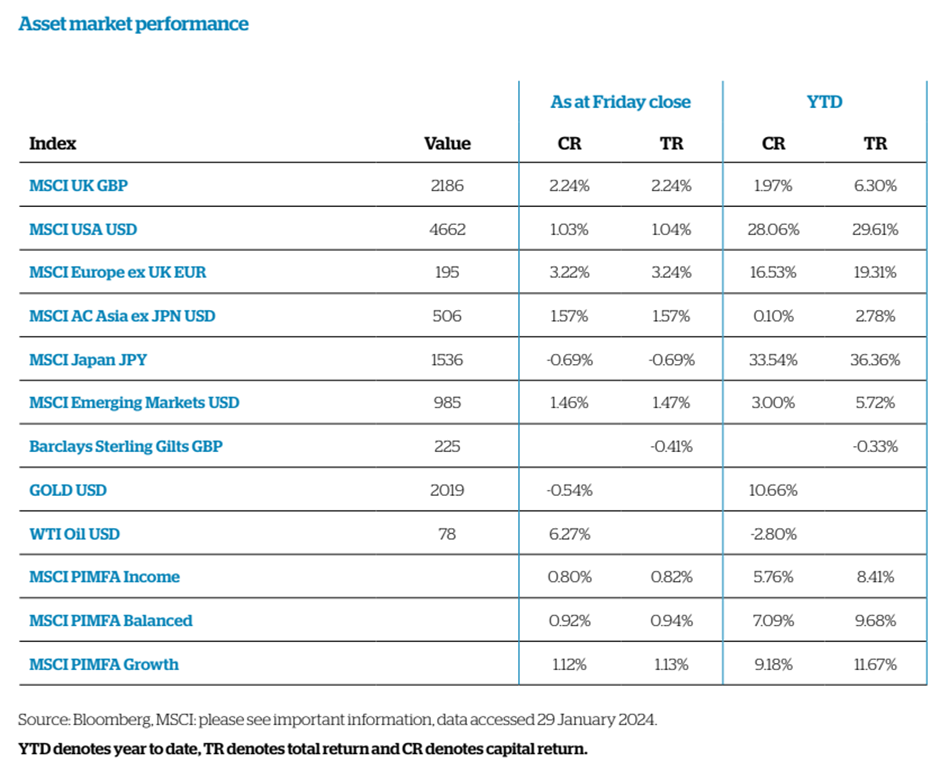
Please see below this week’s Weekly Market Commentary from Brooks Macdonald, which was received yesterday afternoon – 29/01/2024:

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

30/01/2024

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management providing a brief analysis of markets and the key news from global economies over the past week. Received this morning 29/01/2024.

Overview: Positive growth sentiment returns

After January’s bumpy start, and the volatile two weeks that followed, it looks like investors are finding their feet again. Almost entirely across the board, regional equity markets are up another healthy amount, with even China managing another positive week. And as suspected, bond markets are having an extremely busy January.

Government debt yields have declined by around 1%, but for riskier corporate borrowers, the turn in sentiment in both markets and economies has resulted in reduced fears of defaults – which has additionally driven down the risk premium (spread), they have to pay above the government. In the US dollar bond market, the US government was paying 10-year interest of just less than 3% in September 2018. Now the yield is about 4.1%. A borrower with a credit rating just below investment grade (BB-rated) was paying just over 6% in September 2018, and now will pay interest of around 6.5%, according to Bloomberg. Only three months ago, that BB-rated borrower was looking at paying over 8%. Perhaps it is no wonder corporate borrowers feel current yield levels are reasonably attractive enough to replenish their loan capital side. The story is similar in the Eurobond market, which has already seen record issuance for January.

It is a good sign for markets and economies that more companies think this is a good time to borrow money. This rise in spirits is getting some backing from moves in the commodities markets (which we write about below) and from business sentiment surveys like the ‘flash’ purchasing managers’ index (PMI) surveys from across the world, released last week. Perhaps sentiment is not racing ahead, but the broad composite measures – which include both manufacturing and service sector companies – are now generally heading above the 50 level, which signals the difference between companies thinking they are in growth or decline. Indeed, the US, UK and even China are at or above the 52 level (which aligns with activity at a normal level and optimum capacity usage).

So, markets have returned to the frame of mind where optimism is slight and risks have been high but are falling. The European Central Bank (ECB) did its bit to keep confidence stable last week. Nobody expected a rate cut (and none was forthcoming) but President Christine Lagarde said there was “stabilisation” in some wage indicators and that companies were currently absorbing wage hikes, reducing the risk of second-round effects on prices. She also gave little pushback when asked about a spring rather than summer start to cutting rates. Next week is the turn of the US Federal Reserve and then the Bank of England. Again, nobody is expecting rate cuts, it will be all about the comments.

Will Xi allow China to profit?

Last year’s prolonged decline in Chinese stocks continued well into January, but last week, Hong Kong’s Hang Seng index rose more than 6% during midweek trading, after news that the Chinese government would step in to stop the rout. On Tuesday, Premier Li Qiang called for “more forceful and effective measures to stabilise the market and boost confidence”. On Wednesday, the People’s Bank of China (PBoC) cut bank reserve requirements, thereby unleashing a trillion Yuan of lending headroom into the banking system. Both the Hang Seng and the CSI 300 – mainland China’s benchmark stock index – rallied in response.

Perhaps Beijing is willing to put its money where its mouth is and – crucially – wants markets to know it. Its words and actions are certainly a step in the right direction and, coming so soon after Premier Li’s speech, will soothe some investor concerns. Ultimately, though, attempts to support short-term confidence in the economy or financial system do not address the core reason for why businesses and investors lack confidence to begin with.

During the crackdowns of the last few years, there has been a growing sense that President Xi Jinping is against not just excesses but private sector profit altogether. He has made it clear that private power cannot be allowed to rival the state (as in the case of Alibaba founder Jack Ma) but this seems to have filtered through to profit-making in general. People are willing to take advantage of the short-term market opportunities the Party hands out, but to truly invest in long-term private sector growth investors need to know they will be allowed to profit without negative comeback. This needs consistent messaging, ideally from Xi himself. Without that, the decline will be hard to stop.

Commodities and growth

The Dow Jones Commodity Index has been virtually flat since the beginning of the year. That is either a good or bad sign, depending on how you look at it. Considering the intentional slowdown in global growth recently, a stable if unspectacular patch should be welcomed. On the other hand, this comes after a protracted downturn for the commodity sector. Dow Jones commodities have lost nearly 9% on a one-year basis at the time of writing. Staying flat is less impressive if the level is already low

Of course, much of that downturn was about oil, but oil is no longer a great indicator of general economic conditions. Metals, in particular industrial metals, are arguably a better signal. The S&P Industrial Metal index has been flat for some time, currently at the same level it was in May last year and with only a narrow trading range since then. But metals became detached from energy prices last year, and that detachment is ongoing. Again, stable metals prices are encouraging, all things considered. Global manufacturing has been struggling for a long time, and despite improvement across the board, manufacturing PMIs still point toward contraction in the UK and Eurozone. The only exception is the US, where the manufacturing PMI unexpectedly jumped to 50.3 in January. US resilience and outperformance is nothing new, though, and is offset by weakness elsewhere – particularly the disappointing China.

The problem for metals is that they cannot sustainably rise on hope alone. Like all commodities, metals futures are subject to short-term speculation but are ultimately physical materials that need to be financed, stored, transported and used. The cost of storage has risen dramatically in recent years thanks to the massive step-up in developed market interest rates which led to a big increase in the cost of the tied-up capital. That means inventories are generally lower, which means prices are much more sensitive to final demand. As such, we are unlikely to see a sustained pick-up in metals prices until growth and demand actually come through.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

29/01/2024