Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see today’s Daily Investment Bulletin from Brooks Macdonald:

What has happened

Yesterday, we saw small pullbacks in the market with the S&P 500 slightly retreating by 0.19% from its record peak, while the yields on 10-year Treasuries edged up for the third consecutive day. Tech sector underperformed, as NASDAQ lost 0.54% and the ‘Magnificent 7’ group fell 0.74%. These movements reflect growing concerns about the sustainability of the recent market rally, particularly considering the S&P 500’s sharp rise of over 25% in less than 100 trading sessions. Additionally, inflation remains a key point of focus, with the US CPI release casting doubt on the Federal Reserve’s ability to implement rate cuts by June.

PPI and retail sales preview

Today’s spotlight will continue to shine on inflation with the release of the US Producer Price Index (PPI) and retail sales data. The PPI is particularly significant as it includes several components that contribute to the Personal Consumption Expenditures (PCE) inflation measure, which the Federal Reserve targets. Although the PCE data will not be available until the end of March, today’s PPI figures will provide a clearer indication of what to expect. Meanwhile, the retail sales report is not anticipated to significantly alter the broader narrative of consumer resilience, despite some recent indications of a cooling labour market that could signal a deceleration in consumption growth.

What does Brooks Macdonald think

Although the tech sector underperformed yesterday, it is still the biggest driver of recent market momentum. Tuesday’s gains in the stock market, post-CPI release, were propelled by tech companies such as Nvidia and Oracle, which reported earnings that surpassed expectations, and Wednesday’s modest pullback was again led by the tech industry. Notably, Tesla’s shares dropped by 4.54%, making it the poorest performer in the S&P 500 year-to-date with a 31.8% decline, surpassing Boeing’s downturn. This increasing divergence within the tech mega-caps is certainly one to watch as it could affect overall investors’ sentiment and the scope of broadening of the current equity market rally.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

14/03/2024

Team No Comments

Evelyn Partners – Investment Outlook

Please see below March’s Investment Outlook from Evelyn Partners, which was received late yesterday (12/03/2024) afternoon:

Balancing growth and inflation

Global economic growth continues to be resilient, providing a backbone of support for companies to deliver on analysts’ earnings expectations. The J.P. Morgan Global Composite Purchasing Managers’ Index, a lead indicator for Gross Domestic Product (GDP), covering both manufacturing and services, shows evidence of gathering steam in January. It reached a level that is consistent with global real GDP growth of 2.8% and has steadily improved over the last few months.

In short, economies have been able to defy the pessimistic expectations from a year ago due largely to healthy job creation as firms continue to replace workers that left the workforce during the Covid pandemic. US demand for available workers (employed plus job openings) is running around 2 million higher than the supply of workers (employed plus unemployed). This points to a healthy jobs market and increases the likelihood that the US can avoid a recession.

A key risk for financial markets is that rapid growth rekindles inflationary pressure and central bankers reconsider their intentions to cut interest rates. Although in the Monetary Policy Committee’s (MPC) last interest rate setting meeting, some Bank of England (BoE) observers noted that inflation could drop below 2% in spring, enough to warrant an interest rate cut. Indeed, the BoE removed its tightening bias and shifted to a more neutral setting by arguing that risks were “more evenly balanced”.

However, elevated wage growth is still a concern for the hawks on the MPC. The Bank’s annual Agents Survey expects wages to expand by 5.4% in 2024, which is above the latest 4% rate of consumer price inflation in January. Should wage data come in stronger than expected it could lead to upward, cost-push pressure on prices. Under that scenario investors could have to wait until later in the year for interest rate cuts.

Wage inflation is less of a problem for the US central bank. The comprehensive Employment Cost Index (ECI), which includes wages, bonuses, and benefits for US civilian workers, grew 4.2% in the fourth quarter of 2023 from a year ago. This is down from a peak of 5.1% in the second quarter of 2022. Importantly, the number of workers quitting their jobs to look for better paid opportunities has steadily fallen over the past year. As a lead indicator for the ECI, the quit rate suggests that the risk of an upward spiral in overall compensation rates has likely eased. Given that consumer inflation is getting close to its 2% target rate, the Federal Reserve will probably feel confident to begin an interest rate cutting cycle in the coming months.

Overall, investors are becoming a little more comfortable that central banks can balance growth and inflation. Given the economic backdrop is relatively benign, the pressure could be on firms to exceed, or at least meet, market expectations for company earnings, and particularly for large-cap stocks.

Size matters for earnings delivery

The Magnificent Seven companies (i.e. Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla) have become a dominant proportion of equity benchmarks. This group currently accounts for 29% of the S&P 500 by market capitalisation and were responsible for around 60% of the returns achieved by the index in 2023.

These Magnificent Seven stocks generated significant net income to enable them to outperform the equity benchmark last year. However, this year has been a different story, as only four of the seven names are currently outperforming the S&P 500. This recent earnings season could hold some clues as to why. Nvidia and Meta have been the biggest drivers of returns so far in 2024, as both companies beat analysts’ estimates and posted strong earnings figures for the fourth quarter of 2023. Take Nvidia, a company that is best known for designing some of the world’s most advanced computing chips. It has seen its earnings for the most recent quarter increase by over 450% compared to 12 months prior.

This rapidly increasing demand for chips is due to firms implementing Artificial Intelligence (AI) into their businesses, as advanced chips are essential to accelerating AI-led processes. This bumper earnings report saw Nvidia’s market capitalisation increase by over $275 billion on the day following its latest earnings announcement, the largest daily increase in market value for any listed company ever.

In contrast, Tesla has been the worst performer of the group this year. It was the only member of the Magnificent Seven to miss on analyst earnings expectations in the fourth quarter and has since seen large downward revisions to its earnings growth outlook. Falling profit margins have hindered the electric vehicle maker’s profitability. This could be in part due to recent price cuts implemented to stay competitive against rival Chinese electric vehicle manufacturers. With this constrained earnings outlook and considering that they’re the only member with a market value below $1 trillion, it might be time to reassess their membership of this exclusive club.

To summarise, the macro environment remains supportive for company earnings, and particularly for large cap stocks to drive the overall market. However, there are still risks. Analysts have already forecast strong earnings outlooks for most of these Magnificent Seven companies over the next five years and valuations have been bid up. The risk is this group of stocks fail to achieve these elevated expectations. Given the Magnificent Seven make up a decent chunk of the US (and global) stock markets, should they miss their earnings forecasts it would likely prove a headwind for stocks overall. Nevertheless, on balance, solid economic growth and lower inflation means this risk is probably manageable.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

13/03/2024

Team No Comments

Blackfinch Investment LTD – The Monday Market Update

Please see the below article from Blackfinch Investment LTD providing a brief analysis of the key factors currently affecting global markets and economies. Received yesterday.

UK

Chancellor of the Exchequer, Jeremy Hunt, delivered a Spring Budget that received a muted market reaction. The key takeaway for households was that the main rate of Class 1 employee National Insurance Contributions would be reduced from 10% to 8% from 6th April. This was in addition to the 2p cut announced at the 2023 Autumn Statement 2023 which came into effect from 6th January.

Hunt also announced the introduction of a new Individual Savings Account (ISA) and British Savings Bonds. The UK ISA will give savers an extra £5,000 tax-free allowance on top of the existing £20,000 ISA allowance, to encourage investment into UK-focused assets.

The latest House Price Index from Halifax reported that UK house prices increased 0.4% in February, the fifth monthly rise in a row. Property prices were 1.7% higher on an annual basis, a slowdown from the 2.3% increase in the 12 months to January. An average UK home now costs £291,699, around £1,000 more than last month.

Housebuilding, which has been contracting in recent months, saw its biggest turnaround since January. The Purchasing Managers’ Index (PMI) jumped to 49.8, up from the previous month’s 44.2, reflecting the recent boost in sentiment that interest rate cuts are coming this year.

The S&P Global UK composite PMI, which tracks activity at services companies and manufacturers, increased from 52.9 in January to 53.0 in February. This indicated a pick-up in growth, after service sector companies reported a sustained increase in business activity, with the fastest rise in new work since May 2023.

North America

Recent US economic data boosted expectations that the Federal Reserve could begin cutting rates sooner than expected, with concern of a ‘hot’ jobs market beginning to dissipate. The US unemployment rate rose to 3.9%, the highest since January 2022, against expectations of staying at 3.7%. In terms of wage growth, average hourly earnings rose 0.1% in February from January, less than the 0.3% growth forecast by economists. Finally, the US Labor Department reported the US economy added 275k jobs in February, more than the expected 200k.

Europe

The European Central Bank (ECB) left its key interest rate at 4.50% after its latest policy meeting. Importantly, its latest staff projections show inflation forecasts has been revised down to an average 2.3% in 2024 and 2.0% in 2025. These forecasts has raised hopes that borrowing costs could come down sooner than thought.

Turkey’s consumer price index (CPI) increased by 67.07% annually in February, up from 64.9% in January, showing prices rising even faster than expected. On a monthly basis, prices rose by 4.53% in February. The Turkish central bank maintained interest rates at 45%, pausing a hiking cycle that had lifted borrowing costs by 3,650 basis points since May 2023. A year ago, rates were down at 8.5%, before a series of hikes to cool inflation.

The final Eurozone Gross Domestic Product (GDP) estimate confirmed the economy stagnated in Q4, barely improving on the 0.1% contraction seen in Q3. A historical data revision meant overall GDP growth came in at 0.4% last year, 0.1% lower than previously thought.

German factory orders plunged 11.3% month-on-month in January following an upwardly-revised 12% rise in December 2023. While the wild swings were attributed to volatility in big-ticket orders, core orders shrank 2.1% over the month. Core investment and consumer goods orders contracted over the month, as the impact of past rate hikes dampened consumer demand and the elevated uncertainty derailed investment.

Asia

According to the revised estimates, Japanese GDP grew 0.1% quarter-on-quarter in the fourth quarter of 2023, instead of a 0.1% dip in the initial estimate, reflecting an upgrade in business investment.

India became the fourth largest stock market in the world with a market capitalisation of INR 390trn (over USD 4.6trn) at the end of February, following five consecutive years of growth. The bull run reflects the combination of strong domestic and foreign buying.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

12/03/2024

Team No Comments

Tatton Investment Management: Monday Digest

Please see below, Tatton Investment Management’s ‘Monday Digest’ providing a brief analysis of the key factors currently affecting global markets and economies. Received this morning – 11/03/2024

At least currency markets noticed the budget

Markets gained again last week, with the S&P 500 hitting another all-time high. But thanks to sterling gaining 1.5% against the US dollar, our table shows negative index returns. Sterling strength may be partly about Jeremy Hunt’s budget, despite the chancellor not giving away so much in the way of fiscal handouts. 

The national insurance cut could boost growth, while the freezing of fuel duties will not. The extra ISA allowance seemed more about show; more of a sop than a solution to Britain’s obvious domestic investment problems. Even these small offerings were enough to send our currency higher, though, with foreign investors becoming more optimistic on sterling assets. The outperformance of UK small cap versus large cap was encouraging too.

Rishi Sunak is unlikely to remain Prime Minister for long, but foreign investors are predicting a relatively smooth transition to a new centrist government, and the budget bolstered those perceptions. Mortgage holders will thank him for not raising borrowing costs. So too will the Labour Party, as it means they will more likely be able to borrow to invest.

The euro also rose, thanks to the European Central Bank (ECB) leaving interest rates unchanged. The ECB will likely cut by the summer, but President Lagarde seems reluctant to be the first developed market central banker to cut. Federal Reserve chair Jay Powell was similarly mildly hawkish in his testimony to US congress, but investors think a cut is at hand. 

Data released on Friday suggests 275,000 US jobs were added in February. That is extremely strong, but the initial data is suspect, as shown by downward revisions to December and January’s initial estimates. Citi Research’s economic surprise indicator shows US economy data is now undershooting economists’ expectations. UK data is starting to beat lowered forecasts while Europe is increasingly beating economist expectations – a great benefit to European equity markets and currency. 

What stands out the most, though, is falling volatility across markets – back to or below pre-pandemic levels in most cases. This tends to go in hand with higher equity valuations, as we are seeing now. High valuations also mean that the market has priced in strong future growth. It may be difficult to get more optimistic so that may mean only mild capital gains. We are likely to see more weeks with small gains but little drama.

Tight might soon feel tighter

Balance sheet adjustments – buying or selling assets – are one of the key ways the Federal Reserve (Fed) manages liquidity in the financial system. One of the most impressive things about the Fed’s post-pandemic quantitative tightening (QT – the selling of bonds and mortgage-backed securities) is that it has gotten so little attention. The infamous ‘taper tantrum’ of 2013 caused upsets in markets – and that was just a suggestion that the Fed might not buy as many bonds as it had, not the current outright balance sheet reduction. 

Reverse repo operations are one of the key tools the Fed has used to temper the effects of QT. In these, the Fed sells securities for cash now and, at the same time, buys them back at a future settlement date – thereby reducing the current cash in the system. They were crucial in the pandemic for draining excess liquidity that the Fed’s own QE had injected, which was causing short-term “congestion”. Reverse repos have been falling significantly for a while, and this reduction has counteracted the tightening effects of QT. The Fed has been tightening with one hand and loosening with another. 

That will likely change, though. The Fed hasn’t told us of any definite plans to taper QT (it is in the ‘talking about talking about it phase’) but the rate of change in reverse repos has already fallen and will level off more the closer operations get to zero. Continuing QT in this phase will probably mean that tight may feel tighter, making markets more volatile.

The key indicator is the gap between interbank lending and the Fed’s reserve rate on repo. When they come closer together it means liquidity levels are at equilibrium. 

The Fed could offset any short-term problems by adjusting repos or QT – but we suspect this could become a politically charged topic this election year. Donald Trump might again criticize the Fed for buying up government debt, so the FOMC will want to keep a low profile. But in a sense they might be damned if they do (through allegations of political interference) and damned if they don’t (through market volatility). This poses more risks to stock and credit valuations. QT hasn’t hurt markets yet, but it still can.

Returning M&A returns?

Mergers and acquisitions are trending up. Corporate deals are usually a sign of business confidence, so it makes sense this is happening when markets are buoyant. M&A activity fell dramatically over the last year, thanks to interest rate rises, but Morgan Stanley researchers think we will see a 50% rise this year compared to 2023. 

M&A deals need motive and financial opportunity. Activity was massive during the pandemic thanks to extraordinary liquidity, but dramatically shrank through rate rises. Rates are now expected to fall – but rate expectations don’t necessarily set current funding costs. Corporate balance sheets and credit spreads have improved, though, while rallying stock markets have helped companies get more capital. We can see this in Capital One’s all-share buyout of Discover Financial, for example. 

There is a huge amount of ‘dry powder’ – capital ready to be invested – held by businesses or private equity funds. Morgan Stanley estimates that global non-financial companies hold $5.6 trillion in cash, while private investors sit on $2.5tn. The US will probably see a lot of activity in private market deals, with less visible partial takeovers or ‘carve-outs’. Regional banks will need to consolidate too, and real estate is primed for M&A. 

Researchers also think Europe will lead the way in M&A activity after a relative drought, with consolidations among asset managers and tie ups between telecoms companies. Japan will likely rebound too, thanks to cyclical factors as well as long-term improvements in corporate governance. Globally, Morgan Stanley expects financials to see the most deals, while energy, health and technology could also stand out. 

M&A activity could catalyse a rotation from growth to value in markets, since the targets for M&A are usually always undervalued companies. Broadly it should mean more money going into stock markets, but the previous big winners will have less to gain.

Please continue to check our blog content for advice and planning issues from leading investment houses.

Alex Kitteringham

11th March 2024

Team No Comments

Blackfinch Asset Management – Monthly Market Moves

Please see below article received from Blackfinch this morning, which provides a detailed global market update for February 2024.

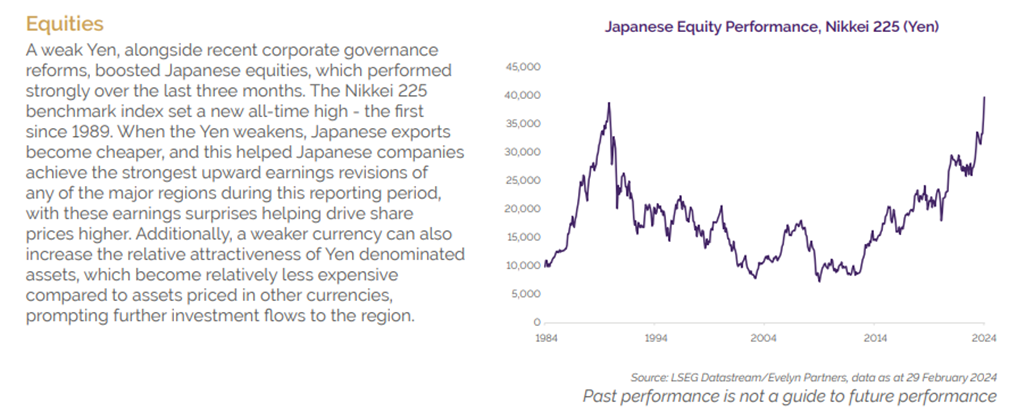
February was a record-breaking month for equity market returns, with several regional indices hitting all-time highs. The key stories were in the US and Japan, with US returns driven by the darling of the Artificial Intelligence (AI) world, Nvidia, boosting sentiment across the market. Japan boasted an impressive corporate earnings season, as well as stark improvements in corporate governance, which helped Japan’s largest index burst through the ceiling set at the end of 1989, when Tokyo real estate was the most valuable on the planet. On the economic front, the UK officially moved into its long-expected technical recession, which sparked some concern for domestic investors. Disappointing inflation data in the US was
largely shrugged off in equity markets by the sheer excitement of AI, as well as the US economy continuing its strong economic growth trend.

Bank of England hints that interest rate cuts are coming…
but not quite yet


• The UK officially moved into a technical recession – defined as two
consecutive quarters of falling national output – at the end of 2023.
The Office for National Statistics (ONS) reported that UK gross domestic
product (GDP) declined by a larger-than-expected 0.3% in the fourth
quarter, following a fall of 0.1% in the third quarter. Although this caused
some concern for local investors, Bank of England (BoE) Governor Andrew
Bailey said he expects this recession will be “shallow” and short-lived.


• UK consumer price index (CPI) inflation remained at 4% in January.
Economists had expected a small increase to 4.2%, meaning it was a softer
reading than predicted and reaffirmed hopes of meeting the BoE’s 2% target.

• The BoE’s decision to maintain interest rates at 5.25% in February, a 16-year high, was no surprise. However, the decision wasn’t unanimous, as varying Monetary Policy Committee (MPC) members voted in different directions, with some preferring to increase the rate by 0.25% and another member opting to reduce it by 0.25%.


• The ONS reported that annual growth in regular earnings, excluding
bonuses, was 6.2% in the fourth quarter of 2023, while pay rises, including
bonuses, reached 5.8%. Economists had expected 6.0% and 5.6%,
respectively. A strong jobs market and wage growth will likely make the
MPC apprehensive about cutting interest rates too soon.

China fighting an uphill battle to economic recovery


• China continued to fight deflationary pressures in January, adding to
uncertainty surrounding its economic outlook, with prices having fallen
at the fastest rate in 15 years. CPI inflation declined 0.8% year-on-year
for January, which marked the fourth straight month of declines and
the sharpest contraction since 2009, after the Global Financial Crisis.
The inflation rate was dragged down by falling food prices, which
dropped by 5.9% year-on-year.


• China did report some encouraging economic data in terms of increased
revenue. Revenue from tourism during the Lunar New Year holiday surged
47.3% year-on-year and surpassed 2019 levels. Domestic tourism spending
hit 632.7bn yuan (£69.7bn), according to government figures, thanks to a
domestic travel boom amid a longer-than-usual break.

• However, we are still seeing a continued trend that foreign direct investment (FDI) into China last year increased by the lowest amount since the early 1990s. China’s direct investment liabilities, a broad measure of FDI, rose by $33bn in 2023, down 81.7% from 2022, according to the State
Administration of Foreign Exchange.

US economy proves too strong for its own good, quashing hopes
of earlier interest rate cuts


• US CPI inflation declined to 3.1% in January, down from 3.4% in December,
but higher than the 2.9% reading economists expected. This was a
disappointing figure at the headline level.


• However, the Personal Consumption Expenditures (PCE) index – the
preferred inflation measure of the Federal Reserve (Fed) – increased by
2.4% in the year to January, down from 2.6% in December. This would have
helped reassure the Fed that inflationary pressures were easing. The core
PCE index, excluding food and energy costs, showed prices rose 2.8% in
the year to January, down from 2.9% a month earlier.


• Despite the positive PCE inflation news, the US jobs market appeared far
too strong for the Fed to consider cutting interest rates just yet. The US
Labor Department reported that employers added 353k new jobs in January taking the unemployment rate to 3.7%, still close to the 50-year low.

• The most disconcerting feature of the jobs report for the Fed was the
strength in worker pay, as average hourly earnings jumped by a surprisingly strong 0.6%. That was the fastest increase in two years, lifting the year-over-year increase to 4.5% from 4.3% in December. This is not the direction the Fed wants to see, as it views taming wages as a critical step in wrestling inflation down to its target.


Summary

As mentioned, it paid dividends to be an equity investor in February. Although economic data across the globe was somewhat mixed, investors in Western markets were again swept up in the AI craze. China was the surprise package for the month, however, with indices rallying due to more targeted stimulus measures from the government. Despite this, Chinese equities remain at 20+ year lows against broader equities. The mood music in the region is still gloomy, as overseas investment expanded at the slowest pace in 30 years in 2023, although GDP did grow by 5%.

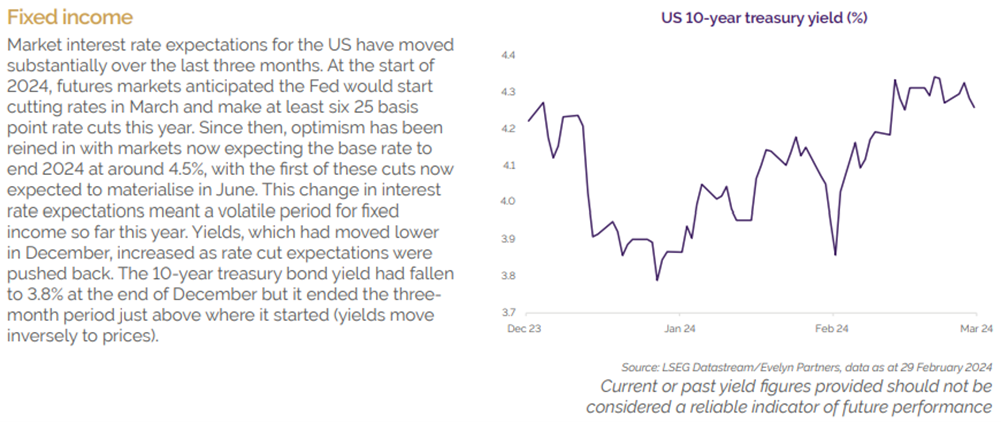
Turning to bonds, the outlook turned negative on rate cuts, with the yield on the ten-year UK government bond (gilt) rising from 3.79% at the start of February to 4.12% by the end of the month, and with the ten-year US Treasury yield increasing from 3.92% to finish the month paying 4.26%. The outlook for high-quality investment grade bonds continued to improve, as February saw over $150bn in new issuance in the US, a record-breaking amount.


Away from equities and bonds, property and infrastructure both fell in value for the month. These assets are particularly sensitive to shifts in interest rate expectations and fell victim to the conclusion from the market that interest rate cuts may not come as quickly as previously hoped, especially in the US.

Please check in again with us soon for further relevant content and market news.

Chloe

08/03/2024

Team No Comments

AJ Bell – 2024 Spring Budget Summary

Please see below an article published by AJ Bell late yesterday (06/03/2024) afternoon summarising the main points from the Chancellors Spring Budget which was delivered in Parliament yesterday.

Today’s Budget was short on surprises, with most of the key announcement already having been briefed to the national media advance.

Key changes announced today include the proposed introduction of a British ISA, a further cut to National Insurance rates for both employed and self-employed workers, relaxation of the ‘high income’ child benefit tax charge, and a proposed summer date for the government’s forthcoming NatWest share offer to retail investors.

British/UK ISA

The Chancellor announced plans to launch a new UK ISA (although he referred to it as a ‘British ISA’ during his speech in parliament), with an annual subscription allowance of £5,000

This will be in addition to the existing £20,000 ISA allowance, with all investments restricted to UK assets.

A consultation on the plans will run until 6 June 2024, with the government proposing that the UK ISA would be restricted to UK shares, gilts and UK corporate bonds. The consultation also suggests preventing holders keeping cash in the accounts, effectively forcing them to invest the money in UK assets.

There is still much to be confirmed and the proposals could yet change considerably, especially given that any future UK ISA product is likely to be introduced after the next General Election.

National Insurance

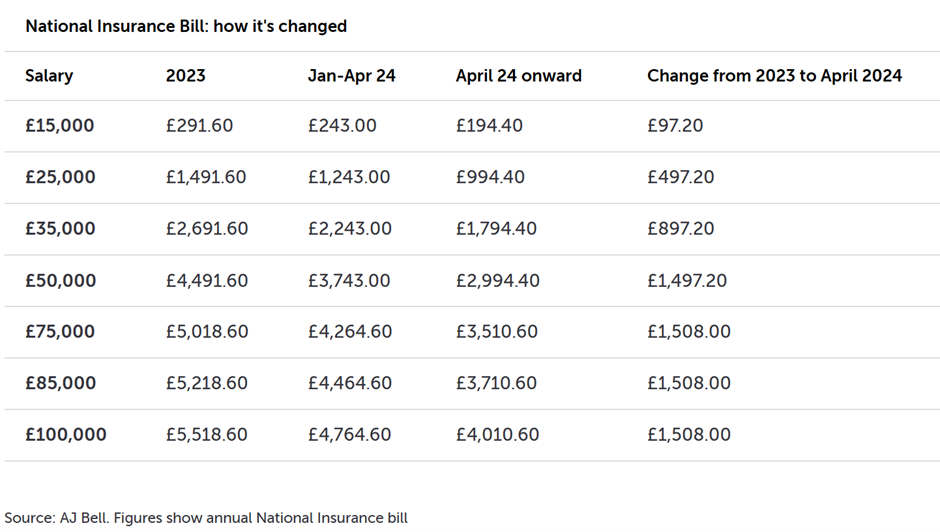
The government has announced a further cut of 2 percentage points to National Insurance, following the cut previously announced at the Autumn Statement and which applied to employed workers’ payslips from January this year.

In aggregate, it means a cut of 4 percentage points to the entry rate of National Insurance since December 2023, with better paid workers seeing a £1,508 boost as a result of the cuts.

It is worth bearing in mind that income tax thresholds have been put into deep freeze, creating a so-called ‘fiscal drag’ effect that has pulled many people into a higher rate of income tax.

For many taxpayers, these changes will only go part way to making up for the additional tax they’re paying as a result of the freeze on income tax thresholds and the personal allowance.

Self-employed NI will also be cut further. Around 2 million self-employed people will see a boost to their earnings from next month, as their National Insurance bill drops significantly. The previously-announced changes from the Autumn Statement were due to come in from April but have now been superseded by a further significant cut to rates. It means that the National Insurance rate for Class 4 contributions paid by the self employed has been cut from 9% to 6%, at the same time as the Government has scrapped Class 2 contributions.

Child benefit

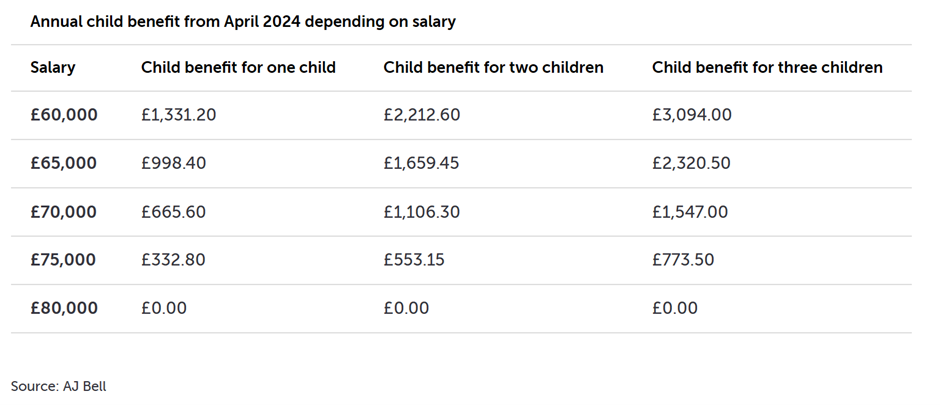
Under the current system, child benefit is gradually withdrawn for those earning more than £50,000 a year. It means households with one earner bringing home £60,000 a year currently get nothing (they can still claim child benefit, but repay it through the high income tax charge).

Under the government’s proposed reforms, the point at which child benefit begins to be withdrawn will increase to £60,000.

Those earning between £60,000-£80,000 a year will see their child benefit gradually withdrawn. So this is good news for those households with earnings of between £50,000-£80,000 who would previously have had to repay any child benefit claimed, but will now be eligible for at least some of it.

Looking further ahead, the government says it wants to reform the system so that eligibility is based on a couple’s combined earnings. Currently, a sole earner on £60,000 gets no child benefit while two earners each on £49,000 will get the full benefit. The reforms could change that, although they aren’t pencilled in until April 2026. Much could change before then.

NatWest

Government has previously pledged to launch a retail share offer for NatWest, giving ordinary investors a chance to buy a chunk of the bank, which remains partially under state ownership.

The Chancellor signalled this could happen in the summer ‘at the earliest’, declining to set a clear timetable for the sale.

There is a fine line to tread here, since the government needs to balance getting a good deal for the taxpayer, while also offering an enticing opportunity for investors without suppressing the value of shares already in circulation.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

07/03/2024

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update from Brewin Dolphin, which was received yesterday evening:

Guy Foster, Chief Strategist, discusses recent economic growth data, while Janet Mui, Head of Market Analysis, analyses US inflation and consumer spending data.

The trend of the market reaching new highs continued at the end of February. The S&P 500 had already broken new ground but was joined by the NASDAQ, which surpassed its previous high seen at the end of 2021.

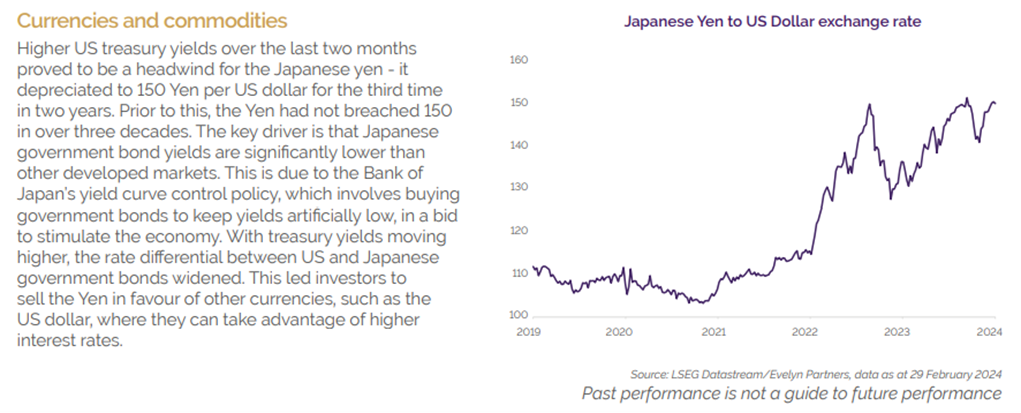
Japan has seen very strong index performance. Part of that has been aided by rapid yen depreciation. As a result, the Nikkei 225 also reached a new all-time high the week before last. But while the US markets are surpassing levels seen in 2021, the Nikkei is making a first all-time high since an extraordinary bubble in stocks and realestate at the end of the 1980s.

The Nikkei index is one of a few price-weighted indices (another being the Dow Jones in the US) where each company’s weight reflects how big its share price is rather than the relative size of the company. Japan’s more conventional TOPIX index remains well short of its late80’s high.

The FTSE 100 remains 4% off its record high, experienced early last year. Like many regions, the UK has underperformed the US recently, but the performance of indices exaggerates the extent. Overall, The UK market generates a dividend yield of 4% which is significantly driven by the energy sector.

Over the past couple of weeks, the stock market experienced fluctuations near record highs as traders awaited a barrage of economic data and remarks from Federal Reserve speakers on interest rates. The market absorbed heavy Treasury and corporate sales amidst month-end positioning, with US yields rising after government note auctions. Blue-chip companies sold a record amount of bonds in February to capitalise on investor demand amid lower borrowing costs.

The most obvious banana skin for the market overall was the US personal consumption expenditure (PCE) data. This ostensibly measures spending and feeds into gross domestic product (GDP). GDP is normally quoted in real terms, meaning it is adjusted for inflation. The Federal Reserve has typically preferred to measure consumer price changes through the PCE over the consumer prices index (CPI). PCE covers a broader range of goods and services, as well as a broader definition of consumers. The PCE process for changing the weightings of categories over time is perceived to be better, and its treatment of housing costs is more reflective of actual costs suffered by homeowners.

CPI, on the other hand, is released earlier during the month and certainly sounds more like the measures of inflation used in other regions (although some argue PCE is methodologically closer to other countries’ inflation calculations).

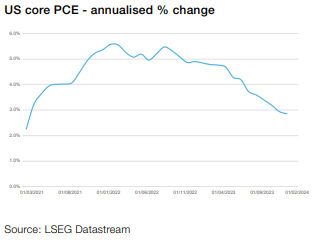
Perhaps the most critical difference between CPI and PCE in recent months is that core PCE, which excludes food and energy, has declined faster than core CPI, and thus paints a rosier picture of the consumer environment, which puts less pressure on policymakers to maintain high interest rates.

It was therefore a boon to investors to see the core PCE price index rising by just 2.8% over the twelve months to January (PCE data are released late relative to CPI). This is the slowest pace of price increases since March 2021. The data were taken positively by the market, seeming to justify hopes of lower interest rates later in the year. Afterall, real spending by consumers declined. But despite the slowdown in the annual rate of inflation, the monthly data were pretty strong, seeming more consistent with the CPI data from earlier in the month.

Gauging trends in inflation is difficult during January when a significant seasonal adjustment needs to be made. There were also a lot of one-off factors distorting consumer activity (such as weather), a strong month for dividend income, and a jump in cost-of-living adjustments for social security payments.

For now, markets expect to see interest rates declining as soon as June, but that will depend upon how policymakers interpret these data.

Federal Reserve speakers continued to influence market sentiment, with officials expressing readiness to lower rates if necessary. However, they emphasised the economy’s strength and the need for caution in policy adjustments.

Boston Federal Reserve president, Susan Collins, and New York’s John Williams, believe it will be appropriate to cut rates for the first time later this year, which is consistent with Raphael Bostic of the Atlanta Federal Reserve, who expects to cut this summer. Federal Reserve governor Michelle Bowman expects inflation to continue to decline further, with interest rates held at their current level — but said it’s too soon to begin rate cuts.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

06/03/2024

Team No Comments

Epic Investment Partners – The Daily Update | China Eyes 5% Growth / Microsoft Could Be A Lot More

Please see today’s daily update from EPIC Investment Partners below:

Chinese Premier Li Qiang has set the country an ambitious GDP target at “around 5%” for 2024. Moreover, Li announced steps to transform the nation’s development model, coupled with defusing the risks fuelled by bankrupt property developers and indebted cities. Li Qiang acknowledged the hurdles facing the world’s second-largest economy during his inaugural work report to the national parliament. “Realising these targets is not easy,” he said to the thousands of delegates gathered at Beijing’s Great Hall of the People. “Policy support and collective efforts from all fronts are essential”, he emphasised. Li also said that China aims to create over 12 million new urban jobs and keep the urban unemployment rate “at around 5.5%”. 

In a rare move, China will also issue CNY1tn (USD139bn) of ultra-long special treasury bonds this year and lower its deficit to 3% of GDP. The bond sale marks only the fourth of its kind in the past 26 years. The most recent sale was in 2020 when the Chinese government issued a similar special treasury bond to pay for Its pandemic response measures. Alongside the treasury bonds, local governments will be allowed to sell nearly CNY4tn of new special bonds, primarily to finance infrastructure spending. 

China’s defence spending will also grow by over 7% this year, the largest increase in five years. Defence spending is expected to rise to around CNY1.7tn ($234bn) in 2024, according to the annual Finance Ministry report. In contrast, the House of Representatives approved an USD886bn defence bill for the US towards the end of last year. 

Over to Microsoft, the largest holding in our Global Equity Fund, which released its ChatGPT AI system, seen by many as the introduction of AI to the masses, just over 300 trading days ago. Since its introduction, the Nasdaq has rallied around 46%. Following the release of Netscape, the first internet web browser in December 1994, the Nasdaq also rallied 46%, in approximately 300 days.  

What happened next? +725% for the next 5 years. 

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Charlotte Clarke

05/03/2024

Team No Comments

Tatton Investment Management – The Monday Digest

Please see the below article from Tatton Investment Management providing a brief analysis of global economic news and market data. Received this morning – 04/03/2024.

Overview: Winners and losers of stabilising yields

Last week was one of positive price action in equities, although the US mega-caps did less well, while bond markets were rather stable. Indeed, stable bond markets are one of the reasons why equity markets can continue to edge up. Interest rates and yields appear close to equilibrium levels, a state of relative steadiness which enables activity to happen. There were no big mergers or acquisitions last week but it is noticeable that companies are increasingly trying to raise equity rather than loan capital. Bloomberg pointed out that companies are finding the near-term cost of equity much more bearable now that dividend yields have fallen in relation to bond yields.

What has struck us in recent weeks is that consumer and business behaviours appear to be sensitive to quite small changes in rates. Small businesses are negatively sensitive and step up efforts to cut costs and reduce debt on any sign of a rise. Particularly in the UK, households are positively impacted by lower mortgage rates which drive a swift rise in housing activity. Currently, US rates are just about bearable for both camps. However, this also implies that the Federal Reserve (Fed) is unlikely to cut interest rates meaningfully. February data suggested US inflation was stabilising just below the 3% level –consistent with a slight Fed easing in the summer or autumn. This Thursday, the European Central Bank (ECB) conducts the first of March’s central bank meetings. We think both the Bank of England (BoE) and the ECB ought to be on the verge of rate cuts. Growth is not collapsing, but neither is it rising. By focusing on labour pricing power alone, they miss the point that it is businesses that are paying that price. It is neither being funded out of money creation nor reflected in rising prices. Unfortunately, for yet another month, we will analyse words, not actions.

February 2024 asset returns review

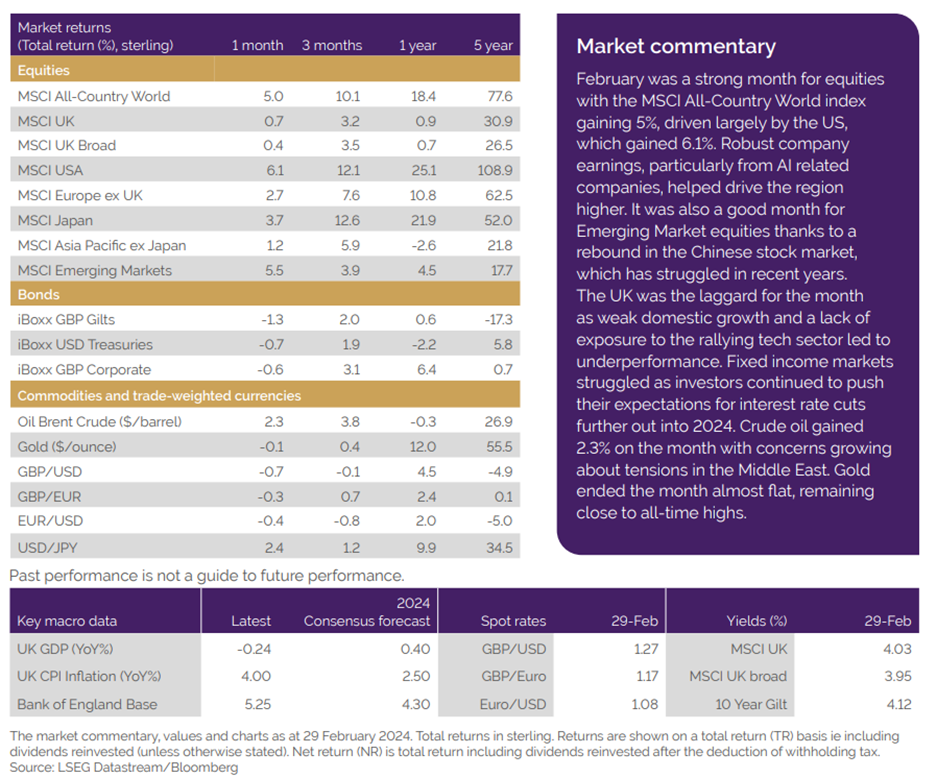
Despite a mid-month lull, February turned out to be yet another strong month for investors, with global stocks delivering a very healthy 4.4% in sterling terms. The US was once again one of the strongest performers, with the S&P 500 jumping 5.2% in sterling terms. February’s broad-based rally was a good sign, allaying previous concerns that too much capital was focused on the US mega-tech sector. Speculation over an artificial intelligence (AI) asset bubble grew before and after Nvidia’s stellar earnings report, with revenue up 265% and profit up over 750% for the year. Euphoria seemed to peak last week though, and trading since has been much more muted. There was also a pick-up in US mergers and acquisitions, a sign of changes in market composition, which helped bring confidence to markets. One clear sign of this is the weaker dollar, suggesting solid global growth expectations. This was also reflected in bond yields, which weakened at the start of the month but subsequently recovered to recent highs.

European stocks gained a respectable 2.9% through February in sterling terms. So far, 2024 has been a steady incline for Europe, but as we have written before, the continent stands to benefit from stronger global growth. If the ECB is able to cut rates soon (and before the Fed) and Chinese demand comes through strong, it will be a potent recipe for growth. The FTSE 100 ended February with a 0.7% gain, ensuring a slight decline in year-to-date returns at -0.6%. Smaller British companies in particular – being more closely tied to the dynamics of the domestic economy – are having a hard time, with UK small-cap equities down 1.2% last month. The disparity between the UK and other markets – particularly the US – leaves UK equities with relatively attractive valuations, at least.

Chinese equities gained an impressive 9.3% in sterling terms, making it the best-performing region for the month. Weak demand and goods prices out of China have been a decisive factor behind lower commodity prices. Accordingly, there was an upswing in oil prices last week, and the commodity index we track gained 1.3% in sterling terms through February. Growing positivity in the global economy is a welcome sign, as is the fact that returns are no longer solely focused on AI. The worry, as usual, is that this could mean returning inflation pressures and a delay in central bank easing. There is no sign of that yet, but we will keep a close eye.

Nigeria shows why reform is always difficult

When Nigeria’s President Bola Tinubu came to power last May, Western investors cheered his embrace of market-friendly policies. These included removing the currency peg with the US dollar, dealing with the consequences of a botched attempt to move Nigeria’s cash-based economy into electronic banking, and scrapping Nigeria’s nationwide fuel subsidies. The latter reform was specifically recommended by the International Monetary Fund (IMF) and Tinubu won plaudits from the World Bank. But Nigeria’s economy has only worsened since; inflation is at nearly 30% and the naira has lost more than 70% since the peg’s removal.

To cushion rapid inflation and a tanking currency, the Central Bank of Nigeria (led by Dr Olayemi Cardoso) raised interest rates last week by an outsized 4% to 22.75%, when a 2.5% lift was expected. The move leaves Nigerian rates at their highest recorded level, but it may still not be enough. The country’s highest inflation rate this millennium is now being driven by currency collapse – itself an effect of dramatic capital outflows. There seems to be a run on Nigerian assets from both foreign and domestic investors, and it is unclear what would stop the flow. The experience of other countries has been that it requires rates to be far enough above inflation to tempt investors to risk earning the ‘carry’ (yield).

Part of the problem is some very unfortunate timing. When global energy prices skyrocketed two years ago, commodity-producing nations like Nigeria benefitted greatly. But what followed, the sharpest monetary policy squeeze in a generation, combined with dramatically lower commodity prices, had the opposite effect. In the last year, when inflation has been steadily declining in Western developed countries, Nigeria and other EM nations have been under increased pressure. Nigeria’s government is thereby focusing on what it can do alone, thereby reducing its economic dependency on the big economies of the US and China.

Last year, the government allowed the regulated banks to resume trading in cryptocurrencies, given that many Nigerians are involved in this market, with some commentators even suggesting that flows from Nigeria were a factor in the recent resurgence of Bitcoin. However, the Nigerian authorities have become worried that the crypto market is part of the Naira’s current instability and so banned the use of the unregulated exchanges. Gaining control of its sliding currency is a necessary first step in stabilising the economy, always a very difficult one to take, and one which modern markets make even more difficult.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

04/03/2024

Team No Comments

The Daily Update | PCE In Line / NYCB Spooks Markets Again

Please see below article received from EPIC Investment Partners this morning, which reports on the latest economic data from the US.

The Fed’s preferred inflation gauge, the personal consumption expenditure deflator (PCE) was broadly in-line with expectations in February, increasing 0.3%mom, slightly ahead of December’s 0.2% print. On an annual basis, PCE was 2.4%, in-line with expectations and 0.2% below the previous reading.  

The core print was along the same lines, coming in 0.4%mom, versus a prior of 0.2%, while the annual value ticked down a tenth to 2.8%, mainly due to base effects. Both the numbers were in-line with market expectations.   

Stronger data, including inflation, has very much been the theme so far this year. However, the Fed along with the market will be looking to see if this has been a “fluke”, or a new trend. Fed speakers Bostic, Goolsbee, and Daly all seemingly unperturbed and continued to tow the party line.  

Goolsbee said we shouldn’t extrapolate one month’s data, Bostic said it shows that the path to target inflation will have bumps along the way, and the dovish Daly repeated that she advocates for policy rate cuts ahead of reaching the 2% target. Additionally, the historically more hawkish Mester reiterated William’s message yesterday, stating that three cuts for 2024 “still sounds about right”.   

Meanwhile, New York Community Bancorp (NYCB) was again in the headlines yesterday after they released several announcements that spooked the market, who were already on edge since the lender reported its exposure to commercial real estate (CRE).  

Regulatory filings from its management “identified material weaknesses in the Company’s internal controls related to internal loan review.” The bank attributed the problems to “ineffective oversight, risk assessment and monitoring activities”.  

The news reignited the controversy that began in January when the company, a significant lender for New York apartments and CRE, announced it was amassing cash to safeguard against possible loan issues. The stock fell over 26% in after-hours trading, on top of the more than 53% it has already lost this year.  

As we have said before, US banks alone hold about USD2.7tn in commercial real estate debt, of which a significant percentage is now underwater.  

We reiterate, this could be a canary in the coal mine that we will be keeping a very close eye on. 

Please check in again with us soon for further relevant content and market news.

Chloe

01/03/2024