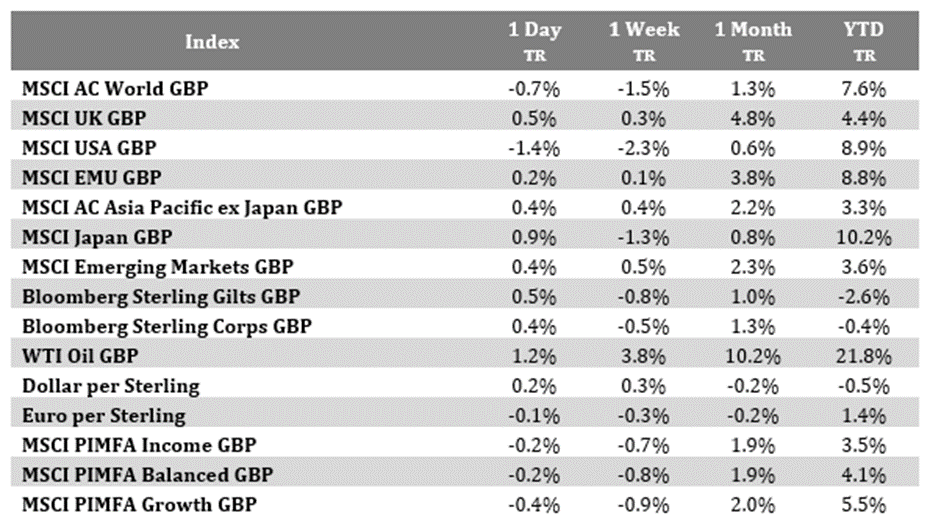
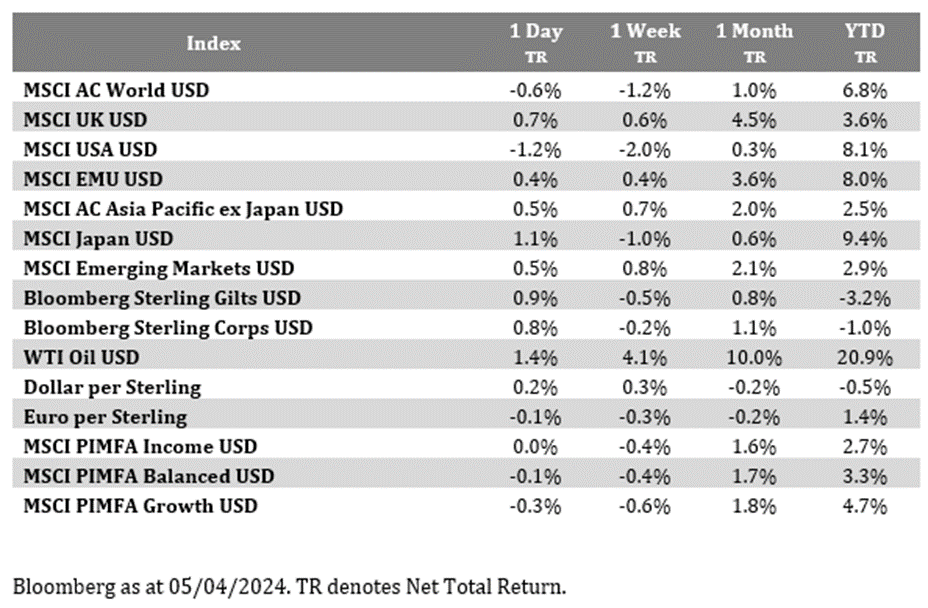
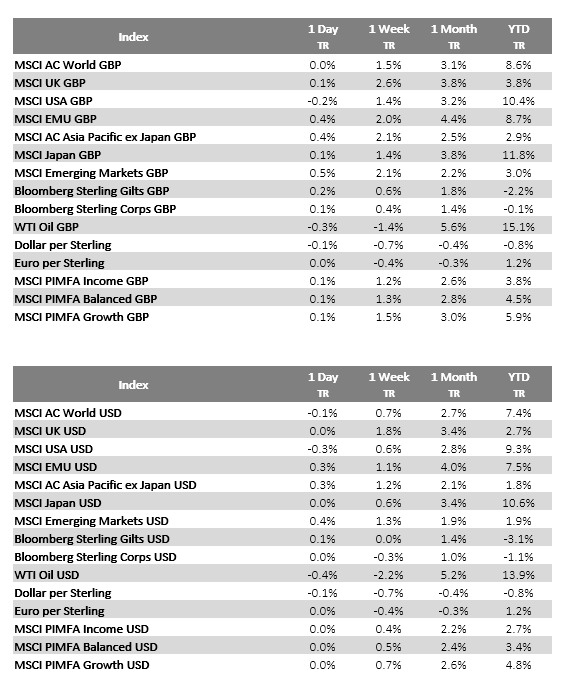
Please see below this yesterday’s global market round-up from Brewin Dolphin, which was received late yesterday afternoon – 09/04/2024:
Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.
What has happened
Government bond pricing in both the US and Europe fell back (with bond yields rising) on Monday, as markets moved to cut hopes for the number of interest rate cuts this year. For context, at the start of the year, markets were pricing in more than six quarter-percentage-point cuts this year from the US Federal Reserve (Fed) – on Monday, this number was standing at less than three. Adding to the latest shift in view, US bank JPMorgan CEO Jamie Dimon said in his annual letter to shareholders, that the US economy “is being fuelled by large amounts of government deficit spending and past stimulus … this may lead to stickier inflation and higher rates than markets expect.” Staying with inflation, ahead of tomorrow’s US consumer inflation data, yesterday we got the latest New York Fed Survey of Consumer Expectations – to be fair it showed a bit of a mixed picture on inflation expectations, though the good news is that 5-year expectations fell by -0.3% points on the previous month, down to +2.6%,
Markets now fully pricing in just two rate cuts from the Fed
Market confidence around the number of interest rate cuts out of the Fed looked to wane further on Monday. Verus the Fed’s ‘dot plot’ of its members which showed last month a median expectation of three quarter-percentage-point cuts this year, markets on Monday moved to price in 61.5 basis points (bps) of cuts by the Fed’s December 2024 meeting, a fall of -3.3bps on the previous day – it implies that only two 0.25% rate cuts are currently being fully discounted.
Middle East tensions take a breather, but China fills the geopolitical gap
Oil prices saw a modest dip down from a five-month high on Monday after Israel said it would remove some troops from Gaza, helping to cool some of the previous week’s geopolitics-led gains. Instead, China looked to be filling the geopolitical gap on Monday- it emerged that US President Biden is expected to warn China about its increasingly aggressive activity in the South China Seas later this week during planned summits with Japan and the Philippines. According to newswires yesterday, a senior US official was quoted as saying that “China is underestimating the potential for escalation … China needs to examine its tactics or risk some serious blowback.”
What does Brooks Macdonald think
There is debate currently as to whether we might see some interest rate policy divergence between the Fed and the European Central Bank (ECB). In the case of the Fed, the probability of an interest rate cut by the US central bank’s June meeting is down to just 52% currently (the lowest since October last year), and the total number of Fed cuts priced by the December 2024 meeting is now just 61.5bps. Contrast that with the ECB where the probably of a cut by June is higher at 91% currently, and the total number of cuts by December 2024 is also higher at 80.5bps currently. All in all, it points to a contrast in the differing economic backdrops with the US showing relatively stronger economic growth currently, but with it, the risk of relatively stickier inflation as well.
Please check in with us again soon for further relevant content and market news.
Please see below, Tatton Investment Management’s ‘Monday Digest’ which summarises all the key factors currently affecting global markets and economies:
Overview: Bumpy start to the quarter
Last week saw 2024’s first real bout of volatility. The S&P 500 had its biggest one-day percentage range in over a year on Thursday. This came after two extremely strong quarters for investors. Indeed, we suspect it was a response to the bull run, and the valuation gap between large and small caps it made.
Commentators attributed it to more headline-grabbing news, like Israel-Iran tensions and the sharp increase in oil prices. It could also be down to asset reallocation from big investors though, as tends to happen at the start of the quarter.
If so, that would mean investors moving away from the US mega-caps that have dominated for so long. Small and mid-cap profits and expectations actually fell over the last year, despite strong US growth. As a result, small and mid-caps are trading at valuations around their historical average price-to-earnings ratio, while the S&P 500 is trading well above. This seems logicical, given small and mid-cap earnings have fallen about 11% since 2023, while large caps’ have climbed 8%. However, this still leaves a 20% unexplained valuation gap between the two stock market segments.
Part of that is about the difference in available financing – since higher interest rates usually hurt smaller or riskier companies more. Small caps will struggle to get capital before rates fall, but 2024 rate cuts keep being pushed back thanks to the resilient US economy. Jobs and wages are still growing, and nominal growth around 5% looks set to stay.
Fed members are playing down the prospect of rate cuts soon. Not only is growth still strong, but the Fed doesn’t want to be seen as partisan in an election year – especially so considering they still hold massive amounts of US treasury debt. This has already created distortions they have had to clean up.
There are good reasons to think small and midcap equities could catch up and outperform US mega-caps. If recession risks fade and rates do start to come down, smaller companies will find it easier to borrow and their risk premia – the return investors demand for a given level of risk – should come closer to that for large companies. The only way this wouldn’t happen is if people think US growth will stay top-heavy, which is unlikely if rates fall and the recovery goes ahead.
The risk is that rates go higher rather than lower, though. Although it might be a good long-term view, rational investors could be in for a rocky ride.
March Asset Review
Global stocks gained an impressive 3.3% in sterling terms through March, capping off an impressive 9.2% rally for Q1 2024. Falling volatility was a key theme of the month and quarter. It tells us investors’ appetite for risk assets has increased – evidenced by the fact virtually all major stock markets were positive.
Markets appear convinced of “immaculate disinflation” – lower price pressures but growth staying decent – and central bankers now seem to be reading from the same page. The Bank of England and the US Federal Reserve both said last month that interest rates will likely be cut by the summer. That led to a 0.9% pick up in global bond prices (the inverse of yields) in March – contrary to the virtually flat trend overall for Q1.
Underlying the -0.1% return for bonds in Q1 is the fact that markets are now pricing in significantly fewer rate cuts for 2024. But it shows how good markets feel, given stocks have roared ahead anyway. Since the late October trough, global stocks have jumped 20% in sterling terms.
UK stocks finally caught up in March too, beating all other regions with a 4.8% jump. BoE messaging and brighter growth prospects were key, but so too was the rally in oil prices, as the FTSE 100 features several big energy companies. Brent crude quietly rose to a five-month high of $90 per barrel.
Europe beat expectations too, rallying 3.7%. China was on the lower end, gaining just 0.8% on the month and finishing Q1 down -1.5% in sterling terms. Chinese stocks improved into the end of March, though, thanks to policy support and stronger business sentiment.
China’s long underperformance might be ending, but that could well mean its disinflationary impulse ends too. If it starts exuding inflation instead, that could hurt markets’ rosy view of the world economy. Let’s hope that view isn’t too good to be true.
Oil breaking higher
Oil prices have had an impressive but underappreciated rally this year: Brent crude is up more than 17% year-to-date, to its highest level since October. Back then, weak global demand preceded falling prices into the end of 2023 – contributing to market excitement around disinflation. The current oil rally therefore threatens to undo some of the progress on inflation.
Middle Eastern tensions and Ukrainian strikes against Russian refineries are constraining supply, but OPEC+, led by Russia and Saudi Arabia, is sticking to its production cuts of 2.2 million barrels a day until June. The cartel’s discipline and cohesion in the face of sharply higher prices has been surprising.
There are also suggestions that Russia’s underproduction is down to a lack of expertise or capacity, following the departure of Western oil companies. Russian production is running significantly below quota, with little sign of improving.
Demand has been strikingly strong, too. Oil inventories declined January, a month they usually build, and demand is way ahead of estimates. The growth recovery in China and the continued resilience of the US consumer are two key factors.
Technical factors could support oil too. History suggests the break above $90 per barrel might mean speculative trading, and spot prices have gone higher than future delivery. There is clearly price momentum and speculation, which seems likely to support prices for now.
The rally doesn’t fit with markets’ overall disinflation story, and if rates fall and growth recovers as expected, it should mean even more oil demand. On the other hand, the very dynamic US production could fill some of the supply gap, and OPEC might allow more production if Russia is lagging. The cartel doesn’t want to crush demand with too high prices.
Speculative rises can often fizzle out too, especially in the era of AI-related high frequency trading. Brent might reach $100, but anything beyond that will be hard to maintain.
Please continue to check our blog content for the latest advice and planning issues from us and leading investment managers.
Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.
What has happened
Equity markets were initially building for a small up-day yesterday, but after Europe closed, in later US hours trading things took a sharp turn down. The US S&P 500 equity index fell by over 2% intraday, ending the session down – 1.23%. The main catalyst for the fall was rising tensions in the Middle East, which has pushed oil prices higher, and in turn adding to worries around the risks for resurgent inflationary pressures. In better economic news, yesterday saw the Euro Area composite PMI (Purchasing Managers Index) which was up to 50.3 for March, versus February’s 49.2, and marking the first time it has been in expansionary territory in ten months. Later today, markets will be focused on the US labour market, with US non-farm payroll numbers for March due – payrolls are seen increasing by at least 200,000 for a fourth straight month. Average hourly earnings are projected to climb 4.1% from the same month last year, which would be the smallest annual advance since mid-2021.
Oil prices hit $91 a barrel
Brent crude oil prices have made new 5-month highs in early trading this morning, building on yesterday’s gains, and briefly trading above $91 per barrel. The latest rise follows mounting geopolitical tensions around the Middle East – Israel has increased preparations for potential retaliation by Tehran after Monday’s strike on an Iranian diplomatic compound in Syria. Meanwhile, US President Joe Biden told Israeli Prime Minister Benjamin Netanyahu this week that US support for the war in Gaza depends on new steps to protect civilians. Separately, Netanyahu said at his country’s security cabinet meeting that Israel will operate against Iran and its proxies and will hurt those who seek to harm it. Oil has rallied this year on the back of combination of tightening global supplies, better than expected demand, and geopolitical risks in both Russia-Ukraine and the Middle East. Finally, regarding Russia, a NATO official said yesterday that Ukrainian drone strikes on Russian refineries may have disrupted more than 15% of Russian capacity, potentially adding to supply constraints.
US dollar strength is not good news for some
This year has seen an arguably already strong dollar move stronger, boosted as markets have in recent months reduced their expectations for the scale of likely Fed rate cuts later this year. As a result, a resurgent US dollar is causing problems for central bankers and governments around the world, forcing them into action to relieve the pressure on their own currencies. By way of example, Japan’s Finance Minister Shun’ichi Suzuki last week warned of “bold measures” to bolster the yen, while Turkey unexpectedly hiked interest rates last month, and elsewhere, Swedish officials have recently said a weaker krona could delay its first move to ease interest rates.
What does Brooks Macdonald think
Exchange rates matter because a depreciating currency can risk increasing the cost of imported goods for the country in question, leading to a drive-up in inflation. Meanwhile, there’s also an increased risk that investment flows could also move away from a country with a weakening currency in search of higher expected returns elsewhere. This so-called ‘capital flight’, which can harm domestic investment and growth, can be a risk for some emerging market countries in particular given their often relative economic reliance on investment inflows to start with.
Please check in again with us soon for further relevant content and market news.
Please see the below article from Brewin Dolphin detailing their key takeaways from global markets. Received yesterday.
Guy Foster, Chief Strategist, discusses the market movements of technology and energy stocks and bond yields. Plus, Janet Mui, Head of Market Analysis, analyses updated purchasing managers indices from the UK, U.S., and China.
The final week before the Easter break was a reasonably positive one for investors. The S&P 500 continued to reach new all-time highs and from a technical perspective there were encouraging signs.
For those concerned about the narrowness of the market earlier in the year, evidence of leadership shifting from technology and growth companies to a broader range of companies is good news.
Sometimes, technical analysis conflicts with fundamental analysis.
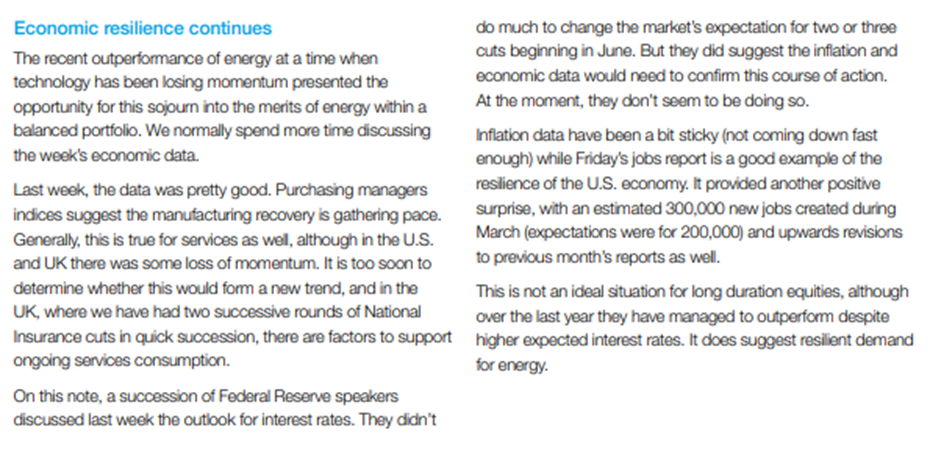
It’s encouraging to see broader participation in market gains, but amongst that increased breadth, energy stocks have been shining in recent weeks. Their strength reflects the return of some inflationary pressure from higher energy prices.
The oil price has risen into the mid $80s per barrel, close to its 2023 peak. The Organization of the Petroleum Exporting Countries (OPEC+) has maintained production cuts despite pressure from members to exploit reserves while demand remains high.
Energy stocks remain a valuable component of portfolios as companies are careful not to over invest, as was their tendency during previous cycles. This should enable the sector to maintain an unusual level of profitability. The energy sector also offers some benefits from a portfolio construction perspective because, as discussed above, energy price rises can be a problem for the economy and for growth equities.
So far in the first quarter, energy prices have contributed to a number of drivers of inflation, which the market has maintained a relaxed attitude to.
Last week, Federal Reserve board member Christopher Waller, who is known as a relatively hawkish member of the Federal Open Market Committee (FOMC), which sets interest rates in the U.S., explained that he sees the recent data on the economic outlook and the labour market to be showing continued strength. This, alongside slower progress in reducing inflation, persuades him that there should be no rush to reduce interest rates.
As it stands, the chance of a cut in June (the meeting after next) remains at a little over 50%, which seems surprisingly high based on current data.
How does Easter affect markets?
Last week was a shortened week for the UK due to the Good Friday bank holiday. The U.S. does not treat Good Friday as a federal holiday, but the stock market does remain closed on that day, by convention. Apart from the UK and U.S., several other markets were open despite strong Christian traditions leading to unusually thin trading.
Various trading strategies have determined there is both a Maundy Thursday and an Easter Monday effect, whereby these days exhibit above average gains relative to other markets. The general prevalence of markets to rise more often than they fall, and the tendency of price moves to be larger during times of lower liquidity, could explain these effects. However, these effects are less pronounced now that algorithmic trading, which doesn’t take holidays into account, has evened out some of the fluctuations in trading activity.
Easter has traditionally been a period of relatively benign markets with the more traumatic market events tending to be associated with September and October. However, it’s almost exactly 16 years ago that Bear Sterns was eventually rescued through its acquisition by JP Morgan, after seeing assets diminished by subprime mortgage exposure, an event eventually overshadowed by the failure of Lehman Brothers later that year.
The bunny and the bubble
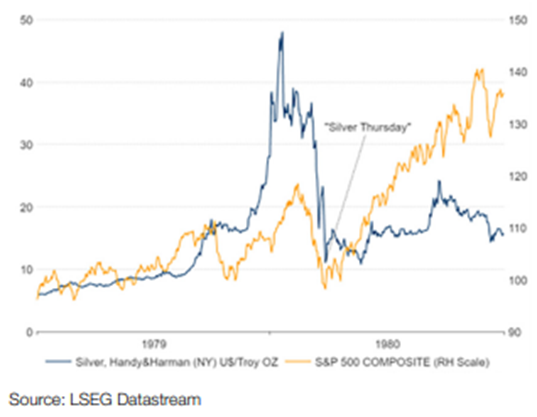
In 1980, Easter marked a tough time for the markets, which had suffered from fears of contagion effects as a speculative bubble in silver was unwound.
45 years ago, almost to the day, Silver Thursday occurred when three brothers (the Hunts) failed in their attempt to corner the silver market, believing the metal to be intrinsically under-valued as a hedge against inflation. Their aggressive accumulation of silver futures contracts sent prices up 500%. However, in response to apparent manipulation, regulators increased margin requirements, forcing the brothers to liquidate positions and resulting in an even sharper decline in prices with possible implications for financial stability.
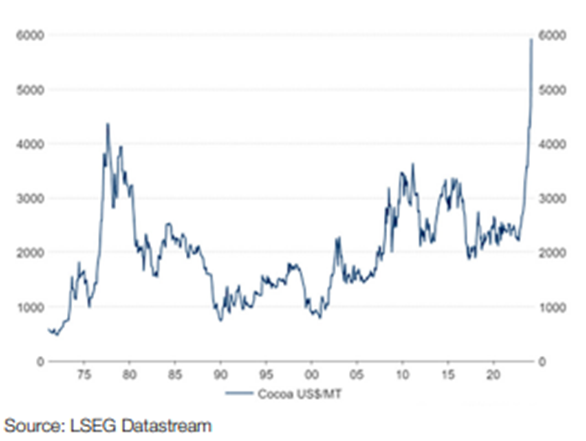
Today, cocoa is experiencing a sharp appreciation. Whilst it’s tempting to attribute this to Easter egg demand, it’s mainly a function of supply shortages due to low crop yields in West Africa, where weather conditions have been too dry. The rise in fertiliser costs driven by the war in Ukraine is also a factor. And yes, demand for chocolate has remained strong among consumers.
The direct impact on inflation will be modest, but it’s one more factor alongside the rise in energy prices, last week’s collapse of Baltimore’s Francis Scott Key Bridge, and continued harassment of shipping in the Red Sea, which has seen Suez Canal volumes down around 50% compared with the same period last year, according to the International Monetary Fund (IMF). These factors make it understandable that policymakers would be wary of easing monetary policy too fast and risking a resumption of the upward inflationary trend.
Please continue to check our blog content for advice, planning issues and the latest investment, market, and economic updates from leading investment houses.
Please see today’s Daily Investment Bulletin from Brooks Macdonald, received this morning:
What has happened
Tuesday saw something of collective risk-off in world markets following the higher-than-expected US manufacturing survey ‘Prices Paid’ print on Monday, its highest reading since July 2022. Stocks and bonds dropped in markets around the world as speculation mounted that major central banks might have to keep interest rates higher for longer. In the US the S&P 500 (-0.72% on the day) saw its worst daily performance in 4 weeks, and in Europe the STOXX 600 (-0.80% on the day) saw its worst daily performance in 7 weeks.
Better economic data signals resilience
Adding to the sense that we might be returning to a narrative where interest rates could stay higher for longer, Tuesday saw a clutch of perceived-resilient economic data. The latest US JOLTS job openings print (so-called as it’s the US Job Openings and Labor Turnover Survey), showed job openings in the US were at 8.756m, a shade higher than the 8.73m expected. Also out yesterday was US factory orders, where new orders for US manufactured goods rose by 1.4% from the previous month, above market expectations of a 1% increase and pointing to further resilience of the US economy. Responding to the data, US 10-year treasury yields were up 3.9 basis points (bps) yesterday to 4.35%, marking the highest level since November 2023. The moves were also echoed in Europe yesterday, with rises there for various 10-year sovereign bonds. Closer to home, the final UK manufacturing Purchasing Manager Index (PMI) for March was revised up to 50.3 (versus the initial reading of 49.9), marking the first print in expansionary territory (represented by a number greater than 50), since July 2022.
Oil prices firmer
Echoing the better economic outlook, oil prices edged higher on Tuesday, touching $89 per barrel at one point intraday for Brent Crude, a level last reached in October last year. Subsequently, they have opened at $89.22 per barrel this morning. As an aside, the broader Bloomberg Commodity Spot Index hit a 4-month high yesterday.
What does Brooks Macdonald think
The recent economic data, out of the US in particular, has pointed to an economic outlook on a relatively solid footing in aggregate, at least in terms of versus expectations. The flipside is that this seems to be driving a revival of the “good news is bad news” inflexion for markets. This is the reaction function, that with good economic news, the worry in markets is that this could drive something of a resurgence in inflation pressures, and could therefore push central banks into a corner where they are forced to have to keep interest rates higher for longer. As a result, the higher that bond yields go, the more they risk becoming a potential headwind for equity valuations, at least in the short-term .. as such, the markets’ risk-off move yesterday was a reflection of that.
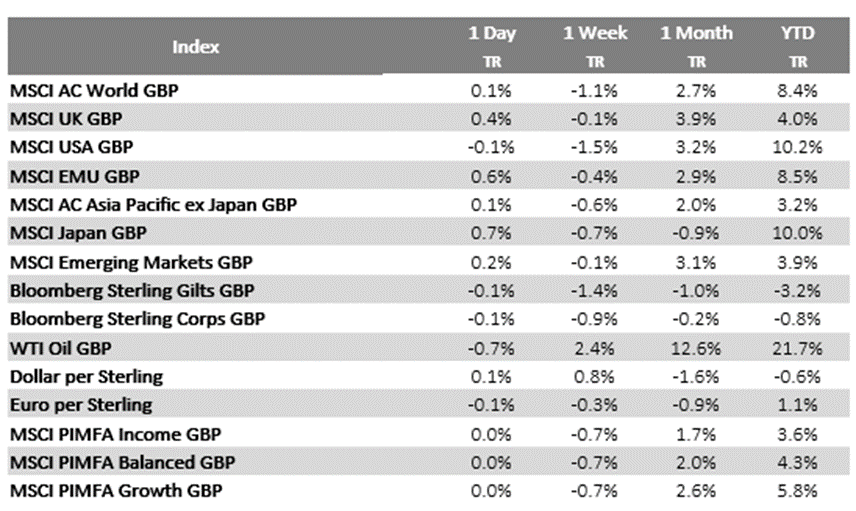
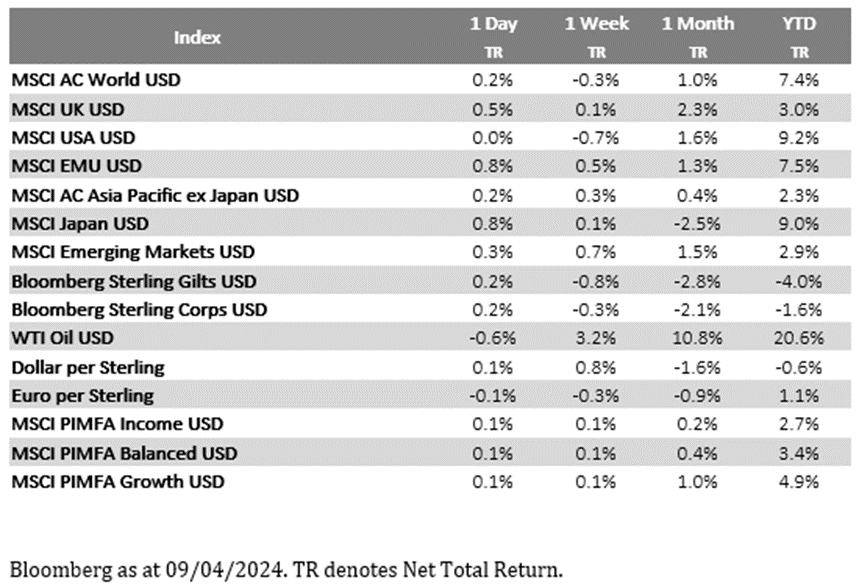
Bloomberg as at 03/04/2024. TR denotes Net Total Return.
Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see below, Tatton Investment Management’s ‘Tuesday Digest’ which summarises all the key factors currently affecting global markets and economies. Received this morning – 02/04/2024
Overview: Everyone is an optimist now
The first quarter of 2024 was another strong one for stocks. That’s a pleasant surprise, given the massive rally that came before. The MSCI World Index has only had one down week since the end of October, and has risen 25% in dollar terms in that time. UK stocks haven’t rallied as much, but the FTSE 100 is now within touching distance of 8,000 points. Flutter Entertainment’s recent US listing switch shows the unfortunate decline in the UK’s worldwide status, but London will keep being a hub for global capital flows even if trades are executed elsewhere.
Corporate bonds have also improved, even for riskier borrowers. Credit spreads have come down even though government yields have gone up slightly. That means overall borrowing costs for companies are only a little higher, on a net basis, than pre-rate rises. Rates are higher but growth is stronger and is expected to remain strong – so firms can afford it.
Volatility has come right down too, with the VIX index at levels not seen since 2019. But expected volatility – as measured by the MOVE index – remains high, suggesting investors are worried yields could spike again. If expectations come down to meet reality, there is still greater risk appetite to be awakened – good news for equities.
That might be fuel for another bullish quarter, but positivity is already priced in. While growth expectations and private sector balance sheets are generally better than pre-pandemic, public sector borrowing is a concern. We saw what this can do during Liz Truss’s not-so-mini budget, and BlackRock’s Larry Fink is warning that the US might be in for something similar. Expect the presidential election to throw a few fiscal bombshells at bond markets.
Another risk is that inflation could come back, with Brent Crude oil prices heading back to $90 per barrel. This could be nothing if oil supplies even out, but it could also spook markets in the short-term. Markets will now look to see if Q1’s corporate earnings results live up to the growth hype.
Inflation volatility creating inflation?
Central banks are now hinting that inflation has been beaten, without causing deep recessions. Commentators call it ‘immaculate disinflation’ and markets need no convincing: year-to-date stock returns are strong in the US, Europe and UK. But there are niggling signs of sticky inflation, particularly in the US and in the global services sector.
A recent paper from Evi Pappa of Carlos III University, Madrid, argues prices have not budged because of inflation volatility. We know that firms often raise prices when inflation is high – the dreaded wage-price spiral – but her research suggests this isn’t just when inflation is high, but when it is rapidly changing. That means we can still see inflationary behaviour even when inflation is coming down.
Intuitively, this is because it creates a feeling of price instability. Firms might want to keep prices high to protect against volatile costs, and consumers might be more willing to accept a higher price if they can’t work out what the fair price should be. Supermarkets regularly exploit this by putting ‘bargain deal’ labels on products to disguise underlying price rises.
Uncertainty is the key element – and we have had plenty of uncertainty in the last few years. This might be why central bankers were preaching ‘higher for longer’ for so long, against market expectations. Pappa’s research suggests that when inflation is volatile, rates need to stay high to discourage companies from building price buffers.
But we think the problem with this story is that it focuses entirely on the supply-side effects. Uncertainty also decreases demand by making consumers less willing to consume – as we have seen in the UK, Europe and China. It is hard to say whether the supply or demand effects will be stronger going forward. The dovish Fed seems to think demand, while the cautious ECB seems to think supply.
Carbon border adjustment
The UK is running a consultation on its carbon border adjustment mechanism (CBAM), to be rolled out in 2027. It follows the EU’s CBAM introduction last year, designed to level the playing field for emissions costs between domestic and foreign goods – a key pillar of net-zero targets.
CBAM is designed to fix a problem with the Emissions Trading System (ETS), a ‘cap-and-trade’ policy where firms trade carbon credits (which allow them to emit) on the open market. The UK and EU’s ETS systems are broadly the same, designed to let the ‘invisible hand’ of the market allocate emission rights to companies that most need them, while giving policymakers the power to control overall emissions.
Unfortunately, ETS leads to ‘carbon leakage’ – emissions from Europe or the UK just being replaced by emissions from somewhere with less stringent regulations. Not only does this negate the environmental impact of ETS, it means that foreign producers – like US companies under no ‘cap-and-trade’ scheme – have a price advantage over domestic producers.
CBAM is supposed to fix this by putting a “fair price on the carbon emitted” by companies selling into Europe. Importers buy CBAM certificates to match the emissions that went into their production (all of which must be thoroughly reported), and the price of certificates is set by the price of carbon credits. The EU’s CBAM is currently in a “transition phase” where firms have to report but not pay, which officials call “a learning period for all stakeholders”.
One of the biggest issues will likely be the sole focus on imports, leaving open the possibility that British and European exports might have a price disadvantage in global markets. The problem, as always with climate policy, is lack of international cohesion. We think CBAM will have a positive impact on reducing emissions, but could be another disadvantage for Europeans. We will watch the transition closely.
Please continue to check our blog content for the latest advice and planning issues from us and leading investment managers.
Please see the below daily update on the markets from EPIC Investment Partners received this morning:
A single mathematics equation kicked off not one, but four multi-trillion-dollar industries that completely transformed how we think about risk.
The crazy part? This game-changing equation originated from some unlikely places – like studying how heat transfers, beating the casino at blackjack, and figuring out why microscopic particles jiggle around randomly (Brownian motion). An unlikely bunch ended up cracking the code on making fortunes from it too – physicists, mathematicians, and scientists rather than stock traders.
The earliest known options were bought around 600 BC by the Greek philosopher Thales of Miletus. He believed that the coming summer would yield a bumper crop of olives. To make money off this idea, he could have purchased olive presses, which, if you were right, would be in great demand, but he didn’t have enough money to buy the machines. So instead, he went to all the existing olive press owners and paid them a little bit of money to secure the option to rent their presses in the summer for a specified price. When the harvest came, Thales was right, there were so many olives that the price of renting a press skyrocketed. Thales paid the press owners their pre-agreed price, and then he rented out the machines at a higher rate and pocketed the difference. Thales had executed the first known call option.
In the late 1800s, French mathematician Louis Bachelier had to take a job at the Paris Stock Exchange to support his family. Observing the chaotic trading floor made him realize that stock prices follow a random walk, just like the erratic movement of particles in Brownian motion. Options can be an incredibly useful investing tool, but what Bachelier saw on the trading floor was chaos, especially when it came to the price of stock options. Even though they had been around for hundreds of years, no one had found a good way to price them. Traders would just bargain to come to an agreement about what the price should be. Applying physics principles, he derived the first formula for accurately pricing stock options.
Fast-forward to the 1970s, and economists finally built upon Bachelier’s work to create the legendary Black-Scholes(-Merton) equation for option pricing. This was adopted by Wall Street faster than you can say “get rich quick.” In fact, it was the quickest adoption of an academic concept in history – it enabled the explosion of multi-trillion-dollar markets for options, derivatives, securitized debt and more. Being able to find patterns of behaviour in this randomness spawned massive hedge funds, led by mathematicians and physicists, that were able to arbitrage the difference between Black-Scholes implied options prices and market prices of those very options. Ed Thorp’s (the pioneer of blackjack’s card counting methodology) Ridgeline and Princeton funds annualised over 20%, and Jim Simons’ Medallion fund made an incredible 66% per year for 30 years by using cutting-edge data science.
Modern-day managers have come full circle – from explaining the randomness and chaos to now finding the remaining predictable patterns within it to make money. However, the mathematics of Black-Scholes(-Merton) transformed our relationship with risk and volatility forever, even creating trillion-dollar industries out of thin air!
Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see today’s Daily Investment Bulletin from Brooks Macdonald:
What has happened
The equity rebound that was in place for much of Tuesday’s trading session in global markets reversed into a net sell-off into the US close. Coming a bit out of the blue, as we have remarked earlier this week, as we close in on the long Easter weekend later this week, thinning trading volumes can at times contribute to increased volatility in asset markets, so this may have been a factor behind the late sell-off yesterday – that and perhaps some end-of-calendar-quarter repositioning might also have been in the mix. To be fair, it’s hard to pin the blame on the economic data that featured yesterday – in US focused-data, consumer confidence held more or less steady month-on-month, while durable goods data showed orders climbed above expectations. Elsewhere, in currency markets the drama over the last 24hrs has been around weakness in the Japanese Yen (JPY), which hit 34-year lows overnight (of 151.97 JPY to the US$) – the weakness was prompted by seen-as-dovish remarks from Bank of Japan (BoJ) member Tamura saying that the BoJ must proceed “slowly” towards normalising its ultra-loose policy. Finally, early morning data has showed that Australia’s inflation rate remained at +3.4% year-on-year in February for the third straight month against analyst expectations for a +3.5% gain.
US bridge collapse risks some inflationary supply-side shocks
In the early hours of Tuesday morning US time, a major bridge in Baltimore, Maryland collapsed after a container ship ‘Dali’, chartered by Danish shipping giant Maersk crashed into it. The Francis Scott Key Bridge, some 1.6 miles long, leads to the Port of Baltimore, the deepest harbour in Maryland’s Chesapeake Bay. It is the busiest US port for car shipments and is also the largest US port by volume for handling farm and construction machinery.
China’s Alibaba scraps logistics unit IPO
Chinese tech giant Alibaba announced on Tuesday that it was scrapping the planned US $1bn+ IPO of its Cainiao smart logistics unit (planned for the Hong Kong stock exchange), with the company citing “challenging IPO market conditions”. Alibaba’s shares are down around 18% over the past year. Reflecting deteriorating market conditions in China, with economic headwinds and hitherto regulatory uncertainty, Alibaba chairman Tsai described the market as “pretty depressed”.
What does Brooks Macdonald think
The US bridge collapse in Baltimore will likely have economic implications that serve as a reminder of supply-chain inflation risks. With global seaborne trade having to divert to other ports along the US eastern seaboard, the expected added cost impact is likely to ultimately feed through into higher prices to the US consumer, as businesses look to recoup increased transportation costs. As a result, at the edges it might show up in US inflation data in the coming months – while important to keep the size impact in perspective, it is nonetheless an additional incremental factor to add into the broader inflation mix for both markets and policymakers to reflect on.
Bloomberg as at 27/03/2024. TR denotes Net Total Return.
Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.
Please see this week’s Markets in a Minute update from Brewin Dolphin, which was received yesterday evening:
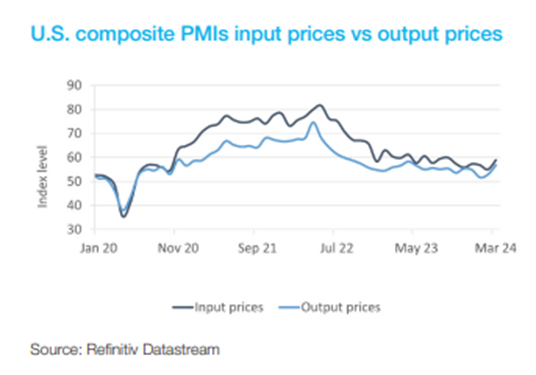
Guy Foster, Chief Strategist, discusses recent dovish interest rate announcements from central banks, while Janet Mui, Head of Market Analysis, analyses purchasing manager indices data from Europe and the U.S.
Last week was big for central bank meetings. Although it saw the Bank of Japan (BoJ) raise interest rates for the first time in 17 years, the week was really characterised by dovishness from the central banks.
Interest rates rise in the East
European investors woke up to the BoJ’s decision last Tuesday morning. Money markets considered it touch and go whether it would hike or not, while consensus forecasts were firmly for the BoJ to keep rates in negative territory. However, news at the end of last week on the outcomes of the “Shunto” wage negotiations made the case for tightening much stronger. The Shunto translates to the spring wage offensive and represents a set season for wage negotiations, so if workers ended up striking together, their employers would not lose market share to peers. RENGO, the Japanese equivalent of the Trade Union Congress (TUC), announced last week that settlements achieved so far were above 5%; they were well below 4% last year. So, inflation by this measure remains strong in Japan.
Other measures seem less conclusive. Most obviously, Thursday’s inflation report would have encouraged the BoJ to tread slowly. Although headline inflation rose over the last year, that was mainly to do with fuel subsidies from last year dropping out of the numbers. The latest monthly inflation prints have been soft. The best measure, seasonally adjusted monthly moves in the core inflation rate, has been too low for the BoJ to hit its inflation target for the last four months. So, although the BoJ did technically surprise the market with an interest rate increase, its rhetoric was cautious enough to leave the outlook for further rate increases wide open. More people are talking about this being a one and done rate hike from the BoJ, although the money market still expects another two hikes this year.
Economic activity edging higher
The most hawkish news for Japan came from Thursday’s purchasing managers indices (PMI). It showed the third consecutive expansion in activity overall, with services growing at the fastest pace in ten months, while the contraction in manufacturing was at its least severe since November. These data suggest demand is holding up in the economy. They also suggest that inflationary pressures remain, as output prices rose in both the manufacturing and services sectors, with higher raw material, fuel, transport, and staff costs being cited as the factors behind the increase.
Although the survey results suggest the above factors might be driving up Japanese prices, the fact that they are not evident in consumer price indices (CPI) suggests they could also be weighing on margins.
By contrast, the U.S. equivalent survey cited increased pricing power alongside “a steepening rise in costs”. This qualitative observation may tell us more about the disposition of the report author than the underlying economy, however, references to pricing power were notably absent from other regions.
U.S. interest rates left unchanged
The Federal Reserve left interest rate policy unchanged on Wednesday. It acknowledged that the economy is doing better than anticipated, easing its growth and inflation forecasts for the year. But the Fed also left unchanged its expectation of three interest rate cuts. That was a slight surprise as CPI data has run hot and the consumer remains resilient. This doesn’t seem to have changed the outlook for rates much, but it has stalled the upward march of year-end U.S. interest rate expectations that have been underway since mid-January.
With Japan raising rates and the U.S. expecting to cut rates, you could be forgiven for expecting the yen to strengthen. It rallied a little in response to the Fed’s meeting, but overall ended the week lower. The reason for this is that while Japanese rates rose last week, the increase was marginal. The more important driver of the exchange rate is where each respective currency’s interest rates will be in the future, and in relative terms, U.S. expected rates have been rising relative to Japanese expected rates (Japanese rates rising less than expected, but U.S. interest rates being cut by less than expected).
The outlook for liquidity
A big focus for the year will be on the timing of the Fed’s exit from quantitative tightening (QT). It sounds from Fed speakers as if this could be announced at its next meeting. This could be a positive story for markets because QT was assumed to be a factor that would weigh on investor demand by reducing liquidity that might otherwise find its way into equity and bond markets. In fact, equity markets have performed admirably while quantitative tightening has been going on, and liquidity watchers put this down to the reduced use of the Federal Reserve’s repo facility.
Repo means repurchase agreement, and it allows an asset owner to raise short-term liquidity by selling an asset, such as a government bond, to another investor whilst agreeing to buy it back at a future date and price. In this way, it turns assets into liquid cash.
Reverse repo, as you might expect, is the opposite; specifically, it involves a central bank such as the Federal Reserve selling securities into the financial system but agreeing to buy them back later. For the duration of the agreement, the Fed will have taken the proceeds out of circulation. So, increasing use of reverse repo is a way of tightening monetary policy and vice versa. The reverse repo facility has been declining as banks have used it less, bolstering their own reserves and offsetting the impact from quantitative tightening. But that decline will need to slow, stop, or even reverse at some stage, which will have an impact on liquidity. The Fed is looking at how this can be coordinated with the more stimulative impact of reduced quantitative tightening.
Markets were strong last week as the Fed reiterated its three-cut guidance, but they have been strong in previous weeks even when that has seemed in doubt. This loose liquidity environment has been one of the explanations, and as the Fed experiments with the winding down of QT and less liquidity is released from the reverse repurchase facility, there will likely be some wobbles in the market. A particular sector to watch will be the U.S. regional banking sector because any shortfall in liquidity is likely to be reflected in declining bank reserves and a return of solvency worries due to the bond assets these banks hold, which currently stand at a loss.
The UK hawks take flight
The final (major) central bank reporting last week was the Bank of England (BoE). Again, there was no surprise about its decision to leave interest rates unchanged, but what did stand out was the change in voting, where two hawks had previously voted to raise interest rates but this time aligned with the majority to keep them on hold. Unlike in other regions, inflation has been declining slightly faster than expected in the UK. Much of this relates to the delayed impact of the utility bills cap, which meant that inflation seemed slower to take off, before being sharper, and lingering longer, after which it is now declining faster once more. Indeed, inflation is expected to drop to, or even below, the BoE’s target in the next couple of months as high monthly increases from a year ago drop out of the latest figures. But it is not expected to last, and despite the downside surprise to UK inflation last week, when looking beneath the surface, those indicators of persistent inflationary pressure remain. The median price increase, having been stable but still marginally too high for the last few months, lurched upward this month.
Some of this lingering inflationary pressure is good news. It reflects the resilience of the UK economy and the fact that the UK seems to be emerging from a cyclical downtrend, as reflected in the PMIs. In addition, as we discussed last week, the housing sector is improving both in terms of demand and construction activity. And, of course, there has been a two, soon to be four, percentage point reduction in tax on a substantial portion of the income for people with a high propensity to spend.
But some of the persistent inflationary pressure is down to a lack of productive capacity, partly explained by a high rate of economic inactivity, which itself is driven by an increase in long-term sickness. No doubt this will be one of the key dividing lines for policy going into the next election.
Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.