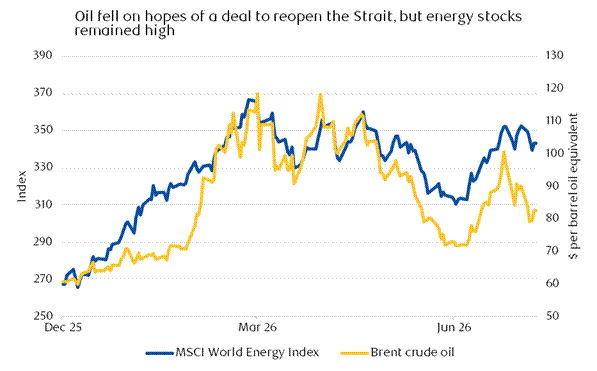Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, received this morning – 21/08/2026:

What has happened?

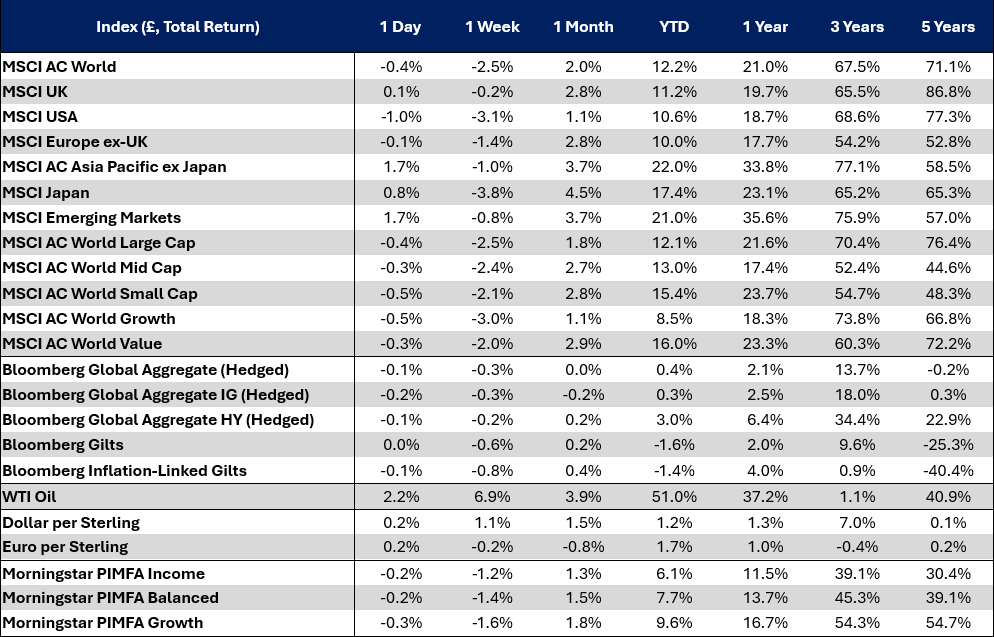
Global bond markets came under renewed pressure yesterday as Wednesday’s rally, triggered by the US Treasury’s plans to expand its buyback operations, quickly faded. US 10-year Treasury yields rose +5.8bps to 4.71%, while a further rise in oil prices added to inflation concerns. Brent crude climbed +2.4% to $93.78/bbl, extending its winning streak to five sessions. The combination of higher yields and rising energy prices weighed on sentiment, with the S&P 500 falling -0.9%, its largest decline of August so far. European markets also softened. French 10-year government bond yields reached a fresh post-2008 high, while UK gilt yields moved higher following stronger-than-expected CBI survey data. Equity performance was mixed, with modest declines across most major continental European indices, while the FTSE 100 edged slightly higher.


Markets seek reassurance but yields edged higher

Treasury yields rose despite efforts from US Treasury Secretary Scott Bessent to reassure markets. Speaking to CNBC, Bessent suggested that Treasury buybacks could be expanded and said policymakers still had a broad toolkit to support market functioning. He also indicated that greater emphasis would soon be placed on fiscal consolidation, although few details were provided. Despite some stabilisation later in the day, Treasury yields ultimately reversed most of Wednesday’s decline.


Oil surge fuels inflation concerns

Geopolitical tensions in the Middle East remained a key market focus, helping to push Brent crude above $93/bbl. The move higher in oil prices drove a sharp rise in inflation expectations, with the US one-year inflation swap recording its largest daily increase since March. Markets consequently nudged up expectations for further Federal Reserve tightening this year. Comments from St. Louis Fed President Musalem also reinforced the view that inflation remains elevated and that underlying demand pressures persist.


What does Brooks Macdonald think?

Importantly, yesterday’s economic data offered little evidence that higher yields are beginning to meaningfully slow the US economy. The Philadelphia Fed Business Outlook rose to its strongest level since 2021, while the survey’s capital expenditure expectations reached levels not seen for decades. Initial jobless claims also remained low, pointing to a labour market that continues to show resilience. Taken together, the combination of firm growth data, a stable labour market and rising energy prices helps explain why bond markets remain reluctant to price in a more benign inflation outlook.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Cherise Lancaster

21/08/2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, suggesting that markets recovered after the US Treasury unexpectedly announced an increase in its buyback operations, while investors remain cautious about the longer-term inflation outlook, received this morning – 20/08/2026

What has happened?

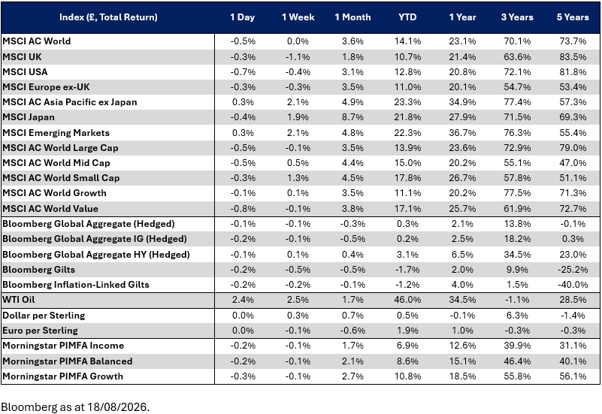
Markets recovered yesterday, led by a sharp rally in long-dated US government bonds after the US Treasury unexpectedly announced an increase in its buyback operations. The move pushed the 30-year Treasury yield down 9.2bps to 5.19%, marking its largest daily decline since June. Equities also benefited, with the S&P 500 rising +0.21%. Healthcare stocks outperformed after Moderna (+176.97%) and Merck (+12.60%) reported positive skin cancer vaccine trial results, although weakness in semiconductor shares continued to weigh on broader gains, with the Philadelphia Semiconductor Index falling -2.12%. Elsewhere, gold rose +4.18%, its strongest gain since March, while Brent crude climbed for a fourth consecutive session to $91.62/bbl.


A signal of support for long-term bonds

The Treasury announcement dominated market attention. Officials said they would at least double the size of buyback operations for longer-dated Treasuries, covering maturities from 10 to 30 years, beginning on 9 September. Although the increase is small relative to the overall Treasury market, it surprised investors given that the Treasury had published its provisional buyback schedule only two weeks earlier. More importantly, it signalled a willingness to support the long end of the market after 30-year Treasury yields reached their highest level since 2007 earlier this week. The result was a strong rally in longer-dated bonds and a notable flattening of the yield curve.


Fed minutes offer little urgency

Investors also reviewed the Fed’s July meeting minutes, which showed that “many participants” believed further tightening could be needed if inflation remained elevated. However, the language stopped short of signalling an imminent rate hike. As a result, expectations for further tightening eased slightly, with 2-year Treasury yields ending the session 0.8bps lower at 4.16%. The move was modest compared with the larger rally in longer-dated bonds.


What does Brooks Macdonald think?

The Treasury’s intervention provided immediate relief for long-dated bond markets, but it does not fundamentally change the underlying backdrop of resilient inflation pressures, elevated energy prices and large government borrowing requirements. The reaction across asset classes was particularly telling. While bond yields fell sharply, gold prices rallied strongly, suggesting investors remain cautious about the longer-term inflation outlook. At the same time, the modest decline in expectations for further Fed tightening indicates markets are becoming more confident, even if central banks remain reluctant to declare victory over inflation.


Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Alexander James Roberts

20/08/2026


Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 18/08/2026.

What’s driving U.S. stock record highs?

Discover why U.S. stocks continue to outperform despite ongoing tensions in the Middle East and softened economic data.

Key highlights

  • Cooling data provides breathing room: Signs of slower economic momentum reduced pressure on the Federal Reserve to immediately raise interest rates.
  • Markets are learning to live with geopolitical risk: Despite continuous tension between the U.S. and Iran and disruption to The Strait of Hormuz, the S&P 500 reached fresh highs.
  • Strong profits are supporting the bull market: An exceptional U.S. earnings season and growing evidence of AI monetisation are helping broaden the equity rally beyond a handful of technology leaders.

Cooling data, hotter market

U.S. data gave markets something close to a Goldilocks combination last week. U.S. inflation cooled following weaker jobs data, but there is still little evidence of a broader downturn.

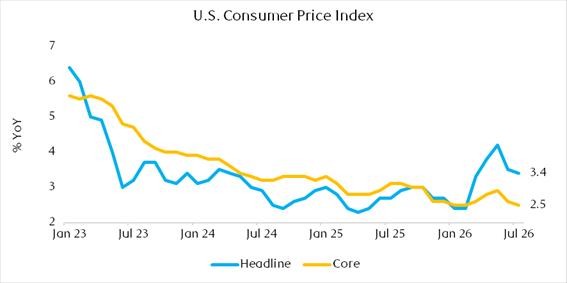
The July headline Consumer Price Index (CPI) rose just 0.1% over the month, taking annual inflation down to 3.4% from 3.5%. More importantly, core inflation rose 0.2%, with the annual rate easing to 2.5%. This was reassuring after surging oil prices raised fears that inflation could reaccelerate.
Source: Bloomberg

There were some yellow flags beneath the surface. Core goods prices accelerated and services inflation also remains sticky.

But producer prices provided relief. The headline Producer Price Index (PPI) was unchanged in July, contradicting expectations for an increase, while the annual rate slowed to 4.7% from 5.5%. This suggests the pipeline inflation pressure is weaker than feared.

Taken together, CPI and PPI have reduced the urgency for the Federal Reserve (the Fed) to immediately raise interest rates again.

This comes after last week’s surprisingly weak jobs report, which showed the U.S. economy lost 23,000 jobs in July. Retail sales also contracted in July, which provided another important test of consumer momentum.

Interestingly, markets currently seem comfortable with a little weakness in U.S. data as investors still see resilience rather than recession.

That distinction is important. The broader economy remains resilient and crucially, corporate profits are exceptionally strong. Some moderation in employment and consumer spending can be helpful for markets if it takes pressure off the Fed.

Markets sharply reduced the probability of a September rate hike following the inflation data, although an increase later this year remains possible.

For equities, that is a relatively favourable combination: growth is cooling enough to give the Fed room to wait, but not enough to derail corporate profits.

However, oil continues to be the obvious challenge to this Goldilocks scenario.

Markets learn to live with Hormuz

Developments surrounding the Strait of Hormuz remain one of the biggest macro risks facing markets given the unprecedented supply shock, but investors have become noticeably less reactive to each new headline.

The conflict remains unresolved and the Strait continues to face severe disruption. The U.S. has intensified its threats towards Iran, while Washington is preparing what Treasury Secretary Scott Bessent has described as “unprecedented additional economic measures” against Tehran.

President Donald Trump has alternated between a more conciliatory tone and renewed threats of pressure, creating occasional flare-ups in oil prices. Brent crude oil has nevertheless remained around the high-$80s per barrel, well below its earlier wartime peaks.

A renewed surge in oil would of course be a concern. It could push inflation higher again and potentially force the Fed back towards tightening.

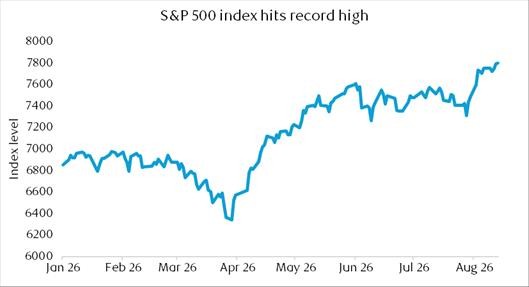
Despite this uncertainty, the S&P 500 reached record highs.
Source: Bloomberg

There is an element of geopolitical fatigue here. After months of U.S.-Iran tensions, markets are becoming more immune to individual headlines. Unless an escalation materially changes the outlook for energy supply, inflation or economic growth, investors appear increasingly willing to look through it.

Ultimately, fundamentals matter more. And right now, those fundamentals remain supportive.

Earnings give the bull market firmer foundations

The second-quarter U.S. earnings season has been extraordinary.

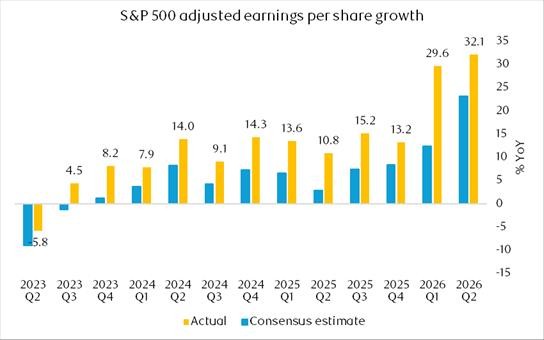
With almost 90% of the S&P 500 having reported by the end of last week, blended earnings growth stood at 50.4% year-on-year. That headline earnings growth number is inflated by hyperscalers’ investment gains from SpaceX, Anthropic and Open AI. Adjusting for those exceptional items that are not related to underlying business operations, S&P 500 earnings growth was still around 32%.

The strength of corporate America is not simply an accounting effect or an AI story.
Source: Bloomberg

At the same time, we are seeing more evidence that enormous investment in AI is translating into revenue and profit. Cloud demand specifically tied to AI has boomed, semiconductor earnings have surged and AI-related infrastructure spending continues to feed through the broader economy.

Perhaps even more encouraging is the broadening of the rally. Technology remains a major earnings engine, but profit growth is becoming less concentrated. That gives the bull market a healthier foundation than one driven purely by a handful of mega-cap stocks and rising valuations.

There are still risks. Expectations for AI are extremely high, valuations leave less room for disappointment, capital expenditure continues to rise rapidly, and free cash flow from hyperscalers have deteriorated.

But for now, the combination of strong earnings, improving AI monetisation and broader participation in profit growth gives investors a fundamental reason to remain constructive.

That also explains why markets have been able to absorb softer economic data and persistent geopolitical uncertainty. The macro backdrop may be cooling, but corporate America is not.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

19/08/2026



Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, received this morning – 18/08/2026:

What has happened?

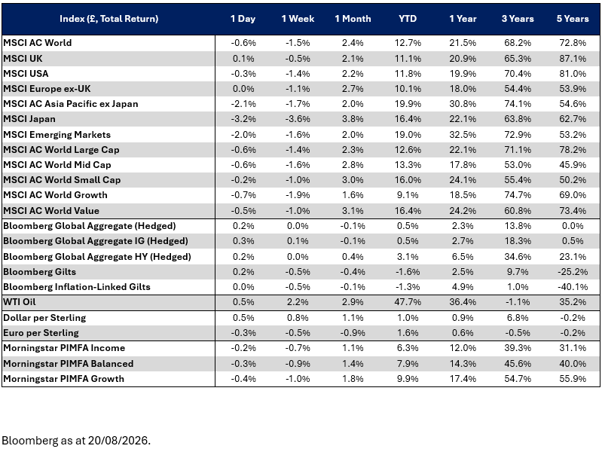
With little sign of a breakthrough between the US and Iran, investors increasingly priced in a prolonged disruption to oil supplies through the Strait of Hormuz. As a result, Brent crude oil rose +2.65% to close above $90/bbl for the first time in two weeks. The rise in oil prices weighed on risk assets on both sides of the Atlantic, as investors considered the potential inflationary impact of higher energy costs. The S&P 500 fell -0.52%, marking its weakest session of August so far, although a rebound in semiconductor stocks helped limit the decline, with the Philadelphia Semiconductor Index gaining +1.64%. Market weakness was broad-based, with the equal-weighted S&P 500 falling -0.92%, its largest decline in more than a month. European markets closed before the sell-off fully gathered pace, but the STOXX 600 still fell -0.22%, extending its losing streak to four consecutive sessions.

Markets brace for a longer standoff

Yesterday’s headlines suggested that both sides remain far apart from an agreement. President Trump said he had no interest in extending the 60-day memorandum of understanding agreed in June, while also reiterating that he was in no hurry to secure a deal. Although Trump referenced a potential back channel with members of Iran’s Revolutionary Guard, Iranian officials rejected the claim, stating that no talks were taking place. Comments from US Energy Secretary Chris Wright also pointed to a patient approach, with the administration focused on playing the “long game” with Iran.

What does Brooks Macdonald think?

Markets are responding not just to higher oil prices, but to what they could mean for inflation and interest rates. A sustained period of elevated energy costs would make it harder for inflation to continue moderating, potentially turning central banks more hawkish. This helps explain why bond markets also came under pressure yesterday, particularly at the longer end of the yield curve. 30-year government bond yields reached multi-year highs across several major markets, reflecting not only higher inflationary pressure but also lingering concerns over fiscal sustainability.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Andrew Lloyd

18/08/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing calm equity markets, AI-related earnings, stronger UK growth, yen intervention, and concerns over the sustainability of US margin expansion, received this morning – 17/08/2026.

Hot weather, chilled markets

Equity markets had another decent week, led by US tech stocks and AI-related earnings. Sentiment, more than fundamentals, explains the shift from July’s volatility to August’s calm: markets have stayed liquid through the summer lull, and leveraged retail investors were flushed out during July’s chip-stock sell-off. Worries are still there, in the main because long bond yields are slowly rising and unresponsive to the slow decline in global core inflation.

Two stories drove last week’s AI outperformance. The FT reported that Anthropic is seeking a $2 trillion IPO valuation, likely in October, beating SpaceX’s record. Meanwhile, CoreWeave’s Q2 results beat revenue forecasts, even as losses widened on higher capital spending. CoreWeave shares jumped 19%. Where investors punished the AI hyperscalers for similar spending last month, they now reward it. We think that’s down to improved liquidity, partly from the US-Japan yen intervention, which has lowered volatility and made investors more comfortable holding risk assets.

UK markets didn’t share the optimism, despite stronger-than-expected growth in June and surprisingly strong growth for Q2 of 1.7% (when annualised) which was powered, encouragingly, by business investment. Some commentators dismissed this as a one-off rebound, but we’d note the UK’s data has outpaced its narrative for a while now. Indeed, growth may be too strong, widening the trade deficit. Overall, though, the news is positive – activity looks reasonably well supported. 2026 is on course to exceed growth of 1.5% despite the extreme heat probably having shaved a few tenths of a percentage point from the total.

Risks remain despite the good mood. The IEA raised its 2026 oil shortfall estimate this week. Markets have grown numb to such warnings, but the underlying situation hasn’t gone away. Numbness cuts both ways: it could also blunt any relief rally if oil supplies improved. The next real test is Jackson Hole later this month, where new Fed Chair Kevin Warsh may signal how he plans to wean markets off central bank liquidity. Given that liquidity is currently buoying investor sentiment, his comments will matter a great deal.

Do currency interventions work?

August’s yen intervention was historic – the first joint US-Japan effort to support the currency in nearly 30 years, forced by the yen’s persistent slide against the dollar. The yen has already unwound some of its gains, so we’ve been looking at past interventions to gauge how long this one might last.

Currency intervention really only began with the 1971 Nixon shock (currencies weren’t free-floating before) and the IMF has allowed it since to counter “disorderly conditions”. The US, unhappy with its trade deficit against G5 nations, struck the 1985 Plaza Accord to weaken the dollar. The plan worked so well that the 1987 Louvre Accord was needed to stop the dollar’s slide, but Louvre couldn’t stop the yen’s rise.

Investors didn’t believe the Bank of Japan could control exchange rates, so piled into Japanese bonds, compressing yields and eventually inflating Japan’s equity bubble, whose collapse triggered Japan’s Lost Decades. It’s a reminder that standing in the way of structural imbalances is exceptionally hard, and can bring serious unintended consequences.

The problem now is yen weakness. Japan’s record current account surplus makes the currency look cheap, but investors won’t buy it, partly because Japanese holders of foreign assets prefer to reinvest abroad rather than repatriate their income. For the intervention to mark a turning point, Japanese investors need to start buying yen-denominated assets. Strong Japanese equities and more attractive bond yields should help, though only if yields elsewhere stop looking better.

The US, meanwhile, wants a weaker dollar over the long term, but Japan’s experience shows intervention cannot beat investor demand. We suspect this month’s action was more uncoordinated skin-saving than strategy – though the scale of the imbalance means it could yet force more coordinated policy, and perhaps a new Plaza Accord, in the weeks ahead.

Beware US margin expansion

US earnings growth looks strong, but the composition of that growth matters too. S&P 500 companies are expected to post around 24% earnings growth in 2026, yet only 9.6 percentage points of that comes from revenue growth. The rest is margin expansion and, as an AllianceBernstein research paper argued last month, margin growth is a less sustainable profit driver than rising sales.

Higher revenues reflect genuine demand and grow the overall pie; margin gains take a larger slice of the pie. They often stem from efficiencies or one-off benefits that are harder to repeat, and history shows strong margin growth tends to be followed by compression. Revenue growth itself boosts margins, and index-level margin growth can sometimes just result from share price gains for the higher-margin companies. But neither of those factors fully explain what’s happening now: broad-based margin expansion at the operating level too.

It might sound odd to complain about profitable companies. Corporate efficiency has long underpinned US outperformance – and we’ve argued that margin expansion is central to Japan’s recent positivity, for example. The difference is that US margins are already historically high and can’t expand indefinitely. High margins attract competition, as we’re already seeing among AI chipmakers, where booming profitability is drawing in new entrants and supply capacity.

There are reasons margins could stay elevated longer than usual, particularly if AI genuinely lifts productivity across the economy – though we’re still waiting for firm evidence of that. Big tech’s enormous AI infrastructure spending, aimed at fending off competitors, also blunts the usual competitive pressure on margins.
But politics are also a constraint. Companies that grow profits by squeezing customers or suppliers attract regulatory and public hostility. Affordability is already a major issue ahead of the US midterms, so unpopular datacentre-driven margin growth looks vulnerable. One way or another, companies cannot keep expanding their profit margins forever.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

17th August 2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, exploring how signs of easing US inflation pressures supported markets. It also highlights the recent decline in oil prices. Received on – 14/08/2026.

What has happened?

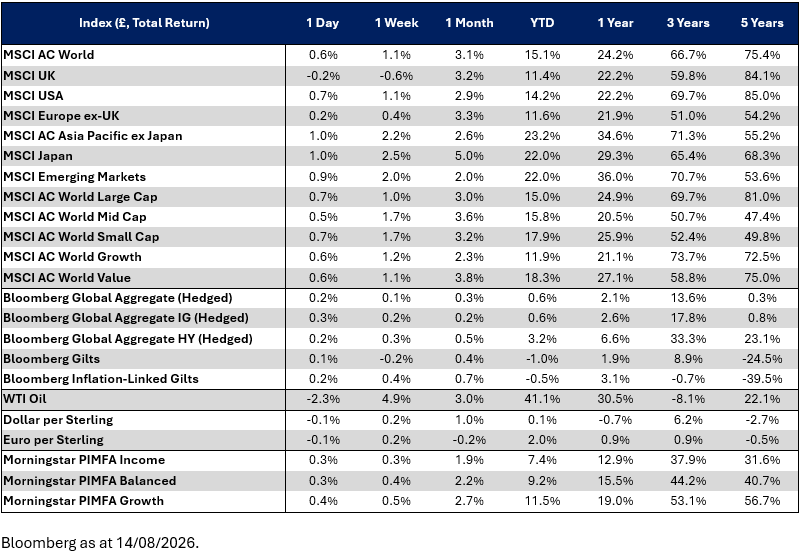
Investors continued to scale back expectations of a near-term Federal Reserve rate hike, helping the S&P 500 (+0.65%) reach fresh highs. The main catalyst was a softer-than-expected US producer price inflation (PPI) report, which reinforced the message from Wednesday’s CPI release that inflationary pressures may be easing. By the close, markets were pricing just a 35% chance of a Fed rate hike in September, down from more than 50% before the latest inflation data. European markets were less buoyant, however, with the STOXX 600 (-0.04%) slipping for a second consecutive day. This partly reflected Europe’s lower exposure to technology stocks and the fact that expectations for the European Central Bank remained largely unchanged, with investors still assigning a roughly 90% probability to a September rate increase.


Softer PPI print calms rate hike fears

Yesterday’s PPI report strengthened the view that the Fed may not need to tighten policy as aggressively as previously feared. Headline producer prices were unchanged in July, compared with expectations for a 0.2% increase, while annual PPI slowed to 4.7% from the expected 4.9%. The data suggested that the recent energy-driven inflation shock may be losing momentum, providing reassurance that inflation is moving in the right direction. Markets responded quickly, with September rate hike expectations falling immediately after the release.


Oil retreats as geopolitical premium eases

The dovish momentum received further support from lower oil prices, with Brent crude falling -2.15% to $87.07/bbl and snapping a six-day winning streak. Prices recovered from their intraday lows after reports that the Houthis were targeting an Aramco refinery in Saudi Arabia’s Jizan region, while Iranian officials reiterated threats around shipping through the Strait of Hormuz. Nevertheless, in the absence of any material escalation, markets unwound some of the geopolitical risk premium that had built up over the previous week, particularly given continued shipping activity through the region despite the tensions.


What does Brooks Macdonald think?

The market reaction over the past two days highlights how sensitive investors remain to inflation data and the implications for central bank policy. The latest CPI and PPI releases have provided reassurance that inflationary pressures may be easing, helping to reduce concerns about an imminent Fed rate hike. Investors remain cautious about removing the possibility of further tightening altogether, however, as both the August employment report and another CPI release are still due before the next Fed meeting.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Alexander James Roberts

14/08/2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, received this morning – 13/08/2026:

What has happened?

Markets took a modestly positive view of July’s US inflation data, with easing concerns about another near-term Federal Reserve rate hike helping risk assets gain ground. Headline and core inflation both came in as expected, and following last Friday’s softer employment report, investors saw less urgency for the Fed to tighten policy again in September. Shorter-dated Treasury yields edged lower, while continued strength in semiconductor stocks helped push the S&P 500 (+0.26%) to within a sliver of its record high. The equal-weighted S&P 500 (+0.16%) also reached a fresh high, pointing to broader market participation. The Philadelphia Semiconductor Index rising +2.49%. Gains have been supported by strong demand for AI infrastructure, with CoreWeave (+19.28%) and Super Micro (+19.02%) surging after delivering upbeat outlooks earlier in the week.


Inflation cools but not all price pressures have disappeared

The CPI report largely reinforced the narrative of gradual disinflation. Headline prices rose 0.1% month-on-month and 3.4% year-on-year in July, while core inflation increased by 0.2% on the month and 2.5% on the year, matching its slowest annual pace since March 2021. There were several encouraging details beneath the headline figures. Energy and gasoline prices fell for a second consecutive month, grocery prices declined for the first time since March, and so-called “supercore” inflation remained relatively subdued. However, the report was not entirely free of inflationary signals. Core goods prices recorded their strongest monthly increase since last September, driven in part by sharp rises in computer software and accessories prices. With memory chips increasingly being directed towards data-centre demand, it is a reminder that the AI investment boom may be creating pockets of pricing pressure within parts of the consumer technology supply chain.


What does Brooks Macdonald think?

The market response suggests investors viewed the CPI report as supportive, but not decisive. Expectations for a September Fed rate hike eased modestly, yet the overall repricing was relatively limited. This nuance was reflected across asset markets. While shorter-dated Treasury yields fell, longer-dated yields were little changed. Meanwhile, oil remained close to $90/bbl, and European gas prices moved higher as hopes for a swift US-Iran agreement continued to fade. Taken together, inflation concerns may be easing, but risks linked to energy prices and geopolitics have not disappeared. Attention now turns to today’s US producer price inflation (PPI) report. Beyond the headline figure, investors will be paying close attention to categories such as healthcare services, airfares and portfolio management, which feed into the Fed’s preferred inflation measure, core PCE. With investors still divided on whether another Fed rate increase will be needed this year, each inflation release has taken on greater significance.


Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Cameron Owen

13/08/2026


Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 11/08/2026.

AI stocks rebound from sharp downturn

AI stocks took a sharp downturn in July after a strong Q2. While performance has rebounded, some investor caution remains.

Key highlights

  • Gulf de-escalation: Oil fell from a high of $100 per barrel to below $80 per barrel amid reports of a possible agreement to reopen the Strait of Hormuz.
  • AI equity volatility: July saw a rotation out of AI infrastructure stocks, driven by efficiency gains in open-weight models and a forced hedge fund unwind.
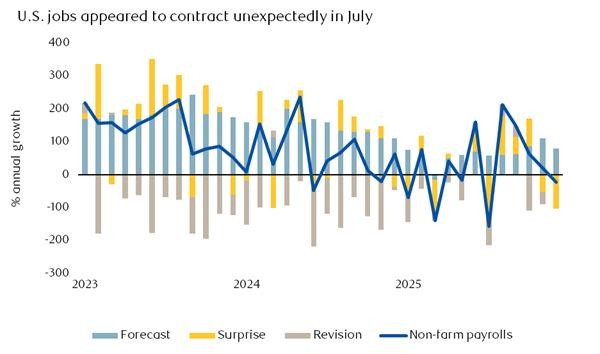
  • U.S. labour market: Jobs data pointed to broad stability, but the July payrolls report showed a surprise decline of 23,000 jobs, keeping interest rate decisions finely balanced.

Gulf tensions ease – oil retreats

Markets opened the week by responding to reports of a possible de-escalation in the Persian Gulf.

Source: LSEG Datastream

Oil fell from a July high of $100 per barrel to below $80 per barrel – a striking move given the collapse of the previous U.S.-Iran ceasefire. A new agreement to reopen the Strait of Hormuz appears to be in preparation, which would entail inbound shipping via Iran, outbound shipping via Oman, both sides clearing mines and no tolls charged. President Donald Trump sounded constructive, while retaining the threat of military action.

Since the onset of the conflict, crude prices have remained lower than analysts would have expected given the scale of supply disruption, and they have tended to fall on any sign of de-escalation. Barriers to a full reopening of the Strait remain high, with Iran appearing to have demonstrated that it can wield influence over the waterway at will.

For portfolios, the practical implication is familiar: energy prices feed through to inflation, central bank thinking, and the cost of everything from a refinery run to an airline ticket. It’s best to avoid getting whipsawed by headlines that change by the day.

AI stocks and shifting sentiment

Alongside the Gulf, AI remained the dominant concern for equity markets.

July saw a sharp rotation out of the AI spending beneficiaries – the companies that sell the equipment used by the AI ecosystem. Bottlenecks in the supply of specific components, most notably high-bandwidth memory (a specialist chip used in AI servers), drove a substantial rally from March to June while July brought a sharp reversal.

The sell-off reflected several factors. Open-weight models (AI systems whose underlying code is publicly available) have been making significant advances in efficiency, suggesting that less server capacity may be required to run them. Hyperscalers – the large cloud providers driving the bulk of investment – have also depleted their free cashflow and may face funding constraints. A significant factor, however, appears to have been a single hedge fund forced to unwind well-known leveraged positions; once the situation resolved, the stocks rallied, though some nervousness persists.

SpaceX captured the market’s conflicting mood. Results beat on earnings and revenue, but were overshadowed by a sharp rise in AI-related capital spending. The stock fell 7% after hours (having gained 9% during the previous session).

Real economy signals a mixed picture

The week brought a range of U.S. jobs data, with stability the best overall description. There was little change in job openings, resignations and layoffs, and jobless claims nearly reached an all-time low. Purchasing managers’ surveys (which track activity across manufacturing and services) showed employment increasing modestly alongside a broad improvement in economic activity across regions and sectors.

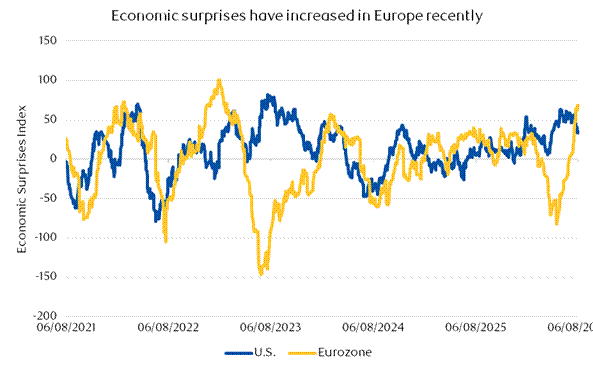
It’s notable that the U.S. no longer stands out as the sole beacon of growth. European economic surprises have exceeded those of the U.S. recently, and the stock market is no longer being driven by a narrow group of AI-related stocks, having seen much broader participation recently.

Source: LSEG Datastream

The synchronicity of that improvement should be enough to shift the window of anxiety from growth towards inflation. However, at a time when numerous sources seem to be showing an improving employment picture, the July employment report from the Bureau of Labor Statistics showed a surprise decline of 23,000 jobs. This fell far short of forecasts, which had predicted an increase of up to 80,000 new jobs. Wage and pay growth also slowed.

This may confuse the outlook for the U.S. jobs market, but it should be reassuring for investors, as many have been concerned about the potential need for interest rates to rise. An increase in September was hanging in the balance, but this seems a bit less likely now.

Source: LSEG Datastream

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

12/08/2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, received this morning – 11/08/2026:


What has happened?

Markets struggled to build on last week’s gains as higher oil prices weighed on risk appetite and pushed bond yields higher. The S&P 500 (-0.06%) and NASDAQ (-0.32%) both edged lower, although strength in energy stocks (+4.63%) helped limit broader declines. Semiconductor shares led the weakness, with the Philadelphia Semiconductor Index falling -2.94% after its strong rebound last week. Intel (-4.06%) announced plans for a $15bn share offering, while Nvidia (-2.86%) unveiled a partnership with several investment firms aimed at mobilising up to $500bn of financing for customers deploying its technology. In Europe, the STOXX 600 (+0.03%) closed at a record high for a sixth straight gain, while the FTSE 100 (-0.35%) underperformed.


Rising oil prices test market optimism

There was no breakthrough in efforts to reopen the Strait of Hormuz, with US-Iran rhetoric continuing to harden and reducing hopes of a near-term resolution. Brent crude rose almost 5% to $87.72/bbl, its fourth consecutive gain. The rise in oil prices reignited inflation concerns and prompted markets to modestly increase expectations for further rate hikes in both the US and Europe. That backdrop weighed on government bonds, with the US 10-year Treasury yield rising to 4.71% and European sovereign yields also moving closer to their late-July highs. Investors remain alert to the risk that sustained energy price pressures could complicate the inflation outlook and slow progress towards central bank targets.


What does Brooks Macdonald think?

Risk sentiment has remained surprisingly resilient so far this month. For the past two years, early August has often been associated with bouts of market volatility, but this year equities have continued to trade near record highs despite rising oil prices and renewed geopolitical uncertainty. Strong corporate earnings and continued enthusiasm around artificial intelligence have helped support markets, although the situation in Iran remains an important risk. For now, investors appear willing to look through the uncertainty, but further deterioration could quickly bring inflation concerns and energy prices back into sharper focus.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Cherise Lancaster

11/08/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management which explores the factors shaping investor confidence, from geopolitical developments and currency intervention to liquidity, bond yields and the strength of US corporate earnings, received this morning – 10/08/2026.

Regaining confidence after July’s drought

Stocks and bond prices are heading higher as the week starts, with US employment data showing enough softness to reduce inflation pressures, diminishing the chances of rate rises.

Another Iran “deal” buoyed markets last week, with Iran and Oman reportedly agreeing a new shipping route through the Strait of Hormuz. This weekend’s Houthi attacks have pushed oil back up somewhat, but the signs of Iran’s willingness to seek a truce should continue to ease the pressure. The Strait is, in Trump’s words, ‘sort of open’. But with each new back and forth, the market impacts dampen.

If the Iran news was more of the same, the US and Japan’s joint intervention to support the yen was a new dawn. It’s the first such coordination in nearly 30 years and feels reminiscent of the 1985 Plaza Accord.

For Japan, it points to higher interest rates ahead. Japan has high inflation, strong growth and a large current account surplus. It’s unlikely the US would step in without some understanding that the BoJ will address those. It could also encourage Japanese investors to bring capital home, boosting the yen further.

The yen-tervention is also a decent chunk of dollar and euro liquidity injected into global markets – though we should be wary of further currency volatility.

Liquidity is improving and corporate earnings are strong, easing equity valuations even as prices rise. The catch is real bond yields, still at their highest since the turn of the century, which make equities look less cheap by comparison. We doubt this reflects bond markets’ growth optimism; more likely, intense capital demand from governments and AI companies is outpacing bond supply.

The risk is high yields luring investors out of stocks, but that’s not our base case. With improving liquidity, falling volatility and a rebuilding of ‘long’ positions (following July’s shakeout), the good mood should last all summer. Let’s hope it’s a long one.

July asset returns review

July was a difficult month for global investors, as stocks and bonds sold off together while volatility rose sharply. Global equities lost 1.3% in sterling terms and bond prices fell 1%, as yields rose. The disintegration of the US-Iran ceasefire dominated the first half of the month. Brent crude peaked above $100 a barrel before falling back, but still finished 18.9% higher in sterling terms, with broader commodities up 11%.


Equities had other problems too. Investors doubted the sustainability of AI-related earnings growth – despite a strong reporting season – and grew anxious about AI infrastructure spending. Previously buoyant chip manufacturers were hit hardest. Large US tech stocks fell 4.5% in sterling terms and the S&P 500 fell 1.4%. Emerging markets dropped 4.4%, dragged down by TSMC, Samsung and SK Hynix, even though China, the biggest EM region, outperformed every other major market with a 5.5% gain.

A fall in growth stocks should be good for bondholders, as bond yields should track growth expectations, but that didn’t hold. Long-term yields spiked, first on energy prices and then after a poorly received press conference from Federal Reserve Chair Kevin Warsh. Long-term real yields reached around 3.5%, the highest in over 20 years. We suspect the bond-equity disconnect comes from buyers in each asset class becoming entrenched, with risk premia rising in both. UK gilts were the most sensitive, as usual – a structural feature more than an opinion on Andy Burnham’s spending plans.

In contrast, UK stocks were among the best performers, gaining 3.6%, thanks to energy companies and minimal tech presence. European stocks slid 0.8% and Japanese stocks 0.4%. On the last day of the month, coordinated intervention to support the yen injected substantial dollar and euro liquidity – a potent remedy for July’s volatility. Sure enough, markets have looked more positive in early August.

US earnings flatter to deceive

US company earnings look phenomenal: S&P 500 firms have just reported 47.4% year-on-year growth for the second quarter, the strongest since the post-Covid rebound in 2021. Looking closer, though, shows those numbers are a little artificial.

The bulk of that growth came from the ‘Magnificent Seven’ tech firms, but not from revenue or margins. Under US accounting rules, shareholdings in other companies must be marked to fair value, so gains for those shares show up as profit even if those gains aren’t crystallised. Amazon, Alphabet and Microsoft are all major private shareholders in Anthropic and OpenAI, and their stakes delivered enormous gains. Amazon alone reported a $53.4bn pre-tax gain, mostly from Anthropic. Alphabet also benefited from its $94.1bn stake in the now-public SpaceX. Those gains cover the period till the end of June – since which time SpaceX’s shares have fallen substantially.

These results feed the ‘circular financing’ narrative that led to AI bubble talk earlier this year: AI earnings rising because AI share prices are rising.

Even so, the underlying earnings are strong. Strip out Alphabet and Amazon’s investment gains, and S&P 500 earnings still grew 29% – below the headline figure, but well above the 24% analysts had expected, and still the best quarter since 2021. Growth was also more broadly spread across sectors than the headlines suggest.

Not every distortion flatters earnings either: Intel’s government stake sits on its balance sheet as a liability, so a rising share price actually weakens its reported earnings.

We think markets are reading this sensibly. AI-related shares are still below their May levels, so valuations have got cheaper even as earnings power ahead. That is hardly bubble behaviour. And last week’s tech rally owed more to solid earnings, falling oil prices and central bank intervention supporting the yen than to misplaced earnings excitement. Investors seem healthily sceptical of AI valuations, yet unable to ignore that underlying earnings remain genuinely strong.

Important Information This material has been written by Tatton Investment Management and is for information purposes only and must not be considered as financial advice. We always recommend that investors seek financial advice before making any financial decisions. The value of investments can go down as well as up, and investors may get back less than originally invested. All calls to and from our landlines and mobiles are recorded to meet regulatory requirements.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

10th August 2026