Team No Comments

Tatton Investment Management: Monday Digest

Please see below, an article from Tatton Investment Management, discussing the impact of Trump’s Liberation Day and the proposed US Sovereign Wealth Fund. Received this morning – 07/04/2025

Trump’s Liberation Day turns into market rout
Donald Trump’s tariffs upset markets unprepared for their magnitude. The shockingly high “reciprocal” tariffs aren’t a response to “Tariffs charged to the U.S.A” as claimed, but a calculation based on regional trade deficits. This widely panned method is suspiciously similar to the one AI models give when you ask for a simple tariff plan. By some calculations, the new weighted average tariff is 18.5% (versus the expected 15%) due to exemptions – but the sell-off worsened when China retaliated with a 34% tariff on the US. Full-blown trade war between the world’s two largest economies greatly concerned investors. 

Growth forecasts have been downgraded, but prospects depend on how policymakers respond. The hope is it’s an opening gambit in trade negotiations – with the extra “reciprocals” up for debate. Markets are wondering whether Trump is for real or for the deal, but Canada and Mexico’s exemptions suggest the latter. 

The baseline 10% unfortunately looks set to stay, largely because the US government needs the money. That’s especially true if Trump goes ahead with his promised tax cuts. Tax cuts would numb the pain, but probably won’t live up to last year’s market hype – judging by sharply lower US bond yields. Yields have fallen due to growth pessimism but, with Trump preparing for fiscal expansion, US bonds might need a higher yield to attract international investors – so could rise over the medium-term. 

The outlook has worsened, but investors should avoid rash decisions. Markets have ricocheted between complacency and capitulation. That’s usually followed by a steep recovery, as investors recognise that there are factors to dampen the shock. The path to mitigation is clear – negotiations bringing down tariffs – and even Trump has said he’s open to talks. Besides that, the Fed has plenty of firepower and other governments look set to pursue fiscal stimulus. It looks like we’re close to the turning point, but there certainly could be volatility ahead. Once the dust settles – and only then – can we evaluate the long-term opportunities to change asset allocations. 

March 2025 asset returns review
March was a bad end to a volatile quarter: global stock prices fell 6.3% and bonds dropped 0.4%, as investors braced for President Trump’s “Liberation Day” tariffs. US stocks once again performed the worst (down 7.9% in sterling terms) while the dollar continued to slide. Normally, the dollar rises when global growth is under threat – but markets saw tariffs as a bigger risk for the US than elsewhere. 

Looming tariffs still hurt other regions, just not by quite as much. European stocks fell 3% in March – but are up a very decent 7.4% for Q1. The UK followed the same pattern (-2% in March, +6.1% in Q1), despite Spring budget negativity. China was once again the best performer, and now leads returns on a monthly, quarterly, half-yearly and yearly basis – thanks to Beijing’s economic stimulus and tech positivity from DeepSeek.

Bond prices fell, but with significant variation. European yields soared after Germany’s proposed reform of the constitutional debt brake – leading to the biggest single-day yield jump since reunification. Global yields felt the shockwave, but it was dampened in the US, whose yields were only slightly higher through March. That’s because of Trump’s disruptive policies weighing on growth expectations. Yields fell sharply into the end of the month, as investors seemed to prefer the safety of bonds over risk assets. 

Lower risk appetite was also reflected in gold prices. The ‘safe haven’ metal continues to soar, and was accompanied by a fall for Bitcoin. That tends to suggest nervous investors. The reason for these nerves was clear: Trump tariffs imposed at the start of April. Uncertainty around these, combined with portfolio rebalancing into the end of the financial year, led to markets bracing for impact. 

The new US Sovereign Wealth Fund
Trump’s cabinet is finalising its plans for a US sovereign wealth fund (SWF). The president’s executive order to propose one was light on details, but SWFs are generally built out of budget surpluses – and the US runs a hefty deficit. The government will have to get creative with its money, but there are options: land, gold reserves, cryptocurrencies, mineral rights and stakes in private companies. In fact, there are already 21 SWFs belonging to US states, with a combined $300bn AUM. The idea of a federal SWF isn’t new; Biden proposed one, though nothing came of it. 

A Trump-ordered SWF would likely focus on infrastructure, manufacturing and defence – in-keeping with the “America First” policy of winning the tech race and bringing back American manufacturing. A SWF that buys up innovative companies and profits from them could also be a way of giving the fruits of US growth back to its citizens. 

Without strong governance, though, SWFs can devolve into slush funds. Worryingly, the Trump administration has little regard for governance or oversight. The president made millions off of his personal ‘memecoin’ just before entering office, while Elon Musk is overseeing the federal funding that he’s profiting from. 

Some have suggested tariffs could fund the SWF. This idea is implausible (the deficit still needs plugging) but revealing: it suggests Trump’s SWF is more of a political tool – a weapon in Fortress America – than an investment vehicle. 

Global SWFs are increasingly partnering with international funds – so Trump’s SWF could be used in foreign policy. If it comes about, it will probably be a part of Russia talks. The head of Russia’s SWF is now special envoy for investment and cooperation and has said Trump’s presidency “opens up new opportunities for resetting relations”. 

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

7th April 2025

Team No Comments

The Daily Update | Tariff Tantrum: No Exit Strategy in Sight

Please see below article received from EPIC Investment Partners this morning, which offers a different view on Trump’s tariff announcement.

The tariffs announced on Wednesday far exceeded expectations, including our own. While the scale of the tariffs is a concern, the bigger issue is the absence of a clear strategy to reverse course. The administration aims to reduce the US trade deficit by imposing tariffs based on the size of a country’s trade balance relative to total imports. That formula won’t change significantly unless there is a substantial shift in the relative competitiveness of the two nations. 

Contrary to expectations that tariffs would support the US dollar, the currency weakened sharply against major peers. This reaction may hint at a broader policy direction. One key factor behind the persistent trade deficit is the dollar’s overvaluation, a result of loose fiscal policy combined with tight monetary conditions. Measures like the Big Mac Index highlight this imbalance, with the Japanese yen appearing undervalued by 46% against the dollar. 

Last year, we noted the potential for a modern version of the 1985 Plaza Accord—a coordinated move to weaken the dollar. The dollar’s drop after the latest tariff news brings to mind President Nixon’s 1971 actions. Back then, Nixon imposed a 10% import tariff and ended the dollar’s convertibility to gold, effectively abandoning the Bretton Woods system. His goal was to weaken the dollar to reduce the trade deficit and boost US competitiveness. Though initially disruptive, the strategy eventually succeeded. Today’s policies may reflect a similar intent. 

However, deliberately weakening the dollar brings risks, including higher inflation. That could complicate the Federal Reserve’s policy path, especially if growth slows at the same time. The result could be stagflation—low growth coupled with persistent inflation—making policymaking significantly more challenging. 

For investors, the outlook is increasingly clear: bond yields are likely to fall. Tariffs raise uncertainty and pressure economic growth, increasing demand for safe-haven assets. Long-duration US Treasuries are particularly well-positioned to benefit from falling yields in such an environment. Historical precedent supports this—when growth slows and uncertainty rises, high-quality bonds tend to outperform. 

Investors should also monitor for signs of coordinated international action to weaken the dollar. Although not widely discussed in the mainstream press, there is speculation about a possible Mar-a-Lago summit, where a coordinated devaluation of the dollar could be agreed. This would simultaneously improve US competitiveness and reduce the need for tariffs. Even hints of such moves could ease tensions and restore stability. Until then, markets are likely to experience subdued growth, falling bond yields, and rising volatility. Bond markets have been under pressure in recent years, but the current environment is very supportive of long-duration, high-quality fixed income. 

Please check in again with us soon for further relevant content and market news.

Chloe

04/04/2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update. Please also refer to the additional comments at the end of the article for further context.

What has happened

The past 36 hours has seen a massive recalibration in markets following US President Trump’s ‘Liberation Day’ tariff announcement on Wednesday evening UK time. Coming into this week, there had been debate as to whether Trump would introduce either baseline or targeted tariff rates – in the end, he did both and based on a formula reflecting the size of relative US trade deficits with trading countries rather than trade barriers per se. Markets reacted swiftly with equity prices down sharply and bond prices up yesterday as safe-havens were sought out – US stocks saw the epicentre of the selling pressure yesterday, with the broader S&P500 (-4.84%), the technology-focused NASDAQ (-5.97%) and the small-cap Russell2000 (-6.59%) all suffering their worst days since 2020, all in US dollar price return terms.

A flawed tariff formula?

Trump has been consistently focused on the size of the US trade deficit, seeing it as the principal marker of perceived trade injustice against the US – that appears to have guided the formula unveiled this week that has calculated the tariffs the US administration is now set to roll out. As regards the targeted tariff rates, Trump’s team is not determining these on the actual tariffs that other countries presently levy against the US but instead using a calculation premised on the US trade deficit for a given country relative to what the US imports from that country. However, trade deficits do not always represent deliberate uneven competition, and instead can often reflect a natural imbalance arising from what goods a country makes and has particular expertise or advantage in.

An unwelcome tariff impact

Tariffs add unwelcome friction into global trade – akin to throwing sand into the gears of often complex cross border supply-chains around the world. Higher tariffs can increase the price of goods imported and sold, which can prove a headwind for end-consumers’ real disposable incomes, and in turn curbing economic growth. Complicating efforts to estimate these tariff impacts, it depends in large part on some still-as-yet unknown factors – for example, will those countries on the receiving end of Trump’s tariffs move to negotiate and compromise, in which case we may have already seen ‘peak tariffs’?, or will there follow a series of retaliation and reprisals from both those countries and the US in turn, risking higher-for-longer tariffs still to come?

What does Brooks Macdonald think

In any negotiation it is not unusual for one side to go all-in at the start with the biggest demands and then pull back somewhat in order to seek a common ground for agreement. For markets, that has to be the hope here, for were these tariffs to stick, then there are clearly adverse risks for both higher inflation pressures and lower economic growth. Complicating that, however, is whether those countries on the receiving end of Trump’s tariffs are able to compromise given that deficits are not always born out of deliberate unfair competitive practices – that could make these tariffs much harder to resolve. For all the events this week, the overarching question still remains whether Trump is seeking an ideological trade reset or a quickly-negotiated compromise – on that key question we are unfortunately no clearer as yet.

Comment

Markets have reacted badly to Trump’s tariffs. As ever, in this type of volatility, you need to remain invested, and if appropriate carry on with regular monthly funding too. For some, it also provides an opportunity to invest capital.

Markets don’t like uncertainty; we need a swift solution. Will Trump bring this to a close quickly? Or will we see drawn out negotiations – or a global tariff war?

The good news is that globally, some countries have been doing well. Japan, China were recovering, and Europe was starting to recover too.

If Trump does bring this tariff ‘negotiation’ to a close quickly, we could see a strong bounce back, or it could take a while for assets to recover.

In October 2024, JP Morgan in their annual report ‘Long Term Capital Market Assumptions’ stated that it would be volatile and that with this outlook, we need to be well diversified with active fund management. I agree.

Steve Speed

04/04/2025

Team No Comments

Brooks Macdonald – The Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their views on the impact of Trump Tariffs on the macro economy. Received this morning 03/04/2025.

What has happened

US markets started Wednesday on a positive note, with the S&P 500 climbing 0.67%—marking its third straight day of gains. Investors seemed optimistic during regular trading hours, but that mood shifted dramatically after the close. In after-hours trading, markets took a sharp dive following news of President Donald Trump’s latest tariff announcements, dubbed ‘Liberation Day.’ The S&P 500 futures dropped over 2%, while the Nasdaq futures fell more than 4% at their peak. Big-name stocks felt the heat too, with the Magnificent 7 group (including Apple, down over 6%, and Amazon and Tesla, both off more than 5%) leading the decline.

Trump’s tariffs plan – US vs the world

The centrepiece of Trump’s announcement is a new tariff structure aimed at levelling the playing field for US trade. Here’s how it works:

  • Baseline Tariff: Starting this Saturday, all countries will face at least 10% on tariff on goods shipped to the US. The UK is one of the few ‘lucky’ ones subject only to this baseline 10%
  • Higher Rates for Key Partners: On April 9, many major trading partners will see much steeper tariffs. For example, the European Union faces 20%, Japan 24%, and Vietnam a hefty 46%. China gets hit hardest with a 34% tariff – on top of a 20% increase announced earlier this year

Not everyone is in the crosshairs, though. Canada and Mexico are exempt for now (though some goods already face a 25% tariff due to separate fentanyl and migration policies). Critical items like pharmaceuticals, semiconductors, lumber, copper, and gold are also off the hook, but they’re under review in separate trade investigations. Steel, aluminium, and auto imports, however, will still face 25% tariffs as recently outlined.

What does Brooks Macdonald think

Trump’s tariff plans raised concerns about higher costs, disrupted trade, and economic uncertainty. If fully implemented, these reciprocal tariffs could push the average levy on US imports to over 25%—a level not seen since the early 1900s and nearly 20% higher than today’s rates. Economists are already sounding the alarm. Early estimates suggest these tariffs could shave 1–1.5% off US economic growth this year while pushing up inflation (measured by core PCE) by a similar amount. Higher costs for imported goods could squeeze consumers and businesses alike, especially if trading partners retaliate with tariffs of their own. For investors, the big unknown is what happens next. Will other countries strike deals to lower these rates, or will they accept this as the new normal and adjust their supply chains? Trump’s openness to negotiation offers some hope, but his warning of potential escalation keeps the risk of a trade war alive.

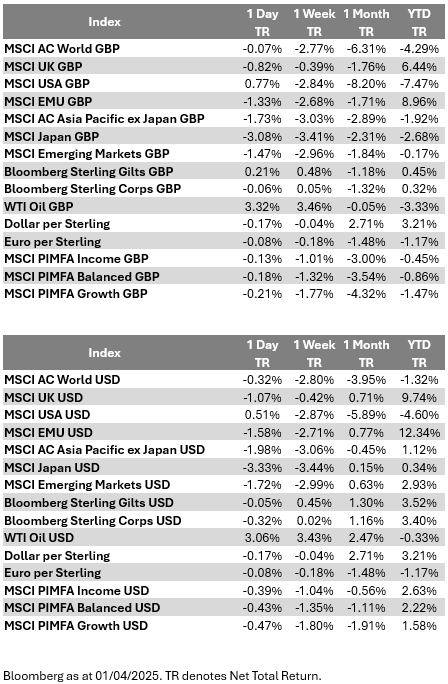
Bloomberg as at 03/04/2025. TR denotes Net Total Return.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

03/04/2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 01/04/2025.

What’s next for U.S. trade tariffs?

We take a closer look at the latest tariff announcements as the world waits for President Trump’s ‘Liberation Day’.

Last week was supposed to be the calm before the storm of U.S. President Donald Trump’s self-styled ‘Liberation Day’, when tariffs will be imposed on a range of the country’s trading partners.

The week saw plenty of information and disinformation over when the tariffs will come, before seeing a surprise announcement on Wednesday relating to taxes on car imports.

U.S. announces 25% tariffs on cars

President Trump imposed 25% trade tariffs on vehicles and car parts last week. According to the White House, the move was made in the interest of national security, for which the automotive industry is a vital component. The tariff on finished vehicles will apply from 3 April, while the tariff on parts will be imposed a month later.

President Trump has consistently expressed his frustration over the practice of building cars in other countries before selling them in the U.S. This new policy aims to encourage more car manufacturing in the U.S. instead. The president hopes this will increase U.S. employment and reduce the U.S. trade deficit.

A graph showing the price of a vehicle sales

AI-generated content may be incorrect.

Source: LSEG Datastream

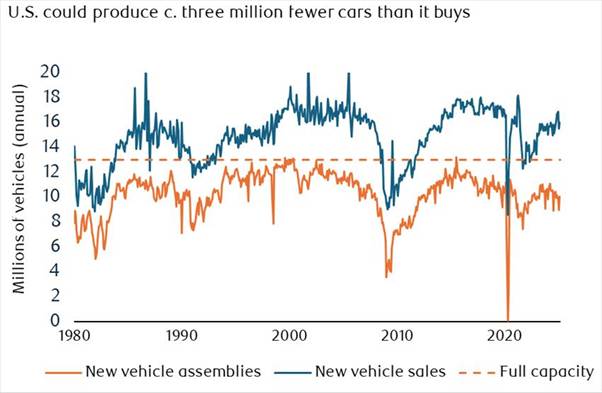
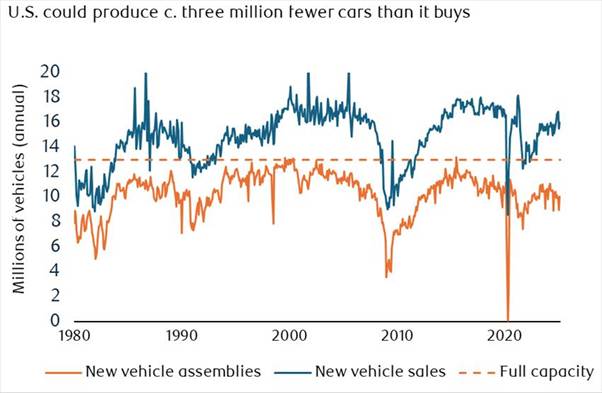
The U.S. sells around 15 million vehicles per year, with some demand having probably been brought forward in anticipation of tariffs.

The U.S. currently produces around 10 million vehicles annually and, at a stretch, it appears to have capacity for 13 million. Over time, the shortfall can be met through additional investment in auto plants, which take a couple of years to build.

There are two important questions to be asked:

  • How long will the tariffs need to remain in place to make executives willing to commit to expensive new plants in the U.S.; and
  • By the time the plants are erected, how long will be left of President Trump’s term, at the end of which policies may be different?

Japan ponders retaliation against auto tariffs

Around 28% of Japan’s exports to the U.S. are cars, so the country will be impacted by this latest tariff announcement. Japanese Prime Minister Shigeru Ishiba insists that all options are on the table when it comes to retaliation.

However, Japan has moved a lot of its car manufacturing to America, and so a portion of its sales will be protected. Economic consultant Capital Economics estimates that around 70% of sales by Japanese firms to U.S. companies are already manufactured in the U.S.

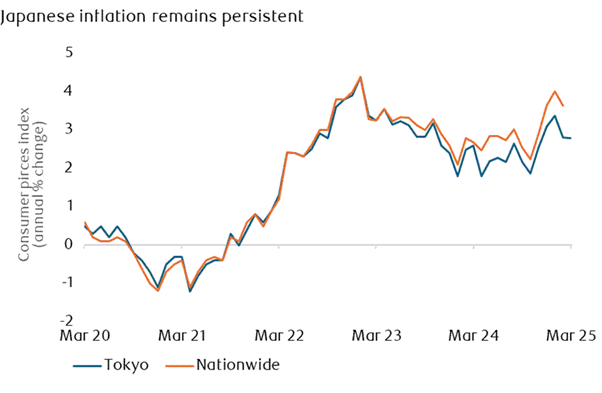
So, despite the considerable threat from the imposition of tariffs, interest rates are still expected to rise in Japan. Members of the Bank of Japan’s Monetary Policy Board seem concerned that food price inflation could be persistent, and there have been signs from the latest shunto (annual spring wage negotiations) that companies are willing to countenance higher payments.

A graph of a graph with numbers and lines

AI-generated content may be incorrect.

Source: LSEG Datastream

At a time when other countries are pondering how fast to cut their interest rates, Japan is poised to continue hiking, especially since consumer prices in Tokyo on Thursday remained stronger than anticipated, which will therefore be true of the equivalent nationwide inflation measure, too.

UK economy gives mixed signals

Friday saw the full release of the UK’s 2024 gross domestic product (GDP) numbers. The economy grew by just over 1% last year, despite some pre-election giveaways by the outgoing administration. The new government shone a light on the fiscal situation, and in doing so cast a shadow over UK consumer confidence. 

A graph showing the price of a vehicle sales

AI-generated content may be incorrect.

Source: LSEG Datastream

Whilst Friday’s numbers show just how turgid the second half of 2024 was, they do reveal that during the final quarters, the combination of growing real wages and cautious spending led the saving rate to reach nearly 12%—the highest figure since 2010—indicating that UK consumers have been saving.

The benefit of that was felt in January and February; retails sales figures seem to suggest that the UK consumer headed back to the shops in the first months of the year. The benefit was also seen in the UK services purchasing managers index (PMI), but below the surface of a strong rebound lies some gloom in the form of contracting employment, which is a response to rising employment costs.

The increase to Employers National Insurance contributions, which was announced in the 2024 Autumn Budget, will take effect from this April. The new tax year will also see first-time buyers paying Stamp Duty Land Tax (SDLT) when buying a home, ending a preferential treatment that saw them exempt from paying any SDLT on properties worth up to £425,000.

Inflation was below forecasts, but this was mainly due to a few volatile items. We know that utility bills will be back on the rise in April, which means inflation will be back above 3% for the rest of the year.

The economy seems stronger in the first quarter of 2025, but inflation is persistent. The Bank of England’s Monetary Policy Committee seems keen to cut interest rates at least twice over the next year, but it will be banking on a slowdown in inflation (excluding utility bills).

In the Spring Statement on Wednesday, the chancellor confirmed that government spending was on track to break one of her fiscal rules. The government had been on track to spend £9.9bn less than it was receiving in 2029/30, but rising interest rates meant that this headroom had been lost.

Over the previous week, the government announced welfare cuts that will take effect from April next year, in addition to further economic measures. By extraordinary coincidence, the £9.9bn headroom was restored but as the last six months have shown, such a small margin means that every time interest rates seem to rise, the prospect of more taxes or spending cuts in autumn will rise.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

02/04/2025

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, an article from Brooks Macdonald providing a brief analysis of the key factors currently affecting global investment markets. Received this morning – 01/04/2025:

What has happened

Yesterday wrapped up a mixed quarter for markets. With global tariff risks rising in Q1, investors rotated into previously unloved parts of the global equity market and challenging hitherto megacap tech leadership. During the quarter, the US ‘Magnificent Seven’ tech group fell -16.0%, weighing on US (and by extension global) equity markets with the US S&P500 equity index falling -4.6%. By contrast, over in Europe, the UK FTSE100 was up +5.0% and the pan-European STOXX600 equity index gained +5.2% in Q1, though investors here were not immune from tariff concerns, with the latter index losing over half of its cumulative year-to-date gains by quarter-end. China’s equity performance meanwhile was sandwiched between US and Europe, with the China CSI300 equity index down -1.2% in Q1 (all in local currency price return terms).

More tariffs coming but tax cut news too maybe?

We have just one more day to wait until US President Trump’s reciprocal tariffs are announced tomorrow, Wednesday 2 April at 3pm US Eastern Time. Yesterday, White House Press Secretary Leavitt said that there would be “country-based” tariffs, with further sectoral duties to come later. Separately on tax cuts, there were comments yesterday from US Treasury Secretary Bessent who said that he was working with Republicans in Congress to deliver Trump’s fiscal campaign promises, including “no tax on tips, no tax on Social Security, no tax on overtime” – meanwhile Republicans are reportedly seeking to formulate a tax cut package in Congress that permanently extends Trump’s 2017 tax cut provisions.

Australia’s central bank keeps interest rates on hold

As expected by markets, the Reserve Bank of Australia (RBA) earlier today left interest rates unchanged (at a cash rate of 4.1%). In their statement, the RBA highlighted an uncertain economic outlook for both domestic activity and inflation, while global risks remain significant driven by geopolitical and policy uncertainties, including US tariffs. For context, the RBA’s 25 basis points interest rate cut back in February this year was its first rate cut since late 2020.

What does Brooks Macdonald think

Markets have been bruised by Trump’s tariff escalation in recent weeks and the impact that they might have on economic growth and inflation – yet these trade levies (in principle) were always part of Trump’s November 2024 election manifesto, alongside his promises to deliver tax cuts and deregulation. So far, there has been an adverse timing mis-match of these two policy strands, with lots of negative tariff news, but precious-little in the way of new news on tax cuts in particular. Given the latest comments from the US administration yesterday around tax cuts, that sequencing of policy news and action could be about to change – it that is the case, a renewed focus on Trump’s market-friendly policies could bring a welcome positive distraction for investors and offer some support for risk assets more broadly.

A table with numbers and symbols

AI-generated content may be incorrect.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd DipPFS

1st April 2025

Team No Comments

Tatton Investment Management: Monday Digest

Please see below, an article from Tatton Investment Management, providing a brief analysis of the key factors currently affecting global investment markets. Received this morning – 31/03/2025

Tariff ‘stick’ to be followed by fiscal ‘carrot’?

Markets have been fluctuating, initially with some positivity due to Trump’s planned phased and toned down tariff “Liberation Day” announcement. However, Trump’s unexpected permanent 25% tariffs on autos and threats of further tariffs swiftly reversed the market mood.

For the Trump administration, tariffs are about trade, domestic jobs, and tariff revenue, though it’s unclear which aim dominates. While tariffs are headline news in Europe, most Americans are only marginally aware. Fox News has no mention of tariffs, while CBS covers it as a secondary story.

Fox’s omission suggests it recognises that tariffs can raise prices for consumers, increase inflation and are generally unpopular. More attention is now on the administration’s first budget bill, which are created by Congress, not the President. The interim budget must pass before September, with the debt ceiling expected to be reached in August. Counterintuitively, Trump requested an amendment to increase the debt ceiling, facing opposition from Republican fiscal hawks.

This may well imply that the focus on spending cuts and tariffs (the ‘sticks’) may be overtaken by larger tax cuts (the ‘carrots’). US equities were supported by thoughts of larger tax cuts, but rising bond yields could harm growth more than tax cuts help.

For the UK and its chancellor Rachel Reeves, there is a similar problem. Trump plans to cut taxes, and Reeves has said she won’t raise them. Investors are sceptical that the Labour government can maintain its hawkish stance if growth undershoots. Despite sticking to its rules, gilt yields have risen, meaning investors doubt the UK economy can be remedied without dramatic expenditure cuts.

To build fiscal credibility, the Chancellor needs to navigate the 2025 slowdown while displaying fiscal hawkishness. Productivity improvements and global economic resilience are crucial. Institutional portfolio rebalancing and economic data releases will influence market movements.

Next week marks the end of a quarter, prompting institutional portfolio rebalancing and against the recent market movements would point to selling bonds and buying back of equity allocations. Important economic data, such as US payrolls, will be released and with Trump’s April 2nd tariff announcements we could have another climactic week, with markets expecting stop-and-start action and little policy clarity. It takes a brave observer to say they know how it will pan out.

Who are the Magnificent Seven?

America’s technology giants – Apple, Amazon, Alphabet, Meta, Microsoft, Nvidia, and Tesla – dominated market returns the last two years but are struggling in 2025. It’s time to reassess whether grouping these “Magnificent Seven” companies together makes sense for investors. Their fundamentals differ significantly, but their grouping has reinforced their similarities.

Investors group the Magnificent Seven (Mag7) together because they are all technology companies with revenue streams from tech innovation, displaying strong earnings growth and healthy balance sheets. For investors they have been top performers, unrivalled earnings growth and very healthy balance sheets with plenty of available cash. However, growth prospects differ markedly. Nvidia is expected to post 22% annual revenue growth until 2028, while Apple is projected at 8%. These differences are not surprising when in market terms Apple and Microsoft already dominate well-established markets, while Nvidia and Tesla are geared towards new and growing markets.

Mag7 companies face different challenges requiring varied business plans. Apple and Nvidia need little capital expenditure, while Meta, Amazon, and Tesla are more capital intensive. These differences mean the risk-reward trade-offs vary across the group and on that basis the Mag7 is not a coherent investment thesis.

Tesla exemplifies why the Mag7 is no monolith. As a car manufacturer it is not a purely a tech firm. Yes, it is the largest carmaker by market cap but not by revenue. Its high valuation relies on rapid sales growth backed by high paced tech innovation, which is uncertain. Tesla markets itself as pioneering new technology, creating a new industry of electric, self-driving cars. This approach is uncertain, making Tesla a different investment proposition compared to Apple.

Tesla’s share price is also tied to the political fortunes of CEO Elon Musk. It soared with Trump’s election win but fell due to backlash against Musk’s politics. Investors struggle to quantify these political benefits when valuing Tesla.

Despite differences, the Mag7 grouping is not entirely incoherent. Their size and correlated share prices mean the correlation will persist. Mag7 funds reinforce this correlation. Grouping in financial products impacts the companies, giving them easier access to capital and higher valuations. Their size also provides political influence, allowing them to collectively lobby for favourable regulation.

Grouping winners together makes sense in a winner-takes-all capitalism. Arguments against grouping the Mag7 apply to other stock indices. Investment themes evolve; the BRIC countries were once a popular theme 20 years ago but are now rarely grouped together. The Mag7 stocks may not be as correlated in 20 years, but for now, there is little reason to think they will split up.

The Rise of Sovereign Wealth Funds

One notable Trump Executive Order from February was to create an American Sovereign Wealth Fund (SWF). Trump claimed it would be one of the largest funds in the world. But why do SWFs matter?

SWFs are state-owned investment funds, often established by countries with government surpluses from natural resources like oil and gas. Trump’s announcement sparked out interest because the US, with a deficit of over $35 trillion, would need significant disruption to create a government surplus for its SWF.  To take a step back, the term “Sovereign Wealth Fund” was coined in 2005, but the concept dates back to state funds in the US, like Texas’s fund for schools, while the first national SWF was Kuwait Investment Authority in 1953.

Energy price rises created government surpluses which led to the creation of SWFs by other oil producers. Norway’s Government Pension Fund Global, established in 1990, is the largest SWF. Nations with wealth from other sources have also created funds, like the Korea Investment Corporation (2005) and Australia’s Future Fund (2006). By 2008, there were 23 SWFs, and the International Forum of Sovereign Wealth Funds was formed.

SWFs have grown significantly, managing over $13 trillion by 2025, up from $1.2 trillion in 2000. Their investments have performed well, better than Public Pension Funds and Central Banks. The IFSWF sets standards for governance and investment practices, defining SWFs as special purpose investment funds owned by the government for macroeconomic purposes.

SWFs have diverse investment strategies. Some, like Abu Dhabi Investment Council, invest in alternative unlisted assets, while others, like Norway’s GPFG, invest in listed securities. SWFs aim to invest proceeds from current account surpluses for the future, anticipating that the source of the surplus may diminish.

Some SWFs exploit their sovereign-like reputations to borrow money at cheap rates, like Singapore’s Temasek. Despite generally being well-run, there have been failures, such as 1 Malaysia Development Berhad (1MDB). Established in 2009, 1MDB faced allegations of misappropriated funds and amassed over $10 billion in debt, leading to political downfall and legal actions.

SWFs have improved governance and, despite some sceptics, have improved their image. Next week, we will explore President Trump’s proposed US SWF, its funding challenges and its ramification on the US and global economy.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

31st March 2025

Team No Comments

The Daily Update – The Looming US debt crisis

Please see below article received from EPIC Investment Partners this morning, which provides an update on the US economy.

Last year, Jerome Powell emphasised the need for an “adult conversation” about US debt. Yesterday’s Congressional Budget Office (CBO) release highlights why this was so. 

The CBO projects federal debt held by the public will hit 100% of GDP in fiscal 2025, escalating to 156% by 2055, surpassing historical peaks. Such debt levels threaten economic growth, increase interest payments to foreign debt holders, and risk fiscal instability, significantly limiting policymakers’ options. 

Economic growth is expected to slow markedly in the coming decades. Real GDP growth is forecasted to decline from 2.3% in 2024 to 1.8% by 2026, averaging 1.6% annually through 2055. Factors such as an ageing population, declining birth rates, and reduced immigration drive this slowdown. Without immigration, the US population would shrink from 2033, directly impacting labour force growth, economic productivity, and tax revenues, ultimately affecting living standards. 

The federal budget deficit remains substantial, with a projected $1.865 trillion shortfall in fiscal 2025, averaging 6.3% of GDP over the next 30 years. Persistent deficits, driven by rising interest payments and primary deficits, amplify the debt crisis, creating a challenging cycle to escape. Federal spending is projected to rise to 26.6% of GDP by 2055, fuelled by interest payments, healthcare costs, and increased Social Security obligations due to demographic pressures. 

Federal revenues will temporarily increase due to the expiration of certain 2017 tax act provisions, then gradually rise to 19.3% of GDP by 2055. This growth primarily stems from rising real incomes and “real bracket creep,” as taxpayers increasingly move into higher tax brackets. 

Policymakers face critical decisions, including entitlement reforms, tax adjustments, and strategic investments to enhance productivity. While the CBO projections assume existing laws remain unchanged, decisive actions could significantly alter this fiscal trajectory, resonating with Powell’s call for responsible governance. 

The interaction between deficit reduction, economic growth, and interest rates is intricate. Meaningful deficit reduction could temporarily dampen demand, prompting the Federal Reserve to lower interest rates to stimulate growth. However, persistent high debt levels, typically hinder economic growth and reduce private investment. 

Research indicates that economies with debt around 100% of GDP may require near-zero interest rates to achieve fiscal sustainability. Attaining this equilibrium involves a combination of fiscal consolidation, structural reforms, and monetary policy adjustments. Addressing the US debt challenge is crucial for long-term economic stability, avoiding future scenarios where debt severely limits economic potential and raises the spectre of possible default. 

Nevertheless, economic pressures suggest a likely return to zero interest rates, creating a highly favourable environment for fixed income investments in the coming years. 

Please check in again with us soon for further relevant content and market news.

Chloe

28/03/2025

Team No Comments

Brewin Dolphin – UK Spring Statement 2025: What it means for your money

Please see the below article from Brewin Dolphin analysing the key measures announced in the UK Spring Statement and how they could impact personal finances, investments, and the wider economy. Received – 26/03/2025

UK Chancellor Rachel Reeves has unveiled the 2025 UK Spring Statement, aiming to balance public finances and “secure Britain’s future in a world changing before our eyes”.

The Spring Statement follows a significant Autumn Budget, in which tax rises totalling £40 billion were announced. Despite a shifting geopolitical scene since that announcement, the Chancellor is resolute in reserving major fiscal decisions to once annually in the autumn, leading to a restrained Spring Statement that zeroed in on expenditure reductions and a boost in defence spending.

Our analysis examines the Spring Statement’s relatively limited measures affecting personal wealth and investments, with Guy Foster, chief strategist, evaluating the UK’s economic prospects in light of the Office for Budget Responsibility (OBR)’s projections.

Financial planning highlights

Tax

The Chancellor’s Spring Statement eschewed further tax rises, maintaining the status quo on income, capital gains, inheritance tax (IHT), VAT, and National Insurance.

Instead, there was a heavy focus on enhancing HMRC’s debt management, targeting promoters of tax avoidance, and intensifying efforts to clamp down on tax evasion. This includes action to prosecute more tax fraudsters, reform the rewards for informants, increase penalties, and tackle advisers facilitating non-compliance.

Looking ahead, the UK’s substantial debt burden and limited fiscal leeway mean that expectations for a more lenient personal tax regime in the upcoming budget are muted. Meanwhile, the current stability in tax legislation provides a window for individuals to review their financial planning strategies in anticipation of possible changes in autumn. Engaging with your wealth planner and professional advisers can help you understand what options are available to you.

Business Relief

Business owners face an increased IHT liability starting April 2026 due to a previously announced £1 million cap on relief. However, a recent HMRC consultation suggested there could be the potential to benefit from the £1 million allowance multiple times.

Any gifts of Business Relief assets between 30 October 2024 and 5 April 2026 will count towards the £1 million allowance, with the reset period for Agricultural and Business Relief set at every seven years from the date of each gift of the assets. It’s important to note that Business Relief investment allowances cannot be shared between spouses, which differs from some other IHT allowances.

With careful planning considering existing IHT strategies, business owners could benefit several times by making multiple gifts on a rolling seven-year basis. Note that it’s vital to consider the suitability of the alternative investment market or other schemes for IHT planning, considering how Business Relief assets are divided between spouses and their eventual distribution upon death. Keeping detailed records of all Business Relief assets transferred since 30 October 2024 is imperative. Currently, this area remains without draft legislation and consultation continues.

The outlook for the UK economy

In the autumn, the government announced significant tax hikes and increased borrowing to fund major investments in public services. The Spring Statement would ideally be an update on how those policies were affecting the economy.

Firstly, it’s important to remember that the government must abide by rules which limit how much it can borrow in the future. These rules are designed to prevent governments from being tempted to take risks now, which could have significant costs later. The OBR’s role is to estimate whether the government abides by these rules.

For the Chancellor, the most challenging thing is to ensure that the current budget (that means day-to-day spending but does not restrict investment) is on course to be in balance by the 2029/30 financial year. At the last budget, the OBR estimated that the government would meet this restriction by £9.9bn — although such forecasts are inherently uncertain.

Ideally, chancellors would like more margin for error, or scope to spend. As it turns out, the forecast has deteriorated due to a combination of weaker economic growth and higher interest rates, leaving the government on course to break its fiscal rules.

This has led to a series of pre-Spring Statement announcements, including welfare reductions and public sector efficiency measures. However, the government intends to increase borrowing, but to use more of that money to invest, particularly in defence.

Whilst few would doubt the necessity of investing in defence, it doesn’t help the Chancellor meet her fiscal rules. For each pound invested in defence, the additional economic activity is relatively modest. By contrast, housebuilding generates a lot of additional economic activity, which is why promising to reduce planning hurdles can improve growth overall, despite carrying no fiscal cost.

The net result is that despite the deterioration in revenue growth assumptions, the OBR judgement once again predicts that the Chancellor will meet her current spending rule at £9.9bn. If that number seems familiar it’s because it restores exactly the same headroom the Chancellor had last autumn. 

Clearly £9.9bn is better than nothing, but the last few months have shown just how easy it is for economic performance to change and for perceived headroom to disappear. So far, most of the current parliament has seen a constant debate over whether tax increases and spending cuts might be required, and retaining this modest headroom invites that to continue. The real risk is that this uncertainty leads to companies feeling too unsure to invest. This is particularly relevant given the existing economic uncertainty that stems from the new U.S. government and its plans to introduce an uncertain range of tariffs.

At a time when the economic outlook is even more uncertain than normal, the Chancellor would ideally have more margin for error.

The other nuance about the fiscal rules is that they allow for the government to meet its targets by forecasting austere measures in the coming years. We share some scepticism about the extent to which spending growth will slow in some departments as the current parliamentary term concludes.

The fiscal rules are just one constraint that the government is under. The other, arguably more meaningful constraint, is the bond market reaction.

If governments are expected to borrow more money or if their actions are expected to boost inflation, then the cost of issuing new government debt will rise. With relatively few announcements made in the Spring Statement, and with recent days having seen reductions in welfare costs, the bond market has been relatively stable. This has been helped by the news indicating that UK inflation slowed slightly during February.

Overall, the Chancellor has reiterated the government’s commitment to its manifesto pledge against raising core personal taxes, taking a more cautious approach after earlier bond market jitters.

Much will now depend on how the economy fares between now and autumn’s budget.

Last night, Trump announced a 25% tariff on all car imports, which could escalate the ongoing tariff war. This could have a global impact on markets and undermine Rachel Reeves Spring Statement yesterday.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

27th March 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 25/03/2025.

U.S. equities start to stabilise

We explore the driving factors behind U.S. equities showing some signs of stabilising over recent weeks.

We’ve seen a fragile recovery in U.S. equity markets, with surveys suggesting trade uncertainty has made consumers and businesses wary (though surveys around politicised events can be unreliable). Weak sentiment indicated a potential rebound. However, several factors conspired to slow economic activity in early 2025.

Trade pain and the pain trade

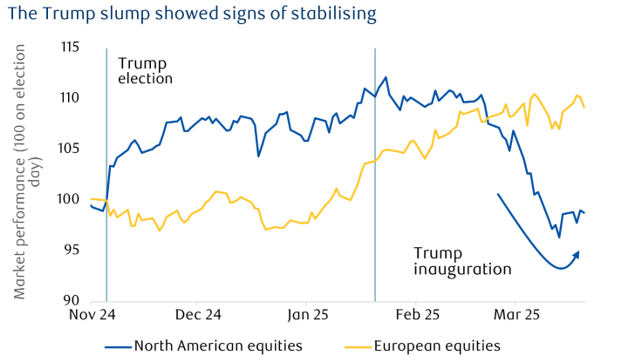
The so-called ‘Trump slump’ paused for breath last week, and the performance of regional equity markets became generally more uniform.

North American Equities post trump

Source: LSEG Datastream

The ‘pain trade’ is the tendency of the market to move in a way that causes the maximum possible pain to the largest possible number of investors. It happens when there’s a very widely and strongly held consensus, such as the belief that U.S. President Donald Trump’s second term would bring a boost to growth from deregulation and tax cuts, and that the artificial intelligence (AI) boom would continue.

In 2008, the U.S. equity market was around 1.5 times as big as the European equity market. By the end of 2024, it had ballooned to more than five times the size. That means any rebalancing from the U.S. to Europe can have a disproportionate impact on the latter. It pays to be aware of these technical factors in order to distinguish them from fundamentals.

Over the same period, U.S. earnings outpaced European earnings by a similar amount. Fundamentally, U.S. companies continue to be much more profitable than European companies and so demand a premium valuation.

Although there has been some deregulation, the market’s focus has been on surprisingly aggressive U.S. trade policy (which seems to have few winners and many losers) and the sudden realisation in Europe that the region would need to re-arm itself.

Are U.S. consumers spending less?

The most obvious rationale for the sell-off in U.S. equities has been the onset of trade tariffs. They seemed to be the trigger, but so far, their impact on the economic data has been restricted to surveys. It will be some time before tariffs show up in the wider economic data, but we can see some evidence of weaker economic activity that pre-dated any tariff announcements.

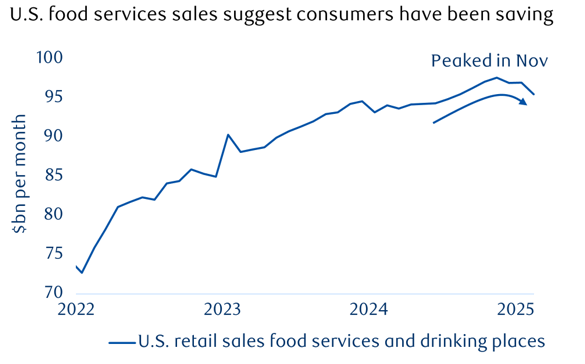
One example of this is U.S. retail sales data, which suggests a decline in consumer spending.

U.S Food Services

Source: LSEG Datastream

U.S. retail sales data has generally underwhelmed, and last week’s announcement did show a further decline in sales at food services and drinking establishments. This could suggest that consumers are going out less—although during the winter, we do see occasional lulls in eating out due to adverse weather conditions.

It looks like the U.S. consumer has been cutting back over the last four months or so. The onset of tariffs may cause them to do so more. Certainly, those who might be reliant upon the state for salary or welfare will be anxious over efforts to rein in government spending. But the U.S. economy has been growing comfortably, at more than 2% a year for the last two years, so there’s plenty of scope for a slowdown without it triggering a recession.

UK announces public spending reductions

Last week, the UK’s Work and Pensions Secretary Liz Kendall announced planned reforms to disability benefits. The government believes the measures will save more than £5bn per year by the end of the decade. The measures are being consulted on but have drawn sharp criticism from Labour backbenchers.

The government hasn’t given figures, but independent assessments suggest the reforms could strip over a million people of their benefits. The measures coincide with the UK’s pledge to increase defence spending and come ahead of the Spring Statement this Wednesday.

Over the weekend, Chancellor Rachel Reeves announced civil service costs will be cut by 15%. The cuts will come from back office and administrative functions and will be achieved through greater use of technology and productivity tools.

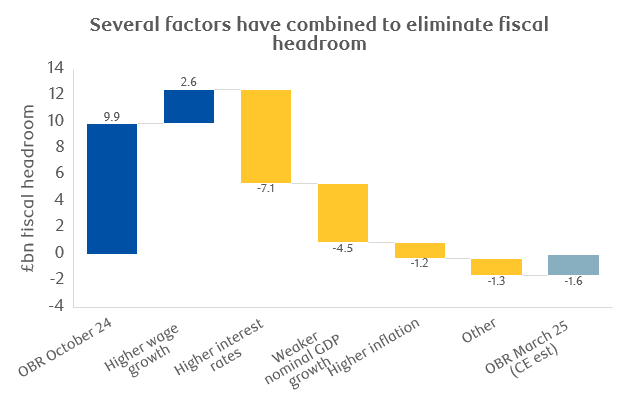
It’s expected that the Office for Budget Responsibility (OBR) will reveal that the government is in breach of its fiscal rules due to a combination of factors. Data released on Friday showed a continued shortfall in the UK budget, with borrowing during February exceeding OBR estimates. The shortfall could be £1.6bn according to estimates by Capital Economics.

Fiscal Headroom

Source: Capital Economics

The government has said that it won’t be increasing taxes in the Spring Statement, so it will need to announce more spending cuts (assuming it doesn’t loosen the fiscal rules).

The fiscal rules are one constraint but they can be fudged. Cuts in the future can be endlessly deferred, but the chancellor must also convince the lenders (i.e. the bond market) that the government is on a fiscally sustainable track.

The less fungible constraint is the impact that increased borrowing would have on market interest rates. As the UK’s fiscal position deteriorated earlier in the year, we saw a sharp rise in bond yields, and the UK remains in the focus of the bond markets.

UK interest rates were kept on hold last week as the Bank of England balanced the competing pressures of too high wages, an apparently slowing jobs market, and the probability of some form of modest fiscal tightening.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

26/03/2025