Team No Comments

EPIC Investment Partners: The Daily Update – Reality Check: Payrolls and the Fed’s Next Move

Please see the below article from EPIC Investment Partners detailing their thoughts following the release of the ADP Employment Report published earlier this week. Received this morning 07/03/2025.

Today’s non-farm payroll report could play a pivotal role in influencing the future path of US interest rates. The ADP employment report, published earlier this week, revealed private-sector employment rose by only 77,000 in February—significantly below the forecast of 148,000. This stark shortfall, particularly if replicated in today’s payroll release, could raise serious questions about hiring momentum and overall economic resilience. While the decline in yesterday’s initial jobless claims might suggest some stabilisation in the labour market, these figures have yet to capture the anticipated government layoffs tied to the DOGE incentive scheme, leaving the true state of employment somewhat obscured.

Trade policy remains an additional concern. Structural imbalances are evident in the US trade deficit, which reached $131.4 billion in January and has exceeded $100 billion in several months over the past year. While some of this deficit stems from front-running of tariffs, it also reflects an overvalued dollar and declining competitiveness, compounded by China’s manufacturing dominance and persistent US energy dependence. Tariffs, rather than directly reducing imports, tend to shift supply chains and act as an additional cost burden, thereby constraining economic growth.

The convergence of weak ADP figures, a sharply lower forecast for GDPNow—which currently predicts the US will contract by 2.4% in Q1 2025—and rising tariffs and geopolitical concerns all point to a weakening economic environment. Even if today’s payrolls do not show the sharp slowdown evident elsewhere, it will not alter the fact that growth expectations are weakening significantly across many sectors of the US economy.

For the Federal Reserve, these intertwined signals—weak job growth, evolving GDP projections, higher than desired inflation and trade imbalances—complicate the policy outlook. Should further data confirm a weakening labour market, especially with delayed government job cuts finally showing up, the pressure for additional rate cuts could mount. Conversely, if employment data proves more resilient, the Fed may opt for a more cautious approach.

Contrary to the expectations of many, the recent surge in US Treasury yields has proven to be short-lived, confounding many market participants. The 10-year yield, which reached 4.79% in mid-January, has since retreated to 4.25%. This rally in Treasuries traditionally signals an expectation of slowing economic growth and a potential shift in monetary policy. However, an additional dynamic is at play. During economic slowdowns, reduced demand for cash from corporations and consumers can lead to a surplus seeking yield in the bond market, increasing demand for safe-haven assets like Treasuries.

Therefore, while the labour market is a lagging indicator, any weakness revealed in today’s non-farm payroll report would reinforce the evidence of a slowdown observed in other economic indicators. Although concerns over tariff-induced inflation may have previously delayed policy adjustments, we believe the bond market has yet to fully price in the extent of the economic softening now becoming apparent.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

07/03/2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update.

What has happened

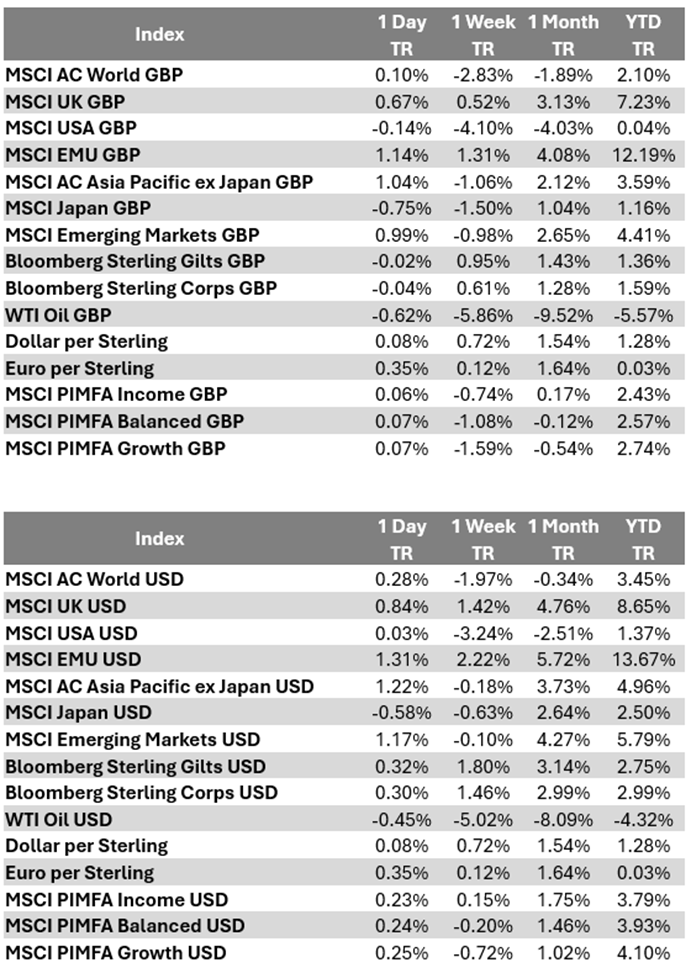
Yesterday saw more tariff headlines, and with it, more tariff-whiplash for markets. Investors have been struggling to keep pace with the policy-pivots from US president Trump, often in the space of hours, let alone days, and that tariff volatility and uncertainty continued through yesterday. In equity markets, the US S&P500 index finished up +1.12%, and the pan-European STOXX600 index gained +0.91%. The biggest gains (and headlines) however, were over in Germany where its plans to ramp up defence and infrastructure spending has lit a fire under the German stock market, with the country’s DAX30 index up +3.38% yesterday, all in local currency terms.         

Tariff watch latest

Just a day after the US imposed 25% trade tariffs on Canada and Mexico on Tuesday, Trump announced yesterday that he has was suspending for one month those tariffs for auto makers – it looks like Trump blinked first, bowing to lobbying from the big US auto companies – Ford, GM, and Stellantis (which includes Chrysler). That said, the US Trump administration continued to stress the coming 2 April implementation date of ‘reciprocal’ trade tariffs with countries around the world that levy US trade currently.

Germany’s fiscal plans are a big deal

More details are shaping up around Germany’s hastily-drawn up plans for possibly as much as EUR 900 billion worth of fiscal spending, which will be split between two funds, one for defence, and one for infrastructure. The sudden zeal of German politicians is being driven by two factors: (1) the unprecedented US withdrawal from providing defence guarantees to Europe going forwards; and (2) the need for German politicians to ram this legislation through the old parliamentary term which has around two weeks left, as there is much less likelihood of securing the two-thirds vote needed to overturn the country’s fiscal debt-brake rule when the new parliament (with different party seat-numbers post the recent German Federal election) takes over later this month.

What does Brooks Macdonald think

Our Brooks Macdonald Asset Allocation Committee guides to a neutral outlook on Developed Europe ex-UK equities, with a broadly in-line-weight across our risk bands relative to our PIMFA benchmarks. While Germany has the debt-to-GDP ratio headroom to allow for this huge ramp in fiscal spending, the same cannot be said of the other major European countries. Supporting this neutral outlook, there are also still significant headwinds for the region, including US tariff risks, increased export-competition from China in autos in particular, and fragile regional economic growth risks more broadly.

Please check in again with us soon for further relevant content and market news.

Chloe

06/03/2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 04/03/2025.

How are tariff threats impacting the economy?

We explain how President Trump’s recent trade tariff announcements have impacted consumer confidence.

Another week passed with geopolitics firmly at the top of investors’ minds. U.S. President Donald Trump was his usual vocal self, but did also signal some decisive action.

President Trump sewed some confusion when he said on his app, Truth Social, that trade tariffs on Canada and Mexico would come into effect in April. It seems likely he was actually referring to his planned reciprocal tariffs, which are due to be decided in April following investigations.

25% tariffs on Canada and Mexico were imposed today. This is due to President Trump stating he wasn’t happy with the efforts made to reduce the inward flow of the addictive substance fentanyl through America’s neighbours. Of course, that could change. However, it’s hard to see how Canada can significantly reduce its share of fentanyl flow into America – it’s estimated that far less than 1% comes in via the northern border.

While tariffs had been threatened against Canada and Mexico, Chinese tariffs were already imposed in February over fentanyl flowing into the U.S. from China. So, it was a shock when President Trump announced that he would increase those Chinese tariffs by an additional 10%. China tends to respond with its own counter measures when tariffs become effective (a wise move given the U.S. president’s tendency to withdraw them at the last minute).

On this occasion, with the Chinese economy still struggling, there’s speculation that this latest challenge could prompt explicit measures to boost economic activity, such as fiscal stimulus or even a currency depreciation. China has recently seen its consumer prices start to pick up, but inflation remains disconcertingly low. For that reason, China wouldn’t need to worry about the inflationary impact of a currency depreciation.

President Trump also discussed potentially selling gold cards to wealthy prospective immigrants. For the sum of $5m (paid to the U.S. Treasury), these would grant the benefits of a green card.

Will Germany loosen its brakes?

The German election results were announced last week. The Christian Democratic Union (CDU) emerged as the largest party, with the previous leaders, the Social Democratic Party (SPD), slipping to third place.

While the results were largely in line with polling predictions, the victory gave the CDU (and its usual electoral partners the Christian Social Union [CSU]) and SPD enough votes to form a governing coalition with a narrow majority of 13 seats. Even if that group worked together with the Greens to relax the debt brake that limits Germany’s ability to borrow, they would fall marginally short of the 66% majority required to achieve the constitutional change.

The importance of this is a matter of debate, because the CDU and Greens would both like to borrow more money, but they would always struggle to agree what it should be spent on. The CDU favours defence, whereas the Greens place more importance on infrastructure.

With constitutional reform seemingly off the table, there are ways to increase spending a little by using loopholes or by declaring an emergency. The looming threat of an antagonistic Russia and/or the weakening of America’s commitment to NATO (without further spending from European peers) under President Trump seem reasonable arguments for an emergency.

Chancellor-elect Friedrich Merz spent the week trying to negotiate for greater defence spending. This was met by howls of protest from other party heads over what they suggested were double standards; Merz has previously held former Chancellor Olaf Scholz to account over borrowing plans and now wants to raise borrowing himself once elections have been concluded.

Nvidia shares its company results

One of the most significant events last week was Nvidia’s earnings results.

It’s late in the earnings season but Nvidia’s results have become an important market gauge for the strength of demand for artificial intelligence and its associated infrastructure. The results were strong, with revenue growth of 78% year-on-year, which was technically well above expectations.

The company’s guidance for the next quarter was also positive, with expected revenue growth of 6% to 8%, which was good, but it didn’t inspire the market. 74% of companies have beaten earnings estimates this year, so sometimes just beating estimates isn’t enough – instead, they must far exceed expectations.

Berkshire Hathaway’s recent results showed strong performance, with operating earnings up 45% for the quarter and 25% for the year. The company’s cash position has increased, and while there were no share buybacks, the valuation isn’t seen as particularly demanding. Warren Buffett’s unwillingness to buy back either his own shares or to make further investments in the market provides an indication that valuations aren’t currently wildly attractive.

Looking ahead

This week, investors will be bracing themselves for a slew of economic events that could significantly impact the markets. Key releases, including manufacturing and services purchasing managers indices (PMI) data, inflation rates, gross domestic product (GDP) growth, and employment numbers from major economies are all set to feature.

Chinese indices, the NBS Manufacturing PMI and the Caixin Manufacturing PMI will provide insights into the country’s manufacturing sector, with expectations of a modest recovery. In the U.S., the Institute for Supply Management (ISM) Manufacturing PMI is expected to show a decline in manufacturing activity, while Japan’s Consumer Confidence Index may indicate a slight improvement in consumer sentiment. 

In addition to these economic events, several major companies are scheduled to report their earnings this week, including Broadcom Inc, Ashtead Group, Admiral Group, and Costco Wholesale Corporation. These reports will provide valuable insights into the performance of these companies and their respective industries. Investors will be watching these releases closely for signs of strength or weakness in economic recovery, which could impact market sentiment and direction.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

05/03/2025

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below, an article from Brooks Macdonald providing a brief analysis of the key factors currently affecting global investment markets. Received today – 04/03/2025

What has happened

In a measure of how investors are responding to the unprecedented geopolitical developments around Ukraine, yesterday saw another big gain for European defence stocks in particular. The pan-European STOXX Aerospace & Defence Index jumped +7.7% yesterday, recording its strongest daily gain in over four years, since November 2020. Among the companies leading those gains, UK-listed BAE Systems closed up +14.6% yesterday, and is now up +40.3% this year alone, all in local currency price return terms.

US pauses military aid to Ukraine

The White House yesterday confirmed that US president Trump has ordered a pause on all fresh military aid to Ukraine not yet drawn down by the outgoing Biden administration. The order applies to all US military equipment not currently in Ukraine, including weapons in transit on aircraft and ships or waiting in transit areas in Poland. While the extent of the affected weapons is not public knowledge currently, Trump had inherited an authority from Biden’s administration to deliver some US$3.85 billion’s worth of weapons from US stockpiles.

Trump tariffs arrive, and trade retaliation comes quickly

There was no last-minute reprieve for US president Trump’s tariffs on Canada, Mexico and China which have come into force in the last few hours. There are now 25% trade tariffs on Canada and Mexico, as well as a second 10% hike in tariffs on China trade on top of past China tariff measures – according to Bloomberg, this collectively impacts around US$1.5 trillion worth of annual US imports. Canada has retaliated with a first wave of 25% tariffs on some US exports while China has added tariffs of up to 15% on US exports.

What does Brooks Macdonald think

Yesterday’s latest US economic data did nothing to ease stagflation fears that have been stalking markets lately. The US Institute for Supply Management (ISM) manufacturing survey headline was weaker than expected (at 50.3), and only just expansionary month-on-month, versus the 50-halfway mark that separates economic expansion and contraction. Within the data, new orders (at 48.6) and employment (at 47.6) were both weaker than expected and in contraction territory, while Prices Paid jumped 7.5 points (to 62.4), and now at the highest level in almost 3 years, since June 2022.

Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World GBP -1.81%-2.26%-2.83%0.31%
MSCI UK GBP 0.71%2.63%3.94%9.12%
MSCI USA GBP -2.75%-2.86%-5.10%-1.98%
MSCI EMU GBP 1.29%1.24%5.60%12.28%
MSCI AC Asia Pacific ex Japan GBP -0.95%-3.89%-0.18%0.04%
MSCI Japan GBP 1.13%-1.67%0.76%0.75%
MSCI Emerging Markets GBP -0.98%-3.91%-0.26%0.71%
Bloomberg Sterling Gilts GBP -0.56%0.16%-0.12%1.08%
Bloomberg Sterling Corps GBP -0.37%-0.07%-0.13%1.29%
WTI Oil GBP -2.96%-3.87%-8.91%-6.15%
Dollar per Sterling 0.99%0.60%2.02%1.48%
Euro per Sterling -0.12%0.40%0.62%0.21%
MSCI PIMFA Income GBP -0.68%-0.48%-0.52%1.93%
MSCI PIMFA Balanced GBP -0.79%-0.68%-0.71%1.97%
MSCI PIMFA Growth GBP -0.96%-0.99%-1.01%1.98%
Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World USD -0.82%-1.67%-0.31%1.89%
MSCI UK USD 1.72%3.24%6.64%10.84%
MSCI USA USD -1.78%-2.27%-2.63%-0.44%
MSCI EMU USD 2.30%1.85%8.34%14.05%
MSCI AC Asia Pacific ex Japan USD 0.04%-3.31%2.41%1.62%
MSCI Japan USD 2.14%-1.08%3.37%2.33%
MSCI Emerging Markets USD 0.01%-3.33%2.33%2.29%
Bloomberg Sterling Gilts USD 0.30%0.81%2.22%2.50%
Bloomberg Sterling Corps USD 0.50%0.57%2.21%2.72%
WTI Oil USD -1.99%-3.30%-6.55%-4.67%
Dollar per Sterling 0.99%0.60%2.02%1.48%
Euro per Sterling -0.12%0.40%0.62%0.21%
MSCI PIMFA Income USD 0.31%0.11%2.06%3.53%
MSCI PIMFA Balanced USD 0.21%-0.08%1.87%3.58%
MSCI PIMFA Growth USD 0.03%-0.40%1.56%3.59%

Bloomberg as at 04/03/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

4th March 2025

Team No Comments

Tatton Monday Digest – Honeymoon Ends Early

Please see below, this week’s Monday Digest from Tatton Investments Management:

Honeymoon ends early

No meaningful recovery for US stocks last week – but a slight warming for European shares. Encouragingly, Keir Starmer’s charm offensive resulted in President Trump saying “tariffs wouldn’t be necessary” for the UK – but Emmanuel Macron’s earlier experience (warm words followed by a 25% EU tariff) shows we shouldn’t get too comfortable. 

Investors are no longer excited about Trump 2.0: the tax cuts and deregulation haven’t happened, but tariff threats and government disruption have. US consumers are similarly disillusioned, judging by sentiment surveys and (slight) signs of corporate stress. But we should expect avid stock market watcher Trump to react with economic support, including the $4.5tn tax cut plan outlined by Congress last week.

Worryingly, German Chancellor-in-waiting Friedrich Merz seemed to suggest US-European negotiations are now futile, but European stock valuations actually improved relative to the US. European bullishness is based on domestic improvement, and the need for defence spending amplifies that. The real long-term benefit for Europe would come from genuine policy cohesion, but that requires strong and unified leadership. We will see if Merz can provide that as his coalition attempts to reform Germany’s constitutional debt brake. 

It’s notable that capital is now flowing out of the US, and even Nvidia’s stellar profits weren’t enough to stem the tide. We wrote before that this could be related to Trump chipping away at the US-led global order that underlies international finance, and the White House’s restrictive “America First Investment Policy” announced last week doesn’t help. 

Now that investors are allocating assets away from the US, you would bet on Trump changing tack. The current market rotation isn’t as pronounced as the one we saw last summer, and US policymakers (both the government and the Fed) have enough manoeuvrability to correct. If they don’t, US exceptionalism will continue to be undermined. In that case, the 100-day honeymoon period for new US presidents could end abruptly.

Higher price caps don’t mean higher prices

Ofgem’s energy price cap will rise 6.4% in April, raising the typical UK household’s energy bill to £1,849 per year. That’s much lower than at the peak of the natural gas crisis, but it does mark a third consecutive quarter of price hikes. This is a concern for the Bank of England (BoE), whose struggle to reach 2% inflation is proving harder than expected.

Ofgem’s price cap limits the rate energy companies can charge rather than overall bills – which is why it’s expressed in terms of the ‘typical’ household. The energy regulator sets it based on wholesale gas prices, for which natural gas is the biggest swing factor.

Gas prices are volatile – down sharply this month but well above levels from a year ago. The interesting thing is that futures contracts for gas are significantly below current prices, suggesting prices will fall over the long-term. That’s why analysts the cap will fall in July – but it could also mean energy companies charging below the upper limit. What’s important is what people are paying, not the official price. Ofgem itself, for example, recommends consumers lock in current rates for the fixed term – and many consumers are doing so.The 6.4% cap hike isn’t really inflationary if people aren’t paying more (by locking in lower rates or by cutting down usage) and that has implications for how inflation is measured. The price index is supposed to capture aggregate costs, but this based on the going market rate. Ofgem’s price hike will impact that, but measuring how much consumers are out of pocket is harder. We see this another reason the BoE should look through current stated inflation and focus on weak UK growth. The bank will be cautious, but shouldn’t overinterpret a one-off hike.

How will the US budget resolution resolve?

The Republican-controlled US House of Representatives passed Donald Trump’s “big, beautiful” budget resolution bill by the narrowest of margins. This non-binding budget blueprint contains $4.5 trillion in tax cuts (though most of these are extensions of Trump’s ‘temporary’ 2017 tax cuts) and $2tn in spending cuts – with government debt plugging the gap. The Senate is now under pressure approve the same resolution (though they passed their own separate version last week), or else opposition Democrats will be able to stifle the bill’s progress. This has to happen before 14 March, or the US government will face one of its frustratingly common shutdowns. 

The bill was touch-and-go; resistance came from both fiscal conservatives worried about excessive debt and moderates worried about punishing spending cuts. The danger for Republicans is that cutting vital public services (like Medicaid health insurance) could upset the populist MAGA base that delivered them power.

We warned before Trump’s inauguration that enacting the disruptive policies before the supportive ones would undermine the economy, and the latest data suggest that is happening. The budget resolution could be a sign that the White House is changing tack in response – though more support will be needed, as most of the tax cuts are just extensions of old measures.

We warned last year that Trump’s tax-cutting plans could worsen the US’ already stretched fiscal position. Fiscal deterioration has felt like a non-issue recently, due to the White House slashing federal spending and the economy starting to weaken in response – but the latest budget reminds us that government borrowing is still a concern. Bond yields have fallen, but that could change, especially if accompanied by the current trend of global central banks selling dollar assets. A sell-off in the world’s biggest bond market is still unlikely, but it’s a risk we have to monitor.

Please continue to check our blog content for advice, planning issues and the latest investment market, and economic updates from leading investment houses.

Andrew Lloyd

03/03/2025

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.

What has happened

A good-but-not-great set of results from Nvidia on Wednesday evening plus more trade tariff comments from US President Trump in the past 24 hours collectively weighed on sentiment yesterday. The US technology megacap ‘Magnificent Seven’ group fell -3.03% on Thursday, with Nvidia down -8.48%. That pushed the US S&P500 equity index down -1.59% yesterday, and on course for its worst week since September, while the pan-European STOXX600 equity index dropped around -0.46%, all in local currency price return terms.

More Trump tariff headwinds for markets

Markets had to weather more Trump tariff headwinds on Thursday. Yesterday saw US President Trump announce an additional 10% trade tariff hike on China, as well as pushing ahead with 25% tariffs on Canada and Mexico, all due to be effective from Tuesday next week, 4th March. In addition, Trump said his plan for “reciprocal” tariffs on those countries that currently tariff US trade would still go ahead as planned in just over a month’s time on 2nd April.

A mixed US economic and inflation picture

Yesterday saw a second update on calendar Q4 2024 US economic growth and inflation. In the mix, US Gross Domestic Product (GDP) rose by an unrevised +2.3% quarter-on-quarter annualised – still a decent number versus the US Federal Reserve’s longer-run US economic growth estimate of +1.8%. However, as regards underlying inflation, according to the US Personal Consumption Expenditures (PCE) price index, core prices (excluding energy and food) rose to +2.7% quarter-on-quarter annualised, faster than the +2.5% initially reported and expected.

What does Brooks Macdonald think

Trump’s tariffs hold a stagflationary tilt-risk for markets, in that, at the edges, such trade levies would dampen economic growth, while buoying inflationary pressures. Of course, it is worth bearing in mind that we have potentially seen this movie before so-to-speak .. at the start of February, Trump’s proposed tariffs against Canada and Mexico were extended by a month with just hours to spare until they had been due to come into force. As the late British historian A.J.P. Taylor, who specialised in 19th and 20th century international diplomacy, reminds us, “nothing is inevitable until it happens.”

Bloomberg as at 28/02/2025. TR denotes Net Total Return.

Please check in again with us soon for further relevant content and market news.

Chloe

28/02/2025

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, an article from Brooks Macdonald providing a brief analysis of the key factors currently affecting global investment markets. Received today – 27/02/2025

What has happened?

Markets were positive for the most part yesterday ahead of US technology megacap Nvidia’s results out after the US close, while tariff remarks from US President Trump late in the day weighed on sentiment. The US S&P500 equity index finished largely flat, while the pan-European STOXX600 and the UK FTSE100 equity indices which had closed earlier did better but were both up by less than +1%, all in local currency price return terms. When Nvidia results did arrive, the tech giant delivered good-but-not-great quarterly results, in turn drawing a muted response from investors which have hitherto grown accustomed to blowout numbers.

Nvidia results

The main focus for global investors yesterday was Nvidia’s results which landed after the US stock market close. In the event, the world’s second biggest company by market value (at around US$ 3.2 trillion) and the poster child for the Artificial Intelligence(AI) spending boom, delivered good-but-not-great quarterly results. The company said revenues would be around US$43 billion over the current fiscal quarter (February-April), just ahead of a market consensus estimate of US42.3 billion, but below the upper end of the range at around $48 billion. Nvidia’s CEO Jensen Huang said that the company would “grow strongly in 2025”, while the demand for its latest ‘Blackwell’ AI chip was “amazing” and the “fastest product ramp in our company’s history”.

Trump’s trade tariff comments knock EU sentiment

Shortly after European stock markets had packed-up for the day, US President Trump threw another tariff-sized spanner in the works for European Union (EU) trade. Trump announced that he was proposing a potential 25% tariff against the EU on “cars and all other things” and coming “very soon”. Given Trump’s comment yesterday that “the European Union was formed in order to screw the United States”, it suggests these tariffs could be widespread across sectors. Furthermore, asked if the EU might retaliate, Trump said “they can’t I mean they can try, but they can’t.” The pan-European STOXX600 equity index opened down -0.7% earlier this morning.

What does Brooks Macdonald think?

Nvidia’s results and share price reaction are a reminder that expectations matter. No one doubts that Nvidia is a great success story and has some amazing products at the heart of the AI boom. The question is: what is the right value to ascribe to Nvidia? With even just the smallest change to Nvidia’s gross margins (currently up in the 70’s%) for example, this can make huge differences to long-term modelling outputs and its share price. What should investors do? At the end of the day, Nvidia is a widely-researched company so outsmarting the market is very difficult – arguably the easiest solution from a portfolio perspective therefore is to be diversified, keeping some but not too much exposure to any one stock to avoid concentration risk, and especially so when it comes to gigantic-sized stocks like Nvidia.

Bloomberg as at 27/02/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

27th February 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 25/02/2025.

What’s next for UK interest rates?

We explain how sticky inflation could impact the Bank of England’s interest rate decisions.

The start of 2025 has seen last year’s equity laggards making the early running. Notably, European equities have performed well following a tough 2024. They were perceived as victims of President Trump’s interventionist economic trade policy and as such, they were unloved and under-owned, but have bounced back firmly.

Like all regions, European companies generate a lot of their revenue globally, but unsurprisingly, they’re the most exposed to European economies. Around 30% of the revenue generated by European companies comes from the region, so when a domestic economy struggles, it has a market impact.

Has the outperformance of European equities reflected a less antagonistic stance from the Trump administration? Far from it. If anything, investors might be more concerned about the challenges posed by President Trump’s actions now than they were before the U.S. election. His tone has been strangely antagonistic towards Europe.

U.S. geopolitical focus adds pressure on Europe

A couple of weeks ago, we discussed the suggestion that the U.S. administration might consider value added tax (VAT) as a barrier to trade – despite logic and research arguing otherwise. Last week, the pressure on Europe shifted to geopolitics, with Secretary of Defence Pete Hegseth telling the Munich Security Conference that Europe should foot most of the bill for Ukraine’s defence against Russia.

Hegseth said returning to pre-2014 Ukrainian borders (when Russia annexed Crimea) was unrealistic, and that NATO membership for Ukraine was also an unrealistic prospect. To underpin the weakness of Ukraine’s negotiating position, President Trump seemed to parrot Russian propaganda by referring to Ukrainian President Volodymyr Zelenskyy as a “dictator” (Ukraine has not held wartime elections).

The Trump administration continues to emphasise that European defence spending should reach 5% of gross domestic product (GDP), a level above the current NATO pledge of 2%. That may be bluster, but the pressure on European countries to meaningfully increase defence spending is real. The difficulty is that most have very limited fiscal scope to do so.

The economic situation in Europe

Some countries, such as France, were already struggling to rein in their borrowing, after having toppled Michel Barnier’s government due to its attempts to take tough choices and reduce borrowing.

The twin needs of higher defence spending and restored public sector balances imply the need for some very difficult political choices, and a net contractionary fiscal policy.

It’s an unwelcome situation for France, which has been struggling economically. France and Germany have substantial manufacturing sectors, which have been experiencing difficulties through a global downturn. Recently, the services sector has also been looking fragile. Friday’s flash estimate of French economic activity from the purchasing managers indices (PMIs) was strikingly weak, driven by a marked deterioration in the services sector. The data may be anomalous.

Neighbouring Germany’s equivalent results were much less stark, as was the broader Eurozone PMI. France’s political and debt situation is distinctly worse than that of many of its European peers. This might be unsettling to its shoppers, but consumers are generally insensitive to these things – until they feel the cost of them in terms of wages, job losses, or inflation. Economic pressure therefore remains for Europe.

However, the prospect of an end to hostilities in Ukraine does bring potential economic benefits. Moscow could increase the gas flow to Europe if peace talks are successful. That would be welcome because replenishing gas storage for next winter is another worry for European leaders. There should also be huge opportunities for construction and redevelopment activity in Ukraine once the conflict has ended.

Like France, the UK saw an implied contraction in its manufacturing and services sectors but that contrasted with a lot of other data out last week. Employment data, whilst notoriously unreliable, suggested that employment numbers weren’t dropping. Wage growth was fast and, even though inflation data was strong, the implication was that UK wages are rising faster than inflation, contributing to stronger-than-feared retail sales growth.

Interest rates have been coming down recently, which provides further support, and the shock of high mortgage rates is beginning to ebb. Consumer sentiment edged higher, begging the question: why are the business surveys so weak?

Some of this could simply be temporal. Consumers are enjoying the decline in inflation over the last two years, cuts to National Insurance contribution rates, and rising house prices. Businesses, however, are planning on how to address the steep increases in employers’ National Insurance contribution rates.

Europe’s next move

The results of this weekend’s German elections have landed, showing centre-right Christlich Demokratische Union (CDU) and centre-left Sozialdemokratische Partei (SDP) winning a majority of the seats in the Bundestag. The new coalition will have big implications for the German economy and beyond. It’s likely it will want to reform the strict national debt brake enshrined within the German constitution – however, this requires a two thirds majority, which it didn’t receive.

The results were in line with pre-election polling and suggest that a two-party coalition can be formed. Whilst that will require cooperation from the centre-left and centre-right parties, it’s considerably more manageable than a three-party government including the Greens.

Tariffs a source of uncertainty for U.S. businesses and citizens

The stream of announcements on U.S. trade tariffs, and subsequent delays or amendments, makes for an unusually opaque economic policy environment, which must be weighing on companies to some extent. There’s some limited evidence that it’s also affecting the U.S. public.

President Trump’s approval rating has been dropping since he took office, which isn’t unusual. Although the economy has remained strong, and the President has been proactive, this suggests that some of his actions are jarring with segments of the public. A majority believe he should have done more to bring down prices. Whilst that’s an unrealistic expectation, it’s one he did little to dispel on the campaign trail and the landmark policies of imposing tariffs and limiting inward migration are inflationary in nature.

Federal employees in particular will be concerned about their futures given the actions of Elon Musk and the Department of Government Efficiency. A recent poll found that just 39% of the public approved of the President’s handling of the economy. This is a decline of 4% from the end of January, after which we’ve had a flurry of confusing announcements on tariffs.

As a reminder, trade tariffs affect many U.S. businesses because they import components, and they affect consumers because ultimately, the cost of import tariffs will typically be paid by U.S. consumers.

At the end of last week, the University of Michigan Consumer Sentiment Survey seemed to underpin this. It showed consumer expectations for inflation in the coming five to 10 years increased to the highest level in nearly 30 years. Meanwhile, the S&P Global Purchasing Managers Index noted a significant shift in business activity in February from just a couple of months previously, which it attributed to “widespread concerns about the impact of federal government policies, ranging from spending cuts to tariffs and geopolitical developments.”

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

26/02/2025

Team No Comments

EPIC Investment Partners – The Daily Update: Gold – Bitcoin characteristics and more

Please see the below article from EPIC Investment Partners detailing their thoughts on Bitcoin and the market for Gold. Received this afternoon 25/02/2025.

Bitcoin remain the bell weather of the crypto world. We do not pretend to be experts on crypto currencies. The key characteristic of Bitcoin is the halving of payments to miners every four years. This means the number of Bitcoins outstanding cannot exceed a finite number (21 million). There are currently 19,969,375 Bitcoins outstanding with a further 1,030,625 Bitcoins left to be mined.

We saw a fabulous chart the other day. A chart from Minex Consulting was used by Rupert Resources, a listed Australian company, in their most recent presentation material. The chart tracks annual Gold discoveries (in millions of ounces) against global exploration (in billions of Dollars) from 1975 to 2023.

In 2005, 300 million ounces were discovered, a record high. Prior to that in the 1980 to 2005 period, discoveries averaged circa 150 million ounces per annum. Global exploitation expenditure has averaged circa $5bn pa over the past fifty years. It peaked in 2012 at $14bn but has since retreated to a range to $5-7.5bn annually.

What interests us is the sharp decline in Gold discoveries since 2005. Discoveries halved between 2005 to 2010 to roughly 150 million ounces. They then halved again to circa 75 million ounces by 2015. Discoveries remained at that level during the period 2015 to 2020 but have fallen off a cliff since.

You can buy things with Bitcoin but you cannot make anything with it. Thanks to its supreme conductivity, Gold continues to play a key role in the global electronics industry while the global jewellery industry is the other obvious significant consumer. Central Banks can be significant buyers or sellers (Thanks Gordon, we have not forgotten) but, equally (if not more importantly) those living in countries where currency depreciation has been an annual event for decades have a healthy respect for the metal’s ability to hold its value in real terms over time.

India comes to mind. On this author’s first visit to India in 1989 16 Rupees would purchase 1 Dollar.  Today, 36 years later, one needs 86 Rupees to purchase 1 Dollar. Over five times as many Rupees.

With its practical uses, as well as a proven ability to hold its value over time, Gold looks the better bet despite its recent run. Particularly if the halving continues.

Please continue to check our blog content for advice, planning issues, and the latest investment, market and economic updates from leading investment houses.

Alex Clare

25/02/2025

Team No Comments

Tatton Monday Digest

Please see below, this week’s Monday Digest from Tatton Investments Management detailing their outlook on global politics impact on business – 24/02/2025

Global politics turn business
Capital markets ended last week on a slightly downbeat note. That was more about the US economy than its astounding shift in foreign policy – but here everyone is focussed on Donald Trump’s recasting of Russia as an ally and Europe as an antagonist. The most immediate impact was a rise in European defence stocks, which will benefit from the inevitable rise in European military spending. Spending will almost certainly be funded by government borrowing, which is why European yields increased more than the US. This should help short-term European growth, but it could also be inflationary. Interestingly, Britain is perhaps the best placed of any European country to benefit from the continent’s defensive shift.

Beyond those moves, markets seem unsure what to make of Trump’s tectonic shift – with most indices unmoved from a week ago. Under the surface, we see signs of falling risk appetite. What happens to markets next will depend more on US market sentiment than politics. Business sentiment disappointed in the world’s largest economy (and in Europe) and now points towards mild contraction. That might reflect previous overconfidence during Trump’s honeymoon period, rather than how bad things are now, but it’s a notable change from the start of the year nonetheless.

We shouldn’t overreact to the US’ political pivot, but we shouldn’t underestimate its market impacts either. The international financial system is built upon the very US-led world order that the president is chipping away at – by focussing on short-term transactional gains rather than long-term stability. A mild outcome would be worsening risk appetite; a terrible outcome would be global financial fragmentation. 

Asset allocation decisions need to be based on a holistic analysis of how these factors will play out. Despite the noise, none of the major global risk signals are flashing red. Markets have dealt with Trump’s disruption well, but we should keep an eye on confidence indicators and Europe’s response will also be crucial. With a new government in Germany being formed by CDU leader Friedrich Merz already saying his “absolute priority” would be to “strengthen Europe as quickly as possible so that we can achieve real independence from the US step by step” more change is coming. 

Risks are rewards for gold
Gold prices are still surging. Bullion is approaching $3,000 per ounce and has become divorced from historical valuation metrics. Historically, real (inflation-adjusted) gold prices have closely tracked real US bond yields, as it’s often considered a currency alternative, but that correlation broke a few years ago. Emerging market central banks started buying the precious metal after Russia was frozen out of the West’s financial system. Net central bank purchases have reignited in the last few months after seemingly plateauing in the autumn. Given the global geopolitical risks around, you would bet on this continuing.

People buy gold when there are global political or financial risks – and Donald Trump’s second term as US president is full of them. On top of that, gold is benefitting from a technical momentum trade. Technical squeezes can be particularly pronounced for an asset like bullion, which has a small physical supply and a comparatively huge market for its derivatives. For example, the cost of short-term gold borrowing has shot up due to a shortage of physical gold, seemingly due to increased demand from New York and subsequently drained supply in London (the world’s largest market for gold trading). 

The long-term trends are hard to untangle from the short-term technical factors. Short squeezes always loosen, and perhaps Donald Trump’s détente with Russia could lessen central banks’ desire to buy bullion. They are unlikely to buy back into the dollar, though, as faith in the world’s reserve currency is based on long-term institutional stability rather than policy whim. It’s hard to see gold demand falling while the political temperature stays high. 

This uncertainty and volatility is why we don’t consider gold a suitable long-term investment. It is the purest store of value there is – but that fact itself affects how we value it. As the old saying goes, “Gold is the currency of fear”.

Commodities point to growth
Commodity prices are a good indicator of global trade – which has been threatened this year by Donald Trump’s tariff threats. The Goldman Sachs Commodity Index (GSCI) is up more than 5% since the start of the year, with copper a particular standout (about 14.7% up year-to-date). The metal is strongly related to green tech, which China is still developing in full force despite US environmental rollbacks. Trump’s tariffs threaten global trade, but commodity prices suggest the underlying fundamentals are holding strong.

The exception has been oil, which has largely traded sideways in 2025. Even if global growth is improving, Trump’s “drill baby drill” policies will keep crude supplies high.

Commodities were weak last year due to the global manufacturing downturn. That was down to China’s weak economy and overproduction, which only started turning in September, after Beijing’s stimulus announcements. Overproduction might sound like a positive for commodities – and in periods it was – but it also means inventories fill up, leading to the peaks and troughs we saw through 2024. Notably, GSCI’s recent spikes (in September and at the start of this year) have coincided with the times when investors feel most confident about Chinese growth.

Improving demand will benefit global trade, even if trade wars pose a risk. The recent commodities rally suggests investors recognise this. The flipside of this, however, is potentially more inflation. Chinese overproduction hurt global growth last year, but it also gave western central banks a helping hand by reducing input costs. A reversal of that trend could be problematic, especially if it coincides with tariffs. That could be worse for the US (with its stubbornly tight labour market) than Europe (with its weak domestic economy). Higher commodity prices are ultimately a good sign for global growth, but there is a nagging feeling that the last leg of the post-pandemic spike in global inflation is the hardest to beat.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

24th February 2025