Team No Comments

Tatton Investment Management – The Monday Digest

Please see the below article from Tatton Investment Management detailing their key takeaways from markets over the past week. Received this morning 24/03/2025.

Bracing for tariff “Liberation Day”

Capital markets were calmer last week. We said before that US investor sentiment had swung too far and could bounce back – and so it proved. This was helped by the Federal Reserve holding interest rates steady and reducing its quantitative tightening (QT) bond sales. The QT reduction is a good sign for market liquidity, and markets interpreted the Fed as dovish. US bond yields fell, which would usually weaken the dollar but, for reasons that aren’t clear, the dollar strengthened – making US stocks one of the best performers in sterling terms.

The biggest help was a quieter White House, and no new government layoffs. Even Trump’s criticism of the Fed (for not cutting rates) was tame by his standards. Simply ending the disruption won’t be enough to get markets back on side, however; Trump needs to make good on his market-friendly policies. If jobs data weakens, he just might.

The biggest geopolitical scares were outside of the US: Turkish president Erdogan imprisoned Istanbul mayor Ekrem Imamoglu, a political rival. This is a problem for Europe, which sources military hardware from Türkiye and needs stability more than ever.

We get the feeling that markets are bracing for Trump’s tariffs on 2 April – his “Liberation Day”. Tariffs could well be avoided through last-minute deals, but it’s hard to see how US demands can be met. The White House wants “reciprocal” tariffs, where this is based on its own estimate of tariff costs. But estimates will vary across countries due to different regulations and economic factors. Insisting on Trump’s version of “reciprocity” will inevitably lead to tit-for-tat.

We await to see how these will play out, but before then we have next week’s US business confidence numbers, and the UK government’s Spring Statement. If confidence numbers are bad, “Liberation Day” could be delayed.

Central Bank Update

Two central bank meetings last week, and no interest rate changes in either. The Federal Reserve held rates steady but predicted worse growth and higher inflation for 2025 – explicitly tied to Trump’s tariffs. However, this didn’t materially shift the Fed’s “dots plot” (a graph of members’ rate expectations), since chairman Powell expects tariff inflation to be “transitory”. That’s because sales tax hikes usually act like one-off cost hits, which don’t impact inflation figures beyond a year.

But it’s a big assumption to think that Trump’s tariffs will be one-offs; he’s already engaged in tit-for-tat with trading partners. Chairman Powell’s comments also avoided any mention of recently weaker employment numbers – which could become a problem if growth slows further.

The Bank of England’s (BoE) 8-1 vote to hold rates was surprisingly emphatic. The UK economy doesn’t look as weak as it did – with the expected drop in employment (in reaction to the national insurance hike) not coming through. However, fiscal policy will remain tight, with the government favouring spending cuts to fund defence, rather than new borrowing. The BoE won’t react until after the spring budget. With hawkish fiscal and monetary policy, UK bond yields could fall.

Japan held rates steady last week in a dovish move – but bond yields counterintuitively rose. This bears closer inspection, as we know from last summer that Japan’s market dynamics can quickly become everyone’s problem.

The ECB is the only central bank not in “wait and see” mode, and we expect it to remain accommodative even after historic defence spending deals on the continent. This is mainly because none of the bonds for the fund raising have actually been issued or spent yet, leaving the economy in an awkward limbo. The financial market impacts of defence spending have already happened but the economic benefit will take a while.

Markets now believe China’s demand promise

Despite Chinese stocks falling into the end of last week, investors on the whole feel good about Beijing’s stimulus plans. The government unveiled a “special action plan” for boosting consumption, rather than industrial production, which has historically been the policy target. The shift since last year has made the Hang Seng index the best performer in 2025 – though the index was also boosted by the release of low-cost AI DeepSeek. Mainland Chinese stocks (less owned by international investors and more sensitive to the domestic economy) have been less impressive.

They are still up year-to-date, however, as investors and consumers have realised Beijing’s consumption support is genuine. That’s impressive, given the global trade context: China is the only country to be consistently piled with Trump tariffs, despite the US president threatening all trading partners. Tariffs pushed down Chinese growth expectations into the start of this year, but these have recently improved. We can see this in bond yields falling then recovering. The net result is that the world’s second-largest economy is in a strong position – just not a spectacular one.

While we are positive about Beijing’s demand-side stimulus, we have always said the government’s penchant for cracking down makes China a fundamentally risky place to invest. That perception created volatility last year, but volatility is much lower this year. This is partly about Beijing’s consistent policy, but also about inconsistent policy in the US. China has historically been risky because you do not know what the policies will be tomorrow – but at the moment that sentiment arguably applies more to the US.

We shouldn’t overstate this, as perceptions could easily change. But Chinese officials are going out of their way to emphasise the nation’s consistent focus on technological and economic progress. Beijing is currently saying all the right things – and investors currently believe them.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

24/03/2025

Team No Comments

Brooks Macdonald – The Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their discussions on Equity markets, current geopolitical affairs with Trump and the Bank of England hold on interest rates. Received – 21/03/2025.

What has happened

Yesterday saw investors circle-back on tariff worries, pulling equity indices lower after what had been a decent session the day before. The US S&P500 equity index edged down -0.22%, while the pan-European STOXX600 equity index underperformed, down -0.43%. Relatively speaking, the UK equity market led US and European markets on Thursday, with the MSCI UK equity index finishing almost flat on the day down just -0.05%, all in local currency price return terms.

Bank of England takes a relatively hawkish turn

With interest rates on hold at 4.5% as expected, yesterday’s surprise from the Bank of England instead came from the split in the votes of the Bank’s Monetary Policy Committee (MPC): of the 9 voting members, 8 voted for no change, with only 1 vote (MPC external member Swati Dhingra) for a 25 basis points cut. That vote split was more hawkish than the expected 7-2 hold-versus-cut split going into the meeting. Meanwhile the Bank said it continued to favour “a gradual and careful approach” to any further interest rate cuts, not least given “an intensification of geopolitical and trade policy uncertainty”.

Canada expected to hold snap election

News reports from Canada’s Globe&Mail have said that Prime Minister Mark Carney is expected to call a snap federal election, expected to take place late April. It appears Carney might be looking to take advantage of a bump in opinion polls for his ruling Liberal Party, following Carney replacing former leader Justin Trudeau. Rather than domestic issues, it is likely to be the ongoing tariff-spat between Canada and US that will dominate the minds of voters running into the election.

What does Brooks Macdonald think

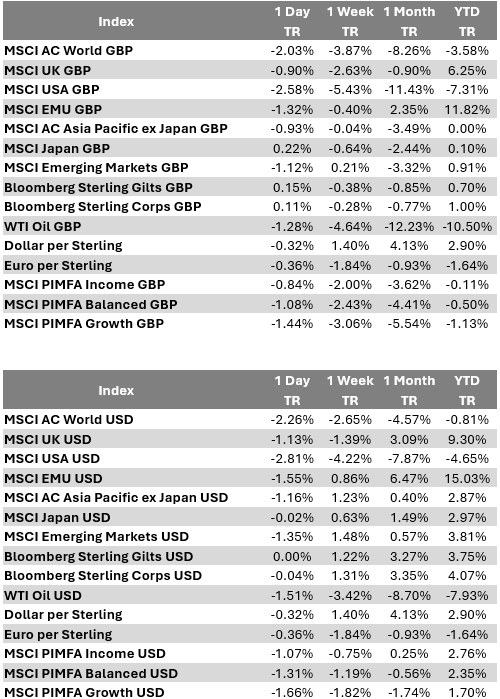
Investors are finishing the week thinking about tariffs again – it is now less than two weeks to go till US President Trump’s Wednesday 2 April “Liberation Day” reciprocal tariff announcement. This is when the US will announce reciprocal tariffs on trade with an as-yet-unknown number of countries around the world and at as-yet-unknown tariff rates. Investors crave certainty, but it seems for the next couple of weeks, that is going to be in short supply – it suggests markets may continue to be volatile for a while yet.

Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World GBP -0.19%2.52%-6.71%-2.91%
MSCI UK GBP -0.05%1.82%1.29%7.68%
MSCI USA GBP -0.19%2.51%-9.81%-6.96%
MSCI EMU GBP -1.17%1.96%1.91%12.81%
MSCI AC Asia Pacific ex Japan GBP -0.06%2.86%-2.17%1.10%
MSCI Japan GBP 0.81%2.74%-0.38%1.75%
MSCI Emerging Markets GBP -0.19%3.04%-1.45%2.87%
Bloomberg Sterling Gilts GBP -0.24%0.41%0.27%0.60%
Bloomberg Sterling Corps GBP -0.13%0.10%-0.35%0.60%
WTI Oil GBP 1.66%2.40%-8.18%-8.08%
Dollar per Sterling -0.02%0.17%2.44%3.54%
Euro per Sterling 0.22%0.25%-0.91%-1.20%
MSCI PIMFA Income GBP -0.13%1.32%-2.44%0.30%
MSCI PIMFA Balanced GBP -0.14%1.57%-3.10%0.04%
MSCI PIMFA Growth GBP -0.17%1.93%-4.09%-0.41%
Index 1 Day1 Week1 MonthYTD
 TRTRTRTR
MSCI AC World USD -0.22%2.70%-4.43%0.52%
MSCI UK USD -0.07%2.00%3.76%11.49%
MSCI USA USD -0.21%2.68%-7.61%-3.66%
MSCI EMU USD -1.19%2.14%4.40%16.80%
MSCI AC Asia Pacific ex Japan USD -0.09%3.03%0.21%4.68%
MSCI Japan USD 0.79%2.91%2.05%5.35%
MSCI Emerging Markets USD -0.21%3.22%0.96%6.51%
Bloomberg Sterling Gilts USD -0.20%0.63%2.91%4.20%
Bloomberg Sterling Corps USD -0.09%0.32%2.27%4.20%
WTI Oil USD 1.64%2.57%-5.94%-4.82%
Dollar per Sterling -0.02%0.17%2.44%3.54%
Euro per Sterling 0.22%0.25%-0.91%-1.20%
MSCI PIMFA Income USD -0.15%1.49%-0.06%3.85%
MSCI PIMFA Balanced USD -0.16%1.74%-0.73%3.58%
MSCI PIMFA Growth USD -0.19%2.10%-1.75%3.12%

Bloomberg as at 21/03/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

21st March 2025

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, an article from Brooks Macdonald providing a brief analysis of the key factors currently affecting global investment markets. Received this morning – 20/03/2025:

What has happened

Equity markets rebounded on Wednesday, with the UK FTSE100 equity index notching up its sixth day of gains in a row, its best run since May last year. But it wasn’t until European markets had gone home for the day that investors really found their mojo with US equity markets on a tear – the bulls were back in force following US Federal Reserve (Fed) Chair Powell signalling that the Fed still sees room to cut interest rates later this year, judging any increase in inflation due to tariffs as only “transitory” – the US S&P500 equity index had its best Fed-day since July last year, the US Dow Jones equity index had its best Fed-day in a year.

US recession risks are “not high”

Referring to external forecasts, Fed Chair Powell yesterday said “a number of them have raised their possibility of a recession somewhat, but still at relatively moderate levels. They were extremely low. If you go back two months, people were saying that the likelihood of recession was extremely low … so it has moved up, but it’s not high”. Powell said that “the economy is strong overall” and added that “labour conditions are solid”. Providing useful context around recession fears, Powell pushed back – “there’s always an unconditional possibility of a recession; it might be broadly in the range of one in four at any time”.

Bank of Japan

The Bank of Japan (BoJ) left interest rates unchanged at its latest meeting yesterday, as expected. Instead, BoJ Governor Ueda focused on uncertainty around US President Trumps’ tariff plans. Ueda noted the impact was “difficult to judge” and that “tariffs could directly affect the economy and inflation … [but] there might be factors we may not find out until much later”.

What does Brooks Macdonald think

“The good ship Transitory” (as Fed Chair Powell called it in August last year) sails again – yesterday’s use of the word “transitory” by Powell was deliberate and comes despite the chequered history of that word in recent years. With interest rates left unchanged as expected, Powell roundly dismissed any fears that trade tariffs might lead to sustained inflation pressures – it suggests that should any economic growth weakness emerge later this year (although Powell said the risk of a US recession was “not high”), the Fed will not hold back in cutting interest rates. For investors, maybe there is still a Fed “put” after all.

A table with numbers and text

AI-generated content may be incorrect.

Bloomberg as at 20/03/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd DipPFS

20th March 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 18/03/2025.

Why are U.S. equity markets declining?

We examine the impact of the Trump administration’s trade policies on the equity markets and businesses.

Last week saw dramatic escalation and then de-escalation in U.S. President Donald Trump’s global trade war.

After the imposition of 25% tariffs on steel and aluminium imports—measures that will severely hurt Canada’s metal production sector and mean higher metals prices for American manufacturers—Canada’s Ontario premier Doug Ford announced he would impose a 25% surcharge on electricity supplied by Canada to America’s northern states. The response? President Trump declared he would double the tariff on Canadian steel.

Both sides have since withdrawn. The 25% tariffs remain in place.

The European Union announced its retaliatory tariffs, which will come into effect in April should the U.S. import taxes remain in place. President Trump again signalled he would retaliate if the EU implemented these tariffs.

By April, there may be more tariffs on EU exports to the U.S. This will depend on U.S. investigations into the need for reciprocal tariffs to counter any trade restrictions that other countries are deemed to have put in place, including value added tax (VAT).

From ‘Trump bump’ to ‘Trump slump’

Trump Election Markets effect

Source: LSEG Datastream

There have been two distinct phases to the market action since last year’s U.S. election.

The first was a repeat of the ‘Trump bump’ experienced in his first term. This took place after the election result confirmed there would be a second Trump term. Investors reacted to the prospect of a Trump presidency, anticipating benefits such as reduced regulation and the possibility of tax cuts.

However, even during the last stages of the Trump bump, European equities had begun to pick up steam and following his inauguration, the Trump bump has become a Trump slump! European equities have broadly managed to continue rising despite a sharp sell-off for global equities, which is almost entirely driven by the U.S.

U.S. exceptionalism has been a remarkable trend over a long period. The U.S. began outperforming following the great financial crisis in 2007-2008. Several stars had aligned for this. The U.S. tech sector finally emerged from the shadow of the tech bubble. Meanwhile, Europe suffered from a debilitating debt crisis and saw a slowdown in China and other emerging markets, which had been strong markets for European exports for many years.

As the economy continued to digitise, America’s economy outperformed. It was aided by more favourable demographics, fortuitous natural resource wealth, a dynamic business environment, and capital inflows from other countries, which kept borrowing costs low despite constant budget deficits.

Global Trade effect from American markets

Source: LSEG Datastream

Many of the conditions that have allowed the U.S. to rise to the top of the pack are being challenged by the Trump administration’s unironic pledge to Make America Great Again. Could populism force the world’s biggest economic success story to give up its crown?

The odds still seem strong for America to remain exceptional.

Its geographic benefits are outstanding from a geopolitical and economic perspective because it’s easily defensible and accessible to trade, with incredible natural resource wealth. Europe, on the other hand, is fragmented, with a Russian aggressor on its doorstep.

The largest U.S. companies have remarkable monopoly power and an unrivalled position in the coming artificial intelligence revolution. There’s controversy about how highly their leadership position should be valued, but the fact they’re the leaders is beyond debate.

How are tariffs affecting business sentiment?

Trump government small business effect

Source: LSEG Datastream

There has been a meaningful sell-off in U.S. equities despite there being little evidence of economic weakness from companies and economic statistics. However, surveys hinted that change is afoot.

A couple of weeks ago, anecdotal comments within the purchasing managers indices (PMIs) indicated a more nervous business community.

Last week, this sentiment was reflected by the National Federation of Independent Businesses (NFIB), which had originally cheered the arrival of a new Republican administration. It still considers now a better time to expand its businesses than at most points during Joe Biden’s presidency, but it’s noticeably less ebullient about it now than just weeks ago.

That’s because the threat of tariffs is likely to mean higher costs, with the risk of disrupted supply chains and, for those who export, the possible imposition of retaliatory tariffs. For many companies, there’s no choice but to pass those additional costs on to clients.

In the long term, some companies have pledged to move manufacturing into the U.S. as President Trump wants. But building new plants for manufactured goods typically takes years, so there’s no quick fix to this threat if the tariff is going to remain until companies have genuinely shifted their production.

The potential impact of tariffs is difficult to quantify, especially as the specific targets, levels and duration of the measures remain uncertain, but we shouldn’t be too concerned by dramatic shifts in survey data. There have been instances of surveys suggesting very pessimistic economic outcomes only to rebound when respondents have a better idea of what the new business environment is going to be like. Brexit would be a good example of this.

The immediate impact of these tariffs will be far more material than the years of inaction over Brexit, but that doesn’t prevent people from overreacting in surveys.

Peak bearishness – prime buying opportunities?

Investor Anxiety Levels

Source: LSEG Datastream

The American Association of Individual Investors (AAII) business sentiment survey has been a terrific barometer of stock market overreaction in the past. It has now risen to levels that have been associated with some of the most timely ‘bottoms’ in the stock market over recent decades.

Peaks in bearishness, as per this measure, that were recorded in March 2003, March 2009 and September 2022, were all tremendous buying opportunities for the coming years. In each of those instances, the market was considerably more depressed than it is at the moment, so we probably can’t expect the dramatic gains they offered. But it does indicate that the tariff message has hit investors hard, which sets up the potential for a rebound.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

19/03/2025

Team No Comments

Brooks Macdonald – The Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their discussions on Equity markets and current geopolitical affairs with Trump and Putin. Received this morning 18/03/2025.

What has happened

Equity markets carried over Friday’s bounce for a second day yesterday. Encouragingly, there was a broadening-out across industry sectors – the US S&P500 equity index was up +0.64% but the equal-weighted version was up by more, rising +1.32%, while the pan-European STOXX600 equity index was up +0.79% on the day, all in local currency, price return terms. In commodity markets, Brent crude oil prices are currently up +1.15% this morning at US$71.89 per barrel on Middle East news that Israel has launched a series of airstrikes against Hamas targets in Gaza overnight, ending the two-month long ceasefire.

Geopolitics sees today’s date loaded with symbolism

Russia President Putin and US President Trump are set to hold telephone talks later today, aiming at ending the Russia-Ukraine conflict. Trump has held out hope that there is “a very good chance” for a deal, with the US still pressing Russia to agree to a 30-day ceasefire, while Russia appears to be holding out on a number of conditions to accompany any agreement. For context, today’s date is significant for Russia – loaded with symbolism, 18 March is the annual date that Russia celebrates its 2014 “reunification” with Crimea.

US retail sales data is just about-good-enough

US retail sales data yesterday was just-about-good-enough to assuage investors’ worries that Trump’s trade-tariffs might already be curbing economic activity. While the headline all-items print was a bit disappointing, excluding automobiles, gasoline, building materials and food services, a “control group” core retail sales sub-index was up +1.0% in February month-on-month. That was better than the consensus market forecast which had been looking for a rebound of +0.4% – it also brings the three-month annualised growth of this core retail “control group” to +3.8%.

What does Brooks Macdonald think

Hopes for a successful Russia-Ukraine peace-deal led to a fall in European natural gas prices on Monday, down more than -3% at one point intraday. That price action makes sense – if the war in Ukraine ends, it raises chances that Russia could come back into the western energy-supply mix and help fill European Union (EU) gas reserves which are currently only around 35% full. Falling energy prices could also help to lower broader inflation pressures, a possibility likely not lost on the minds of central bank officials this week as they think about where to set interest rates.

Bloomberg as at 18/03/2025. TR denotes Net Total Return.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Alex Clare

18/03/2025

Team No Comments

Tatton Monday Digest – Just Another Growth Scare, or More?

Please see below, this weeks Monday Digest from Tatton Investment Management – Received 17/03/2025

Just another growth scare, or more?
The stock market sell-off has resumed and US equities are officially in correction (-10%). US inflation was lower than expected, which usually pushes down bond yields, but the opposite happened – demonstrating that capital is flowing out of the US. The rapid sentiment shift from a month ago suggests we could see a bounce – but ‘buy the dip’ will only prevail if investors think the US outlook hasn’t fundamentally changed. We must stay level-headed. Companies themselves aren’t yet signalling earnings deterioration, even if macroeconomists are.

European stocks sold off too, having previously been unscathed. It’s a recognition that a slowing US and sharp Trump tariffs hurt everyone – regardless of the growth boost from defence spending. The previous European rally still has room to run (the dollar is still historically expensive) but there may not be as much room for fiscal expansion outside Germany as hoped. The UK is a case in point: Downing Street is signalling spending cuts to fund defence, rather than new borrowing. We also shouldn’t be surprised if the Spring statement includes extra tax rises. 

Markets are still focussed on the US and Trump, not just his tariffs but his spending cuts – which are now clearly impacting Americans’ confidence. We argued before that Trump is likely respond with stimulative policies, and progress is being made on his “big, beautiful bill” of tax cuts. But things could get worse before they get better, if Trump picks an unnecessary fight with the Federal Reserve. Still, the US fundamentals are still strong, even if the sequence of policies has damaged confidence. 

At the bottom-up level, analysts think profits will be strong, and these should be helped by tax cuts and deregulation. In these challenging times, investors should focus on the fundamentals. This is especially so for investors buying in now at a discount. To quote Warren Buffett on stocks and bonds: I like buying quality merchandise when it is marked down.  

Trump’s best laid tariff plans
With Trump’s tariffs now in place, the media spotlight has focussed on a paper from White House economic adviser Steven Miran, which explains their rationale: “A User’s Guide to Restructuring the Global Trading System”.

Miran’s central point is that the dollar’s reserve status makes it unnaturally strong, rendering US exports uncompetitive and destroying American industry. He thinks tariff threats can get concessions from other nations because of this. But Miran also argues that tariffs wouldn’t cost consumers because they make the dollar stronger (as money goes into the US to build production) and neutralise costs. That’s the first stage of the plan, but the endgame (once short-term cost impacts have worn off) is a “Mar-a-Lago Accord” to artificially weaken the dollar and address what Miran thinks is the underlying cause of the US trade deficit.

The plan has so far tripped at the first hurdle: the dollar is weaker, not stronger, because exchange rates are more about capital markets (who are scared of Trump’s restrictive policies) than trade. Miran assumes American economic and currency supremacy is fixed – but the US’ economic strength comes from the very openness that his administration is now trying to close. This isn’t just a Trump phenomenon; global central banks have been diversifying away from the dollar since Biden froze Russia out of the dollar payments system.

Miran’s theory is debatable, but the biggest problem is its implementation. The paper explicitly says that a tariff plan needs transparency and consistency, but Trump’s will-he-won’t-he approach is the exact opposite. Tariffs are just one part of Trump’s agenda, and the other parts (deportations, forcing Europe to build its military, cutting off China) plausibly work against the tariff plan. Unpredictability is a feature of Trump’s “art of the deal”, not a bug. But complicated trade plans and short-term manoeuvring do not mix.

Will private equity problems stay private?
It hasn’t got much attention amid the current US market sell-off, but the big private equity (PE) firms are doing very badly. PE has always been correlated with small and mid-cap stocks – since PE firms usually buy up those size companies and sell them on years later. US growth expectations (and hence earnings expectations) have deteriorated, so you would expect PE to have a harder time. But the interesting thing is that PE firms’ price-to-earnings valuations have fallen sharply – by a similar margin to the technology mega-caps. This suggests that markets’ fears about US growth are even more pronounced in PE than listed equity.

This seems to be about liquidity troubles, not just growth fears. Monetary policy is still historically tight, and PE’s assets under management contracted in 2024 for the first time since 2005. PE managers are now branching out to retail-oriented sources like ourselves to offer their products, because the traditional PE money (wealthy families and pension funds) is harder to come by. The liquidity squeeze isn’t huge, but it has been enough to stifle PE activity – and it is now hurting the share prices of the biggest firms. 

The important thing to watch will be whether these problems spread beyond the PE sector. PE’s growth over two decades has distorted stock markets by buying up small and mid-cap companies at high valuations – and the process has been largely debt-fuelled. The PE expansion has been able to continue for so long because the money has kept flowing in – but that is no longer true. The contraction could just be a blip, but we have been concerned about the risks PE poses to the broader system for a while. The fall in PE firms’ shares isn’t an alarm bell, but it’s a warning. We hope private equity’s problems stay private.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

17th March 2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.

What has happened

Markets had a better day yesterday despite ongoing trade tariff worries, helped by a lower US consumer inflation print. The US S&P500 equity index rose +0.49%, the ‘Magnificent 7’ megacap tech group bounced +2.27% to their best day in 6 weeks, and the pan-European STOXX600 equity index gained +0.81%, all in local currency price-return terms. The VIX ‘fear’ index (a US S&P500 equity-options-derived volatility gauge) registered its biggest one-day drop so far this year.

Weakest US core inflation in almost 4 years

The latest US Consumer Price Index (CPI) monthly report for February landed yesterday, buoying risk assets. Both headline (all-items) and core (excluding energy and food) numbers surprised on the downside. The annual headline CPI rate of +2.8% (below +2.9% expected, and versus +3.0% in January) was the weakest since November, while the core CPI annual rate of +3.1% (below +3.2% expected, and versus +3.3% in January) was the weakest print in almost 4 years – since April 2021.

Bank of Canada cuts interest rates

The Bank of Canada (BoC) cut interest rates by 25 basis points yesterday, taking rates down to 2.75%. The move was in line with market expectations and brings the tally of cumulative cuts to 225bps in less than a year since the first BoC cut back in June 2024, when rates were at 5%. Referencing the latest US-Canada trade tariff uncertainty, the BoC said that “heightened trade tensions and tariffs imposed by the United States will likely slow the pace of economic activity and increase inflationary pressures in Canada”.

What does Brooks Macdonald think

There is a tug-of-war around the outlook for the US going on in markets currently. On the one hand, the latest economic data all suggest a US economy which is still far from stagflation: S&P’s US Manufacturing PMI (Purchasing Managers’ Index) survey saw the strongest reading in almost 3 years, since June 2022; the JOLTS’ (Job Openings and Labour Turnover Survey) US worker voluntary ‘job-quits’ were the highest since July 2024; and US annual core CPI inflation was the weakest in almost 4 years, since April 2021. Against this, US president Trump’s continued trade tariff headlines are clearly sapping investor confidence and causing sizeable market jitters – the risk is that the longer this goes on, the greater the likelihood that it could start to show up in economic activity data. For now, predictions of an imminent US recession are, thankfully, still wide of the mark.

A table with numbers and text

AI-generated content may be incorrect.
A table of currency exchange rate

AI-generated content may be incorrect.

Please check in again with us soon for further relevant content and market news.

Chloe

13/03/2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 11/03/2025.

On Tuesday last week, the U.S. imposed 25% tariffs on most imports from Mexico and Canada. The exceptions to this were potash (a fertiliser used in farming) from both countries and energy products from Canada, which would be tariffed at a reduced rate of 10%.

Canada, however, has been quick to react with retaliatory tariffs, including an export tariff on the electricity it provides to northern U.S. states, which is designed to impose a real cost on U.S. consumers. Over the weekend, former governor of the Bank of Canada Mark Carney successfully contested the leadership of the Liberal party and will soon become prime minister. 

Referring to the trade war, Carney said “We didn’t ask for this fight, but Canadians are always ready when someone else drops the gloves.”

Earlier today, in response to those retaliatory measures, U.S. President Donald Trump announced that tariffs on Canadian aluminium and steel would be increased to 50% on 12 March.

By last Wednesday, it seemed there would need to be an exemption for the car industry, because many products cross the border several times during the manufacturing process. Car makers argued that subjecting their cross-border supply chain activity to tariffs that European and Asian carmakers don’t suffer from puts America at a disadvantage. It’s unclear why this took until Wednesday to recognise because it had been widely discussed during the presidential campaign.

An exemption was granted on Thursday for goods traded under the United States-Mexico-Canada Agreement (USMCA) – the agreement negotiated by President Trump’s first administration.

Investors are bracing for the impact of President Trump’s erratic trade policy. This U-turn on Mexican and Canadian tariffs follows an eleventh-hour decision last month to defer their implementation until 4 March. The president lauded the progress made in the fight against fentanyl imports since the tariffs were first threatened. However, he promised there won’t be another deferral in April, when reciprocal tariffs on Mexico and Canada are due to come into effect following a review.

The seemingly endless stream of deferrals and modifications to the Canadian and Mexican tariffs follow February’s attempt to end the tariff exemption on small packages (which had to be temporarily halted due to logistical challenges related to enforcement).

It’s surprising that these challenges hadn’t been foreseen. However, the Trump administration has seemed to be in a state of disillusionment over the effect of tariffs and trade. President Trump believes companies in another country selling goods to Americans are effectively ripping America off, and that producers pay tariffs; overwhelmingly, it’s consumers who pay them. This is not a widely held opinion.

The art of the deal war

Perhaps what’s most surprising about his approach is his apparent desire to go after all other countries at once (assuming he follows through with promised reciprocal tariffs in April).

Analysts acknowledged ahead of the election that the U.S. would be in a strong position to negotiate with other countries under the threat of tariffs because trade doesn’t actually make up a particularly large share of the U.S. economy. However, it seems this position of strength is being squandered.

Other countries may trade more, but if the U.S. imposes tariffs on all trading partners simultaneously, as President Trump seems to be suggesting, and if those trading partners impose counteracting tariffs, this raises the amount of U.S. trade subject to tariffs relative to peers, who’ll be trading largely tariff free between each other.

Thousands of years of military strategy, dating back to Sun Tzu’s text ‘The Art of War’, contains variations of the idea that the best path to success is to ‘divide and conquer’. Whilst not a warrior, the Trump administration seems more willing to unite its rivals. Perhaps it’s telling that in his negotiating guide ‘The Art of the Deal’, Trump never really addresses the power dynamics that come from collective or individual negotiations (despite this being a tried and trusted path to negotiating success).

The effects seem telling. Business surveys have shown a marked deterioration in confidence. In some cases, this has been reflected in less activity. In others, the shoe seems likely to drop in coming months. Companies struggle to explain how they’ll react to tariffs because they don’t know what these tariffs will be.

It seems reasonable to believe that a company might be more willing to invest in a new U.S. plant than a non-U.S. plant given the threat of tariffs. However, the decision to invest at all might be in question if you don’t know what tariff you’ll pay on imported components, or how much of a tariff advantage there is to invest in the U.S., relative to the much higher labour costs.

The only certainty is uncertainty

Some business surveys include anecdotal comments from submitters. Almost all of them are negative at the moment, and most of them cite tariffs as the reason for anxiety. An example that stands out from the Institute for Supply Management (ISM) manufacturing survey says: “Management now has us running scenarios to project tariff impacts to our business. They want numbers in 24 hours on variables that equate to a wild guess. Interesting times we live in.” This shows how difficult it is for companies to make decisions when the taxation of imports changes almost by the day.

A number of retailers reported earnings last week, and so the topic of tariffs came up with management. Very few companies have anything significant to say in terms of their mitigation strategies. Commentary tends to make trite references to leveraging global buying power and focusing on value for customers. Very few know exactly what the impact will be or can do much about it in the short term.

There has been some evidence of a slowing U.S. economy. The Citigroup Economic Surprise Index edged below zero, suggesting the economy was performing worse than expected.

Perhaps most extraordinarily, the Federal Reserve of Atlanta’s current estimate of gross domestic product (‘nowcast’), known as GDPnow, fell sharply at the beginning of last week. The biggest detractor came from the sharp increase in imports. Imports reduce GDP while exports increase it, but as businesses anticipate an increase in tariffs, they try and buy ahead of the tax increases. That effect should reverse in coming months, notwithstanding the constantly moving tariff environment.

U.S. consumer confidence drops

However, beyond this, there also appears to have been a more pronounced drop in consumption. This seems likely to reflect an increase in economic caution.

Reduced retail sales and weaker confidence surveys have been the clearest indications that the economy is turning. The U.S. labour market broadly held firm. The non-farm payroll report showed employment creation was weaker than expected and the unemployment rate rose unexpectedly. However, some of that impact is due to a higher-than-average number of workers being unable to work due to bad weather.

Government employment will receive lots of scrutiny as the impact of the Department of Government Efficiency builds. So far, federal government employment was only down by 10,000 jobs in February, but next month will be a better test.

There was some reassuring news on inflation, with lower-than-expected wage growth. Given the weak economic data momentum recently, this firmed up bond markets’ expectations of three rate cuts from June this year.

Forget MAGA and get MEGA

Whilst President Trump’s activities may be dampening economic activity in the U.S., they seem to be accelerating it in Europe.

An acrimonious meeting between President Trump and Ukrainian President Volodymyr Zelenskyy saw the U.S. halting aid and ending intelligence sharing with Ukraine. The move was a devastating blow to Ukrainians and a boost to Russia. It had a galvanising effect on Europeans.

On Tuesday evening, German leaders announced their intention to reform the constitutional debt brake to essentially allow for open-ended borrowing for defence. It would also allow for the creation of a €500bn special purpose vehicle for infrastructure investment. 

The announcement came on the same day that European Commission President Ursula von der Leyen proposed her ‘ReArm Europe’ plan. The plan includes providing loans to member states to buy military equipment and, more importantly, a commitment to trigger the European Union (EU)’s national escape clause. This would prevent military expenditure from being counted in the bloc’s punishment mechanism for countries breaching EU spending limits. 

So, while Trump is trying to Make America Great Again, it’s also time to Make Europe’s Guns Again. Hardly a reassuring thought but one that has boosted the equity market and pushed down European bond prices.

There are immense challenges around increasing defence spending at a time when European countries have very stretched public finances. France’s government fell last year after struggling to pass tax increases to try and restore its fiscal poise.

Aerospace and defence companies can be challenging investments as they are inherently unpredictable, have complicated accounting, and rely on government orders. Following the recent rally, European defence stock valuations appear generous and are vulnerable to headline risk, so we’re not inclined to chase this rally.

However, stepping back, increased European defence and infrastructure spending may have longer-term benefits for European indices beyond the defence sector, so we’ve raised our allocation to European equities.

We also cut our gold weighting slightly, remaining overweight. The conditions supporting gold remain broadly in place. It could be sensitive to a further rise in bond yields, but recently, gold has been relatively resilient in the face of yield movements. Instead, it seems to be driven more by being bought by central banks seeking to reduce their dependence on U.S. dollars.

There’s little indication of that trend changing, but in recognition of the extremely strong performance from gold, we thought it was prudent to take some profits.

What’s coming in the week ahead

This week, the economic landscape will be filled with key events that will likely shape market expectations and investor sentiment.

We’ll see the release of several significant economic indicators, including China’s inflation rate, Germany’s balance of trade, and the U.S. Job Openings and Labor Turnover Survey, inflation rate, and producer price index. These data points will provide valuable insights into the current state of the global economy and will likely influence monetary policy decisions and market trends.

The Bank of Canada’s interest rate decision and the UK’s GDP growth rate will also be closely watched. 

In terms of corporate earnings, this week will see reports from several major companies, including Oracle, Ferguson, Adobe and Inditex. Investors will be watching these reports closely for signs of growth and guidance – although for some companies, the tariff confusion will complicate this.

If recent weeks are anything to go by, scheduled releases from companies and statisticians will be overshadowed by the latest erratic action from President Trump. 

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

12/03/2025

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, an article from Brooks Macdonald providing a brief analysis of the key factors currently affecting global investment markets. Received this morning – 11/03/2025:

What has happened

Continued uncertainty in markets around US president Trump’s global trade tariff plans came home to roost on Monday. With fears that tariffs might curb economic growth yet stoke inflation pressures, equity share prices dropped, and government bond prices rose. However, rather shaping up as blanket risk-off move, there was some rotation into the more defensive parts of the market in evidence: global equity defensive sectors including Healthcare outperformed the wider market on the day, beating Technology stocks.  In fixed-income markets, credit spreads saw a noticeable widening, with US high-yield spreads (versus US government bonds) posting their widest levels in six months.

US megacap technology stocks lead the day’s losses

The US megacap technology ‘Magnificent Seven’ group (made up of Alphabet, Amazon, Apple, Meta Platforms, Microsoft, NVIDIA and Tesla) were among the biggest falls on Monday. Falling -5.41%, the group fell into bear market territory, defined as a fall of -20% or more versus the previous peak in December, now down -21.75% in dollar price return terms. More broadly, however, markets have seen some rotation into defensive sectors in recent weeks – indeed, so far this year in sterling total return terms across MSCI World (developed markets) sectors, while Technology is down -13.15%, Healthcare is up +4.02%.

A setback for German fiscal plans

Germany’s latest plans for releasing the country’s fiscal ‘debt brake’ in order to allow for infrastructure and defence spending got a setback on Monday. The Green Party yesterday said they would not support amending the constitutional debt brake – that matters as given the share of the various parties’ seats in the current German parliament, the Green’s votes are needed to secure the two-thirds vote majority required to overturn the rule. Rather than a hard ‘no’ however, this appears more a negotiating tactic, as the Green Party left the door open to further talks and added that they would introduce their own legislation, expected to ensure that any spending also includes a share for climate change projects.

What does Brooks Macdonald think

Megacap technology stocks have played a big part of the broader US and global equity market rally in recent years, but as a result it has led to some uncomfortable concentration risks with equity indices dominated by just a few tech giants. We have been mindful of this for some time – at the beginning of last year our asset allocation committee added to US small and mid-cap stocks rather than increase our allocation to larger capitalised stocks and megacap tech names in particular. While Technology is one of our two key global equity themes (alongside Healthcare), given our preference for diversification we are underweight the ‘Magnificent Seven’ group of stocks relative to our PIMFA benchmarks across all five of our client-risk band models.

A table with numbers and symbols

AI-generated content may be incorrect.

Bloomberg as at 11/03/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd DipPFS

11th March 2025

Team No Comments

Tatton Monday Digest – The Return of Regional Divergence

Please see below, this weeks Monday Digest from Tatton Investment Management – Received 10/03/2025

US stocks fell once again last week, while European and Chinese shares did well. The background to this was a spike in European bond yields and more political uncertainty from the Trump administration.  

European stocks jumped on Germany’s larger-than-expected defence spending package, because European manufacturers have struggled for years and have spare capacity. Firing up the factories will boost growth, even if the goods don’t get used. The real hope, though, is developing economically productive tech and ensuring genuine European cooperation (discussed below). The fiscal boost sent European bond yields sharply higher, which may be uncomfortable for fixed-income investors, but this is ultimately more a growth story than a debt scare. 

Elsewhere, Trump imposed tariffs, then took them off again. The administration’s tariff rationale is that they reduce US demand for imports and draw in capital to build US based factories – boosting the dollar and neutralising the impact on consumers. But in reality, the dollar has weakened, because of the impact on market sentiment (and hence capital outflows). The only way to reduce the US trade deficit (Trump’s stated aim) in the short-term is to reduce US demand, but strong demand is what makes the US economy strong. More generally, the White House’s tariff plan requires consistency and forward-planning – the opposite of Trump’s volatile policymaking. 

Trump has always been politically volatile, but his economic policies used to be reliably market-friendly, which no longer seems to be the case. This makes US stocks more risky, but it doesn’t mean you should put all your money in European defence. A few months ago, the story was about US outperformance – and that could come back if Trump decides to make good on his tax cut and deregulation promises.  

In an uncertain and fragmented world, diversification is your friend. That has always been central to our long-term investment strategy, and it’s important now more than ever. For want of a better phrase, keep calm and carry on.  

February asset returns review 

February saw a notable change of fortunes for investors. Global stocks dropped 1.9% in sterling terms, while bonds gained 1.2%. The equity fall was largely about US underperformance, while British, European and Chinese stocks meaningfully gained. Last year, investors were excited about Trump’s tax cut and deregulation agenda. Those haven’t come, but tariff threats and disruption have. US stocks fell 2.6% in response, and the dollar sank. Gold prices rose on a mixture of geopolitical fears and supply imbalances. 

Despite political fears, European stocks gained 2.3% last month – concentrated on defence stocks expected to benefit from Europe’s rearmament. European bullishness was not just about defence, but second round growth impacts and capital flows from US markets. UK stocks also rose 2% in February, and are well-placed to benefit from European defence spending. Impressively, UK equity has now outperformed the US on a 12-month basis.  

China was February’s best performing region, up 9.9% in sterling terms. Growth is improving, thanks to government stimulus – and the release of low-cost AI model DeepSeek suggested their may be more to come. Chinese stocks are, remarkably, now the best performers on a 12-month basis, but investors should be wary of overexposure. Chinese assets are still down on a five-year basis, and Beijing’s fondness for intervention makes them fundamentally risky.  

Global bonds performed well in aggregate, with the biggest contribution coming from a fall in long-term US yields, while UK and European yields remained stable. But we should note that the beginning of March has seen more bond volatility.  

Commodity prices fell 2.6% in February, due to tariff risks and lower oil prices. Oil’s fall is not just about trade wars but Trump’s plan to boost US oil production. By contrast, industrial metals like copper performed relatively well, due to Chinese growth expectations.  


Can guns generate growth for Europe? 

Europe’s historic defence spending agreements are expected to boost the continent’s growth. German Chancellor-in-waiting Friedrich Merz announced a plan to exempt military spending from the country’s constitutional debt limit last week, along with a €500bn infrastructure fund. This was followed by 26 EU countries (excluding Russian-allied Hungary) agreeing the European Commission’s €800bn plan.  

Defence companies will see the biggest upside – showcased by Rheinmetall shares nearly doubling year-to-date – but the fiscal spree is forecasted to boost the economy overall (by 0.6 percentage points per year, according to the Kiel institute). That’s why broad European stocks have outperformed the US this year. 

Growth benefits can only come if the defence spending stays in Europe – rather than just buying American equipment. That’s true for both short-term revenues and any long-term gains from technological developments, but the rise in US defence stocks suggests investors aren’t fully convinced that will happen. Nonetheless, we suspect European leaders will be desperate to spend the money on domestic industries.  

The UK has an established defence industry so is well-placed to benefit – but it clearly doesn’t have the same production capacity as the US. Defence spending could therefore be inflationary, as rapidly increasing demand for limited supply is a recipe for price rises. This could lead to a tighter European Central Bank – potentially undermining the growth upside. Politically, though, the ECB will not want to undermine the war effort, so we should expect some leeway. 

The real long-term benefit for Europe could be closer cooperation. The EU’s lack of common fiscal policy has long been a barrier for the economy. But once nations agree on joint defence funds, agreeing on other spending might get easier. Germany’s infrastructure fund is a case in point. This is a unifying event for a continent that has sorely lacked unity. We hope that spirit can continue.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

10th March 2025