Team No Comments

Tatton Investment Management: Tuesday Digest

Please see below, an article from Tatton Investment Management, providing a brief analysis of the key factors currently affecting global investment markets. Received today – 06/05/2025

Markets cheer US policy stabilisation
Last week was a good one for markets, despite a negative US Q1 GDP and mixed Mega Tech earnings reports. The GDP print caused a selloff in early Wednesday trading, but strong earnings from Meta and Microsoft precipitated a recovery on the day. Apple and Amazon’s earnings were weaker, but all projected solid capex plans. 

Tuesday saw a step back. Trump was helpful in suggesting that the US would lower tariffs on China eventually and that talks were imminent; and services data showed more positivity than expected. However, Trump’s Truth Social Post promising 100% tariffs on foreign films caused consternation, pulling down the share prices of Netflix and other media providers.

The announcement appears to have been the start of new policy thought rather than the opening of a thought-out strategy and may well be heavily amended. Nevertheless, it is the first time that services have been included in tariffs, something which the US had previously sought to exclude. Most in the US media industry would hope this will go away but the “100%” start makes a quick disappearance difficult. 

Encouragingly, Tuesday’s decline was small and implied market volatility remained around Friday’s level. Overall, implied volatility has dropped in the last few weeks, thanks to more conciliatory tones from US treasury secretary Scott Bessent – markets’ favourite member of Trump’s cabinet. His prominence since the US bond selloff last month has eased fears that the less market-friendly elements of the Trump administration rule the roost. Given Trump’s negative approval ratings, Bessent’s prominence will hopefully continue. 

The fact it only took a couple weeks of Trump quiet to calm markets suggest that investors see global growth as fundamentally strong and the president as fundamentally pro-growth. Whether that stability can continue – once policy disruption filters through to the economic data – remains to be seen.
 
The contraction in Q1 US GDP was down to increased imports ahead of tariffs (imports are subtracted from domestic sales). Counterintuitively, that might mean higher growth when imports fall later on, even though it signals weaker demand. As such, it’s more important to watch employment data – like the surprisingly strong April jobs report. Other jobs data has been mixed, suggesting companies are neither hiring nor firing. The Federal Reserve will focus on that data, and markets expect more interest rate cuts only by the year end – starting in July.
 
Longer-term rate projections have actually moved up – suggesting stronger growth 18-24 months from now. That would require more policy stability, of which there were some signs last week: US-India talks, Ukraine mineral deal, Germany’s coalition agreement. It also requires more dovish central banks, which is probably a safer bet, with the Bank of England set to cut rates next week.

April 2025 asset returns review
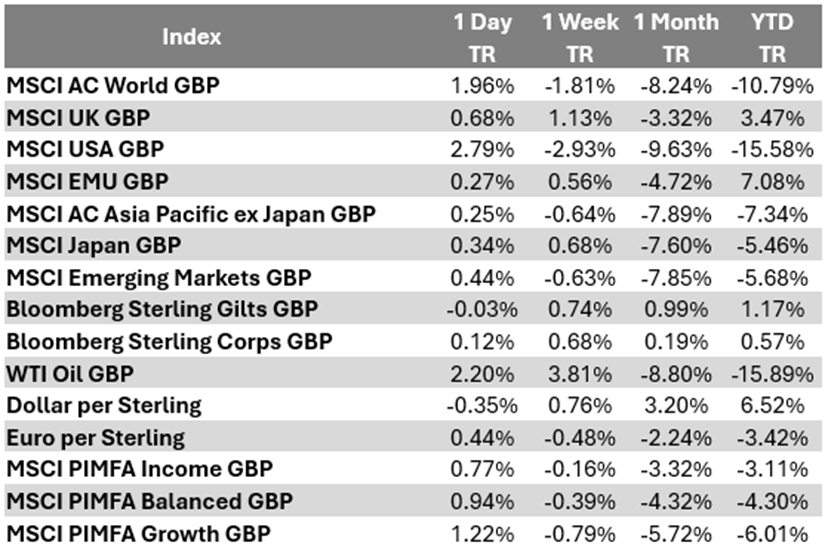
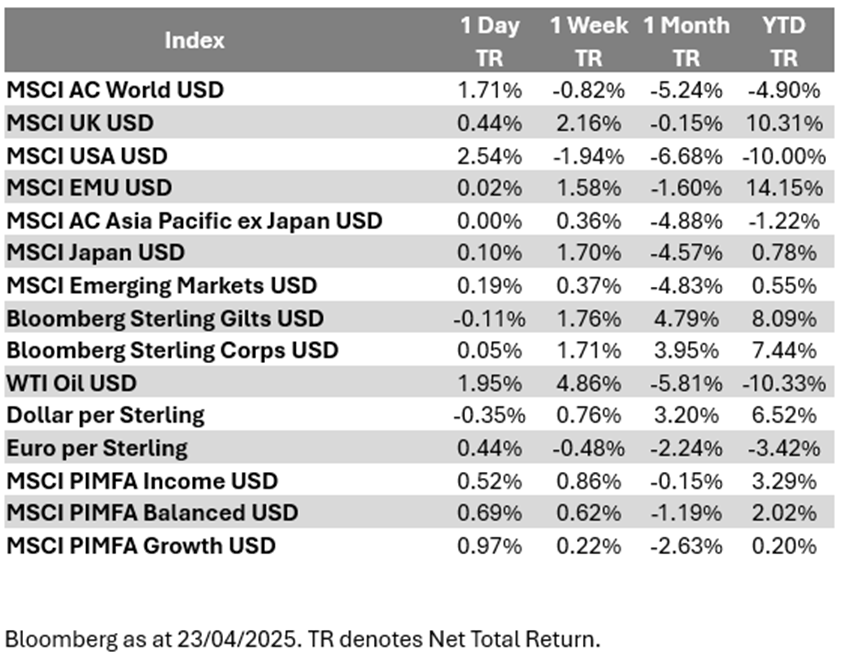
April was one of the most turbulent months for markets since the 2008 global financial crisis. Most stock markets are down at the end of it in sterling terms, but the slight rise in bond prices cushions some of the portfolio losses. 

Trump’s “Liberation Day” tariffs started the equity selloff, and losses mounted once Europe and China retaliated. Volatility eventually spread to US government bonds, due to highly leveraged investors (pension funds) needing to sell to meet margin calls. After Trump backed down, bond markets calmed, liquidity returned and hence a “buy the dip” mentality took hold. Even so, US stocks are the worst performers year-to-date in sterling terms, down 10.9%.

That is exacerbated by the falling dollar. Higher US yields – and a European interest rate cut – would normally push up the US currency, but investors are questioning how safe a haven the dollar is. European stocks are benefitting from this rotation – and were one of the few positive performers in April. The UK declined slightly by comparison, but is still up 5.4% year-to-date. This is partly down to looser monetary policy and partly because markets think Trump will cut trade deals with Britain and Europe.

China’s tariff prospects are worse, after a tit-for-tat escalation that has left sky high tariffs in either direction, making Chinese stocks April’s worst performer, even if they are still up for the year. Investors like Beijing’s domestic stimulus plan, but do not like it playing hard ball on trade. Markets still expect lower US-China tariffs than currently in place, but that requires thawing of relations.

April ended with US GDP release showing the economy contracted in Q1. That was down to America’s import rush (imports are subtracted from domestic production) ahead of tariff imposition, but the worst part is that it signalled both weaker growth and higher inflation. Hopefully, these clear impacts rein in Trump’s wilder policies.
 
Emerging markets caught in trade war crossfire
Last month’s International Monetary Fund (IMF) and World Bank Spring Meetings gave interesting insights into emerging market prospects during Trump’s trade wars. EMs are usually export led and therefore sell more to the US than they buy – which is why many were hit with high “reciprocal” tariffs.

This has caused a sharp pick up in EMs’ corporate credit spreads (the difference between US bond yields and EM corporate yields). A falling dollar would normally help reduce the debt burden, but this year’s decline in the dollar has been counteracted by credit spreads.
 
EMs do come into this difficult period in better financial shape, though. While credit spreads have increased, underlying credit ratings are higher than crises past. The IMF’s long-term support has had a big role in this, not only agreeing loans but working on financial stability – which is why many EM central banks have scope to cut interest rates. These improvements are why many EM investors haven’t abandoned EM assets altogether – as you might expect in a ‘risk off’ phase – but are instead being selective, according to JPMorgan’s survey of EM investors.

Unfortunately, IMF support for EMs is probably one of the reasons Trump considers such trade bodies anti-American. The Bretton Woods institutions cannot exist without US support – not only due to US funding but because the “Washington consensus” means nothing without Washington’s consent. One only need look at the World Trade Organisation (WTO), which has lacked a full appellate board since Trump’s first term and is effectively toothless. EMs would struggle if Trump gutted the IMF, but thankfully US treasury secretary Scott Bessent has suggested reform rather than destruction.
 
Unfortunately for EMs, we don’t know if Bessent’s reformist trade approach will win out in Trump’s cabinet. But they are at least better prepared for this turbulence than in the past.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.


Marcus Blenkinsop

6th May 2025  
Team No Comments

EPIC Investment Partners: The Daily Update

Please see the below article from EPIC Investment Partners, focused on the prolonged contraction of US manufacturing. Received today – 02/05/2025

US manufacturing is caught in a protracted slump, with the ISM Manufacturing PMI stuck below 50 in 28 of the past 30 months. From November 2022 to December 2024, it didn’t register a single expansionary reading – a 26-month contraction streak, the longest on record. Hopes of a turnaround were dashed in March when the index slipped below 50 once more with April’s reading declining to 48.7. 

Manufacturing accounts for around 10% of GDP, but it often signals broader shifts in the economic cycle. A PMI below 50 means more firms report deteriorating conditions than improving ones. The length of this downturn implies more than a passing slowdown; it suggests demand is weak, in part due to the uncompetitive nature of US manufacturing, which in turn is heavily influenced by an overvalued dollar. A stronger dollar makes US goods more expensive abroad and imported goods cheaper at home, undercutting domestic producers. Orders are shrinking, production is slowing, and firms are reporting margin pressure as costs rise. 

Headline GDP growth has muddled through, but the detail paints a more fragile picture. Real GDP fell 0.3% in Q1 2025, while real final sales – a better gauge of demand – dropped by 2.5%. These figures mirror what manufacturers are experiencing. The ISM’s Production Index fell to 44.0 in April, and export orders collapsed to 43.1 – the weakest in over a year. 

Inventories are also rising, but not for the right reasons. Businesses have stockpiled goods ahead of new tariffs, only to find demand lacking. The resulting overhang threatens further production cuts. ISM officials have described the build-up as precautionary and temporary, yet with new orders weak, the adjustment could be painful. 

Tariffs are amplifying the strain. Companies report halted Chinese shipments and cancelled client orders due to unpredictable import costs. In some sectors, tariffs of over 100% have rendered products uncompetitive. The ISM Prices Index jumped to 69.8 in April, the highest since mid-2022, reflecting rising costs for materials like steel and aluminium. Yet soft demand makes it difficult for firms to raise prices, squeezing margins. 

The employment picture is also deteriorating. April’s factory employment index ticked up slightly but remains in contraction. Firms are laying off staff or halting recruitment altogether, in sharp contrast to the relative strength seen in the services sector. That divergence is increasingly unsustainable. 

Unlike past recessions, this isn’t a collapse but a slow erosion. PMI readings in the mid-to-high 40s point to steady, grinding contraction. The comparison is more with the industrial slowdowns of the 1990s or 2015–16 than the crash of 2008. But even without a formal recession, the risks are mounting. 

Markets now await today’s payrolls report, which could prove pivotal. The Federal Reserve faces a complex balancing act: tariffs are adding temporary upward pressure to inflation, while broader growth indicators turn soft. Rate cuts are unlikely without clear labour market deterioration, particularly a rising unemployment rate. Yet if the Fed delays too long, it risks keeping rates too high during a slowdown already well underway. For investors, the message from the factory floor is becoming harder to dismiss: the manufacturing slump is no longer a warning sign — it is the story — and one unlikely to improve unless the dollar falls sharply, the Fed cuts rates meaningfully, or both.

The figures outlined in this report paint a bleak picture for US manufacturing. The dollar’s role as the global reserve currency props up its value, making imports to the US cheaper and exports to the rest of the world more expensive. This reduces the competitiveness of US exports which dampens overseas demand for their products.

Trump’s tariff policies are also starting to bite as import duties begin to be paid on raw materials. This is likely to be passed on to consumers in price rises, but already weak demand for American goods makes this difficult. American manufacturing businesses are seeing their margins reduced.

Trump’s take on trade deficits, that they equal opposing tariffs, is a misunderstanding of sophisticated global supply chains that have been built up over decades. US manufacturing does not enjoy a comparative advantage over exporting nations like China and much of South East Asia.

Unless we see Trump row back on these policies, or a significant depreciation of the dollar, then manufacturing in America is likely to remain in contraction.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

2nd May 2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.

What has happened

May has got off to a good start for markets. Yesterday saw key equity indices extend their run of back-to-back daily gains, in part down to strong US megacap tech earnings from Microsoft and Meta the day before. While the latest tech results overnight from Amazon and Apple were a bit more mixed, this morning the broader risk-on mood has had a shot in the arm after China said it is evaluating trade talks with the US, with Asian equity markets reacting positively. Finally, in focus later today will be US ‘non-farm payrolls’ jobs data for April where markets are looking for an unchanged +4.2% unemployment rate.

Possible thawing in China-US trade tensions

Earlier today, China’s Commerce Ministry said in a statement that it had noted that “the US has recently sent messages to China through relevant parties, hoping to start talks with China” and that “China is currently evaluating this”. In terms of possible next steps, and as a condition to negotiations, the statement asked to the US to “show its sincerity and be prepared to correct its wrong practices” by scrapping the current reciprocal tariffs.

Key equity indices extend their run of gains

The US S&P500 equity index was up +0.63% yesterday, extending its run of gains to 8 days in a row – that is the longest winning streak since August last year, and leaves the index “only” -1.18% below its 2 April close after which US President Trump’s ‘Liberation Day’ tariffs were announced. Elsewhere, the pan-European STOXX600 and UK FTSE100 equity indices just managed to eke out by the thinnest of margins, another day’s gain (both edging higher by +0.02%). It was marginal though – for example, while the FTSE100 notched up a 14th daily gain in a row, a joint record since the index was formed back in 1984, looking at different indices, the MSCI UK equity index (owing to a different constituent index composition), was actually marginally down on the day. All in local currency, price return terms.

What does Brooks Macdonald think

This morning’s statement from China signals the strongest indication yet that the trade tariff stalemate between the world’s two-biggest economies could get resolved. For context, the positive reaction in markets this morning comes against US-China tariff rates on both sides that are so high currently that they effectively amount to a trade embargo in all but name. It is still very early days, and there are thorny trade issues for both sides to address, but China’s apparent willingness to enter trade negotiations is in itself welcome news.

Please check in again with us soon for further relevant content and market news.

Chloe

02/05/2025

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

What has happened

Equities yesterday added another day to an impressive run of gains, wrapping up a volatile month. The US S&P500 and the pan-European STOXX600 equity indices have now both rallied for 7 days in a row, while the UK FTSE100 equity index has notched up 13 days in a row of gains and the FTSE100’s best run in over 8 years. Since the markets close on 2 April, after which the US unveiled its “liberation day” tariffs, those 3 indices are respectively now “only” down -1.80%, -1.76%. and -1.32%, all in local currency price return terms. Looking to the day ahead, strong numbers last night after the US close from megacap tech companies Microsoft and Meta are expected to help equity markets today, while attention will turn later on to Apple and Amazon results due after the US close later today.

US GDP weaker, but distorted by a big surge in imports

Yesterday saw the advance estimate for US calendar 1Q Gross Domestic Product (GDP) released. The data showed Quarter-on-Quarter (QoQ) annualised real (constant prices) GDP shrinking -0.3%, versus market expectations for small growth of +0.3% – it was well below Q4 2024’s +2.4% print and the average growth of close to +3% over the past 2 years. To caveat, however, within the data there was a big distortion from a surge in goods imports (where imports are subtracted from GDP), which clocked a QoQ annualised growth rate of +50.9% in Q1.

Microsoft and Meta deliver strong numbers and outlook

Microsoft and Meta (the parent company of Facebook) both delivered strong results after the US close yesterday, sending both companies’ shares up in after-market trading by over +5% each. On the outlook for artificial intelligence (AI), both companies signalled continued strong demand: for Microsoft, its Azure cloud computing division which includes AI spend, posted an estimate-beating +33% revenue growth; for Meta, the company raised its capex spend plans for this year, with its CEO Zuckerberg saying that “the pace of progress across the industry and the opportunities ahead for us are staggering”.

What does Brooks Macdonald think

The latest US GDP data hides some cross-currents to be mindful of – with companies frontloading stock ahead of US tariffs, a surge in imports distorted the US 1Q GDP data – because any goods imported into the US are by definition not produced in the US, they are subtracted from US GDP. Instead, economists sometimes prefer looking at ‘real final sales to private domestic purchasers’ to get a cleaner snap-shot of consumer demand – indeed, US Federal Reserve Chair Powell has said in the past that this measure “usually sends a clearer signal on underlying demand” – on this measure the picture is a bit more encouraging, showing a +3.0% QoQ annualised increase in 1Q, and slightly up on the +2.9% QoQ annualised increase seen in 4Q last year.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

1st May 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 29/04/2025.

Tariff talk and rate cut hopes amid economic caution

Downgraded growth forecasts and more tariff talk. Could rate cuts cushion the tariff blow?

Softening tone from Trump. Will it last?

There are more U-turns from the White House, likely from the compounded market pressure due to the sell-off of U.S. stocks, the U.S. dollar and U.S. treasuries in unison.President Trump said he would be willing to “substantially” pare back his 145% trade tariffs on China and said both sides have been talking, though China has denied the latter. From being unapologetically provocative on China to the suggestion of “being nice” in just a matter of weeks, it’s no wonder “Trump chickens out” is a top trending hashtag on Chinese social media Weibo.

The softening in aggressive rhetoric came after a meeting with key U.S. executives from Walmart, Home Depot and Target. The sky-high tariff rates on China will significantly disrupt supply chains, risk empty shelves when inventories are run down, and raise the price of imported goods for the average American consumer. This is an indication that opinions from the Corporate American elites have some sway on President Trump.

Though perhaps the reason for backing down is simple – the trade war between the U.S. and China is “not sustainable”– as Treasury Secretary Scott Bessent neatly put it. The U.S. has a trade deficit of $274 billion with China, from where it imports $439 billion and exports $165 billion. At first glance, it seems China stands to lose the most, if a large part of these export revenues is lost. But as China stands firm and as days go by, it becomes increasingly apparent that the U.S. will suffer more in the near-term given its heavy reliance on a range of household goods and industrial inputs from China. American businesses and consumers will either find it difficult to substitute those Chinese imports or will pay a higher price due to tariffs.

Given the sensitivity of U.S. consumers on inflation and how integrated U.S. businesses are with supply chains in China, it’s difficult to see how these astronomical tariff rates can last for weeks, let alone months or years.

Aside from tariffs, President Trump also U-turned on his claims of firing Fed Chair Jay Powell. While President Trump reiterated his call for interest rate cuts, he said he had no intention of firing Chair Powell. Whether he means it from the bottom of his heart is debatable, but the point is, the bond market serves as a guardrail on how far he can test the boundaries.

While the trade drama is almost certain to continue, the recent developments did provide hope that the worst of the provocations are over. What we can learn from last week is that economic pragmatism and market pressures do hold Trump back, at least to some extent. That said, some credibility on the U.S. administration is damaged and investors are assigning a higher risk premium on U.S. assets under Trump 2.0.

The economic cost of tariff uncertainty

It’s certainly a welcoming development that the most aggressive tariff rates may scale back. Given the economic damage is self-inflicted, the U.S. administration does have control to reverse all these damaging decisions. What it cannot control and easily amend is the confidence and credibility lost. The impact of policy uncertainty on economic activity is often manifested through the confidence channel. We have already seen a plunge in various U.S. consumer and business surveys, with a worrying combination of higher price expectations and a decline in the desire to spend or invest. The latest PMIs in major developed economies provided yet more evidence of the potential stagflationary (higher inflation, lower growth) impact of Trump’s tariffs.

Source: Refinitiv Datastream.

Since the escalation of trade tariffs, various high-profile executives and sell-side economists have been warning about the negative impact. The latest World Economic Outlook by the IMF presents another authoritative voice on the subject. Unsurprisingly, the IMF has downgraded global growth forecasts due to trade tensions and deteriorating sentiment. The 2025 U.S. GDP growth forecast has been slashed by 0.9% to 1.8%, a very significant downgrade in just a matter of three months. While a U.S. recession is not expected, the IMF has raised the probability of this happening to 40%. Setting aside cyclical worries, the new reality highlighted by the IMF is that the global economic system, that has operated for the last 80 years, is being reset.

Rate cuts to cushion the tariff blow?

After the decisive rate cut by the European Central Bank due to economic concerns, the question is how far will central banks go to cushion the economy from tariff blows. There is a willingness to cut rates to support the economy for sure, but it all depends on whether there’s room to do so i.e. does inflation mean monetary policy can be loosened.

It’s interesting to hear the views of Monetary Policy Committee (MPC) member Megan Greene on the subject. She feels tariffs actually represent more of a deflationary risk than an inflationary risk. While the tariffs are expected to raise prices in the U.S., the UK could see the opposite effect due to the diversion of cheap Asian exports, a weaker dollar and the softening of demand from slower growth. The takeaway from the perspective of one of the most hawkish policymakers of the Bank of England is that the concern on growth probably outweighs that of inflation.

While Fed Chair Jay Powell is applauded to stand firm on no rate cut for now, two Fed officials expressed support for a rate cut if there’s more evidence of an economic slowdown and deterioration in the labour market. It seems that central bankers are adopting an agile mindset to deal with this new macro environment of multiple shocks. As growth outlook deteriorates, traders are pricing in a few more rate cuts in the UK, U.S. and the Eurozone for the rest of 2025.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

30/04/2025

Team No Comments

EPIC Investment Partners – The Daily Update: Trump Tariff’s Troublesome Tentacles

Please see the below article from EPIC Investment Partners detailing the ongoing impact of Trump Tariff’s on the US economy. Received this morning 29/04/2025.

The world is spending a great deal of time trying to justify the dubious hypothesis that tariffs help domestic manufacturers… even if it is true, it ignores the large potential cost to exporters and consumers.

Tentacle 1: Small domestic business. 40% of imports into the US are for domestic manufacturing use, often consisting of intermediate goods used as inputs in domestic manufacturing processes. 37% of US imports from China are indeed these intermediate goods for which prices have now doubled, and whilst domestic production of these input goods may cover some of the gap, it cannot replace all the imports in the short-term. Less than 5% of iPhone components are currently manufactured in the US, and aside from the chipsets coming from Taiwan, most of the phones are made in China. Whilst Apple may be able to get a reprieve on import tariffs, we are not sure the rest of the small-to-mid-cap firms will be so lucky. We have not yet mentioned that small businesses make up 36% of exports, and there could be significant retaliatory tariffs on their exports too. As a reminder, in 2024, small businesses in the US accounted for 46% of all employees and are historically more sensitive to margin compression. 

Tentacle 2: Freight. In attempts to encourage US shipbuilding, steep fees are being levied on Chinese-owned or built ships. There is no doubt this will raise freight costs, but we are yet to see how profound the ripple effect will be. This will impact US exporters trying to seek out the cheapest shipping options. Oil and Liquefied Natural Gas (‘LNG’) will have other problems too. Only three of the eight hundred complex LNG carriers are US-built ships, dating back to the 1970s! Interestingly, the only US shipyard looking to build one right now is owned by Korea’s Hanwha Ocean.

Tentacle 3: Loss of confidence from non-US investors. The 90-day pause has not helped reduce uncertainty. Trump compared the US to a department store, stating: “I am this giant store. It’s a giant beautiful store and everybody wants to go shopping there. On behalf of the American people, I own the store and will set the prices”. However, the jump in longer-term yields suggests that not everyone wants to go shopping in the US. Furthermore, the store may start running out of stock. The port of Los Angeles is the largest entry point for Chinese goods, and they expect arrivals to be down by a third. Airfreight is also down significantly. US importers will be running down stockpiles while looking to store new deliveries, duty-free for now, in bonded warehouses or divert them to Mexico or Canada. If the department store has no stock and no one wants to shop there, can they still set prices? 

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

29/04/2025

Team No Comments

Tatton Monday Digest – Improving mood versus slowing growth

Please see below article received from Tatton this morning, which provides a global market update.

Capital markets bounced last week, supposedly because of Trump backing down on Chinese tariffs and Federal Reserve independence. 

We should be careful about these rationalisations. Greater liquidity led to a better mood in stocks and bonds, and a ‘buy the dip’ mentality from US retail investors. Trump suggesting Chinese tariffs could be lower – and that Fed chair Powell could keep his job – certainly helped, but this isn’t crisis averted. Institutional investors are still nervous, and tariff uncertainty has all but halted business investment. 

The mood benefitted from the public appearances of US treasury secretary Scott Bessent, who sounded much more constructive on trade, tariffs and the Fed. Unfortunately, we don’t know how long Bessent’s time in the sun will last. Trump likes his cabinet to fight for policy influence – exemplified by last week’s shouting match between Bessent and Elon Musk. China also called Trump’s claims of dialogue “fake news”. Beijing might be bluffing when it says they have more stomach for trade war, but the suggestion will anger Trump’s inner circle. Bessent’s ‘adult in the room’ style won out last week, but it might not next time. 

The fact US businesses can’t plan ahead – and hence can’t invest – is a growth negative for the world’s largest economy. US stocks are still more expensive than others in price-to-earnings valuations. That has been sustained for decades by exceptional profits, but the latest earnings reports show that exceptionalism is fading. 

Other regions could pick up some of the investment slack – most notably Europe, which is being forced to invest in its own capacity. And it’s worth noting that calls of a global recession aren’t backed up by the economic data. But the rest of world can’t fully make up for the reduction in US business investment. The growth outlook is therefore weaker than at the start of the year. We shouldn’t be surprised if last week’s positivity is soon tested. 

Tariff recap: what’s here and what’s near?

Trump tariffs are always in the news, but it’s surprisingly difficult to find out which tariffs are actually in place. The table below shows US tariffs currently in effect and those soon expected.

US imports from Mexico and Canada face a 25% import tax – except those covered by the USMCA trade deal Trump signed in 2019. The White House says that USMCA compliant goods account for 50% of Canadian imports and 38% of Mexican imports. Non-USMCA compliant energy and potash imports face a lower 10% tariff.

Trump suspended his “reciprocal” tariffs until 9 July, but the baseline 10% on most countries – and 25% on cars, steel and aluminium – is still in place. China faces a higher 145% rate, despite the president’s softer rhetoric last week. Chinese electronics are currently exempt but probably won’t remain so, and the de minimis rule excluding small orders up to $800 will end on 2 May. 

Looking ahead, the most likely outcome is a patchwork of bilateral trade deals. Despite White House antagonism towards Europe, many expect lower tariffs eventually. China is more complicated, as it’s unclear whether Trump is tactically or ideologically opposed. But trade deals take longer to sign than Trump’s 90 days, so even in the best case scenario we will probably see last-minute unilateral declarations from Washington. 

More tariffs are on the way, like 25% for pharmaceuticals and semiconductors. It’s also possible the US will threaten to tariff China’s trading partners – similar to their plan for Venezuela. Then there is the USMCA renegotiation between the US, Canada and Mexico looming next year. In the meantime, trade experts’ best guess for average US tariffs by the year end is 15-20%. That wouldn’t mean a deep recession, but the fact nobody is sure what will happen doesn’t help. 

Fed independence: it would have been a nice idea

Trump saying he has “no intention” of firing Federal Reserve chair Jerome Powell was a relief for markets, as central banks’ operational independence is a cornerstone of the global financial system. 

The central bank independence movement started in the 1920s, but was put on hold during WWII and the Keynesian macroeconomic consensus that followed. When the consensus collapsed during the 1970s inflation crisis, the role of central banking had shifted from emergency lending to ongoing economic management – which led to banks gaining legal independence from the 1980s. Economists generally think independence has succeeded in giving central banks credibility and taming inflation. 

But independence has always been more an aspiration than a reality. Governments scrutinise central banks, and successful economic policy requires fiscal and monetary coordination. Trump adviser Stephen Miran has argued this coordination means Fed independence isn’t realistic or desirable – but you could argue it means the opposite. Monetary policymakers need to think about the implications of public spending on interest rates, which requires thinking on longer timeframes than short-term election cycles. Fed independence is reminiscent of Gandhi’s famous line, when asked about Western civilisation: “I think it would be a good idea.”

Markets certainly don’t like Trump’s attempts to squash this aspiration. The longer-term impact of Fed’s independence removal would be on bonds. Interestingly, this might actually reduce our preferred measure of government ‘credit risk’ (the difference between government bond yields and Fed-guaranteed interbank swap rates) because it would mean the treasury can directly print money to pay off its debts. The real risk is that the money would become worthless – meaning higher yields. This puts the Fed in a bind. Arguably, Powell should cut interest rates because of weaker US growth, but the uncertain impacts of Trump’s policies on inflation is stopping the Fed from doing so. Hopefully, the White House won’t stop Powell from acting altogether. 

Please check in again soon for further relevant content and market news.

Chloe

28/04/2025


Team No Comments

EPIC Investment Partners The Daily Update – Tariff Stalemate Fuels China’s Renminbi Push

Please see the below article from EPIC Investment Partners detailing their discussions on the Tariff stalemate between the US and China, and China’s push for the internationalisation of the Renminbi. Received this morning 25/04/2025.

Negotiations between China and the United States remain deadlocked, with both nations imposing substantial tariffs on each other’s imports. US Treasury Secretary Scott Bessent has described these tariff levels as “unsustainable,” underscoring the urgent need for significant reductions to facilitate productive dialogue. Despite assertions from the US suggesting ongoing discussions, Chinese officials have repeatedly denied these claims, highlighting that no substantive negotiations are currently underway. This diplomatic impasse underscores deep-rooted differences and indicates a near-term resolution is unlikely.

Amid this standstill, China is actively redirecting its strategic efforts towards strengthening global diplomatic relations and accelerating the internationalisation of its currency, the renminbi (RMB). This strategic pivot directly addresses vulnerabilities exposed by dependency on the US dollar, particularly as geopolitical tensions intensify.

On 21 April, the People’s Bank of China (PBOC), alongside other financial regulators, issued clear directives urging state-owned enterprises (SOEs) to prioritise the renminbi in overseas transactions. This significant policy directive aims explicitly at reducing China’s reliance on the US dollar, thereby enhancing its financial autonomy and international economic influence. China’s insistence on complete removal of US tariffs aligns closely with its broader strategy to mitigate external pressures and assert greater control over its economic trajectory.

PBOC Deputy Governor Lu Lei has highlighted the importance of improving cross-border financial services and payment networks, essential for wider adoption of the renminbi internationally. Although the tangible impacts of these directives are yet to materialise, the strategic intent signals a deliberate and substantial shift in China’s long-term economic planning. Accelerating the renminbi’s global adoption serves not only to increase the currency’s prominence but also to leverage enhanced financial autonomy amid ongoing international friction.

Successful internationalisation of the RMB could significantly reshape the global economic landscape. A stronger and more broadly accepted renminbi would enhance China’s geopolitical leverage, attracting countries eager to diversify their foreign exchange reserves and mitigate dollar-centric financial risks. This shift would bolster China’s overseas investment capabilities, particularly benefiting initiatives like the Belt and Road, by enhancing the purchasing power of Chinese enterprises abroad. This may extend further to acquiring stakes and knowledge in key industries like AI and robotics.

Domestically, a stronger renminbi aligns with China’s overarching goal to shift economic growth from export dependency towards increased domestic consumption and the development of higher-value-added industries. We have seen this with electric vehicles, where China is the world leader producing 60% of the world’s electric cars and 80% of the batteries that power them.

China’s firm stance highlights the deepening divergence between the two economic superpowers. The US demand for mutual tariff reductions contrasts starkly with China’s insistence on unilateral US tariff removal, deepening the stalemate. Consequently, this unresolved conflict appears likely to endure.

In response to this persistent impasse, China is clearly leveraging the situation to expedite its currency internationalisation agenda, potentially redefining global financial dynamics. For investors, understanding this strategic shift is crucial, as it has disruptive implications for the future structure and stability of global finance. We will keep you updated as this story unfolds.

Please continue to check our blog content for advice, planning issues, and the latest investment, market and economic updates from leading investment houses.

Alex Clare

25/04/2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see the below article from Brewin Dolphin, examining some possible explanations for why the U.S. dollar is weakening and discussing the recent European Central Bank interest rate decision and the prospect for further cuts. Received – 23/04/2025

The dollar declines

One of the most notable features of the Trump 2.0 market reaction has been the weakness of the dollar. This is notable because in previous periods of financial stress, the dollar has tended to strengthen.

Any weakness felt by the U.S. is often assumed to be felt even more harshly by its trading partners as it’s transferred to them via the global financial system. An important difference in this period of stress compared with previous ones is the unorthodox strategy the U.S. has adopted of fighting all its trading partners simultaneously. As a result, the economic impact is likely to fall more heavily on the U.S. than on other countries.

The U.S. tariff strategy has already pivoted. It’s still broad, but now specifically targets China with the deepest measures while, allegedly temporarily, applying a baseline 10% tariff to all other countries. A key question is whether this could change from being a principally U.S. problem to becoming a principally ‘all-other-countries’ problem. There’s also the question of whether the start of trade talks will see the U.S. negotiating on a weaker dollar through some kind of accord.

Trade Balances

Source: IMF, LSEG Datastream

Some of President Donald Trump’s advisers see the devaluation of the dollar as a policy goal. This is because the Pax Americana, which has existed since the end of the Second World War, has since been shown to bear some economic costs (perceived or real) for the U.S.

Most notably, the establishment of the Bretton Woods Agreement cemented the U.S. dollar as the reserve currency of the global financial system. It required other countries to accumulate foreign currency reserves in dollars. An inadequate supply of dollars would restrict the amount of trade that could take place, but trading partners need to get those dollars from somewhere and the only possible sources are loans, U.S. foreign aid, or earning them through trade.

So, initially the U.S. needed to supply the world with dollars, which it did through the Marshall Plan (aid) and running trade deficits, eventually undermining the dollar’s convertibility into gold. While the currency stability implicit in the Bretton Woods Agreement ended during the 1970s, the use of the dollar as a reserve currency remained.

Foreign Exchange

Source: IMF, LSEG Datastream

During the 1980s, this caused the dollar to appreciate relative to other currencies. The Plaza Accord – a joint agreement between France, West Germany, Japan, the United Kingdom, and the United States – was signed, in which all participants agreed to intervene to weaken the dollar.

Stephen Miran, the Chair of President Trump’s Council of Economic Advisers, has previously published a plan for a Mar-a-Lago Accord, with the objective of bringing about a weaker dollar. A weaker dollar could be an area in which the president and his advisers are in agreement.

However, a weaker dollar seems likely to imply higher borrowing costs (less foreign ownership of treasuries), which would bring real costs to U.S. taxpayers. 

If the U.S. does want to weaken the dollar, there are ways for investors to benefit. That would happen if foreign central banks reduced the weightings to dollars within their foreign exchange reserves. A beneficiary would be gold, which has been very strong.

Gold, which had once accounted for around 60% of foreign exchange reserves, fell to just 6% during the financial crisis and gradually rose until 2024, when its growth sped up, reaching nearly 15% once more.

Various actions may have motivated this. Many developing world economies have held large U.S. dollar foreign currency reserves, but reliance on the dollar exposes them to sanctions that the U.S. might wield in the future.

The U.S. president’s recent apparent disregard for key federal institutions, such as the judiciary and the independent central bank, is concerning and could potentially weaken the dollar even further.

This was brought into sharp relief around the Easter weekend, when President Trump made a series of comments and social media posts insulting and expressing his dissatisfaction with Federal Reserve Chairman Jay Powell.

Added to this is the possibility that current day America no longer wants the central role in the global trade and financial system that American economist Harry Dexter White negotiated for at the Bretton Woods conference.

The trade talks begin

U.S. Trade run

Source: IMF, LSEG Datastream

The first round of trade talks began last week. Japan is the first government to be granted the opportunity to negotiate with the U.S. According to mercantilists, Japan has been a longstanding adversary to the U.S. In fact, it was Japan that inspired President Trump to publish his open letter calling for protectionism in 1987.

President Trump announced that the talks had seen big progress, although details were scant. Ryosei Akazawa, Japan’s Economic Revitalisation Minister, said more talks will take place this month and that the currency wasn’t discussed. That’s a surprising development because Japan’s alleged currency manipulation has been a constant source of President Trump’s ire.

The resolution of trade issues with Japan may take months and it remains to be seen how many concurrent trade negotiations the U.S. is prepared to run. Japan alone will not materially change the size of its trade deficit.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

24th April 2025

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below, Brooks Macdonald’s Daily Investment Bulletin which summarises the key issues currently affecting global investment markets. Received today – 23/04/2025

What has happened?

The last 24-hours has seen more Trump-news whiplash for markets, with the latest turn of events signalling a possible easing in US-China tensions as well as (after the US close yesterday) some relief for US Federal Reserve watchers. The better tariff hopes pushed the US S&P500 equity index up +2.51%, its strongest day’s performance in two weeks, and unwinding the previous day’s falls in the process. Over in Europe, given markets were closed on Monday, not having to claw back a previous day’s losses meant the gains yesterday were a bit more muted, with the pan-European STOXX600 equity index up +0.25% and the FTSE100 up +0.64%, all in local currency price return terms. Also notable yesterday was US megacap technology stock Tesla shares which rose in after-hours trading despite weaker results after its CEO Musk said he would step back “significantly” from the US Department of Government Efficiency.

Trump administration eases US-China tariff worries

There were welcome signs of an easing in tensions coming out from the US Trump administration yesterday. In a JPMorgan-hosted closed event on the sidelines of the IMF (International Monetary Fund) meetings in Washington DC yesterday, according to sources in the room, US Treasury Secretary Scott Bessent said that of the US and China, “neither side thinks the status quo [on the current tariff rates] is sustainable”. Following that, US President Trump separately said that he didn’t see the need to “play hardball” with China and planned to be “very nice”, adding that tariffs could drop “substantially, but it won’t be zero” if the two countries can reach a deal.

An independent Fed after all

After the past weekend’s headlines that suggested Trump was seeking to find ways to remove US Federal Reserve (Fed) Chair Jerome Powell from office (before Powell’s term is set to end next year, May 2026), yesterday was another welcome walk-back from US President Trump. Taking questions from the press yesterday, Trump said that he had no intention of firing Powell despite his frustration with the central bank not moving more quickly to cut interest rates: “Never did,” Trump told reporters yesterday, adding that “the press runs away with things. No, I have no intention of firing him, [but] I would like to see him be a little more active in terms of his idea to lower interest rates.”

What does Brooks Macdonald think?

It is hard to keep up with the almost daily U-turns in policy and views coming out from the US Trump administration at the moment – not surprisingly, markets are on edge and volatility is high. But making knee-jerk investment decisions in the heat of the moment, which can carry far-reaching longer-term performance consequences, is rarely a good idea. Instead, our focus continues to be on keeping a balanced and diversified approach, aiming to position our asset allocation choices to weather economic uncertainties effectively, and focused on a long-term investment strategy that is adaptable yet grounded in sound principles, aiming to position portfolios to effectively navigate the economic uncertainties that lie ahead.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

23rd April 2025