Please see the below article from EPIC Investment Partners detailing their discussions on the Labour Market. Received this morning 16/05/2025.
For nearly six months, weekly changes in continuing jobless claims have alternated consistently—rising one week, falling the next—for 24 consecutive weeks. The likelihood of such a precise pattern emerging randomly is extraordinarily slim, approximately 8.4 million to 1, strongly suggesting data quirks rather than genuine economic movements.
Continuing claims offer critical insights into labour market health, reflecting how swiftly unemployed individuals secure new employment. While regular fluctuations are normal, this remarkable alternation signals statistical anomalies more than actual shifts in employment conditions.
We attribute this unusual pattern primarily to flawed seasonal adjustment methods, designed to smooth predictable variations in hiring, such as holiday or seasonal cycles. Administrative factors—like staggered filing schedules or delayed reporting from certain states—could introduce consistent week-to-week volatility unrelated to underlying economic fundamentals. If filing schedules were to change, the previous seasonal adjustments would introduce this saw-tooth pattern in the data. We can’t be certain, but this seems the most likely explanation.
Yet beneath these statistical irregularities lies an important and genuine trend: continuing claims have been steadily edging upward, approaching their highest levels since late 2021. This increase indicates unemployed workers are facing longer job searches, a reality seemingly at odds with robust payroll employment figures. Such divergence suggests increasing friction and caution among employers, nuances not immediately apparent in headline job data.
Initial unemployment claims remain relatively low, reflecting minimal mass layoffs. However, the gradual rise in continuing claims highlights subtle but real softening in labour market conditions. Employers appear increasingly cautious, resulting in slower hiring and longer periods of unemployment for jobseekers.
In our view, the upward drift in continuing claims points to genuine but modest weakening in labour market dynamics. Should this trend persist, it could negatively affect consumer spending and corporate profitability, thereby influencing monetary policy considerations. Conversely, easing labour market tightness could help moderate inflationary pressures, potentially allowing the Federal Reserve greater flexibility in its policy approach.
Although the alternating weekly pattern is likely a statistical curiosity, it underscores the necessity of cautious data interpretation. By focussing on multi-week averages we get a clearer picture of the trend than the more volatile weekly data. Ultimately, the gradual but persistent rise in continuing claims is an early sign of potential economic softening that warrants careful attention in the months ahead.
Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.
Please see below article received from EPIC Investment Partners this morning, which provides a re-assuring reminder to long-term investors.
In the world of investing, headlines often spark dramatic market moves—but it is the underlying fundamentals that determine lasting success. The recent rollercoaster of reactions to Trump’s policies offers a timely reminder for institutional investors: do not let short-term noise derail your long-term strategy.
Markets initially surged on Trump’s promises of tax cuts, deregulation, and a broadly pro-business agenda. The early rally reflected optimism around stronger corporate earnings and economic growth, with many investors positioning for reflation. But sentiment shifted swiftly as tariffs and trade tensions took centre stage. Uncertainty mounted, global growth forecasts softened, and defensive positioning became the consensus—not because fundamentals collapsed, but because narrative-driven fear took hold.
Institutional investors felt the pain. Many de-risked portfolios amid fears of an economic hard landing—just as quality growth stocks began to recover. From late April, the market turned decisively, punishing underexposure to structurally advantaged names.
Take Meta, for example. Oversold on concerns that advertising demand was evaporating, the stock fell to $480. Those fears proved overstated: Meta rebounded over 37% to $659 within weeks, buoyed by strong earnings and upbeat guidance.
NVIDIA followed a similar path. It dropped below $95 amid worries that Big Tech would slash AI capital expenditure. But those concerns quickly dissipated as Microsoft, Amazon, Alphabet, and Meta reaffirmed AI investment as a long-term priority. The stock surged back to $135, underscoring AI’s structural growth potential.
This earnings season highlighted a clear bifurcation. While many companies tread water or guide cautiously amid ongoing macro risks—such as inflationary pressures and geopolitical uncertainty—a select group, particularly in tech, industrial automation, and med tech, is steamrolling ahead. The market is rewarding operational resilience, pricing power, and exposure to secular growth drivers.
The key takeaway? Headlines drive short-term volatility, not long-term returns. Real wealth is built by owning high-quality, resilient businesses through cycles—not by reacting to noise. The bigger risk for institutions is not volatility but being underexposed to the long-term secular winners. Portfolio construction should prioritise capturing enduring secular trends while not overreacting to transient macro noise or headline-driven swings.
Please check in again with us soon for further relevant content and market news.
Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.
What has happened
US megacap technology shares had another good day yesterday. Nvidia was up +4.16%, pushing the ‘Magnificent Seven’ technology group of companies’ share prices (Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia, and Tesla), up +1.75%. Elsewhere however, there was some investor buying fatigue creeping into markets after the rally over the past few weeks, with the equal-market-capitalisation-weighted version of the US S&P500 equity index down -0.62%. Over in Europe, without megacap tech to fall back on, the pan-European STOXX600 equity index was down -0.24%, while overnight Asian equity markets are a touch lower also (all in local currency price return terms).
UK economy stronger than expected in Q1
UK Gross Domestic Product (GDP) data for calendar Q1 is out this morning – the data shows the UK economy has been doing better than expected, growing at +0.7% in Q1 2025 versus Q4 2024. That is an acceleration from the +0.1% GDP growth rate in Q4 2024 versus Q3 2024 and was above forecasts looking for +0.6% in Q1 2025. Furthermore Q1 2025 was the strongest quarter-on-quarter growth rate since Q1 2024. That said, keep in mind that while GDP numbers are always backward-looking, perhaps this is even more the case currently given how US President Trump’s 2 April tariffs are reshaping the global economy more broadly.
Middle East geopolitics
There are news reports overnight that Iran is willing to sign an agreement around concessions for its plans for making nuclear weapons in return for a lifting of US economic sanctions. Specifically, Ali Shamkhani (an adviser to Iranian Supreme Leader Ayatollah Ali Khamenei) has confirmed that Iran would conditionally agree to limit future uranium enrichment to lower (sub-weapons grade) levels consistent with civilian energy generation use. That better geopolitical outlook is helping to push back on Brent crude oil prices, down -3% today currently at around US$64 per barrel – for context, those oil prices are well off their $80+ per barrel 2025-year-to-date highs back in January (as an aside, as we have written about before in our Daily Investment Bulletins, keep in mind that lower oil prices, if sustained, can have a material dampening impact on any inflation pressures elsewhere).
What does Brooks Macdonald think
This morning’s UK GDP data is more difficult than usual to extrapolate. Aside Trump’s 2 April tariff plans where the recent UK-US trade deal leaves 10% universal tariffs largely in place, the domestic UK economic picture is somewhat tougher now given the hike in employer National Insurance costs that came into effect last month. The Bank of England’s latest economic projections arguably reflect that picture, with UK GDP growth expected to effectively stall in calendar Q2, with an estimated growth rate of just +0.1%.
Please check in again with us soon for further relevant content and market news.
Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 13/05/2025.
Markets rally on positive trade new
We examine how easing trade frictions have helped boost equity markets.
Source: LSEG DataStream
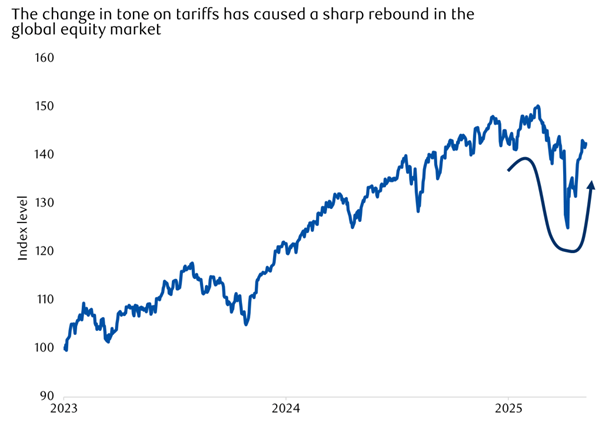
If the onset of tariffs was a major headwind for the markets, then the easing of them should be seen as a tailwind. Globalisation allows countries to specialise in activities in which they have a comparative advantage; doing so increases global economic growth, allowing each country a larger individual share of that growth.
With that in mind, the news last week was dominated by the lifting of trade restrictions. After ‘Liberation Day’, it’s become increasingly clear that the Trump administration is seeking deals that lower tariffs, but questions remained over which countries it dealt with first, when this was done and how much tariffs would be lowered by.
We got a partial answer last week when U.S. President Donald Trump announced a “full and comprehensive” trade agreement with the UK. For context, this isn’t a traditional free trade agreement, which would take the form of an international treaty and would usually need to be implemented by legislation. Instead, this is President Trump agreeing to amend the trade tariffs that he placed on UK exports by executive order under emergency powers.
As far as we can tell, the agreement is verbal at this stage, and details will be agreed over the coming weeks.
America had placed 25% tariffs on steel, aluminium, cars and car parts from all countries, but the UK has achieved a partial exemption from that, with steel and aluminium being potentially zero tariffed. The UK has also been promised preferential treatment when President Trump applies tariffs to the pharmaceutical sector. In both these instances, details remain unclear.
Most UK car exports to the U.S. will be tariffed at 10% and there were some agreements on aeronautical deals (the U.S. buying engines from the UK and the UK buying planes from the U.S.). The cost of these easements is that the UK has had to drop some agricultural tariffs – it will probably adjust its digital services tax, too.
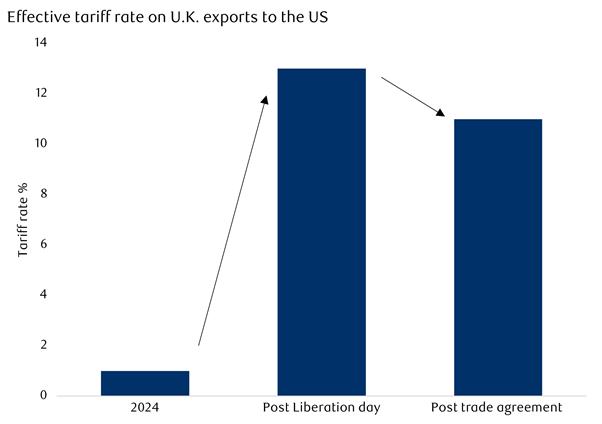
The overall impact of these measures is likely to be very small, though. This is partly because the most significant measure, the 10% universal tariff rate on all (now most) exports to the U.S., will remain in place, so the average tariff rate has only come down a little bit. Moreover, the UK runs fairly balanced trade with the U.S. anyway, and so the initial measures didn’t really affect us that much. Achieving big gains from trade is now much harder than it used to be, since the most significant barriers have already been dismantled.
Declining tariffs are generally good news, but the UK deal suggests that trade with the U.S. is likely to be subject to a minimum tariff level of 10% on most goods. As discussed a couple of weeks ago, the U.S. seems very ready to reduce tariffs with China. President Trump reiterated last week that he won’t do so pre-emptively, but it’s clear that the current rate of 145% tariffs won’t remain in place.
The UK also agreed a more conventional trade deal with India after three years of negotiation. The government says this deal will boost the UK’s gross domestic product (GDP) by £4.8bn by 2040. To put this into context, that’s only 0.19% of the UK’s current GDP. So, however things play out, this isn’t likely to be something that really moves the needle for the economy.
Overall, tariffs remain a force that’s likely to depress growth and increase inflation – but they’re set to decline from their current levels.
Source: LSEG DataStream
The Bank of England’s Monetary Policy Committee (MPC) probably had relatively little notice of the trade deal, and its effect was marginal anyway. Instead, the MPC has been focusing on an economy which has experienced relatively little growth momentum and a cooling inflation picture.
As an important caveat, there will be an increase in inflation over the coming months due to gas and electricity bills, but beyond that, disinflationary pressures seem set to bring the inflation rate back down towards target. Jobs growth has been softening and job postings have been declining. The cost of employees has risen due to the increase to Employers National Insurance contributions, and companies now have the options of absorbing the costs in their profit margins, passing them on in higher prices (inflation), or reducing their staff numbers.
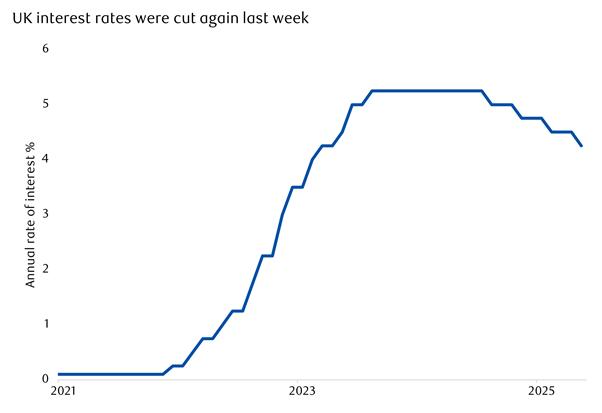
This creates a lot of uncertainty, which was reflected in a three-way split when the MPC voted on whether to cut interest rates last week; two members wanted to cut interest rates faster and two wanted to stay on hold.
In the end, the majority decision was a 0.25% cut, but that uncertainty meant that markets reduced their expectations for future cuts for the time being. Interest rates are currently expected to fall from 4.25% to 3.5% or 3.75% by the end of the year.
Source: LSEG Datastream
As we’ve seen so often before, the markets are climbing the wall of worry that was built by President Trump’s erratic behaviour during the first few months of his second term.
Interest rates have been falling in the Eurozone, have started to fall in the UK, and will likely fall in the U.S. too (eventually).
Last week, the U.S. Federal Reserve left interest rates unchanged (as expected) as the outlook for inflation is difficult to gauge due to the erratic trade policy environment. However, with equity sentiment quite depressed, the conditions for markets to continue climbing that wall of worry seem quite supportive in the short term.
Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.
Please see below, Brooks Macdonald’s Daily Investment Bulletin which summarises the key factors currently affecting global investment markets. Received today – 13/05/2025
What has happened
Yesterday saw a massive rise in US equities, but other equity markets rose too, as news landed that US and China had agreed to a temporary climb-down in trade tariffs. US equity markets (which had previously seen some of the biggest daily falls following US President Trump’s 2 April tariff ‘Liberation Day’), rocketed higher. The US S&P500 equity index was up +3.26%, its third best day in the last five years, as megacap tech led with the ‘Magnificent Seven’ group (Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia, and Tesla), up +5.67%. In contrast, the gains across other equity markets yesterday were smaller in comparison: the pan-European STOXX600 equity index was up +1.21%, while the FTSE100 equity index was up +0.59%. All in local currency price return terms.
Tariff relief might be only temporary
Yesterday saw a huge climb-down in US-China tariff rates, and much more than had been hoped for in markets. Both sides reduced tariffs by 115 percentage points for a 90-day period, with US tariffs on Chinese exports coming into the US down to 30% from 145% (and China tariffs on US exports going into China down to 10% from 125%). But a note of caution that this tariff relief might be only temporary – keep in mind that as recently as last week, US President Trump had said that he felt that a “80% tariff on China seems right”, while previously he had talked about a 60% tariff rate during last year’s US Presidential election campaign.
Did China just agree to open up its economy?
Without offering any specifics, Trump yesterday said that as part of the US-China temporary tariff relief measures, he heralded “a total reset with China”, with China agreeing to “suspend and remove all of its non-monetary barriers”, and that “China agreed to open itself up to American business.” While Trump conceded that “it’s going to take a while to paper it, you know, that’s not the easiest thing to paper”, he said that this was “the best part of the deal .. maybe the most important thing” to have come out of the trade talks. If confirmed, this would be in line with the US Trump administration’s push for more market access in China for US businesses as part of resetting the balance of trade between the two countries.
What does Brooks Macdonald think
Yesterday’s better tariff news impacts bonds as well as equities. With the US-China tariff climb-down, that has quashed for now fears of an imminent US recession. However, the flipside of this relief around the economic growth outlook, is that there are now less interest rate cuts expected – that has driven government bond yields, both in the US but also elsewhere including UK and European yields, materially higher over the past 24-hours. While this has negatively hit bond prices across the bond maturity curve, relative-to-benchmark shorter duration bonds do provide a degree of insulation from such bond market volatility, given their relatively smaller interest rate sensitivity.
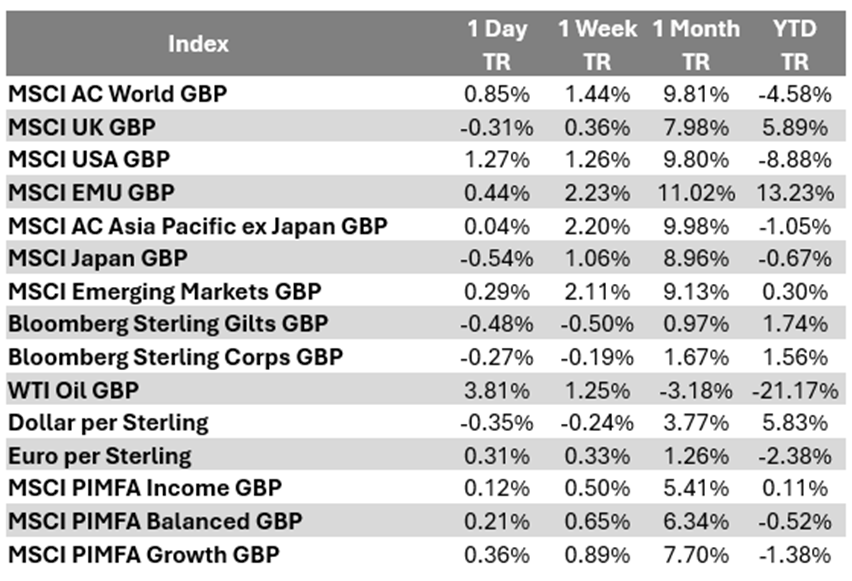
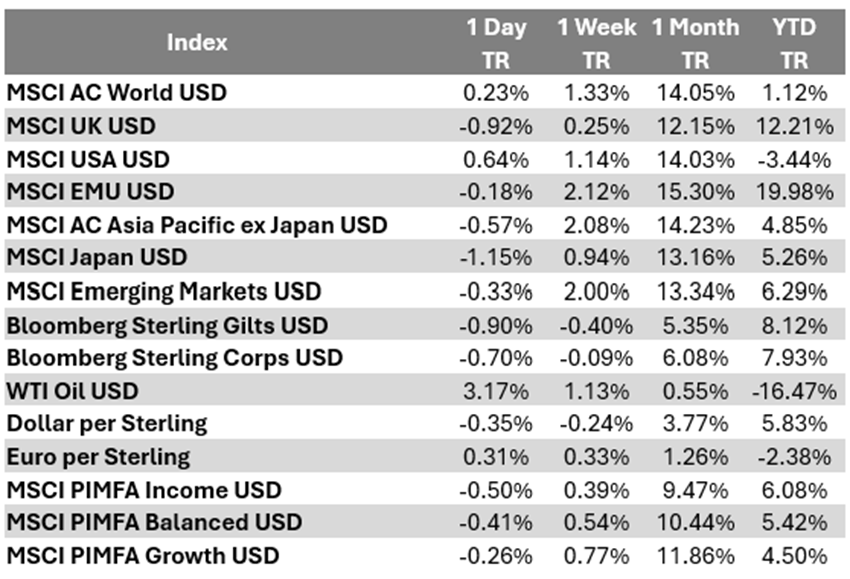
Bloomberg as at 13/05/2025. TR denotes Net Total Return.
Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.
Please see below, an article from Tatton Investment Management analysing the key factors currently affecting global investment markets. Received this morning – 12/05/2025
Markets calm but trouble still bubbles
Despite India-Pakistan hostilities, markets remained calm – thanks to trade deal progress and a sense that global growth will resume. Friedrich Merz’s failure to get first-round confirmation of his chancellorship was embarrassing but proved a market irrelevance at the end of the week. An India-Pakistan war certainly wouldn’t be irrelevant, but markets don’t think it will come to that and are more interested in the triangle of trade deals: UK-India (signed), UK-US (announced), US-India (in the works).
Trump proudly portrayed the UK-US ‘deal’ as unfair to UK goods exporters, but given it doesn’t include services (which the UK sells much more to the US) Starmer is probably right that this is the best for now. The broader narrative is once again that Trump tariffs are just “the art of the deal”. We see economic headwinds increasing, but can’t deny tariffs have brought leaders to the table.
Meanwhile, the Bank of England cut interest rates – though not as decisively as hoped – and the Federal Reserve held steady, to Trump’s displeasure. UK rate cut expectations dropped, but Britian is still on course for lower rates. The Fed’s situation is tougher: Trump called chairman Powell “Too Late” to cut rates and support US economy, and he’s right. What he’s missing is that tariff uncertainty and a tightening labour market from immigration prevention are causing the delay.
The EU’s retaliatory tariffs and Trump’s film industry tariffs don’t fit the “art of the deal” narrative. Investors consider these idle threats – and they might be. But threats themselves can be enough to stifle business activity, as we’re already seeing.
This suppression of activity is a problem for the precariously balanced US jobs market and its tightening credit conditions. Next week’s senior loan officers survey will be telling, but debt financing for small companies is already burdensome. These problems can be avoided if Trump relents or the Fed cuts – but the president seems unwilling and the central bank unable. If nothing changes, things could get nasty.
Markets are pricing in a positive resolution – but, like in January they may be underestimating the risks.
India’s art of the trade deal
Despite conflict with Pakistan, Indian stocks are significantly up from a month ago. Markets are more focussed on India’s trade deals – one signed with the UK and another in the works with the US. The former has been brewing for three years, but was clearly hurried over the finish line by Donald Trump’s trade wars. This probably helped New Delhi get concessions from the UK (the politically unpopular national insurance exemption) in exchange for a relatively moderate, though still meaningful, lowering of its high import tariffs.
Removing the US’ 26% “reciprocal” tariff on India is the bigger prize, and a deal suits both governments. India gets to keep one of its biggest customers, and Washington gets access to one of the world’s fastest growing economies. Ironically, negotiations are made easier by India’s currently sky-high tariffs. They have plenty of room to fall and Prime Minister Modi wants to open up India’s economy anyway. Over the long-term, this could be the ‘beautiful win’ President Trump claims, but the short-term impact for Americans will be small, as the US trades much less with India than Europe or China.
The fact higher tariffs give you an easier start in negotiations is one of the main reasons Trump likes them in the first place – as the US-UK deal shows. But that ‘hard bargain’ approach perversely punishes regions where trade is significant and relatively open, and might therefore give the US’ most important trading partners a bigger incentive to retaliate, as we see with China and the EU.
It’s also incompatible with Trump’s other tariff aims. Tariffs that go up just to come down don’t provide stable tax revenues or incentives for business investment. India’s experience shows the tactical approach is currently winning out, but those other goals could come back to the fore.
Are US small caps facing a credit crunch?
Small cap US stocks suffered after “Liberation Day” tariffs, but the impact on their debt financing has gone under the radar. The total interest paid by US small caps, as a percentage of earnings, is now at its highest level since the early 2000s – thanks to the lagged effect of sharply higher interest rates since 2022. Smaller companies tend to have higher debt-to-earnings ratios, but total debts aren’t growing especially fast. Rather, more of that debt is having to be refinanced at sharply higher rates than many locked in pre-2022.
Smaller companies started the year thinking that Trump would cut taxes and regulation, while the Federal Reserve would keep cutting interest rates – which made them seem like safer borrowers and thereby lowered credit spreads (the difference between corporate and government bond yields). But Trump’s disruptive policies have instead rocked business and consumer confidence, dampened growth expectations and hence raised credit spreads once more. The real kicker, though, is that uncertainty around tariffs is preventing the Fed from cutting rates – even though there is an argument the US economy needs it.
A credit crunch could still be averted, if the Fed does cut fast or if Trump enacts his pro-growth promises – and both those scenarios become more likely the worse the economy gets. Without that relief, though, small caps will eventually come under stress. JPMorgan predict that default rates for the worst-rated companies will climb to levels seen after the dotcom bubble.
Defaults are a clear sign of recession – which many are now predicting for the US. If the squeeze on small cap credit continues, we will get dangerously close to that point. The Fed will no doubt watch what happens to small cap credit closely. They may be forced to act – regardless of what happens to tariffs.
Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.
Please see the below article from Brooks Macdonald detailing their discussions on key economic events that occurred yesterday. Received this morning 09/05/2025.
What has happened
US equity markets on Thursday were riding higher on optimism that following a UK-US trade deal announced yesterday, there might be more US deals to follow, including even perhaps between the US and China. Elsewhere the picture was more nuanced with the UK FTSE100 equity index falling, perhaps reflecting the reality that the UK is still facing tariffs across most sectors – indeed, while UK Prime Minister Starmer referred to yesterday’s agreement as a “historic deal”, as it stands the UK is actually in a worse-off position than before the 2 April US tariff ‘Liberation Day’ Trump announcement.
UK-US trade deal … there are still tariffs for UK
Despite yesterday’s UK-US trade deal, there are still tariffs for UK. In autos, the latest 27.5% total tariff rate (made up of US President Trump’s extra 25% on top of the 2.5% that was originally in place) will now be 10% (so still 4x higher than before Trump took office in January), and only for a quota of 100,000 cars (above that volume, a 27.5% total auto tariff rate would kick back in – for context last year the UK exported around 102,000 cars into the US, so while the deal largely covers existing production for autos, in effect, there is an additional tax on any UK hopes to grow car exports into the US). Elsewhere, aluminium and steel tariffs were cut to zero. Crucially however, for most other sectors the universal base line 10% tariff rate that Trump has levied on all countries globally will also remain in force for the UK as part of this deal as it stands currently.
Bank of England
The Bank of England yesterday wrong-footed, for now at least, dovish hopes that they might accelerate the pace of interest rate cuts going forwards. While yesterday’s 25 basis points (bps) cut in the UK interest rate to 4.25%, from 4.50% previously, was considered by markets to be a foregone conclusion, the Bank was determined to be more balanced around the rate outlook – that was reflected in the split of votes among the Bank members behind yesterday’s cut – there was a 3-way split, with 2 votes for no change, 2 votes for a bigger 50 bps cut, and 5 votes for a 25bps cut, the latter which is what the Bank did.
What does Brooks Macdonald think
Even though UK government bond gilt yields rose on Thursday, the Bank of England probably has more interest rate cuts still to come. From the Bank’s own latest forecasts published yesterday, UK economic growth is mixed (with next year revised lower), unemployment rate projections are higher, private sector wage growth forecasts are flat to lower, and consumer inflation is now expected to be lower than previously assumed for every year of the Bank’s forecast horizon through to 2027. Drilling down to an interest rate forecast is tricky, but Bank governor Bailey yesterday said that market expectations for a terminal interest rate of 3.5% was “not unreasonable” – whether that level is hit later this year is probably the big question now, with markets appearing to be split on whether the Bank delivers 2 or 3 more 25 bps-cuts in 2025.
Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.
Please see the below update from Evelyn Partners regarding today’s Bank of England Monetary Policy Committee’s decision to cut interest rates by 0.25% to 4.25%:
What happened?
As expected by economists, the Bank of England (BoE) cut its base interest rate by 25 bps to 4.25%. The decision was made by a majority of 7 who voted for a rate cut, against 2 that wanted to keep them unchanged.
What does it mean?
While the macro picture has changed since the last Monetary Policy Committee (MPC) meeting in February to become more disinflationary, the BoE appears focused on cutting interest rates at a gradual pace of around one-quarter percentage point per quarter since it began easing last August.
This comes despite concerns over US trade tariffs and policy uncertainty that suggest downside risks to growth, a point made by the BoE governor Andrew Bailey at an Institute of International Finance event in Washington last month. Indeed, the latest PMI data indicates weak manufacturing and services sector activity. Subpar growth is feeding through to softer inflation data.
Furthermore, energy prices have also been trending south: the price of Brent crude oil is down nearly 30% from a year ago, while sterling appreciation against the US dollar should also act to reduce import prices somewhat. All these factors should put ease inflationary pressure in the near term.
Nevertheless, MPC members will be wary of cutting interest rates too quickly. First, it is not clear what impact US trade tariffs will have on inflation. Second, the latest nominal weekly earnings for the whole economy of 5.6% year-on-year (on a three-month moving average) is running uncomfortably higher than prevailing inflation. And finally, the latest YouGov survey of household inflation expectations has picked-up to 4%, its highest rate since October 2023.
Bottom Line
Looking forward, the MPC is expected to stick to gradual and careful guidance on interest rates by cutting once a quarter, as the risk of policy error remains high. Nevertheless, gradually lower rates should provide some insurance against downside risks to the economy and UK domestic stocks.
Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.
Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 07/05/2025.
Oil price hits lows as OPEC accelerates production
We examine potential reasons for OPEC producing 400,000 extra barrels of oil a month – and how this could help President Trump.
Saudi Arabia shifts OPEC strategy
Shortly after the ‘Liberation Day’ furore, OPEC (the Organisation of the Petroleum Exporting Countries) announced an increase in oil production. In many ways, it was the opposite reaction to what would normally be expected. OPEC increases energy production when energy is undersupplied or reduces it when demand for oil is weak (this usually happens when the economy is weak). It does this to prevent the oil price from falling too low.
OPEC is a cartel. It manages the oil price to ensure that oil producing countries make healthy profit margins. Unusually low demand or members producing too much oil are two reasons oil prices could be weak.
Since the ‘Liberation Day’ tariffs were announced, growth expectations have generally declined. Normally, you might expect that OPEC would reduce production in anticipation of weaker oil demand. Instead, it announced increased production immediately after the tariffs were announced; this week, it announced further increases. Why?
OPEC has been struggling to control the energy market because of new supply introduced from non-OPEC members. The U.S. is a big one since it developed shale oil. While OPEC restricts its own production to maintain high margins, it’s also ceding market share to higher-cost shale oil producers at the same time.
Despite OPEC’s efforts, the oil price has fallen, largely due to weak demand from China. OPEC may have decided that if it can’t maintain the margin it needs, then its next best option is to leverage its position as lowest cost producer, pump more oil, allow the price to fall and discourage further supply from non-OPEC members.
Market rally on the Trump Fold
Source: LSEG/DataStream
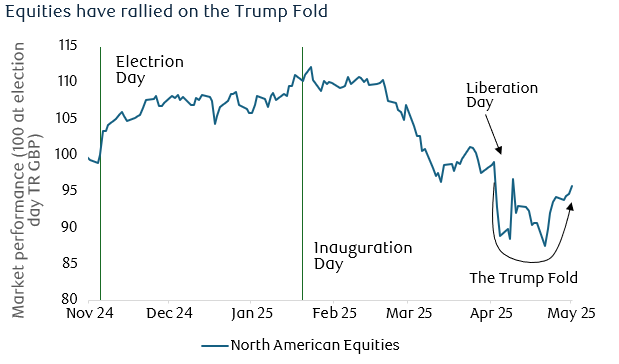
The early part of U.S. President Donald Trump’s second term has been challenging for stocks. Most notably U.S. stocks, which took their biggest hit when he shifted his rhetoric from “Make America Great Again” to “Make America Wealthy Again”. This coincided with his announcement on ‘Liberation Day’ tariffs, prompting a remarkable sell-off in global, particularly U.S., stocks.
Within a week, those tariff measures were partially walked back. Notably, the 90-day delay in the implementation of the individual tariff rates, affecting 60 countries, prompted a sharp rally in stocks. However, the president was keen to impress that the tough stance on trade was still in place by doubling tariffs on China. The situation has been chaotic ever since. Businesses have been in turmoil as they grapple with the measures and Apple announced last week that the measures would impose $900 million in additional costs this quarter. It presumably could have been worse, as the impact of tariffs was again diluted in response to a revolt from investors and business leaders. Consumer electronics were exempted, and although President Trump attributed this to the forthcoming additional measures on semiconductors, so far, those measures haven’t materialised. All of this has allowed a period of ‘announcement-calm’, during which the stock market has recovered most of the ground lost since ‘Liberation Day’.
By the end of Thursday last week, the S&P 500 had risen for eight consecutive days, a record run of strength. That still leaves U.S. stocks well below Inauguration Day levels, and the extent of the U.S. recovery is flattered when presented in local currency terms (i.e. U.S. dollars), due to the weaker dollar. Perhaps the leadership of the U.S. recovery has been a more significant factor.
Over this very short period, investors have used this weakness as an opportunity to get back into the exceptional U.S. companies that will benefit from the artificial intelligence (AI) revolution, a trend that will certainly outlast President Trump’s second term. Whether ‘Trumpism’ endures beyond the next few years remains less certain.
When will the economy weaken?
Source: LSEG/DataStream
Last week’s U.S. Q1 GDP estimate was weak, suggesting that the U.S. economy contracted by -0.1% in Q1 (-0.3% on an annualised basis). Although this might suggest that the tariff policy has been a failure, in truth, the headline weakness is quite misleading.
Anticipation of tariffs prompted businesses and consumers to stock up ahead of possible measures. Imports detract from GDP while exports add to it, so this front-running weighed heavily on GDP in Q1. Final demand, by contrast, was very strong, also reflecting front-running of tariffs.
Trade will certainly be more of a tailwind in the second quarter; however, the uncertainty and higher costs are likely to be an overwhelming headwind to both consumption and investment.
The economy is currently showing potential, despite business and consumer surveys suggesting otherwise. Consumer confidence, according to the U.S. Conference Board, has collapsed to a level last seen in the depths of the initial COVID-19 wave. Respondents expressed more negative views on the labour market, expected higher inflation, and perceived the highest risk of recession in two years.
Businesses responding to the Institute of Supply Management (ISM) Manufacturing survey were also downbeat. Decline in new orders slowed, suggesting that business activity continues. The anecdotal comments released alongside surveys have been telling. All ten issued by the ISM mentioned tariffs in a negative light, citing difficulty in finding non-Chinese sources for tariffed imports, and an inability to tender for business because of the uncertainty over costs.
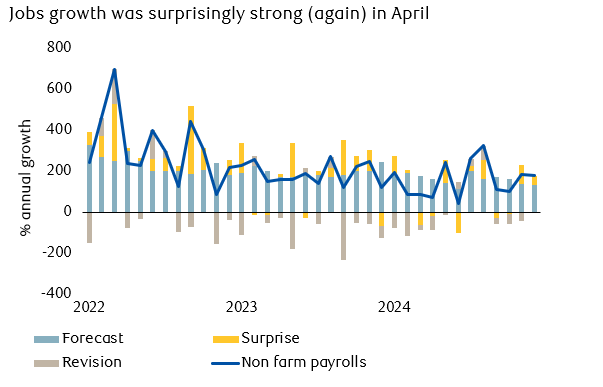
All eyes are on the labour market now. A fall in job openings reported Tuesday and a rise in jobless claims reported on Thursday, alongside the survey evidence listed above suggest the jobs market should be weakening. However, the official jobs report was a little stronger than expected. There were some negative revisions to previous reports, but forecasts now expect jobs growth to slow down to around 50,000 per month over the rest of the year.
The art of negotiations
Last week highlighted the different negotiating styles of the Chinese and U.S. administrations. We’ve previously described how Trump’s negotiating style aligns with aspects of his book ‘The Art of the Deal’ (despite allegations that he wasn’t particularly involved in its writing).
The key philosophy of ‘thinking big’ has been evident in terms of the measures used and, presumably, the concessions sought, although little substance has come from the negotiations so far. He has been aggressive, and outspoken, which are key tenets of ‘The Art of the Deal’ approach. One missing element has been a resolution. The book suggests that negotiations should be reconciled quickly, something that is unlikely to be possible in trade negotiations.
Perhaps most controversially, President Trump has actually made concessions. In general, his book suggests that concessions are unwise and can be perceived as a sign of weakness. However, he does suggest that a very aggressive negotiating stance can be moderated to make the opponent feel they have achieved something. It’s certainly conceivable that for many countries, reducing a 20% tariff to 10% could be perceived as a victory, despite being in a much worse position that they were just a few months ago.
China is now seeking to reduce a 145% tariff, which offers enormous scope for negotiation. According to Trump’s book, concessions should be given in return for negotiating wins, which has categorically not happened yet, it seems clear that the strategy has been at least partially flawed.
By contrast, China’s approach seems more consistent with Sun Tzu’s ‘The Art of War’. Ironically, despite being a military treatise, the text recommends avoiding conflict where possible. It takes a more strategic and measured approach, which seeks to win without fighting.
Last week, China sought to project a strong position, claiming not to be in talks with the U.S., while representatives of the White House were keen to concede that a deal and tariff reductions are possible; they’ve even suggested that current tariff rates are unsustainable. It seems to have been a public relations victory for China so far, but that doesn’t diminish its powerful need to persuade the U.S. to reduce taxes on trade with the richest economy in the world.
Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.
Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.
What has happened
The past 24-hours have seen more tariff trade war swings for investor sentiment. On the positives, it was confirmed late yesterday that US Treasury Secretary Bessent and US Trade Representative Greer will be heading tomorrow to Switzerland to hold trade talks with China’s Vice Premier He – that and separately, US President Trump yesterday promised an announcement that will be “as big as it gets” later this week, while Bessent said some “very good” offers had been made in trade negotiations by other countries. On the negatives, there are reports that the European Union (EU) are making detailed plans to hit US goods with tariffs if US-EU trade talks fail, while Trump yesterday said that “We don’t have to sign deals, they have to sign deals with us. They want a piece of our market. We don’t want a piece of their market.”
Oil prices
Oil price weakness has been something of a theme so far this year, notwithstanding a small bounce this week, in part as tariff-led economic growth fears have risen. Adding to downside risks, the Organization of the Petroleum Exporting Countries (OPEC) plus certain non-OPEC members including Russia (OPEC+) in their latest meeting last weekend agreed to accelerate oil production hikes. These increases in supply are designed to ultimately unwind post-COVID production curbs that were put in place to protect prices, but which have cost OPEC+ producers global market share. However, OPEC+’s latest production hike raises concern that such additional supply could lead to a global glut just as a global tariff trade war threatens broader economic growth.
China cuts a key policy interest rate
China’s central bank, the People’s Bank of China (PBOC) earlier today announced that it will be cutting a key policy interest rate, its 7-day reverse repurchase agreement (reverse repo) rate to 1.4% from 1.5% as well as separately lowering the reserve requirement ratio for banks. The measures announced should guide borrowing costs from the banks lower and release some extra monetary liquidity into the economy. This is because by cutting the reverse repo rate, the PBOC can boost monetary liquidity by making it less attractive for banks to deposit excess funds with the central bank – as a result, this encourages banks to instead lend more of those excess funds into the economy, increasing the overall money supply and promoting economic growth.
What does Brooks Macdonald think
Oil price weakness so far this year might be unwelcome news for energy producers, but it might be much better news for central banks. Oil prices can at times be a significant swing factor for the broader inflation outlook. At a time when tariff trade wars are risking higher price pressures as a result of increased trade friction in international trade, lower oil prices might help to keep a lid on inflation, and in turn might offer central banks some room for manoeuvre in being able to cut rates should economic growth falter.
Please check in again with us soon for further relevant content and market news.