Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below, todays Daily Investment Bulletin from Brooks Macdonald covering their thoughts on the overnight events in the Middle East:

What has happened

Markets have been rocked overnight by fresh Middle East geopolitical risk, with Israel launching air strikes on Iran’s nuclear and ballistic missile programme sites, and warning of more action to follow. Iran has already retaliated, sending drones into Israel and vowing further reprisals. With renewed fears of Middle East conflict emerging earlier this week alongside risks of a wider Middle East conflict, that has pushed the oil price higher – at one point overnight Brent crude US dollar oil prices were up around +13%, peaking at US$78.50 per barrel – for context, that marked a gain of around +20% from where prices were at the start of June at under $65 per barrel – at the current time, the Brent crude oil price has pulled back some of its latest move, and is currently trading up at around US$73 per barrel, up around +5% on the day.

Israel’s strike on Iran

As we said in our Daily Investment Bulletin only yesterday, with US President Trump growing less confident around the prospects of limiting Iran’s nuclear programme through talks, reading between the lines it suggested a higher risk of military action instead. The US overnight has claimed that Israel acted without US involvement or assistance – however, according to Israeli public broadcasts, Israeli officials notified the US before beginning the strikes. The United Nations atomic watchdog (the International Atomic Energy Agency) has said there are no signs of increased radiation at Iran’s main nuclear enrichment site, Natanz in central Iran – while there are reports that a number of Iran’s high-ranking military officials and nuclear scientists have been killed.

Market reaction

Unsurprisingly, markets are reacting in a risk-off move this morning, with equity markets lower, and safe havens, including US Treasuries, the US dollar currency and gold prices all higher earlier. For the UK FTSE100 equity index, the falls this morning appear to be limited, largely due to gains in oil major heavyweight stocks BP and Shell this morning following the higher oil price moves overnight. Prior to the events overnight out of the Middle East, yesterday had seen equity markets put in a solid session, with US equity indices up on the back of a weaker-than-expected US Producer Price Index (PPI) inflation report, echoing the weaker US Consumer Price Index (CPI) inflation data the previous day.

What does Brooks Macdonald think

Keep the latest oil price moves in context. Back in January, Brent crude oil prices were even higher, at over US$82 per barrel at one point mid-January. So far this year, for the most part, oil prices have been in a downward price-channel, as markets have reacted to increased oil supply from OPEC+ (Organization of the Petroleum Exporting Countries plus non-OPEC members including Russia), who have been continuing to reduce post COVID pandemic supply curbs, alongside broader economic growth concerns amid global trade tariff uncertainty. If history is a guide, conflict-driven higher oil prices usually subside as wider economic and supply/demand fundamentals reassert themselves – nonetheless, there will likely be unwelcome oil price volatility in the interim.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

13th June 2025

Team No Comments

EPIC Investment Partners: The Daily Update

Please see below, an article from EPIC Investment Partners providing a brief analysis of the UK economy following the recent GDP data release. Received today – 12/06/2025

The UK economy is exhibiting increasing signs of strain, with multiple indicators pointing to a marked downturn. The labour market, a key barometer of economic health, is under growing pressure. According to the Office for National Statistics (ONS), the unemployment rate has climbed to 4.6%, the highest level in four years, accompanied by weakening wage growth and significant job losses across critical sectors.  

This uptick in unemployment follows April’s policy changes, including an increase in payroll taxes and the national minimum wage, part of Chancellor Rachel Reeves’ latest Budget. Wage growth has also faltered, with average weekly earnings (excluding bonuses) rising just 5.2%, below expectations and down from 5.5% previously. Growth in private sector pay has been particularly subdued, with recent public sector pay deals providing only modest support. 

At the same time, consumer spending is showing signs of fatigue. Retail sales growth in May slowed to just 1%yoy, the weakest pace of 2025 and well below both the year-to-date average of 2.5% and April’s inflation rate of 3.4%, indicating a decline in real-term spending. According to the British Retail Consortium (BRC), lower consumer confidence is leading shoppers to cut back on discretionary purchases, particularly fashion and high-ticket items. While food sales remained resilient, the broader retail picture is increasingly fragile. 

Financial markets responded, sterling fell against the dollar, while expectations for a Bank of England interest rate cut shifted to September (from November).  

Attention now turns to Chancellor Reeves’ Spending Review later today, where a credible response to these gathering challenges will be closely scrutinised.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

12th June 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 10/06/2025.

Markets calm despite ongoing trade uncertainty

Recent events have fostered a surprising lack of market movement, despite ongoing trade tensions.

Chinese Tariff Truce

Source: LSEG Datastream

As we enter the summer period, it’s worth reflecting on what a hectic year this has been for markets. But more recently, there’s been a period of unusual calm. This isn’t a period of calm in which markets rally, we’ve essentially already experienced that. This has been a period in which markets have actually done very little.

There’s normally some kind of rotation taking place between sectors and styles at all times, but for the second half of May, the markets entered a bit of a holding pattern.

The calm began following the relief rally sparked by the deferral of the ‘Liberation Day’ tariffs and coincided with the de-escalation of mutual tariffs between the U.S. and China. Those events gave rise to the markets’ new favourite acronym TACO − Trump Always Chickens Out.

During this period of calm there has been plenty of news to potentially rock markets. The Trump administration has been stressing the challenges of reaching an agreement with China. It’s also trying to pass a bill that will allow it to impose taxes on foreign investments if other countries impose unfair taxes on the U.S. That bill, at least ostensibly, has been the cause of infighting within the president’s former inner circle. It’s been largely ignored by the equity market but has been causing anxiety for bond investors due to the bond issuance it would promise in the future. All the while the TACO accusation was brought to President Trump’s attention and this could prompt him to push back against it.

So, there’s been plenty to potentially worry the market over the last few weeks, but it has managed to cope with that anxiety for now. We can’t be sure why that is, but an obvious potential catalyst is the end of the deferral of those ‘Liberation Day’ tariffs, now just a month away.

Gold and Silver Prices

Source: LSEG Datastream

The de-escalation of trade talks doesn’t discourage the trend of central banks adding to their reserves of gold, which is likely to be a long and slow-moving phenomenon. However, gold has risen whenever trade fears have escalated and has slid back as they ease. This can be seen in the ratio of gold to other metals, most notably precious ones like silver.

The ratio of gold to silver has been rising over time because silver doesn’t have such an acute restriction on supply that gold does – for this reason, silver has tended to be a poor man’s gold in an investment sense. However, currently silver supply is quite limited, making it seem like an attractive metal in its own right. Therefore, with the ratio of gold to silver stretched by recent trade anxiety, there’s scope for a recovery in silver prices, which took effect last week.

Beyond this correction in the ratio, precious metals, in particular gold, should benefit from America’s abdication of its role of reserve currency as well as concerns over the expanding U.S. fiscal deficit.

The euro rally, despite falling relative interest rates, echoes previous market responses to political developments

The ECB has cut interest rates by 25 basis points, bringing the deposit rate down to 2%. Despite this, the ECB’s policy rate is now considered broadly neutral, and future rate decisions will depend on the evolution of the trade backdrop. The ECB has maintained its gross domestic product (GDP) forecast for the year but expects growth to slow down in subsequent quarters due to trade policy uncertainty.

The ECB’s stance is data-dependent, and it is open-minded about the direction of its next rate move. The labour market is tight, with low unemployment and moderating wage growth. Loan demand is picking up, and monetary policy is no longer considered restrictive. The deposit rate is now broadly neutral, and markets are pricing in one more rate cut this year.

The implications for investors are that the euro is likely to appreciate over the longer term, despite current bond yield spreads moving against it. The euro has been creeping higher, and some investors are questioning whether it can break out to higher levels. However, extraordinary developments such as the Trump administration’s policies can justify deviations from relative interest rate fundamentals. This happened before when the euro rallied due to populist governments failing to win European elections before it eventually fell again due to the victory by the Five Star Movement in Italy.

Longer-term, the path of least resistance for the euro appears to be up, driven by higher inflation in the U.S. compared to the Eurozone and a cheap currency relative to estimates of purchasing power parity. If Europe can avoid being at the centre of another crisis, it seems reasonable to believe that the euro rally has further to go.

Overall, investors should keep a close eye on the trade backdrop and the ECB’s policy decisions, as these will have a significant impact on the euro’s trajectory.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

11/06/2025

Team No Comments

M&G Wealth Weekly Market Commentary

Please see below article received from M&G Wealth yesterday afternoon, which provides an insight into market movements and the broader economic landscape.

This week’s highlights

  • Markets rise despite mixed economic data: stocks and bonds gained over the week.
  • US-China trade talks offer optimism: S&P 500 now up 20% from April lows.
  • Tesla tumbles: a heated exchange between President Trump and Elon Musk unsettled investors.

Market review

Early in the week, US economic reports pointed to challenges in manufacturing and services sectors. The Institute for Supply Management (ISM) Manufacturing Purchasing Managers Index (PMI) fell, signalling contraction for the third consecutive month and ISM Services PMI had its first decline in nearly a year.

The US labour market showed mixed signals. Job openings exceeded expectations at 7.4 million. However, a recent employment report showed a slowdown, with only 37,000 new jobs added in May – the lowest since March 2023.

US President Trump and China’s President Xi held a phone conversation aiming to ease tensions. While details on trade negotiations remained unclear, markets responded positively, with the S&P 500 briefly entering a bull market – up 20% from April lows.

However, momentum slowed later in the week following an exchange of sharp words between President Trump and Tesla CEO Elon Musk. Their disagreements ranged from recent spending legislation, past political ties and concerns over government contracts. Tesla shares fell 14.26% on Thursday.

Outlook

The economic environment has been resilient so far. The recent stumbling blocks posed to tariff implementation on the scale initially laid out, have offered a temporary reprieve for world leaders and policymakers. We expect markets to remain volatile as the legality of Trump’s tariffs moves into the spotlight, meaning nations may pause or pivot on their efforts to strike trade deals with the US.

Chart of the week

ECB reduces interest rates The European Central Bank (ECB) has reduced interest rates again, bringing the deposit rate down from 2.25% to 2%. This marks a significant shift, as rates have now been cut by half since their peak in September 2023.

The decision comes in response to declining inflation in the eurozone, which fell to 1.9% last month – below the ECB’s 2% target. Additionally, the central bank adjusted its inflation forecasts, lowering projections for 2025 and 2026 to 2% and 1.6%, respectively.

ECB President Christine Lagarde highlighted concerns about ongoing tariff uncertainty and its potential impact on economic growth, reinforcing the need for rate cuts. However, she also suggested that the ECB is nearing the end of its rate-cutting cycle.

What this means for you

Varying inflation levels and trade tariff uncertainty continues to influence market performance across the globe, strengthening the importance of maintaining a well-diversified long-term investment approach, rather than reacting to short-term market swings. By staying committed to carefully considered plans, investors can navigate through periods of volatility and uncertainty.

Please check in with us again soon for further relevant content and market news.

Chloe

10/06/2025

Team No Comments

Tatton Investment Management – Monday Digest

Please see below, an article from Tatton Investment Management analysing the key factors currently affecting global investment markets. Received today – 09/06/2025

Summer starts with less spring


Global stock markets edged close to all-time highs, but the Trump-Musk spat knocked Tesla shares – though thankfully not much else. The bust-up is probably less important than the week’s other political news: the UK Defence Review suggests tax rises, the Germany-US meeting went well, and US-China negotiations trundled along.

Stock prices were helped by lower bond yields – even though these came from weaker growth. The US’ non-farm payrolls (US jobs figures) came in relatively strong, but other US employment data look weak. We said before that companies were neither hiring nor firing – but the latter part is now threatened. The Federal Reserve will be watching the employment data closely, and markets now expect two rate cuts by the year’s end. Soft data didn’t spook equity investors, though, as it was only mild and bond yields have been the bigger concern lately.

German and French bond yields actually spiked this week – despite the ECB cutting rates. This was because ECB president Lagarde said the rate cutting cycle is nearly over, which markets took as hawkish on rates but fairly bullish on European growth. The euro rallied, as did sterling. Part of this is dollar weakness, but we should recognise UK and European strength (the best performing stock markets this year).

Dollar weakness is a concern for US assets. Capital has flowed out of the world’s biggest market this year due to higher risks. For international investors, the dollar is one of those risks. The S&P 500 is still firmly negative year-to-date for British and European investors, for example.

Risk-reward metrics (like Sharpe ratios) have shifted, leading non-US institutional investors to reallocate away from the US – as we said they would. These trends can reinforce themselves: capital outflows weaken the dollar, which increases currency risk, which, at the margin, forces more allocation away from US assets. Currency moves will be crucial to watch from here.

May asset returns review


May was good to global investors, with global stocks up 4.7% in sterling terms and all major regions in the black. Equity investors feasted on the so-called “TACO trade” (Trump Always Chickens Out) and Donald Trump’s promised tax cuts. The US was May’s best performer, up 5.3%, largely thanks to its tech sector gaining 8.6%.

US tax cuts led to debt fears in bond markets, however. This drove US treasury yields up substantially through the month, which caused a stock market wobble mid-month. Thankfully, the government bond sell-off didn’t crank up corporate borrowing costs (thanks to low issuance of corporate bonds), and better-than-expected data helped equities quickly recover.

UK government bonds were particularly hurt by higher US yields, losing 1.2% in May. Downing Street’s fiscal discipline message isn’t affecting its borrowing costs (which remain at the mercy of the US) but is arguably helping sterling strength. UK stocks rallied 3.8% last month and are behind only China over the last 12 months. The euro also strengthened against the dollar, a sign that the US-to-EU capital flow continues. Germany’s fiscal expansion is seen as positive – as it has much more room to issue debt – and Europe is the best performer year-to-date, up 12.8%.

China was the weakest region (+2.1%) in May but is still the strongest over 12 months, despite tariff threats and the government’s inability to properly stimulate its weak economy. Commodities were the worst performers but were still positive overall – up 0.6%. We take this as a sign of market liquidity and risk appetite, evidenced by the pullback in gold prices (which go up when investors are fearful).

The return of liquidity and risk appetite was May’s defining characteristic. Trouble bubbles away under the surface, impacting bonds and capital flow out of the US. But for now, investors seem happy to let them slide.

Earnings analysts are as uncertain as everyone else


American companies’ Q1 earnings were good, but strength was yet again focussed on the Magnificent Seven (Mag7 – Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia, Tesla). The Mag7 posted 30.2% year-on-year growth versus 8% for the other S&P 500 companies, and smaller companies struggled. Even the Mag7 has become more of a Mag6, with Tesla’s profits falling a miserable 40% year-on-year (and that’s before any of the Trump-Musk threats).

The Mag7 delivered some of the best surprises too – with Amazon, Alphabet and Meta beating earnings estimates. The communication services sector (including Alpabet and Meta) is now the only one with projected 2025 earnings higher than at the start of the year.

Corporate earnings expectations have been hit this year, falling 1% from January to April and another 2% after “Liberation Day” tariffs. Normally, positive earnings surprises like those seen for Q1 would push up future earnings projections – since companies are building from a higher base. But while the Mag7’s beat cranked up Q2 expectations, earnings beyond that are largely unchanged. This is, again, about tariffs. Apple has been particularly threatened by the White House, for example, and was one of the Mag7’s weaker earners.

Earnings analysts basing their projections on macroeconomic policy predictions is a little problematic. It’s a top-down approach, when earnings estimates are supposed to be bottom-up. It could certainly be positive for stocks: if companies are more resilient than expected or the TACO narrative prevails, earnings surprises would likely spur a rally. But you would always rather have precise earnings estimates. They are what stock valuations are based on, impacting investment decisions.

In other words, if analysts are influenced by the prevailing market narrative more than company specifics, it increases the chance that stock markets themselves are mispriced. This mispricing might work out for the best, but reliable information is better than unreliable information.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

09/06/2025

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, Brooks Macdonald’s Daily Investment Bulletin which highlights the key factors currently impacting global investment markets. Received today – 06/06/2025

What has happened?

Equity markets struggled for direction yesterday with positive and negative news flow creating a tug-of-war for investors. While market sentiment got a boost from a positive read-out of a telephone call between US and China Presidents Trump and Xi, against this there was an unexpected rise in weekly US initial jobless claims, hitting a 7-month high. Adding to downside pressure on markets, while the European Central Bank yesterday cut interest rates as expected, unexpectedly it laced the move with hawkish commentary saying that it was “nearly concluded” with the rate-cutting cycle. Later today, all eyes are on the latest (May) US non-farm payrolls employment data, due out at 1.30pm UK time – a Reuters survey of economists is looking for +130,000 jobs added in May, which if that is the number would be the smallest gain in 3 months.

Musk and Trump have a very public falling-out

A dramatic falling-out played out over social media yesterday between the world’s richest man Elon Musk and US President Trump. Musk’s Tesla share price plummeted -14% on Thursday, while Trump’s social media platform share price (Trump Media and Technology) dropped -8%. Trump said he was “disappointed” by Musk’s criticism of Trump’s tax and spending cut bill, while Musk said Trump would have lost the election without his support and responded “yes” to a suggestion that Trump should be impeached. Following Trump’s threat to “terminate” Musk’s companies’ government contracts, Musk has since signalled he might be open to a cooling-off period in his war of words with Trump.

ONS reporting error weakens confidence in UK economic data

The UK Office for National Statistics (ONS) yesterday admitted that Consumer Price Index (CPI) inflation data for April was overstated. The error arose from Department of Transport data where the number of vehicles subject to tax in the first year of registration was too high. It means that the annual all-items CPI reading for April should have been +3.4%, and not +3.5% as was previously reported. Nonetheless, the correct figure of +3.4% was still higher than the +3.3% that had been expected at the time and was still sharply higher versus the +2.6% reported in March. Despite the error, the ONS said it would not be revising the official published (now incorrect) figure. The next (May) monthly CPI print from the ONS is due out Wednesday 18 June.

What does Brooks Macdonald think?

Economic data quality is crucial. It is hard enough for businesses, consumers and investors to discern the economic outlook, let alone if the quality of the data cannot be trusted. This is not the first time the ONS has had data issues, but it is not a UK-only phenomenon – the US Bureau of Labour Statistics (BLS) announced only this week that it had “suspended CPI data collection entirely” in parts of Nebraska, Utah, and New York, due to government cutbacks resulting in fewer people and resources available to do all the statistical work necessary – in BLS parlance, it said that “current resources can no longer support the collection effort”. All in all, question marks around economic data quality and reliability add an unwelcome layer of uncertainty for investors to have to navigate.

Bloomberg as at 06/06/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

6th June 2025

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below, Brooks Macdonald’s Daily Investment Bulletin which summarises the key factors currently impacting global investment markets. Received today – 05/06/2025

What has happened

Wednesday saw global equities (as measured by the MSCI All Country World Index in US dollar price return terms) hit a fresh all-time record high for the first time since February earlier this year. Yesterday’s gains came about despite weaker US economic data, as investors instead appeared to focus on hopes that the data could boost chances for interest cuts later this year. That global equities have hit a fresh record is pretty impressive (albeit measured in dollars where the US dollar is weaker in recent months) given there is still significant uncertainty on the tariff policy outlook. Later today, the focus is on the European Central Bank (ECB) interest rate decision due at 1.15pm UK time, where an interest rate cut (which would be the ECB’s eighth cut in the current cycle) is widely expected.

US banking deregulation expectations

Yesterday saw Senate approve US President Trump’s pick of Michelle Bowman for the position of US Federal Reserve (Fed) vice-chair for banking supervision. Bowman, who has served on the Fed’s board as a governor since 2018, is expected to be a ‘light-touch’ advocate, in keeping with Trump’s plans for banking deregulation, and is expected to get such a programme underway – this would also fit with recent comments from US Treasury Secretary Scott Bessent who said last month that “the growth of private credit tells me that the regulated banking system has been too tightly constrained”. Amongst some of the possible banking deregulation measures under consideration, this could include a relaxing of the rules around setting banks’ capital buffer requirements, more co-ordinated and streamlined regulatory oversight, as well as quicker and likely more sympathetic regulatory views towards bank merger-and-acquisition activity going forwards.

US economic data buoys interest rate cut hopes

It seems we might be back to a ‘bad news is good news’ mindset in markets – this is the idea that bad economic news is good news for markets as it might buoy hopes for interest rate cuts. The weaker economic news yesterday came in two parts: first, an ADP Research Institute report of US private payrolls saw hiring up by the smallest increase in over 2 years, since March 2023; second, the US ISM (Institute for Supply Manufacturing) Services survey for May dropped below the 50-midpoint mark that splits the month-on-month economic picture between expansion versus contraction – it dropped to 49.9 in May from 51.6 in April – in addition, as the ISM chair Steve Miller commented, survey respondents “continued to report difficulty in forecasting and planning due to longer-term tariff uncertainty”.

 What does Brooks Macdonald think

It will be interesting to see if any US-led banking deregulation spurs similar moves in other countries as banking regulators around the world will likely come under pressure to avoid suffering undue competitive disadvantage for their own home-grown banking champions. As a counter to this, there are valid arguments that too much banking deregulation might weaken the counter-cyclical ability of banks to weather economic downturns, which some government policy makers might be more cautious around relaxing. Either way, in the near-term, any banking deregulation is likely to boost banks’ lending growth outlooks and with it set an improved earnings outlook for the banks as well, providing another tailwind for risk-asset markets more broadly.

Bloomberg as at 05/06/2025. TR denotes Net Total Return.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

5th June 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 03/06/2025.

Trump tariffs face setback as markets calm 

U.S. trade court challenges Trump’s tariffs, potentially easing trade tensions – but a longer fight may lie ahead.

U.S. Court of International Trade strikes down tariffs

There have been dramatic legal twists this week in the ongoing saga over President Donald Trump’s trade tariffs. The U.S. Court of International Trade (CIT) ruled that the Trump administration’s ‘Liberation Day’ tariffs were illegal, exceeding the president’s authority under the International Emergency Economic Powers Act (IEEPA). As a result, the 10% universal tariff, 20% fentanyl-related tariffs on China, and 25% fentanyl-related tariffs on non-compliant imports from Canada and Mexico (under the U.S.-Mexico-Canada Agreement) were all set to be removed. 

That would have led to a reduction in the effective U.S. tariff rate, which would likely remain at 6.5% instead of rising to 15%. It would mean lower tariff revenue, now estimated at around $115bn annually, rather than the previously estimated $360bn. Tariff revenue offset some of the planned increases to borrowing, which are driven by the administration’s plans to roll over and extend tax cuts. The U.S. budget deficit would reach around 7% of gross domestic product (GDP) under the House of Representative’s plan with a lower tariff income, rather than remaining near 6% of GDP with a higher tariff income.

However, plenty of uncertainty remained over this. The president’s authority under IEEPA was deemed an overreach, but he could still use Section 232 investigations, Section 301 tariffs, or other (mostly untested) options to impose tariffs on trading partners.

Section 232 allows the president to impose tariffs on imports that threaten national security, and it was this route he used for steel, aluminium and, more tenuously, car imports. Section 301 allows the U.S. Trade Representative (USTR) to impose tariffs on imports from countries that engage in unfair trade practices. That seems the most appropriate means for reciprocal tariffs, but it requires an investigation into those practices. The USTR did initially conduct an investigation. However, the eventual tariffs were imposed based on trade balances rather than the investigation, and no country was exempted.

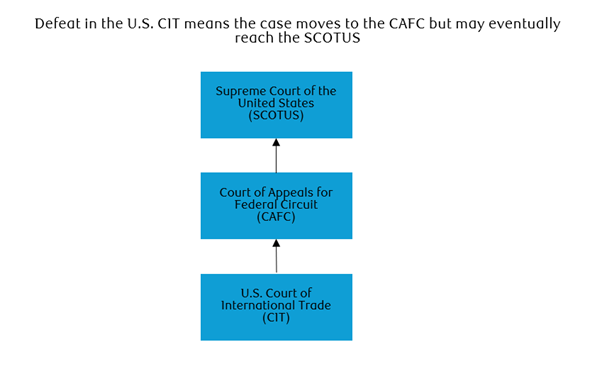
Supreme Court

The initial CIT decision was seen as good news for the stock market and the U.S. dollar. However, gains faded. There are a few reasons for caution. The most obvious being the risk that the decision could be challenged, which it was.

A U.S. federal appeals court granted a temporary reprieve to the Trump administration’s global tariff plans on Thursday, pausing the CIT’s ruling. The U.S. CAFC issued a stay “until further notice,” effectively putting on hold the CIT’s decision that had blocked the tariffs and given the administration ten days to unwind the levies.

There will now be a further pause until 9 June, when the CAFC will decide on the request for a longer-term stay.

If the Court of Appeals reinstated the CIT decision, it wouldn’t be good news across the board. The additional fiscal pressure due to lost tariff income would put the public finances under more pressure, which would be bad for bonds and could undermine stocks. It also adds to the narrative that the administration is being curtailed by ‘unelected judges’ sowing more division within a polarised nation. The case would likely then go to the U.S. Supreme Court, which currently has a majority of conservative members. Sky-high trade uncertainty would continue to undermine business activity and companies would opportunistically use any temporary stays of the tariff measures to bolster inventories, causing trade to be lumpy and unpredictable.

American consumer sentiment improves

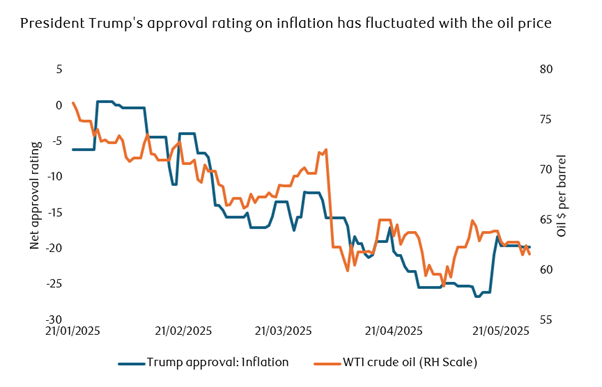
U.S. consumer confidence improved during May. This reflects a greater sense of positivity that has developed in the U.S. and that’s reflected in a stabilisation of President Trump’s approval rating.

Trumps approval rating

Source: LSEG Datastream

The natural path of presidential popularity is downward, and President Trump was becoming unpopular at a historically fast pace. However, his approval ratings have steadied and recovered during May. This likely reflects the deferral of the highest tariff rates and the prospect of trade deals being announced (like the one with the UK).

Tariffs have yet to wreak the kind of havoc media headlines might have suggested, and other factors have offset them. Most obviously, the price drop in energy markets has offset price inflation in other categories.

OPEC agrees to cut oil production

Last week, the Organisation of the Petroleum Exporting Countries (OPEC) agreed to cut oil production in the future. However, the latest near-term plan to increase production was approved over the weekend.

These increases are a means for Saudi Arabia to punish its fellow cartel members for breaking previous production limits. An increase in production will weigh on the oil price, hurting the finances of oil producing companies and nations. However, it will be cheered in the U.S., where the lack of tax on gasoline means that volatile swings in energy commodity markets are felt directly in the pockets of U.S. consumers. Recent falls will feel very much like a tax cut for many Americans, boosting growth and reducing inflation.

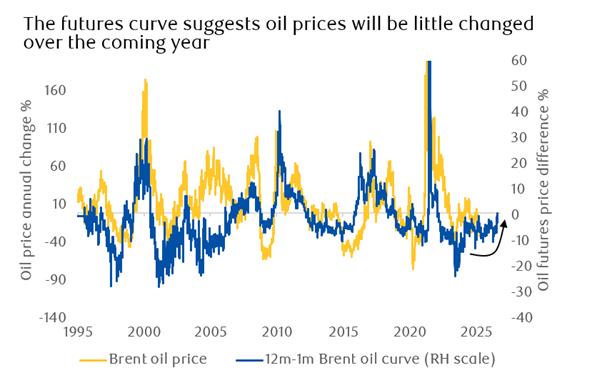
Anticipated shortages of crude oil due to production cuts from OPEC and possible disruption in the Middle East had caused the oil futures curve to become ‘backwardated’ (futures prices are below current oil prices). Usually when this happens, it indicates energy prices will be weaker in the future, as seen in this instance. Oil prices fell as OPEC temporarily expanded production, which it’s poised to do again this weekend.

The news for energy investors has been poor due to these production increases. But with a flat-to-upward sloping curve, the outlook seems more balanced. Energy stocks are a useful component for portfolios that are otherwise vulnerable to the growth and inflation impact of an oil price spike.

Oil prices

Source: LSEG Datastream

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

04/06/2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides a global market update for your perusal.

What has happened

Markets had a mixed first-trading day of the new month yesterday. The US S&P500 equity index rallied late in the day to finish up +0.41%, as strength in semiconductor stocks led the market higher despite weaker manufacturing survey data. Elsewhere, the pan-European STOXX600 equity index closed marginally lower at -0.14%, closing before that late US intraday rally had kicked in, while Asian equity markets overnight are mostly higher (all in local currency price return terms). Finally – breaking news this morning that the Dutch government has collapsed after the far-right Freedom party quit the governing coalition citing disagreement over migration and border control policy – if a new coalition cannot be formed, it is expected to trigger a snap general election – the timing is unfortunate given the Netherlands is due to host world leaders for a NATO (North Atlantic Treaty Organization) summit later this month.

US manufacturing data underwhelms

The latest US Institute for Supply Management (ISM) manufacturing survey for May was released yesterday. In it, the headline print was 48.5, a six-month low; it was down month-on-month from April’s 48.7, below 49.5 expected, and below the 50-midway point that divides between month-on-month surveyed economic activity contraction versus expansion. Of particular note, within the data, the imports index sub-component fell to 39.9, from 47.1 in April, below its low point during the Covid pandemic and at a level last seen back in May 2009 when the US economy was coming out of the 2008 Global Financial Crisis.

China manufacturing data weaker

Earlier this morning, China has released its own latest manufacturing survey activity data for May. The Caixin/S&P headline print was 48.3, below 50.7 expected, down from 50.4 in April, marking the lowest reading since September 2022, and the first sub-50 reading since September last year. The weaker print in part reflects a drop in the new export orders sub-component, which fell for the second month in a row and was at the lowest level since July 2023.

What does Brooks Macdonald think Tariff uncertainty between the US and China, triggered by US President Trump’s 2 April “Liberation Day” announcement, is already starting to show up in the data – as evidenced by weaker China export and US import data, respectively. Given the recent 90-day pauses in the most extreme parts of Trump’s tariffs, it will be interesting to see whether there might be a subsequent bounce-back in these export and import readings in the coming months. However, it suggests that even if this is the case, there will still be a high level of uncertainty around the range of economic forecasts, and which will likely keep markets on edge for the time being.

Please check in again with us soon for further relevant content and market news.

Chloe

03/06/2025

Team No Comments

Tatton Investment Management – The Monday Digest

Please see the below article from Tatton Investment Management detailing their discussions surrounding the ongoing Trump Tariff saga and how trade markets are responding. Received this morning 02/06/2025.

Complacency or checks and balances

The pullback a couple weeks ago has proved just a blip, thanks to the TACO trade (Trump Always Chickens Out) and a US trade court ruling Trump’s tariffs illegal (though the ruling was quickly suspended). Markets were happy but the previously “Mr Nice Guy” president was furious.

So we expected and got some Nasty Trump. On Friday, steel and aluminium tariffs were raised from 25% to 50%, probably signalling a greater focus on sectoral levies. While there is probably more internal logic to a sector-based approach, this makes country-based negotiations generally more complicated and certainly disrupts current talks. Deadlines are unlikely to be hit.

The start-date for the increase is Wednesday but, given his beef with the chicken jibe, there is virtually no hope of a Trump back-down.

The end of the Q1 US earnings season has been resilient. Nvidia continued to show the AI boom is driving profit growth. Meanwhile, US consumers are still showing some confidence and previous recessionary signals have faded. This helped credit spreads come down and financial conditions ease. The main problem now is that economic strength will prevent the Federal Reserve from substantially cutting interest rates – especially since companies are still retaining employees.

It’s notable that markets took the court’s tariff ruling so well, considering bond investors have been fretting about government debt. Tariff revenues are necessary to fund Trump’s tax cuts, and that’s why the Republican-controlled Congress will almost certainly hand tariff-setting power back to the president.

Unlike the US, the UK is signalling some fiscal discipline but a little less so. Everyone expects tax rises to fund the budget gap, and Reeves intends to keep to the rules – except that she might change those rules to allow more investment spending, given that the IMF helpfully suggests she cuts herself some slack. Any such change will give the UK a one-off boost, raising overall debt levels and increasing probably, marginally, increasing the interest burden. Nevertheless, on balance, the policy mix is likely to improve long-term stability, helping rate expectations and sterling. It’s just unfortunate that our borrowing costs are still heavily tied to the undisciplined US.

As for the fights a wounded Trump might pick, the Fed independence question could rear its head again. The Supreme Court recently suggested the president could fire who he wants, but curiously signalled an exception for the Fed. Jerome Powell shouldn’t get too comfortable though, as many in the White House are looking to test the bounds of executive power.

Meanwhile, China’s economic weakness is being taken as evidence that Beijing might play nice – but this might be mistaken. Beijing could well replace economic prosperity with nationalist expansionism, like a rumoured Taiwan blockade in the autumn.

But markets are more focussed on the positives. We hope that’s a good sentiment sign, rather than complacency. 

The end of US exceptionalism?

By “American exceptionalism” we mean the dominant of US asset performance over the last decade and a half, particularly in stocks. This shouldn’t be confused by the political theory of American exceptionalism – though the shared name is no accident; both about people believing that the US is exceptional. This has manifested in US assets being the best and safest earners in tangible (Sharpe ratio) and intangible (reserve currency safe haven, stable business-friendly government) terms. We’ve written before about how the US’ current account deficit typically returns as a flow of dollars into its asset markets. That, combined with US businesses’ focus on high profit industries, has led to corporate profits and equity valuation outstripping the world.

But Trump’s erratic policies are undermining both pillars of American exceptionalism: high returns and low risks. His obsession with balancing the trade deficit would undermine the flow of dollars back into asset markets, but even without that the uncertainty is preventing business investment and souring consumer sentiment – which dampens long-term returns. That uncertainty also makes US assets riskier, like the spike in volatility we saw post “Liberation Day”. It’s telling that the dollar has not recovered in line with US stocks recently, suggesting the safe haven status has been weakened.

The end of US exceptionalism doesn’t mean bad returns; the US economy is too resilient for that, and ‘buy the dip’ mentality is too strong. But it means returns will be less world-beating. That’s a problem for American companies – as their high stock valuations depend on capital inflows which have already started reversing this year. We expect that trend to continue, as long-term institutional investors reduce their portfolio allocations to the US. This might only be a marginal change – but a marginal change on such a huge part of global markets means a big impact on global markets.

China’s Belt and Road

US trade isolationism has many wondering if China could capitalise – perhaps through its Belt and Road Initiative (BRI). More than 150 countries have signed BRI agreements with China, which typically provides capital and labour for overseas infrastructure. Westerners often consider the BRI a foreign policy tool, but it was originally a solution to economic imbalances: China had too much capital and construction capacity, but needed access to materials.

Some accuse Beijing of “debt trap diplomacy”, as BRI agreements are opaque and have left poor countries facing high debt payments. Foreign policy experts don’t find this accusation credible, and many BRI agreements have been mutually beneficial – particularly with Latin America, which now trades more with China than it does the US.

Beijing would struggle take advantage of US isolationism, though, and BRI investment has slowed in recent years amid an economic downturn. Beijing domestic stimulus programs take precedence over building trade ties. The trade ties China is building seem mostly practical – ‘connector’ countries on route to the US.

Cutting off China is also part of the US’ plan – as seen in Panama abandoning its BRI deal after a visit from Washington. The Trump administration also made sure to include anti-China measures in its trade deal with the UK, and is reportedly planning to do the same for any EU deal. The US wants to force its trade partners to chose between the world’s two largest economies.

There’s no guarantee everyone will pick America, of course. Brazil’s Lula recently declared he wants “indestructible” relations with China, at a conference of 33 Latin American and Caribbean countries in Beijing. President Xi notably promised to back Panama against US threats at that meeting, showing how the US’ hard line could backfire. A Chinese-dominated world trade order is unlikely but, amid US aggression, many leaders will like the sound of Xi’s promised multipolar world.

Please continue to check our blog content or advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

02/06/2025