Hot off the press, I’ve just come off a webinar update from Prudential notifying us of the following positive Unit Price Adjustments (UPAs):
Series E only
PruFund Growth + 2.58%
PruFund Risk Managed 4 + 3.00%
PruFund Risk Managed 5 + 2.56%
The underlying unsmoothed assets were tested against the smoothed prices, the corridors, at 10.56 this morning.
You might ask why we have different UPAs for the different versions of PruFund? For the following reasons:
Different asset mix
The starting position
Different smoothing limits
The last point, different smoothing limits, doesn’t apply to the three funds we use noted above. The monthly smoothing limits in use for the funds we use is 5%.
Please see this link for details on how ‘smoothing’ works:
Brewin Dolphin’s weekly market update, emailed on 23/06/2020 as below:
Global shares rebounded last week but have still not made up for the losses incurred in the previous week’s sell off. Equity indices in the US rose yesterday and Asian markets were flat or slightly up, while in the UK and Europe, share markets closed down. However, markets got a boost today after President Trump said that the Phase 1 trade agreement with China was still “intact”. As a result, Asian markets closed higher on Tuesday, while equities in the UK and Europe were heading up in early trading.
Last week’s gains*
FTSE100: 3%
Dow Jones: 1%
S&P500: 1.85%
Dax: 3.2%
Nikkei: 0.77%
Hang Seng: 1.4%
Shanghai Composite: 1.6%
*Data to close on Friday 19 June
Virus treatment breakthrough
The positive news on the virus front was that Dexamethasone, a cheap, widely available corticosteroid significantly reduces death rates in severely sick Covid-19 patients. Sadly, this doesn’t slow transmission and is therefore unlikely to materially affect the willingness of policymakers to allow a full resumption of economic activity.
Cases rising globally
And there wasn’t much more good news on the virus front. The big picture globally has not changed; the trend in new cases remains up, driven by increasing numbers in emerging countries such as Brazil, India, Pakistan, Mexico, Saudi Arabia, Bangladesh, Indonesia and South Africa.
Perhaps the most worrying growth is in the southern states of America where hospitalisations are beginning to put real pressure on ICU capacity in Alabama and Arizona.
A new outbreak in Beijing has hopefully been rapidly suppressed, albeit at the cost of intensified lockdown efforts in one of China’s most important cities.
The trouble with easing lockdowns…
In Europe case numbers have stopped falling and, as efforts have switched towards reopening the economies, there has been a clear failure to decisively suppress the virus.
This is particularly marked in the UK where we are less than two weeks away from the Fourth of July, when bars and restaurants could be allowed to reopen. Boris Johnson is due to make an announcement on the reopening of parts of the hospitality sector this week.
UK case numbers have stopped falling which must make it difficult to proceed with lifting lockdown at anything other than a very cautious pace.
Wall Street not so far from Main Street
Whilst there is a lot of scepticism about how the recent rally in markets is disconnected from the real economy, our research shows that, in the US at least, the retail sector has proven to be freakishly well-aligned with the stock market after rebounding strongly in May. Where it is disconnected is further upstream, with industrial production barely staging any recovery at all.
US Retail sales vs S&P 500 Source: Refinitiv Datastream June 2020
Chinese stimulus
After holding off from their traditional recipe of credit and infrastructure growth, the Chinese authorities have found themselves resorting to that playbook again. Excavator sales have picked up as fixed asset investment by state owned enterprises has begun outperforming private sector investment, just as it did during 2016. Money supply growth has been picking up and the authorities are particularly keen to see funds deployed to Chinese small and medium sized enterprises which account for 80% of Chinese employment.
UK asset purchases to slow down
It is far from clear how the Bank of England would react to supply shock-induced inflation, but for now the policymakers remain in reasonably dovish mood. The Bank kept interest rates unchanged last week but increased its asset purchase target by £100bn. However, it is spreading that out over the remainder of the year, rather than the next three months, marking a marginally more hawkish announcement than had been expected.
That saw a rise in gilt yields as it means net issuance (i.e. bonds not bought by the Bank of England) is likely to be higher over the coming three months, although we don’t yet know how evenly the Bank will spread out its purchases. We think there may be modest upside for yields, notwithstanding the Bank’s generally dovish mindset. Recent movements in commodity prices, the rally in oil and a slight pickup in economic activity would all be consistent with rising gilt yields.
Pull out quote suggestion “UK case numbers have stopped falling which must make it difficult to proceed with lifting lockdown at anything other than a very cautious pace.”
Capital and income from it is at risk.
Neither simulated nor actual past performance are reliable indicators of future performance.
Performance is quoted before charges which will reduce illustrated performance.
Investment values may increase or decrease as a result of currency fluctuations.
The information contained in this document is believed to be reliable and accurate, but without further investigation cannot be warranted as to accuracy or completeness.
A good input from Brewin Dolphin with regards to the global shares rebounding last week. The weekly market updates from Brewin Dolphin are useful given the current volatility we are experiencing.
Keep checking back for regular up to date blog posts.
Please see the below investment outlook received from J.P. Morgan today (Tuesday 23rd June):
In Brief
In early June the market was pricing in a V-shaped recovery from the pandemic-driven economic contraction. We expect the recovery to be more gradual, with a few stop-starts along the way. Extremely low interest rates will help, but unemployment and corporate deleveraging could be a drag on growth.
The extent of near-term uncertainty, as well as the potential for political risk to mount as we approach the US election, could generate more market volatility.
For individual market sectors, the outlook depends on the path of the pandemic. If a full and sustainable reopening of the economy becomes possible, we may see a further rally for the most beaten-up sectors, coupled with a style rotation. For now, we believe it makes sense to maintain a nimble approach, with a focus on quality and an eye to ESG risks.
Low-risk options for income seekers are increasingly scarce. Rather than stretching for yield, investors may be better off being selective within fixed income and using a wider range of income-providing asset classes, including real assets for those who can accept lower liquidity.
Developed market government bonds look less and less likely to play their traditional roles of providing income and protecting portfolios in periods of market stress. Investors may need to look beyond the traditional 60:40 portfolio, with a greater role for alternatives and flexible fixed income strategies.
No one predicted that in the first half of 2020 the world’s economies would be brought to a virtual standstill by a global pandemic. Even had we have known the virus was coming, we would not have predicted that by mid-year the S&P 500 would have managed to climb back above 3000 (EXHIBIT 1).
We have global policymakers to thank for the market’s resilience. According to current analysts’ expectations, the policy response has helped one-year forward earnings expectations to find a floor and start to improve. In the sharp rally since 23 March, markets looked to be pricing that the combined actions of governments and central banks in recent months will have successfully absorbed the economic losses of Covid-19 to engineer the perfect V-shaped recovery (EXHIBIT 2).
While the policy response has been commendable, we believe the market’s expectation of the recovery in early June was too optimistic. It’s not that we believe people will permanently change their behaviour – we are social animals, after all. We just think it will take a little longer to get back to full normality.
Chief among our concerns is that the virus itself may linger and some need for social distancing will remain, in countries such as the US and UK, at least. In addition, high unemployment and a dramatic increase in public and private debt may serve to restrain spending in the recovery. We may also be at the beginning of a period of difficult political fallout as politicians seek to apportion blame for the crisis. The US election of 3 November could have important market implications. With the UK having left the EU but not yet having secured a new trade deal, Brexit might also – once again – generate volatility.
In summary, we acknowledge that the commitment from governments and central banks shouldn’t be underestimated. And, if more stimulus is needed, it will come. This makes us cautious about being underweight risk assets. But we need to see that policy action is influencing fundamentals. Valuations and uncertainty around the economic and earnings outlook make us cautious about advocating an overweight position in equities. We therefore think investors may benefit from having more than one toe in this rally, but not from jumping in with two feet.
In what follows, we provide greater information on our view of the shape of the recovery. We then consider three investment themes for the second half of the year:
1) Considerations for investors in the near term, given uncertainties and potential volatility
2) Options for investors in need of income
3) Rethinking a 60:40 portfolio in a world of zero bond yields
WHAT SHAPE WILL THE RECOVERY TAKE?
As shutdowns are eased around the world, forecasters are debating the likely shape of the recovery. The optimists point to a V-shaped recovery, the pessimists L-shaped, and the cautious look for something less linear, such as W, U or √.
In truth, it is very difficult to know at this stage. The risks aren’t black swans, they are known unknowns, but we simply don’t have enough information at this stage to form our judgment.
The first set of known unknowns relates to the virus itself. As the economic and fiscal costs have become apparent, politicians have hurried to ease shutdowns, whether the infection is under control or not. It is possible that the combination of a degree of ongoing social distancing, track and trace systems, and better hygiene practices will mean that the reopening happens without a reacceleration in infections. But there is also a risk that the infection rate will pick back up. Governments may be reluctant to re-impose shutdowns in such a scenario, but there will still be economic costs if people choose to socially distance voluntarily (EXHIBIT 3).
We are closely tracking how the virus progresses as well as using high frequency data to gauge the extent to which economic activity is normalising (EXHIBIT 4). To find the latest statistics on these, please refer to our On the Minds of Investors piece, Monitoring the global impact of Covid-19, which is updated twice a week.
As the weeks and months drag on, the more lasting consequences of the recession will become more evident. Policymakers globally have made a gallant attempt to limit the impact and absorb the losses of Covid-19. Grants and subsidies aimed to shift the losses on to government balance sheets. These, in turn, were shifted to central bank balance sheets as asset purchase programmes were expanded to absorb the additional issuance. Governments have been able to issue record high levels of government bonds, at record low interest rates.
Furlough, or short-shift schemes have been the cornerstone of the policy response in Europe (EXHIBIT 5). However, unemployment has still risen in the UK. The moves on the continent of Europe have been more moderate, but we suspect this is flattered by people not categorising themselves as unemployed because they are not actively looking for work due to either a need to look after children or a choice to remain socially isolated.
In the US – which hasn’t adopted widespread furlough schemes – unemployment rose to 14.7% in April though came down slightly in May to 13.3%. We would be considerably more worried about a double-digit unemployment rate were it not for the fact that the US social safety net has been made considerably more generous. Indeed, estimates suggest that 75% of those that have lost work are in fact better off given the additional USD 600 a week that has been added to unemployment benefits. This boost to benefits is set to expire on 31 July and, though an extension of some sort looks likely, it is likely to be less generous. We are therefore monitoring labour market data closely to gauge any shift in unemployment from those currently classified as temporary to permanent (EXHIBIT 5).
What will be the lasting consequence of higher levels of public debt? Is a new wave of austerity ahead? Public sector pay and benefit freezes – which were an important component of the spending restraint in the last expansion – seem unlikely given the degree of austerity fatigue in the population. Wealth taxes may be appealing given the resilience of asset prices, but these policies run into the practical problem that much of people’s wealth is stored in housing assets and held by individuals that are asset rich and income poor. One off ‘Pigouvian’ income taxes on higher earners are also being touted. We see it as more likely that finance ministers will forge ahead with plans to tax the large multi-nationals that obtain tax advantages by choosing favourable domiciles.
There is one global debt-reducing strategy we see as almost inevitable: interest rates will be held down for the foreseeable future. One suspects that policymakers are hoping for a repeat of the post-war period, in which a combination of yield curve control and financial repression kept the interest rate below nominal growth and helped erode government debt as a percent of GDP (EXHIBIT 6).
Lower interest rates will help corporates, which, on aggregate, have also experienced a significant rise in debt as a result of Covid-19. While we don’t expect governments to focus on deleveraging, the same may not be said for the corporate sector. Corporate deleveraging may constrain investment spending and employment growth and, in turn, the economic recovery.
So what is the letter most apt to describe the economic recovery? Our standard alphabet might not suffice but, in our view, expecting a symmetrical V is too optimistic. The recovery is likely to be more gradual, with a few stop-starts along the way. All the while, investors should be mindful of some sizeable tail risks lurking.
One such risk is China’s relationship with the world in the wake of Covid-19. Our opinion is that de-globalisation is easier (politically) said than done. China is highly integrated in global supply chains. As the 2019 trade war demonstrated, it is very hard to reduce trade links without causing significant economic harm in western economies. However, it does seem likely that China will come under scrutiny for regulatory standards, which may in turn raise inflationary pressures. Despite the economic realities, rhetoric towards China may intensify for short-term political reasons.
Nowhere is this more evident than in the US, which enters full election mode in the coming months. At this stage it is still difficult to say anything definitive about who will win, whether the victor will have full control of Congress, or the impact on markets.
The top priority for whoever emerges successful will be to manage the recovery as the economy restarts in earnest in 2021. Tough choices will need to be made about whether to push on with further stimulus or to try to tighten the purse strings as the recovery takes hold. President Trump had already flagged his desire for a second round of tax cuts prior to Covid19, but with US national debt-to-GDP now set to rise above 100% this year, further corporate tax cuts could face greater opposition. While Trump is yet to lay out a clear agenda for a second term, the tough-on-China and tough-on-trade stances that were at the core of the 2016 Republican campaign will remain a key tenet of his approach.
For the Democrats, as the most left-leaning candidates exited the primary race, so did their policies. Yet it is clear that presumptive nominee Joe Biden’s vision for corporate America is still very different to that of President Trump. Two topics that investors will need to monitor closely are a proposal to use anti-trust legislation to clamp down on ‘Big Tech’ and plans for corporate tax changes. Biden’s campaign team has also been keen to emphasise its candidate’s tough-on-China credentials. Historically, escalating trade tensions have favoured the higherquality US stock market relative to other regions, but a ramp-up in pressure on the tech titans would pose risks to US market leadership given the high weights to the technology and communication services sectors in US indices.
The second half of the year may therefore put us in the unusual position in which the political risk premium may be higher on US assets than on those of continental Europe, where the signs look increasingly positive. Though it still needs to be ratified by all EU member states, the European Recovery Fund is a significant step forward. Not only will it provide invaluable short-term help for countries like Italy but it provides a strong signal for the long term with regards to the fiscal integration that is much needed to complement the monetary union.
If the recovery in the US lags due to lingering Covid risks, and perceptions of political risk change, we could see downward pressure on the dollar.
CONSIDERATIONS FOR INVESTORS IN THE NEAR-TERM GIVEN UNCERTAINTIES
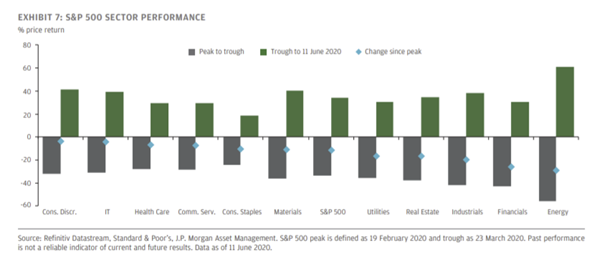
While the S&P 500 suggests a V-shaped recovery is priced in, at the sector level the narrative is more nuanced. From the start of the year to the S&P 500 trough in March, some of the most obviously affected sectors were hardest hit. Meanwhile, the likely winners from people remaining at home, other than for their food shop, outperformed.
The bounce-back since March has included some of the worst performers during the sell-off (EXHIBIT 7). For example, energy, autos, clothing retailers and restaurants have all outperformed during the rally, presumably on hopes of a partial rebound in activity as the economy starts to reopen. But some of the perceived beneficiaries of a world with more working and shopping from home, such as home improvement retailers, tech companies and industrial (including warehouse) properties have also rallied strongly. Meanwhile, despite improvement from their lows, airlines, hotels, department stores and retail properties remain among the weakest performers year to date.
What are the risks and opportunities from here under different potential scenarios:
Scenario 1: A full and sustainable reopening of the economy with social distancing no longer required. The most beaten-up sectors could rally further, while the sectors that have gained the most could be vulnerable to profit taking and rotation into cheaper companies as it becomes clear we won’t all work and shop from home forever. This would also likely coincide with a style rotation from large cap to small.
Scenario 2: An acceleration in infection rates leading to renewed shutdowns. At least part of the rally since March could reverse for most sectors, but those most exposed to further shutdowns could suffer the most as solvency concerns increase.
Scenario 3: Partial reopening of the economy but with some social distancing remaining in place. Sectors that might be able to reopen with some social distancing, such as department stores, autos and energy, could benefit further. Airlines, hotels and dine-in restaurants could struggle as solvency concerns increase. The most expensive stocks among the current winners could also suffer from valuation deratings and earnings disappointments, as unemployment remains elevated.
Which scenario plays out depends largely on the path of the virus itself, which is unknown. Given this uncertainty, we think it makes sense to avoid potential value traps, where solvency concerns could increase further. But we also think it makes sense to avoid the most expensive companies, where there is a lot of good news already in the price.
We also think this recession will increase the momentum behind sustainable investing. Robust ESG screening processes should capture the risks to corporate earnings from potential changes to taxes and other political interventions. The crisis has underscored the benefits of screening companies on nonfinancial metrics such as corporate governance and human capital management. We believe companies will increasingly be rewarded for demonstrating responsible capitalism given that there are, unfortunately, likely to be more lasting consequences of this recession for lower income and minority groups. Finally, although governments will be strapped for cash coming out of this recession they will also been keen to support infrastructure projects that can fuel the recovery. We expect these projects to be focused on the shift to a zero-carbon economy. The European Green deal is one such example.
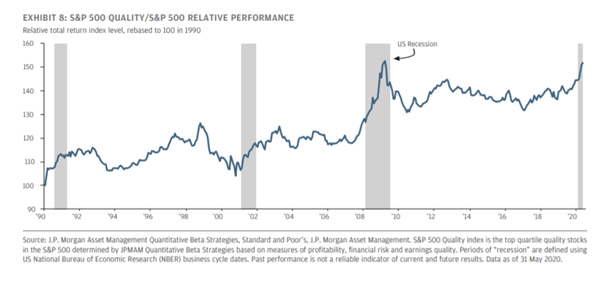
An active, nimble approach, with a current focus on quality companies (EXHIBIT 8), a keen eye on valuations, and consideration of ESG risks, therefore appears the best way of navigating the uncertainty facing investors.
SEEKING SUSTAINABLE INCOME
Central bank actions so far this year have performed the essential role of keeping government borrowing costs low but, for those seeking income, the negative side effect is that lowrisk income options are increasingly scarce.
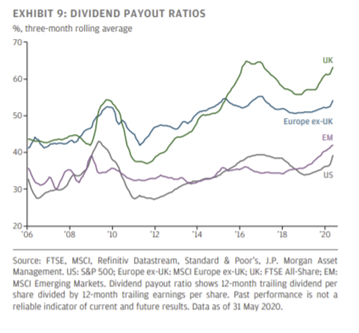
Investors have been turning to higher risk asset classes, including equities, for income over recent years, yet dividend cuts have become a hot topic as companies look to shore up balance sheets against the shock from Covid-19. While we acknowledge that many companies – particularly those who are receiving government support – may find it difficult to maintain payouts over the coming months, it is essential not to mistake what, for many firms, will be a cyclical issue for a structural one. On a regional basis, we see US dividends as most resilient. The lower dividend payout ratio of the US market provides companies with more flexibility to maintain dividends in periods of weaker earnings. Higher use of buybacks provides a buffer for companies to cut before dividends are hit. Regulatory pressure on banks, in particular, has also been lower so far in the US than in Europe.
Riskier parts of fixed income, such as corporate credit and emerging market debt, are other areas that may warrant attention when hunting for income. The Federal Reserve’s decision to buy both investment grade and high yield credit for the first time helped to pull spreads back from their widest levels in March, but credit spreads still sit significantly above their levels of the start of 2020. Central bank purchases in both the US and Europe should provide something of a backstop for corporate bond prices in the second half of the year, although we advocate an increasingly selective approach as investors move further down the quality spectrum and the need to differentiate between (more temporary) liquidity issues and (more permanent) solvency issues becomes more important.
Outside of fixed income, real assets may also have a larger role to play in portfolios as an alternative income source. While asset prices in areas such as infrastructure have not been immune to the pressures seen in public markets so far this year, income streams have broadly remained stable. But, of course, investors will need to be able to accept lower liquidity as the trade-off for moving into these types of asset classes.
The risks of overstretching for yield when hunting for income have been made very clear by the market volatility so far in 2020. Higher levels of income can only be achieved via higher levels of risk in some shape or form. Rather than ramping up risk to achieve a fixed yield target, income-seeking investors may be better off using a wide range of asset classes to build well-diversified portfolios that are in line with their risk appetite, and accepting the level of yield available as a result.
60:40 WHEN BOND YIELDS ARE NEAR ZERO
Perhaps the clearest investment challenge that will endure well beyond Covid-19 is that of how to construct a portfolio in a world of very low government bond yields.
Government bonds have traditionally played two roles in a portfolio. One is to provide a steady and stable source of income. The other is to protect a portfolio in times of market stress. Traditionally, recessions would coincide with central banks cutting interest rates, sending bond prices higher at a time when stock prices were falling. This reduced the overall scale of capital loss in bear markets.
As we look ahead, developed world government bonds don’t look like they will serve either purpose. Even long-duration government bonds provide very little – if any – income in much of Europe. And unless central banks entertain the idea of taking interest rates into negative territory (or deeper negative territory, for those already deploying negative interest rates) then bond prices cannot rise much in periods of market stress.
Meanwhile, shifting to, say, a 90:10 allocation or substituting government bonds for high yield bonds would help boost return prospects but result in a portfolio that was far less able to weather bouts of volatility.
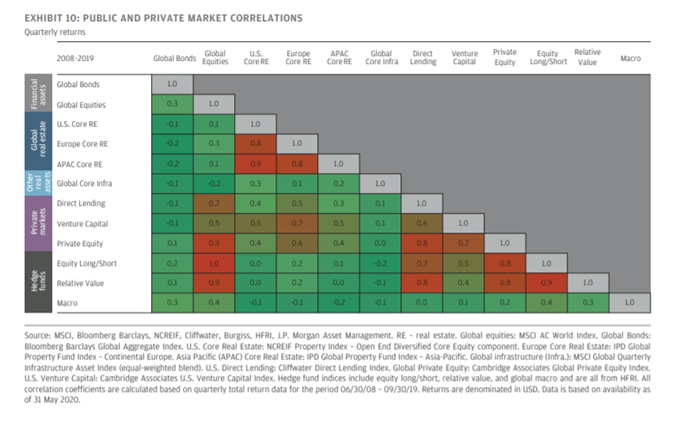
The challenge is therefore to find assets that have low correlation to stocks and ideally provide income along the way. While there are still highly rated government bonds – such as Chinese government bonds – that offer modest positive yields, in our view it may be better to look to the alternative markets. EXHIBIT 10, taken from our Guide to Alternatives, shows the asset correlations. Within liquid strategies, macro funds have tended to do a good job of providing downside protection. Less liquid options include direct real estate and core infrastructure, which both have relatively low correlations to stock markets and offer relatively strong income.
J.P. Morgan is a global leader in financial services, offering solutions to the world’s most important corporations, governments, and institutions in more than 100 countries. This in-depth analysis of markets by a world leading financial services organisation can prove valuable as we venture into the unknown as Coronavirus restrictions are gradually loosened and we attempt to return to ‘normal’.
We still believe now as much as ever that gaining a consensus view of the markets by reviewing the opinions of a variety of market leaders is key. Market behaviour is very much on a knife edge right now, and it is important that we frequently review these views so that we are well informed and in turn can keep you up to date.
Please see below a blog received yesterday from Legal & General Investment Manager’s (LGIM) Asset Allocation Team, which outlines their team’s key beliefs within the markets at the moment.
As you can see from the above, global economic stimulus is expected and this will present some medium to long-term opportunities for investing. It remains important to stay invested in order to benefit from the economic impact of the proposed stimulus measures.
Please continue to check our Blog content for the latest investment, markets and economic updates from leading investment houses.
Please see the below article by AJ Bell received yesterday (Sunday 21st June):
This week’s online meeting of the European Union’s members to debate the proposed €750 billion COVID-19 recovery plan is vitally important economically and politically. For progress to be achieved and help offered to those who need it, amid predictions that EU GDP will drop by 8–12% in 2020, all 27 nations must agree on:
the amount of money to be spent, on top of an EU budget of some €1.1 trillion (itself a matter of some friction between member states);
the conditions for awards of the capital available, which appear to include both green and digital criteria for would-be recipients;
how the money is to be spent, and the mix between loans and grants; and
how and when the money is to be repaid and over what time period, starting in 2027.
The discussions are therefore an opportunity to present a united front, tackle the viral outbreak and shore up the EU edifice at the same time, just as the Brexit negotiations with the UK start to heat up again.
Coming of age
“From the narrow perspective of investing in stock markets, it seems that global capital is yet to be fully convinced by the merits of the European project.”
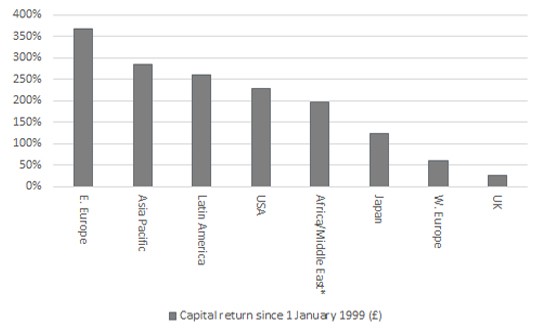
From the narrow perspective of investing in stock markets, it seems that global capital is yet to be fully convinced by the merits of the European project. The sterling-denominated performance of the Stoxx Europe 600 index ranks it seventh out of eight in capital terms since the euro came into being on 1 January 1999.
This poor performance may reflect the lingering effects of the debt crisis that first boiled over a decade ago, as well as the difficulties of providing a solid financial platform with which to support political union, in the absence of fiscal and banking union to support a single currency and unified monetary policy.
EU stock markets have lagged badly since 1 January 1999
Source: Refinitiv data. Capital return in sterling terms. *MSCI Africa/Middle East since inception in September 2003.
It may also reflect the different aims and needs of the 27 member states which are again becoming apparent as the recovery plan and budget come up for discussion.
The most serious questions of the plan are being asked by the so-called Frugal Four of Germany, Denmark, Austria and Sweden.
Failure to agree, in the twenty-first year of the existence of the single currency, would raise existential questions about the euro and the EU’s purpose and usefulness. Government is there to provide assistance in times of crisis above all others and, were the EU to fail to offer help to those nations which COVID-19 has treated most cruelly – notably Italy and Spain – then scope for further local disaffection with the supra-national powers in Brussels is considerable.
“Those nations which COVID-19 has treated most cruelly – notably Italy and Spain – suffered the most in the wake of the debt crisis that started in earnest just under a decade ago. Stock markets clearly believe they have not enjoyed anything like the same degree of economic benefits from monetary union as Germany.”
After all, these countries suffered the most in the wake of the debt crisis that started in earnest just under a decade ago. Stock markets clearly believe they have not enjoyed anything like the same degree of economic benefits from monetary union as Germany. (Eagle-eyed investors will note that two of the three best-performing developed European stock markets since the euro’s launch do not even use the single currency).
In stock market terms, the north looks like a clear winner under the euro compared to the south
Source: Refinitiv data. Capital return in local currency terms.
Great divide
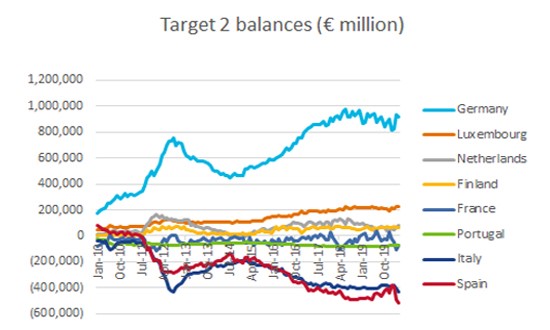
This north-south divide can be seen in another way, via the TARGET2 payments mechanism.
TARGET stands for ‘Trans-European Automated Real-time Gross Settlement Express Transfer’ system. In essence, the system is there to help balance trade flows but it could also reflect capital flows. Supporters argue that the TARGET2’s smooth functioning shows that it balances out the capital needs of the EU’s member nations. Sceptics assert that TARGET2 merely highlights huge capital flight from the south to the north and Germany in particular.
Germany’s TARGET2 surplus is still swelling even as French, Spanish and Italian deficits grow
Source: European Central Bank
No harm is done – unless an EU member defaults or drops out of the monetary union. Then those which have a positive balance are on the hook for the deficits of the member in the red. This may be why the €750 billion recovery plan alarms the Frugal Four, as they fear it could be the first step to debts being aggregated and funded at EU level, potentially leaving them to subsidise what they see as the spendthrift southern members.
“The European Central Bank is doing its bit to keep the plates spinning and, as is the case elsewhere, quantitative easing (QE) is boosting equity and bond markets to at least create some kind of feel-good factor.”
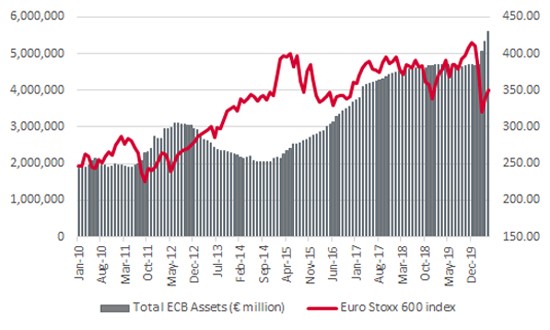
The European Central Bank is doing its bit to keep the plates spinning, as it holds headline interest rates at zero and its €650 billion expansion of the Pandemic Emergency Purchase Programme (PEPP) to take the total to €1.35 trillion. As elsewhere, that quantitative easing (QE) largesse is boosting equity and bond markets to create some kind of feel-good factor.
More QE from the ECB boosts European equities
Source: European Central Bank, FRED – St. Louis Federal Reserve database, Refinitiv data
But whether QE provides a lasting solution is unclear. The cost of meeting each crisis – 2007–09, 2011–15 and now COVID-19 – is becoming ever greater each time. The euro is under less scrutiny than it would be, even if has lost 84% of its value against gold since its launch, because sterling, the yen and the dollar are also at the mercy of identical monetary policies (and all are down by more than 80% against the metal, too). Investors may not welcome another round of patch fixes and last-minute fudges from the latest series of talks, especially if they only serve to stoke further support for anti-EU parties in the south, should those nations start to feel neglected again.
This article was written by AJ Bell Investment Director, Russ Mould, who has been in that role since 2013. Prior to that he was a Fund Manager from 1991.
Views from experts in this industry help give us a view of the ever-changing landscape.
Keep checking back for our regular blog posts and updates.
As the country was reacting to the Global COVID-19 Pandemic and protective measures were being rolled out we had one staff member ‘self-isolating’ in line with Government guidelines. Like the rest of the UK and world, we at People and Business had to make some quick and decisive Business Interruption Plans in late March 2020.
After an emergency Board Meeting, we looked at all scenarios operationally, financially stress testing the business before taking the decision to facilitate remote working for staff members not self-isolating. As we have a fantastic digital infrastructure, skilled and knowledgeable IT consultants, we were able to move quickly to get our staff the right tools to operate from home and maintain phone lines seamlessly.
Working from home
The next important phase was ensuring our staff were happy and comfortable working in their own home office environment. Our confidence in the team was quickly evidenced to be well placed. As they rose to the challenge and excelled once again in their flexibility to deliver. We are blessed with exceptional staff members, who not only successfully adapted to new working conditions but creatively drove through new working processes.
We have twice daily phone or video calls with all staff members working from home. This has enabled us all to continue working as a team and assisting in maintaining our mental health and collective belonging in what has been testing times. With lockdown being enforced, we envisaged that personal difficulties may occur, so offered a private and confidential, personal wellbeing counselling service. We engaged a professional, experienced Mental Health Counsellor, to help look after us all if required.
Customer Focus
Steve continues to lead from the front with his strong work ethic and customer centric focus. As an organisation, we instil the same value across the team. This is echoed by how we have kept our customers informed in the COVID-19 crisis. We are proactively in regular contact with our customers. The cloud-based phone lines have been maintained and regular blogs have been posted to our website as the markets, industry, our organisation and the world reacts.
As an organisation we have met the challenges head on and from a business perspective, we remain robust and resilient. The proactive measures we have put in place ensure we are in a strong position to continue delivering the service our customers expect and deserve. As we have evidenced, we are able to continue working and thriving whilst having key staff working from home. We will continue working to keep each other safe, our organisation safe and the UK safe by taking the most responsible working approach appropriate to the business circumstances.
What the future holds
While we are still a long way from business as usual, there have been a few changes happening and indeed the UK COVID-19 alert level has just been downgraded from four to three, so we will continue to monitor the situation, but safe in the knowledge we are successfully working in ‘unusual’ Business as usual practices.
Some of our experience gained over this crisis may help us evolve and improve our service to clients. As a team we constantly look to innovate with our client centric focus.
Moving forward, with new skills and working practices, we will sustain and adapt as the world continues to evolve. We can leave our customers safe in the knowledge that our business is on firm footings and aiming to continue its organic growth as we look after the financial needs of our customers.
Please see below an article received today and published by A.J. Bell last Friday (12/06/2020) detailing the importance of fund research and diversification during adverse market conditions.
At first glance, fund-by-fund level attribution of any multi-asset active portfolio may appear confusing, with a mirage of both reds (negative relative returns) and greens (positive relative returns). The AJ Bell Active MPS attribution is no exception, and a number of the underperformers have significantly struggled on a relative sense. However, we actually take great comfort in this picture, as too many negative returns – or, indeed, too many positive returns – could indicate a mismanagement of risk and a lack of diversification. Holistically speaking, the AJ Bell Active MPS performance has been pleasing, both since the product’s launch and through the crisis experienced in March 2020, with an encouraging track record when compared with likeminded active peers.
The unspoken truth about single-strategy active fund performance is that most fund managers take on inherent biases through their investment style exposure. This can, on its own, largely explain much of the performance attribution analysis and is the very reason that performance profiles can be very volatile against an index. A fund manager’s performance can be very strong for many years, during which they get heralded as ‘stars’, only to give back some or all of the relative return (against a mainstream index) in the subsequent years, as the market environment changes and their style goes out-of-fashion – often in a dramatic sense, too. They then get labelled as ‘duds’, or other more disparaging terms. For this very reason, the fund research element of the process at AJ Bell is driven by qualitative analysis. Our quantitative screening process is not, therefore, the dominant factor, but more a useful tool to sense-check our understanding of what a fund could achieve in different market environments. It’s only when you understand this about a manager that you know whether they’ve had a favourable tailwind or been pedalling into a headwind.
In building portfolios, we first and foremost want to invest with conviction and back the fund managers we truly believe can deliver to their stated objectives through multiple market cycles, and in a repeatable manner. This should help the portfolios at AJ Bell to deliver better risk-adjusted, long-term returns. At the same time, the whole portfolio should always maintain diversification by both fund manager and investment style.
Typically, the crystal ball tends not to be very reliable and so, when considering asset allocation, rather than forecast macro events and capital market reactions or market peaks and troughs, our preference is to judge what value creation or destruction remains in an asset class. With diversification in mind when constructing portfolios at AJ Bell, we look to award capital to a number of fund managers with different inherent biases. This leads to blending fund managers, which may not necessarily neutralise all risk factors, but certainly mitigates unwanted risks. Otherwise, there is a very real risk that you will end up with one big momentum portfolio that looks great initially, but then runs out of steam when the wind changes direction.
Therefore, it should not be surprising to learn that the Active MPS portfolios tend to be fairly neutral on investment-style risk against our benchmark by owning offsetting positions. These offsetting positions do not necessarily have to be in the same regions, as we consider the portfolio in total. The portfolios have held a couple of funds which have strongly underperformed on a relative sense and, much like any index fund, the portfolio as a whole is exposed to a whole host of factors at any one time. For instance, whilst the first quarter return of 2020 for the Fidelity Index World fund was circa -15%, the large- and mid-cap value stocks within that portfolio equate to around one third of the exposure and yet nearly two thirds of the fund’s performance detraction. A similar pattern can be seen in the active portfolios, whereby one or two funds have heavily detracted from returns but are offset by other funds held.
The value investment style has come under immense pressure over the past three years, as it has significantly underperformed its growth counterpart, a phenomenon that continued throughout the crisis occurring in March 2020. As a result, any fund which is biased towards value is more likely to have experienced severe underperformance against its mainstream respective index, depending on the extent of its skew. This is one of the key reasons behind the extensive effort directed towards fund research, with thorough research being undertaken prior to initiating any position. This is imperative so that a fund manager’s investment process and philosophy is fully understood – while we also delve under the bonnet and spend time understanding individual stock positions, sectors and themes. This enables us as investors to clearly and concisely understand what to expect from any fund behaviour (excluding poor stock selection, of course).
Across the active MPS range, the funds that should resonate with you while considering the content of this article are Man GLG Japan CoreAlpha, Lazard Emerging Markets and D&C Worldwide US Stock; all have had poor relative performances since our launch over two years ago. While we continually challenge our initial investment thesis, when we stand back and check the facts (aside from a spell of poor performance since our initial investment at the launch of the portfolios), these funds continue to behave in a manner that is expected given the market conditions. These funds therefore remain very relevant within the portfolio to play the part for which we awarded capital to them in the first place – and so they live to fight another day!
Value as an investment style remains extraordinarily cheap these days, and we hold confidence in these funds. When the time comes that markets rotate away from growth and start rewarding value stocks, these value funds could be in the right place to benefit handsomely. However, we are the first to admit that we don’t know when that point will be and, as a result, we never bet the ranch on any one view. As such, you should always expect to see a diverse range of holdings in our portfolios, that in isolation may perhaps look questionable, but remember: it’s how the holdings work together that’s important, not necessarily what they do on their own. That is the benefit of portfolio diversification.
Please continue to check our Blog content for the latest economic and market updates from leading investment houses and professionals.
Brewin Dolphin emailed their weekly market update on Tuesday evening (16/06/2020) as below:
Another good quick update from Brewin Dolphin. These ‘Markets in a Minute’ updates they post weekly give you a good insight without getting overly in depth or technical, just the key points from the week.
Please see below two articles uploaded by Royal London yesterday (15/06/2020). These articles provide an update on the latest market view and economic view according to Royal London.
As you can see from the above, markets remain volatile and it is important to remain invested in order to achieve your long-term goals.
Please continue to check our Blog content for the latest investment, markets and economic updates from leading investment houses.
Please see the below update posted last week by 2 of Jupiter’s Japanese Equity fund managers.
Dan Carter and Mitesh Patel discuss the increasing frictions between China and other developed nations, as Japan seeks to limit foreign influence on companies and the US rhetoric toughens. What are the implications for globalisation and supply chains, which are already showing fragility as a result of Covid-19?
In October last year we focused upon Japan’s Foreign Exchange and Free Trade Act (FEFTA), after planned revisions to this seemingly arcane piece of regulation sparked fears of a chilling of the increasingly febrile activist scene, setting back Japan’s progress to better management and a better functioning market. In late April 2020, however, the Japanese Ministry of Finance (MoF) clarified the revision to the Act and explained that almost all investors would be excluded from the most restrictive requirements such as seeking pre-authorisation for stock buying.
In its announcement, the MoF considerably assuaged concerns that the revision was a conspiracy to restrain meddlesome foreign activists, but in doing so confirmed the official narrative: that this legislation is designed to regulate state-directed investment into Japanese companies operating in strategic sectors. Whilst many investors are wiping their brows that the conspiracy theories have been (almost) put to bed, it seems to us that the implication of the official narrative is likely to be a power greater to investors in the mid to longer term.
An uncomfortable reality
The revised FEFTA flashes the spotlight on an uncomfortable reality. As it grows in size and influence, China’s aim of being global number one becomes ever more concerning for the US and its allies such as Japan. The friction caused as these national strategic ambitions grind against one another has already begun to affect the investment landscape – through curbs on FDI such as FEFTA – and will continue to do so into the longer term. But how?
One theme could be the de-globalisation of manufacturing, also known as re-shoring. In its Covid-19 recovery package the Japanese government announced that ¥244bn (c.$2.2bn) would be earmarked for companies wishing to bring production back to Japan from China. The pandemic has highlighted the fragility of global supply chains but also provided cover for a shot to be fired in this new cold war. We have previously written about the trade interdependence between China and Japan.
If cross border supply chains do begin to become untangled then clearly Japan will need to make more of its own machinery, textiles and chemicals. As investors we have sought to avoid manufacturers of basic materials and that will not change, but there may be producers of more value-added intermediate products which warrant attention. If reshoring does gather pace, Japan’s continually dwindling labour force suggests that factory automation companies, engines of efficiency such as Daifuku (which is held in the strategy), will be relied upon increasingly heavily. It is not all good news though; a repatriation of Japanese production would also mean a concentration of currency exposure once again. For too long Japanese manufacturers’ profits were tied closely (inversely) to the yen, globalisation at least allowed these bindings to be loosened and a reversal would be unwelcome.
Technology as a battleground
Perhaps the primary battleground is likely to be technology. The Huawei affair has highlighted the extent to which Chinese technology has become relied upon internationally. Similarly, China continues to need overseas companies, such as the semiconductor production equipment makers, to facilitate the build-out of its own strategically important tech industries. If Chinese ambitions continue to jar with those of the US, as well as Japan and Europe, the result could be increased technological self-sufficiency. As investors we need to carefully weigh up the opportunities and threats of this eventuality – a technological arms race will only make the possession of real technology leadership, enjoyed by companies like Lasertec and Tokyo Electron, more valuable, but a deeper fissure between geopolitical blocs could restrict addressable markets.
As investors we are hypervigilant of the temptation to overreach – we are not setting up any heroic anti-consensus positions with the above geo-strategic pondering. Rather the competing ambitions of the world’s major players create a reality in which our investee companies must operate – just as economic, social and environmental realities do – and it would be remiss of us ignore this. For so long the world order has been set, roles assumed, and relationships taken for granted. As this order shifts it will be important for investors, ourselves included, to factor these new realities into our decision making.
Jupiter is a well-established fund manager with an increasing presence in Europe and Asia. The views from fund managers provide a good insight into the current market issues.

 Source: Refinitiv Datastream June 2020