Team No Comments

Alibaba and Apple face increasing regulatory scrutiny

Please find below details in relation to the market values of Alibaba and Apple, received from AJ Bell, yesterday afternoon.

The tide seems to be turning against large tech no matter where they are listed as regulators hit back

Thursday 16 Sep 2021 Author: Martin Gamble
E-commerce giant Alibaba has lost roughly half its market value since founder Jack Ma criticised China’s financial regulators last October.

That has led to the current backlash against not just the technology sector but also the gaming, education and entertainment industries. A Goldman Sachs basket of US-listed Chinese shares has halved since peaking in early 2021.

For Alibaba, all roads seem to lead to its mobile payment platform company Ant whose initial public offering, thought to be worth around $37 billion, was suspended last November.

On 13 September 2021, Alibaba’s shares were again under pressure after state regulators said they wanted to break up Alipay, Ant’s leading mobile payment app which has over 1 billion users.

Beijing wants to create a separate independent app for the loans business which issued around 10% of the country’s non-mortgage consumer loans last year.

In addition, it is requiring Ant to share user data in a new credit scoring system which would be partly state-owned, according to the Financial Times.

The real issue for the regulators is maintaining control of the monetary system, argues current affairs magazine The Diplomat.

Alipay customers use a currency issued by the platform’s parent company Alibaba, rather than the state currency renminbi, when they use their phones to make a transaction.

It just happens that the Alipay currency has a one-to-one exchange rate with the state currency (renminbi) and is backed by reserves held by Alibaba. The problem is that Alibaba isn’t regulated as a commercial bank and therefore operates outside the financial system.

The Chinese central bank is looking to solve this problem by being one of the first to issue its own digital money and integrating Alipay and other private payment systems, regaining control of the currency.

It’s not just China cracking down on large technology companies. Phones and computer giant Apple lost a pivotal case against gaming company Epic Games, maker of the hugely successful Fortnite. Apple had blocked the game after Epic tried to bypass the Apple app store payment system.

While US District Judge Yvonne Gonzalez Rogers stopped short of calling Apple a monopolist and found that the commission it charged app developers (30%) wasn’t a violation of competition law, Rogers said Apple’s conduct was anti-competitive.

The ruling means Apple is forbidden from stopping other companies’ apps including buttons or external links that direct customers to purchasing mechanisms as well as in-app purchases.

Benedict Evans, an independent technology analyst, says Apple generated around $15 billion last year from app commissions which only represents 5% of company revenue, so even if they were to eventually disappear it would be small beer in the bigger picture.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

David Purcell

17th September 2021

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see investment bulletin below from Brooks Macdonald received yesterday – 15/09/2021

What has happened

Despite a decline in bond yields, triggered by the US CPI release, equities failed to make ground with the US index falling driven by value sectors such as banks. Those sectors which are more sensitive to the pricing of longer-term rates, such as technology, outperformed.

US CPI

Whilst it may feel like every US CPI release this year has been a surprise to markets, yesterday’s release was the first downside surprise since November last year. The month on month headline number came in at 0.3% vs expectations of 0.4%, with some of the key transitory sub-components retreating. Used cars and trucks saw their first decline in 6 months after driving much of the month on month increase earlier in the year. Not every component slowed however and energy picked up, driven by gas prices. The US core CPI number that excludes this energy element (as well as food) rose just 0.1% month on month compared to the 0.3% expected. Whilst there are signs of a deceleration of inflationary pace, energy and commodities more generally are likely to cloud the near term numbers even if they ultimately prove transitory. Over in the UK, the CPI release this morning showed inflation of 3.2% year on year, against market expectations of just 2.9%, a sign that the deceleration may not be a global phenomenon yet.

The Winter Plan

England’s Chief Medical Officer announced that ‘winter is coming’ as the UK government unveiled its toolkit for fighting COVID during the colder months in the Northern Hemisphere. Plan A is to effectively stick to the current guidance and use the vaccination driver (first/second doses and boosters) to increase population level immunity. Plan B would see a reversal to the status quo earlier in the summer with masks and work from home advice amongst the options. The UK Prime Minister was keen to stress that lockdowns remained available to the government but this looks increasingly unpalatable politically which may mean the government leans into Plan B earlier to avoid needing to make that decision.

What does Brooks Macdonald think

The US CPI number is the most hotly anticipated of the inflation releases, partially because the US is the world’s largest economy but also as it is being used to predict the path of inflation in other developed nations. Yesterday’s deceleration points to an easing of some of the transitory factors that have muddied the data over the summer but with commodities hitting decade highs, it is unlikely to entirely reverse short term.

Another quick update from Brooks Macdonald, these regular investment bulletins help us keep up to date with what is happening in the markets.

Please continue to check back for our latest blog posts and updates.

Charlotte Clarke

16/09/2021

Team No Comments

Brewin Dolphin Markets in a Minute: Stock markets ease as inflation fears return

Please see below for Brewin Dolphin’s latest Markets in a Minute Article, received by us yesterday evening 14/09/2021:

US and European stocks fell last week as the prospect of higher inflation and slower economic growth weighed on investor sentiment.

The S&P 500 and the Dow ended their four-day trading week down 1.7% and 2.2%, respectively, amid a higher than-expected rise in producer prices and concerns about the Delta variant’s impact on the economic rebound.

The pan-European STOXX 600 eased 1.2% as the European Central Bank (ECB) said it would trim its emergency bond purchases. The FTSE 100 also fell 1.5% on concerns the Bank of England could start increasing short-term interest rates.

In contrast, Japan’s Nikkei 225 extended the previous week’s gains, adding 4.3% amid ongoing optimism that the new prime minister will bring further fiscal stimulus. China’s Shanghai Composite rallied 3.4% after newspapers reported ‘candid’ talks between the country’s leader Xi Jinping and US President Joe Biden.

S&P 500 ends five-day losing streak

The S&P 500 added 0.2% on Monday, ending its five-day losing streak, as rising oil prices boosted energy stocks. Airlines and cruise line operators also performed strongly, after the seven-day US Covid-19 case average fell to 144,300 from 167,600 at the start of the month.

UK and European stocks also edged higher, after a top European Central Bank official said recent gains in inflation did not yet pose a risk, and that the extremely low level of inflation seen in 2020 needed to be taken into account.

The FTSE 100 opened Tuesday’s trading session down 0.3%, after the Office for National Statistics reported that while UK company payrolls have returned to pre-pandemic levels, the recovery is uneven and labour shortages are likely to persist for the rest of the year.

US producer inflation accelerates

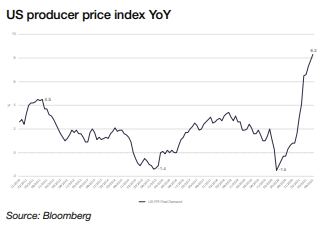
Last week saw the release of the latest US producer price index, which is a measure of inflation based on input costs to producers. The index rose by 0.7% in August from the previous month, which was a slowdown from July’s 1.0% increase but above estimates for a 0.6% rise.

The index rose by 8.3% on an annual basis, which was the biggest yearly increase since records began over a decade ago. This followed a 7.8% annual increase in July.

The data, which comes amid supply chain issues, a shortage of goods, and heightened demand related to the pandemic, suggests inflationary pressures are persisting despite the Federal Reserve’s insistence they will prove temporary and ease through the year.

Firms are also facing cost pressures from the tight labour market. The closely watched US Jobs Openings and Labor Turnover Survey (JOLTS), released last Wednesday, showed there were a record 10.9 million positions waiting to be filled in July, up from 10.2 million in June. It marked the seventh consecutive month of increased job openings, fuelled by factors such as enhanced unemployment benefits, school closures and virus fears.

ECB to trim bond purchases

Over in Europe, the ECB said it would move to a ‘moderately lower pace’ of pandemic emergency bond purchases following a rebound in eurozone economic growth and inflation. ECB president Christine Lagarde sought to reassure investors by stating that the shift to a slower pace of purchases was not tapering. This contrasts with the US Federal Reserve and the Bank of England, which have signalled they plan to start tapering asset purchases this year.

In comments reported by the Financial Times, Lagarde said the economic rebound was ‘increasingly advanced’, but added: “There remains some way to go before the damage done to the economy by the pandemic is undone.” She pointed out that two million more people are out of work than before the pandemic, and many more are still on furlough schemes.

Lagarde added that a fourth wave of infections could still derail the recovery, while supply chain bottlenecks could last longer and feed through into stronger-than-expected wage increases.

BoE split over rate increase

BoE governor Andrew Bailey gave a speech last week in which he revealed the central bank’s policymakers were evenly split between those who thought the minimum conditions for considering an interest rate hike had been met, and those who thought the recovery wasn’t strong enough. According to Reuters, Bailey said he was among those who thought the minimum conditions had been reached, but that they weren’t sufficient to justify a rate hike.

The comments have led to speculation that the next vote could skew towards raising the base interest rate, which currently stands at 0.1%.

Bailey also said there were signs that the UK’s economic bounce back from the pandemic was showing some signs of a slowdown. Indeed, data published by the Office for National Statistics on Friday showed monthly gross domestic product (GDP) grew by 0.1% in July – lower than the expected 0.5% rise and the 1.0% growth seen in June. Output in consumer-facing services fell for the first time since January, driven by a 2.5% decline in retail sales. Output from the construction industry also dropped amid a shortage of building materials and higher prices.

Please continue to utilise these blogs and expert insights to keep your own holistic view of the market up to date.

Keep safe and well

Paul Green DipFA

14/09/2021

Team No Comments

LGIM Blog

Please see below the latest article received from Legal & General Investment Management’s Asset Allocation Team which was received late yesterday (13/09/2021) afternoon and covers their views on a number of topics:

As you can see from the above Shortages are being felt globally and the initial thoughts on the labour market improving in Autumn have been curtailed slightly as a result of people reassessing their work/life balance.

They also disagree with the consensus that equity markets are heavily over-priced and their recession indicators remain benign. They believe there are still investment returns to be achieved despite the market rally being behind us.

These views represent the LGIM Asset Allocation Team and other providers views could differ.  

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

14/09/2021

Team No Comments

Watch margin debt as tech giants keeps powering S&P 500

Please see below article received from AJ Bell yesterday afternoon, which examines which factors could disrupt the stocks currently leading the US market to record highs.

The S&P 500 index continues to barrel higher, setting fresh peaks as it does so. The American benchmark has advanced for seven straight months, its best run without a loss since its 10-month romp between April 2017 and January 2018, even if some of the market technicals have not convinced everyone.

As this column noted last month, the small-cap Russell 2000 index and the Dow Jones Transportation index have yet to set fresh peaks, to imply the current advance lacks the breadth that provides confidence in the foundations of the upward move.

In this context it is interesting to note the first dip in US margin debt since February 2020, just as the pandemic hit and investor confidence quickly drained away.

Margin debt is the amount of money an investor borrows from their broker via a margin account to buy shares (or even short sell them).

This looks smart when markets are rising (as the investor or trader can get more exposure) but looks less clever when markets are falling. Indeed, falling asset prices can force so-called margin calls where the investor or trader must start repaying the loan – and sometimes they must sell other positions to fund that repayment, creating a negative feedback loop in markets.

This first dip in margin debt must be watched, especially in light of Securities and Exchange Commission queries about regulatory filings from the investment platform Robinhood and questions about its business model and whether payment for order flow is appropriate.

It remains to be seen whether this dampens some of the liquidity flow which has done so much to elevate certain sections of the US stock market but it may be no coincidence that what looked like some of the frothier areas have started to flag.

HOT AND COLD

Whether trading losses are sparking a slight decrease in risk appetite or whether a more cautionary approach (perhaps considering Federal Reserve reverse repo operations and talk of tapering) is lessening demand for initial public offerings, cash shells known as SPACs and growth and tech stocks is hard to divine.

But what is clear is that some of the hottest areas of the US market are showing some sign of cooling.

New market entrants have started to lose their appeal, judging by the performance of the Renaissance IPO ETF and Renaissance International IPO ETF. The former is currently tracking the performance of 72 American new floats, the latter 62 global ones.

The International vehicle may be suffering owing to its 44% weighting toward China and the US-oriented version is at least trying to claw back lost ground.

Enthusiasm for cash shells set up to acquire what they fancy is also waning. The Next Gen Defiance SPAC Derived ETF, which tracks a basket of nearly 300 SPACs is down by more than a third from its high.

This is perhaps less of a surprise when you consider the data from SPACinsider.com which shows how 308 SPACs are looking for a target even though 263 have already floated. In the end, supply may be outstripping demand.

Even Cathie Wood’s ARK Innovation ETF, the darling of growth and momentum-seekers, has found the going to be a bit tougher of late. The $22 billion behemoth, whose biggest holdings are Tesla, Teladoc and Roku, trades a fifth below its high (although supporters will counter that it is up by a quarter from its spring lows).

None of this is conclusive and the attempted rallies in the ARK Innovation ETF and the Renaissance IPO ETF could yet signal the next upward surge in US equities. Investors would do well to keep an eye on them and trends on the monthly margin debt figure from FINRA as useful indicators of market sentiment.

Yet for the US market to really roll-over its leaders must falter. And in fairness there is little sign yet of investors falling out of love with Facebook, Apple, Amazon, Netflix, Google’s parent Alphabet and Microsoft.

Their aggregate $9.8 trillion market cap is the equivalent of more than three times that of the FTSE 100 and they represent a quarter of the S&P 500’s value between them. If the S&P is to stumble, these names will have to do so.

Spotting what could cause that is the hard bit, such is their dominance, and in the absence of regulation it may take a jump in interest rates or a wider, unexpected shock to prompt investors to sell such core holdings, just as happened with the oil price shock and inflation in 1973-74.

This did for the previously unassailable ‘Nifty Fifty’, an informal designation for 50 popular large-cap stocks in the 1960s and 1970s.

Please check in with us again shortly for further news and market analysis.

Take care.

Chloe

13/09/2021

Team No Comments

Why gloomy US jobs data didn’t derail the market

Please see the below article from AJ Bell:

The point at which the Federal Reserve could start tapering bond purchases might have been kicked down the road.

The US equity markets have remained resilient in the face of poor US non-farm payroll growth in August. The consensus estimate was for an increase of 735,000, however the reported figure was just 235,000.

Two factors explain the market’s apparent irrational exuberance to what appears at first glance to be a very bearish jobs report.

First, the media has focused on one specific aspect of the report, which presents an overly dismal picture of the American jobs market. A more detailed and stoic examination of the data depicts a more optimistic scenario.

Second, the apparent weakness in the jobs data is likely to prompt the Federal Reserve to postpone any plans for tapering bond purchases that are part of its economic support measures, which is likely to underpin current equity valuations.

While the August headline non-farm payroll figure was distinctly disconcerting, other aspects of the jobs report were far more encouraging.

The unemployment rate fell to 5.2% in August from 5.4% in July. Moreover, wages continued to grow, increasing 4.3% on a year-on-year basis, and 0.6% on a monthly basis. This compares with estimates for 4% and 0.3% respectively. In addition, the job gains for July were revised up to 1.1 million.

Another potential source of optimism relates to labour shortages. The removal of additional unemployment insurance payments is likely to act as a catalyst for workers to re-enter the jobs market. Better access to childcare as schools reopen should also remove a further obstacle for individuals hoping to get back into work.

Keep checking back for more of our regular blog content including market insights and views from some of the world’s top investment managers.

Andrew Lloyd DipPFS

10/09/2021

Team No Comments

Daily Investment Bulletin

Please see below, Daily Investment Bulletin, received from Brooks Macdonald yesterday afternoon, which provides information on economic developments impacting European and US markets.

What has happened

Monetary policy and COVID provided the drum-beat for investors on Tuesday. In Europe, markets fell as investors appeared to be nervous around the chances that the European Central Bank (ECB) might taper from its current ‘significantly higher’ level of PEPP (Pandemic Emergency Purchase Programme) asset purchases when ECB governors meet on Thursday. Meanwhile, over in the US, markets were similarly weak as the COVID delta variant continued to weigh on sentiment in the wake of last week’s weaker US jobs report. At a sector level, technology stocks were a relative outperformer on the day.

UK government signals tax rise on workers, businesses and shareholders

UK prime minister Johnson announced a tax hike for workers, businesses and shareholders on Tuesday. Billed as necessary to help support the NHS as well as social care spending needs, national insurance, which is tax on earnings, will rise by 1.25% from April 2022 for both employees as well as employers. As the Institute for Fiscal Studies noted on Tuesday, ‘it is really a 2.5 per cent tax rise on earnings … today’s announcements constituted a Budget in all but name’. The Institute of Directors also rounded on the tax plan this week, calling it ‘an extraordinary time to be considering adding to the cost of employing people’. As well as the increase to national insurance tax, there is also a hike on dividend tax with an increase of 1.25%. According to the plans announced, from April 2023, national insurance tax rates will revert back to the current level and the rise will be replaced by a new dedicated ‘health and social care levy’, which will become a separate tax on earned income from April 2023. Separately, the government also confirmed on Tuesday that the ‘triple-lock’ formula for annual state pension increases would be suspended for one year. Instead, the calculation will be based on the greater of 2.5% or inflation, while the third component of average wage increases would be disregarded for one year.

US plans COVID ‘six-pronged strategy’

On Tuesday it was confirmed by White House press secretary Psaki, that US President Biden would later this week on Thursday outline a ‘six-pronged strategy’ and which would involve ‘working across the public and private sectors to help continue to get the pandemic under control’. The announcement is likely to include an update on the plans, initially announced in August, around delivering COVID vaccine ‘booster jabs’ likely later this month. According to US CDC’s vaccine tracker (US Centers for Disease Control and Prevention), 75% of US adults have now had at least one vaccine dose.

What does Brooks Macdonald think?

The UK rise in national insurance contributions breaks a key Conservative manifesto pledge not to increase any of the main rates of tax. That said, it’s worth remembering that this promise pre-dates the COVID pandemic which went on to up-end many governments’ spending plans around the world. In terms of what it means for markets, perhaps more significant is the broader cadence from policy makers, in that following the unprecedented levels of fiscal support during the pandemic last year, this year, fiscal prudence seems to be the dominant theme. At the edges, this also perhaps adds a bit of a headwind for those investors looking for a sustained fiscal impetus to drive a durable reflationary narrative. As we have said before, with 2021 being a year of transition, this is not the year to try to decisively swing the asset allocation ‘bat’ behind any one particular investment style. Instead, balance in portfolios remains key.

Source: Bloomberg as at 08/09/2021. TR denotes Net Total Return.

Please check in with us soon for further relevant content and market news.

David

9th September 2021

Team No Comments

LGIM Asset Allocation Team

Please see below the latest article from the Legal & General Asset Allocation Team which was received on 06/09/2021 and details their thoughts on markets:

Dancing in the dark

Markets remain in a holiday mood. The narratives on which we are focusing are slow-moving – inflation, the Delta variant, and the usual politics and economic datapoints. Could it be that investors are dancing in the dark, totally oblivious to the risks out there?

As with all Key Beliefs emails, this email represents solely the investment views of LGIM’s Asset Allocation team.

Relax

The Jackson Hole symposium is supposed to be a largely academic affair, but it excites investors as we’ve had a few shock policy announcements in the past.

This year, though, Federal Reserve (Fed) chair Jay Powell choose to relax investors. He doubled down on the view that inflation is likely to prove transitory, and gave five reasons to believe recent elevated readings could be temporary:

1) The lack of breadth behind the inflation spike. We largely agree with this assessment. However, we will be watching carefully should we see signs of broadening, especially in traditionally more sticky services.

2) Moderating inflation in pandemic-sensitive components. No dispute from us here. Used-car prices appear to have flattened off and indeed we expect them to become a large drag on inflation in 2022 as prices fall back to more normal levels.

3) Wages that remain consistent with inflation goals. While true, it is surprising that wages have not been weaker given the rise in unemployment. With demand expected to continue growing well above trend, if participation fails to fully recover the danger is that wage pressures intensify next year.

4) Stable long-term inflation expectations. Again true, but our research finds that the formation of inflation expectations is largely adaptive, so the risk is that the longer actual inflation remains elevated the more it might begin to place upward pressure on inflation expectations.

5) Global disinflationary pressure. Powell believes there is little reason to think this has suddenly reversed or abated. We nevertheless find evidence that some of the factors could be moderating, as globalisation seems less intense with countries increasingly looking inward and becoming more protectionist. Fiscal policy, while not yet fully embracing modern monetary theory, appears far less disciplined. Finally, and perhaps most important, is the shifting behaviour of central banks, led by the Fed. Its new framework is a commitment to run the economy hot, partly because it believes continued global disinflationary pressure and well anchored inflation expectations will ensure any inflation increase is so gradual it will have time to adjust policy smoothly.

All in all, Powell could well be proved correct. We also expect inflation to fall back to target for a while next year, but risks to this sanguine inflation outlook appear to the upside.

The power of love

If you ever need a clear example of the power of Strategic Asset Allocation (SAA), compare the performance of UK mid-cap managers versus US large-cap managers over the five years ending June 2020. The best-performing UK managers achieved 36.7%, while the worst-performing US large-cap manager performed slightly better with a 36.8% return. SAA drives portfolio returns, plain and simple!

There are many different models for SAA, some developed by Nobel Prize-winning economists. One unique point about our SAA approach is that we don’t believe it makes sense to presume that one model is able to capture the ever-changing complexity of financial markets well enough. We try to learn and take something from many different models.

For instance, the Yale model gets lots of attention among investors. It is heavily invested in absolute-return strategies and illiquid assets, and has hardly anything in standard asset classes like government bonds and equities. It helps that the endowment does not run daily or weekly liquidity funds and can spend a lot on fees and governance. We see the value of alternatives as well. They form an important and differentiating part of our strategies, but we look for solutions that fit daily liquidity and a more limited fee budget.

Finally, when it comes to building an SAA portfolio, we believe it is all about seeking exposure to the rewarded risks in a (cost) efficient way, getting rid of unrewarded risks, and trying to prevent a dangerous concentration of risks.

As with most things in investment, SAA is more an art than a science and investors should be wary of putting all their money in one model.

Back to life, back to reality

Perhaps surprisingly given the rally we have seen in equities and the narrative moving at a snail’s pace over the summer, consensus positioning isn’t that extreme.

One of our favourite sentiment indicators, the ‘bull minus bear’ survey of the American Association of Individual Investors, is flagging quite neutral sentiment.

The reality is that many people remain cautious. In our view, the most prevalent worries are:

1) Valuations. People usually point to absolute equity valuations, which indeed are scary, but we think valuations relative to bonds matter most.

2) Potential for rising inflation and interest rates. Though inflation is one of our key worries, we are more relaxed about the downside risks to equity markets from rising inflation and interest rates.

3) Peak growth momentum. The Delta variant and its rolling impact on growth is front of mind for many investors. Although growth momentum is fading, that needn’t necessarily take equities lower. Earnings momentum remains favourable, allowing valuations to drift lower while markets grind higher.

We therefore believe the bullish market case remains in place: the economy seems mid cycle, with massive excess savings, quite neutral positioning, and committed support from central banks.

Please continue to check back for our latest blog posts and updates.

Charlotte Ennis

08/09/2021

Team No Comments

Weekly Market Commentary – Spanner in the works from the US Jobs Report

Please see below commentary received from Brooks Macdonald yesterday evening, which presents market analysis following the European Central Bank’s latest monetary policy meeting. 

This week begins with a holiday Monday in the US for Labor Day, with markets closed in the country. In reality, this is just a brief respite before the pace picks up a gear, and there’s quite a lot to keep investors focused. 

The big event this week is the ECB’s latest monetary policy meeting due on Thursday, where attention will be on whether or not they decide to start to taper back their recent higher-level of asset purchases. Elsewhere, we also have central bank policy decisions from Australia (on Tuesday), and Canada (on Wednesday). 

The recent US Jobs Report significantly missed expectations

In the US, investors will be trying to figure out what last week’s US jobs miss means for the Federal Reserve (Fed) and for the timing of any tapering decision. Later this week, the US Producer Price Index (PPI) is due on Friday, which sets up the inflation-focus ahead of US Consumer Price Index (CPI) due the following week. Finally, according to recent reports from Bloomberg, US President Biden might decide this week who is going to be the next Fed Chair. Powell’s current term as Chair ends in February next year, but expectations are that he is likely to get a second term, not least given reports last month that US Treasury Secretary and former Fed Chair Janet Yellen has endorsed Powell’s renomination.

Just as markets had digested Fed Chair Powell’s Jackson Hole script, Friday’s US jobs report has put a bit of a spanner in the works. A week ago, Powell had indicated that with an inflation goal already met and an employment goal in sight, the Fed might soon start to taper its $120bn a month of asset purchases. But then Friday happened, and US non-farm payroll data showed just 235,000 jobs added in August. This is a big miss, given markets had been expecting a print more than three times bigger, versus 725,000 expected1. 

It was also well outside of the bottom of the forecast range (of 400,000 to 1 million). To put it in context, despite a positive revision to July, this was the lowest monthly jobs add in seven months. Behind the weakness, there was a sharp slowdown in hospitality and retail job creation. Employment in ‘retail trade’ declined over the month by 29,000 jobs, and there was also a loss of 42,000 jobs in ‘food services and drinking places’2. As the US Bureau of Labor Statistics report noted, ‘employment in leisure and hospitality is down by 1.7 million, or 10.0 percent, since February 2020.’ All in all, it’s hard not to see how this report will give some support to the view that the COVID-19 Delta variant is having an impact on both the pace of the economic recovery and the labour market recovery. In terms of how it might influence Fed-thinking, it will be interesting to see what Fed members say about the jobs report, and this week, we have a number of scheduled Fed-speaker events worth keeping an eye on. 

Investors will look to see if the ECB will slow down the Pandemic Emergency Purchase Programme (PEPP)

The highlight for markets this week will be the ECB’s latest monetary policy decision due on Thursday, along with ECB President Lagarde’s press conference that follows the statement as usual. The big question for investors is whether or not the ECB will decide to slow down the recent ‘significantly higher’ rate of Pandemic Emergency Purchase Programme (PEPP) purchases into calendar Q4. In the last week or so, we’ve seen a more public airing of views from both hawkish and dovish ECB governing members. On the outlook for inflation, on the one hand we’ve seen Germany’s Bundesbank chief Weidmann saying ECB members shouldn’t disregard the risk that inflation could accelerate faster than currently anticipated. Against this, ECB chief economist Philip Lane, who recently argued that inflation surprises still did not challenge his views about the temporary nature of price pressures as wage growth, remained muted in his view. All in all, it’s difficult to come down on one side or the other ahead of Thursday.

With the miss in the US jobs report, it is perhaps inevitable that investors will worry that a resurgent COVID-19 infection picture is impacting on the pace of the US economic growth recovery. As for the monetary policy outlook, for the Fed to green-light a future taper programme, the labour market needs to show continued improvement, and Friday’s print won’t have helped that cause. At the end of the day, we have to keep in mind that it’s only one data point. Instead, it now leaves the focus for markets on the Fed’s next monetary policy meeting later this month, on 21 – 22 September. However, the odds that the Fed will press the button on a taper start-date at this September’s meeting are now a little bit longer.

Please check in again with us soon for further news and relevant content.

Stay safe.

Chloe

07/09/2021

Team No Comments

Powell reassures markets that the Fed wont rush rate hikes

Please find below an update from Invesco, received late on Friday, reassuring markets that the Fed won’t rush rate hikes.

Kristina Hooper, Chief Global Market Strategist, Invesco Ltd

Key takeaways

Some Fed officials took a hawkish tone

At Jackson Hole, several Federal Reserve officials were emphatic that tapering needs to begin – and soon.

Powell’s remarks calmed markets

But Powell offered a kinder, gentler view of tapering, declining to establish a timeline.

No rush on rate hikes

Powell also noted that rate hikes have a more stringent set of conditions and are uncoupled from tapering plans.

Last week — in the dead of August — the Kansas City Fed held its annual Jackson Hole Symposium. In a true sign of the times, the symposium was not actually held in Jackson Hole this year, as had been originally planned; instead, it was held virtually. This underscored the reality that things are not back to normal.

Some Fed officials took a hawkish tone

In the run-up to Federal Reserve Chair Jay Powell’s speech, several Fed officials were emphatic that tapering needs to begin soon. Kansas City Fed President Esther George said she expects the Fed to start tapering shortly. Dallas Fed President Robert Kaplan called for tapering to be announced by September and to begin by October or soon thereafter. Perhaps most surprising — and most hawkish — were the words of St. Louis Fed President James Bullard.

Bullard worried that the Fed’s balance sheet expansion is creating a housing bubble. He said that the tapering process should be finished by the end of the first quarter. What’s more, he articulated serious concerns about inflation; he seems sceptical that inflation is actually transitory and argued that by March 2022, the Fed would be able to assess whether inflation had moderated. He suggested that if inflation hadn’t moderated, the Fed would have to get “more aggressive,” which I would presume to mean rate hikes, and that would be sooner than expected. Not surprisingly, these hawkish comments rattled markets.

Powell’s remarks calmed markets

But then came Powell’s speech, and markets breathed a sigh of relief.  It’s true that things are certainly not back to normal, and Powell made that clear. He recognized that the pace of the recovery has exceeded expectations — and has been far swifter than the recovery from the Great Recession, with even employment gains having come faster than expected. However, he underscored the unusual nature of the recovery – he described it as “historically anomalous” — with personal income actually having risen. He said that while labour conditions had improved significantly, they were still “turbulent.” And of course, he pointed out that the economic recovery is being threatened by the resurgence of the pandemic.

Powell also underscored the unevenness of the economic recovery, that the Americans least able to carry the burden are the ones who have had to do just that. He emphasized that the services sector has been disproportionately affected, noting that total employment “is now 6 million below its February 2020 level, and 5 million of that shortfall is in the still-depressed service sector.”1

A kinder, gentler tapering

While George, Kaplan and Bullard took a more hawkish stance on tapering, Powell offered a kinder, gentler view. He recognized that the “substantial further progress” test for inflation had been met, but did not announce the start of tapering, or even call for it to be announced by September. He acknowledged that at the July Federal Open Market Committee (FOMC) meeting, most participants believed it would be appropriate to taper this year. And he recognized that in the month since the last FOMC meeting, there has been more progress on the economic front — but that there has also been further spread of the COVID-19 Delta variant. My read on this is that tapering is likely to be announced soon, but that Powell would like to maintain some flexibility given the uncertainties presented by COVID.

Powell seemed more certain in his assessment that inflation is largely transitory. He offered up compelling arguments to support that view, especially pointing to longer-term inflation expectations remaining anchored. I found this gave credibility to his more dovish stance.

The key takeaway: A ‘conscious uncoupling’

Powell channelled his inner Gwyneth Paltrow in asserting that rate hikes are uncoupled from tapering. In other words, he suggested that we shouldn’t expect rate hikes to begin just because tapering has ended. He asserted that rate hikes have a different and far more stringent test: “until the economy reaches conditions consistent with maximum employment and the economy is on track to reach 2% inflation on a sustainable basis.”1 This was perhaps the most important takeaway from the speech, given that markets seem far more concerned with when rate hikes will begin rather than when tapering will begin.

Looking ahead

All eyes will be on the August jobs report, due out at the end of this week. There are whispers that this could be a blowout with more than 1 million non-farm payrolls created. If that happens, I believe the Fed would be even more comfortable announcing tapering in September and starting to taper in October.

Further off into the distance, questions are swirling about whether Powell will be re-nominated as Fed Chair. While I suspect there may be a little grumbling from the extremes on both aisles of Congress, my money is on his re-nomination. However, speculation about this — and the future of the vice chairs (the vice chair and the vice chair for supervision) — will certainly occupy some markets watchers’ time in the coming months.

Please check in with us soon for further relevant content and market news.

David

6th September 2021