Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, Brooks Macdonald’s ‘Daily Investment Bulletin’ which provides a brief update on global investment markets. Received this afternoon – 28/09/2023

What has happened?

US bond yields continued their grind higher yesterday with the US 10-year Treasury yield now at 4.61% after another rise in oil prices stirred fears of a higher for longer inflationary backdrop. With these moves the US dollar has also been appreciating further, with the dollar index almost back to levels seen in November last year. US equities managed to stay flat for the day, but this conceals a high level of intraday volatility and general uncertainty.

Bond moves

Bond markets are certainly leading broader financial markets now with bonds seeing another heavy selloff yesterday. The Bloomberg aggregate global bond index, a widely used measure of the broad bond market, reached its lowest price level of 2023 as the benchmark 10-year and 30-year Treasury prices fell. These moves are quickly moving into the real economy with the US 30-year mortgage rate now at 7.41%, the highest level since December 2020. While the lag is relatively short, mortgage rates do act with a delay so there is likely further upside to these rates in the coming weeks. European bonds were also under pressure with 10-year bund yields hitting a 10-year high and Italian bonds underperforming after the Italian government unveiled a 4.3% expected deficit for 2024.

Oil Prices

The latest move higher in bond yields, which move inversely to prices, has been catalysed by growing inflation expectations caused by the uptick in energy prices. Brent crude closed above $96 per barrel yesterday, a fresh high for 2023. The US oil benchmark, WTI, saw an even greater percentage climb yesterday with the price moving to a one-year high of $93.68. While recent moves have been spurred by supply cuts, yesterday’s moves reflected lower-than-expected storage levels in the Cushing oil reserves.

What does Brooks Macdonald think?

Robust US economic data has been a key pillar of the soft-landing narrative in recent months however the recent consumer confidence data, and yesterday’s card spending data, suggests that the US consumer is showing signs of slowing. The US consumer discretionary sector has declined by almost 10% over the last fortnight as investors start to price in a heightened risk of a hard landing.
Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

28th September 2023
Team No Comments

Brewin Dolphin – Markets in a Minute

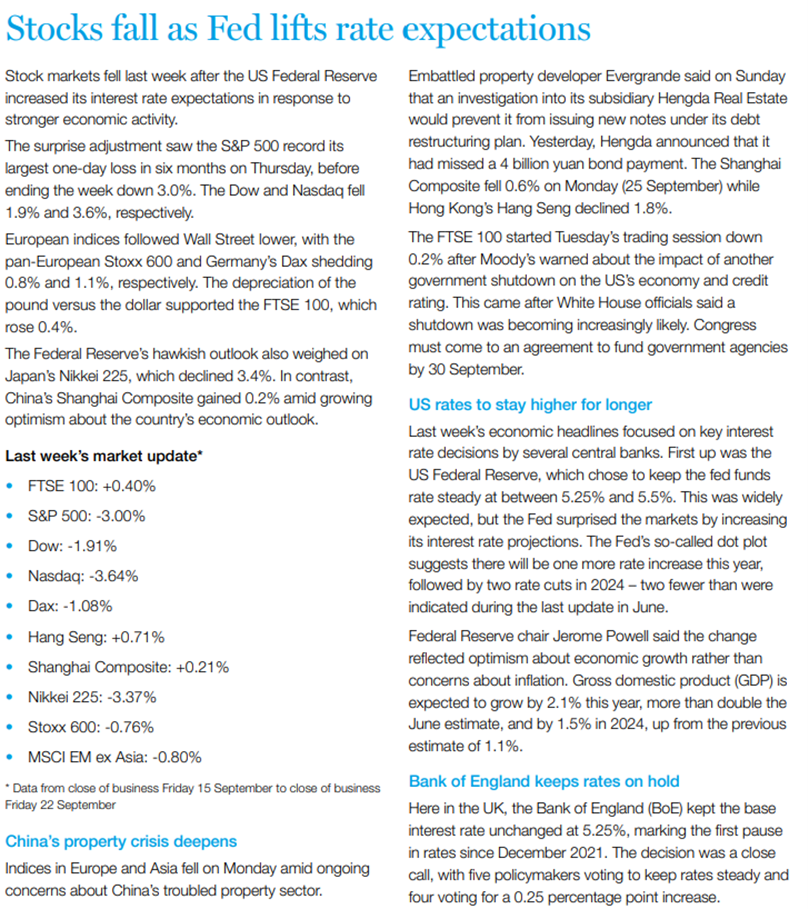
Please see below the latest ‘Markets in Minute’ update from Brewin Dolphin, which covers their views on recent events in markets and was received late yesterday (26/09/2023) afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

27/09/2023

Team No Comments

Brooks Macdonald Weekly Market Commentary

Please see below Brooks Macdonald’s Weekly Market commentary, received yesterday afternoon – 25/09/2023

Brooks Macdonald Weekly Market Commentary  

  • Bond yields rose last week after a hawkish Federal Reserve meeting combined with strong labour market data
  • This week sees the US revise its gross domestic product (GDP) estimates from as early as Q1 2005 which will inform future GDP expectations
  • Inflation will be in focus this week with the US, Euro Area and Japan all releasing important data

Risk appetite improved yesterday with the US equity market enjoying its broadest rally of September so far. Small cap US equities, which have underperformed their larger cap equivalents in 2023, outperformed on the day. European equities and UK equities also posted strong returns.

These rallies within equity markets happened despite the oil price continuing to grind higher. Brent Crude, the international oil benchmark, hit another year to date closing high of US$93 with the price now above US$94 today. The first order impact of this will be US gasoline prices which will continue to make the September month-on-month headline inflation numbers challenging. Other commodity prices may also be impacted by the El Nino event which is now expected to be more severe. The dramatic temperature fluctuations disrupt crop cycles and therefore put pressure on global food supply alongside the current grain supply issues from Ukraine.

The market implied probability of an interest rate hike from the European Central Bank (ECB) yesterday had been edging up in the last week and ultimately proved correct as the ECB hiked by 25bps. The ECB deposit rate is now at its highest level since the ECB’s creation and the last 15 months of hikes also represent the fastest pace of hikes in its history as well. It was however a closer call than previous meetings with President Lagarde pointing to a ‘solid majority’ within the committee backing the hike which feels softer than the traditional ‘overwhelming’ majority for other hikes. The ECB also raised its inflation projections for this year and 2024 with higher energy prices the main justification for this. Economic growth forecasts were revised lower with hopes for a Euro Area recovery pushed into 2024.

With the ECB revealing this incremental hike yesterday, the key question is whether this is now the peak interest rate for the cycle. President Lagarde was asked this specifically, replying that ‘we can’t say that’ given the economic and inflation uncertainties. The market is pricing in a 45% chance of a further hike from the ECB before the end of the year but whether this transpires will be highly dependent on the evolving inflation picture.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Charlotte Clarke

26/09/2023

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management providing a brief analysis of the key factors affecting global markets. Received this morning – 25/09/2023.

Overview: to yield or not to yield?

Last week, stocks and bonds ended up bruised following the ‘hawkish pause’. The US Federal Reserve (Fed) announced on Wednesday it would hold interest rates steady at 5.25-5.5%, but threw in some stern forward guidance to dispel doubts it might be easing off. Fed Chair Jay Powell’s talking points were much the same as they have been for the better part of two years: the US economy is still strong, inflation is too high, and consistently tighter monetary policy will be needed for the foreseeable future. The Fed backed up its words with a ‘dots plot’ projection that showed another rate rise this year, then holding steady in 2024. It was a reaffirmation of Powell’s commitment to keeping rates higher for longer.

Bond yields spiked on the back of the news. Ten-year US Treasury yields touched above 4.5% during early Friday trading – the highest level in 16 years. The move up in risk-free rates naturally makes equities look less attractive by comparison, sparking a sharp drop off in the S&P 500. There are concerns that equity valuations in terms of price-to-earnings multiples look vulnerable, especially after such strong stock performance without earnings growth for most of this year. Longer-term growth assets – typically more sensitive to interest rate moves – are therefore under threat again. With sluggish global growth all limiting the upside of company earnings and a ‘higher for longer’ monetary policy, investors are starting to wonder whether fixed income assets like bonds, with their now attractive yields, are better value than stocks. This ‘negative carry’ is a headwind to equities in the short term and re-establishes bonds as a value adding portfolio diversifier, however, long term investors know that only risk assets have historically been able to outperform inflation meaningfully.

Are oil price rises an inflation comeback or just a blip?

International oil benchmark Brent hit $94 per barrel (pb) during trading last Tuesday, the highest level since October last year, when markets and the world economy were still reeling from the Russian war. Higher oil prices can be tough at the best of times but are a major headache for central bankers fighting stubbornly high inflation – referenced by Christine Lagarde when the European Central Bank (ECB) raised interest rates recently. But higher oil prices are difficult for markets as well as policymakers, lifting headline inflation at a time when it is still uncomfortably high and acting as a tax on consumers and businesses unable to pass on costs. Morgan Stanley estimates the inflationary effect of a $20pb increase like the one seen since June would be a 0.5% addition to eurozone inflation. Not an astounding figure after the year we have had, but still an uncomfortable contribution.

With labour markets tight and inflation expectations (up to recently) high, consumers and businesses are now quick to react to higher price signals. Fuel prices are the most visible of these signals. Tight capacity – not just in oil and commodity markets but throughout the economy – means second-round inflation effects are now much more likely. As central bankers are keenly aware, the inflation genie is only just now getting back into the bottle, and hence higher oil prices are keenly noticed. On the other hand, should higher oil prices dampen consumer spending, this could lessen the Fed’s impetus to raise rates or keep them high. The Fed’s own research suggests an oil price increase of 10% takes 16 basis points (0.16%) off consumption and 14 from GDP. Compressing consumption and economic activity is the goal of rate rises, so in that sense higher oil prices may be doing the Fed’s job for it.

Again though, we should be cautious about jumping to conclusions. Core US inflation came in at 4.3% in August, which would still be well above the Fed’s 2% target if it translated directly into future inflation. While the trend is pointing down, the Fed will not want anything to disrupt this – as higher fuel prices surely could. The key point to watch is whether higher oil prices have a bigger effect on consumption and activity, or as a price signal for consumers. Markets nervously await the answer.

Trojan Horse tech

The artificial intelligence (AI) theme is hard to get a handle on from an investment perspective. Are these new technologies a revolution waiting to happen, or a bubble waiting to burst? We are not at dotcom levels of hype (yet), but ‘machine learning’ and ‘language models’ have reached corporate buzzword status. From a business perspective, the obvious benefits come from productivity growth. This has been one of the hardest things to find for more than a decade, low productivity being one of the key reasons behind the period of low growth following 2008’s Global Financial Crisis. Even in big tech, which has long been home to eye-watering stock valuations, there was a feeling some time ago that genuine innovation was lacking – particularly in stagnating markets like smartphones. The AI excitement changed all of that, even if productivity improvements take time to filter through.

Companies have been working on AI for decades and its potential was never exactly a secret, quite the opposite in fact, given that most of the building blocks are open source. Yet it took the release of ChatGPT with its generative language model to really kickstart the financial push in AI’s direction. What changed then was not the technology itself, but the perception of what it could do and how close we might be to world-altering changes.

Of course, entering a new market to fund a longer-term objective of changing the market altogether is a ‘Trojan Horse’-style strategy, and the fact that AI technologies will almost certainly create lots of new revenue streams in the future does not mean all the market valuations, especially on a stock level, are justified. To be sure, the words ‘generative AI’ are certainly good for certain share prices, but overall market appetite is fairly contained, historically speaking. This has surely something to do with the wider financial backdrop too. Interest rates have risen at the fastest pace in a generation, while global growth and near-term demand prospects look weak. In a way, perhaps this forces markets to make a longer-term evaluation.

The question, as ever, is how businesses will turn the current technologies into future earnings. And of course, knowing which companies might do so best would be nice too. Time will tell who the winners will be, and especially whether incumbents will reap the benefits, or whether newcomers can shake up the equity market. For now, though, having a ‘beacon of hope’ for what may generate real growth over the next decade is to be welcomed by investors.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

25/09/2023

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, Brooks Macdonald’s ‘Daily Investment Bulletin’ which provides a brief analysis of global investment markets. Received this morning – 22/09/2023

What has happened?

Both equity prices and bond prices sold off yesterday – the weakness driven by a higher-for-longer interest rate message from central banks this week, as well as better US weekly jobless claims data on Thursday pointing to a still-resilient US jobs market. US longer-dated bond yields hit new highs for the cycle, with the US-10year Treasury yield at one point over edging above 4.5% in trading overnight, which is the first time that has happened since 2007. Meanwhile the US 10yr real yield, up 6.6bps yesterday hit a post-2009 high of 2.11%. Earlier on Thursday, the Bank of England (BoE) narrowly voted 5-to-4 in favour of keeping rates on hold. Of the 9 MPC (Monetary Policy Committee) members, 5 voted for a pause, versus 4 voting for a 25bps hike. This marked the first time the BoE has left rates unchanged in almost 2 years, since November 2021. With markets reading the BoE decision as effectively supporting a higher-for-longer rate outlook as opposed to an even-higher-but-shorter peak, yields on UK government bond gilts rose across the maturity curve, with bond prices falling. In interest-rate derivative markets yesterday afternoon, peak rates were expected to only be around 18bps higher than now, so markets were no longer fully pricing in any more UK rate hikes this cycle.

Bank of England calls time on its 14-meeting rate hike streak

While the BoE’s pause mirrored the US Federal Reserve (Fed) the day before, there the similarity ends. While the Fed delivered a hawkish pause, it did so from a relatively more constructive backdrop, having doubled its real (constant prices) GDP outlook for 2023, while cutting its unemployment rate forecasts. For the BoE, its own pause arguably reflected having to balance inflation risks versus a more cautious economic picture – the BoE on Thursday cut its estimate for UK real Q3 GDP quarter-on-quarter growth from 0.4% to just 0.1% and said that ‘underlying growth was also likely to be weaker’ for the 2H of 2023. Perhaps a little ominously, the BoE also noted that ahead of its rate decision, it had had an early look at the flash UK PMIs (purchasing manager indices) for September which have only just come out this morning at the time of writing – as it turns out, both UK manufacturing and services remain in contractionary territory (with readings under 50), although services is weaker month-on-month, whereas manufacturing is a little better.

Bank of Japan keeps policy unchanged

As largely expected, the Bank of Japan (BoJ) used its latest meeting earlier this morning to keep all its policy settings unchanged. By a unanimous vote, there was no change to its short-term -0.1% negative interest rate policy setting, and no change to its guidance for the 10-year government bond yield target at ‘around zero’. As BoJ Governor Ueda said at the subsequent press conference earlier, “We have yet to foresee inflation stably and sustainably achieve our price target. That’s why we must patiently maintain ultra-loose monetary policy”, adding that “since we published the July outlook report, inflation isn’t overshooting sharply, but it’s not slowing as much as we expected.” Not surprisingly, in currency markets the Japanese Yen has weakened versus the dollar post the announcement. Earlier, the latest Japan all-items CPI (Consumer Price Index) annual inflation print for August came in at 3.2%, the lowest reading for 3 months, down slightly from 3.3% in July, and versus markets which had been expecting a flat 3.3% number. Meanwhile, core CPI (measured in Japan by excluding fresh food but still including energy) was 3.1% year-on-year.

What does Brooks Macdonald think?

The narrowness of the Bank of England vote to pause interest rates highlights the uncertainty around the economic outlook. We have yet to see the full impact of the cumulative 515bps of UK central bank rate hikes since December 2021, given interest rates work with around a lag of 18months or so for the full impact to reach the wider economy. That the BoE again used the phrase for keeping interest rates “sufficiently restrictive for sufficiently long” suggests that it is still keen to temper rate cut hopes anytime soon. All in all, the BoE’s communications seem to be in line with other central banks in distinguishing between an interest rate ‘pause’ and an outright ‘pivot’.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

22nd September 2023

Team No Comments

Evelyn Partners Update – September Bank of England MPC Decision

Please see below article received this afternoon from Evelyn Partners, which reports on the Bank of England’s holding of the base rate at 5.25%.

What happened?

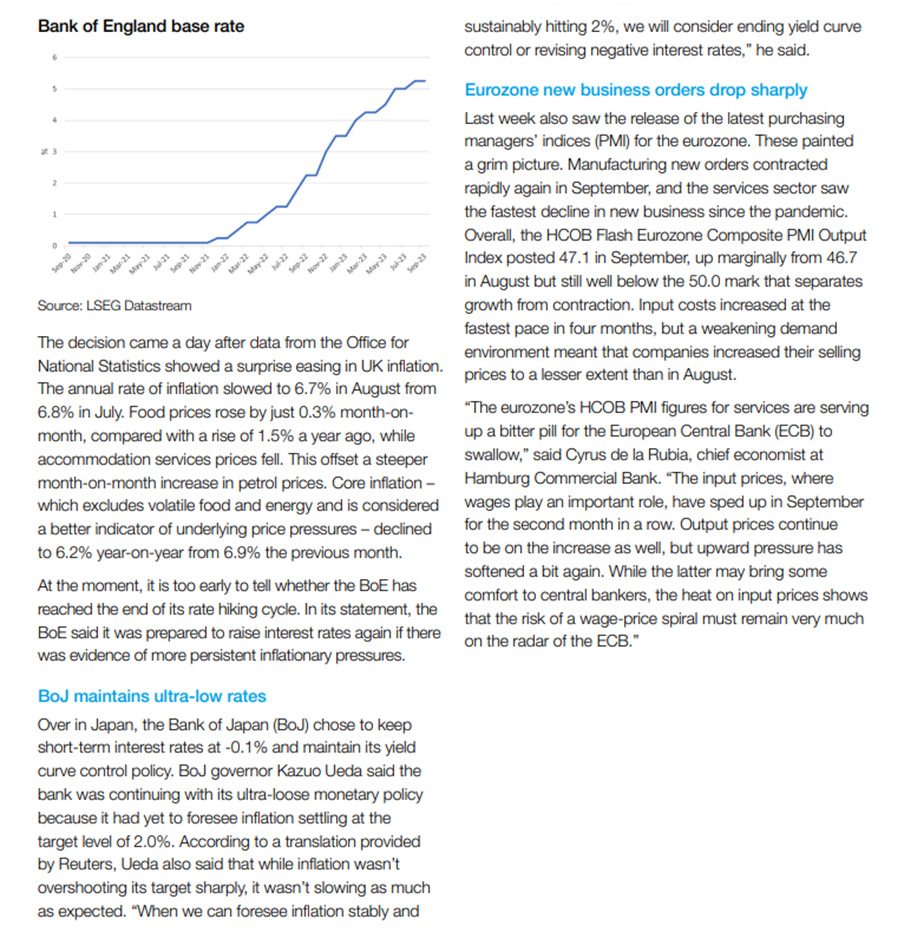
The Bank of England held the base rate at 5.25% at their meeting today. This ends the run of 14 consecutive interest rate increases.

The committee vote was split, with 5-4 members voting in favour of maintaining interest rates.

What does it mean?

Going into today’s meeting, money markets were split 50:50 on whether the Bank of England would raise interest rates. In the end the MPC voted to hold the base rate at 5.25%. Notably, the Bank also said that policy must be restrictive for ‘sufficiently long’, indicating that interest rates will be held higher for longer.

The decision follows some good progress on the inflation front over recent months. Annual headline CPI inflation reached 11.1% in October last year, but it has since fallen by over 4 percentage points. August’s data saw headline inflation surprise on the downside, printing 6.7% year-on-year (vs the consensus expectation of 7.0%). The Prime Minister’s pledge to halve inflation this year, from 10.1% in January to approximately 5% in December, looks to be on track; economists expect inflation to average 4.5% in the fourth quarter of this year.

A key threat, however, comes from the energy sector. The price of oil has increased in recent months as Saudi Arabia and Russia extended voluntary supply cuts to the end of this year. This comes on top of cuts agreed by OPEC+, a group of oil exporters, to the end of 2024. Higher oil prices typically take around one-month to feed through to petrol prices, so we can expect to see higher prices in the coming weeks and months. Another lingering source of inflation in the UK comes from rents, which have yet to peak. Having said that, we still expect inflation to ease in Q4; lower energy costs following the October change to the Ofgem price cap will help households across the country.

In the absence of further shocks, it looks like the BoE is now at, or very close to, the end of its hiking cycle. Attention will now turn to rate cuts, although markets are only pricing one 25 bps cut by the middle of 2024. This is consistent with our expectation that the Bank will keep policy tight through 2024 as they continue to fight inflation.

A continuation of its restrictive policy is supported by the empirical evidence. A recent paper by International Monetary Fund analysed over 100 inflation shock episodes in 56 countries since the 1970. It finds that ‘Countries that resolved inflation implemented restrictive policies more consistently over time’. The BoE and other CBs will be well aware of these findings and will not want to repeat the mistakes of their predecessors by easing policy too early.

In response to the decision, the pound sold-off, hitting its lowest level in six months. While UK equities rallied on the news.

Bottom Line

A close vote saw the Bank of England decide to hold the base rate at 5.25%. We are now at, or very close to, the end of the hiking cycle, but we expect monetary policy to remain restrictive for the foreseeable future.

Please check in again with us shortly for further relevant content and market news.

Chloe

21/09/2023

Team No Comments

Evelyn Partners Update – UK August CPI inflation

Please see the below update from Evelyn Partners sharing their thoughts on this morning’s UK inflation announcement for August:

What happened?

UK August annual headline CPI inflation was reported at 6.7% (Bloomberg consensus: 7.0%), versus 6.8% in July. In monthly terms, CPI was 0.3% (consensus: +0.7%), compared to a fall of -0.4% in July.

What does it mean?

The broad downward trend in inflation is still intact. Back in October last year, annual headline CPI inflation had reached 11.1%, but it has since fallen by over 4% points since then. Much of that deceleration has come from lower energy prices in the transport (i.e. fuel) and housing and household services (i.e gas and electricity) categories.

However, it could be argued that the decline seen in energy prices are in the rear-view mirror. Looking forward, the risk of another leg up in inflation from energy prices has increased a little following the August decision by the Saudis and Russians to implement new crude oil supply cuts into year end. This tightening in supply, along with solid economic growth in the US driving demand, has been behind the 30%-plus surge in Brent crude oil prices since June. UK petrol prices at the pump are edging up to reflect higher crude oil prices. The good news for households is that wholesale natural gas prices have barely budged: though peak winter demand has yet to come. For the moment, there is no evidence of a sharp acceleration in natural gas (or electricity) prices that could impact future inflation data.

Another lingering source of inflation comes from rents within the services category, which has yet to peak. Landlords are probably using a tight labour market lifting wages, higher mortgage rates and increased demand from record net immigration as an opportunity to raise rents.

Nevertheless, surveys of inflation expectations have come down from peaks. The YouGov household survey of one-year UK inflation expectations is currently 4.4%, compared to a peak of 6.3% in August 2022. This suggest that the risk of inflation becoming entrenched in the economy is contained and should reduce pressure on the Bank of England to raise interest rates significantly from here. As it stands, money markets have priced one more 0.25 percentage point rate hike when the BoE’s Monetary Policy Committee next meets on 21 September, and then a pause from there. 

Bottom Line

Despite pockets of inflationary pressures (i.e rents), the broad deceleration trend in inflation is intact and this increases the likelihood that the BoE is close to the end of its interest rate-hiking cycle.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

20th September 2023

Team No Comments

Brewin Dolphin: Markets in a Minute

Please see below, Brewin Dolphin’s ‘Markets in a Minute’ which provides a brief analysis of the key news from markets and global economies over the past week. Received yesterday evening – 19/09/2023

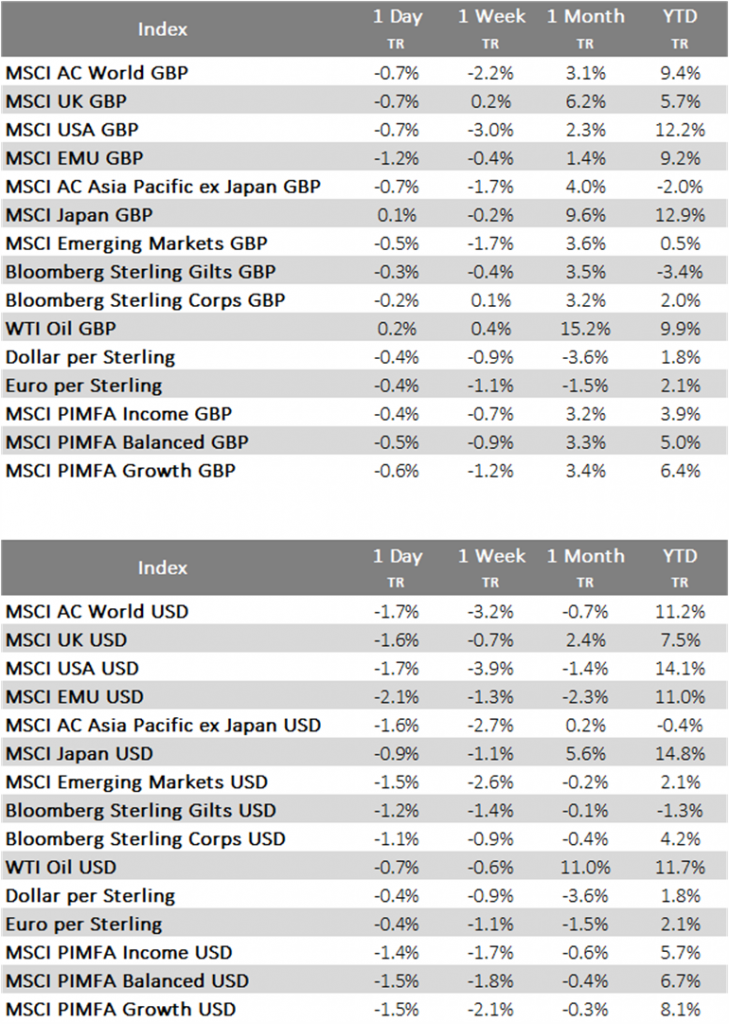
Stocks mixed as US inflation accelerates

Stock markets were mixed last week as an uptick in US inflation raised concerns that the Federal Reserve may be further away from its 2% target than initially thought.

In the US, the S&P 500, Dow and Nasdaq fell 0.8%, 0.1% and 1.5%, respectively. Technology stocks lagged after Apple’s new iPhone 15 received mixed reviews.

In Europe, the Stoxx 600 added 1.3% after the European Central Bank (ECB) hiked interest rates but raised hopes that it could be nearing the end of its monetary tightening campaign. The FTSE 100 surged 2.9% as the pound depreciated against the dollar. A weaker pound helps to support the index because around 70% of FTSE 100 company revenues come from overseas.

In China, the Shanghai Composite ended the week down 0.8% as investors weighed ongoing weakness in the property market against signs of stabilisation in the broader economy.

Investors await key interest rate decisions

Stock markets were mixed on Monday (18 September) ahead of this week’s key interest rate decisions. The impact of rising oil prices on inflation data also weighed on investor sentiment. The FTSE 100 retreated from a four-month high to finish the day down 0.8% at 7,653. The pan-European Stoxx 600 declined 1.1%, while Wall Street indices managed fractional gains.

The Federal Reserve is expected to keep interest rates on hold when it meets this week. However, stronger-than-expected economic data has led to heightened uncertainty about the future path of interest rates. The BoE is expected to hike rates by another 0.25 percentage points to 5.5%. This week will also see policy decisions from central banks in Japan, Brazil and Turkey.

US inflation rate rises to 3.7%

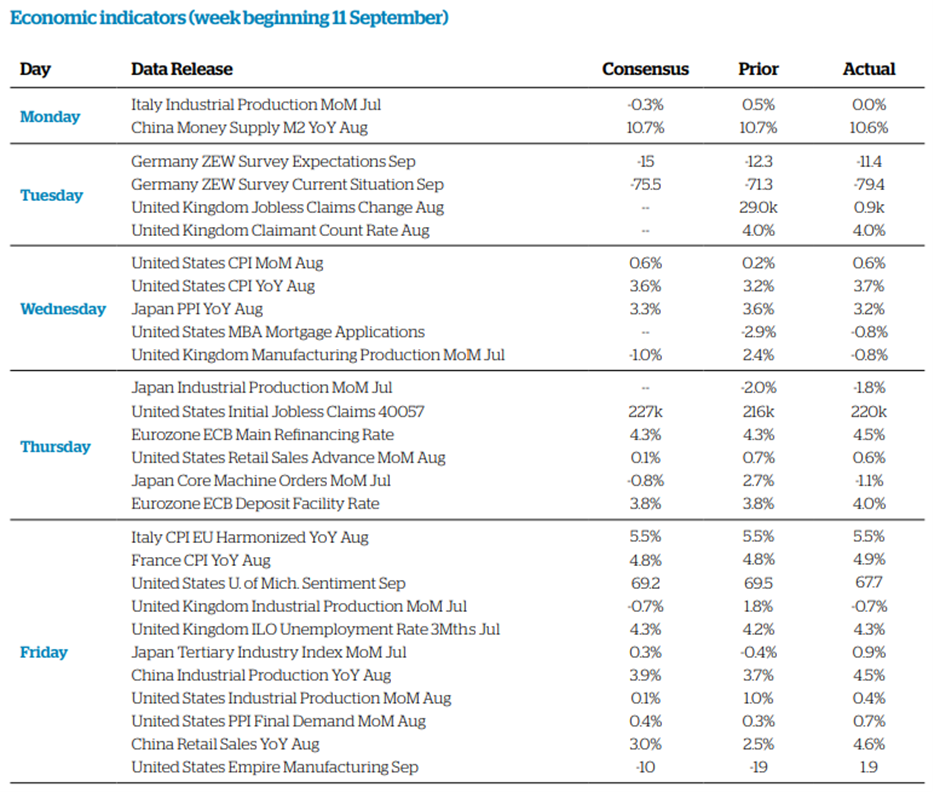
Last week saw the release of the closely watched US consumer price index (CPI) report, which showed inflation rose by more than expected in August, largely because of higher energy prices. The annual rate of inflation edged up to 3.7% from 3.2% in July.

On a monthly basis, prices rose by 0.6% in August, the biggest monthly gain of 2023 so far. Energy prices rose by 5.6% month-on-month, including a 10.6% surge in gasoline prices. Even when volatile energy and food prices were stripped out, ‘core’ CPI rose by 0.3% month-on-month, up from 0.2% in July. This marked the first acceleration in core inflation for six months.

ECB lifts key deposit rate to 4.0%

In Europe, the ECB defied calls for a pause in interest rate hikes, and instead chose to lift its key deposit rate to a record high of 4.0%. There had been speculation that the central bank would keep rates on hold amid signs of a weakening eurozone economy. However, the ECB said inflation was still expected to remain too high for too long, and it was “determined to ensure that inflation returns to its 2% medium-term target”.

The ECB also said rates had reached levels that would “make a substantial contribution to the timely return of inflation to the target”. Commentators interpreted this to mean that the ECB had made its final hike of the current cycle, with some suggesting that rates could be cut in the first half of next year. However, ECB president Christine Lagarde responded by saying: “We have not decided, discussed or even pronounced cuts.”

UK economy shrinks more than expected

Here in the UK, data from the Office for National Statistics (ONS) showed gross domestic product (GDP) contracted by 0.5% in July, which was worse than analysts had predicted. Industrial action by NHS workers reduced health service activity, while extremely wet weather weighed on retailers and the construction sector. For the first time since summer last year, all three major sectors – manufacturing, services and construction – contracted. Nevertheless, Darren Morgan, ONS director of economic statistics, said the broader picture looked positive, with growth in all three major sectors over the past three months.

Chinese retail sales pick up pace

Last week saw some signs of a stabilising Chinese economy, with both retail sales and industrial production growing by more than expected in August. According to the National Bureau of Statistics, retail sales grew by 4.6% year-on-year, up from 2.5% in July and much higher than forecasts of 3.0%. Industrial production also grew by a better-than-expected 4.5% year-on-year, up from 3.7% in July.

On the flipside, fixed asset investment, the historic driving force of China’s growth, missed forecasts, expanding by just 3.2% year-on-year, down from 3.4% in July. This was driven by a deepening slump in real estate investment in China.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

20th September 2023

Team No Comments

Brooks Macdonald – Weekly Market Commentary

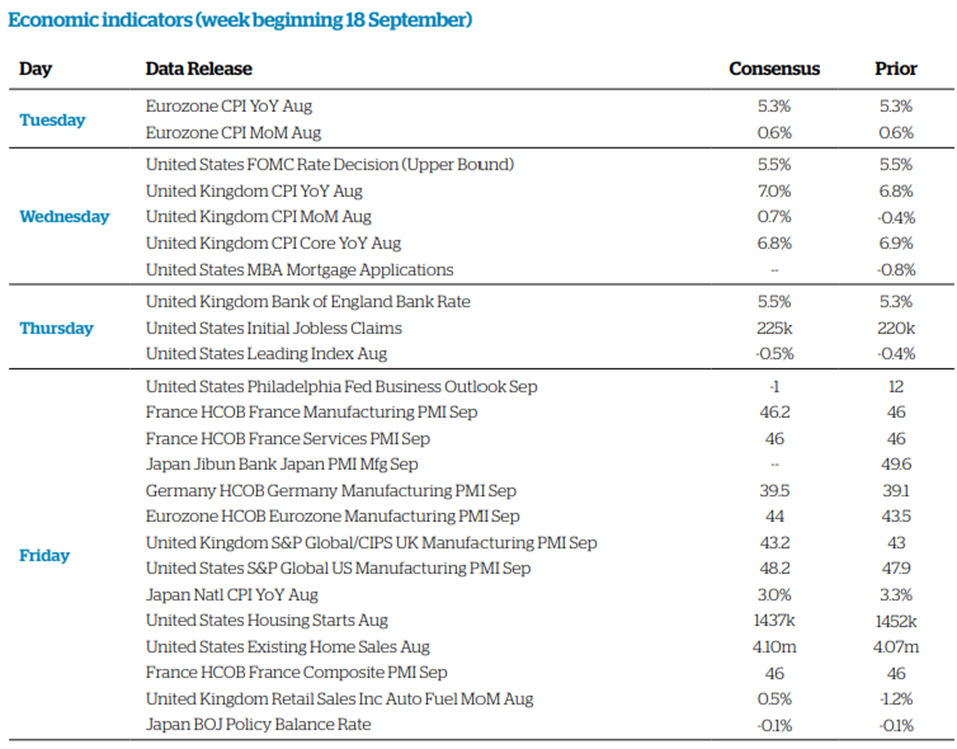
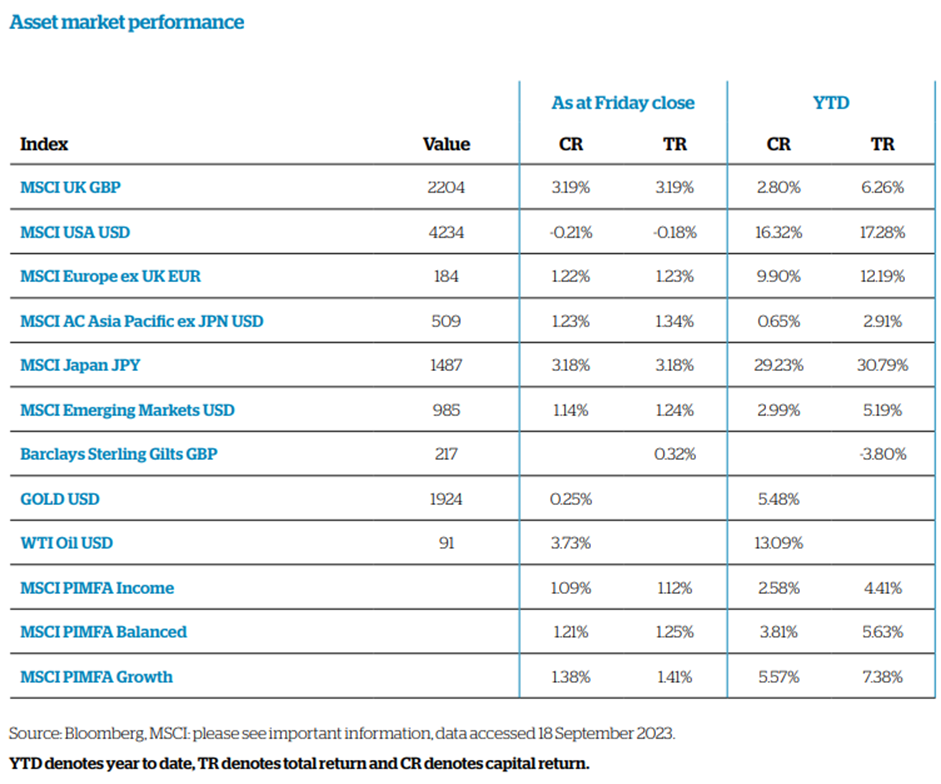
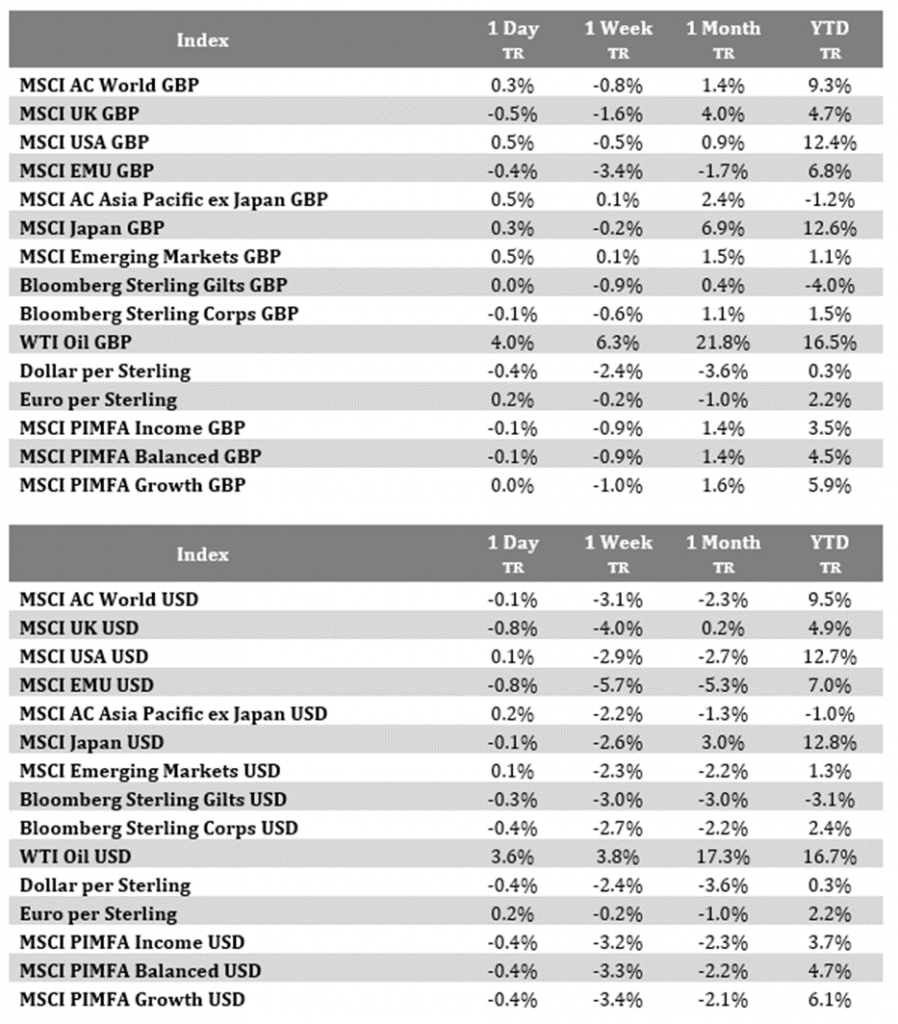
Please see below the latest ‘Weekly Market Commentary’ update from Brooks Macdonald, which covers their views on events in markets over the last week and was received late yesterday (18/09/2023) afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

19/09/2023

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management providing a brief analysis of the key factors affecting global markets. Received this morning – 18/09/2023.

Overview: Central bank hawks still determined to defang inflation

This time last week, it still seemed as if European Central Bank (ECB) policymakers would hold off on another rate hike, following some dire economic data. But on Thursday, the ECB raised its deposit rate once again by 0.25% to an all-time high of 4%. Markets took the somewhat unexpected news in their stride, with only the yields on short-dated money market paper increasing. The tone adopted by ECB President Christine Lagarde reinforced investor sentiment that this begins a period of rate stability that would last for a few months before rates come down again after next spring. Indeed, euro-denominated bond yields fell with increased pessimism about the domestic economy.

Across the pond, US retail sales and inflation showed more strength than expected. Generally, US actual activity data has exceeded expectations for a few weeks as opposed to sentiment data which has been more mixed. And China’s credit growth data (which we discuss in the second article below) has shown a glimmer of light, as did retail sales and industrial production, perhaps the sign of another economic bounce after the myriad of policy announcements.

As we head towards the end of the third quarter, US earnings expectations for next year continue to push higher, which is leading to a relatively broad sense of optimism. It has also been notable that stocks with good earnings expectations momentum have recently turned to being the leading performers rather than ‘thematic’ stocks like those associated with artificial intelligence. In general, institutional investors feel a lot more comfortable when earnings are what is causing equity price rises. Overall, it’s noticeable across the board that volatility and associated risk has continued to edge lower, perhaps signalling a period of steady calm. The strength of the Arm Holdings NASDAQ debut (which climbed 25% after the IPO priced it at $51 per share) has helped as well. The positivity seemed enough to offset another week of oil price rises.

Europe and the UK face some stiff headwinds compared to the Americas and Asia at the moment, and that is feeding through, particularly into the currencies. Both the GBP and the EUR have slid another notch against the USD and, reversing the trend of the previous weeks, are now weakening relative to RMB and stable against the JPY. Without the prospect of near-term fiscal or monetary policy action, this may continue for some time.

The ECB plays its hand, but what will the Bank of England do?

We await the Bank of England’s (BoE) rate decision on Thursday, and many investors are wondering whether it will pause its rate hiking cycle after 14 consecutive hikes. Less-than-encouraging data releases last week have only heightened the tension. The UK’s gross domestic product (GDP) shrank by 0.5% in July, as the double impact of a soggy month and industrial strikes took a toll on growth. Perhaps the ECB’s deliberations after poor data releases offer us a clue to the BoE’s thinking. Catherine Mann, one of the external members of its Monetary Policy Committee (MPC), has already signalled her vote for another rate rise, although other committee members seem more reluctant.

The August survey from the Royal Institute of Chartered Surveyors (RICS) suggested housing sentiment has become notably darker following some mid-summer lightness. They see little house-selling activity and expect prices to go lower in the coming months. This echoed Nationwide’s House Price Index for August, which showed a drop of 0.8% from July. Often, a weaker housing market feeds into the wider economy and lowers inflationary pressures. But we are not really seeing this at the moment. Transaction volumes have been low, and landlords are opting to pass on higher costs (interest rates and possibly energy and maintenance) to their tenants.

The UK’s situation feels oddly similar to the recent problems in China. Xi Jinping chose to deal with the problem of affordability which has had a substantial impact on the domestic economy. Our government has to grapple with the impact on affordability of long-term housing undersupply for both buyers and renters. Elevated tenant demand relative to supply allows landlords to keep rents high or increase them – and that is occurring during this period of change. Meanwhile, the average cost of a house is now about 7.5 times the average annual wage (our calculation from the Nationwide data and Office for National Statistics data), down from 8.5 one year ago. It still has a long way to go before we get close to the pre-2000 level of below 5 times, when interest rates were at similar levels. Either wages will have to keep rising at a reasonable clip for a long time (which comes with inflationary tendencies) or house prices have to fall further, or both.

Chinese growth: no bazooka but lots of bullets

Following its reopening late last year, Beijing has kept up a steady stream of policy supports coming to the sluggish Chinese economy. But these have not been enough to persuade investors of Chinese prospects – least of all foreign investors. Much of the market commentary has focused on whether Beijing will use its ‘bazooka’, a reference to full-throttle stimulus used in previous difficult periods like 2008 and 2015. There is little indication that the government will fire its big gun, but the received view is that investors will not be tempted back unless they do. The short-term growth forces are gathering in China and, with foreign investors already having dumped so much of their stock of Chinese assets (short Chinese equity has become a crowded trade), this is an ‘easier’ base from which to get a rebound in stock prices. The big question for western investors, though, is what all this means for the long term, and whether a longer-term reassessment of how China fits into the global economic and financial picture may be necessary.

The so-called ‘Japanification’ of China – long-term stagnation fuelled by aging demographics and historic asset bubbles – is an increasingly popular narrative, and renowned economist Mohamed El-Erian opined last week that China might not become the world’s largest economy after all. Some commentators have even suggested not stagnation but acute crisis, thanks to a property-inspired financial implosion. We suspect that might be overly pessimistic. While we see the ‘Japanification’ narrative as a little oversimplified, it is fair to say that China’s assets have become much more difficult to call beyond a certain timeframe, predominantly as domestic and international policies have become more influential. Short-term bounces are possible, but we expect the unenthusiastic attitude displayed among foreign investors will continue.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Charlotte Clarke

18/09/2023