Team No Comments

Brooks Macdonald – Daily Investment Bulletin

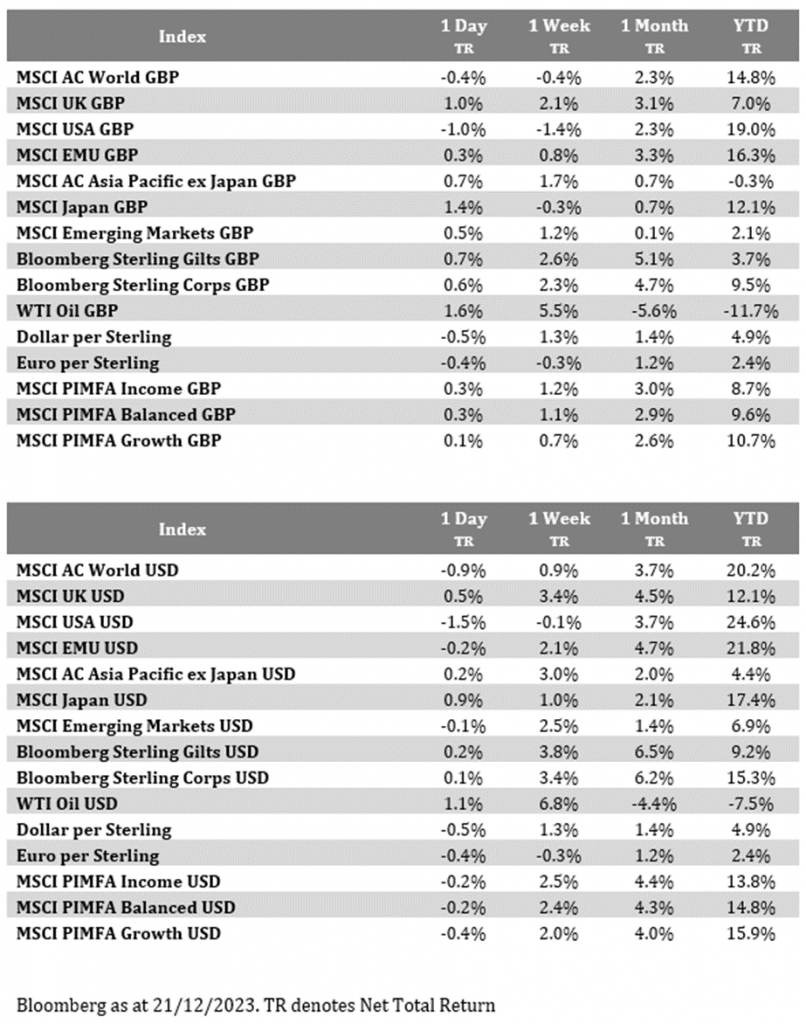
Please see below, Brooks Macdonald’s ‘Daily Investment Bulletin’ which provides a brief analysis of the key factors currently affecting global markets. Received this afternoon – 21/12/2023

What has happened?

The relentless march higher of US equity markets was interrupted late on Wednesday with the headline index off c. -1.5% on the day. The catalyst is not clear however after markets have traded solely in one direction for several weeks, regardless of central bank speakers or the incoming data, a snap back is arguably warranted.

Central banks

Despite the negative tone within equity markets, bond markets continued their rally with the US 10-year Treasury yield falling to 3.85% while the 2-year yield is now just 4.33%. Investors continued to ramp up their expectations of imminent interest rate cuts with bond markets now implying a 92% probability of a cut by March and 1.5% of cuts next year in totality. One of the factors that may have caused the sharp sell-off late yesterday is the growing gulf between the Fed’s dot plot of interest rate expectations and what is priced into the market.

Inflation

There was good news for the UK yesterday as headline CPI inflation fell more than the market was expecting to 3.9%. This was 0.4% below expectations but the Core CPI number, which excludes food and energy, saw an even more dramatic move lower, coming in at 5.1% versus 5.6% expected. Investors increased the number of interest rate cuts they are expecting from the Bank of England in 2024 and the gilt yield curve rallied. Over in Germany, the Producer Price Index inflation numbers showed significant deflation with the index contracting by -7.9% year-on-year compared to -7.5% expected. This helped European bond markets share in the rally seen in the US and UK.

What does Brooks Macdonald think?

On top of the positive inflation stories yesterday, the Conference Board’s US consumer confidence showed a resilient US consumer. Despite this, equities fell quite substantially at the end of the day which suggests a degree of investor fatigue around quite how quickly the market outlook has shifted from bleak at the end of October to unashamedly bullish by the end of the year.

Please continue to check our blog content for advice and planning updates from leading investment managers.

Alex Kitteringham

21st December 2023

Team No Comments

Evelyn Partners Update – UK November CPI inflation

Please see below article received from Evelyn Partners this afternoon, which provides an economic update as we approach Christmas and the end of 2023.

What happened?

UK November annual headline CPI inflation was reported at 3.9% (consensus: 4.4%), its lowest pace in over two years, versus 4.6% in October. In monthly terms, CPI fell 0.2% (consensus: +0.1%), compared to remaining flat at 0% in October.

November annual core CPI (excluding food, energy, alcohol and tobacco) was 5.1% (consensus: 5.6%), versus 5.7% in October. In monthly terms, core CPI was -0.3% (consensus: +0.2%), versus 0.3% in October.

What does it mean?

Today’s encouraging inflation print confirms the continuation of the downward trend in inflation. Just over a year on from headline CPI peaking at 11.1% in October 2022, it has since decelerated by over 7% points, with much of that deceleration in the headline rate coming from lower energy prices in the transport (i.e. fuel) and housing and household services (i.e. gas and electricity) categories. What was even more promising was the downward movement in core inflation, which has decelerated to its lowest rate since January 2022.

As it stands, Brent crude oil prices are now down roughly 4% for the year despite heightened geopolitical risk in the Middle East and OPEC+ output cuts. This reduces the risk of upside in retail petrol and diesel fuel prices. This weakness in oil prices has been reflected in the CPI basket for transport which decelerated by 1.7% in November. On an annual basis this segment of the economy is now exhibiting deflation, with the 12-month inflation rate turning negative.

Looking elsewhere in the divisional breakdown, goods inflation has now decelerated to 2.0% on an annual basis. While services, although slowing, remains more resilient at 6.3% for the last 12 months.

Food and non-alcoholic beverages continue to put pressure on the wallets of households, with this segment exhibiting the highest monthly inflation rate for any category at 0.3% for November. On an annual basis, prices in this segment have risen by 9.2%.

Bottom Line

With both headline and core CPI inflation slowing at a faster rate than expected in November, this should reassure policy setters at the Bank of England that high interest rates are having the desired effect of materially decelerating inflation. The Monetary Policy Committee should now be able to focus on when to cut rates, rather than if additional tightening is required. Money markets are currently expecting these interest rate cuts to materialise in the second quarter of 2024.

Please check in again with us soon for further relevant content and market news.

Chloe

20/12/2023

Team No Comments

Brewin Dolphin Markets in a Minute

Please see below article received from Brewin Dolphin yesterday afternoon, which comments on US inflation figures, interest rate decisions from the Federal Reserve and Bank of England, and Chinese economic data.

The glass is very much half full for the investment world at the moment, with good news being taken as such and bad news being shrugged off.

Continuing the theme of the last two months, gains have come from the anticipation of a more benign inflationary outlook. European inflation numbers have seemed to endorse that view, dropping quite sharply over the last few months. US inflation has been more nuanced; data released last week were broadly in line with expectations, but the underlying composition of inflation could give cause for concern.

US core inflation picked up during November to a pace that would be inconsistent with the Federal Reserve meeting its inflation target. It is well understood that core inflation is heavily influenced by shelter, and shelter inflation will reflect rents and changes in house prices with a lag, representing the time it takes for tenancy agreements to be renewed. That means there should be some disinflation to come from the housing slowdown that has already occurred. More recently, the impact of housing on the consumer price index (CPI) has become clouded. Demand for new housing seems depressed but house prices have been rising for the last few months. The recent sharp decline in bond yields means that US mortgage rates have been declining, which ought to offer further support for house prices and have some knock-on effect for shelter CPI.

Moreover, the Fed looks beyond core CPI these days to try and gauge underlying price pressures. While core inflation strips out volatile food and energy prices, so-called ‘supercore’ inflation comprises services inflation excluding energy and housing. This measure should reflect the general level of inflationary pressure driven by the balance of the labour market. It accelerated slightly this month and has been running ahead of the Fed’s implied inflation target for the last four months.

Interest rates

With this backdrop, the Federal Reserve announced its latest changes to monetary policy. Broadly, policy was left unchanged, as had been universally expected, but the press conference and statement surprised the market by being more dovish than anticipated. The Fed cut its inflation expectations and raised its growth expectations for what is left of 2023. More meaningfully, it also lowered the expected interest rate at the end of 2024 to a level that implies three interest rate cuts will take place over the year. This comes at a time when the Fed is also expecting inflation to remain above target (albeit only modestly). It is surprising the Fed would endorse rate cuts whilst seeming to tolerate above target inflation. For context, market-based interest rate expectations moved lower and now imply nearly six interest rate cuts over the next twelve months.

Labour markets are the key determinant of the inflationary environment but are often observed to be lagging indicators. By the time the unemployment rate has started rising, it has often developed a momentum that makes it difficult to stop. The fear of this, at a time when Fed chairman Jerome Powell believes policy is “well into restrictive territory”, will be the motivation for this dovish tilt.

One factor that has been helpful in curtailing inflation in the US is the relatively benign performance of wages. Wage growth peaked around the turn of last year in America but has not yet done so definitively in the UK or eurozone.

Europe

That discrepancy probably motivated the Bank of England (BoE) in its more hawkish tone. Three Monetary Policy Committee (MPC) members voted to raise interest rates again, believing there was evidence of persistent inflationary pressure. They were outvoted and policy was left on hold.

The MPC decision came after the release of quite weak monthly gross domestic product (GDP) data on Wednesday, on top of Tuesday’s relatively poor labour market data. BoE governor Andrew Bailey took a more predictable line, emphasising the battle to contain inflation was not yet won and the Bank would “take the decisions necessary to get inflation all the way back to 2%”.

All central banks become heavily motivated by the latest economic data at potential turning points in interest rate cycles. The data for the UK does seem quite weak, whereas there are tentative signs of the European economy recovering some momentum. This morning saw a slight setback in the purchasing managers indices for Germany and France. This was mirrored by the UK’s ailing manufacturing sector but bucked by the UK services sector, which expanded faster for a fourth consecutive month.

Meanwhile, in the east…

A lot of data was released last week detailing the Chinese economy. There are some signs of recovery, with annual growth numbers like the 10% expansion in retail sales seeming quite healthy. This is somewhat illusory though, as China was in lockdown this time last year. The thorn in the side of the Chinese economy remains the property market. Data released today showed the continued decline in new home prices. It comes after the conclusion of the Central Economic Work Conference (CEWC). The post-meeting communique signalled some measures would come in to try to bring relief to the Chinese economy. But the promise was vague and modest, suggesting perhaps a couple of interest rate cuts and a further easing of required reserves at banks (which would enable them to lend more to the economy).

China maintained its growth target of around 5%, which sounds ambitious given the weakness of the economy. But, again, this reflects the fact that last year, China was in lockdown, and so growing 5% from that depressed level should be neither taxing nor impressive.

Please check in with us again soon for further relevant content and market news.

Chloe

20/12/2023

Team No Comments

Brooks Macdonald: Weekly Market Commentary

Please see this week’s Weekly Market Commentary from Brooks Macdonald which provides a brief analysis of the key factors currently affecting global investment markets:

  • The Santa Claus rally is underway after the Federal Reserve allows the market’s interest rate pivot to continue
  • Despite pushback from some Federal Reserve speakers, markets expect the first US cut during Q1 2024
  • Meanwhile, the Bank of Japan may only now exit its negative interest rate policy this week

After the Federal Reserve endorsed the market’s dovish pivot of US interest rate policy, risk appetite received a significant boost. By the end of the week, the US bond market implied 141bps of interest rate cuts by the end of 2024 and an over three-quarter chance that the first cut would take place by March. Bonds rallied against this backdrop with both the 2-year and 10-year yields down c. 0.3% on the week, this marks the best week for US Treasuries since the extreme market volatility of March 2020. Equities also performed strongly with the US leading the way with a 7th consecutive weekly advance.

Despite the Fed meeting sounding relatively dovish, Fed speakers on Friday were keen to push back against the growing consensus around a Q1 2024 first cut. President Williams said that the Fed ‘aren’t really talking about rate cuts’ yet and that March felt ‘premature.’ President Bostic struck a similar tone, saying that he wasn’t ‘really feeling that this is an imminent thing.’ Bostic suggested that the Fed may only start cutting interest rates from Q3, offering a counterweight to the strong bond market rally of last week. By the end of Friday the market had reduced the quantum of cuts expected in 2024 by 8bps.

The central bank focus will continue this week even as we approach the Christmas period. There has been much speculation as to whether the Bank of Japan’s negative interest rate policy would be ending at this meeting, with the market apportioning a rough 50:50 chance of that outcome. Reports have suggested that the Bank of Japan may hold off an announcement this week but strongly signal the move as ‘live’ for January’s meeting.

Whether the policy comes to an end at this meeting or next meeting is an aside to the remarkable fact that the US has gone through a full rate hiking cycle but that the disinflationary forces in Japan have been so powerful that only now is a positive interest rate on the cards.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

19/12/2023

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below Tatton Investment Management Monday Digest article received this morning – 18/12/2023.

Policy and politics set to play a pivotal role in 2024 

Heading into 2024, capital markets are in a somewhat contradictory position. Global growth has been slow (and in some places negative) for some time, while central banks have raised interest rates at the fastest pace in a generation. But despite all those challenges, equities have had a good year overall. With inflation finally falling, central banks are now loosening their vice grips, and bond markets are predicting a slew of rate cuts from the major players starting as early as March. That has pushed risk valuations in favour of equities and, perhaps more importantly over the long term, has even bolstered growth expectations. How these expectations play out will be crucial for markets next year.

And yet, anxiety lingers. The rise in equity valuations has left stocks looking a little expensive, particularly in light of damp growth expectations in some regions. And despite the fact that no one seems to believe them, central bankers beyond the US are still toeing the official line that rates will have to stay higher for longer pretty much everywhere. 

The consistent theme of this year has been that whenever markets look overexcited, monetary policymakers pour cold water over rate cut expectations. The policy outlook has become the dominant driver of markets, and ignoring what policymakers tell us has made for a volatile ride in investments all year. We expect this to continue for at least the early part of 2024. Ever since the financial crash of 2008, investors have been extremely sensitive to expected monetary policy, and 2023 was no different. This is historically unusual, but it could just be because – for most of that period – rates have been historically low. Rates staying lower for longer increases the sensitivity to rate changes because longer-duration assets gain in relative value and thus make up a larger share of the market (the so-called duration effect). Now that real interests (inflation-adjusted, i.e. what is left after inflation is subtracted) have moved higher, it is possible we will see fewer valuation effects and more focus on earnings stability and growth.

Growth prospects for the UK and Europe greatly deteriorated this year, while the US powered ahead thanks to the incredible resilience of the American consumer and considerable fiscal stimulus. Now, with inflation plummeting, interest rates will surely follow here and in Europe. Across the Atlantic, however, and regardless of the latest Fed acknowledgment that rates have peaked, market expectation remains that looser policy there might take some time. As we go through 2024, that could mean underperformance in the world’s largest economy – a reversal of what we have seen for years. If that happens, bond and equity dispersion will be joined by currency volatility. Such volatility makes firm predictions difficult. Looser monetary policy and (in the latter half of the year) an economic recovery in Europe are likely. Beyond that, unfortunately, we can only predict unpredictability.

Outlook for regions

US: The US was indisputably the standout performer this year, with US equities once again outperforming other markets. But the US economy might not be as strong as its global peers in 2024. Partly, this is about starting points; the US has grown more quickly than the rest but that growth did not spread outwards in 2023. Next year could see US demand providing more external support. That past strength is also likely to keep the Fed relatively less accommodative than other central banks (despite investors perceiving a dovish shift in the Fed’s policy following its December 2023 meeting). This could mean underperformance in US markets relative to Europe or even Emerging Markets. Currency volatility may result, perhaps continuing the recent trend of dollar weakness, which is again generally a growth positive for the global economy. There is also the small matter of a presidential election next year, which is likely to bring further spending promises and plenty of political instability. That being said, energy – especially natural gas and electricity – is much cheaper than in Europe and nowhere looks ready to match the depth and dynamism of the US economy.

The US might well become the victim of its own success in 2024. The liquidity from the pandemic period still is yet to be worked off. Meanwhile the lagged impacts from the pandemic-inspired loose fiscal stance are likely to keep the Fed from cutting rates as early as the European Central Bank (ECB) in Europe, even though growth is weakening. Markets seem to have a rosy view of Fed policy at the moment and so could end up disappointed. In our view, interest rates are likely to come down in Europe (and possibly even in the UK) before the US. These factors could bite in the second half of the year. At that point, Fed policy will have sucked up most of the excess liquidity while real disposable income growth may be slowing (possibly as wages growth slows and goods deflation lessens). We may even see the US flirt with recession. If so, currency volatility and, hence, wider market volatility, is likely.

UK: Monetary policy is perhaps the most important part of Britain’s outlook for 2024. Despite the perceived hawkishness of the Bank of England’s Monetary Policy Committee (MPC), we expect interest rates to come down, thanks to inflation finally falling back to target, and rate cuts should be underway by the summer. This will mean falling bond yields and a pick-up in equity valuations. UK equities are notably cheaper than global counterparts on a price-to-earnings basis, reflecting years of neglect by foreign investors. Valuations have plenty of room to climb and – since we expect positive bond market movements – Britain looks good value.

Next year will almost certainly see another General Election (though the latest possible date is January 2025, which is unlikely but cannot be fully ruled out) which, barring an historic turnaround, is likely to deliver a Labour government. Given Keir Starmer’s cautious approach, though, we do not expect this will dramatically change medium-term growth prospects or financial conditions. There are some hopes that trade negotiations with Europe might be improved by a structurally less antagonistic government, but any effect from this will likely be long in the future. Overall, it will likely be slow and steady for UK investors, but starting from a low base will help.

Eurozone: Economic weakness should mean supportive European monetary policy early in 2024. With any luck, and with the global economic tide potentially turning, this could translate into stronger growth in the second half of the year. These cyclical factors, combined with the relative cheapness of European equity versus the US, should mean market outperformance as of late, but risks remain. There is a risk that the European Central Bank (ECB) has overtightened already, throwing the fragile economy into deeper recession than needed. On the other hand, the continent is still recovering from its energy price shock and the fiscal deterioration it brought. We do not think these factors will disrupt what is ultimately a positive story, but we must stay wary.

We expect tight fiscal policy to be a feature of most major regions in 2024, but probably more so in Europe. That only increases the urgency of the ECB’s rate cuts, which are now a matter of when not if. Headline Eurozone inflation has been on a downward path for months. Markets have subsequently brought forward their rate cut expectations to as early as March. And even then, many commentators are suggesting the ECB is once again ‘behind the curve’ on inflation – only this time in reverse. With so much gloom around the Eurozone economy, growth optimism may seem strange. But looser monetary conditions and a recovery in global growth are sure to benefit the Eurozone. European equities are some of the most cyclical there are; the start of a new cycle should serve them well.

Emerging Markets: If our central scenario of a global cyclical recovery and weaker dollar plays out, Emerging Markets (EMs) stand to benefit in 2024. This would be helped by a Chinese economic recovery, particularly if consumers there felt confident again. With the inherent economic and financial risks surrounding the world’s second largest economy, EMs would do well to focus on securing their own prospects. Fortunately, this is already underway, particularly for regions like Brazil that sorted their inflation problems early.

For China, the main question is now not whether Beijing is willing to soften its deleveraging stance and promote growth, but whether it can. Private sector business confidence appears to have plummeted when one looks at market-based indicators. While government borrowing is now rising, private sector borrowing continues to decline.  The recent spike in consumer default numbers, and the weak pricing power for goods exporters, suggests it might not be so easy. Even with central government support, we expect China to radiate disinflation for at least the early parts of 2024.

The green shoots of a global recovery, if and when they show, should boost sentiment around EM assets. But with the global economy in such a precarious position, 2024 will likely be another year where differentiating between EMs is key. 

Outlook for asset classes

Bonds: In line with our expectations for government and central bank policies, we expect bond market dispersion in 2024. Despite ECB President Christine Lagarde indicating a continued bias towards tightening, a mild tightening in fiscal policy, softening wage rises, energy price falls and generally lower inflation should allow interest rates to fall sooner in Europe than in the US. That is likely to mean a widening of the gap between US and European yields in the early part of the year. 

Shifts in the long-term risk premia – how long-term bonds are valued against short rates – have become more prominent in 2023. These have fallen sharply since October, dropping below historic averages. With inflation still lingering, we expect them to move higher in 2024 – primarily in the US. Relative risk valuations will impact credit spreads too, but these have thankfully been resilient. Even though growth is weak (and in some cases negative) investors do not seem to fear widespread bankruptcies or financial instability. That is good, since it will likely mean a ‘buy the dip’ mentality in corporate bond markets.

Equities: We expect global equities to be a tale of two halves, especially in the US. The heavily anticipated global recession – if it comes – will mean stagnant or falling corporate earnings, lowering the base attractiveness of stocks. On the other hand, a lot of that negativity is already priced into current equity values, after global stock markets saw heavy losses in 2022. Investors are tempted to look forward to the cycle after this one – when central banks will loosen policy and growth can start again. Optimists are hopeful about the next cycle, pessimists are still worried about this one, and everyone else is caught in the middle. Markets will likely go back and forth between these two modes until the underlying economic data makes it clear who is right.

The strength of the US equity market, much like its domestic economy, has been unparalleled in recent years. In particular, the outperformance of the US mega caps was stunning in 2023. Share prices for the so-called ‘Magnificent Seven’ – the most highly valued companies in the S&P 500 – increased by more than 70% in response to the generative AI investment craze, while the remaining stocks in the S&P gained just 10%. Whatever the justification for this outperformance, it means the US continues to be more expensive (on a price-to-earnings basis) than anywhere else.
 
Comparatively, British and European stocks are trading at cheap valuations. This is certainly true for the UK, whose attractiveness as an investment destination has been in decline since before Brexit. These, historically relatively cheap valuations are still a little pricey in absolute terms, at least for where interest rates are. But Europe’s rate cuts are effectively confirmed at this point, while we have argued elsewhere that the UK must follow suit. If global growth is stronger than expected, British and European equities stand to benefit.

The rest of the global equity picture is mixed for 2024. In Japan, improvements in corporate structures have gone under the radar in recent years, but it is clear that companies and shareholders are seeing the fruits of structural change. Margins are improving (from admittedly low levels) and Japanese workers are among the cheapest in the world for their skill levels. Any pick-up in exports (which can only come from a global cyclical rebound) will likely have second-round effects on wages and domestic demand, making Japanese stocks a worthwhile bet.

Currencies: Assuming our policy and economic outlook holds up, the US dollar should decline in 2024, but with bouts of volatility in currency markets. The dollar has become undeniably expensive over the last few years – thanks to impressive capital flows into the US – and this process has to stop at some point. There is every reason to think that point will come next year. Even a mild outperformance from outside of the US would likely cause some capital outflow, lowering the dollar’s value. The Japanese yen could be a particular beneficiary – considering its current cheapness on a purchasing power basis.

Commodities: Commodity prices – oil and gas in particular – will probably stay weak into the start of 2024. As the year goes on, though, global growth expectations should shift. Global growth usually means stronger commodity demand, so prices should be supported. But the amount of support depends on many factors, like where growth is expected to come from and in what form. Outside of oil and gas, metals have slowly lost ground – with the exception of iron and steel. This will not turn around until growth recovers, which is unlikely before the middle of 2024.

The biggest demand swing could come from China, whose government has made clear it prioritises consumer demand and building activity. If Beijing keeps revving the economy, prices for commodities in general will be well-supported. In this sense, we should keep an eye on commodity prices, as these could signal a wider recovery.

Property: There is potential for a property rebound in 2024, but whether it happens will depend on policy. The past year has been difficult for residential property, but activity has picked up across the world – even in China’s ailing building sector. This happened after the fall back in long-term bond yields, which suggests current rates are cheap enough to spark building activity. 

Commercial real estate, on the other hand, is still in a clearing phase. The stable, post-pandemic level of demand for retail and office space is not yet clear, while input costs (including insurance) are also in flux. The end of 2023 has seen European real estate investment vehicles come under pressure – a trend that will likely be repeated across the world.

The biggest hope for property prices is government building policy. Next year will see nearly half the world’s population go through elections, and building is an easy sell for most politicians. In multiple regions, we have already seen suggestions of looser planning regulation. This has the potential to unlock substantial amount of growth for the wider economy. Prospective governments might see this as an easy win, considering that many building projects are at least partially funded by private groups, lowering the spending that appears on their balance sheets.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Charlotte Clarke

18/12/2023

Team No Comments

Evelyn Partners Update – December Bank of England MPC Decision

Please see the below article from Eveleyn Partners detailing their thoughts on today’s Bank of England MPC decision to continue to hold interest rates at 5.25%. Received this afternoon 14/12/2023.

What happened?

The Bank of England (BoE) held the base rate at 5.25% at their meeting today. This was the third consecutive meeting at which they have held rates at this level and was in line with market expectations.

The committee was split in its vote, as it was in November, 6-3, with the three external members of the committee continuing to prefer another 25bps increase.

What does it mean?

Today’s decision by the Bank of England will not come as a surprise to markets.  What is of interest is the tone and rhetoric of the statement today. The Bank maintained its hawkish stance, that rates would need to be “sufficiently restrictive for sufficiently long” and leaving the door open for further tightening should inflationary pressures persist. That contrasted with yesterday’s FOMC statement which took a more dovish tone.

The economic backdrop to today’s meeting remains difficult. The economic data has been mixed since their November meeting, and the while progress on inflation has been made, uncertainty remains around the outlook. CPI inflation has fallen by 2.1% to 4.6%, undershooting the committee’s estimate of 4.8%. In terms of real GDP, October figures showed a 0.3% contraction, which leaves the economy set to undershoot the Banks 0.1% estimate for growth in Q4.

The fiscal backdrop has also changed, with the Chancellor easing policy in the Autumn statement and government suggesting there might be more to come in the Spring Budget, potentially adding inflationary pressure.

After the November MPC meeting, the first cut in interest rates had been priced in for August 2024. Since then, markets have grown increasingly optimistic about the timing of rate cuts – expected in May shortly before today’s meeting and remained little changed immediately after.

Bottom Line

We think the UK economy faces more inflationary challenges than some of its global peers, in particular the US, and would suggest the market for UK rates has been swept up recently in a wave of euphoria over interest cuts coming sooner than previously expected. Our view is that while the direction of travel is correct, there is risk that markets are disappointed when cuts do not come through as quickly as currently priced in.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

14/12/2023

Team No Comments

Evelyn Partners Update – December FOMC monetary policy decision

Please see the below article from Evelyn Partners detailing their thoughts on the Fed’s decision to continue to hold interest rates at their present level. Received this morning 14/12/2023.

What happened?

The Federal Open Market Committee (FOMC) voted to keep rates on hold at 5.25-5.5% for the third meeting in a row. This marks the end of the US tightening cycle.

What does it mean?

Last night we received some good news from across the pond: the US Federal Reserve signalled that the tightening cycle is over, and it will pivot to easier monetary policy next year.

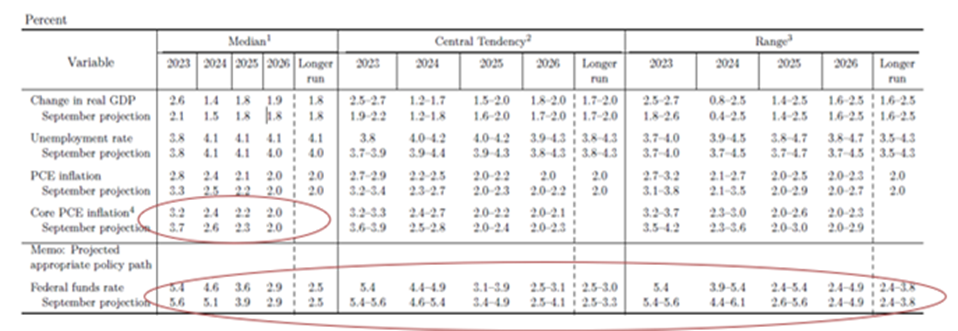
This signal came via three sources. First, the summary of economic projections, which collates the forecasts of committee members, showed that monetary policy is likely to be easier next year. The projections show that the median expectations for interest rates in 2024 were revised down from 5.1% to 4.6%—a notable move given that the previous forecasts were only submitted 3 months. This change was driven by a major downside surprise in the recent inflation data: the committee now expects core PCE inflation to be around 3.2% for 2023, instead of 3.7%.

Second, the dot plot – which maps the committee’s projections in more detail – also showed a notable decline in interest rates in the coming years.

In response, the Fed funds futures, which capture market-implied future interest rates, moved to price in 6 cuts next year, instead of the 4 expected before the meeting. The Fed isn’t expected to cut at its next meeting in January, but the market then anticipants three consecutive cuts from March to June, and it assigns a high probability of cuts in July and September. 

Third, Chair Powell half-heartedly pushed back against the market’s dovish interpretation of this evidence. He noted that it was “too early to declare victory” but admitted that the committee had been talking about when to cut rates. He also said that the Fed would need to start cutting rates “way before” inflation reached its 2% target. These statements imply the next step will be to cut rates.

Unsurprisingly, markets rallied strongly on this news. The S&P 500 and Nasdaq gained ~+1.4%, while the US 10-year yield fell below 4% having topped 5% as recently as September.

Bottom Line

Last night the US Federal Reserve signalled that the tightening cycle is over, and it will pivot to easier monetary policy next year.

Unsurprisingly, markets rallied strongly on this news. The S&P 500 and Nasdaq gained ~+1.4%, while the US 10-year yield fell below 4% having topped 5% as recently as September.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

14/12/2023

Team No Comments

Brewin Dolphin – Markets in a Minute

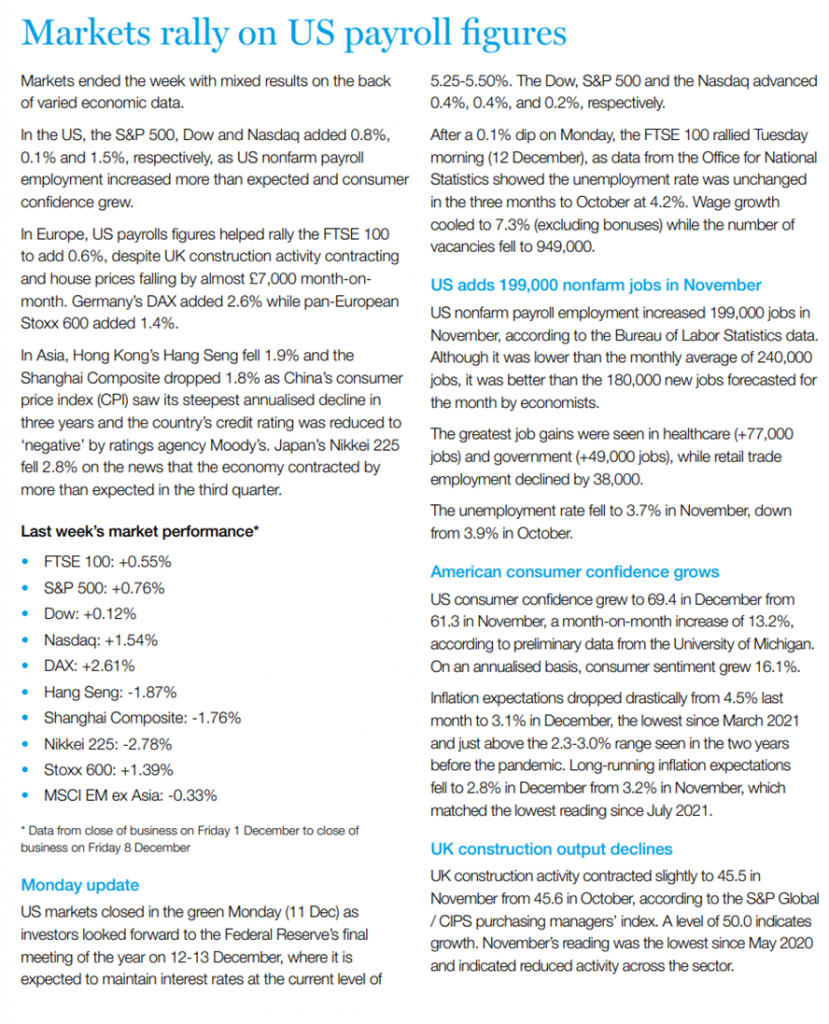
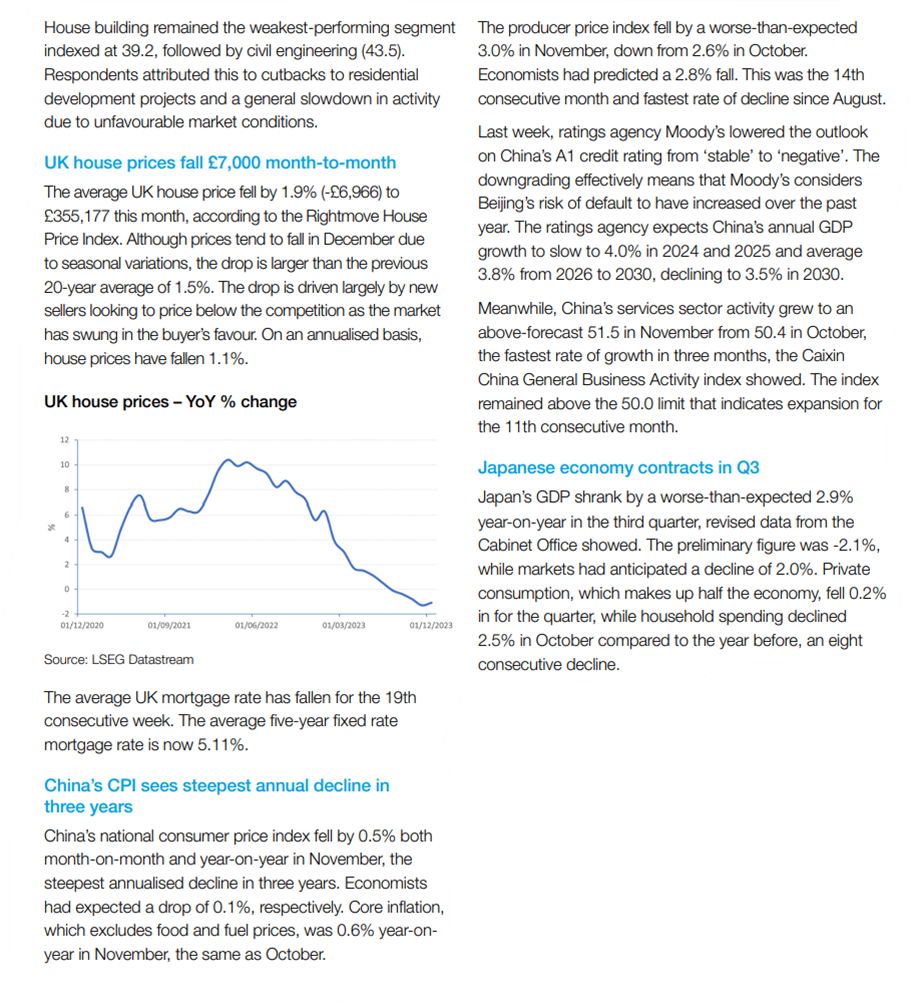
Please see below the latest ‘Markets in Minute’ update from Brewin Dolphin, which covers their views on recent events in markets and was received late yesterday (12/12/2023) afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

13/12/2023

Team No Comments

Brooks Macdonald: Weekly Market Commentary

Please see below, Brooks Macdonald’s ‘Weekly Market Commentary’ which provides a brief analysis of the key factors currently affecting global investment markets. Received yesterday afternoon – 11/12/2023

Despite the US equity market now posting its 6th consecutive weekly gain, there should be no complacency ahead of this week which sees a Fed meeting, an ECB meeting and perhaps most importantly, a US CPI print.

Before we move onto this week, we should acknowledge the US employment report which was slightly stronger than markets were expecting on a headline level and saw the US unemployment rate fall to 3.7% versus the 3.9% expected. Average hourly earnings were also slightly stronger than expectations. Taken as a whole, the US jobs report pushed back against the soft-landing narrative and expectations for a near immediate loosening of policy. There was some good news on Friday however as the University of Michigan survey showed 1 year inflation surprising to the downside, coming in at 3.1% versus the 4.3% that was expected.

The jobs report is likely to dissuade the Fed from sounding too dovish this week and markets also reduced the implied number of interest rate cuts in 2024 as a result. The key question for Wednesday’s Fed meeting statement will be whether the Fed explicitly rebukes the market’s pricing of around 4½ 25bp interest rate cuts in 2024. With the jobs report in recent memory, the Fed is likely to strike a more cautious tone, saying that while rate rises are likely finished, this does not mean rate cuts are imminent. The tone of the statement and press conference will be key, as will the dot plot of interest rate expectations. The ECB and Bank of England will report on Thursday, with expectations of a pause in interest rates from both central banks.

Before we get to the trio of central banks, markets will need to contend with the US CPI release on Tuesday. The consensus expects there to be no month-on-month inflation at a headline level and 0.3% growth for Core CPI. The major difference between these two readings is the gas price which is down -8% since October and is excluded from the Core CPI reading. The two-day Federal Reserve meeting will already be underway when the CPI report lands but it is undoubtedly going to feed into their thinking if we see an upside or downside surprise.

Please continue to check our blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

12th December 2023

Team No Comments

Overview: Expectations of a US ‘soft landing’ increase

Please see below ‘Monday Digest’ article received from Tatton this morning, which provides a global market update as we approach Christmas.

After a gangbusters November for global capital markets, December is also currently on a positive track with trading volumes higher than November’s averages generally, suggesting quite a bit of capital is being put to work by investors.

Global bond yields have fallen yet again (meaning bond prices have risen), driven by fears of slowing global growth. Economic data has been mildly soft, while energy and commodities have been weak. European bonds outperformed following dovish noises from members of the European Central Bank (ECB).

Economic data showed soft (but not awful) purchasing manager survey indices, offset somewhat by US mixed employment data. In the US, the job agency ADP’s November employment report weakened but Friday’s US employment report surprised economists by showing 199,000 jobs were added in November, a reasonable level of job creation paired with a very surprising fall in the unemployment rate, down to 3.7% from October’s 3.9%. Still, rate expectations have fallen because the policy setters at the US Federal Reserve (Fed) appear be more focused on inflation declines than worrying about what level of unemployment is too low for comfort. Nevertheless, bond investors had expected the US unemployment rate to worsen to 4% at least and November’s data does not support the case for any rate cuts without some other factor impinging.

But it seems bonds and equities are taking more of a cue from commodities and energy.

Equities ended the week back up to recent highs, with the US ‘Magnificent Seven’ bouncing back from fears about their exposure to softer consumer demand. Stocks had seen softness despite falling bond yields, as investors started to worry that earnings prospects may be challenged, with oil sending quite a weak growth signal.

Last week, we said how OPEC’s inability to act as bloc had led to ineffective supply cuts. Since then we have seen more oil price falls, and in addition, global industrial metals and agricultural prices moved down. They are less volatile than energy prices (mainly because energy stores are always relatively low compared to ongoing use) so the lesser decline is still significant. Commodity prices are still higher than they were 2021 but the decline from mid-2022 is clear. In the past 15 years, the biggest demand swing has emanated from China and there are all sorts of signals that the world’s second-largest economy is not providing the growth leadership that the largest economy in the world has given us.

With COP28 coming to a close at the weekend, the discussions have been neither a help nor a hindrance to asset and commodity prices, nor perhaps should they be, although COP28 president Sultan Al Jaber took the opportunity to swing the debate towards responsible fossil fuel policies. Ultimately, progress on dealing with emissions will be in the enactment of detailed policy, so perhaps this is good news. The conference also turned its attention to the loss of the natural world, which many think is a good refocusing.

Moody’s weighs in to add to the Chinese gloom
November was the continuation of a miserable year in Chinese markets, where economic and policy disappointments have been the defining feature. At the time of writing, the CSI is down 12.5% year-to-date in renminbi terms, while the Hang Seng has dropped a painful 18.3%. Weaker-than-expected growth and trade – compared to admittedly high expectations – has been the root of China’s issues for some time. The government has repeatedly tried to counteract this with various support schemes or political pronouncements – to varying degrees of success.

Last week brought another headache for Beijing, after ratings agency Moody’s cut China’s credit outlook to negative. Moody’s pessimism extends to both government and private banking debt – both of which are feeling the pressure from an extended property market downturn. Moody’s has only changed its outlook on Chinese credit, and a slight downgrade is unlikely to affect China’s medium-term borrowing capacity in a big way. That said, the news is clearly not a good thing for the Communist Party government and financial stress has been worsened by the exodus of foreign investors from Chinese markets this year.

The Chinese Politburo met last week to avow a significant fiscal push next year. Among the policies being swung into action, the People’s Bank of China (PBOC) has introduced something that looks very much like quantitative easing (QE), or the buying of bonds. This policy can work in different ways but one of its possible implications is that financial market liquidity improves, which can then feed through into rises in risk asset prices. The lack of foreign equity buyers has generated much comment but the similar lack of domestic equity buyers has also been notable.

Chinese consumers are feeling pessimistic to, and for good reason: 8.5 million of them (around 1% of the total working-age population) have defaulted on debt payments since the start of the pandemic and been blacklisted by authorities. As well as severely constraining China’s domestic demand – a side of the economy Beijing avowedly wants to foster – struggling consumers cannot pay taxes, hence reducing the government’s funds and worsening its fiscal metrics. All of this puts the Party in a precarious position.

This weakness is surely one of the main reasons China has been so conciliatory toward the west in recent months. It is hard to see President Xi’s meeting with President Biden last month – his first visit to the US since early 2017 – as anything other than a big peace offering. Trade tensions between the world’s two largest economies may well continue, but they are likely to be pushed much more by Biden than Xi. For the global economy at least, conciliation is a positive. But for China, its underlying weakness seems worryingly hard to address.

Please check in again with us soon for further relevant content and news.

Happy Christmas.

Chloe

11/12/2023