Team No Comments

Weekly market performance update Tuesday 1 September 2020

Please see below for the latest market update from Invesco this morning:

The main focus of the week was the Jackson Hole Symposium and comments from Fed Chairman Jerome Powell on the way forward for US monetary policy (see chart of week). A “dovish”, risk asset supportive Fed remains the order of the day. Andrew Bailey, the governor of the Bank of England, also spoke at the Symposium, where he emphasised that the BoE had plenty firepower left to fight off recessions and stimulate growth. The other “highlight” of the week was the unexpected resignation of the long-standing Japanese Prime Minister, Abe, which potentially brings some shortterm uncertainty to Japanese politics, although the key reforms of the Abenomics-era are likely to be sustained by whoever emerges as his successor.

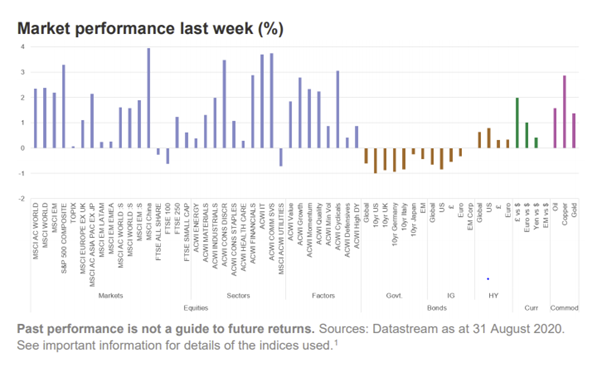
Global equities had a strong week, edging higher last week, with the MSCI ACWI hitting an all-time high on Friday. Gains were again led by the US, where the NASDAQ is now up over 30% YTD. EM also had a good week. Strength in IT-related stocks boosted Growth ahead of Value, despite strength in Financials, as bond yields moved higher. UK equities underperformed, down slightly on the week, with a stronger £ weighing on the foreign earnings-heavy FTSE 100.

Fixed income markets had a tougher week. Rising yields hurt government bond markets, which in turn negatively impacted the closely correlated IG market. Both were down slightly on the week. HY, however, managed a small gain, with global spreads and yields hitting post-crisis lows.

The dovish Fed pushed the US$ back close to its post-crisis lows, with gains strongest in £ and the Euro, with the former now having regained all its previous YTD losses and the latter at its highest since 2018. A weaker US$ provided a boost to commodities, with oil, copper and gold all making modest gains.
  • One of the highlights of last week was the speech by the Federal Reserve Chairman, Jerome Powell, at Jackson Hole, which he used to officially announce historic changes to the Fed’s approach to setting monetary policy. A shift in policy that had been widely expected given the policy framework review that Powell had initiated nearly two years ago.
  • The chart shows the 3-year monthly moving average of PCE headline inflation over the past two decades and the Fed’s target rate of 2%. It clearly shows that there has been a persistent shortfall of inflation relative to the 2% objective over the past decade. In light of this, the FOMC now “seeks to achieve inflation that averages 2% over time”. Powell emphasized that the new inflation strategy is “flexible”, with the Committee aiming to achieve this objective “over time” without defining a specific lookback period or horizon over which to achieve the average. Although the Fed has been deliberately vague as to the extent of overshoot that will be tolerated, the upshot is that the Fed is now aiming for above-target inflation.
  • At the same time with the 50-year low in unemployment (3.5% in late 2019/early 2020) failing to push inflation higher, the Fed will also now focus on “shortfalls” rather than “deviations” in employment from its maximum level, and won’t raise interest rates in response to labour market strength in the absence of clear signs that inflation is actually rising.
  • What does this mean for monetary policy? It effectively gives the Fed more leeway to run looser for longer policy. This means that the Fed Funds Rate is unlikely to be going up anytime soon. Goldman Sachs believe that it won’t be until 2025 that tightening starts. And with average inflation likely to weaken before it strengthens, there is an expectation that this will potentially open the door for further unconventional policy measures at the FOMC’s September meeting (16th).
  • And the implication for financial assets? The higher inflation outlook on its own should benefit real assets (equities, gold and other commodities) over nominal fixed income (government and corporate bonds), although easier monetary policy for longer should also underpin bonds. Finally, a more “dovish” Fed will likely put some downward pressure on the US$.

Key economic data in the week ahead:

  • A pick-up in news flow from the previous week.
  • A lot of survey data will be published. Final PMI readings for August for major economies (US, Japan, EZ and UK) will come out on Tuesday (Manufacturing) and Thursday (Services and Composite). These are expected to confirm the results from the Flash surveys a couple of weeks earlier, with the highest readings in the UK and the US, while the EZ and Japan were the laggards, with the latter still below the 50 level.
  • In the US, alongside the PMIs there are also the closely followed ISM Manufacturing (Tuesday) and Services (Thursday) surveys for August. The former is expected to see a marginally more positive reading of 54.5, but the latter is forecast to decline to a still robust 57.4. The first Friday of the month brings US Non-Farm Payrolls expected at 1.5m, slightly lower from the 1.7m in July. US unemployment is expected to show a reduction to 9.8% from 10.2% in July. The Underemployment rate, however, is forecast at 16.5% – slightly lower than last month’s 18% and perhaps a truer reflection of the current state of the US labour market. Ahead of this data, US Initial Jobless Claims on Thursday is expected to show an improvement to 950k last week from 1,006k the previous week.
  • In the UK, July’s money and credit figures are published on Tuesday and are expected to show further signs that business and household borrowing rates are moving back towards normal. Mortgage Approvals, for example, are expected to rise to 55k from 40k, but that is still well below the 60-70k range seen prior to the crisis. Likewise, Consumer Credit growth is expected to be in positive territory for the first time since April (£0.8bn). Nationwide’s House Price Index comes out on Thursday, with August expected to see a 0.5%mom increase, which would make it 2%yoy. Pent-up demand and the Stamp Duty holiday are clearly helping here.
  • Preliminary CPI for August in the EZ is released on Tuesday and expected to continue to show inflation at very weak levels, flat mom compared to July’s level of -0.4%mom. This would leave headline inflation at a mere 0.2%yoy and Core at 0.9%. Retail Sales for July are published on Thursday and, while remaining positive (1.4%mom), are expected to be somewhat weaker than in June (5.7%mom).
  • In Japan the Jobless Rate for July on Tuesday is expected to increase to 3.0% from 2.8%, so somewhat above the lows of 2.2% seen in late 2019. The closely followed Jobs-toApplicants Ratio is expected to decline further and at 1.08x would be the weakest since early 2014.
  • In China, business surveys dominate the week with both the Caixin and Official PMIs being released. Little change is expected in both sets of readings, with all remaining above the 50 level and Services continuing to be stronger than Manufacturing.
  • Australia rarely gets a mention here, but on Wednesday Q2 GDP is published, which will confirm that the economy has slipped into its first recession for a remarkable 29 years.

Invesco are market leading investment managers and so their views and insight can be valuable in providing a well informed and holistic view of the markets.

Updates like these are useful tools in keeping your views of the markets widespread and up to date.

Stay safe and well.

Kind Regards

Paul Green

01/09/2020
Team No Comments

What the race to the White House means for portfolios

Please see the below article posted by AJ Bell late last week:

Milwaukee, Wisconsin, and Jacksonville, Florida, are home to two of America’s National Football League’s 32 teams: the Green Bay Packers and the Jacksonville Jaguars. Owing to the pandemic, it is not clear at the moment whether gridiron fans will be allowed into their stadia at any stage this season to watch the games, which are due to begin in September.

But two other important events in these cities have already fallen foul of COVID-19. Last week’s Democratic Party convention, slated for Milwaukee, became a virtual affair as the majority of speakers stayed away, even while Joe Biden and Kamala Harris punched their ticket as the party’s chosen pairing for next US Presidential Election – which is due on Tuesday 3 November. Meanwhile, the Republican incumbent in the White House, Donald Trump, had already cancelled his planned convention in Jacksonville, although a pared-down affair took place in Charlotte, North Carolina, earlier this week, as he and Vice President Mike Pence prepared to run for a second term in office.

The race is now on between the Trump/Pence and Biden/Harris teams to give advisers and clients something else to mull over as they continue to wrestle with how the pandemic will continue to affect the world’s largest economy. The political temperature will only rise from here, with three presidential television debates scheduled for 29 September, 15 October and 22 October and one vice-presidential contest on 7 October before Americans head to the ballot box.

Voting patterns

In admittedly very crude terms, you might expect the US stock market to prefer a Republican President to a Democrat one, with the Grand Old Party generally seen as being in favour of small(er) Government and less inclined to interfere in business matters and free markets than the Democrats.

“Over 18 presidencies since the election of Harry S. Truman in 1948, the Dow Jones Industrials has, on average, done better under Democratic presidents than it has under Republican ones.”

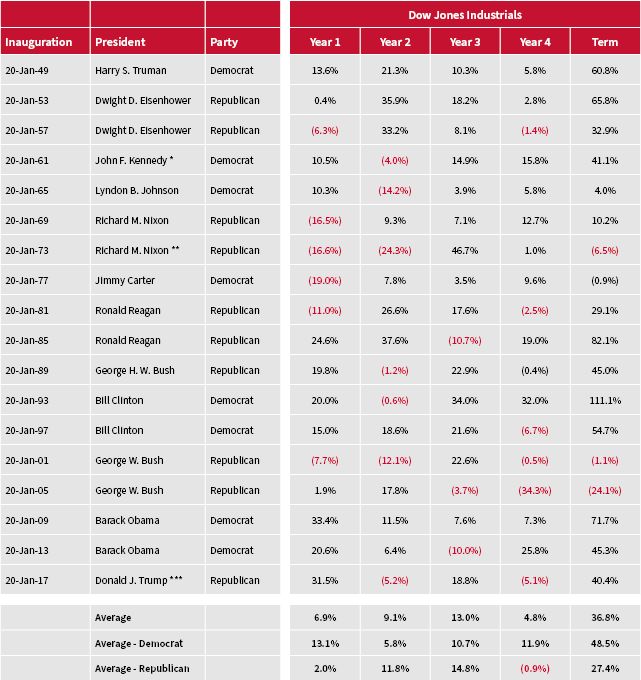
However, it generally has not worked out like that, at least not in modern times. Over 18 presidencies since the election of Harry S. Truman in 1948, the Dow Jones Industrials has, on average, done better under Democratic presidents than it has under Republican ones. Even more intriguingly with 2021 in mind, the Dow has done much better in the first year of a Democratic term than it has a Republican one, with an average gain of 13.1% compared to 2% from their rival incumbents.

The Dow Jones has tended to perform better under Democratic presidents than Republican ones, especially during the first year of a term.

Source: Refinitiv data. * John F. Kennedy assassinated in November 1963 and replaced by Lyndon B. Johnson. ** Richard M. Nixon resigned August 1974 and replaced by Gerald R. Ford. *** Data for Donald J. Trump as of 17 August 2020

A long time ago

It therefore is not as simple as ‘Republicans good, Democrats bad’ when American politics is assessed through the very narrow prism of the US stock market. This is particularly the case now, when the Republicans were running up the sort of budget deficits that would make even the most ardently pro-spending Democrat blush, even before the pandemic forced an emergency fiscal response.

Moreover, if advisers and clients cast their minds back four years ago, the Democrats’ Hillary Clinton was then seen as a bit of a shoo-in for the 2016 election, as the Republican’s Trump had surprised everyone by winning the Grand Old Party’s nomination. Trump was also widely perceived as a potentially negative result for markets, thanks to his sabre-rattling on issues such as diplomatic relations with China, Iran and Mexico and desire to rip up several trade agreements, including the North America Free Trade Agreement (NAFTA).

But that isn’t how it turned out.

“It may still trade below its all-time high, but the Dow Jones Industrials index is up by some 40% since Trump’s inauguration on 20 January 2017.”

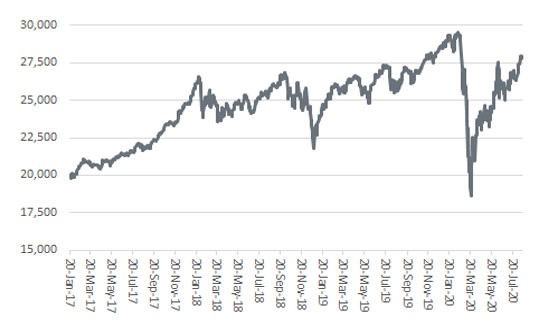
It may still trade below its all-time high, but the Dow Jones Industrials index is up by some 40% since Trump’s inauguration on 20 January 2017, thanks to what had been a steady economic expansion, tax cuts and an accommodative US Federal Reserve, which had pretty quickly backed away from raising interest rates and sterilising Quantitative Easing, even before COVID-19 swept around the globe.

Dow Jones Industrials has powered higher during Trump presidency

Source: Refinitiv data. Covers period since inauguration ceremony on 20 January 2017.

This suggests that there is more than just politics at play when it comes to how a stock market performs, with monetary policy, economic performance and the possibility of exogenous shocks (such as a pandemic) all factors to be considered, among others, even before we get to the vexed issue of valuation.

“How much of a bearing November’s winner has upon financial markets’ performance will to a degree depend upon which party wins the House of Representatives and the Senate, so advisers and clients will need to consider this too.”

That said, Trump has undeniably been influential, from his market-pumping tweets to his economy-pumping tax cuts. How much bearing November’s winner has upon financial markets’ performance will to a degree depend upon which party wins the House of Representatives and the Senate, so advisers and clients will need to consider this too. Trump has achieved less in the second half of his term as the Democrats have controlled both houses on Capitol Hill.

The tricky things is sorting out the policies that are just electioneering and slogans from the plans that may actually be enacted. As the economist Robert Sowell once noted: “Economists are often asked to predict what the economy is going to do – but economic predictions require predicting what politicians are going to do and nothing is more unpredictable.”

The run up to a Presidential election is always interesting, this year even more so with the Covid-19 Pandemic and the complications this has brought and continues to bring.

The next few months will be an interesting ride!

Please continue to check back for further updates on the US Presidential Election and the affect this has on the markets as well as our usual variety of market updates and blog content.

Andrew Lloyd

01/09/2020

Team No Comments

FTSE primed to play catch-up after lagging US stocks

Please see below for the latest market update from AJ Bell: 

The pound losing its recent strength and oil stocks responding to a higher commodity price could boost the index

Investors in UK stocks have been looking jealously (or frustratingly) at the performance of the US markets and wondering why the FTSE 100 has stubbornly refused to rebound as fast.

Year to date, the S&P 500 is up nearly 5% and the Nasdaq is up 25% whereas the FTSE 100 is down nearly 19%, all on a total return basis.

The answer is simple – the UK stock market is very under-represented by tech stocks which is the sector that has driven US markets this year.

The UK is also heavily weighted towards banks and energy stocks, two of the worst performing sectors in 2020.

The former has been depressed by a drop in interest rates, rising concerns over potential bad debts as consumers and companies struggle as a result of the pandemic, and the suspension of dividends.

The energy sector has been hit by a big decline in the oil price and a reduction in dividends making it less appealing to income investors.

Yet are we about to see a reversal of fortunes?

Recent strength in the pound versus the US dollar will have worked against the multitude of companies on the FTSE 100 which earn in the latter currency, but whose share price is quoted in the former. Those dollar earnings will be worth less when translated into sterling.

Approximately three quarters of the FTSE 100’s earnings come from outside the UK, so foreign exchange rates really matter to the performance of the index.

Bank of America this month turned bullish on UK equities, partly because it expects the pound to weaken again on the back of rising no-deal Brexit risks. If sterling weakens then dollar revenues, once converted back into sterling, are worth more.

The bank also believes the energy sector should catch up with recent strength in the oil price, thereby giving another support to the FTSE 100 with oil producers Royal Dutch Shell (RDSB) and BP (BP.) being major constituents of the index.

Such predictions would suggest investors are right to remain hopeful for better returns from the FTSE. However, performance is still dependent on economic activity picking up around the world and unfortunately there are some mixed signals.

Stock markets last week took a tumble after the US central bank expressed concern that the pandemic could greatly impact the US economy in the medium term.

The latest Eurozone PMIs disappointed while the US and China’s recent figures have been more upbeat. These are various indices which show confidence levels from purchasing managers and which are a good economic bellwether.

Against this backdrop, the latest Bank of America survey of fund managers shows that institutional investors remain bullish about markets despite a difficult backdrop.

It’s an ever-moving feast and investors would be best served by not fiddling with their portfolios in response to every bit of economic data that comes out. Stay diversified and accept that there may well be some parts of your portfolio lagging others – it’s just the nature of investing.

A brief but concise summary like this is an efficient way of keeping your views of the markets up to date.

If you read the previous blog you can see Jupiter’s Fund Manager, UK All Cap, James Bowmaker’s views on the FTSE too.

Take care and keep well.

Paul Green

28/08/2020

Team No Comments

Jupiter Asset Management – Active Minds Blog

Please see Active Minds article below from Jupiter Asset Management – received 27/08/2020

Active Minds – 27 August 2020

James Bowmaker – Fund Manager, UK All Cap

Could the FTSE emerge from lockdown fitter, happier and more productive?

The apparent schism between Growth and Value in global equity markets is starkly illustrated by the FTSE 100 Index, said James Bowmaker, Fund Manager, UK All Cap, in a week where a single US tech company rose to become larger in value than the entire FTSE 100.

The FTSE is down around 20% year-to-date, which is worse than most of the European indices and much worse than the US indices. On a three-year view, ignoring dividends, it is only up around 3% over a period when the S&P 500 Index doubled. To make matters worse, the FTSE has had a tailwind over this period due to the weaker pound boosting overseas earnings, although Brexit uncertainty has kept global investors away. Even more embarrassing, the FTSE 100 Index has underperformed the MSCI World Value Index over most of the past three-to-five years.

Why? There are far too few Growth stocks in the index and too much Value. At the start of 2020, banks and oil companies accounted for around a quarter of the index and around a third of its dividends. These businesses faced structural pressures, had dividend payout ratios that were regarded as unsustainably high and were backed by volatile commodities and/or cyclical earnings.

But that was then – what about now? We’ve seen aggressive cost cutting and huge dividend cuts in large caps, James pointed out. Some of the cuts are temporary but the dividend reductions of 50%-60% by the large oil & gas companies are permanent. So, starting from here, the prospective dividend yield for the FTSE is around 4.2% – once dividend resumptions are factored in – a yield close to its medium-term average. Furthermore, the cuts have reduced the imbalance in the index and its payouts so the overall yield from the FTSE 100 Index ought to be more sustainable. Banks and oil now account for around 15% of the index compared with 25% at the start of the year and their dividend contribution is no longer 35% of the index payout but a more reassuring 15%. Meanwhile, pharmaceutical companies, with their more stable earnings, now account for a greater proportion of the index and its yield. For investors worried about the prospects of a derating in growth stocks, James says they could do worse than look at the FTSE as it never had that risk in the first place! 

Talib Sheikh – Head of Strategy, Multi-Asset

Growth rally still has legs

Growth vs Value does indeed continue to be the million-dollar question, echoed Talib Sheikh, Head of Strategy, Multi-Asset. The NASDAQ and S&P 500 have hit all-time highs once again, as the growth and technology stocks that dominate these indices continue to see their share prices benefit from the low interest rate environment and negative real yields. Talib expects this trend to continue for some time to come, as he argues that the prime focus for central banks around the world now is to keep real interest rates as low as possible.

Federal Reserve Chairman Jerome Powell’s speech at the virtual Jackson Hole summit later this week is keenly anticipated. Markets are expecting some guidance on how the central bank will address the issue of low inflation, which has persistently fallen below their 2% target for the last decade. Talib expects the Fed will eventually move towards state-contingent forward guidance where they don’t raise interest rates until reaching a certain target. Given this is a live debate and that real interest rates should remain lower for longer, Talib thinks the Growth rally has further to go. In the multi-asset strategy, Talib and the team are focusing on what they believe are high quality assets in the US and high quality, undervalued cyclical stocks in Asia, which are more attractive compared to Europe.

James Clunie – Head of Strategy, Absolute Return

Markets continue to ignore fundamentals

Executing a valuation-driven process remains challenging in the current market environment, where the Growth vs Value performance gap has reached record levels on many measures, said James Clunie, Head of Strategy, Absolute Return. But James and the team continue to believe that the price you pay for an asset is the most important starting point for returns over any sensible time horizon. James used two stock examples to demonstrate the stark contrast in characteristics of stocks found in the strategy’s long and short books.

First, he used the example of a US burger chain as an example of the kind of stock he looks to short. Through a quantitative lens, it looks like a bottom-quartile stock, with poor quality measures, rapid asset growth, and high issuance of new equity, for example. In terms of its valuations, on a discounted cashflow (DCF) model, if you model in 20% growth for the company over the next seven years, assuming margins that meet the industry best thereafter into perpetuity, you can reach fair value – in other words, when you buy its shares, you’re capitalising an extremely rosy future, and paying up for it today as if it’s already happened (and it’s pricey!).

Directors are selling its shares; meanwhile, short sellers are present, and rising. It’s also had significant broker downgrades over the past month, for 2021 and 2022. There’s a lot of work to be done in terms of its business model. It has had a run of disappointing results, and its latest set of numbers recorded losses. However, despite all of these factors, the company’s shares are only down around 2% year to date.

In contrast, James discussed a global shipping company held in the long book. While its balance sheet isn’t perfect, on a quant level, it’s a top-quartile stock; and on a DCF model, it’s trading at about fair value, depending on which assumptions you make. It has a reasonable shareholder base, and it has had huge earnings upgrades, driven by falling fuel costs. Nevertheless, its shares are down around 1% year to date. While it’s not possible to predict where markets are heading, if the market regime does change in favour of value stocks, James and the team believe there is plenty of upside potential for stocks like this.

Patty Cao – Assistant Fund Manager, Emerging Markets Debt

Window of opportunity opens for emerging market bonds

Emerging market debt has been resilient this year as central banks keep rates ultra-low and along with governments provide ample economic stimulus, said Patty Cao, Assistant Fund Manager, Emerging Market Debt. China’s faster-than-expected economic recovery from the impact of the coronavirus has been positive for the asset class, as has the generally improving trend for global PMI data, she said. US real yields at record lows have led to a weaker dollar, which also is supportive for emerging markets, and there is abundant liquidity in the asset class. Retail flows into emerging market debt funds have been positive since July, mostly in hard currency bonds, though local currency fund flows have risen more recently.

The strategy is overweight in local currency emerging market rates, while hard currency corporate bonds have appealing valuations, Patty said. Corporate bonds in hard currency look attractive compared with sovereigns, offering higher yields with shorter duration. She noted that among emerging market currencies, the Turkish lira and Brazilian real have both suffered declines this month.

Positive developments on a coronavirus vaccine and improving economic growth should provide a good environment for emerging market bonds and support continued fund flows for the asset class, Patty said.

A useful article for getting an insight to the market from market experts within their specified field.

Please continue to check back for our regular blog posts and updates.

Charlotte Ennis

28/08/2020

Team No Comments

Michael Lucas

‘After years of putting off sorting my pensions out, I finally used the services of Carl Mitchell and People and Business. I am so glad that I did. The service was amazing and total professionalism. I put it off due to my lack of understanding. That all changed after Carl took me through my pensions and what could be achieved and how my portfolio could look. He explained things in a simple way and wrote a report in a way I understood. I am more than pleased how my pension is performing. I would highly recommend to anyone and be passing details onto others.’

Michael Lucas
27/08/2020

Team No Comments

What Proposed Climate Reporting Duties Could Mean for Trustees?

Please see the below article published recently from Royal London;

Lorna Blyth looks at how an amendment to the Pension Schemes Bill could force pension schemes to align their investment strategies with the Paris climate agreement.

Summary

An amendment to the Pension Schemes Bill has been proposed which could force pension schemes to align their investment strategies with the Paris agreement. This article looks at the implications for trustees, and asset owners more generally, as they consider how they measure and report on the impact of climate risk and the UK commitment to reach net zero carbon emissions by 2050.

Background

The Paris agreement, signed in 2015 by the majority of global leaders, established a legally binding commitment to curb carbon emissions in order to limit the global temperature rise to below 2 degrees celsius with the ambition to work towards a lower threshold of 1.5 degrees. In order to reduce the risks associated with long lasting or irreversible changes to the earth’s atmosphere and ecosystems the Intergovernmental Panel on Climate Change (IPCC) reported that global carbon emissions would need to reach net zero by 2050. In 2019 the UK government committed the UK to achieving this target and became the first major economy to pass this into law. Policymaker focus is supporting this transition and we are seeing a much greater focus on sustainability from the government and the regulator.

The levels of pension savings and wealth in the UK is a significant part of the UK economy and has a huge part to play in helping companies to meet this target through voting and engagement rights that share ownership brings. There is no doubt that climate risk is an investment risk and going forward those responsible for investment solutions will be expected to have explicit policies on climate risk to explain how they are addressing it and building a roadmap to move to net zero.

What is climate risk?

Climate risk could crystallise in a number of different ways given the complex nature of the risk and the different time horizons for impacts. Typically we see the risk impacts grouped into two categories – physical risk and transition risk.

Physical risk relates to the impact of climate change, for example damage to land, buildings or infrastructure as a result of adverse weather conditions or rising sea levels as well as the knock on effects such as food shortages, supply chain disruption and civil unrest.

Transition risk relates to the disorderly impact on markets as a result of the transition to a low carbon economy. This could include the impact of policy action such as carbon pricing, emission caps and subsidies or the emergence of changing consumer behaviours and reputational risk as expectations to address climate change evolve and increase.

It won’t have escaped you that some of the knock on effects described here are similar to those that many of us have experienced as a result of the COVID lockdown measures put in place by governments. The impact this has had on our lives, wellbeing and finances has not been neat and orderly, nor has it been the same for all of us and it’s not difficult to imagine how the effects of climate change could bring similar impacts, albeit on a much larger scale.

The scale of the challenge

To help bring the impact of climate change into a financial context a recent report by the Carbon Disclosure Project forecast that $1trn of climate related costs will be borne by 200 of the world’s largest listed companies within the next five years. Regulations currently require that trustees disclose and report on their climate policies and the government has made it clear that their aim is for schemes to start actively managing their exposure to climate-related risks in order to limit the risk climate change poses to their members’ future retirement income. This focus has also been extended to IGCs who now have a specific remit to provide an independent consideration of a firm’s policies on environmental, social and governance factors including climate change.

Where to start

Transparency is a key first step in order to understand climate risk and the impacts on the investment strategies and a good place to start is the Task Force on Climate Related Financial Disclosures (TCFD). It was set up in 2015 and delivers a set of consistent, climate-related financial risk disclosures for use by companies in providing information to investors, lenders, insurers, and other stakeholders. It’s a widely-adopted approach to manage and report climate risk and provides a framework to help trustees embed this within existing governance and decision making processes including defining investment beliefs, setting investment strategy and manager selection and monitoring.

TCFD reporting is voluntary at the moment however it will become mandatory by the end of this year and as an asset owner we have already committed to report against the TCFD framework.

A net zero economy is the direction of travel and the risks that lie in how we get there will affect investment returns. Given the scale of the challenge the quicker we can understand and quantify these risks the better in order that we can manage them and deliver not only good returns for customers but also a more sustainable future.

This blog demonstrates what we have been talking about with regards to ‘socially responsible investing’ and investments shifting in the ‘ESG’ direction.

As we have noted before, we expect the majority (if not all) investment companies to keep moving towards this style of investing over the next few years, particularly once the FCA post their guidance and position with ESG policies and investing.

The FCA began consulting on this late last year and were due to publish their findings this year, however this has been delayed due to the Pandemic and we expect them to publish this later in the year or in early 2021.

Andrew Lloyd

27/08/2020

Team No Comments

Brewin Dolphin – Markets in a minute

Please see below an article published by Brewin Dolphin yesterday (25/08/2020), which summarises last week’s investment market performance:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

26/08/2020

Team No Comments

Prudential PruFund Growth Positive Unit Price Adjustments – 25/08/2020

Prudential PruFund Growth Positive Unit Price Adjustments 25/08/2020

I have just finished listening to Prudential about their quarterly update on their ‘PruFund’ range of ‘smoothed’ multi asset funds.

PruFund Funds are reviewed for their Expected Growth Rates (EGR) and their Unit Price Adjustments (UPA) on either a monthly or quarterly basis.  They also have daily smoothing limits too.

The good news is that there has ben no change to EGRs, on PruFund Growth this remains the same at 5.70% gross per annum for pension and ISA investments.

Further good news on the UPA follows for Series A and Series D PruFund Growth:

Series A                                2.73% increase to fund value

Series D                                2.74% increase to fund value

The difference in increase is accounted for by a slight difference in product charges.

Series A covers Flexible Retirement Plan pensions and the ISA product and Series D covers the Prudential Retirement Account, earlier investments.

Please note that Series E for later Prudential Retirement Account investments had a positive UPA of 2.58% applied on 25/06/2020 on a monthly review.

‘Smoothing’ can include further price reductions as well as possible increases.  Volatility will remain based on the current market situation and outlook.

Different charging structures will impact on actual net returns as disclosed in reports etc.

Should you have any questions on the above please do not hesitate to contact me.

Steve Speed

25/08/2020

Team No Comments

Legal & General Update: Summertime, and the living is easy

Please see the below article posted late yesterday (24/08/2020), by the investment management team at Legal & General.

Summertime, and the living is easy

Markets have effectively been flat-lining recently and trading volumes have collapsed by even more than normal in the summer. We believe this is a sign that there is not yet broad exuberance in markets, but also that the risks around crowded trades are bigger than normal.

This update represents solely the investment views of LGIM’s Asset Allocation team.

A known unknown

The ‘inflation versus deflation’ debate is likely to intensify in the coming years, but at least for a while it’s mainly going to be a theoretical discussion. Some great economists have recently predicted runaway inflation, as today’s policy measures are injecting cash directly into the hands of consumers, while other equally great economists have forecast continuous deflation, pointing towards the demand shock and output gap.

We need to acknowledge that so far there hasn’t yet been a satisfying explanation for why there has been so little inflation in recent years, despite strong growth and record low unemployment. How can the market possibly have conviction on the future path of inflation when we collectively were not very good at predicting the past five years?

What does this ‘known unknown’ mean for our inflation positioning? In the absence of a strong directional view, we will need to play inflation tactically; positioning and the market narrative become the important drivers. At the moment we are short UK and European inflation, as we think both are overpriced.

Nothing to see, yet

The first half-year review of the US-China Phase One trade deal has been postponed and not yet rescheduled. It is unclear what caused the delay in the talks, although President Trump has said he cancelled them. Markets have ignored the delay for now as both sides still have incentives to keep the agreement intact before the US elections and expect the talks to happen relatively soon.

We believe China views the deal as a stabiliser to bilateral relations with the US, while from Trump’s perspective the deal is an important political asset during the presidential campaign.

On a different front in what we see as ‘the new cold war’, the US again tightened restrictions on Huawei, by blacklisting more of the Chinese company’s subsidiaries and reducing its access to chips and technology that have been developed or produced with US involvement.

We don’t think Huawei is an immediate breaking point for China, where reactions to the news were muted. Over the medium to long term, we believe Huawei and 5G will certainly become a major area of competition between the US and China. In the short term, however, Huawei can in our view survive until after the US election.

Wall Street versus the High Street

Clients often ask us whether we perceive a disconnect between markets and the real economy.

We believe there are three reasons that explain their apparent divergence:

  1. Central banks have slashed rates and restarted asset purchases while governments embarked on fiscal stimulus. This has pushed interest rates even further down. All else being equal, lower yields are good for risk assets through the discounting of future earnings.
  2. Markets are a forward-looking mechanism. It’s the collective view of market participants on the future state of the world, not the current state, that drives asset prices. It is therefore the expectation of a better economy in the future that drives markets up today. We believe markets look forward about three to 12 months. Given this window, the question around the discovery of a vaccine comes into play. The probability of such a vaccine by mid-2021 is around 80%, in our view. Focusing on this allows investors to imagine a world in a somewhat normal state by then.
  3. The outperformance of mega-cap technology stocks is distorting the market picture as well. The Nasdaq has outperformed the S&P 500 year to date, for instance, while the S&P 500 ex Technology is still down in 2020. This could end up in a technology bubble, but we don’t believe we are there yet. Our bubble monitor, the Heiligenberg Index, is elevated but not yet in the stratosphere. We therefore remain overweight technology.

The combination of these three factors should give some comfort that the disconnect between financial markets and the real economy is a matter of perception. Having said that, we remain cautious in our current positioning as we believe the market has gone too far, too quickly in its optimism on earnings, the economy, politics, and the shorter-term virus dynamics.

Its good to have an insight into how some of the big investment companies Asset Allocation teams think, it helps us get a view on current market trends and how these are being factored into investments funds and portfolios.

This year has been a unique year for markets and investors and you can see a range of views, Legal & General being more cautious, from fund managers.

Keep checking back for more updates as we navigate our way through these strange and unprecedented times.

Andrew Lloyd

25/08/2020

Team No Comments

Brooks Macdonald – Weekly Market Commentary

Please see below the weekly market commentary from Brooks Macdonald – received 24/08/2020.

Weekly Market Commentary | Fed policy review findings to be revealed this week amidst rising Coronavirus cases in Europe

24 August 2020

Read detailed economic and market news from our in-house research team.

  • Weekly Market Commentary
  • COVID-19 updates

By Edward Park

  • European COVID-19 cases continue to rise, raising the risk of further reintroductions of restrictions
  • The Jackson Hole economic symposium takes place this week with Jerome Powell expected to discuss the Federal Reserve (Fed) policy review
  • The Republican National Convention contains a keynote from Donald Trump on Thursday – investors will be looking for any China hawkishness as the November election approaches


European COVID-19 cases continue to rise, raising the risk of further reintroductions of restrictions

The second wave of COVID-19 in Europe continued to gain pace over the weekend with France, Italy and Spain all seeing an increase in new cases. Investors will be watching to see if this is the prelude to a reintroduction of restrictions or any localised lockdowns. This uncertainty appears to largely be in the price however, with European equities and US futures starting the week strongly.

The Jackson Hole economic symposium takes place this week with Jerome Powell expected to discuss the Federal Reserve (Fed) policy review

The main event this week is likely to be the Jackson Hole economic symposium on Thursday and Friday. The keynote speech will be from Fed Chair Jerome Powell and he is expected to unveil the key findings and next steps from the Fed policy review. The full results are likely to be delayed until the Federal Reserve’s September meeting, but the key messages will be important to the future path of interest rate and inflation expectations. The review considers, amongst other items, whether the Fed could move away from a fixed inflation target to an average target. In practice this would mean far less sensitivity to upside surprises in inflation during this economic cycle. 

The Republican National Convention contains a keynote from Donald Trump on Thursday – investors will be looking for any China hawkishness as the November election approaches 

In terms of speeches, Donald Trump will be giving his main speech on Thursday at the Republican National Convention. However, with Trump to appear on every night of the convention, there is the possibility that this could generate volatility. On both national polls and betting odds there is a significant gap between Joe Biden and Donald Trump opening up, which increases the risk of escalating rhetoric as November approaches. Markets will be looking particularly closely at any proposed actions around China hawkishness which could impact the bull run in US equities over the last month. With just ten weeks to go until the 3rd November election date we continue to expect this to be the primary source of market volatility.

US Fiscal stimulus talks appear at a stalemate with the Democrats and White House still far apart. This continued disagreement makes it even less likely that an agreement, even a ‘skinny’ deal, will be reached ahead of the return from Congress’s recess in September. US politics will remain the market’s focus but closer to home, Brexit trade talks continue to generate an impasse, particularly over the ‘level playing field’ and fishing rights. 

Another quick update from Brooks Macdonald, the weekly market updates are useful in providing a short summary of events from around the world over the past week.

Please continue to check back for our regular blog posts and updates.

Charlotte Ennis

25/08/2020