Team No Comments

Stocks rise as recession fears ease

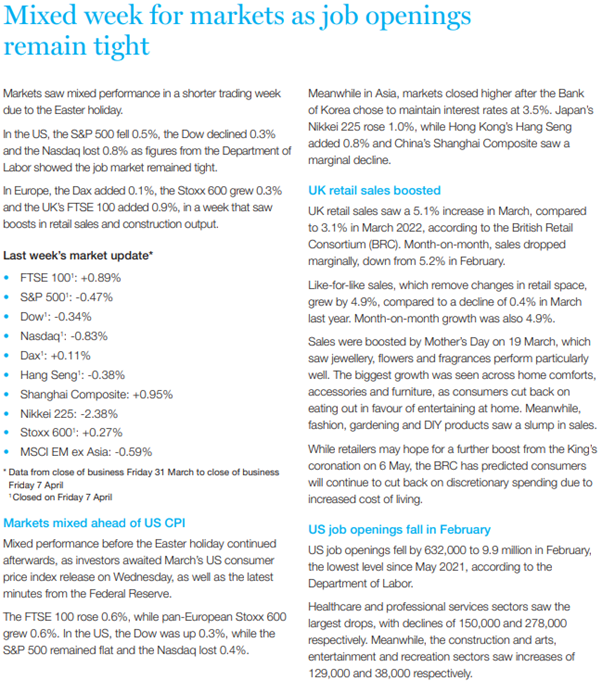
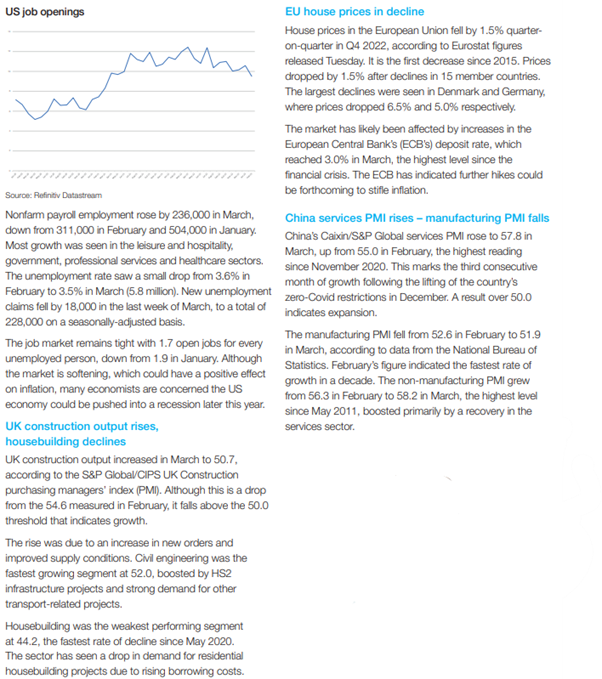
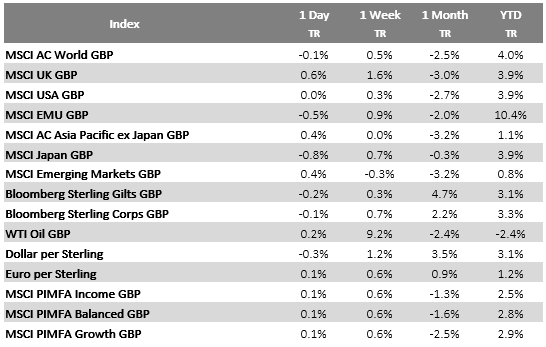
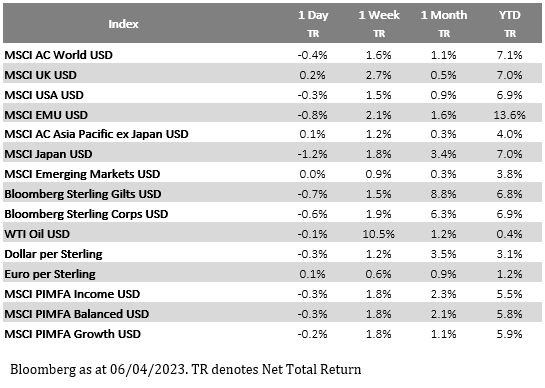
Please see below ‘Markets in a Minute’ article received from Brewin Dolphin yesterday afternoon, which provides a positive global market update.

Stock markets rose last week as signs of economic growth and easing inflationary pressures boosted investor sentiment.

The FTSE 100 ended its holiday-shortened trading week up 1.7% after figures showed the UK economy rose above its pre-pandemic levels in February. The pan-European Stoxx 600 also rose 1.7% following increases in eurozone industrial output and investor morale.

In the US, the S&P 500 and the Dow advanced 0.8% and 1.2%, respectively, as the annual rate of inflation slowed to its slowest pace since May 2021.

In Japan, the Nikkei 225 surged 3.5% after Warren Buffett said he intended to add to his investments in Japanese stocks. China’s Shanghai Composite edged up 0.3% as investors weighed a surprise 14.8% year-on-year increase in exports against softer-than-expected inflation.

Investors await slew of quarterly earnings

Stock markets had a quiet trading day on Monday (17 April) as investors braced themselves for this week’s raft of US quarterly earnings reports. Bank of America, Morgan Stanley, Netflix and Tesla are all due to release their results this week.

In economic news, a report from the Federal Reserve Bank of New York showed factory sector activity in the region significantly improved in April. The NY Empire State manufacturing index rose from -24.6 in March to +10.8 in April, smashing forecasts of -18 and marking the first increase in five months.

UK economy rises above pre-Covid levels

Figures released by the Office for National Statistics (ONS) last week showed the UK economy has finally risen above its pre-Covid levels. Although gross domestic product (GDP) was unchanged between January and February, revisions to data from previous months meant the economy ended the month 0.3% bigger than in February 2020.

February’s reading was held back by strike action in the services sector and was below the 0.1% expansion forecast in a Reuters poll. However, an upwardly revised 0.4% expansion in January led several commentators to speculate that the economy is unlikely to have contracted in the first quarter. Only a month ago, the Office for Budget Responsibility said GDP would shrink by 0.4% in the first quarter.

US inflation falls to 5.0%

Over in the US, investors were encouraged by figures that showed consumer inflation eased in March to its slowest pace since May 2021. The consumer price index (CPI) rose by 5.0% year-on-year, down from 6.0% in February, according to the Bureau of Labor Statistics.

Energy prices decreased 6.4% year-on-year, with gasoline and fuel oil falling 17.4% and 14.2%, respectively. In contrast, electricity rose 10.2% over the year, while natural gas grew by 5.5%. Food at home prices rose 8.4%, whereas food away from home prices rose by 8.8%.

Core inflation (excluding food and energy) rose by an annualised 5.6% in March. The largest driver was shelter, which grew 8.2% over the year and accounted for over 60.0% of the total increase. Other indexes that saw notable increases included motor vehicle insurance (15.0%), household furnishings and operations (5.6%), recreation (4.8%) and new vehicles (6.1%).

On a monthly basis, headline inflation rose by a lower[1]than-expected 0.1% in March, down from 0.4% in February, while core inflation grew 0.4% in March, down from 0.5% in February.

Producer prices unexpectedly fall

Further evidence of easing inflationary pressures came from the US producer price index (PPI) report. This showed prices paid by businesses unexpectedly fell by 0.5% in March, bringing the year-on-year increase to 2.7%, the smallest annual rise since January 2021.

Two thirds of the decline was attributed to falling goods prices, particularly energy, which decreased 6.4%. In contrast, when excluding food and energy, goods prices grew 0.3%.

Services also saw a decline of 0.3% in March, the largest decline since April 2020. This was primarily driven by a 0.9% drop in trade services margins.

Core PPI – which excludes food, energy and trade services – gained 0.1% in March, down from 0.2% in February. On an annualised basis, the index grew by 3.6%.

Eurozone industrial production rises

In the eurozone, figures from Eurostat showed industrial production grew by more than expected in February, thanks to easing supply chain issues and low energy prices. Industrial production rose by 1.5% month-on[1]month, bringing the year-on-year increase to 2.0%.

Further encouraging data came from the Sentix index of investor morale, which rose in April after dipping in March. The assessment of current conditions rose to the highest level in more than a year.

Please check in again with us soon for further relevant content and news.

Chloe

19/04/2023

Team No Comments

Brooks Macdonald – Weekly Market Commentary

Please see the below article from Brooks Macdonald providing their Weekly Market Commentary. Received this morning 18/04/2023.

A slightly lighter economic calendar, but more company results instead this week

Despite a weaker day on Friday in dollar terms, equity markets managed to finish the week in positive territory, as financial stress fears continued to recede after last month’s hiatus. The flipside though, is that markets have been rebuilding expectations around a Fed hike on 3 May when the Fed next meets, with probability of a 25bps hike now at 81. Turning to the week ahead, it’s a slightly lighter economic calendar. In terms of what to look out for, China’s Q1 growth following its reopening will be in the spotlight when it releases Gross Domestic Product (GDP) numbers tomorrow. Elsewhere, investors will be focusing in on labour market and inflation releases from the UK due tomorrow and Wednesday respectively. Over in the US, the Fed releases its latest ‘Beige book’ on Wednesday, where the regional Fed banks gather up anecdotal information on current economic conditions in their areas. With the US Q1 earnings season now underway, company results ramp up with more bank results due this week, including Bank of America, Morgan Stanley, and Goldman Sachs, as well as results from Tesla, IBM and Netflix. Finally, the global flash PMIs for April due Friday will bookend the week, as investors continue to focus on recession risks.

US bank sector results gets off to a good start

Friday saw US bank sector results get underway, with bellwether JP Morgan easily beating expectations. Alongside an expected boost to deposit inflows following customers seeking perceived safety in the bigger banks, JP Morgan also posted a huge jump in its net interest income (which is broadly speaking the difference between what it pays on deposits and earns on loans and other assets). Significantly, JP Morgan CEO Jamie Dimon and his team stressed that the 1Q deposit inflows were not driving its higher interest-income forecast, now expected to be $81bn this year, up from a previous estimate of $74bn, with Dimon saying that “the US economy continues to be on generally healthy footings, consumers are still spending and have strong balance sheets, and businesses are in good shape,” Clearly one bank’s results doesn’t dictate the whole sector, and it’s likely that results from some other US banks, including smaller regional banks in coming weeks might look less robust, but as results go, it was a good start to the earnings season, which investors are watching closely in terms of the expected earnings outlook for this year.

US debt ceiling talks still a tail-risk

Later today sees US House of Representative Speaker Kevin McCarthy (Republican) giving a speech that’s expected to cover the Republicans’ position on the issue. As a recap, the US is expected to come up against the debt ceiling again this summer, and the Republicans have said they want concessions like spending cuts in return for passing an increase. Since the Republicans now have a majority in the House of Representatives, versus a Democrat-controlled Senate, it suggests that there will have to be some concessions from both sides. For the time being, investors on balance seem to be framing these talks as largely political still, but that does leave a tail-risk for markets should the mood on Congress deteriorate.

What does Brooks Macdonald think

Despite firming expectations of a Fed hike next month, markets are still expecting cuts later this year, with the Fed December meeting rate expectation currently at 4.50%. While that’s up a long way from the 3.75% low at the height of the US banking turmoil last month, it is still at odds with a Fed which on balance is likely looking to want to hike and then hold rates at those higher levels. With the next Fed meeting only two weeks away on Wednesday, this week is the last time we’ll be able to hear from Fed speakers before their blackout period begins on Saturday.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

18/04/2023

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management, providing a brief analysis of the key stories from global markets and economies over the past week. Received this morning – 17/04/2023

The return of calm bodes well for Spring

Considering how unnerving the first three months of the year were, UK investors in globally-diversified multi-asset portfolios (akin to the ones we manage) have not fared too badly. Mildly positive returns across the risk spectrum tell the story of another storm having passed without sinking global capital markets. Of course, predicting a less turbulent lead-in to summer may be foolish. While most global regions appear to be on a gentle economic upswing (and China’s upswing looks increasingly robust) US weekly employment data has been weakening noticeably and, by our measure, is close to becoming a signal of recession. Meanwhile, UK employment has also weakened. Across the Western world, small companies continue to be stressed by high short-term lending costs, if they can even get loans. Some have no longer access to loans at all. In the US, the profitless tech companies are still finding access to equity cash difficult to come by.

This suggests that until central banks are comfortable headline inflation no longer poses a threat, destabilising bankruptcies remain a strong possibility. Last week, we had mixed messages from central bankers, with either warnings about rate rises or statements about “wait-and-see”. We are still yet to hear anyone proposing that cuts should be made. The all-too-predictable danger is that rate cuts are only discussed after economies have started falling. But to give central bankers their due, they have yet to induce recession despite the talk for the past year. The renewed calm in markets is a positive for the prospects of a soft landing. But the outlook feels delicately balanced. Yes, we have lower volatility and progress to towards smaller ‘waves’ in markets and the economy. At the same time, the inflation genie is slowly being squeezed back into the proverbial bottle. This all bodes well – for now.

Mixed risk signals abound

The US dollar has been notably weaker this year. Of course, as the world’s reserve currency, dollar moves are affected by much more than economic fundamentals. Dollar assets, like US Treasury bills, are regarded as safe havens by investors. As such, the dollar tends to strengthen when markets fear weak global growth – one of the defining narratives of last year. By the same token, the dollar tends to weaken when markets are hopeful for the global economy, as other riskier assets become more attractive relative to those US safe havens. Economists therefore sometimes interpret dollar weakness as a sign of risk appetite.

A risk-on move makes some sense in the current environment. Now that economic weakness is clearly coming through, investors are increasingly looking ahead to the next growth cycle. Indeed, US Federal Reserve officials have even started hinting that interest rates might loosen in the near future. The problem is that this rationale does not fit with the wider market moves experienced. The US stock market has traded basically flat over the last two weeks, and shown little sign of a sustained up-turn.

Moreover, gold – the historical safe-haven asset – has rallied strongly over the last month. And to make matters more confusing, so too have the – decidedly less safe – cryptocurrencies. Both Bitcoin and Ethereum have had overwhelmingly positive returns this year, the latter up 55% in dollar terms and the former climbing an eye-watering 75%. What to make of these mixed signals? Looking at the current state of capital markets and the global economy, it is impossible to say for sure, but we have some doubt that dollar weakness and crypto strength should be interpreted solely as signs of general optimism, and other factors are at play, including a dramatic pick-up in Chinese liquidity. In the meantime, the lower dollar is good news for those countries whose currencies have gained, given their input prices from global trade in dollars have fallen, thereby reducing inflation pressures and also improving their relative price competitiveness.

China’s rebound accelerates, while Beijing postpones political agenda

The Chinese government has wholeheartedly shifted to a pro-growth policy set-up this year, abandoning its zero-Covid policy and loosening commercial lending restrictions. As a result, things are undeniably looking better in the world’s second-largest economy. We knew Beijing would provide plenty of fuel for growth, in the form of liquidity injections and easier lending conditions, and signs are clear that this is now having a strong impact. The most recent business sentiment indicators published at the end of March showed a remarkable pick-up coming in the services sector, with the non-manufacturing purchasing managers’ index (PMI) at 58.2 last month, the highest recorded figure since early 2011. China’s manufacturing sector is a little less buoyant, with March’s figure at 51.9, down from 52.6 in February. This suggests an uneven recovery, propelled by consumer spending over industrial activity.

Financial conditions have also eased markedly over the last couple of months, with big increases in overall money supply and the much-watched total social financing numbers. With little inflationary pressure, a desire for domestic growth and muted external support, the People’s Bank of China cut its reserve requirement ratio by another 25 basis points to 10.75% in March. This should encourage banks to lend more, and comes on top of vast liquidity support handed out to struggling property developers last year. Officials are clearly not complacent in supporting growth, as evidenced by the Finance Vice Minister’s plea for more fiscal support and tax cuts for small companies.

While policy conditions are extremely pro-growth, the Chinese government is fully aware that the recovery is fragile. This is likely one of the reasons behind Beijing’s recent détente with western leaders. French President Macron and European Commission President Ursula von der Leyen held a joint summit with President Xi Jinping last week, amid China’s increased military activity in the Strait of Taiwan. Despite the harsh rhetoric between Chinese, US and European officials over recent weeks, Beijing is clearly showing a desire to engage rather than pull out of difficult talks.

One of the most important things to understand about Chinese politics is that issues of national sovereignty – including Taiwan, Hong Kong and Xinjiang – are treated as non-negotiable by the Communist Party, and are therefore ringfenced from economic considerations. What this means is that even if Beijing engages in sabre-rattling around Taiwan, we should still expect conciliatory tones in other areas, in large part because the Chinese economy still needs all the support it can get. And while western consumers struggle, the last thing China will want to do is erect further barriers to trade. Growth is set on an expansion path in China, both now and for the near future. President Xi will not want to crush the green shoots of a recovery. We should therefore expect pragmatism going forward.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

17th April 2023

Team No Comments

Evelyn Partners Update – Investment Outlook

Please see below article received today (14/04/2023) from Evelyn Partners summarising their investment outlook:

Please continue to check our blog content for advice and planning issues and the latest investment markets and economic updates from leading investment houses.

Adam Waugh

14/04/2023

Team No Comments

Brewin Dolphin: Markets in a Minute

Please see this weeks Markets in a Minute update from Brewin Dolphin received late yesterday afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

13/04/2023

Team No Comments

EPIC Investment Partners – IMF Growth Forecasts Blog

Please see below and article received from EPIC Investment Partners this morning (12/04/2023), which summarises their views on the International Monetary Fund (IMF) recently revised forecasts for the UK economy and predictions for other global economies:

The Daily Update: IMF Growth Forecasts

Yesterday (11/04) the International Monetary Fund (IMF) upgraded its outlook for the UK economy, saying it now believes Britain is on track to contract by 0.3% this year, half the 0.6% decline the IMF forecast in January, then expand by 1% in 2024. However, that’s where the good news ends for Blighty, as the IMF believes we will still be the worst-performing large economy on the planet this year. Only Germany will be the other advanced nation to see negative growth this year, and that is by just 0.1%.

So much for Chancellor Jeremy Hunt’s view that the “the declinists are wrong, and the optimists are right” about the UK’s economic prospects. Not that he sees anything wrong in that statement. “Thanks to the steps we have taken, the OBR says the UK will avoid recession, and our IMF growth forecasts have been upgraded by more than any other G7 country,” he said. As they say, torture the statistics long enough and eventually they’ll confess.

Overall, the IMF downgraded its forecast for global growth by a small margin of 0.1% from its 2.9% projection in January, lower than the 3.4% seen last year, with a slight recovery next year to 3%. However, there is a 25% chance that global growth will fall below 2% for the first time since the 2008-09 global financial crisis, more than double the normal odds.  

The Fund’s chief economist Pierre-Olivier Gourinchas said the global economy was at risk of a hard landing, pointing to governments and central banks being behind the curve on getting the inflation genie back in the bottle whilst avoiding slamming the brakes on growth and employment. “We are entering a perilous phase during which economic growth remains low by historical standards and financial risks have risen, yet inflation has not yet decisively turned the corner”, he said.  

Advanced economies are now projected to grow by 1.3% this year and 1.4% in 2024. Within the G7, the US leads the way with an expansion of 1.6% in 2023 and 1.1% in 2024. Canada is eyed at 1.5% for both this year and next, with Japan following with estimates of 1.3% and 1% respectively. After growing 3.5% last year, the EU is viewed as growing 0.8% and 1.4%.  

Away from the G7, emerging markets and developing economies are forecast to grow 3.9% this year after a growth of 4% last year and 4.2% next year. China’s forecast came in at 5.2% and 4.5% with India leading the way at 5.9% and 6.3%. Russia’s economy contracted 2.1% last year, however the IMF believes it will recover most of that contraction with 0.7% growth this year and 1.3% in 2023.  

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

12/04/2023

Team No Comments

Tatton Investment Management – Tuesday Digest

Please see below, a ‘Tuesday Digest’ from Tatton Investment Management discussing the key economic news from the past week. Received this morning – 11/04/2023

Overview: A spring of hope after the gloom of winter?

As the second quarter gets underway, the chances of a global recession seem lower now than they were towards the end of last year. Indeed, a combination of events during the first three months of the year have arguably reduced the likelihood of negative real growth occurring in the next 12 months in most regions. The exception is the US, where chances have increased marginally – the most interesting outcome of this is that it may have reduced the chances of global recession even more.

March saw a flare-up of bank mistrust, which gave investors and capital markets an uncomfortable reminder of the global financial crisis. Bank lending was already tightening and events in March will have made it worse. But rather than tipping things over the edge, markets have viewed this as helping central banks in their inflation fight. Even so, still-sticky inflation makes it harder for central bankers to decide how to proceed, and even harder still for strategists to forecast.

Last week’s crop of economic data only added to the evidence that higher rates in the US are creating a more difficult environment there than elsewhere. Industry has already been slowing, but rates are more keyed on services, which had been expending smartly. The data from the Institute for Supply Management (ISM) showed an unexpected fall, still at a mildly expansionary level of 51.2 but below the ‘inflationary’ level of 52.

It may be that the weaker data from March was directly caused by the fears about banks. Those fears have passed quickly and nobody other than the banks’ equity (and Additional Tier 1) holders have suffered – a very small group. As such, the forthcoming data could bounce back and, with it, inflation. In that case, we’ll be back to square one, only with a weaker set of small businesses.

Right now, the risks feel finely balanced. Will inflation continue to decline, or will it take another financial sector blow-up to make central banks more dovish? At this point, we are happy enough to have stocked up on long maturity bonds in our portfolios after yields spiked higher, but otherwise we remain neutral on risk as the second quarter of 2023 runs its course.

A brief assessment of the global economy

The predictions of imminent recession that pervaded forecasts last year have so far proved somewhat pessimistic. However, economists were generally opining that a stronger than expected 2022 would mean less strength in 2023, so forecasts for the first two quarters of this year were adjusted down.

Yet again, the world’s major regional economies continue to be more resilient than forecasts would suggest. For us, the most notable improvement has been in the Eurozone where economists now estimate gross domestic product (GDP) to rise 0.5% quarter-on-quarter, or 2.1% annualised. By comparison, US GDP is estimated to rise 0.3% quarter-on-quarter (1.3% annualised). The motivation for better expectations has come from falling gas and electricity prices.

China’s growth expectations were also upgraded for this quarter. While China’s rebound proved slower than expected, next quarter’s expectations have been upgraded substantially to a year-on-year growth level of above 7%. Moreover, travel freedoms have spread some of the benefit to the rest of Asia. Meanwhile, Japan’s growth estimates remain positive but optimism has faded, against the trend of other regions.

While consumer confidence has generally improved, house prices remain under some pressure globally and construction has become quite subdued. Business confidence has also improved, and service businesses have become positive. Manufacturers are generally pessimistic still, even if things are not getting worse.

So, overall and in aggregate, the first quarter was a little better than expected. However, the global economy is not growing significantly, and that makes the financial ecosystem somewhat fragile. Perhaps economists remain more concerned about risks than resilience so low expectations can still be beaten for the rest of the year. Much will depend on a resumption of progress towards lower inflation.

Please continue to check our Blog content for advice, planning issues and the latest investment, market, and economic updates from leading investment houses.

Alex Clare

11/04/2023

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below article received from Brooks Macdonald today 06/04/2023 which provides their views on recent global market events:

What has happened

Market sentiment worsened yesterday with additional data releases pointing towards weakness in economic growth. The ADP’s private payroll report came in far lower than market expectations, mirroring some of the softening labour market evidence from the job openings survey on Tuesday. US equities fell yesterday with technology shares underperforming despite rate expectations continuing to fall.

US economic data

After the ADP report set the scene for a risk-off day of equity market trading, the final PMI readings for March were released. There were some sizeable downgrades versus the flash estimates with both the services and composite readings disappointing. To cap off the weak day for data, the US ISM services index came in lower than estimates with declines within the employment and new order subcomponents compared to the previous month. These data releases cemented the market’s view that it was no more than a coin toss as to whether the Fed will raise interest rates by 25bps at their May meeting. Given the focus on employment readings in recent days this sets the market up for the US jobs report which is released tomorrow despite most markets being closed for Good Friday.

US employment report

In terms of what to expect from the jobs report, the consensus expectation is for 240k new jobs to have been created in March, down from the 311k seen in February. The unemployment is expected to remain steady at 3.6% and average hourly earnings are expected to tick down on a year-on-year basis from 4.6% to 4.3%. With the softer employment numbers recently, a major question will be whether this has impacted wage inflation or the average length of the working week (which is expected to remain steady at 34.5 hours).

What does Brooks Macdonald think

Despite employment remaining tight compared to historical averages, investors are starting to consider whether we may be seeing a pivot in labour market strength. The US employment report is therefore crucially important as it could confirm the recent trends in business demand for new workers. Investors will have until Monday in the US, and Tuesday in the UK, to conclude whether the report provides further impetus to the decline in equity markets this week.

Please check out blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Adam Waugh

06/04/2023

Team No Comments

Markets boosted by rising oil prices

Please see below Markets in a Minute article received from Brewin Dolphin yesterday evening, which provides a global market update.

All major indices finished last week in the green as rising oil prices helped to boost energy stocks, while fears of financial instability eased.

In Europe, the Stoxx 600 gained 4.0% and Germany’s Dax added 4.5% after eurozone inflation eased to 6.9% year-on[1]year in March, down from 8.5% in February. The UK’s FTSE 100 rose 3.1% after fourth quarter gross domestic product (GDP) figures were revised upwards.

Over in the US, the Dow added 3.2% and the Nasdaq rose by 3.4% in a week that saw the Federal Reserve’s preferred inflation gauge rise by a less-than-expected 0.3% in February.

China’s Shanghai Composite edged up 0.2% and the Hang Seng gained 2.4% after premier Li Qiang said China would work to expand its domestic market, improve the business environment, and prevent financial systemic risks.

Markets mixed as global oil output cut

Markets closed with mixed results on Monday (3 April) following a decision by the Organisation of Petroleum Exporting Countries (OPEC+) to cut oil output by more than one million barrels per day. The move could harm efforts to cool global inflation, and has raised new concerns about a further US interest rate hike in May.

The pan-European Stoxx 600 ended the day down 0.1%, whereas the UK’s FTSE 100 gained 0.5%. Energy stocks performed particularly well, with Shell and BP adding 4.5% and 4.3%, respectively. In the US, the Dow gained 1.0% and the S&P 500 rose by 0.4%.

In economic news, the Institute for Supply Management’s manufacturing purchasing managers’ index slipped by more than expected in March to 46.3, the lowest level in nearly three years, as new orders declined.

US core inflation cools

Last week saw the release of the closely watched US core personal consumption expenditure (PCE) index – the Federal Reserve’s preferred measure of inflation. Core PCE, which excludes food and energy, rose by a lower-than-expected 0.3% in February, an improvement on the 0.5% increase seen in January. On an annual basis, core PCE increased by 4.6%, down slightly from 4.7% in January.

Headline PCE, which includes food and energy, grew by 0.3% month-on-month and 5.0% year-on-year, compared to 0.6% and 5.3%, respectively, in January. Food prices rose by 0.2%, goods prices by 0.2% and services by 0.3% month-on-month, while energy prices declined by 0.4%.

Eurozone inflation eases

The eurozone headline inflation rate slowed to 6.9% in March from 8.5% in February, according to figures released by Eurostat on Friday. This was lower than the 7.1% increase forecast by economists and represented the largest drop since 1991. The decline was largely driven by a reduction in energy costs, which helped to ease cost[1]of-living pressures. Annual energy inflation fell from 13.7% to -0.9%. In contrast, prices for tobacco, food and alcohol grew by 15.4% in March year-on-year.

Core consumer price growth, which excludes food and energy, grew to 5.7% from 5.6% in February, reaching an all-time high. This result, combined with unemployment remaining low at 6.6%, has added to expectations of further interest rate hikes by the European Central Bank. Investors are broadly expecting a 0.25 percentage point increase in May, with up to two more hikes of the same size in the summer.

UK house prices see highest fall since 2009

Here in the UK, house prices fell by 3.1% year-on-year in March, the largest decline since July 2009, according to figures from Nationwide. Prices fell by 0.8% month[1]on-month, the seventh-consecutive monthly decline. The average house price in the UK is now £257,122.

Separate data from the Bank of England showed the number of mortgage approvals increased to 43,500 in February, up from 39,600 in January. This was the first rise in six months. Meanwhile, net mortgage lending dropped from £2bn in January to £0.7bn in February, the lowest level since 2016 (excluding Covid).

Revised US and UK GDP figures released

Figures released by the Commerce Department last week showed the US economy grew by slightly less than expected in the fourth quarter of 2022. GDP grew at an annual pace of 2.6%, lower than the previous estimate of 2.7% and down from 3.2% in the third quarter. This was driven by downturns in exports, non-residential fixed investment, state and local government spending, and a decline in consumer spending to 1.0%.

Economists have predicted US GDP will grow by up to 3.2% in the first quarter of this year. On an annual basis, expectations are for growth of 0.3 percentage points to 1.2%. Sentiment has been dampened due to recent turmoil in the banking sector.

Meanwhile, revised figures from the Office for National Statistics showed the UK avoided a technical recession in the fourth quarter of last year as GDP grew by 0.1%. GDP in the third quarter showed a decline of 0.1%, a smaller contraction than initially thought. A technical recession is defined as two consecutive quarters of contraction.

Please check in again with us soon for further relevant content and market news.

Chloe

05/04/2023

Team No Comments

Brooks Macdonald – Weekly Market Commentary

Please see the below article from Brooks Macdonald, providing a brief analysis of the past week’s economic and markets news. Received yesterday afternoon – 03/04/2023

Equities rallied on Friday as US and Eurozone inflation expectations came in below market expectations

Equity markets ended Q1 strongly on Friday, with the US index staging a late rally to cap off a positive week for markets as investors look to move past the banking turmoil of recent weeks. A significant driver of the risk on move was Friday’s softer-than-expected inflation data, which allowed bonds to rally after a tough week for the asset class.

On Friday the latest Core Personal Consumption Expenditure (PCE) inflation index was released, which came in at 0.3% month-on-month, lower than market expectations. The year-on-year reading of the US Federal Reserve’s (Fed) preferred inflation measure also missed expectations, coming in at 5%. Inflation expectations were somewhat of a mixed bag with the University of Michigan survey showing a fall in 1-year inflation expectations whilst those over 5 and 10 years rose. We also saw the Eurozone area inflation released which missed expectations after concerns had risen that European inflation would be stickier after the German release earlier in the week.

OPEC+ announced over the weekend that they were set to cut oil production by 1 million barrels-a-day

Over the weekend the OPEC+ group of oil exporting countries unexpectedly announced that they would cut oil output starting in May. The cut is set to exceed 1 million barrels a day with Saudi Arabia alone cutting 500,000 barrels a day. OPEC+ agreed to allow Russia to keep production unchanged as it struggles to finance the ongoing war in Ukraine. The White House strongly opposed this latest cut, citing its impact on consumers and its global inflationary impact. Global oil demand has been soft in Q1 of 2023 with oil prices falling each month of this year so far, as a result it is currently uncertain as to the equilibrium price for oil after the supply cuts. Falling oil prices have been a major driver of some of the disinflationary forces of the last 6 months and therefore policy makers will be concerned that the latest OPEC+ move may push back against their attempts to control inflation.

The risk of higher energy prices over the coming months will concern governments and central banks

Oil prices have started the week sharply higher with US equity market futures pointing to a lower start to US trading after the late rally on Friday. Lower energy prices have undoubtedly played into the lower 1-year consumer inflation expectation numbers released on Friday. Policy makers will be very conscious of the risks that a new surge in energy prices will represent and this will give further impetus to central banks to retain a hawkish narrative.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

4th April 2023