Team No Comments

Rising interest rates – what happens next?

Please see below article received from Brewin Dolphin yesterday evening, which discusses why inflation remains high, whether a US recession is imminent, and the longer-term outlook.

Why is inflation still high after multiple rate hikes?

Interest rate changes can take a long time to materially affect inflation. Part of the reason is that many loans have fixed terms, where the interest payment does not immediately reflect changes in the central bank policy rate. Rate hikes have started to make an impact, but it will take time for the full effect to be felt.

The extent to which rate hikes influence different inflation categories varies. Central banks exercise a lot of control over house price and rental inflation, as this is a very interest rate-sensitive sector. Rate hikes have already depressed real-world rental inflation, but this takes time to impact consumers as it depends upon when rental agreements are renewed.

Wage inflation tends to be the most important determinant of services inflation excluding housing. The eventual drop in consumer and business spending from rate hikes leads to weaker demand for workers, which then depresses wages. In this sense, rate hikes have a big impact on services ex-housing inflation, but there can be long lags. At present, labour markets in many countries are very tight. For example, in the US there are currently 1.6 job openings for every unemployed worker. This tightness is keeping services ex-housing inflation running strong, notwithstanding the building headwind from higher rates.

Rate rises tend to have a weaker impact on tradeable goods inflation. Food inflation has dropped sharply in recent months in the US, but it remains strong in the UK and other European countries. The Russian invasion of Ukraine, regional weather and its impact on harvests, and foreign exchange movements explain much of the relative divergence in food price inflation in the US and Europe.

When will mortgage holders feel the impact?

It goes without saying that those who are on variable[1]rate mortgages are already feeling the impact of higher mortgage rates. But most households in the US and UK are on fixed-rate deals. Some households on fixed-rate mortgages have already begun to marginally reduce their spending in anticipation of their deals coming up for renewal at higher rates. In its May monetary policy report, the Bank of England (BoE) estimated that higher mortgage rates reduced UK aggregate household consumption by 0.3% in the first quarter of the year. This reduction in spending is being driven by mortgage holders on variable rates as well as those on fixed rates that have already reset.

We would expect that the majority of the reduction in spending will occur when fixed-rate deals actually renew. Roughly 85% of residential mortgages in the UK are fixed, but with terms for the most part at five years or less. The BoE estimates that higher mortgage rates will reduce aggregate household consumption by almost 0.5% by the fourth quarter of 2024. Notably, mortgage terms in the US are generally fixed for a much longer period, often to 30 years.

Another potential impact of higher mortgage rates is an increase in homeowners defaulting on their loans. The extent to which defaults occur will be linked not just to how high mortgage rates go (and for how long they stay there), but also by how the economy evolves. It is safe to say that if unemployment rises substantially, mortgage defaults will increase.

Have rate hikes been more effective in the US?

Several forces have brought inflation down faster in the US than in other regions. For one, the Federal Reserve (Fed) has been more aggressive in its monetary tightening efforts compared to most other central banks. The Fed has so far raised rates by five percentage points. This is above the 4.4 percentage points of hikes implemented by the BoE and 3.75 percentage points of hikes by the European Central Bank.

Meanwhile, until last autumn, the US dollar was strong, which depressed traded goods inflation. Weak European currencies relative to the dollar had the opposite effect. In addition, the inflation stemming from Russia’s war in Ukraine has had more of an impact on Europe. Wage-driven inflation has been a factor on both sides of the Atlantic, as demand for workers has been strong. But the UK has struggled more than most countries with labour supply, with Brexit likely a contributing factor.

What is the relationship between rate hikes and recessions?

Of the 13 Federal Reserve rate hike cycles since the mid-1950s, ten have been followed by a recession that began within a year-and-a-half of the last rate hike of the cycle. While this is clearly a high hit rate, it’s important to note that tightening cycles don’t happen in isolation and are not always the main driver of a recession.

Of the four US recessions that have occurred since 1990, the Fed certainly played a role, but the rate hikes were arguably not the primary cause of any of them. In two of these cycles, a shock rather than rate hikes was the primary cause of the recession. This was the case in 1990, when the economy only went into recession after the oil price spike due to the Gulf War. It was also the case in early 2020, when the recession was all about the Covid shock and had little to do with the Fed’s rate hikes of 2018.

In the other two cycles, the recessions were driven more by the unwinding of large excesses. In 2001, the recession was much more about the contraction in technology-related investment spending than it was about Fed rate hikes. Consumer spending (which represents about 70% of the economy) didn’t decline at all in that recession. In 2008/09, Fed rate hikes certainly acted as a catalyst (as was the case in 2001), but the recession was more about the unwinding of the excesses in banking and housing following a period of very lax lending standards. The main point is that the relationship between rate rises and recessions is not straightforward.

We believe it is more likely than not that the US suffers a recession, with a start date at the end of this year or perhaps in early 2024. But our conviction in this forecast is not high as there are pathways to a ‘soft landing’ (a slowdown in economic growth that avoids a recession). Europe and the UK may avoid an outright recession, but we expect growth to be sluggish. If a US recession does occur, it will likely be mild. A mild recession would limit increases in both the unemployment rate and mortgage defaults. It is also worth highlighting the supply/demand backdrop for housing, which is tight. House prices will suffer as this BoE rate cycle goes on, and to the extent that unemployment rises. But because there is so little supply, that should help to limit the declines. Similar supply and demand dynamics exist to support UK house prices in the face of higher mortgages rates.

What has happened historically after periods of low interest rates?

Central banks hiked rates rapidly in several periods during the 1970s and 1980s, but rates were not low heading into these cycles. Rates were low for a long time following the global financial crisis of 2008, but the subsequent rate hike cycles (2015-18 for the Fed and 2017-18 for the BoE) were very modest. There’s no good historical precedent for the current environment.

Mark Twain’s quote, “History does not repeat itself, but it often rhymes”, is often used to compare economic cycles. As highlighted above, some cycles involve shocks. Other cycles involve the build-up and subsequent unwind of excesses and imbalances. Some cycles see both occur. This cycle has its own similarities and differences with those of the past.

Please check in again with us soon for further relevant content and news.

Chloe

19/05/2023

Team No Comments

Brewin Dolphin: Markets in a Minute

Please see this week’s Markets in a Minute update from Brewin Dolphin received late yesterday (16/05/2023) afternoon:

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Carl Mitchell – Dip PFS

Independent Financial Adviser

17/05/2023

Team No Comments

Brooks Macdonald – Weekly Market Commentary

Please see below, Brooks Macdonald’s Weekly Market Commentary providing a brief analysis of the key economic and market news over the past week. Received yesterday afternoon – 15/05/2023

Equity markets were subdued last week with US equities seeing small losses and European equities small gains. Technology equities outperformed with large cap US names leading the narrow but powerful rally seen in 2023.

Inflation expectation data suggests that consumers think that inflation will be stickier in the US

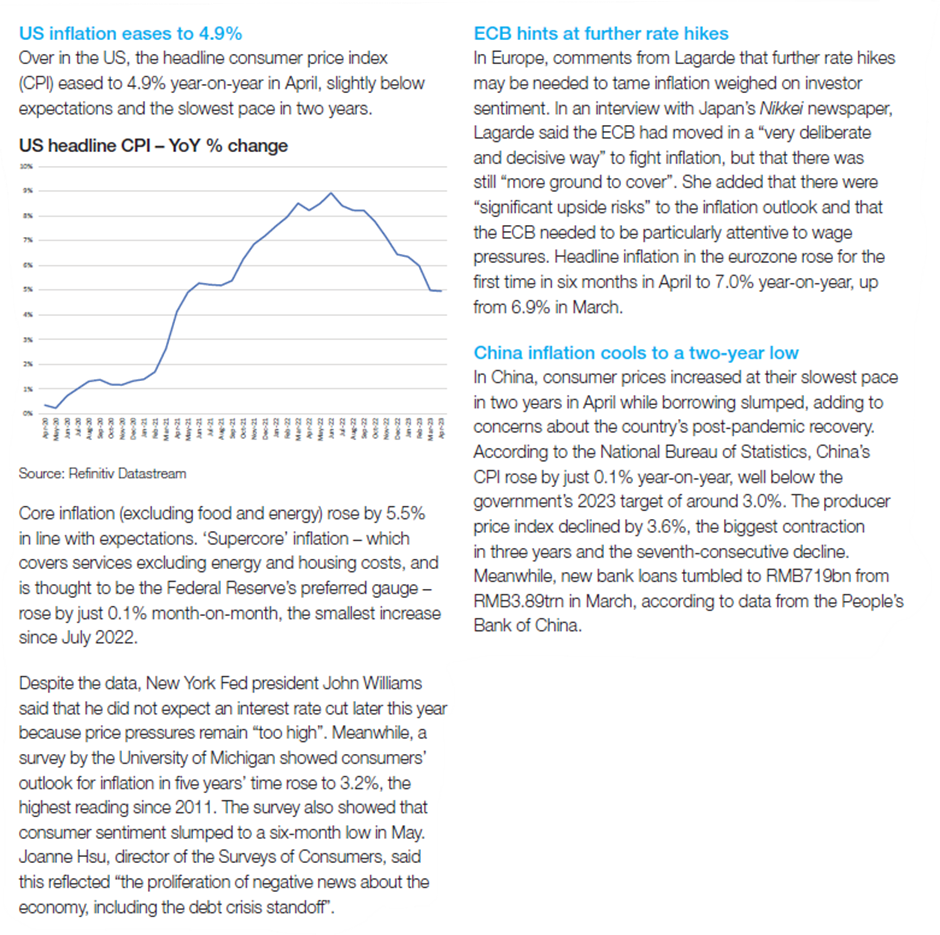
On Friday last week the release of the University of Michigan’s consumer and inflation data damaged sentiment. The long-run consumer inflation expectations rose to 3.2%, ahead of 3% in the prior reading and market expectations of just 2.9%. This number is often revised however the US Federal Reserve (the Fed) will be concerned that this may suggest that inflation expectations are becoming more anchored. The one-year measure of expectations was also above expectations but did fall slightly from the month prior. Consumer sentiment was worse than markets had expected, with consumers citing fears of a more protracted recession as a major contributor to the more sombre reading. This week investors will be looking to the US retail sales numbers on Tuesday which are expected to have expanded but for a meaningful proportion of this expansion to have been caused by higher gas prices. The headline number therefore may be a distraction and the data is likely to confirm a slowing in consumption compared to the start of 2023.

Allegations of fraud in the initial jobless claims puts the data release in focus this week

The high-frequency US initial jobless claims data is released on a weekly basis and will be watched closely on Thursday given this is the week where the surveys are completed for the next US employment report. Media reports and statements from the Massachusetts Department of Labor suggest that the recent initial jobless claims data may be misleading in suggesting a softening of labour market tightness. The state has accounted for around half the rise in four-week moving average claims since the late January low. Should these claims have been subject to fraud, as the data and media reports suggest, the initial jobless claims may start coming down significantly, whilst this would be good news for the US economy it is of course less positive for inflation.

UK labour market data this week will help determine whether the UK continues to hike interest rates

With the focus previously on US labour market strength, this week will see the release of UK labour market data which is particularly important as bond markets debate whether there will be a pause in the UK interest rate. Should the data continue to show strength in wage prices this will put pressure on the Bank of England to maintain its tightening stance.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

16th May 2023

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management, providing a brief analysis of the key stories from global markets and economies over the past week. Received this morning – 15/05/2023.

Overview: Trust the MPC to rain on May’s parade

After a period of waiting, things are hotting up after central banks acted as expected. Although equity and bond markets have been bearing up well, in our estimation, underlying risks have increased since May began. Last week, it was the turn of the Bank of England (BoE) to increase the UK base rate to 4.5%. After members of the Monetary Policy Committee (MPC) digested reports of tepid growth of 0.1% for Q1 (with March contracting by 0.3%), the 0.25% hike was nailed on. The BoE raised its estimate for economic activity this year and no longer thinks there will be a recession. However, year-on-year inflation is now likely to take longer to ease off, and is expected to remain above 8% as of June, and to finish 2023 at 5.1%. It says the risks are skewed towards inflation staying well above its 2% target. Not everyone agrees. The BoE still worries the UK does not have enough resources to fuel overall growth which is why it sees inflation risks skewed to the upside. The biggest resource shortage is the number of workers (skilled and unskilled) needed to do the work, and it’s difficult to see how this will be resolved in the short to medium term.

Meanwhile, the environment for businesses across the developed world remains difficult. Rises in short-term rates have happened almost everywhere and at the same time. Indeed, apart from the early 1980s, there has never been a such a period with virtually all central banks acting as if in concert. That unified action also means their policies have an unprecedented global impact, magnified by a more interlinked world than in the 1980s. At Tatton, we’re sure central bankers take into account the impact of each other’s decisions, and yet this final phase of rate rises could be viewed as coordinated overkill.

US debt ceiling brinkmanship is nothing new

US Treasury Secretary Janet Yellen has warned the federal government could default on its debt obligations very soon. Perhaps the oddest thing about this state of affairs is that it doesn’t feel like big news. The Treasury hit the current debt ceiling – at $31.4 trillion – on 19 January. Since then, it has been steadily running down the ample funds in the Treasury General Account, buffered by April’s tax receipts. President Biden wants to “take the threat of default off the table”, but Republican House speaker Kevin McCarthy has said his party’s position remains unchanged. Estimates for when the X-date (when the US is officially unable to meet its obligations) falls due are varied, with the latest suggesting it could come in August. But Yellen has warned the government might be unable to meet all its obligations as early as 1 June.

While the media gets excited about the debt ceiling soap opera, we’ve all been here before (at least three times since 2011, to be exact). And realistically the US government’s default risk is zero. Moreover, behind all the brinkmanship, US lawmakers will not want to bankrupt the government. Nevertheless, Biden’s suggested invoking of the 14th Amendment – which states the viability of US Treasury bonds cannot be placed into question – is a signal of how seriously he takes the situation. We mostly agree that reaching the dreaded X-date without an agreement is extremely unlikely but would point out brinkmanship can push things over the edge even when all participants do not mean it to. More important is what happens between now and the X-date – particularly for federal employees. The issue will likely see a short-term resolution, but that sets up an interesting budget confrontation later in the year. As well as dictating actual federal spending, that could well set the agenda for next year’s presidential election.

European energy prices: the great reset?

Wholesale gas prices – the main determinant of energy costs for European households and businesses – have not been this cheap since July 2021, when Russia began constricting supply in the lead-up to its invasion of Ukraine. Softer global economic activity appears to be a reason for commodity weakness this year – not just in gas but oil too. Brent crude prices are currently at around $75 per barrel, down from a peak of over $110 last summer. 

The removal of Covid restrictions has led to an economic rebound in China and previous Chinese growth spurts coincided with substantial commodity price rises. So why has this not happened so far this year, despite definitely positive growth in the world’s second largest economy? Recent import data from China shows a decline in the value of oil and gas imports. Interestingly though, the volumes of oil being imported are still very high – just cheap. Indeed, the implication is that the prices are well below market. This is almost certainly because China is soaking up cheap oil on offer from Russia, which has ample supply but few willing customers in the west. We suspected this was going on for some time, and the latest data effectively confirms it. Global energy distribution has reset; the higher prices of 2022 have encouraged new sources of supply. The Russian reduction of energy supply to the world as a whole has proved temporary. 

While few will be pleased that Russia is finding buyers for its gas and oil, it probably means that Europe’s peak of the energy crisis – the worst in the post-war era – is now past. After Russia began its war in Ukraine, we said global energy markets would drastically restructure, but without necessarily altering the fundamental balance of supply and demand. We are arguably seeing the results of this restructuring now. If so, it would mean downward price pressure is reaching an end. Europe’s energy crisis has certainly improved, but the continent might still have a tough winter ahead.

Please check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

15/05/2023

Team No Comments

Evelyn Partners Update – May Bank of England MPC decision

Please see the below article from Evelyn Partners for their thoughts on the Bank of England Monetary Policy Committee’s decision to raise interest rates by 25bps:

What happened?

The Bank of England increased rates by 0.25% today at the May monetary policy meeting, which was consistent with market and economic expectations. This takes the base rate to 4.5%, its highest level since 2008. The Monetary Policy Committee (MPC) voted 7-2 in favour of 25bps.

What does it mean?

The Bank of England (BoE) followed the Federal Reserve (Fed) and the European Central Bank (ECB) in raising its base interest rate by 25 bps. While it appears the Fed is pausing its interest rate hiking cycle, the BoE and ECB could still have some work to do. Much will depend on the incoming data.

At 10.1% in March, UK inflation remains stubbornly high. In contrast, US and Eurozone CPI rose 4.9% and 7%, respectively in April. This divergence has been driven by two main factors. First, like the rest of Europe, the UK has experienced a major energy price shock since the Russian invasion of Ukraine.

Second, the UK has experienced far greater labour shortages than the rest of Europe, similar to what we have seen in the US. Many young European workers have left the UK after Brexit and older workers are leaving the labour force due to long-term sickness. This has placed upward pressure on wages and inflation.

As a result, markets have repriced their expectations of the peak in the UK base rate over the last month – they now expect a peak of 5% instead of 4.5%. But much will depend on the data over the next couple of quarters.

We expect to see UK inflation start to ease as the base effects turn more favourable and the impact of higher rates is felt by the real economy. In its latest forecasts, the Bank of England now expects inflation to fall to around 8% for Q2 and 5% by Q4. They expect to meet their 2% target by the end of 2024.

On the plus side, the Bank now thinks the UK will avoid recession in 2023. It revised its 2023 GDP forecast up from -0.5% to 0.25%.

Bottom Line

With inflation remaining stubborn, the Bank will continue to monitor the incoming data before deciding whether to raise interest rates again. With the Monetary Policy Committee continuing to judge that “the risks around the inflation forecast are skewed significantly to the upside” we would not be surprised to see further hikes from the MPC

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

12/05/2023

Team No Comments

Stocks mixed as Fed and ECB hike rates

Please see below ‘Markets in a Minute’ article received from Brewin Dolphin yesterday evening, which provides an update on global markets.

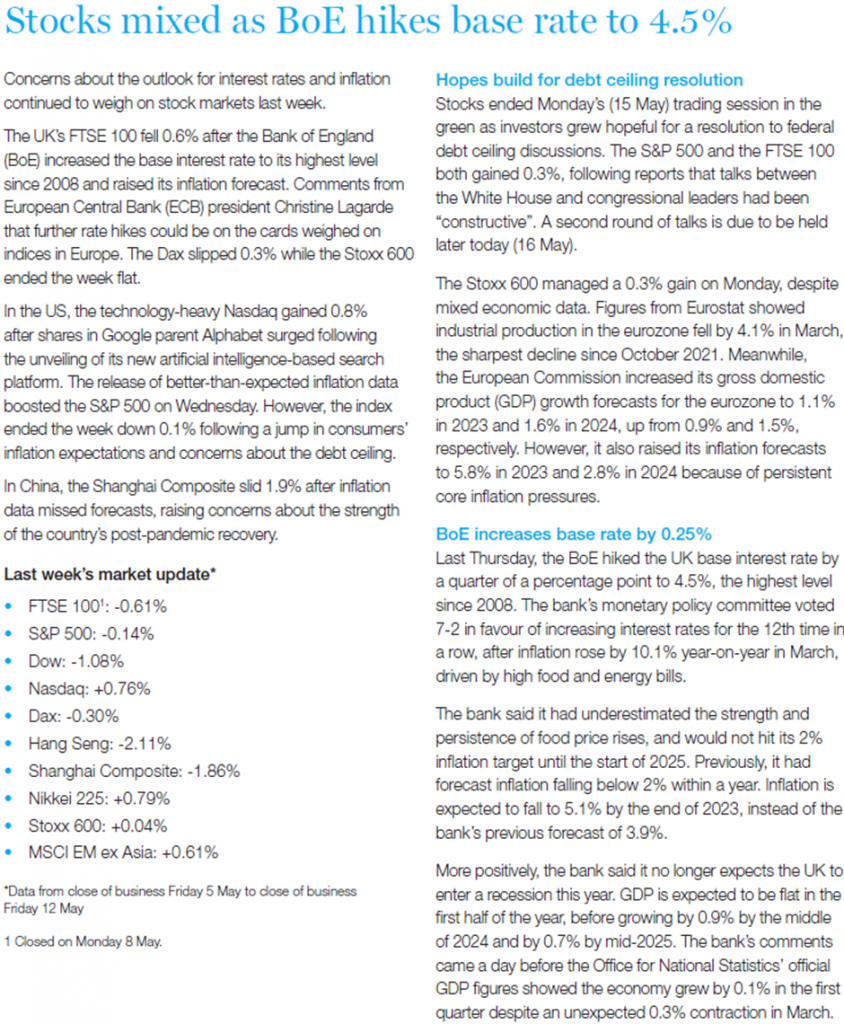
Stock markets were mixed last week as the US Federal Reserve and European Central Bank (ECB) hiked interest rates.

The S&P 500 rallied on Friday after the US nonfarm payrolls report beat forecasts. Despite this, the index ended the week down 0.8%, following comments from Fed chair Jerome Powell that interest rate cuts might not happen as soon as investors had hoped.

The pan-European Stoxx 600 declined 0.3% after ECB president Christine Lagarde said interest rates would rise to “sufficiently restrictive levels” until inflation eased to the bank’s 2% target. The UK’s FTSE 100 fell 1.2% ahead of the Bank of England’s (BoE) interest rate decision on 11 May.

Japan’s Nikkei 225 added 1.0% during the first two days of the week following a sell-off in the yen. The index was closed for the remainder of the week for national holidays. China’s Shanghai Composite ended its holidayshortened trading week up 0.3%, despite the official manufacturing purchasing managers’ index falling into contraction territory for the first time since December.

Stocks slip ahead of US inflation data

Stock markets fell on Tuesday (9 May) as investors looked ahead to the release of US inflation numbers on Wednesday. The consumer price index will be closely monitored for any insights into the Federal Reserve’s next monetary policy decision.

The BoE is expected to hike interest rates for the 12th time in a row on Thursday, with economists and markets anticipating a quarter of a percentage point increase to 4.5%. It comes after official data showed the rate of inflation stood at 10.1% in March, far higher than expected.

US nonfarm payrolls beat forecasts

Last Friday saw the release of the closely watched US nonfarm payrolls report, which showed surprisingly strong jobs growth in April. Some 253,000 new jobs were added during the month, higher than the 180,000 forecast by economists and the 165,000 job gains recorded in March.

The report from the Department of Labor also showed average hourly earnings increased by 0.5% month-onmonth, the highest rate since the middle of last year. Meanwhile, the unemployment rate fell back to a 53-year low of 3.4% from 3.5% the previous month.

Separate data showed the number of job openings shrank for a third consecutive month in March. However, there are still 1.6 job openings for every unemployed person, which suggests the labour market remains tight.

Fed hikes rates as expected

Earlier in the week, the Federal Reserve hiked interest rates by a quarter of a percentage point, taking the benchmark fed funds rate to between 5.0% and 5.25%. The statement from the Federal Open Market Committee omitted language saying that further policy firming may be appropriate. Instead, it said officials would take into account how the impact of monetary policy was accumulating in the economy.

At a press conference later in the day, however, Powell indicated that it was too soon to say with certainty that the rate-hiking cycle is over. Powell said the Fed was “closer, or maybe even there”, but that it was “prepared to do more” and future policy decisions would be made on a meeting-by-meeting basis. Powell also indicated that a pivot to cutting rates would not occur this year.

ECB scales back rate increases

The ECB also increased interest rates by a quarter of a percentage point last week, scaling back from its three previous half-percentage point increases. The move takes the main policy rate to 3.25%.

However, Lagarde indicated that the fight against inflation is far from over. “We have more ground to cover and we are not pausing, that is extremely clear,” she said. Lagarde added that some of the ECB’s rate-setters had called for a bigger increase and that the “inflation outlook continues to be too high for too long”. Headline inflation in the eurozone rose for the first time in six months in April to 7.0% year-on-year, up from 6.9% in March.

Housing market shows signs of stabilising

Here in the UK, data from the Bank of England suggested the housing market could finally be stabilising after the turmoil caused by last autumn’s mini-budget. Net mortgage approvals rose for a second consecutive month to 52,000 in March, up from 44,100 in February and much higher than expected. This came after data from Nationwide showed UK house prices unexpectedly rose by 0.5% in April, following seven consecutive months of declines. The cost of an average home increased to £260,441, which was still 2.7% lower than a year ago.

Please check in again with us soon for further relevant content and news.

Chloe

11/05/2023

Team No Comments

Liontrust – Investing for a healthier future

Please see below, an article from Liontrust highlighting the potential opportunities of investing in companies that are striving to provide a healthier future for society. Received this morning – 09/05/2023

With billions of people living longer than ever yet often in poor health, there is a growing focus on investing to improve people’s quality of life.

As society prospers, one of the constant and reliable areas of growth is in enhancing living standards. Medical innovation has driven up life expectancy across much of the world, with significant advancements in the ability to treat ill health and disease. Meanwhile, society has benefited from dramatic improvements in living standards with better urban environments, air quality and nutrition.

Yet there are significant challenges ahead. The combination of rising lifestyle diseases and an ageing population is placing significant strain on healthcare services such as the NHS. But while the challenges are immense, they also provide huge opportunities for those companies innovating to provide solutions to the issues and potential rewards for investors.

Post the Covid-19 pandemic, there has been a renewed focus on the need to improve the nation’s health and wellbeing. According to a survey by Public Health England, 40% of respondents gained around 3kgs of weight during the period. However, a survey by the British Heart Foundation show that two-thirds of respondents say that exercising is a top priority for improving their physical and mental health in the wake of coronavirus.

Martyn Jones, fund manager on the Liontrust Sustainable Future team, says: “The desire to improve quality of life and living standard continues to be an important driving force in the global economy and will provide a strong tailwind to the companies exposed to these trends. Our job is to back the rare businesses that can harness these tailwinds and generate strong profitability over the long-term with durable competitive advantages.”

A key investment theme for the Liontrust Sustainable team is Delivering healthier foods – which seeks to find companies that are helping to improve the nutritional characteristics of food in order to tackle the obesity epidemic.

Jones says: “By 2026, the market for healthier food and drink is expected to be worth around $1 trillion and an area of the market that we particularly like is in the flavour technology space.

“It is a cost that rarely makes up more than 10% of food and beverage products but is extremely important to the end consumer. In our view, this is not just a trend, but a market experiencing structural long-term growth.”

Jones highlights Kerry Group as a great example of this in the Sustainable Future portfolios. Established in 1972 as a dairy cooperative, it has since evolved to become one of the largest and most technologically advanced ingredients and flavours technology companies. Their innovations help to reduce salt, fat and sugar while retaining taste, texture and flavour.

The Sustainable team also focuses on investing in health, under its Enabling healthier lifestyles theme, through companies that provide goods or services that enable people to live a more active and happier lifestyle, such as gyms and fitness chains.

Yet with consumers globally facing a cost-of-living crisis and looking for ways to make ends meet, many are trading down from more expensive options to low-cost options such as Basic-Fit in Europe.

Though lockdowns across the world during the peak of the pandemic have been tough for the gym market, Jones believe that the tougher the situation, the more well-established low-cost providers will take market share, as they are already positioned to embrace home workouts and have lower operating costs and membership fees.

He adds: “Much of our sustainable thinking at Liontrust focuses on a cleaner and safer world in the future but a third goal requires people to be healthy enough to enjoy this. With a fifth of the world’s population expected to be overweight or obese by 2025, and related diseases impacting both life satisfaction and expectancy, there are issues we simply have to face.

“We believe that the long-term improvements in our living standards and quality of life will persist, driving growth in our themes and long-term returns of companies providing some of the innovative solutions.”

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Alex Kitteringham

9th May 2023

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see below todays (05/05/2023) Daily Investment Bulletin from Brooks Macdonald:

What has happened

Market sentiment on Thursday showed a split between continued worries around the health of US regional banks on the one hand, versus better than expected results from US tech heavyweight Apple. With Apple’s results announced after the regular market close however, they didn’t arrive in time to help the broader market, which closed lower on the day. For the day ahead, the focus is likely to stick with the banks sector, but elsewhere in economic news, US monthly non-farm payroll employment data for April is due – according to a Reuters survey, payrolls are expected to have increased by 180,000 jobs last month, which would be the smallest gain since December 2020 and which would be the third month in a row of deceleration in employment gains.

US regional bank worries continue

US regional bank news it seems is bookending the week. After the failure and sale of First Republic to JP Morgan at the start of this week, US regional banks resumed their share price slide on Thursday. In the crosshairs, PacWest’s share price has seen heavy falls this week on the back of a Bloomberg story that the bank was exploring sale options. While PacWest has since confirmed that “the company has been approached by several potential partners and investors – discussions are ongoing”, the bank has tried to calm market nerves, saying in a statement released yesterday that “the bank has not experienced out-of-the-ordinary deposit flows following the sale of First Republic Bank”, and that “core customer deposits have increased since 31 March”.

ECB hikes and leaves door wide-open for more, in contrast to Fed’s latest signalling

The European Central Bank (ECB) hiked interest rates by 25bps on Thursday, taking its deposit rate to 3.25%, a post-2008 high, and up from a negative rate of -0.5% in less than a year when it first starting hiking in July 2022. While the pace of hikes was a downshift from 50bps at each of its previous 3 meetings, the ECB did not appear to follow the Fed regarding interest rate path outlooks. While the Fed on Wednesday hinted at a possible pause, the ECB left the door wide-open for additional tightening on Thursday. As well as plans to stop reinvestments of its Eur3.2trillion Asset Purchase Programme from July, ECB president Lagarde said there were “still significant upside risks to the inflation outlook”, and on future possible rate hikes that “we have more ground to cover and we are not pausing”.

What does Brooks Macdonald think

There is a something of a separation in the way that both policy makers and markets are thinking at the moment. For central banks, they continue to believe that they can separate the interest rate ‘inflation vs economic growth’ trade-off from bank stress. Equally, markets are continuing to take solace in the latest Q1 earnings beats, including from tech, and meanwhile treating the current US regional bank hiatus as non-systemic. How US regulators in particular tackle the thorny issues around their regional banks, both in terms of regulatory oversight but also in terms of the potential for any deposit insurance cap changes in the weeks and months ahead will be key.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Andrew Lloyd DipPFS

05/05/2023