Team No Comments

EPIC Investment Partners: Bank of England losses add to the chancellor’s woes – by Sir John Redwood

Please see below, an article by Sir John Redwood for EPIC Investment Partners, providing a detailed analysis of the Bank of England’s operations in the bond market. Received yesterday – 23/06/2025

The Bank of England’s legal status and aims

The Bank of England is 100% owned by the state, led by a Governor appointed by the government and ratified by Parliament. The Governor reports to Parliament’s Treasury Committee on his actions and policies. Parliament legislates to reset the Bank’s aims and tasks when it wishes. 

The Bank has under its current legislation an independent status to set the key base short term rate and to publish its own economic forecasts. It made large purchases of bonds (£895bn at peak) in response to the banking crash of 2008, briefly after the Brexit vote, and on a large scale during Covid. This was a joint policy of government and the Bank. All purchase programmes required Chancellor sign off with the grant of full Treasury indemnity against any losses the Bank might incur on the bonds.

The main aims of the Bank are to keep inflation at around 2% and to ensure financial stability in the UK markets and banking system. It had a good record on inflation in the decade following the banking crash of 2008, against a benign deflationary world background and with plenty of Chinese competition in goods helping keep prices down. Like the Fed and ECB, but unlike the Swiss, Japanese and Chinese central banks, the Bank of England presided over a surge in inflation this decade, hitting a peak of 11% in late 2022 against the 2% target.

The Bank did not keep markets stable in 2007-9, when there were violent convulsions in the banking system, as in the US as well. There was a short crisis in the UK in late 2022. Markets were driven down by rises in official rates here and in the US, an expansionary budget which was reversed, the Bank’s announcement of a major sales programme of gilts and the plight of pension fund investments in geared bond funds. Pension funds had to sell bonds to cover losses and meet calls on their leveraged positions. This forced the Bank to temporarily reverse its bond sales plans and to buy bonds again to stabilise the market.

The Bank and the Asset Purchase Facility

The joint government/Bank bond portfolio was acquired by the Asset Purchase Facility (APF) at the Bank. As it bought bonds from the market, more cash was deposited with the commercial banks, who in turn increased their deposits with the Bank of England. In the early years of the APF, with interest rates falling, the Bank made money on the difference between the amount of interest it earned on the bonds and the lesser amount it paid out for the deposits.  Up to mid 2022 the Bank was paying its profits (£123bn) on this over to the Treasury, who spent the cash. When rates started to rise the Bank moved into loss on the portfolio, as the low interest rates it had locked in by buying the longer term bonds were below the higher and rising level of interest on the deposits it held from the commercial banks. The Treasury had to start paying out for the losses. 

The Bank added to the losses by proceeding with a programme of bond sales into the market. The bonds were well below the purchase price they had paid, as interest rates had gone up a lot, depressing the price of the bonds. The long dated bonds were often more than 50% down on purchase price and recorded large losses which the Treasury is now paying. No other central bank that had bought up bonds to provide stimulus during Covid lockdowns has been selling bonds at a loss. They wait for the bonds to mature, when they get back the original issue price of the bonds. The closer a bond gets to maturity the closer the market price will move to the original issue price, reducing the losses at a time of higher interest rates. 

In 2023-24 the UK Treasury paid £44.5bn to the Bank for bond losses in the APF. The Office of Budget Responsibility is forecasting losses of £257bn from mid 2022 to mid 2033 when they expect the portfolio to be wound up. These losses are now becoming a matter of public debate, with some urging the Bank and government to take action to reduce them and save the Treasury some money. The other trading profits and losses of the divisions of the Bank are very small in comparison to the APF losses.

The Bank deliberately paid too much for the government debt or bonds it bought to drive their prices higher, often paying well above the repayment value of the bond in order to get interest rates well down.

A graph of a graph showing the growth of the company's shares

AI-generated content may be incorrect.

What are the Bank’s options on bond losses?

The Bank is currently incurring three types of loss. There is the loss on sales in the market at depressed prices. There is the lesser loss on maturity on bonds bought above issue value. There is the running loss on the interest differentials.

There is nothing the Bank can do to avoid losses on maturity. The private sector is the winner as they sold the bonds to the Bank at a high price and can buy them back at a lower price when new replacement bonds are issued for the maturing ones.

The Bank can suspend or cancel its bond sales at a loss. It does not argue there is a necessary monetary purpose for the sales and is out of line with other central banks. Holding them for longer means continuing revenue losses on the interest differences, but avoids large one off up front losses. Future interest differential losses may reduce as interest rates fall. Capital losses will be much reduced by holding. 

The Bank can change the amount of interest paid to commercial banks on their deposits. The European Central Bank (ECB) changed its policy in 2023. It pays no interest on a specified minimum level of reserves a commercial bank has to keep with the Central Bank. It has a lower deposit rate from its lending rates to reduce its losses. The markets accepted this meaner treatment of commercial banks in its system. 

Some Bank of England critics think it should return to the older system when it did not pay interest on reserves. This would be a much tougher policy on the banks than the ECB one, cutting bank profits and income considerably, much as a bank tax would. This might have adverse market consequences and could have an impact on credit growth and general economic growth. Banks would need to balance the wish to withdraw reserve deposits and make better use of them with the impaired profit and cashflow which could affect their capacity to lend.

What might the Bank do?

It seems unlikely the Bank will suddenly remove all interest on reserves, as they tend to move cautiously and would not wish to be seen to be following Reform party policy. The Bank may, with behind the scenes government encouragement, take more limited action to reduce some of the losses. This they could most easily do by postponing long bond sales. The Bank will be concerned at how longer rates have risen this year and are now consistently higher than in the late 2022 period of bond volatility. They are less likely to create a minimum reserve requirement with no interest, as they have written about how they find it difficult to judge what the correct level of reserves should be. 

Markets will be watching carefully the increases in spending announced as part of the Spending Statement and considering what budget action will be taken later this year to ensure conformity with the Chancellor’s fiscal rules. There is general agreement that more tax revenue will be needed to keep to the requirement to balance the revenue account later this Parliament. For the time being the UK offers higher rates than the US, Euro area and Japanese bond markets provide, whilst we await clearer news on the trajectory of future spending and borrowing. There is likely to be more negative speculation before the budget reveals more about how the revenue side could get closer to matching the increased spending. 

The Bank has allowed too much inflation and is now keeping longer term interest rates higher for longer as it continues to sell so many government bonds. Its large losses invade the budget arithmetic and add to the fiscal pressures which are impeding better UK growth.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

24th June 2025
Team No Comments

De Lisle Partners Commentary on Iran

Below are the latest insights from the De Lisle Partners investment team regarding the recent developments in Iran. Received today – 23/06/2025:

Despite weekend commentators gaming out a range of negative scenarios for an Iranian response to US strikes, we – and the markets – remain calm. In early futures trading on Monday, the Dow Jones, S&P 500 and Nasdaq indices are all slightly positive, while the larger initial move in crude oil was sold.

This is not without precedent, as markets have previously strengthened on US interventions in the Gulf. For example, the S&P 500 rose 4% in early 1991 at the start of the First Gulf War, ending the 1990/1 recession, and went straight on up in a surge of nationalism to trade 16% higher by February 11. Even energy stocks kept pace although the oil price went down.

Today Monday June 23 the market is not so depressed, having already surged since April. But we have clues from this morning’s futures markets and from the rise in the Tel Aviv, Egypt and UAE stock markets yesterday that there is plenty of support for the US strikes. Gold is down and the dollar is up as a further show of confidence in American exceptionalism. Trump’s display of decisive power seems well liked in these politically fractious times.

The reaction today is muted because there is little current concern. The Houthi threat to the Strait of Hormuz is not credible and China and Russia have looked on. American confidence is shown in the 0.6% rise in the dollar and longer-term oil futures reflect little concern of supply disruption. Gold, as a proxy for fear, is not moving much this morning.

For us, our themes are unchanged. Our portfolio is steadfast in long-term secular themes in re-industrialisation and power infrastructure while being counterbalanced by exposure in oil service that strengthens on geopolitical uncertainty. We remain at low levels of liquidity and would add to existing holdings selectively on weakness.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

23rd June 2025

Team No Comments

Tatton Investment Management – Monday Digest

Please see below, an article from Tatton Investment Management analysing the key factors currently impacting global investment markets. Received this morning – 23/06/2025:

The risks are real – but priced in – up to this point of escalation 

Last week’s Israel-Iran escalation ended with higher oil prices, a slight knock to equities and a slightly stronger dollar. Even if that seemed a relatively muted reaction to an historic event, it did nevertheless suggest that markets thought the US would join Israel’s attack. This explains why oil is up by only $1 following the US’ attack over the weekend and that should mean oil continues to stay within ‘normal’ ranges – but that depends on the nature of Iran’s reaction, namely whether it will indeed try to block the Strait of Hormuz as voted for by its parliament on Sunday.  

Last week, potential US involvement created internal tensions between Trump’s MAGA isolationists and old-school Republican war hawks. But his move to action appeared to have rallied and consolidated the factions which could further embolden the president in his aggressive policies, which has the potential to cause market volatility to increase after all. 

Trump also called Federal Reserve chair Powell “stupid” for not cutting interest rates. He’s right that the slowing US economic could do with lower rates, but it’s his tariffs, deportations and general chaos that’s preventing the Fed from doing so. The Fed recognises that the medium-term trend is towards lower rates, but Trump has them in purgatory. It’s heartening, at least, that Powell and co are staying level-headed.  

The Bank of England also held steady but is in a different situation (with a stabler government). It signalled an August cut and will be helped by sterling’s strength.  

Conversely, dollar weakness is a problem for the Fed. The dollar has stayed low despite the US stock market recovery, and the currency effects make middling US company earnings look worse for international investors. This is especially when considering that virtually all the earnings positivity comes from the globally focussed Magnificent Seven.  

Dollar weakness this year reflects stronger growth elsewhere (the FTSE 100 hit a new all-time high) so it’s fitting that ECB president Christine Lagarde wrote about the need for a “global euro”. Currently, US capital markets are joining the Fed in purgatory. Investors now await not just the Israel/US-Iran war but the 9 July tariff deadline.  

The UK equity liquidity problem 

The FCA has just launched its Private Intermittent Securities and Capital Exchange System (PISCES) to boost investment in UK companies. It opens up more companies to private investment, but we think the main problem with UK capital markets is the lack of trading liquidity. This illiquidity comes from high transaction costs and a post-Brexit exodus of market makers, and it has resulted in Britain having one of the lowest domestic ownership rates of its stock market (just 31%). Illiquid markets are more prone to sudden price drops – increasing risks for investors and hence decreasing equity valuations. PISCES opens up more saleable assets, but doesn’t encourage more buyers and market makers.  

The EU has similar liquidity problems – owing largely to the lack of retail investors (relative to the US boom in retail investing). European markets are dominated by large institutional investors, whereas from a ‘gap risk’ perspective you would rather have many small buyers and sellers. Big institutions also prefer to keep their trades away from public order books, so that others can’t copy their trades and move the price before the large orders are fulfilled. That lack of transparency decreases the perception of liquidity.  

Europe’s problems are compounded by a lack of common regulation (as ECB president Lagarde argued in a Financial Times op-ed), which discourages investment banks from acting as market makers. But the bigger problem – as in the UK – is high transaction costs. The US has much lower transaction costs and an integrated market, increasing liquidity and benefitting American companies. 

Reducing UK stamp duty on share trading would therefore help bring back liquidity, but so would greater regulatory alignment with Europe. With London’s financial expertise, Britain has a real opportunity to capitalise on Europe’s investment drive. But reforms need to make it easier for buyers too – not just open more assets for sale.  

Yield breakup? 

UK and US government bond yields are tightly correlated. To understand why, it helps to look at historical bond trends: global yields used to be high and fairly independent, but came down together after 1997, thanks to the freer movement of global capital and the advent of independent but often coordinated central banks. Yields dispersed somewhat after the 2008 financial crisis – and again post-pandemic – partly due to regional factors (e.g. the euro crisis) but largely due to slower economic growth in Europe and the UK, compared to the US.  

There are a couple interesting trends to note here. First, Japan and China don’t follow the same pattern as the rest of the world, due to their different growth profiles. Second, UK yields used to be more tightly linked to Europe than the US – but this changed after the Liz Truss bond market crash.  

Does the current UK-US correlation mean UK growth and inflation is more similar to the US than Europe? Perhaps on the inflation front, as we do have a tighter labour market than the EU, post-Brexit. But the growth comparison makes less sense: the US economy has raced ahead, but Britain has been sluggish. The relationship makes even less sense when you consider that Trump’s current fiscal expansion (from tax cuts) is starkly different from Downing Street’s fairly stringent fiscal rules.  

It’s possible that US and UK yields are connected because the traders of those bonds are themselves linked. If so, the relationship seems fragile, especially if Trump keeps breaking trade links. Currency movements – like sterling’s gains against the dollar this year – could be the thing to break it, as that would mean capital flows into UK bonds and out of US bonds. Indeed, further declines in the world’s reserve currency – coupled with growing government debts – could see yields break apart globally. It will pay for investors to stay alert to the risks and opportunities this changing landscape presents of the coming months.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

23rd June 2025

Team No Comments

Brooks Macdonald – Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their discussions on the ongoing conflict in the Middle East and interest rates. Received this morning 20/06/2025.

What has happened

Global equity indices were lower on Thursday, as a US decision whether to attack Iran appeared to remain on a knife-edge. Later, with US markets shut for “Juneteenth” holiday and after European markets had closed for the day, US President Trump gave a message effectively saying he was giving Iran up to 2 weeks to negotiate a deal aimed at limiting Iranian nuclear capabilities. With Middle East escalation paused for now, oil prices are down overnight while most Asian equity markets are up this morning.

Middle East

White House press secretary Karoline Leavitt last night delivered a dictated message from Trump, saying that “based on the fact that there’s a substantial chance of negotiations that may or may not take place with Iran in the near future, I will make my decision whether or not to go within the next two weeks.” Meanwhile, the US has continued to build up its military presence in and around the Middle East – the US Navy’s newest and most advanced aircraft carrier, the USS Gerald Ford has this week been ordered to deploy to the Mediterranean Sea and is set to become the third US carrier strike group to be positioned in or near the Middle East.

UK interest rates on hold

While UK interest rates yesterday stayed at 4.25% as expected, the Bank of England’s 9-member Monetary Policy Committee (MPC) saw a surprise dovish split: 3 MPC members voted for a 25 basis point cut, 1 more than expected, and versus 6 MPC members who voted for no change. In addition, Bank minutes released yesterday echoed the context for more possible cuts later this year, citing weak economic growth and clearer signs of loosening in the UK labour market. Looking forwards, the Bank continued to see the “gradual and careful” withdrawal of monetary policy restraint remaining “appropriate”.

What does Brooks Macdonald think

With the surprise dovish tilt to the Bank of England’s latest meeting this week, that has fed into the UK interest rate outlook. Looking at market expectations yesterday afternoon, based on derivative option pricing, that pointed to 50.1 basis points (bps) of cumulative interest rate cuts by the Bank of England’s December meeting later this year, with a first 25 bps cut fully-priced-in for the Bank’s September meeting.

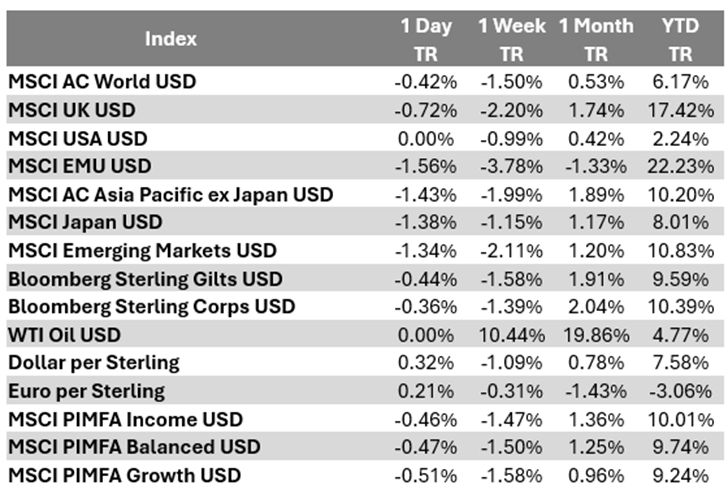
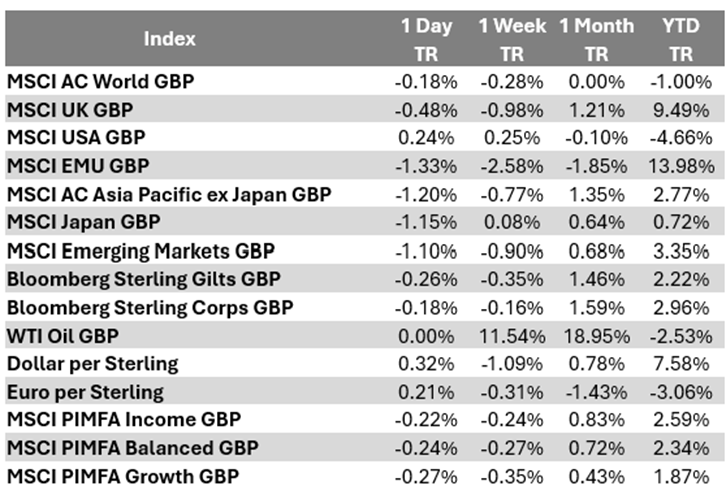
Bloomberg as at 20/06/2025. TR denotes Net Total Return.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

20/06/2025

Team No Comments

Evelyn Partners Update – June Bank of England MPC decision

Please see below, Evelyn Partners thoughts on today’s Bank of England interest rate decision:

What happened?

Coming hot on the heels of the Federal Open Market Committee leaving US interest rates unchanged last night, the Bank of England (BoE) followed suit with a widely expected ‘hold’ in their midday release keeping their target rate at 4.25%.  This is a continuation of the one-cut-every-other-meeting approach since the current easing cycle began last August.

The vote was split 6-3, versus the 7-2 shown by the Bloomberg survey, with Dave Ramsden joining external members Swati Dhingra and Alan Taylor on the dovish side, preferring to reduce the Bank Rate by 25 basis points, to 4.00%.

The meeting did not come with updated forecasts, but guidance recognised ‘there remain two-sided risks to inflation’ with the ‘gradual and careful approach to the further withdrawal of monetary restraint’ reiterated.

What does it mean?

The focus of Bank watchers was if the news flow had been enough to sway members in the dovish direction… and clearly it had.

Since the May Monetary Policy Report, the Monetary Policy Committee (MPC) has seen two rounds of GDP, inflation, and labour market releases.  Overall, the economy has proved to be more resilient than the MPC expected with the latest data coming in with quarter-over-quarter growth at 0.7% (versus 0.6%), inflation slightly hotter at 3.4% (versus 3.3%) but with the labour market softening quicker than expected.  Unemployment rose to 4.6% in the three months to April (ahead of the BoE’s 2Q25 projection) and HMRC’s latest PAYE Payrolled Employees Monthly change came in at -109k (vs 20k surveyed).  Wage momentum, while still elevated with average weekly earnings 3-month/year-over-year at 5.3%, showed progress coming in below the anticipated 5.5%.

Outside of the domestic data releases, marginal progress has been made on the trade front with the ‘UK-US Economic Prosperity Deal’, the ‘UK-India Trade Deal’ and the new UK-EU deal all small positives for the UK’s growth outlook.  However, economic policy uncertainty remains elevated globally with geopolitical developments in the Middle East further muddying the outlook.

Bottom Line

The BoE held interest rates steady at 4.25%.  The UK swap market is pricing in an 85% chance of a cut at its next meeting in August and one further cut through to the end of 2025.  Given Ramsden’s reputation as a bellwether on the committee, it will be interesting to see if weakening labour market data encourages more committee members to start look through inflation concerns, resulting in the pace of quarterly rate cuts picking up.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Andrew Lloyd

19/06/2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below, todays Daily Investment Bulletin from Brooks Macdonald covering their thoughts on markets and the ongoing Geopolitical Issues:

What has happened

Yesterday saw global equity markets seesaw as US President Trump left everyone guessing whether the US would join Israeli attacks on Iran. Elsewhere, the US Federal Reserve left rates unchanged as expected – the Bank of England announces its latest interest rate decision (also no change expected) at 12 o’clock midday today UK time. US markets are shut today (“Juneteenth” public holiday), so expect trading volumes to be lighter elsewhere.

Middle East

While Trump said yesterday that Iran had reached out about the possibility of negotiations, he said that he hadn’t yet made his mind up about US military strikes. Yesterday the Wall Street Journal reported that Trump had privately approved of attack plans but had held off on the final order. Overnight, Bloomberg has reported that US officials are preparing for a possible US strike on Iran in the coming days.

US Federal Reserve

As widely expected, the US Federal Reserve (Fed) left interest rates unchanged yesterday for the fourth meeting in a row, at a range of 4.25-4.5%. As for Fed members’ rate expectations ahead, the median estimate for -50bps of cumulative cuts by calendar 2025 year end was also unchanged. There was a small hawkish shift however – more Fed members see no cuts at all this year, while the median rate expectation was nudged up for 2026 and 2027.

What does Brooks Macdonald think

Reflecting tariff risks, Fed members nudged up inflation expectations for 2025 and 2026, while economic growth was nudged down. Feeding into our more cautious outlook recently, the risk is that the tariff impact eventually shows up in the economic data, albeit with a lag. As Fed Chair Powell said yesterday, “ultimately, the cost of the tariff has to be paid, and some of it will fall on the end consumer … we know that because that’s what businesses say, that’s what the data say from the past.”

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

19th June 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 17/06/2025.

Markets calm despite conflict in the Middle East

Despite the recent conflict in the Middle East there has been a surprising lack of market movement.

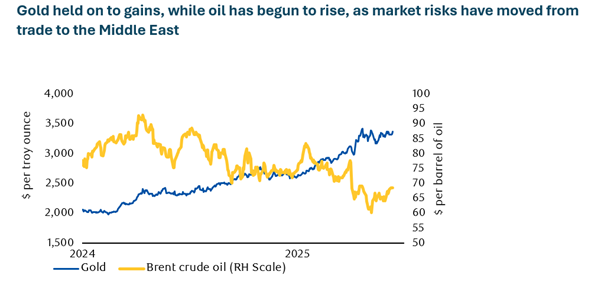
Gold prices, Oil prices

Source: LSEG Datastream

On 12 June, 2025, Israel launched a series of airstrikes targeting Iranian nuclear and ballistic missile facilities, scientists, and senior military personnel, marking a significant escalation in the long-standing conflict between the two nations. The attacks reportedly damaged the Isfahan and Natanz uranium enrichment facilities, whilst also striking the Fordow but with limited success.

Iranian state media confirmed the killing of the Commander of Iran’s Islamic Revolutionary Guard Corps (IRGC), Hossein Salami, however it is the attacks on the nuclear facilities which is of greatest strategic importance as the actions taken so far would slow but not prevent Iran’s progress in enriching uranium to the grade required to develop a nuclear weapon.

In recent months, Iran has made rapid advances in its uranium enrichment activities, with the International Atomic Energy Agency (IAEA) finding Iran in breach of non-proliferation obligations. Israel’s Prime Minister, Benjamin Netanyahu, stated that Iran has enough enriched uranium for nine atomic bombs and insisted that the preventive action was necessary to avert a full-scale nuclear crisis. Israel has indicated that ending that progress is its objective, and it has a strategy to achieve it over a number of weeks.

The situation is volatile, and there is a risk of a wider conflict involving other regional actors. For now, Israel and Iran have been exchanging fire with Israel expanding targets to include energy infrastructure. A particular focus is on the U.S., whose involvement would mark a clear escalation but is assumed to be required in order to do lasting damage to the Iranian nuclear programme. President Trump’s comments on the subject have been vague and laced with implicit threat but so far, the U.S. official line is that it is not a party to this conflict.

Possible options for an imperilled Iran would be disruption of traffic through the narrow strait of Hormuz, however the U.S. Fifth Fleet’s presence in Bahrain makes it unlikely that this can be achieved for an extended period.

The market reaction has been fairly benign so far. That reflects hopes that the conflict can be contained and an assumption that we won’t see the kind of global energy supply interruptions which occurred in the 1970s. 

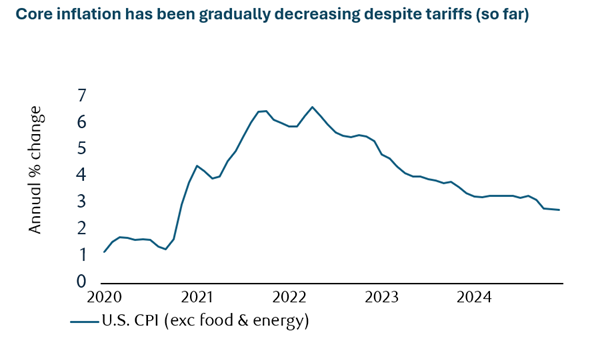
A line graph with numbers and text

AI-generated content may be incorrect.

Source: LSEG Datastream

The U.S. Consumer Price Index (CPI) report for May showed a 0.1% monthly increase in core inflation, below expectations for the fourth consecutive month. Despite the current lack of impact from tariffs on inflation, it’s likely that the effects of the tariff-driven boost to U.S. inflation will be felt soon. The effective average tariff rate is currently at 15%, significantly higher than the 2.4% rate prior to Trump’s inauguration, and is expected to add around 1.5% to U.S. inflation. While some categories, such as appliances and toys, saw a notable pickup in prices, others, including apparel and footwear, experienced declines.

The report also highlighted the impact of tariffs on businesses, with some being forced to absorb the higher costs themselves, rather than passing them on to consumers. This is in line with Trump’s stated desire for businesses to eat the tariffs, rather than increasing prices for consumers. However, with the huge surge in imports prior to the tariff increases, businesses may be able to sell their existing inventory without raising prices, which could delay the impact of tariffs on inflation. Nevertheless, with the average effective tariff rate expected to remain high, it’s likely that goods prices will start to rise due to Trump’s tariffs in the near future.

The CPI report also provided insight into the state of the labour market and its impact on inflation. Core services ex-shelter inflation was weak, rising less than 0.1% monthly, which suggests that there isn’t much labour market-driven inflation. This, combined with the decline in airfares and the drop in inbound U.S. tourism, may indicate caution among American consumers.

Shelter inflation also decelerated further, with primary residence rental prices hitting a new cycle low, and measures of new lease inflation signalling that shelter inflation will remain subdued in the months ahead.

The implications of the CPI report for Federal Reserve (Fed) policy are significant. While the Fed has made progress in getting inflation lower, with the six-month annualised rate of change in the core CPI near its cycle low, the risks of cutting rates too early and losing credibility are high. It’s unlikely to cut again until there is a meaningful weakening in the labour market and/or more clarity around the impact of tariffs on inflation. With trade uncertainty still high and the potential for tariffs to boost inflation, the Fed will likely wait for more clarity before making its next move.

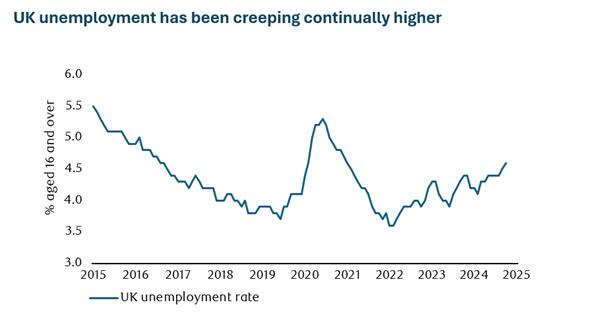
UK Unemployment rate

The UK economy is at a crossroads, with recent data releases painting a mixed picture of its health. On one hand, the labour market appears to be slowing down, with payroll employee numbers falling by 109,000 in May, the worst first estimate of payrolls in two years. This decline, combined with a rise in the unemployment rate to 4.6%, gives the Bank of England’s Monetary Policy Committee (MPC) license to cut interest rates again. They’ll probably stay on hold at next week’s meeting, but lower interest rates in August seem likely.

However, other indicators suggest that the labour market is not as weak as the payroll data suggests. The more dated, but less volatile, Labour Force Survey (LFS) showed a healthy increase in employment in April and business surveys have also stabilised or improved since March. The redundancy rate has fallen to its lowest level since before October’s budget.

The Recruitment and Employment Confederation (REC) survey indicates that the worst of the jobs slowdown may be over. The permanent staff placements index is still at an eight-month high, excluding April’s reading, and the temporary staff placements balance rising to a six-month high.

The recent spending review has also shed light on the UK’s fiscal situation, with the government maintaining its commitment to increase overall day-to-day resource spending by 1.2% in real terms on average between 2025/26 and 2028/29. However, this increase is largely driven by a rise in healthcare spending, which will absorb most of the increase in the total spending envelope. The government has announced plans to increase defence spending to 2.6% of Gross Domestic Product (GDP) by April 2027, which will add to the fiscal burden.  So, we’re back in a situation where unprotected departments will be asked to make cuts in real terms.

In the housing market, the recent stamp duty hike has caused a temporary slowdown, but overall, the market seems stable. After a strong start to the year, momentum in the housing market has stalled a little. However, the RICS survey showed an improvement in forward-looking indicators, such as price expectations and sales activity, and the sales-to-stocks ratio, although still low, suggests that there’s little overhang of unsold property that would weigh on prices.

The UK GDP data for April suggested that the economy declined, partly due to the weakness of trade and the associated efforts of companies to get ahead of President Trump’s tariffs, but the domestic economy was also sluggish. Overall, the second quarter is on course for a small decline and over the course of the year growth will likely be just about 1%.

So, recession still seems unlikely, but with domestic businesses cutting spending to compensate for increased costs due to tax rises and the government quite constrained in terms of its spending, there seems adequate reason to cut interest rates.

In the UK, government spending is constrained, and interest rates are falling, whereas in the U.S., bond issuance continues at pace and the economy is holding up surprisingly well, all of which suggests that the outlook for UK government bonds is better than that for the U.S. treasuries. 

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

18/06/2025

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below article received from Brooks Macdonald this morning, which provides  a market update for your perusal.

What has happened

A degree of relative calm returned to markets yesterday, as fears of a worst-case Middle East conflagration eased. While Iran and Israel continue to trade attacks, there is a growing view that the latest conflict might yet be contained. Avoiding further escalation, Israel has not targeted Iranian oil production while Iran has not targeted US people or assets in the region – and crucially for the oil price, Iran has as yet shown no interest in blockading the Strait of Hormuz through which close to 30% of the world’s seaborne oil trade goes through.

Signs of Middle East de-escalation?

Rather than ratcheting up, it seems the conflict might even be de-escalating behind the public rhetoric. The Wall Street Journal said yesterday that Iran was signalling it wanted to end hostilities and restart nuclear talks, citing unnamed Middle Eastern and European sources, while a similar report by Reuters said that Iran conveyed that message through Qatar, Saudi Arabia and Oman. Separately, Iranian foreign minister Abbas Araghchi yesterday said that “the Islamic Republic of Iran has never left the negotiating table”. According to US news website Axios, there may be meeting this week between US Middle East envoy Steve Witkoff and the Iranian foreign minister to discuss a nuclear deal and an end to the Israel-Iran conflict.

Markets shift back to risk-on

Global equity markets rose, while US government bond, gold and oil prices all fell back yesterday. The US S&P500 equity index finished yesterday up +0.94%, recouping most of Friday’s -1.13% decline, while the pan-European STOXX600 equity index was up +0.36%, having dropped by -0.89% on Friday. Overnight in Asian equity markets, the Japanese Nikkei225 equity index has closed up +0.59% (all equity indices in local currency price return terms).

What does Brooks Macdonald think

Overnight the Bank of Japan has left interest rates unchanged and announced it is looking the slow the rate at which it reduces its bond purchases next year, both decisions widely expected. On the latter, the Bank is presumably hoping to take some of the heat off Japanese government bond yields which have risen this year. This is all market positive as it reduces the risk of ‘something breaking’, avoiding a redux of the market hiatus last August when the Bank hiked rates unexpectedly.

Please check in again with us soon for further relevant content and market news.

Chloe

17/06/2025

Team No Comments

Tatton Investment Management – The Monday Digest

Please see below, an article from Tatton Investment Management analysing the key factors currently affecting global investment markets. Received this morning – 16/06/2025:

Markets calm but not comfortable


Markets’ reaction to the war that broke out Friday, after Israel’s strike on Iran, has been mild. Global stocks have fallen slightly, while gold prices and the dollar have edged up. Oil prices climbed the most – and their future inflationary impact is probably why bonds fell as yields rebounded. Investors have become a little desensitised to geopolitical mayhem. You might call that resilience; you might call it resignation. In any case, we have said for a while that investors (particularly in the US) might be overly optimistic. 

On the UK spending review, it was notable that Chancellor Reeves stuck to her fiscal rules, even though she probably would have got away with tweaking them. Bond yields fell, sterling strengthened and the FTSE 100 gained in response – a reaction any party’s chancellor would welcome. Despite weak growth, the UK has an opportunity to take advantage of US capital outflows – but our markets have a trading liquidity problem, which we’ll write more on soon. 

US stocks held up decently, despite weaker earnings and lower than expected inflation. Trump will take that as tariff vindication, but really it suggests economic weakness. It means companies will struggle with higher input costs. Stocks can still grow in that sluggish environment (they did before the pandemic) but we shouldn’t expect the stellar returns of the last few years. 

The other concern is that slower profit growth means higher equity valuations – which already look expensive compared to higher bond yields. There are reasons to doubt the bond valuation effect: there are more bonds than there used to be (see below) and they’re not easily substitutable for stocks. But eventually, higher bond yields make equities more vulnerable, either because companies need to raise capital (see Eutelsat) or sharply higher yields make everyone afraid. High yields are a big problem for equities if investors expect a recession. That’s a risk, but hasn’t happened yet. 

Governments borrow more but could pay less


Markets are worried about government debt sustainability. We call government bonds ‘risk free’ because they can theoretically print money to pay back the loan (assuming they borrow in their own currency) but they are still risky by the usual understanding. We measure these risks in two ways: the term premium (long versus short-term yields) and swap spread (government yields minus central bank guaranteed interbank lending). Both measures have increased across most major economies, for a simple reason: government debt has grown much faster than private debt in the last decade. 

That means governments are demanding more capital than companies. Or inversely, the private sector is deleveraging, relatively speaking, with corporates eating less of the capital pie. Corporates have also been issuing less equity for an unusually long time – despite the fact investors are happy to buy that equity. There are a couple of ways of looking at this. A Keynesian would say governments are making up for the shortfall in private sector credit demand; a supply-side economist would say governments are crowding out private investment by making borrowing rates too high to be profitable. The truth is probably somewhere in between. 

Even a slight crowding out of investment could constrain long-term growth – depending on your beliefs about the efficiency of public versus private spending. Japan is arguably a cautionary tale here: its debt-to-GDP ratio is higher than any other large economy, plausibly one of the factors behind its decades of stagnation. China might be on that same path, with massive government debt expansion in the last decade and a weak private sector to show for it. 

The interesting thing about these examples is that they show how higher government debt can actually mean lower yields – by lowering growth. That’s the opposite of what people usually worry about when they worry about growing government debt.

China exporting disinflation to Europe


Many expect US tariffs on China will mean Chinese exports being rerouted to Europe – and hence lower European goods inflation. This isn’t happening yet, but Americans’ rush to buy ahead of tariffs is distorting the data. Chinese exporters have room to grow their European consumer share, but JPMorgan analysts point out that changing market shares don’t affect official inflation statistics in the short-term. Europeans buying more Huawei and less Apple only lowers inflation if Huawei prices fall. JPM see the bigger short-term impact coming from the euro’s 7% appreciation against the renminbi. But even this currency impact is relatively small.

Changing market shares eventually impact inflation by changing the weightings of different goods. That could take a while, though, and it would require a consistent shift towards buying Chinese. This could be difficult, because European politicians are already worried about Chinese ‘dumping’ of electric cars. There’s nothing sinister about China selling cheap goods after overproducing, but ‘dumping’ is a politically persuasive story. German carmakers and British steel producers have already lobbied for import controls on this basis, and politicians will get more sympathetic the more China exports. 

That’s good news for Washington, which wants European anti-China tariffs to be included in any US-EU deal (and successfully put them in the UK-US deal). European leaders have been reluctant to go along with the US trade war on China in the past, but the difference now is that domestic European pressures could push them in the same direction. 

We think it’s likely, therefore, that the EU will put up some trade barriers with China – albeit not the 145% tariffs Trump likes to post on social media. Potential EU tariffs will probably be more commensurate with the scale of Chinese ‘dumping’, which is likely why bond markets aren’t expecting significant European disinflation.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

16th June 2025

Team No Comments

EPIC Investment Partners – The Daily Update: The Jobs Report Paradox: What a 696,000 Employment Plunge Means for the FED

Please see the below article from EPIC Investment Partners detailing their discussions on a tightening Labour Market. Received this morning 13/06/2025.

Over the past few weeks, we have focussed closely on the jobs market. Why so much attention? With inflation moving towards the Federal Reserve’s target, any further easing will increasingly depend on clear signs of labour market weakness. While recent payroll data and a stable unemployment rate appear reassuring, the underlying reality is notably different.

The Bureau of Labor Statistics (BLS) employment report for May 2025 illustrates why headline figures can be misleading. The report indicated a modest payroll gain of 139,000 jobs; however, a closer look reveals a much weaker picture. Strikingly, total employment measured by the Household Survey fell sharply by 696,000. This is not simply a statistical anomaly—it may signal a hidden deterioration in the labour market.

Each month, the BLS produces two employment measures from separate surveys. The Establishment Survey provides the headline payroll figure, counting each job on employer payrolls separately—even multiple jobs held by one person. This approach can inflate perceptions of strength. In contrast, the Household Survey directly interviews individuals, counting each person as employed only once, while including self-employed and agricultural workers who are not captured by payroll figures.

In May, payroll jobs rose slightly by 139,000 to 159.6 million, yet the Household Survey reported total employment fell by 696,000, dropping to 163.3 million. This divergence is largely because around 625,000 people exited the labour force entirely—they were not merely unemployed; they stopped looking for work altogether. This coincided with an additional 813,000 people categorised as “not in the labour force,” including retirees, students, those with family responsibilities, and discouraged jobseekers.

As a result, the labour force participation rate fell 0.2 percentage points to 62.4%. When the working-age population grows (as it did by 188,000 in May), yet fewer people actively engage in employment, deeper structural issues emerge. The headline unemployment rate remaining steady at 4.2% masks this underlying weakness, as it excludes individuals who have stopped actively seeking employment.

Moreover, the strength in payroll data may be overstated by the BLS’s Birth/Death Model, which estimates jobs created or lost by businesses not yet captured in surveys. This model relies on historical data, potentially problematic in a rapidly shifting economy. Recent downward revisions (totalling 95,000 fewer jobs in March and April) reinforce this concern, indicating that payroll growth may have been previously overstated, making the current divergence even more significant.

Investors should not rely solely on headline payroll numbers. May’s employment report clearly demonstrates that headline strength can mask genuine underlying weakness. Declining total employment and increased workforce exits point to structural challenges potentially limiting future economic growth and productivity. Investors should therefore adopt a cautious perspective, acknowledging the employment landscape may be weaker and more vulnerable than initial headlines suggest.

For the Federal Reserve, which targets maximum employment and stable 2% inflation, these nuances are critical. While typically prioritising payroll figures, the Fed will also closely monitor labour force participation and overall employment levels. If underlying employment continues to weaken, this could prompt policymakers to adopt a more accommodative stance sooner rather than later. So, despite the positive headlines citing payroll growth, the Fed may in fact be much closer to resuming its easing cycle than many currently assume.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

13/06/2025