Team No Comments

Jupiter Insight: Will we see a more regenerative form of capitalism?

Please see the below insight from Jupiter Asset Management’s Environment & Sustainability Fund Manager, Abbie Llewellyn-Waters, which we received earlier this week:

It has become clear that we are at a precipice of change. The status quo has been shattered and there is an opportunity to reconsider a new normal. This applies to capital markets as well and underpins the need to deliver a more regenerative approach to investing and how we rebuild our economies to become structurally more sustainable.

Despite the easing of lockdowns throughout the world, there remains speculation about whether the old demand trends for fast or luxury fashion, as well as eating, drinking and travel, will hold. For example, only 9% of people polled by YouGov in the UK wanted things to return to exactly how they were before the crisis.

From our perspective, we see a great opportunity in companies that are positioned to transition to a more regenerative form of capitalism – where companies that treat workers well, don’t exploit vulnerable communities in their supply chain, that take proactive action in a crisis, and that limit their impact on the environment, will be more attractive to investors.

We anticipate that asset prices will increasingly reflect this. In fact, Harvard published a white paper in May  that looked at parallels between US share prices and salient corporate social responses to Covid-19 (such as sick pay policies, appropriateness of government aid acceptance, dividend cuts), and concluded that there was a clear alpha correlation between the two.

Sustainable investment themes have accelerated

Sustainable themes have accelerated as a result of the Covid-19 crisis. Firstly, momentum for environmental policy has gathered pace, despite the fragile state of the global economy. Policymakers have been quick to draw the link between the coronavirus and the environment – like viruses, greenhouse gases care little for borders. The debate around carbon policy, and specifically carbon tax, has notably speeded up. The recent eye watering impairments within the oil sector brings further caution to the broader carbon capital at risk in the system.

There has also been important research quantifying pollution reduction, one of the few positives from this crisis. There has been a staggering drop in emissions through the crisis, at a level that is obviously unsustainable but has at least demonstrated the efficacy of urgent policy response. As a result of the global measures to combat Covid-19, the IEA (International Energy Agency) expects global CO2 emissions this year to decrease to levels of 10 years ago. This is significant and could support the case for a more agile economic culture that includes more working from home. It is effectively an ‘investment-free’ solution to help deliver the legal commitments of the Paris Agreement.

There also continues to be strong momentum in human capital management within the sustainable companies that we focus on, with an increasing correlation between fair treatment of workers and share price returns.

Finally, another interesting new theme is sustainable supply chain management. For years, efficiency has been the overriding aim in supply chains – “just enough, just in time”. Covid-19 has shifted the focus to security. While this has implications for working capital, it also offers new revenue opportunities. For example, infectious diseases have previously been mischaracterised as an issue mainly for developing markets. But R&D investment into non-Covid infectious diseases in developed markets is increasing, which has the potential to create entirely new revenue streams.

All in all, we expect the journey ahead to be much more complex than the Q2 market rally might suggest. As active long-term investors, our focus remains finding high quality companies that are leading the transition to a more sustainable world.

As we have highlighted over the past few months, sustainable investment themes and ESG are being talked about now in the press more and more by the regulator, fund managers and investors.

If you haven’t already caught up with these blogs, please see the below links which will take you to our 3-part blog series, ‘An Introduction to ESG’ which we posted over the past month for a basic introduction to what ESG is, how its measured and what we at People and Business are doing to make sure we are moving in the right direction with regards to sustainable investment themes.

Part 1 – https://www.pandbifa.co.uk/what-is-esg-an-introduction-part-1/
Part 2 – https://www.pandbifa.co.uk/what-is-esg-an-introduction-part-2/
Part 3 – https://www.pandbifa.co.uk/what-is-esg-an-introduction-part-3/

Andrew Lloyd

29/07/2020
Team No Comments

PruFund Series E – Monthly Review

Please see below the monthly update for July, which was published by Prudential yesterday for their PruFund Series E funds only, which details no Unit Price Adjustments (UPA) will be applied:

There are no Unit Price Adjustments (UPAs) for the Series E PruFund range of funds at this month’s PruFund Investment Date.

On the monthly PruFund Investment Date, a UPA is applied if the unsmoothed price is:

  • 4%, or more, higher than the smoothed price, for our PruFund Cautious, PruFund Risk Managed 1 or PruFund Risk Managed 2 funds, or
  • 5%, or more, higher than the smoothed price for our PruFund Growth, PruFund Risk Managed 3, PruFund Risk Managed 4 of PruFund Risk Managed 5 funds

The next quarterly review of the entire PruFund range of funds, which will include a review of Prudential’s long-term growth expectations and subsequently the funds underlying Expected Growth Rates (EGRs) will take place on the 25th August 2020.

In exceptional circumstances, as was seen in March, Prudential can make Unit Price Adjustments outside of their normal review dates and these adjustments can be either upwards or downwards.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

28/07/2020

Team No Comments

Blackfinch – Monday Market Update

Please see the below market update received from Blackfinch Asset Management earlier today:

UK COMMENTARY

  • Tensions between the UK and China continue to rise over Huawei’s ban from the UK’s 5G network and the suspension of the Hong Kong extradition treaty.
  • The IHS Markit Household Finance Index (HFI) for July rose to 41.5 from 40.7 in June. However, 31% of the survey’s respondents said their jobs were less secure than before the pandemic hit the UK.
  • Data from Rightmove suggests that the average price of a house in the UK has risen to £320,265, an increase of 2.4% since March.
  • Boris Johnson’s self-imposed July Brexit deadline looms, with the potential for an agreement seeming unlikely.
  • The CBI Industrial Trends Survey for July showed the total orders balance recovered to -46 from -58 in June. Economists had, however, expected a stronger recovery to -38.
  • Retail sales show a 13.9% month-on-month increase in June, following on from May’s 12.9% increase.
  • The IHS Markit/CIPS Flash UK Composite Purchasing Managers Index (PMI) for July rose to 57.1 from June’s 47.7.

US COMMENTARY

  • COVID-19 case numbers continue to rise, however weekly numbers to the 20th July show that the rate of increase has slowed in 36 states over the previous week.
  • US government orders the closure of the Chinese consulate in Houston, raising further questions around ongoing tensions between the countries. China retaliates by ordering the closure of the US consulate in Chengdu.
  • Donald Trump admits that the COVID-19 pandemic is likely to get worse before it improves.
  • US home sales show their biggest monthly rise on record, increasing by 21% in June, albeit the recovery was slightly lower than expected.
  • US jobless claims show their first increase since late March, rising by 109,000 to 1.42mln.
  • US Secretary of State Mike Pompeo accuses China of being “increasingly authoritarian at home, and more aggressive in its hostility to freedom everywhere else”.

EUROPE COMMENTARY

  • European leaders reach agreement on a €750bn pandemic recovery fund consisting of both loans and grants.

COVID-19 COMMENTARY

  • UK based small-cap drug developer Synairgen has potentially discovered a life-saving treatment for acute cases of COVID-19. Results from a recent trial ‘could signal a major breakthrough in the treatment of hospitalised patients’.
  • The vaccine being developed by Oxford University and Astrazeneca continues to provide positive and safe results in trials.

This update provides you with a short summary of events from around the world over the past week.

Please check back for our regular market updates from a range of providers.

Andrew Lloyd

27th July 2020

Team No Comments

Cover Magazine – Health Insurance Scams up 15% During Pandemic

Please see below an article uploaded by Cover Magazine last week and received on 24/07/2020, detailing scammers efforts to exploit people during the ongoing Coronavirus pandemic:

Research by Aviva has shown that unscrupulous tactics and fraudulent communications related to financial services products have risen as a result of coronavirus.

According to the Aviva Fraud Report, suspicious emails, texts and phone calls related to health insurance have increased by 15% since the pandemic – up from 11% pre-Covid (1 January 2019 – 29 February 2020) to 27% during Covid (1 March – 15 June 2020).

For life insurance, the percentage of people who reported receiving suspicious communication were up 10% – from 14% to 24% – during this period.

This compares to a 7% rise in car insurance, 3% rise in pensions and 2% increase in annuities related scams.

According to the report, a typical health and life insurance scam involves a cold call telling consumers “It’s time to review your policy”. The fraudsters will claim they’re from a reputable insurance company or that they’ve been asked to do this by the regulators – all in a bid to gain trust. They may offer lower premiums but what they don’t mention is that the lower premium also means reduced cover – often leaving the consumer with a worthless policy.

The survey of 2009 Brits also found one in five (22%) reported having been targeted by suspicious communications which mentioned coronavirus – which equates to 11.7 million people in the UK.

Almost half (46%) said they didn’t report these suspicious communications, even though they suspected it was a financial scam. The most common (41%) reason given was because they didn’t know who to report the communication to.

Peter Hazlewood, group financial crime risk director at Aviva, said: “While the types of financial scams are generally the same as those before the pandemic, fraudsters are exploiting the pandemic to take advantage of people when they are at their most vulnerable. They are using coronavirus as a pretext to lure potential victims. The scams range from attempts to sell people unsuitable insurance to, at worst, stealing their entire retirement savings. The impact on victims is not just financial either, it has a detrimental effect on people’s mental wellbeing too.”

The research found that one in 12 (8%) of those surveyed have been the victim of a financial scam which related to coronavirus. Of those, 41% said being the victim of a scam negatively affected their mental health.

In June this year, Action Fraud reported £5million having been lost to fraud since February – a figure likely to be far higher due to a lack of reporting. Hazlewood added: “It’s clear from our research that fraudsters will use whatever tactics necessary to get hold of people’s hard-earned money. If you’re interested in getting a lower premium or taking out a new insurance policy, do a bit of research yourself – and don’t be forced into anything by unexpected phone calls from strangers. If you’re not sure whether a financial services company or a communication is legitimate, report it – to us, Action Fraud or the Police. And, while this may feel like an unsettling time for many, the advice we’d give to people is not to panic. When it comes to investments, decisions made in haste and under stress are rarely good ones.”

It is important to remain vigilant with your data and if you have received a communication that you are unsure of, please contact your provider or financial adviser for further details.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

27/07/2020

Team No Comments

AJ Bell Youinvest – How to beat the potential capital gains tax hike

Please see article below from AJ Bell Youinvest on the potential capital gains tax hike – received 23/07/2020.

How to beat the potential capital gains tax hike

The tax system could soon change to help the Government raise money to cover some of its Covid-19 support efforts

Thursday 23 Jul 2020 Author: Laura Suter

Chancellor Rishi Sunak has signalled he is looking to shake up how capital gains tax (CGT) is paid, which could leave taxpayers with a higher tax bill.

Sunak has asked the Office for Tax Simplification to look at how CGT is structured, whether the tax can be simplified and if more help can be given to individuals in the administration of the tax.

While he doesn’t explicitly say so, many people assume that the timing of the review indicates the Chancellor could be looking at changing the tax as one way to raise money in order to pay for the Government’s cost of the current Covid-19 pandemic.

The Government has spent a large amount of money on helping the country to stay afloat during the current crisis and everyone expects this year’s Autumn Statement to reveal how it plans to pay for this support. While additional Government borrowing is one solution, tax hikes may also be on the agenda.

The review will look at the differences between the CGT system and the income tax system, how private residence relief works and the reliefs and exemptions on offer.

PUBLIC OPINION

The move might not be entirely unpopular with the British public. Research from AJ Bell showed that two thirds of people think we have a responsibility to contribute towards the cost of the recent measures.

When questioned, the most popular tax to increase was either dividend taxes or CGT, with 37% of respondents thinking it was acceptable to raise those taxes. This was followed by a third of people who said income tax and 22% who said inheritance tax.

WHAT COULD CHANGE?

Changing tax rates: One area that may change is the rates charged on CGT (see below for current rates). There is a big difference between the rates charged for income tax and CGT.

An additional rate taxpayer, for example, would pay 45% tax on any income they make over their personal allowance, but only 20% on their investment gains. One thing the Government could do is bring these rates in line with each other.

Cutting allowances: In a similar vein to above, individuals have a tax-free rate for their income and for their capital gains – currently £12,500 before income tax kicks in and £12,300 for CGT.

These allowances could be brought together, so someone only has one lot of £12,500, for example, before they incur tax. This would bring lots more people into the bracket of having to pay CGT.

Scrapping main home relief: At the moment you pay no CGT on the gains you make on your main home – in part this is offset by the fact that you have to pay stamp duty tax when you buy a new home.

However, one suggestion has been that the Government could remove or limit this relief. This would mean lots of people who had made a gain on their property would face a large tax bill, but in turn could raise a lot of money for the Government. It would be an odd move to make just as the Government has put in other measures to try to get the housing market moving.

HOW CAN YOU BEAT THE HIKE?

If you’re worried about any rise in the tax rates or cuts to allowances, you could think about locking in gains now. Remember, anything in an ISA or SIPP is exempt from CGT, so you don’t need to worry about those gains. But outside of these tax wrappers your investments could face CGT.

You can choose to cash in gains up to your annual allowance this year, in order to lock in some gains and make use of that allowance. If your gains are higher than your allowance, you could transfer assets to your spouse so they can use their allowance.

Transfers to spouses are exempt from CGT, but if they then sell the assets they’ll face CGT on any profit between the price you bought the investment and the price at which they are selling. If you transfer assets to them, they can then cash in the gains and use their annual allowance to avoid a large tax bill.

For example, let’s assume Mrs Smith has investments that have a £25,000 gain on them, and she is a higher-rate taxpayer. If she sold those investments in one tax year, she’d use her £12,300 allowance but still pay tax at 20% on the remaining £12,700 gain – which would equal a £2,540 tax bill.

However, if she transferred the investments with the remaining £12,700 gain on them to her husband, who is a basic-rate taxpayer, he could use his £12,300 tax free allowance – leaving just £400 of gains to pay tax on. At his lower 10% CGT rate this would mean a tax bill of just £40 – saving £2,500.

Another option is cashing in the gain and rebuying the asset in your ISA, assuming you have some of your annual ISA allowance remaining. This is called ‘bed and ISA’ and means you can use your annual allowance, keep hold of the investment and future gains will be exempt from CGT.

HOW DOES CAPITAL GAINS TAX WORK?

You pay capital gains tax on any profit you make when you sell an asset that has risen in value.

Some assets are tax free, including your main home. Everyone gets a tax-free allowance each year, which is currently £12,300 per person.

Beyond this level any gains are taxed depending on your income tax rate, so basic-rate taxpayers pay 10% (or 18% on property) while higher and additional-rate payers pay 20% (or 28% on property).

If you give money to your spouse you don’t have to pay CGT, nor on assets including land, property or shares you gift to charity. If you make a loss on an asset you can offset that against any gains you make on other assets in order to reduce your tax bill – and you can carry forward losses into future years.

A useful article covering the potential changes to capital gains tax and a breakdown of how capital gains tax works. The Government has spent a large amount of money on helping the country during the Coronavirus Pandemic and it will be interesting to see how the Government plans to pay for this support and what changes will be made.

Please continue to check back for our latest blog posts and updates.

Charlotte Ennis

24/07/2020

Team No Comments

Active Minds: China’s recovery drives Asian bull market

Please see below for Jupiter Asset management’s latest ‘Active Minds’ article received by us late on the 22nd July 2020:

Jason Pidcock

Head of Strategy, Asian Income

China’s recovery drives Asian bull market

The bull market in Asia continues, noted Jason Pidcock, Head of Strategy, Asian Income. We’ve seen lots of large index constituents in China and Hong Kong rallying sharply, with some reaching all-time highs. Some people may find this a bit ironic given the negative political news coming out of China and Hong Kong, but this hasn’t prevented capital from flowing into those markets. Jason highlighted that this isn’t just in terms of domestic inflows – foreign capital is also buying Chinese and Hong Kong stocks.

What’s really driving Asian equities is the V-shaped recovery in China’s economy, said Jason. China is in a better position than many other economies, with second-quarter GDP up 3.2% year on year, following a contraction of 6.8% in the first quarter. So, it’s on track with expectations for a full recovery from the decline sometime in the second half of the year. Lots of Chinese businesses are doing well, too. Companies are forecasting profit growth and they’ve got strong balance sheets. While many parts of the world are seeing dividend cuts, many Chinese companies are not cutting dividends, and furthermore, many are actually growing their dividends, partly because of their net cash positions.

There’s been minimum impact from recent geopolitical tensions on Hong Kong, too. The UK symbolically suspended its extradition treaty with Hong Kong and placed it under an arms embargo, and the US has officially removed Hong Kong’s special trade status. Economic impact will be quite minimal though, as it should only affect about 1% of Hong Kong’s total exports. The Hong Kong dollar peg is unlikely (and technically difficult) to change, and capital flows into Hong Kong have gone up sharply since the announcement of the drafting of the National Security Law at the end of May. Hong Kong has had to lock down the economy to a degree because of a new flare up in virus cases, but most people are seeing this as temporary; it’s not having a big impact on most of the larger-weighted stocks listed there.

Overall, Jason expects to see Asia Pacific equities continue to trend higher; within the region, it’s Northeast Asia that’s driving growth.

Chris Smith

Fund Manager, UK Growth

Why aren’t supermarkets making more profit?

The UK has been the worst performing major developed market year to date, said Chris Smith, Fund Manager, UK Growth. That in itself isn’t so remarkable, as the UK has lagged behind major global peers for much of the last five years, but Chris said that the magnitude of the underperformance has accelerated in 2020. The reason for this is partly because the UK stock market has a larger exposure to structurally challenged or cyclical sectors, such as oil majors and financials, than many of its peers, and not much of a technology sector.

So, if the UK market faces so many challenges, where can a stock picker investing in UK stocks look for opportunities? Chris used a couple of examples to illustrate where he does, and does not, find attractive stock ideas in this environment.

At first glance, supermarkets seem like one of the winners from the Covid-19 pandemic, registering record like-for-like sale growth in many cases as shoppers stockpiled ahead of lockdown. Chris, however, sees them as structurally challenged ‘old world’ businesses. Despite that record sales growth, supermarket profits are forecast to be broadly flat year-on-year in the UK. This is because the increased sales were focused on low margin staples, and office workers, tourists etc staying at home means supermarkets are selling far fewer high margin items such as ‘on the go’ convenience food and drink. Online deliveries have gone up significantly, but this also has a dilutive effect on margins, as purchases are again focused on low margin items and the costs of fulfilling orders are higher than for in-store purchases.

Ultimately, Chris doesn’t see supermarkets as an attractive long-term investment for a growth investor like him. More attractive, however, is the testing and certification industry. It is essentially an oligopoly, with three major players all experiencing strong organic growth across the cycle from 2006-2019. The industry is also exposed to a lot of long-term structural growth trends, such as more regulation, higher safety standards, ESG in the supply chain, and cybersecurity, among others.                           

Richard Watts

 Head of Strategy, UK Small & Mid Caps

UK midcaps – go where the growth is

Richard Watts, Head of Strategy, UK Small & Mid Caps, also discussed the UK’s recent underperformance, noting that the domestically-biased FTSE 250 Index is down around 25% year to date, which is significantly worse than the 16% decline of the more international FTSE 100 Index.

In turn, the UK stock market is trading at a 25% discount to its long-term average against the broad global equity market as represented by the MSCI World Index. This valuation trough is at its lowest since World War II, so it does look cheap. The UK market has also hugely underperformed relative to where government bond yields are so, in Richard’s view, the market looks very good value.

Part of the malaise is down to the weakness of the pound and its volatility against a backdrop of Brexit uncertainty in particular hurting many midcap stocks, which collectively are more exposed to the economically-sensitive parts of the economy (housebuilders, engineers, travel companies, pubs and restaurants) than the FTSE 100 Index. More recently it has also reflected the outlook for dividends, as many companies had to cut dividends or cancel them to access government support schemes.

In the small and midcap strategy, Richard and the team have been overweight in structural growth for some time – it’s been clear that the pandemic has greatly accelerated the shift towards online retailing, pulling forward some two to three years of growth. This is having a very positive impact on the earnings of such companies and the strategy. And it’s no surprise that the team is underweight in travel, store-based retailers, pubs and restaurants, as they think consumers are still very nervous. This can be seen in the number of restaurant table bookings (not) being made. The team expects pub like-for-like sales to be down around 40% year-on-year, so they are wary of having too much exposure to these areas. Instead, they are seeking economically-sensitive exposure through those businesses that they believe will emerge from the crisis in better shape and which are not reliant on consumer spending where, in their view, it will take time for confidence to recover.

Joel Ojdana

Credit Analyst, Fixed Income

Don’t miss the double-B boat

Double-B credit offers great opportunities in today’s US high yield market, said Joel Ojdana, Credit Analyst, Fixed Income. Classed as the better-quality end of high yield credit, these businesses are well suited to the ‘new normal.’ In a world where negative real rates imply a slow global recovery, and with enormous debt at both the corporate and sovereign level likely to dampen productivity, these better-quality balance sheets and businesses should benefit.

Unprecedented support from the Federal Reserve also continues to drive spreads tighter, said Joel, and has opened up a financing window to corporate borrowers that is not at all typical during a ‘normal’ recession. With more monetary support expected by the market, BB-credit spreads are likely to further compress, in Joel’s view, offering a great opportunity. That said, it’s important to discriminate, because the pandemic has created both winners and losers within the US high yield segment – the Technology and Utilities sectors have outperformed year to date, while the Energy and Transport sectors have plummeted, for example. Finally, BB-rated corporates also frequently issue 10-year bonds, which is typically the longest duration in the high yield market and therefore should offer the most potential upside if spreads do tighten further.

These articles are useful for breaking down input into sectors, allowing experts of their particular sectors to offer insight within their specified field. This facilitates an all-round view of the markets.

Please keep reading these blogs to keep your own view of the markets up to date.

Keep well and safe

Paul Green

23/07/2020

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see below an investment market update article published by Brewin Dolphin on 21/07/2020 and received yesterday:

Global markets rise on vaccine hopes

Global share markets largely rose over the past week on encouraging reports of progress with some of the coronavirus vaccines currently in development.

Chinese stocks weakened, however, after a period of very strong performance, although we see this as a switch to a more gradual rate of increase rather than an outright reversal of fortunes.

Bond prices rose, perhaps because investors are still nervous that the withdrawal of fiscal stimulus will cause economic conditions to worsen in the future, but economic data was broadly positive over the past week, especially in the US and China.

Last week’s markets performance*

  • FTSE100: 3.2%
  • Dow Jones: 2.3%
  • S&P500: 1.24%
  • Dax: 2%
  • Nikkei: 1.9%
  • Hang Seng: -2.5%
  • Shanghai Composite: -5%

*Data for the week up to close of business on Friday 17 July.

A bright start to the week

Markets were up in the US and across Europe yesterday as the marathon summit to decide on the €750bn European Recovery Fund showed signs of progress. UK shares lagged, however, with the FTSE100 closing down by 0.49%. The EU summit eventually concluded with a deal in the early hours of Tuesday morning, helping push markets up yet again. UK and European shares were heading up in early trading.

Earnings season kicks off in US

Last week saw US earnings season get under way and the biggest US banks (JP Morgan, Goldman Sachs, Citibank, Bank of America and Wells Fargo) put aside $35bn in loan-loss provisions which weighed on their reported earnings. However, it is important to remember that these numbers are just estimates.

Overall, the earnings season is going reasonably well. According to headline statistics, 52 companies beat earnings estimates compared with 13 who fell short, giving a “beats to misses” ratio of 80%. We don’t find much value in this number as, come good times or bad, the beats-to-misses ratio for earnings is invariably around 80%, with estimates seemingly massaged up and down between reporting periods to create a somewhat artificial optimism.

Generally, though, earnings reports have been reasonably well-received by the market and this is better news – it implies that guidance, to the extent that companies have been able to offer any, has been well received.

One exception would be Netflix, whose subscriber growth numbers disappointed the market despite management warning that the pace of growth would slow. Shares dipped 15% in after-market trading.

Upbeat Main Street

Last week saw consensus-busting US retail sales figures, with sales up 7.5% in June following a record 18.2% increase in May.

Source: Datastream / US Census Bureau July 2020

That came on top of an encouraging manufacturing purchasing managers’ indices in Philadelphia and New York which, taken together, would suggest activity has stopped contracting and is now expanding at a healthy rate.

The Federal Reserve Beige Book, a survey of the 12 US regional Federal Reserve districts, was also positive, showing economic activity increased in almost all jurisdictions and consumer spending picked up as many nonessential businesses were allowed to reopen.

Industrial production rose 5% in June, business inventories fell 2.3% and home-builders’ confidence for this month returned to the March’s pre-lockdown level.

Things were a bit more mixed in the UK. The May GDP figure was disappointing for the market and there was very little comfort taken in the unemployment rate remaining low, given it is likely to increase as state support is withdrawn. However, UK retail sales jumped by 3.4% in June, up from a 5.9% fall in May.

China’s trade was better than expected. Forecasters expected to see a 9% decline in imports, but actually got a 3% increase, reflecting stronger local demand.

Stimulus news

In the US, the unemployed are set to lose their $600-a-week in extra unemployment benefits on 31 July. If this cut goes ahead the strong retail sales numbers will deteriorate very quickly, and so we expect them to be extended, especially given it is an election year.

In Europe, the €750bn European Recovery Fund was approved early on Tuesday after one of the longest meetings in EU history. The agreed package includes €390bn of grants to countries most in need, and €360bn of low-interest loans. The package of grants was pared back from an initial proposal of €500bn, due to opposition from the so-called Frugal Four (Austria, Denmark, Netherlands and Sweden). In return, those countries will now receive bigger annual rebates from the EU.

West vs East

The big news in the escalating tensions between the US and China was President Trump ending Hong Kong’s special status with US. The implications of the move are still to be determined but ought to mean the loss of preferential trade arrangements. That will have limited implications for the US, but will be very harmful for Hong Kong’s domestic economy.

In response China summoned the US ambassador and said it will sanction US officials, while the US said it will sanction people and entities that it thinks are undermining Hong Kong’s freedoms. This is a fast-moving situation and further developments are expected this week.

COVID vs humanity

More bad news for Hong Kong is the outbreak in coronavirus cases that may actually exceed those experienced during the first wave of the crisis. It is worth remembering, however, that the city weathered the initial wave relatively well. The most economically significant growth in cases remains in the US. Looking for positives, the rate of growth looks to have peaked, giving hope that the actual numbers may slow this week or next. There have also been fewer hospitalisations, which seem to have peaked along with deaths. Normally these metrics would lag behind case growth, but it appears that voluntary social distancing by “at-risk” groups may have flattened the curves for these most dire metrics.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

22/07/2020

Team No Comments

Jupiter European Growth Strategy – Newsletter – Q3 2020

Please see article below from Jupiter Asset Management written by the European team at Jupiter – received 21/07/2020

Summary

  • Welcome to the second instalment of our quarterly series of investment updates from your European Growth team at Jupiter.
  • Alongside our usual monthly fund commentaries, we aim to build a library of insights into the way we think and the way we work. Think of this as the behind-the-scenes extra to the main feature.
  • This quarter we give an update on the team, consider the global reach of our investments and offer an alternative perspective on the value of dividends.

Team update

We are very pleased to announce two new hires to support the European Growth strategy. We look forward to welcoming Nikisha and Phil and hope to introduce them to you in person when conditions permit. 

The first, Nikisha Mistry, has joined us from Merian where she has worked on the European Smaller Companies strategy for the past three years. Nikisha will begin by focusing on ideas and holdings in our Smaller Companies funds but over time will, like all of us, broaden her coverage to the entire European investment universe.

Phil Macartney is an experienced equity investor we know well and are excited to have joining us. Phil is a UK and European analyst having worked on both long and long/short funds over 13 years. He joins us from Columbia Threadneedle where he was co-manager on the Threadneedle UK Mid-250 fund and also deputy manager on the Threadneedle UK Absolute Alpha fund. Phil joins the team in September.

Our culture of challenge and constructive debate will only be enhanced by these two excellent hires.

Around the world in 80 days 

In lockdown for 80 days or so and unable to follow in Phileas Fogg’s footsteps, we have had time to consider the global nature of our strategy. Our search for companies with sustainable advantages naturally leads us to businesses that compete on the world stage.

As European equity investors, we regularly meet many who bemoan Europe’s prospects. They cite demographic headwinds and bureaucratic, inefficient governments. Some are hampered by large debts while others with strong fiscal positions are reluctant to spend.

We see things differently. Whether it is the digitalisation of the financial system in Brazil, the dynamism of healthcare in the United States or the emerging middle class of consumers in China,  European-listed companies offer us access to many attractive growth opportunities. And, being European, they often come with better corporate governance, accountability and a focus on sustainability, too. 

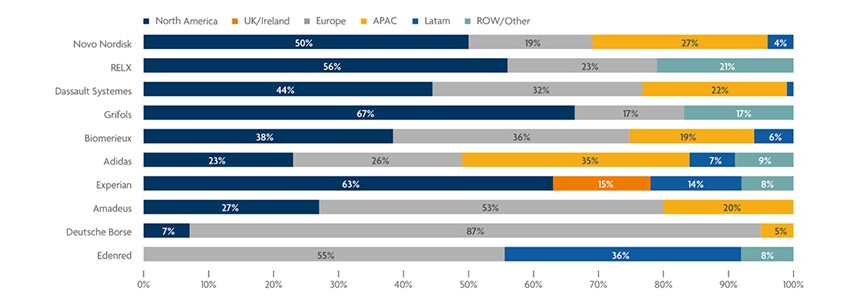
Revenue by Geography FY19

Chart: Company revenues by geography full year 2019 for some of our largest holdings. (Source: Jupiter, Bloomberg)


Global healthcare

Although the USA is known for innovative biotechnology, it is not alone. Europe was a pioneer in the process of plasma exchange – the harvesting of antibodies from blood donors to make therapeutic agents used to treat many autoimmune conditions. The pioneers, Dr Grifols and his two sons, built up the eponymous company in which we invest – it is still run by members of the family today and generates over two-thirds of its profits from the US market. Grifols continues to innovate. One potential area of promise is Alzheimer’s disease, where research has shown its products slow the progression of the disease in some patients with moderate Alzheimer’s. 

Accessing Chinese consumers

A family feud between the Dassler brothers resulted in the creation of Puma and Adidas. Today, both would agree on the importance of China to the sporting goods industry. Last year, Adidas generated 35% of its revenues in the Asia-Pacific region with China being the largest contributor. A favoured brand among some 400m Chinese millennials, Adidas has stores in over 1,200 cities in China but hopes to expand to 2,400 to meet the growing demand. A strong digital footprint allows it to serve customers through its own website and those of partners such as Tmall.

Formalising the Brazilian economy

Edenred, a French company originally spun out of Accor, delivers digital payment solutions that appeal to clients far beyond its traditional homeland. Its products efficiently deliver benefits to corporate employees, give companies greater control over their expenses and help governments formalise their economies. In 2009, Latin America alone accounted for 40% of total operating profits. Here, over 90% of its business is digitalised compared to two-thirds in Europe. Digitalisation allows Edenred to offer many different benefits to its customers in a highly-attractive and cost-effective manner.  

Global leadership in niche markets

Global leadership is not the preserve of large companies. Smaller companies often dominate their markets, especially in niche areas. For example, Dometic, with a market cap of just Eur2.3bn, is the leading manufacturer of appliances and components for recreational vehicles. It enjoys a market share of 45%, some four times greater than its nearest rival. Dometic’s headquarters may be in Sweden but over half of sales arise from the Americas, its largest market.

A preference for effective capital allocation – why we don’t focus on dividend yield

Companies are increasingly asking us what we think about their dividend policies. You can probably guess why.

It’s been an extraordinary year. For equity investors, huge uncertainty and immense share price volatility have made many traditional valuation metrics meaningless. Income investors have had a torrid time as supposedly stalwart dividend payers cancelled or clawed back payments to offset collapsing revenues, bolster over-stretched balance sheets or assuage societal scrutiny.

When Royal Dutch Shell surprised the market in late April, cutting its dividend for the first time since the Second World War, parts of the financial press went into overdrive.

“…investors who have diligently saved for retirement and rely on shares that pay regular dividends, now face a shortfall in their annual income” (This is Money – 31 March 2020)

This kind of sensational hyperbole misses the point. The real issue is that such dividend cuts are likely symptomatic of a material reduction in the intrinsic value of the company.

A common misunderstanding

Even though dividends are decided annually by the board, some investors use the dividend yield to determine the attractiveness of a company. However, we believe this is a poor guide to the intrinsic value of a business and can lead to poor corporate capital allocation.

Nevertheless, dividends are considered, by many, as a significant part of how a company creates value for its shareholders. Consequently, some management teams slavishly try to meet specific dividend expectations or consistently grow the annual dividend per share. But is this really the best use of investors’ hard-earned savings? Do they really care how their investments are liquidated. And, more importantly, should they care? 

Given that investors can create their own dividends by liquidating a portion of their holdings, we argue that the rational investor should not care1. That’s because dividends are not free income, they come at the expense of capital. If you receive a 5 cent dividend on a Eur1 share, the share price will drop in value to 95 cents. It is, in effect, an enforced capital release, not a creation of value. In our view, it makes more sense for the investor or portfolio manager to decide what capital to release and from which underlying assets, not a company management ignorant of the requirements of its individual shareholders.

If the right opportunities exist – reinvest

It is our firm belief that company managements should focus on whatever will create the greatest risk-adjusted total return for their shareholders. Thus, we would much rather a management reinvested excess cash flow into projects and opportunities with an attractive internal rate of return than feel obliged to return it to shareholders. The opportunity cost of cash returns (dividends and share buy backs) can be substantial. Reinvesting excess capital at high rates of return within the business will enable shareholders to harvest a much greater income over time, than if a company simply returned all excess income annually. 

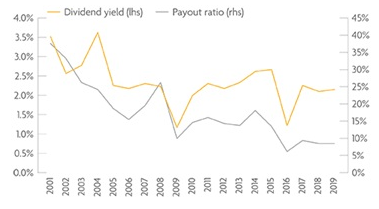
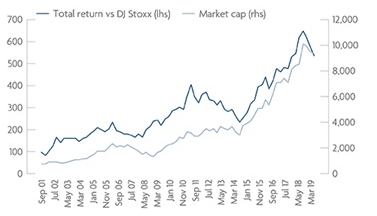
Campari, the drinks manufacturer, provides an example of how thoughtful capital allocation creates value for long term shareholders. Campari’s management is perhaps less constrained than many. With just one key majority shareholder, it is supported in its longer-term growth ambitions. And although Campari does pay a dividend, it is essentially an afterthought. What matters to management is the long-term creation of value. Here, Campari’s strategy is to acquire local or regional brands and then develop their appeal to a broader market. Its brands include Aperol, Grand Marnier and, of course, that great bitter, Campari. By using its excess capital to acquire niche spirits brands, Campari has moved from being a relatively small player to a key competitor in the global spirits market. Had management instead focused on maintaining a 40%-50% pay-out ratio then the investment story would have likely been quite different.

Campari – capital allocation decision to reduce dividend pay-out ratio (rhs %)

Campari – Relative share price performance and Market Capitalisation (Eur m)

Charts: Campari chose to reduce its dividend pay-out ratio and use its free cash flow to focus on long-term value-enhancing M&A. This has created huge capital appreciation for shareholders in absolute terms and also relative to the wider market. (Source: Jupiter, Bloomberg)

That is not to say that companies should not pay dividends. If there is no opportunity to enhance shareholder returns through further investments then excess cash should be returned.

Your Jupiter European Growth team:
Mark Nichols, Mark Heslop, Sohil Chotai, Nikisha Mistry

An interesting article from the European team at Jupiter Asset Management which gives us a good alternative perspective on the value of dividends and the global reach of their investments.

Please continue to check back for our latest blog posts and updates.

Charlotte Ennis

22/07/2020

Team No Comments

A.J. Bell Blog – Fund Transaction Costs

Please see below an article published today by A.J. Bell providing clarification on the transaction costs (expenses) incurred by fund managers when dealing with investments.

The MiFID II and PRIIPS regulations have been in force for some time now, having come into effect in January 2018. A key part of these rules relates to transparency in costs and charges disclosure, and a particular requirement of this was for asset management firms to disclose transaction costs.

The additional disclosure is designed to help investors make informed choices, but the presentation and comparison of transaction costs continue to cause some confusion even two years on. In this article, we will look at an overview of how these costs are calculated and what they mean for fund investors.

What are transaction costs?

Transaction costs represent the expenses of dealing in the underlying investments in a fund’s portfolio. These costs have, of course, always been present prior to MiFID II and PRIIPs, so they are not ‘hidden charges’ per se, but they do have an effect on an investor’s overall returns and therefore the regulations now mandate that firms should provide a clear disclosure of them to investors so that they can assess the total cost of ownership for products.

Transaction costs for funds are made up of three parts:

  • explicit costs;
  • implicit costs; and
  • anti-dilution benefits.

In a simple form, the costs disclosed to investors can be calculated as follows:

total transaction costs = explicit costs + implicit costs – anti-dilution benefits

Explicit costs

These are the ‘direct’ charges incurred when a fund manager purchases or sells the underlying instruments in their funds. Typically, these are things such as commissions paid to brokers and taxes such as Stamp Duty.

Implicit costs

As their name suggests, implicit costs are not directly incurred by the fund manager. Rather, they represent the difference between the price of a security (mid-price) immediately before an order is placed in the market (this is sometimes called the ‘arrival price’), and the price that the trade is actually executed at. This difference is sometimes called ‘slippage’. Due to market movements, implicit costs can be positive or negative.

Anti-dilution benefits

Large investor subscriptions or redemptions often mean that a fund manager is required to trade in the underlying portfolio, and the costs of this are borne by all investors in the fund rather than just the investors who have caused the trading. To combat this, many funds use an anti-dilution mechanism to dampen the effects of large investor subscriptions and redemptions.

For example, swing pricing, dual pricing or a fixed-dilution levy may be used to cover the costs of dealing from new transactions. The MiFID II and PRIIPS rules allow these anti-dilution benefits to be subtracted from overall transaction costs – but only up to the amount of dilution actually caused by trading. Fund managers using an anti-dilution mechanism may therefore disclose relatively low transaction costs.

Example calculation

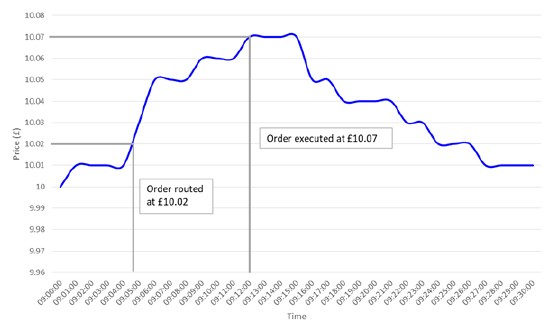
To show how transaction costs are calculated, let’s look at a theoretical example. In this example, a fund manager is purchasing 10,000 units of a security from a broker which charges a commission of 3%. The purchase is routed to the broker just before 9.05am and, at that time, the mid-price is £10.02. The price of the security is steadily rising, and when the broker executes the order at 9.12am, the mid-price is £10.07. This is shown in the graph that follows.

What transaction costs have been incurred here?

The explicit cost is the broker’s commission: 10,000 x £10.07 x 3% = £3,021
The implicit cost is due to the market movements: 10,000 x (£10.07 – £10.02) = £500

So, total transaction costs here are £3,521.

Our scenario showed the price for a purchase where the market was rising. If the price had fallen, then the implicit transaction cost would actually have been negative. This works the opposite way for sales – rising markets result in negative costs and falling markets show positive costs.

Transaction costs as a comparative tool

The level of transaction costs can be a measure of the execution quality obtained by a fund manager. Used in the right way, they can be a good comparison when analysing the value of different fund choices, which was the intention behind the MiFID II and PRIIPs regulations. Transparency has certainly been increased across the board, with some asset managers choosing to go further than regulations strictly dictate and disclosing transaction costs not just in funds, but also in model portfolios, for example.

However, whilst it would be tempting to think that ‘smaller is better’, when comparing fund transaction costs you have to make sure that you are not comparing apples with oranges.

There are many factors that might affect transaction costs, and in particular the strategy and objectives of the fund should be borne in mind.

  • Funds dealing in less liquid securities will generally have higher transaction costs than those dealing in more liquid securities. More liquid securities are typically executed much more quickly than less liquid securities, hence the gap between the arrival and execution price is smaller.
  • Funds with a high turnover will tend to show a higher level of transaction costs – so, actively-managed funds, which typically transact more often than passive funds, will tend to have higher transaction costs for this reason.
  • Some funds may disclose negative transaction costs – this could be due to their investment and trading style, or could be due to incorrect application of the rules – something that the FCA has noted and investigated.

Also, although we haven’t gone into the technical details in this article, there are some slightly different calculation methods for implicit costs, such as a different method for new (under three-years-old) funds, which can produce subtly different results.

Summary

Disclosure of transaction costs has provided another way for investors to compare funds. Although it can be a fairly complicated area, it pays to do your research beyond the headline numbers – as we have seen, there are some nuances to be aware of when reviewing these costs.

Finally, it is important to note that net performance includes all of the costs discussed in this article and so, as well as looking at the total costs of a fund, analysis of net performance remains a robust way of assessment between different products.

Please continue to check our Blog content for advice and planning issues and the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

21/07/2020

Team No Comments

M&G Property Fund Update

Please see the article below published by A.J. Bell last week (14/07/2020) and received yesterday, which provides an update on the status of the M&G Property Portfolio fund:

Investors in the M&G Property Portfolio will have to wait at least another month before they can get their hands on their money, with the fund’s suspension extended for another 28 days. Investors have endured more than seven months of suspension so far and it now feels likely that the extension could continue until the end of the year.

This update provides a small glimmer of hope, as the independent valuers on the fund say they have clarity over pricing in another two areas of the property market: central London offices and student accommodation. Along with industrial and logistics properties, this means that they can accurately price 28% of the fund. However, that means more than 70% of the fund is still invested in assets where there is no certainty over their value – the fund has a long way to go before it gets below the FCA’s 20% threshold for uncertainty over valuations.

The majority of property fund investors are doing so partly for the income they’ll receive, but this has been very uncertain during the Covid-19 crisis, with many companies unable to pay rent or deferring it. The managers on the M&G fund say they are now getting 71% of their rent due, slightly up from two-thirds in April, meaning investors should expect a similar 30% haircut to their income payouts from the fund.

The M&G property fund is fighting fires on two sides before it can re-open: one on the accurate valuation of its assets and another on the level of liquidity in the fund. Investors will be disappointed that no properties have been offloaded since last month’s update and there are still £180m of assets either under offer or exchanged on. Considering over the past seven months of the fund closure there has been almost £150m of assets sold, there could be a long road to go before there is sufficient cash to re-open.

As you can see from the above, there is still a fair bit of uncertainty surrounding the M&G fund in terms of re-opening and its peers will be facing similar challenges.

Commercial Property investment still has a vital role to play in portfolios, as it remains a great investment diversifier.

It is important to remain patient and focus on your long-term investment goals.

Please continue to check our Blog content for the latest investment, markets and economic updates from leading investment houses.

Please keep safe and healthy.

Carl Mitchell – Dip PFS

IFA and Paraplanner

20/07/2020