Team No Comments

EPIC Investment Partners – The Daily Update | China High Tech Drive

Please see today’s daily update from EPIC Investment Partners received this afternoon:

The four-day Third Plenum in Beijing was the first meeting of the Central Committee that President Xi presided over since securing a third term in power. The lack of specific measures to tackle the ongoing residential property woes was disappointing although the shift to increase overall funding to local authorities was welcome. President Xi also vowed to make “high-quality development” the guiding force of the economy. 

The global manufacturing of solar panels is totally dominated by China. Estimates vary but the surge in capacity in recent years has seen capacity utilisation slump to 50-60%. P-type solar cells dominate capacity at present (circa 85% market share) but are likely to be replaced by the more efficient N-type solar cells .

N-tyle cells are designed with a specific doping process to improve efficiency and performance. Doping refers to introducing impurities into a pure silicon wafer to alter its electrical conductivity. P-type cells have an efficiency of between 15-22% although some have been rated as high as 23.6%. N-type cells can reach efficiencies of 25.7% and one would expect that number to climb further.  

The International Technology Roadmap for Photovoltaic projects that N-type cells’ mono-crystalline silicon (c-Si) will reach a market share of 28% by 2028, up from a mere 5% in 2017, while Solar Magazine estimates that N-type cells will account for 70% of production by 2032. 

Interestingly the Ministry of Industry and Information Technology (MIIT) recently announced new guidelines stipulating that existing and new capacity on N-type solar cells must exceed an average photoelectric conversion efficiency of 25% and 26%, respectively. Is this the death knell for the 85% market share P-type cells as “high-quality development” accelerates? Probably. Some estimates suggest that over 20% of current capacity will exit the market in short order, potentially lifting capacity utilisation significantly. 

The larger, better financed and better managed firms will survive and benefit from the exit of bit time players. We have seen this in the Chinese steel industry where decarbonisation and digitalisation dominate official policy. 

Please continue to check our blog content for the latest advice and planning issues from leading investment firms.

Charlotte Clarke

30/07/2024

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management providing an insight into markets over the past week.

Don’t fear the rebalance

The rough patch for global stocks continues – yet again concentrated in the frothy US mega-caps. Smaller caps continue to be a bright spot, but in aggregate these gains are being outweighed by large-cap losses. The “Magnificent 7” (Mag7 – Apple, Amazon, Alphabet, Meta, Microsoft, Nivida, Tesla) looks far from magnificent, falling more than 11% since early July. Ultimately, though, we think the market-wide rebalance is positive.

Tesla was the worst offender last week, losing 12% share price after extremely disappointing Q2 profits. The electric carmaker is being hit by both sour tech stock sentiment and a global downturn in the autos market. Chinese overproduction means carmakers have no pricing power – and there is a similar story in microchips. Manufacturers are under real pressure.

Fortunately, that weakness is not yet spreading into services – as it historically has. The problem is firmly on the supply side, and demand has held up reasonably. For now, it looks like manufacturing weakness is a good thing for consumers – lowering their prices and giving them more money to spend on services. That could change (particularly if manufacturers cut jobs) which we will have to keep an eye on.

We welcome the large-to-small cap rotation, but Mag7 losses could still be painful for markets overall. Those companies are big enough that their troubles weigh down the entire stock market – in which US consumers are heavily invested. Still, capital readjustment helps growth prospects for smaller caps, as will the Federal Reserve’s upcoming rate cut. The case for global, not just US, growth is still strong. The UK has been a notable bright spot, for example, thanks in large part to the new government’s closer European relations.

Last week’s market wobble might not be over, for the US mega-caps at least. But the rotation will hopefully move capital from where it was too concentrated to where could have the biggest growth benefits. Investors should not fear the rebalance.

Sahm-thing to worry about?

The “Sahm rule”, a US recession indicator based on how quickly unemployment is rising, is close to being triggered. The rule says that a recession starts when the three-month average unemployment rate is 0.5 percentage points above its lowest level in the previous 12 months – because when unemployment rises, it usually rises quickly. After US unemployment climbed to 4.1% in June, the gap has now narrowed to just 0.43pp.

We are unlikely to trigger the 0.5 threshold soon for technical reasons (the previous low drops out of the monitoring period next month) but a similar regularity noted by former New York Fed president Bill Dudley (three-month average unemployment 0.3pp above the cycle low) has already been breached. Of course, recession indicators are all rules of thumb that come with exceptions, and American economist Claudia Sahm, the rule’s namesake, noted last year that her rule would not be the first to break down during this post-pandemic cycle.

The key question is whether unemployment will stabilise at the current rate, or job losses will spiral. Fed officials seem to expect stabilisation, largely because current unemployment is close to their estimate of the ‘neutral’ rate. This is backed up by the ‘Beveridge curve’ – data showing that there is a balancing point between unemployment and job vacancies (increases in the latter are usually thought to be inflationary). June’s unemployment was at that point, which we can interpret as neutral (as the Fed seems to) or, more worryingly, as a tipping point.

Past resilience of the US economy should perhaps suggest a positive view, but this might be counteracted by the drying up of pandemic-era savings. Upcoming rate cuts will help in any case, but businesses might not be far from cutting jobs. The US economy certainly looks more fragile than it did a few months ago.

China won’t ship out inflation

The cost of shipping freight out of Shanghai has soared recently. This has historically been an indicator of downstream inflation – thanks to its effect on Chinese goods producers, and eventually US consumers. Spiking Shanghai freight are therefore worrying many about a return to global inflation. But we think this time is different, and we won’t see inflation shipping out of China.

What seems to be pushing up costs this time is a massive pickup in US demand for Chinese goods. This is almost certainly due to Donald Trump: the former president and Republican candidate unleashed a wave of tariffs on Chinese trade during his first term, and has promised to do so again if re-elected. His administration will reportedly target 60% or higher tariffs on Chinese goods. With Trump currently the favourite for November’s election, Chinese exporters and US importers think this might be the last realistic chance to trade. So, they are rushing to exchange goods, even if freight costs seem prohibitive.

This is unlikely to result in price pressures down the line, simply because Chinese firms are in no position to put up prices. Its domestic economy is weak and the government has been exacerbating a severe overproduction problem. That has resulted in ‘dumping’ goods (particularly electric vehicles) on international markets, pushing down prices. This is one of the key reasons global manufacturing is so weak. At the moment, China is exporting disinflation.

Chinese producers will likely bear the freight shipping costs, because they have little choice. Whether Trump wins or loses in November, we should expect the rush of China-US shipping to end in 2025. Freight costs are not as inflationary as in the past.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

29/07/2024

Team No Comments

The Daily Update | The Mirage of Western Prosperity: A Debt-Fuelled Illusion

Please see below article received by EPIC Investment Partners yesterday, which provides a global economic update.

The global economy has been spluttering for years, even before the pandemic struck. Sluggish growth, especially in economic powerhouses like China and the G7, painted a grim picture. We speculated many years ago that this slowdown was likely caused by shrinking working-age populations, a demographic trend that has persisted post-pandemic. Despite some recent glimmers of recovery, the underlying problems remain, masked by a perilous reliance on debt. 

Take the United States, for example. A 2.7% GDP growth rate might seem rosy, but it’s a mirage. The US government is running a gargantuan 7% budget deficit, borrowing far more than it earns. This unsustainable fiscal policy conjures an illusion of growth, but it’s a house built on sand. 

The situation isn’t much rosier in other major economies. Growth forecasts for 2024 in nations like Canada, France, Germany, and the UK are all significantly lower than their pre-pandemic levels in 2019. While US employment figures might appear robust, the reality is that the economy is propped up by government spending, not genuine productivity. 

Adding to the unease is the alarming level of debt in these nations. Except for Germany, all G7 countries have a debt-to-GDP ratio exceeding 100%. Servicing such high levels of debt at interest rates above GDP growth is simply not sustainable. 

This addiction to debt has ominous consequences. As Jerome Powell, the Chairman of the Federal Reserve, has cautioned, this trajectory is unsustainable. In a recent speech, Powell emphasised the gravity of the situation: “The U.S. federal government is on an unsustainable fiscal path. The debt is growing faster than the economy. It’s as simple as that.” 

Powell’s stark warnings underscore the precarious nature of the current economic situation. The US, and indeed much of the Western world, is living on borrowed time. Ironically, while there is much handwringing over ESG and sustainability policies, there’s little discussion about whether government spending itself is sustainable. 

In light of these mounting pressures, substantially lower interest rates are not just likely, they are inevitable. The sheer weight of accumulated debt, coupled with anaemic economic growth, leaves central banks with few options. This shift towards lower rates is not a policy choice, but an economic imperative. 

The question is not whether interest rates will fall, but how far and how fast. 

Please check in again with us soon for further relevant content and market news.

Chloe

26/07/2024

Team No Comments

EPIC Investment Partners – The Daily Update

Please see the below article from EPIC Investment Partners detailing their insights into GPU’s (graphic processing units), AI and the Energy Market. Received yesterday 24/07/2024.

Data centres are hardly new. Global installed capacity has been compounding at 10-20% per annum for twenty years plus. Traditionally driven by central processing units (CPUs), the advent of graphics processing units (GPUs), which excel at parallel processing, has been a game changer. GPUs can handle many smaller tasks simultaneously making them ideal for complex calculations involving large datasets. The drawback is that they consume three or four times the power of a CPU.

Google’s AI driven Gemini gives a handy analogy “imagine a chef (CPU) in a kitchen. The chef can handle complex recipes (complex tasks) but can only work on one dish (one task) at a time. On the other hand, a bakery (GPU) with multiple ovens can handle many simpler tasks (calculations) simultaneously, like baking cookies (smaller calculations)”. 

Electricity demand in developed economies such as the United States and Europe has been more or less static for the past two decades but the arrival of EVs, heat pumps and now GPU driven data centres looks to be transforming the outlook for global electricity demand. Jefferies recently published an excellent report highlighting the likely trends. Using IEA data, Jefferies estimate that European electricity demand will climb 7% over the next two years with EVs, heat pumps and data centres accounting for half the increase in demand.

Underlying these findings are Jefferies’ expectations that European data centre capacity will compound at 10-20% over the next decade. We wonder if these forecasts are too conservative.  While there remains a lot of ‘hype’ in the capital markets when it comes to AI developments, there is little doubt that AI is transformational.

With ‘net zero’ targets seemingly falling by the wayside, an unexpected boom in electricity consumption is unhelpful. To quote from a recent Bloomberg article “The world needs to be capturing about 1 gigaton of CO₂ a year by 2030 to be on track to reach net-zero emissions by 2050 and limit the global temperature rise to 1.5 degrees Celsius (2.7 degrees Fahrenheit) above mid-19th century levels, the International Energy Agency estimates. That’s 26 times what’s being removed annually now. And it’s three times what would be captured if all the projects now planned or under construction are operating by 2030”.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

25/07/2024

Team No Comments

Brewin Dolphin: Markets in a Minute

Please see below, Brewin Dolphin’s ‘Markets in a Minute’ update which offers a brief analysis of the latest movements in global markets. Received late last night – 23/07/2024

Markets had a lot to digest last week, which began with the high drama of an assassination attempt on former U.S. President Donald Trump. The details of the shooting have been well-covered elsewhere, but the impact on markets and the economy was determined by the boost it gave to former President Trump’s already soaring odds of victory.

Later in the week, Trump accepted the Republican nomination and named 39-year-old Ohio Senator J. D. Vance as his running mate. Trump’s miraculous escape, and a charismatic and articulate performance by the new potential vice president, marked a very successful week for the campaign.

The travails of President Joe Biden have also been helpful. Over the course of his week, his chances of victory were downplayed by giants of the Democratic Party including, according to the Washington Post, former President Barack Obama. The Democrats’ top-ranking senator, Chuck Schumer, was reported as having urged Biden to step down. A statement issued by his office didn’t deny the report. Furthermore, former Speaker of the House of Representatives Nancy Pelosi reportedly told House Democrats she believed he could be urged to exit the race.

To cap the week, Biden contracted Covid-19 and left the White House to self-isolate. Over the weekend he then succumbed to pressure and stepped down. What happens next is really uncharted territory.

The Democrats hadn’t formally named Biden their candidate – however, they’ve gone through the primary process, which should have made that a formality. He won almost all of the just under 3,900 delegates who would get to nominate him in a vote at the Democratic National Convention on 19-22 August.

Because Biden has stepped down, those delegates are understood to be able to transfer their votes. However, they’ll want to avoid doing so based upon personal whim. The President’s endorsement of Vice President Harris makes that process easier. Harris should also have access to Biden’s campaign funding. Indeed, funds began flooding in once news of Biden’s withdrawal became known.

Another candidate would need to begin fundraising from scratch, so it seems very likely that Harris will be the Democratic candidate. Whether the candidate is confirmed at the nominally open convention or pre-determined in a preparatory online poll should be decided this Wednesday, when Democratic National Convention organisers hold a meeting to discuss protocol.

Political analysis site 538’s polling tracker shows Trump has increased his polling lead by three percentage points. This suggests the race for the White House remains competitive. In head-to-head polling, Harris performs about the same as Biden against Trump.

Although recent events have been favourable for Trump, the objective evidence is that he’s now leading in what’s still a surprisingly tight race. The Democrats changing candidates will see them lose the advantage of incumbency but offers an opportunity to reset their campaign.

How has this impacted markets?

In terms of the market impact of these events, the increased possibility of Trump winning was accompanied by a steepening of the yield curve. He’s assumed to have plans to raise debt and generate inflation, which means longer-term interest rates should be higher. Longer-dated bonds rallied in early trading after Biden’s withdrawal, suggesting a small reversal of the Trump trade of higher longer-term borrowing costs. This comes alongside evidence from last week that the Federal Reserve (the “Fed”) would be in a better place to cut interest rates having now seen two months in which so-called “supercore” inflation (services consumer price index excluding housing costs) was negative.

Supercore inflation had been running frustratingly high throughout 2024, but May and now June have given negative readings, which will be massively reassuring to the Fed. Potentially lower short-term interest rates and potentially higher longer-term interest rates mean the yield curve has started to steepen, or at least become less inverted.

In an interview with Bloomberg released early last week, Trump made some important remarks. On the positive side, he seemed to indicate he would allow Fed Chairman Jay Powell to complete his term. Although he added the caveat, “especially if I thought he was doing the right thing.”

Trump signals clearly that he won’t allow the central bank as much independence as more conventional candidates would. That said, he isn’t indicating there should be a change in policy.

Developments in chipmaking

Markets experienced a stumble last week and Trump’s words may well have had something to do with it. After a period in which stocks have performed well (mainly driven by large-caps such as technology and communications services, with a specific focus on semiconductors), we have begun to see a reversal of some of these trends.

Firstly, small-caps began outperforming, then a sharp sell-off began in the semiconductor names. In the previously mentioned Bloomberg interview, Trump refused to commit to protecting Taiwan from potential Chinese aggression. Indeed, he accused the island state of having “stolen” America’s chips industry.

America’s support for Taiwan is important, most obviously in terms of being prepared to provide direct naval support, as Biden has promised. However, assuming Taiwan retains its territorial defences, the challenges of an amphibious assault would seem to be almost insurmountable.

If Trump’s comments did lead to conflict in Taiwan and that led to disruption to the Taiwan Semiconductor Manufacturing Company’s (TSMC) production, the implications for the sector would be harsh, with shortages downstream and a big reduction in demand upstream.

However, if Trump’s preference is reducing reliance on foreign-manufactured semiconductors, that implies a big increase in demand for semiconductor manufacturing equipment makers.

During Trump’s tenure, TSMC committed to building plants in Arizona. But its appetite may be waning as construction difficulties and a chipmaking skills shortage have slowed construction and dimmed the outlook for output. Trump may be calculating that a little jeopardy would keep TSMC focused on expanding its U.S. operations.

One such company would be ASML, which also fell as the market reacted to Trump’s comments. However, it would be wrong to suggest that Trump was the only factor weighing on the stocks. The Biden administration is reportedly considering more severe curbs on the use of U.S. technology within Chinese chip manufacturing processes. This is a threat designed to encourage companies like ASML to limit their business with China.

The news came in a week when earnings from companies within the chipmaking value chain have seemed quite robust. ASML, which makes chip manufacturing equipment, and TSMC, which uses that equipment, both reported strong orders.

Will the Bank of England cut interest rates?

Back in the UK, we had a succession of data to welcome in the new government.

As speculated in previously weekly round-ups, the welcome declines in the consumer price index (CPI) were most impressive in the last report ahead of the election. In June, CPI failed to drop below the 2% target, as had been the consensus forecast. Instead, headline inflation remained at 2% while core inflation accelerated slightly. This was considered bad news for the Bank of England’s Monetary Policy Committee (MPC), which might discourage it from cutting interest rates.

However, we noted the decline in median CPI, which seems a more stable estimate of underlying price pressures. It suggests that eventually, like in the U.S., underlying inflation will ease in the UK.

If, on the surface of it, CPI data might prompt the Bank of England to delay cutting rates, subsequent wage growth rates were stable enough to rekindle its appetite. Furthermore, Friday’s retail sales were weak and will provide another modicum of encouragement for the MPC, which seems eager to reduce interest rates if the move can be supported by recent data.

In totality, last week’s data should provide the ammunition it needs, although the market believes it’s a coinflip whether rates get cut or not.

Over and outage…

Lower interest rates would be encouraging for the markets. However, last week ended in a downbeat mood. Following the semiconductor sell-off, there was a global technology outage due to a flawed cybersecurity software update by CrowdStrike. This impacted Microsoft and had ongoing implications for many other users.

Most striking was the impact on air travel, which itself suffers from cascading effects when parts of the schedule are disrupted. With both airlines and airports affected, the impact was significant. However, a botched update is a less concerning cause than a malicious cyberattack and should not on its own cause lasting market angst.

Please continue to check our blog content for the latest advice and planning issues from leading investment firms.

Alex Kitteringham

24th July 2024

Team No Comments

Brooks Macdonald Daily Investment Bulletin

Please see below today’s Daily Investment Bulletin from Brooks Macdonald, which was received this morning, 23/07/2024:

What has happened

Equity markets began to regain their footing yesterday with the Magnificent 7 (+2.33%) leading the recovery after a 4-day slump last week. The renewed vigour comes just as the corporate earnings season is set to ramp up, with industry giants Tesla and Alphabet poised to release their financial results after market close in the US today. The anticipation of these announcements has infused the market with a sense of optimism, contributing to significant gains in major indices such as the S&P 500, which rose by 1.08%, and Europe’s STOXX 600, which increased by 0.93%. Both indices experienced their best sessions since the early days of June, recouping a portion of their recent declines.

Politics driving market?

In the political arena, the aftermath Joe Biden’s withdrawal from the presidential race captured the media’s attention, though there remains some scepticism regarding any immediate, substantial changes in the election’s trajectory. Donald Trump continues to be viewed as the leading candidate, with a Republican victory still perceived a likely outcome. While Trump’s momentum has contributed to some of the recent significant shifts in the market, it is the narratives of disinflation and a potential ‘soft landing’ for the economy that appear to be more influential. Investors are keenly awaiting the release of the second-quarter GDP and June’s core PCE inflation data, which are anticipated to reinforce these themes. The bond market has already fully factored in expectations for a rate cut in September.

What does Brooks Macdonald think

There is no single catalyst behind the resurgence in momentum and growth stocks. A commonly cited explanation is that the market rotation into small caps following the CPI announcement last week may have been overly aggressive. Despite some concerns about capital expenditures in AI versus their monetization, and a projected deceleration in earnings growth for major technology firms, expectations remain high. The six largest companies within the index—Amazon, Apple, Alphabet, Meta, Microsoft, and Nvidia—are still projected to achieve an impressive y-o-y earnings per share growth of 30%, while the remaining companies in the index are expected to see a more modest growth of 5%.

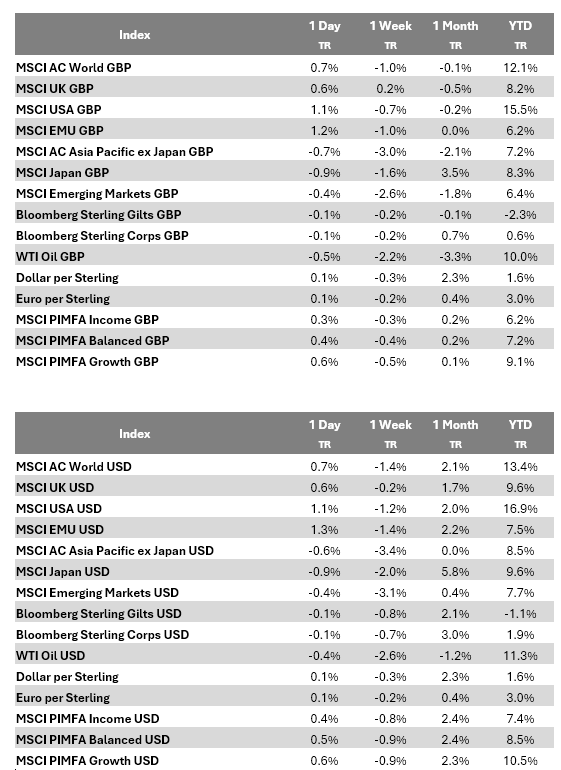
Bloomberg as at 23/07/2024. TR denotes Net Total Return.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Charlotte Clarke

23/07/2024

Team No Comments

Tatton Investment Management – Monday Digest

Please see the below article from Tatton Investment Management providing an insight into markets over the past week.

Shock, rotation, growth?

An astounding week, that started with an attempted assassination of Donald Trump, ended with the largest global IT outage in history. As a result, markets now assume Trump will be president – and have priced in the tax cut benefits to small cap US stocks. The outage caused lots of disruption, but little market volatility as yet.

It adds further pressure to mega-tech stocks, which have struggled following a massive market rotation into small caps. The global system failure might also push more money into cybersecurity (even though this particular episode wasn’t an attack), following Google’s $23bn acquisition of Wiz. We need to keep an eye on the long-term implications of this trend.

The assassination attempt has made Trump the presumptive next president in markets’ view, and there is clear excitement about another round of corporate and personal tax cuts – benefitting the small-cap Russell 2000. We welcome a rotation away from the previously dominant mega-cap tech stocks, but markets are arguably ignoring the negatives of a Trump presidency – most notably, a deterioration of US fiscal metrics and potential bond market volatility. Bond markets are calm at the moment, but that could change.

The large-to-small cap rotation is a momentum story, and we have noticed that, in recent years, momentum has become a dominant market driver. That might have something to do with the presence of AI in trading strategies, which is a slightly concerning thought (since AI-driven behaviour typically becomes very unpredictable). Nvidia is a good example: its rally has driven down its risk premia dramatically, despite being an historically volatile stock. This pattern is the same across the mega-caps, which are typically more volatile than the rest of the US stock market. 

Those trends might flip if rotation continues, but we worry that mega-cap losses might start to dwarf the small-cap gains – because of the former’s sheer size. That could negatively affect market conditions or consumer confidence (through the balance sheet effect). Greater market equality might be a long-term benefit, but we need to be vigilant.

Small cap rotation

Small cap US stocks continued outperforming the tech mega-caps last week – in stark contrast to the Magnificent 7’s incredible rally for most of this year. Weaker inflation data prompted the switchover, as markets now think the Federal Reserve might cut rates this month, or by September at the latest. 

That goes against the usual narrative somewhat: small caps are thought to lose out when economic activity weakens (as in a disinflation environment) because they are sensitive to near-term growth, while ‘growth’ stocks like tech are thought to be benefit when rates fall. Instead, markets clearly think rate cuts will be a big boon for small companies – possibly because borrowing costs are now such a burden that the effect of changing them is bigger. 

Small caps were also boosted by expectations that Donald Trump will win the presidency, with his agenda of tax cuts and deregulation. We think there might be fiscal and bond market problems with this further down the line (he wants to expand the deficit, but his foreign policy could deter the capital inflows needed to do so), but markets are not showing signs of fear yet.

Losses for the Mag7 are harder to explain (they should benefit from tax cuts too) but we think they are mostly about momentum. The relative balance of expected earnings growth has shifted enough to make investors question the mega-caps’ huge valuations, which have become stretched after a phenomenal rally this year. We wrote a while ago that market concentration in the Mag7 was mostly because no one could match their profit growth – but this may no longer be the case. Hopes for a better balance in economic profit distribution has allowed the rotation that many have been clamouring for all year long. That inevitably drags money away from tech – but that could well be a good thing.

Renminbi strength is political, not economic

Chinese growth looks weak after disappointing GDP numbers – and many think it is weaker than the official figures say. Deflation is still a big problem; month-on-month inflation has been negative since April. The communist party’s third plenum (a key economic meeting) was remarkably quiet about the problem this week. Beijing clearly favours a gradual approach, more in keeping with Xi Jinping’s long-term deleveraging goals. Stimulus has been stop-start in recent years, as the government is reluctant to inflate the credit bubble again.

Deleveraging an economy is much smoother if export demand is strong – but that has been battered by tariffs and trade wars. These are only set to get worse if Donald Trump wins a second term, or the EU imposes its planned tariffs. In this weak environment, you would normally expect the currency to fall in adjustment, making exports more attractive. But the renminbi has remained stable against the dollar – and appreciated massively against the weak yen, making Chinese exports to Asia (where most of Chinese trade is) more expensive.

Beijing’s reluctance to devalue its currency – thereby tightening financial conditions – is surprising, and seems to be the result of other political goals, rather than an aim in itself. Devaluation would undermine domestic confidence in the economy and international perceptions of the currency. Trump would undoubtedly jump on it and call Beijing a currency manipulator, while the EU would potentially dial up tariff talk. 

In terms of selling goods to the west, therefore, there would be little benefit – since the currency discount would be nullified by tariffs. The situation is different among Asian neighbours, of course, but is the Chinese economy detached enough from the west to rely on this trade? In the months and years to come, answering that question will be crucial.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Carl Mitchell – DipPFS

Independent Financial Adviser

22/07/2024

Team No Comments

EPIC Investment Partners – The Daily Update | The World Bank’s Drought Gambit

Please see below article received this morning from EPIC Investment Partners.

The World Bank is poised to expand its catastrophe bond (cat bond) programme with the introduction of its first drought bond within the next 12-18 months. This initiative, likely to focus on Africa, represents a significant evolution in the Bank’s efforts to provide financial protection to vulnerable countries against natural disasters. 

George Richardson, director of the capital markets and investment department at the World Bank Treasury, highlighted the institution’s ambition to venture into the drought space. This move comes as the World Bank has already facilitated over USD 4.8bn in cat bonds across 17 transactions, primarily covering earthquake and wind risks in the Pacific and Caribbean regions, with Mexico being a prominent issuer. 

The existing cat bond program, operated through the International Bank for Reconstruction and Development (IBRD), has proven effective, making USD 568m in insurance payouts to date. These financial instruments have played a crucial role in helping emerging economies mitigate the economic fallout from storms and earthquakes for over a decade. 

However, the introduction of a drought bond presents unique challenges. Richardson emphasised the complexity of modelling droughts, wildfires, and floods compared to earthquakes or storms, particularly for parametric cat bonds where payouts are triggered by specific physical parameters of an event. The fundamental hurdle lies in the need for extensive historical data to enable accurate risk modelling by various agencies. 

The timing of this initiative is particularly pertinent given the recent severe drought conditions in Southern Africa. The region has been grappling with its worst drought in years, exacerbated by the naturally occurring El Niño phenomenon and rising global temperatures due to greenhouse gas emissions. These factors contributed to numerous record-breaking weather extremes in the past year, underscoring the urgent need for financial mechanisms to support affected countries. 

In addition to expanding its cat bond offerings, the World Bank has introduced Climate Resilient Debt Clauses (CRDC) for vulnerable, low-income countries. This innovative feature allows governments to defer loan repayments for up to two years if hit by a severe natural disaster. Seven countries, including several in the Caribbean and Montenegro, have already adopted these clauses. Some are currently evaluating whether to activate this provision in the wake of Hurricane Beryl, which recently caused extensive damage across several Caribbean islands. 

The World Bank’s multifaceted approach to disaster risk financing, encompassing both cat bonds and flexible loan terms, demonstrates its commitment to supporting countries vulnerable to climate-related disasters. As global temperatures continue to rise and extreme weather events become more frequent and severe, these financial instruments will play an increasingly critical role in building resilience and facilitating rapid recovery in the world’s most vulnerable regions. 

Please check in again with us soon for further relevant content and market news.

Chloe

18/07/2024

Team No Comments

Evelyn Investment Partners – UK June CPI Inflation

Please see the below article from Evelyn Investment Partners detailing their thoughts on this morning’s UK inflation announcement for June. Received this morning 17/07/2024.

What Happened?

UK June annual headline CPI inflation came in at 2.0% (consensus: 1.9%), versus 2.0% in May. In monthly terms, CPI was 0.1% (consensus: 0.1%), compared to 0.3% in May.

Core CPI inflation (ex-energy, food, alcohol and tobacco) came in at 3.5% (consensus: 3.5%) vs 3.5% in May. In monthly terms, Core CPI was 0.2% (consensus: 0.1%), compared to 0.5% in May.

What does it mean?

Despite headline inflation remaining in line with the Bank of England’s (BoE) inflation target for a second consecutive month, June’s inflation data came in very slightly warmer than forecasters had been expected.

Within today’s data, the category for clothing and footwear was responsible for nearly half of this month’s deceleration in the annual rate, with prices falling by 1.2% for the month of June, decelerating the annual rate to just 1.6%. Similarly, the basket for food and non-alcoholic beverages continued to ease, decelerating to 1.5% on an annual basis. This has helped drive the overall basket for goods firmly into deflationary territory with prices in this segment contracting by 1.4% over the last 12 months.

Meanwhile it’s the services sectors of the economy which are still running hot, with an annual inflation rate of 5.7%. within this, restaurants/hotels posted the strongest monthly print, with prices rising 0.9% compared to the month prior. As has been seen in previous locations during her tour, there is speculation that Taylor Swift’s ‘Eras tour’ that gripped the UK during June could be responsible for driving up hotel prices during the month.

However, looking forward:

Ofgem has signalled a further £122 reduction in the energy price cap effective from July 1, this 7% reduction should help to further cool household pricing pressures later this summer and further cement headline inflation at a rate within the BoE’s target. 

Furthermore, the slowing trend in core CPI inflation remains broadly intact. Lead indicators, such as producer price inflation is also heading south. Moreover, cost-push led inflation from wages that feed into the service sector is also decelerating. In addition to weakening employment data, annual private sector wage growth slowed to 5.8% in April, down from a peak of 8.2% in June 2023.

Bottom Line

Even as headline inflation remains within target for its second consecutive month, the continued strength in services inflation will likely remain a cause for concern for committee members at the BoE, heading into their August meeting. However, it remains to be seen if this will be alarming enough to delay their first rate cut later into the year. Currently markets are only pricing in a 35% chance of a cut in August, while prior to this inflation print that number stood at around 50%.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

17/07/2024

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see the below article from Brewin Dolphin detailing their discussions on the UK and US markets over the last week. Received 16/07/2024.

The major development over the weekend was the assassination attempt on former U.S. President Donald Trump. According to online prediction market PredictIt, the probability of Donald Trump winning the upcoming U.S. election has risen from 60% to about 66% since the event.

Market reactions have been relatively muted despite such a dramatic event, but there are some important observations as markets price in a higher chance of Trump being re-elected. Longer-term U.S. government bond yields have edged higher relative to shorter maturity bond yields. That is because a Trump re-election is expected to be more inflationary due to tariff threats.

Markets also believe there will be a bigger fiscal deficit and more supply of bonds because of Trump’s pledge to extend tax cuts. U.S. equities reacted favourably, but that may also be due to higher hopes for rate cuts as soon as September.

Cuts come into view

The U.S. consumer price index was the most anticipated data last week and coincided with Federal Reserve (the “Fed”) Chair, Jay Powell’s semi-annual testimony at the Senate earlier in the week. The outcome of both events helped cement the market’s view that U.S. interest rate cuts are coming soon.

Powell said the latest data shows that U.S. labour market conditions have cooled considerably from where they were two years ago. Indeed, we discussed the week before last how the U.S. unemployment rate has been steadily picking up and temporary help services jobs have fallen sharply. Because the labour market is no longer as tight, wage growth has slowed meaningfully. U.S. economic data indicated more of a soft patch recently, and Powell recognised that elevated inflation is not the only risk the Fed faces anymore.

The Fed’s mandate has two objectives: 2% inflation and full employment. In the past two years, the priority has been on curbing inflation. But, as inflation has made great progress, the balance of priority is now shifting toward full employment.

Powell is perceived to be leaning on rate cuts, but he’s keen not to commit to a specific timeline. The guidance is that more good data would strengthen the Fed’s confidence that inflation is moving sustainably towards 2%.

U.S. inflation eases

The Fed and the markets did not have to wait long for that evidence. Last Wednesday, both U.S. headline and core consumer price index (CPI) inflation were reported at below estimates. U.S. headline inflation surprisingly contracted by 0.1% month-on-month (MoM) in June, which was the first time the CPI was negative since we started getting the high prints back in 2021. CPI slowed more than expected on a year-on-year (YoY) basis too, with headline CPI now at 3% and core CPI at 3.3%.

The slowdown in inflation is broad-based, which is welcome. The categories most responsible for driving the downturn in core inflation were the two big shelter categories – rent and owners’ equivalent rent, which together account for over 43% of the weight in the index. Both decelerated sharply, rising just under 0.3% MoM. This is finally starting to reflect the slowdown we’ve observed in new lets inflation.

Core goods inflation is now negative for the third consecutive month. Notably, durable goods prices fell sharply by 4.1% YoY in June, which could be a symptom of weaker demand. Airfares and new or used car prices were all falling in June. The Fed’s preferred measure, so[1]called supercore CPI (core services excluding housing), contracted marginally for the second month in a row, a very different picture compared with the average +0.7% MoM pace in the first quarter of the year.

The satisfactory set of inflation data and cooling jobs data paves the way for the Fed to cut soon. Markets are now pricing in about 62 basis points of rate cuts by the end of 2024 and have fully priced in a 25-basis point cut in September. It feels like we really are finally inching towards a Fed interest rate cut, following wild fluctuations in expectations throughout the year.

The market reacts

Perhaps the most interesting aspect of the CPI release was the market reaction. Bond markets saw a marginal reduction in bond yields across maturities, while gold prices gained as real yields fell. The U.S. dollar weakened as real yields fell and interest rate differentials between the U.S. and other major economies are likely to narrow.

Lower bond yields and a dovish Fed tend to support growth stocks due to their sensitivity to interest rates, as their prospective profits are further out into the future. But mega-cap technology stocks, particularly the so-called “Magnificent Seven” (Microsoft, Apple, Alphabet, Tesla, Amazon, Meta and Nvidia), have plunged post-CPI, dragging the S&P 500 index down due to being heavyweights of the index.

Meanwhile, the S&P 500 Equal Weight Index and S&P 500 ex-Magnificent Seven posted gains. The most stunning move was the Russell 2000 (small cap) Index, which surged +3.6% on the day, the biggest outperformance versus the large-cap S&P 500 since 2020. While it’s tempting to extrapolate a one-day move, the CPI report spurred excitement on the resurrection of small cap stocks via a rotation away from valuation-rich mega-cap stocks.

Time for the lightweights to shine?

The obvious reasons for being more bullish on small caps is the rate cuts argument; smaller businesses have struggled in the higher rates environment, whereas mega-cap companies have robust cash reserves that have shielded them.

Positioning is another argument. Given the extended rally in mega-cap tech stocks due to their embrace of artificial intelligence (AI), it’s unsurprising that investors are taking profits on winners and seeking out laggards.

That said, it’s not a foregone conclusion that small caps can persistently outperform. The conditions needed for small caps to outperform are low rates and a robust economic environment (usually at the recovery phase of the business cycle). Small caps tend to lead the markets when coming out of a downturn – but the U.S. economy is not coming out of a downturn, it’s in late cycle. Also, a shallow rate cut cycle is expected, provided there’s no recession.

All in all, lower inflation, rate cuts, and a soft landing are beneficial to the entire market backdrop. We may well be heading into an environment where both small and large caps can prosper. It’s not a zero-sum game, as fresh capital can be deployed as investors become increasingly confident in the outlook.

Index concentration has been raising concerns amongst some investors, so a broadening of the rally is a welcome development and would support a more sustainable long-term rally for the broad indices.

A brighter outlook

Across the Atlantic in the UK, luck is in the air since a new government took office. The outlook for the UK has brightened despite the contentious weather this summer. One notable piece of data to be cheerful of is that the UK gross domestic product (GDP) growth in May (+0.4% MoM) was double that expected by economists.

This means not only did the UK come out of a shallow recession, but activity is recovering faster than expected, with second quarter growth likely to be around 0.6% to 0.7%. This will be a boost to the new Chancellor Rachel Reeves, who wants to make kickstarting economic growth a “national mission”.

With stronger GDP data, a new government that is perceived to bring stability and a pushback on UK rate cut expectations, the pound traded at its strongest level in a year against the dollar, and in almost two years against the euro.

Investors are increasingly singing their praises for UK assets, a huge change from being one of the least popular regions since Brexit. Fundamentally, the pound remains cheap compared to its long-term average and purchasing power parity, whereas UK equities are trading at half the valuation of U.S. equities.

There is indeed room for UK equities to catch up if more international investors upgrade their allocation from negative to neutral or overweight. Our view is that some diversification into the value plays that the UK is so heavily weighted in makes sense at this stage. It can provide a relatively cheap hedge against inflation risks and growth-style equities in portfolios.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

17/07/2024