Team No Comments

Brewin Dolphin – Markets in a Minute – Is U.S. technological supremacy under threat?

Please see the below article from Brewin Dolphin detailing their thoughts on China’s new artificial intelligence (AI) lab and what this could mean for U.S. tech supremacy and their thoughts on the developments related to President Trumps’ trade tariff threats. Received this morning 29/01/2025.

Last week was always likely to be a lively one, beginning, as it did, with the inauguration of the most unorthodox U.S. president in living history, Donald Trump. In contrast to 2017, this version of a Trump presidency seems more organised and able to act faster and more decisively. Political events didn’t dramatically impact the market in either inauguration week, but the greater sense of calm may have been beneficial this time around.

When will Trump impose trade tariffs?

Most major markets performed well, but global investors will have experienced some movement in currencies. The U.S. dollar has lost ground, which probably reflects the fact that tariffs were not imposed on day one of the Trump presidency. U.S. tariffs on imports from Europe, for example, make European goods more expensive for U.S. consumers. As a result, those consumers buy fewer European goods, which means they need fewer euros. This is why, when a tariff is expected, the currency of the country imposing it tends to rise. The effect is to dilute the impact of the tariff, which is why there hasn’t been an improvement in the U.S. trade deficit since the return to the use of tariffs during President Trump’s first term.

Despite this, the threat of tariffs looms large over America’s trading partners. On his first day in office, President Trump claimed 25% tariffs would be imposed on Canada and Mexico by 1 February.

Perhaps acknowledging that tariffs won’t improve America’s trade balance, their use now seems to serve one of two purposes. In Trump’s first term, the threat of tariffs against Mexico and Canada achieved a renegotiation of the prevailing trade agreement. Tariffs against China were imposed and mostly remain, and the bilateral deficit between the U.S. and China has reduced since then. So, tariffs can be threats, temporary measures, or structural impediments to trade, and can be used to reduce reliance on a trading partner.

A Fox news interview with President Trump saw him declare that he didn’t want to impose tariffs on China, affording some relief to a region bracing for them.

Trump was gracious in his praise for China’s President Xi Jinping and North Korea’s Supreme Leader Kim Jong Un, occasionally displaying his fondness for autocrats, which can seem somewhat disturbing. However, he was critical of Russian President Vladimir Putin, whom he’s previously seemed deferential to.

Addressing business leaders at the World Economic Forum in Davos, Switzerland, he appealed to Saudi Arabia to lower oil prices to end the war in Ukraine. A cut in oil prices would be achieved by shipping more oil, which is inconsistent with President Trump’s desire to see America pump more oil, and his desire for Europe to buy oil from the U.S. We have to be wary of placing too much emphasis on Trump’s wish list, which typically includes several mutually exclusive items.

President Trump announces major AI investment

The performance of the U.S. equity market has been broadening out since the election. Although 2024 was a strong year for the ‘Magnificent Seven’ technology-enabled mega-cap stocks (Amazon, Meta, Alphabet, Tesla, Nvidia, Microsoft and Apple), last month saw the group lose ground against the broader market.

That trend was interrupted when the Trump administration announced a major investment in AI infrastructure called Starlink. The Japanese firm Softbank, with support from Abu Dhabi’s investment fund MGX, will fund investment in AI infrastructure led by U.S. firm OpenAI, which it’s claimed could reach as much as $500bn.

The U.S. government isn’t funding the project but is clearing regulatory hurdles. Perhaps this announcement was the biggest surprise of the new administration.

Is U.S. technological supremacy under threat?

Hot on the heels of the Starlink announcement came the news that an upshot Chinese AI lab called DeepSeek appears to have produced an AI model that can rival the Western leaders such as OpenAI and Meta’s Llama. The new model employs a ‘mixture of experts’ system, which involves splitting tasks into distinct groups of similar sub-tasks. Separate models are trained for each of those groups, which echoes the way human tasks were made more efficient through specialisation during the 20th century.

The DeepSeek model was put together with a fraction of the expenditure that went into the current best-performing models and caused ructions in a stock market that’s become very focused on how companies will monetise the benefits of AI.

DeepSeek’s approach implies that a similar quality of model can be achieved with a smaller or inferior set of chips – naturally, this would be very concerning for Nvidia, which is valued on the basis of high volumes of cutting-edge chips. The repercussions for the semiconductor value chain could be material.

A few notes of caution should be considered, though. DeepSeek hasn’t disclosed its training weights and some have questioned how confidently we can trust its development costs. It’s likely selling its product for lower margins than OpenAI. The DeepSeek model does fall short of OpenAI in some specialist processes.

Naturally, many global potential users would be nervous about using a Chinese model due to privacy or censorship concerns. But Western providers should be able to replicate DeepSeek’s open-source model. It might not matter too much for chip demand, though.

In the 19th century, William Stanley Jevons observed that greater efficiency in steam engines caused coal demand to rise rather than decline because it drives greater adoption. The modern world is full of examples of humans doing more of something on the back of technology making it more efficient, rather than taking the savings. Washing clothes, refrigerating (first food, then buildings) or lighting the Las Vegas Sphere are some examples.

So, having more efficient models seems likely to accelerate and expand adoption rather than reduce the demand for chips.

The U.S. has risen to its position of technological supremacy through being open and competitive. One school of thought suggests that massive state-facilitated investment in infrastructure plays to the observed AI scaling laws, whereby increasing parameters and computing capacity will derive better models. But Michael Porter, the authority on competitive advantage, notes that it stems from “pressure, challenge and adversity”.

DeepSeek claims to have achieved this breakthrough despite being limited by U.S. technology export restrictions, which raises questions about whether the United States’ industrial strategy is as foolproof as originally hoped.

How will President Trump impact immigration?

Immigration was a major policy priority, and the new administration took several steps to reduce immigration and prepare to deport unauthorised migrants. Much of this has been achieved by executive order, but legislation requiring the detention of undocumented immigrants suspected of crimes, even if they have not been charged, was passed by the Senate on Monday 20 January.

The legislation was able to pass so swiftly because it was supported by some Democrats. Ultimately, President Trump has discussed deporting millions of unauthorised migrants (estimates assume there are over 11 million in total). Doing so would be costly and logistically challenging. The greatest concern would be that a substantial reduction in workers risks causing inflation. The risk is particularly stark in sectors with high immigrant workforces, such as agriculture. Allowing immigration policy to drive a substantial increase in food prices due to a shortage of workers would be a substantial own goal, which is just one reason the administration is likely to fall short of its target to deport millions of unauthorised migrants.

How is the UK economy faring?

Away from the U.S., the UK’s public finance numbers were released, showing a higher-than-expected borrowing figure of £17.8 billion. However, this includes a one-off investment in military equipment. Excluding this, the borrowing figure would have been significantly lower.

The UK’s bond yields have been underperforming compared to other regions, and the market is pricing in a high probability of an interest rate cut in February.

Although the quality of the UK’s employment data has been poor, it seems there’s a clear trend emerging of slowing jobs growth, which may even have turned negative in the last two months (the data can be heavily revised, so it’s hard to say with certainty).

Retail is a sector that’s particularly under pressure. Retailers are large UK employers and so feel the brunt of the increase in employer’s National Insurance contributions, which was announced in last October’s Autumn Budget.

Sainsbury’s announced last week that it would cut 3,000 jobs and stagger a planned pay increase to reduce costs. Job losses wouldn’t just be on the shop floor; the supermarket plans to cut 20% of senior management positions. 

This week: Earnings season, interest rate decisions and confirmation hearings

This week will be an important one for the fourth quarter earnings season. So far, earnings season has gone well, largely supported by the banks, with decent results from companies like Fastenal, Amphenol and Schwab. The current percentage of beats to misses (the number of companies that have beaten or missed analysts’ earnings expectations) is running slightly ahead of its historical average. This week will include the first of the ‘Magnificent Seven’ (Apple, Microsoft, Meta and Tesla) and broaden out the sectors reporting.

On Wednesday, the U.S. will be setting interest rates. So far, all forecasts are for rates to remain on hold, despite the new president saying he would “demand that interest rates drop immediately”. Analysis of the options market reveals a small but growing expectation that the Federal Reserve’s next move could be to increase rates, rather than cut them. To be clear, the majority view is still that the next move will be a rate cut, but uncertainty surrounding the new administration’s policies has led to a cohort of bond traders betting on an interest rate increase.

President Trump may be happier with Thursday’s European Central Bank meeting, in which interest rates are almost certain to be cut. These meetings come after Japan raised interest rates by 0.25% to 0.5% Friday morning. This was widely expected, so focus was on the Bank of Japan forecasts, which saw a sharp upgrade to expected inflation – so the risks to Japanese interest rates seem skewed to the upside.

There will be more action on the political front too, with confirmation hearings for the new U.S. Secretary of Commerce, Howard Lutnick, and one of the most controversial selections, Robert F Kennedy Jr. as Secretary of Health and Human Services.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

29/01/2025
Team No Comments

Brewin Dolphin – Insight: What can investors expect from Trump 2.0?

Please see the below article from Brewin Dolphin examining the potential impact on the global investment landscape of a Trump administration. Received yesterday 27/01/2025.

The President Trump reboot has well and truly arrived. We may be just a few days in, but the implications for the global economy and investors are already starting to take shape.

As we navigate this new landscape and a flurry of executive orders are signed, it’s first worth remembering what powers the president has and how he might like to wield them.

The power of the President

As President, Trump leads the executive branch of government, which is responsible for enforcing laws. Congress writes those laws, although in modern times, the President has a significant influence over their drafting. If Congress drafts a law without the President’s input, he can veto it.

This separation of powers checks the President’s power. However, Trump’s Republican Party controls Congress and in his first term he also gained significant influence over the third branch of government, the judiciary (courts), therefore reducing the check’s effectiveness.

The President also uses executive orders, instructions from the President to a federal agency to undertake a specific action. Unlike laws passed by Congress, executive orders can’t spend money or change taxes, but do offer Presidents significant power over non-budgetary matters.

These arrangements haven’t changed since President Trump’s first presidency. What has changed is his team…

Team Trump unites

There is a greater cohesion at the start of this Trump presidency. In 2017, members of his own team sought to water down or delay some of his initiatives. In 2025, the Trump administration seems to be pulling in the same direction.

But what is that direction?

Since the election, the three main categories the administration has been targeting have remained broadly the same.

Trump and taxes

Policy direction

Trump’s first term saw sweeping tax cuts across personal and corporate taxes, some of which are due to expire during 2026. Given he campaigned on a pledge to lower taxes for this election, his priority will be to ensure that those existing cuts are made permanent or extended. He may even try to cut taxes further, particularly for companies producing goods in the U.S.

The reality

As mentioned, these budgetary processes need to pass through Congress, which will probably feel compelled to rollover existing tax cuts. One major obstacle to further tax cuts is the U.S.’s substantial budget deficit, which stood at over $1.8 trillion for the 2024 financial year and took U.S. national debt to over $35 trillion. Given this challenge, achieving additional tax cuts appears to be a difficult goal.

The impact

If taxes can be cut, it could encourage consumers to spend more, which would bolster U.S. growth. Typically, this would lead to increased employment. However, with low unemployment there’s limited scope for this, so tax cuts might instead lead to inflation. Considering these factors, the most likely outcome seems to be a continuation of existing tax cuts, with only minor additional cuts. Whatever the decision, it will likely take weeks if not months of negotiation.

On his other goals, President Trump has been able to act faster…

Trump and immigration

Policy direction

Trump has been outspoken about the need to rein in immigration and has also discussed deporting millions of unauthorised migrants (estimates assume there are over 11 million in total).

The reality

Trump has already taken several steps to reduce the number of immigrants and prepare to deport unauthorised migrants. Much of this has been achieved through executive order, but legislation passed through Congress within days, requiring the detention of migrants suspected of crimes, even if they haven’t been charged. This legislation was passed swiftly because it was supported by some Democrats. Ultimately, President Trump’s efforts in this area are likely to continue.

The impact

There is undoubtedly a substantial human cost associated with deporting unauthorised migrants, one that should be deeply considered. It will also come at a significant monetary cost and pose considerable logistical challenges. However, the greatest economic concern is that a substantial reduction in workers could risk causing inflation, particularly in sectors with high immigrant workforces, such as agriculture.

Allowing immigration policy to drive a significant increase in food prices due to a shortage of workers would be a substantial own goal. This concern is just one reason why the administration is likely to fall short of its unauthorised migrant deportation targets.

Trump and tariffs

Policy direction

One of Trump’s key objectives is to win benefits for America by imposing taxes on imports (tariffs).

The reality

President Trump immediately ordered a series of investigations which are a precursor to imposing tariffs. On his first day in office, he claimed 25% tariffs would be imposed on Canada and Mexico by 1 February 2025.

Tariffs serve multiple purposes within Trump’s world. In his first term, tariffs on Chinese imports aimed to reduce imports from a strategic rival, with debatable success. Alternatively, Trump has used tariffs as bargaining chips to renegotiate trade agreements, as demonstrated against Mexico and Canada in his previous term. So, tariffs can be threats, temporary measures, or structural impediments to trade.

The impact

The direct economic impact of tariffs is to discourage trade. This means in the first instance, it’s likely to reduce economic activity for net exporters and increase it for net importers. This has been reflected in stronger U.S. economic growth expectations for the U.S. relative to other regions.

Tariffs will also increase prices. A price increase is inflationary, but only for imported goods. Typically, this effect is temporary as tariffs are a one-off increase in cost. Tariffs may be charged on imports, but those higher prices are paid for by consumers and, with inflation high on voters’ priority lists, excessive use of tariffs could be unpopular.

Generally, if one country imposes tariffs, the target of those measures will impose countervailing (retaliatory) tariffs. So far, countries have been cautious about responding to Trump’s threats, waiting for a clearer sense of what will be enacted and what is mere rhetoric. For the UK, it’s unlikely to be a major target of the Trump administration’s trade policies given its trade deficit with the U.S.

In a speech to the World Economic Forum last week, Trump also complained about European sales, or value added, taxes. These are often seen as barriers to trade, as imports are subject to the local sales tax, while exports aren’t. The interactions between VAT and trade are complex, and research has cast doubt on the intuitive belief that VAT enhances export competitiveness. However, Trump is an intuitive individual and may threaten tariffs until European sales taxes are dropped. This might seem like a welcome outcome for UK consumers, but like all taxes, if VAT was cut, something else would need to rise to replace lost revenue.

What about deregulation?

Underlying the President’s agenda is a broad thrust of deregulation, including environmental policy. This aims to ease investment in the U.S. and boost American economic capacity.

The President has ordered Federal waters to be made available for oil drilling, which could add to U.S. growth and help to moderate inflation. Meanwhile, Trump has once again ordered that the U.S. withdraws from the Paris Climate Agreement.

Perhaps the biggest surprise of the new Trump administration has been the announcement of a major investment in artificial intelligence (AI) infrastructure, led by U.S. firm OpenAI and backed by Japanese firm Softbank and Abu Dhabi’s AI investment fund. The U.S. government is not funding the project but is clearing regulatory hurdles for the deal, which is valued at up to $500bn. 

A new era of uncertainty?

In the weeks leading up to and following President Trump’s election victory, financial markets anticipated higher inflation, and the early days of his presidency have done little to dispel this expectation.

Trump’s economic policies aim to stimulate growth through deregulation and tax reform. However, this growth may come at the expense of other regions due to the implementation of tariffs.

The upshot is that U.S. stocks or companies exposed to the U.S. economy are likely to enjoy the thrust of the new government’s policies more than other regions (perhaps unsurprisingly). According to the International Monetary Fund (IMF), among advanced economies, the U.S. is stronger than previously projected on continued strength in domestic demand. The IMF raised its growth projection for the U.S. this year by 0.5%, to 2.7%, as a result.

However, overly vigorous immigration policy and tariff enforcement could potentially restrict economic growth or exacerbate inflationary pressures. In this context, the President’s repeated threats to influence interest rate policy have been unsettling to bond markets. For now, this has resulted in higher yields than those seen in the months preceding the election, making them attractive to investors. Nevertheless, just how fast and loose President Trump is willing to play with inflation will need to be monitored closely.

While most actions taken so far align with pre-election expectations, the early days of the administration have not resolved many of the uncertainties either.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

28/01/2025

Team No Comments

Tatton Investment Management – Monday Digest

Please see below, this week’s Monday Digest from Tatton Investment Management, analysing the key factors currently affecting global investment markets:

Is the Trump trade still on? 

Capital markets were a sea of green in Donald Trump’s first week back. US investors like his tax cut, deregulation agenda, but we have argued they might be underestimating the risks. Britons and Europeans might be biased though – as one survey revealed we are among the most pessimistic about what Trump means for our own futures. US investors think Trump’s threats are “the art of the deal” and the early interactions with US trading partners suggest they might be right. Even so, political volatility can frustrate policy – as in Elon Musk’s recent disagreements with some of Trump’s announcements. 

Not all the US optimism is about the Trump trade, though. US economic data is strong and the Federal Reserve has made some dovish signals. That has led to increased demand for government bonds, whose yields look attractive. The most in-demand have been UK gilts – whose yields have now sunk below the US, despite predictions of UK fiscal disaster. A record oversubscribed bond auction last week showed international investors are more than happy to lend to the treasury. 

The flipside of investors putting America first has been many putting Europe last. There was talk of “peak pessimism” on Europe at the World Economic Forum in Davos, but it’s notable that European stocks have been performing very well in total return terms this year. Business sentiment surveys suggest that Europe’s fortunes may be turning: European businesses are gaining confidence, while Americans are seemingly losing it. We should note that the US numbers are likely obscured by the Trump transition and should return to positivity, however.  

European leaders have also expressed a desire to work with Trump and expand their military spending – as he has long demanded. That would effectively mean fiscal expansion, the short-term growth benefits of which shouldn’t be underestimated. We have argued for a while that, despite the doom and gloom, there is a plausible recovery scenario for Europe. More people seem to now believe it.  

How valuable is a Trump meme? 

Cryptocurrency traders are big fans of Donald Trump – but the new president angered many in the industry when he launched he and his wife each announced their own memecoins on the eve of inauguration. $TRUMP soared then quickly sank, and many criticised it for undermining faith in digital currencies. A crypto-friendly executive order, signed this week, went some way to redeeming him in the industry’s eyes, but inflating memecoins does nothing to help cryptos in the long-term. 

Trump promises to be “the most pro-crypto president” ever, and Bitcoin prices hit a new all-time high after his inauguration. Crypto traders hope that a friendly White House will accelerate adoption and overcome the reputation of volatility and excess that has kept cryptos out of the mainstream. 

$TRUMP and $MELANIA don’t help that reputation. Memecoins are speculative by nature – with prices based purely on the popularity of the meme – and hence some in the industry accused the president of corruption, using his position to boost his wealth. The irony is that the “speculative bynature” critique is often levelled at cryptocurrencies broadly. We suspect some of the anger might be down to nerves at how stretched the crypto rally has become, and the frothy trading in lesser known tokens. 

Cryptocurrencies are slowly entering the investment mainstream, but we still don’t consider them appropriate for our portfolios, because they are fundamentally hard to value. The technology underlying them – most notably blockchain – does have value in its economic potential, however, as do companies that trade in such assets and technologies. Crypto-related assets might be appropriate for long-term investors, but for cryptos themselves to be appropriate, we need to see broad acceptance and commonly agreed valuation methods. Trump’s policies might eventually help that, but inflating your own memecoin bubble does the opposite.  

The changing commodity outlook 

Commodity prices have been on a decent run over the last month, but the price outlook is uncertain because of global growth uncertainty. In general, we expect a near-term cyclical boost followed by long-term oversupply – but this varies across different commodities. 

The oil market was oversupplied in 2024, but prices were supported by OPEC+ production cuts and geopolitical scares. Oil could rally from here, due to US sanctions on Russian shipping and the strength of US demand, but the longer-term outlook is less promising. President Trump plans to boost US production, and tariffs could weigh on demand.  

The natural gas outlook is similar: supplies are currently tight (mainly in Europe) but Goldman Sachs expect a long-term boost in liquified natural gas (LNG) supplies from the US and Qatar. Some expect this to be outweighed by demand increases owing to AI datacentres, but we don’t see much evidence of this yet.  

The exception is China, where energy demand has been strong and will likely continue thanks to government stimulus and efforts toward the green transition. This will benefit copper prices more than steel – which has traditionally rallied on Chinese stimulus.  

Goldman Sachs expect last year’s gold rally to continue, as central banks keep buying the precious metal to diversify away from the dollar and hedge against inflation and geopolitical risks. Trade risks from Trump tariffs will likely mean more gold buyers.  

Higher near-term commodity prices mean more inflation pressures. This might force the Federal Reserve to keep interest rates high, given US economic strength, but the European Central Bank is likely to ‘look through’ any spike and support its weak economy. The ECB will be particularly pleased if Goldman Sachs are right about the LNG supply glut. While that is a long-term consideration, it would remove the biggest headwind for European growth. The supply-demand balance could look very different in a few years. 

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

27th January 2025

Team No Comments

EPIC Investment Partners – The Daily Update | The Road to Neutral

Please see below article received from EPIC Investment Partners this afternoon, which provides market predictions for 2025.

As next week’s FOMC meeting approaches, we turn to our proprietary Fed funds model for insights into the likely path for US interest rates. Developed in the 1990s, the model analyses US capacity utilisation, unemployment, and inflation to predict the appropriate federal funds rate. While the neutral rate—or r-star—represents the interest rate that neither stimulates nor restricts growth, the model focuses on projecting short-term policy adjustments by analysing capacity utilisation and unemployment. At present, the federal funds rate remains above the neutral level, estimated at roughly 3%. 

Capacity utilisation, a key indicator of economic slack, currently stands at 77.6%, below its historical average. This underutilisation signals room for economic growth without triggering inflation, providing scope for a more accommodative policy stance. With inflation expectations anchored at 2% and a real rate of 0.5–1%, the neutral rate is estimated at approximately 2.5–3%, serving as a benchmark for evaluating monetary policy. Historically, periods of below-average capacity utilisation have supported lower rates, as slack reduces inflationary pressures. While a pause in rate adjustments is likely in January, gradual cuts toward this neutral range seems likely as 2025 progresses. 

The neutral rate is closely tied to capacity utilisation and unemployment, key inputs in our Fed funds model. While the model does not explicitly estimate the neutral rate, it aligns federal funds rate predictions with prevailing economic conditions, reflecting shifts in these metrics. Periods of high slack, for example, signal the need for lower rates, aligning policy with prevailing economic conditions. 

Market expectations for 2025 broadly align with the model’s forecast for federal funds rate adjustments, which consider both economic slack and inflation trends. Despite the uncertainty surrounding fiscal policies under the current administration, the economy remains below the conditions needed for a neutral monetary policy stance. Monetary policy remains restrictive, with rates above neutral estimates. A pause during the January meeting would provide an opportunity for the Fed to evaluate incoming data and refine its outlook. Should inflation continue to moderate alongside subdued capacity utilisation, a gradual shift toward the neutral rate is expected as economic slack persists and inflation moderates. However, the transition will require careful calibration to prevent reigniting inflationary pressures or undermining growth. 

Further Fed easing sets the stage for opportunities in fixed-income markets. Looking through the uncertainty of fiscal policies, higher-quality investment-grade emerging market bonds are particularly well-positioned to benefit from declining interest rates and stabilising global economic conditions. Mexican credit, in particular, looks attractively valued, offering compelling opportunities for investors looking for opportunities to diversify. These assets combine robust credit profiles with attractive yields, making them a compelling choice for investors looking for alpha opportunities. With risk sentiment likely to improve alongside monetary easing, 2025 offers a favourable environment for higher quality emerging market debt. 

Please check in again with us soon for further relevant content and market news.

Chloe

24/01/2025

Team No Comments

EPIC Investment Partners: The Daily Update | Europe’s ‘Existential Challenge’

Please see below, an article from EPIC Investment Partners providing a brief analysis of the current economic conditions within Europe. Received today – 23/01/2025

At the World Economic Forum in Davos, Christine Lagarde delivered a sobering assessment of Europe’s economic landscape, warning of an “existential crisis” that demands immediate attention. The ECB president highlighted the continent’s vulnerability to the US’s shifting global economic strategy, particularly in light of Trump’s “America First” policies. 

The economic outlook paints a challenging picture. The IMF forecasts a meagre 1% expansion for the eurozone, starkly contrasting with the US’s projected 2.7% growth. Germany, Europe’s largest economy, has experienced two years of contraction and is expected to grow by only 0.3% this year. 

Deep pessimism about Europe’s economic prospects has been discussed by several key economic figures. Concerns mounted around several critical issues: leadership challenges in Germany and France, the rise of far-right movements, technological regulation uncertainties, and the overall strength of the European Union. 

Ursula von der Leyen, European Commission president, acknowledged the stakes, emphasising the importance of preserving transatlantic trade relations. With bilateral trade volumes at €1.5tn, both sides have significant interests at risk. 

The challenges extend beyond economic metrics. Technology and AI regulation emerged as crucial battlegrounds, with one executive warning that a conservative approach could further marginalise Europe. The continent faces pressure to adapt quickly to evolving global economic and technological landscapes. 

Despite the gloomy forecast, some voices of optimism emerged. Spain’s economy minister, Carlos Cuerpo, highlighted his country’s strong performance, with estimated growth of 3.1% last year, outpacing the US, coupled with a booming labour market. 

On a further positive, solar power marked a pivotal moment in the European Union’s energy transition last year, generating 11% of electricity and surpassing coal’s 10%. Solar generation increased by approximately 22% to around 304 terawatt hours, while coal power fell nearly 16% to about 269 terawatt hours, reflecting a broader shift away from fossil fuels. With wind and solar now comprising 29% of EU electricity generation and countries like Germany and Poland reducing coal usage, Europe is making significant strides towards a more sustainable energy future. 

Please continue to check our blog content for the latest advice and planning issues from leading investment managers.

Alex Kitteringham

23rd January 2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 21/01/2025

There was something quite abstract about having a big week of economic data in the final run-up to the inauguration of a U.S. president who’s promised to shake things up.

Analytically, we can go through the motions, identify the outliers and the seasonal discrepancies, and take a view on the likely trajectory of the economy going forward. But we also need to appreciate that some things are likely to change with the new administration.

Returning to the here and now, inflation was the major focus last week, with the U.S. reporting producer and consumer prices data. The UK also reported its inflation data on the same day. This would normally be of only local interest, but with UK bonds having underperformed, and a measure of political pressure building on the UK government over its handling of the economy, gilts have threatened a return to infamy.

And what did the data tell us?

UK inflation was below expectations, which was very well received by the market, and likely very welcome in the halls of government. The decline in the headline inflation rate was marginal, but it’s core inflation, which strips out the volatile food and energy prices, that’s been the thorn in the UK economy’s side. It slowed from 3.5% to 3.2% per annum.

This was excellent news, and enough to see UK government bonds rallying. However, there was a fairly hefty caveat. Although food and energy prices are stripped out, other volatile prices aren’t.

A good example of these would be airline fares, which fluctuate wildly – not just from month to month, but even from day to day. They typically rise as the Christmas holidays begin but drop sharply on Christmas Eve and New Years Eve when few people want to travel. These dates were used to measure return flights for European and long-haul flights and would therefore have depressed the overall figures. It means that air fare inflation seemed to rise less than previous years.

Despite this, measures we like to follow continue to point to further disinflation. The rise in the median consumer price index (CPI) category was lower than last month, and services inflation had already slowed in recent months. Overall, core inflation may have been a little flattered by the measurement of air fares, at 3.2% per annum. It remains too far above target, but has been coming down, and should continue to do so.

The UK differs from the U.S. in an important regard. Persistent U.S. inflation could be ascribed to the strength of the country’s economy. Strong retail sales growth indicates that growth is likely to be at an annual rate of around 3% in the final quarter. In the UK, Thursday’s quarterly gross domestic product (GDP) data and Friday’s retail sales data were both very weak.

The strength of the U.S. economy, and the ensuing rise in U.S. and global bond yields, meant there was a lot of anticipation for higher U.S. inflation data. Indeed, prices rose faster in the U.S. over December, reflecting the rise in oil prices. But the core measure of inflation slowed without any of the irritating statistical gremlins that plagued UK inflation figures. The market reaction has been surprisingly strong to a modest undershoot of one measure of inflation. This is an indication of how nervous investors had been about the prospect of a re-acceleration in prices.

There’s been room for optimism as far as inflation data is concerned but that, as economists like to say, is ceteris paribus (all other things being equal). But we know that all other things won’t be equal.

How will a second Trump presidency differ from the first?

On Monday, Donald Trump was sworn in as the 47th President of the United States, and it’s looking like he’ll hit the ground running with early policy measures.

During his first term, Trump was politically intuitive but inexperienced and unconnected. He struggled to build a team to implement his policies and ended up relying on the Republican Party establishment to suggest colleagues and advisers. These included members of the administration such as Steven Mnuchin (Secretary of the Treasury), Gary Cohn (Chief Economic Adviser) and Rob Porter (White House Staff Secretary), who didn’t share the president’s agenda and worked against it. Consequently, it was a year before any tariffs were actually announced.

This time around, the Trump administration has prepared better, and Trump himself has built a team around him who are ideologically aligned (mostly). There are differences, but those are more likely to be evident later in the presidency.

Some members of President Trump’s administration, such as Scott Bessent, who’s been nominated as Treasury Secretary, see tariffs as more of a bargaining chip. Imposing tariffs now enables the administration to seek concessions in other policy areas. The most obvious example is encouraging other NATO members to invest in defence (U.S.-made defence) on pain of tariffs.

Other members of the administration, such as Peter Navarro, one of the few survivors of Trump’s original administration, consider tariffs against China at least to be a means of permanently moving away from economic integration with a strategic rival.

The above is an example of the nuance that can exist within a particular policy area amongst an aligned group of individuals. But there are multiple policy areas that have the potential to impact the economy. Tariffs are relatively easy to understand, even if we don’t yet know how broad they’ll be. Tariffs are also inflationary. They raise prices, albeit only on imported goods. Because goods form a small and declining share of the CPI basket, the impact will be limited, at least initially.

How will Trump’s policies impact the U.S. labour market?

The greater question is about the impact of immigration controls on the U.S. labour market. After data released in early January showed strong growth in employment, and with surveys suggesting that companies expect to hire more staff due to greater economic optimism, the availability of staff may become a big issue (as it was during 2022).

Exactly how many undocumented migrants President Trump will be willing and able to deport remains to be seen. It may only need a reduction in migration to start reducing the supply of workers and trigger renewed inflation. This is particularly true in the agriculture sector, which utilises a lot of migrant workers.

This will be amongst the key policy areas to watch out for announcements now that Trump has been inaugurated.

Finally, it’s worth mentioning the beginning of earnings season on Wednesday, which saw a buoyant start. As always, it was the banks that marked the unofficial start. Generally, their results were strong. Net interest margins have risen as savers feel less inclined to shuffle their savings around seeking the optimum rate available. Meanwhile, the big investment banks made large profits from trading bonds around the U.S. election, an early benefit of the new president.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

22/01/2025

Team No Comments

Brooks Macdonald The Daily Investment Bulletin

Please see the below article from Brooks Macdonald detailing their thoughts on a recently sworn in Trump administration. Received this morning 21/01/2025.

What has happened

With US financial markets closed yesterday, investors instead watched Donald Trump being sworn in as the 47th US president. President Trump subsequently wasted no time in signing a raft of executive orders tightening immigration, ending green energy incentives in favour of oil and gas, and (albeit late in the day yesterday) planning tariffs on Canada and Mexico. Equity futures markets, which had earlier rallied on the lack of tariff news, subsequently retraced some of those gains, while the US dollar which had weakened earlier in the day, saw a jump up against most major currencies.

Trump ends green energy incentives

US President Trump yesterday ordered an “immediate pause” in spending on clean energy and other climate initiatives, deriding former US president Biden’s signature climate law (the ‘Inflation Reduction Act’) as the “green new scam”. Trump also ordered the US Environmental Protection Agency to consider eliminating the ‘social cost of carbon’, a metric used to help justify environmental policies. Earlier in his inaugural address, Trump defended a renewed energy focus on oil and gas production, saying that “we have something that no other manufacturing nation will ever have: the largest amount of oil and gas of any country on earth. And we are going to use it”.

US Trump trade tariff plans

Overnight, President Trump has said he plans to impose previously threatened trade tariffs on Canadian and Mexican imports into the US, saying that “we’re thinking in terms of 25% on Mexico and Canada … I think we’ll do it February 1st”. Trump also threatened to apply higher tariffs on Chinese imports as well as tariffs on European Union imports. However, while Trump indicated he was still considering a universal tariff on all foreign imports to the US, he added that he was “not ready for that yet”.

What does Brooks Macdonald think

In the past 24 hours, financial markets have had an early reminder of what life will be like under a US Trump administration. In particular, overnight we have seen volatility in markets as an initial relief around the absence of immediate sweeping tariffs has given way to nerves following Trump’s announcements of his Canada and Mexico trade levy plans late in the day. One early takeaway from all this is that Trump is likely to be highly ‘transactional’ in his approach to tariffs as well as other policy areas too potentially – that could make it very hard indeed for investors to anticipate and plan for overall policy narratives and expected economic and market impacts.

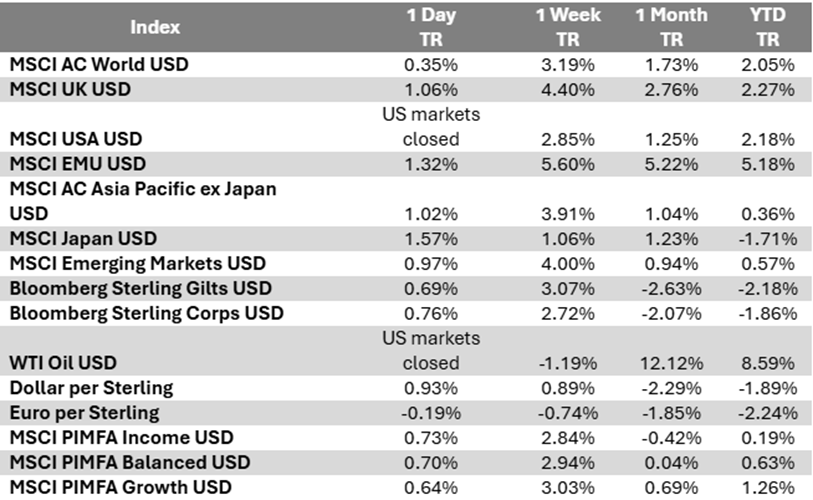
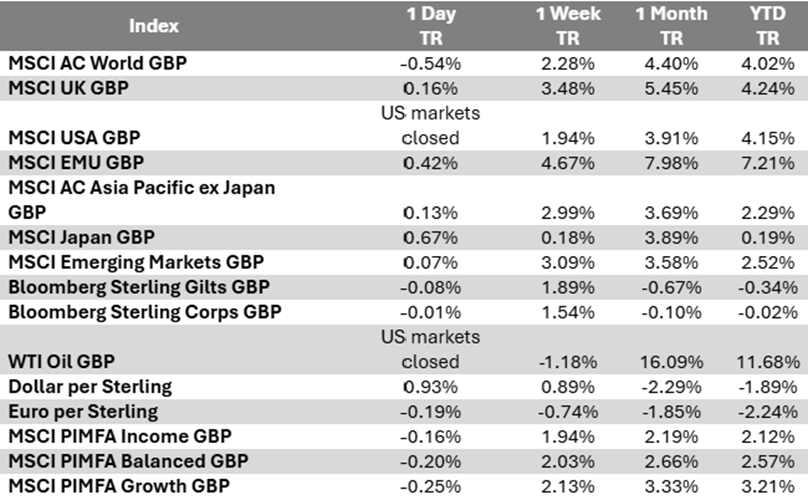
Bloomberg as at 21/01/2025. TR denotes Net Total Return.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

21/01/2025

Team No Comments

Tatton Investment Management – Monday Digest

Please see below, this week’s Monday Digest from Tatton Investment Management, analysing the key factors currently affecting global investment markets:

Calmer markets ahead of Trump inauguration 

Global stocks bounced back 2% last week and bond markets calmed. UK investors did not even have to rely on a weak pound to boost sterling-based returns. UK government bonds recovered from the previous sell-off, as we cover below. Lower-than-expected inflation data for December makes an interest rate cut at the Bank of England’s (BoE) next meeting likely, and there was a refreshingly dovish speech from one BoE committee member. Annual inflation will almost certainly go up (due to higher energy prices) but we have argued the BoE should ‘look through’ near-term inflation and at least one BoE official seems to agree.  

Markets were also worried about sticky US inflation, but those fears receded. December’s inflation report was in line with expectations, but investors reacted as though it was lower. The most encouraging signs are slower wage growth (despite job gains) and a smaller contribution from the shelter component. High interest rates are still compressing activity, which gives the Federal Reserve scope to cut. Global markets would welcome that, considering recently tighter financial conditions – thanks in large part to the strength of the dollar. 

Tight liquidity conditions might mean downgrades to global growth forecasts this year – which will hurt smaller companies in particular. Notably, last week’s equity bounce-back became much more focussed on the mega-caps as the week went on, having initially started in small-cap. Oil prices also increased, but that looks like a pure supply-side story, following US sanctions on Russian shipping. Geopolitics are uncertain ahead of Donald Trump’s inauguration – but hints are the Ukraine will be a top priority, and that Trump could be more supportive of Ukraine than most assume.  

Trump’s second term brings uncertainties but potential rewards. It helps that we start it with calmer markets than a week ago. Long may that continue.  

Gilt and anxiety 

Thankfully, UK government bonds (gilts) calmed down this week. The previous spike in gilt yields was led by higher yields elsewhere, but exacerbated by concerns over Britain’s economy and government fiscal policy – which many feared would lead to persistent ‘stagflation’ (no growth but high inflation). This then hit the same structural gilt market weakness revealed after the Liz Truss ‘mini budget’ in 2022: pension funds’ overexposure to volatile inflation-linked gilts. You might have expected pension funds to end their overexposure after that crisis, but the Bank of England settled the gilt market and meant funds reduced rather than closed their positions. Recent gilt volatility reignited the problem.  


We said last week that this panicked selling made long-term gilts very cheap. Theoretically, long-term real (inflation-adjusted) bond yields should represent the market’s expectations for long-term economic growth. One of our preferred measures for this (constructing a theoretical future bond out of 15-year and 30-year yields) spiked above 2.5% last week, which suggests strong growth despite all the commentary focussing on the UK’s weaker long-term growth prospects. This suggests that gilt panic was more about short-term sentiment than long-term expectations and long gilts are a good buying opportunity.  

Sure enough, gilt traders took the buying opportunity this week, pushing yields down from their highs and putting them once again in line with US yields. This was helped by the government reiterating its commitment to fiscal discipline and, particularly, unexpectedly low inflation data from December. This settled the nerves and allowed investors to appreciate how cheap long-dated gilts are. The narrative that gripped gilt markets last week always looked too dire to be true; this week’s news made it even less convincing. We shouldn’t expect plain sailing – given the UK’s uncertain outlook – but historically high yields make long-term gilts look good value. 

More to come from India 

India has had huge success in the last few years, but positivity has faded in recent months. Its stocks are up 30% since the start of 2023 and GDP grew 8.2% in the 2023-24 fiscal year. Foreign investors have sold out of India since the autumn, though, and growth has slowed. Interestingly, capital outflows have coincided with investor optimism about China, following Beijing’s stimulus announcements. Realignment away from China was previously helping India in trade and investment terms, and it looks like the sentiment about the two markets mirror each other.  

Economists expect the Reserve Bank of India (RBI) to cut interest rates next month, but inflation is still high and the rupee has fallen sharply against the dollar. Currency weakness will likely be inflationary, given India imports 90% of its oil. But, the RBI isn’t independent (the government installed a more dovish governor just last month) and seems comfortable letting the rupee slowly decline. India has consistently higher inflation than elsewhere, which means its currency is losing its real value quicker than other nations – a recipe for further declines. 

The RBI’s dovishness makes sense when you consider purchasing power, though. The rupee’s recent slide hasn’t been by as much as the difference between Indian and global inflation. That effectively means the rupee’s purchasing power has increased; Indians are able to buy more, despite the weaker currency. That’s what you expect in a strong economy, but policymakers won’t want India’s purchasing power to increase too quickly, as that would undermine the cheapness that has boosted Indian trade and investment. A managed decline in the rupee is therefore reasonable.  

The long-term case for India is strong, despite the recent decline in foreign investor sentiment. It’s based on long-term trends of domestic economic reform and global trade realignment – which both have room left to run.  

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

20th January 2025

Team No Comments

EPIC Investment Partners – The Daily Update | Demographic Deflation: The Bond Trade You are Missing

Please see below article received from EPIC Investment Partners this morning, which provides a global market update.

Despite US Treasury yields suggesting higher growth and inflation in the years ahead, demographic trends tell a different story. By 2033, annual deaths in the United States will surpass births, leaving net migration as the sole driver of population growth, according to the Congressional Budget Office (CBO). Without sufficient immigration, the population would shrink, undermining economic growth, worsening fiscal pressures, and intensifying the challenges of supporting an ageing society. 

Recent OECD data starkly illustrates the issue: the working-age population’s growth rate has fallen to just 0.15%, sharply down from its peak of 2.24% in July 2000. Declining birth rates and an ageing population are primary drivers, but restrictive immigration policies have further compounded the slowdown. 

From 2017 to 2021, annual net migration averaged only 750,000, a significant reduction driven by stricter border enforcement, reduced refugee admissions, and tightened visa restrictions. The CBO projects net migration to average 1.4 million annually in the coming decades, but this estimate appears overly optimistic given persistent political resistance and growing global competition for skilled migrants. 

The stakes are immense. Without sufficient immigration, the US faces a shrinking workforce and fewer taxpayers to support an expanding number of retirees. Social security and healthcare systems, already strained, will face widening funding gaps, increasing the fiscal burden on younger generations. Slower economic growth would further constrain the government’s ability to meet its obligations, driving the debt-to-GDP ratio even higher. 

Demographic shifts also reshape inflation and interest rate dynamics. A shrinking population reduces demand, creating deflationary pressures akin to those seen in Japan, where decades of demographic stagnation have coincided with weak growth and persistently low inflation. In the US, these deflationary trends could partially offset upward pressures on interest rates caused by sustained fiscal deficits. 

Immigration is the clearest solution. Migrants not only fill labour shortages but also sustain demand and drive innovation. Between 2000 and 2018, immigrants accounted for nearly half of the growth in the working-age population. However, countries like Canada and Australia are actively competing for talent, adopting aggressive immigration policies that threaten to outpace the US. To remain competitive, the US must streamline visa processes, expand pathways for high-skilled workers, and implement integration programmes. 

The bond market’s pricing, reflecting expectations of sustained growth and inflation, conflicts with long-term demographic realities. Projections for net migration must be realised to avoid population decline. If migration fails to meet these expectations, the US risks slower growth, intensifying fiscal pressures, and reduced global competitiveness. 

Given these demographic and fiscal constraints, long-term bond yields appear too high. A return to zero-bound interest rates is plausible as debt servicing and demographic stagnation exert downward pressure. Persistent budget deficits make the current debt trajectory unsustainable, underscoring the urgent need for deficit reduction and immigration reform. Without these changes, a disruptive market correction may ultimately enforce this reality. 

Please check in again with us soon for further relevant content and market news.

Chloe

17/01/2025

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 14/01/2025

We may never know whether former Prime Minister Liz Truss was thinking “this is my moment” while her chancellor delivered the government’s growth plan (known colloquially as the mini-budget) to the House of Commons. It has, however, been known ever since as the ‘Liz Truss moment’ and has become shorthand for markets dumping a country’s assets in protest of an unsustainable tax and spending plan.

‘Liz Truss moment’ ranks alongside ‘Lehman Brothers moment’ as a descriptor of a severe market reaction. But perhaps it bears more in common with the more dramatically named ‘Black Wednesday,’ which the UK suffered in 1992 when it was forced to devalue the pound and leave the European Exchange Rate Mechanism (ERM).

In that instance, the Bank of England (BoE) was charged with maintaining the pound’s level within a 6% band against other members of the ERM. The band was too high for the UK, and as the pound started to slide out of it, the BoE was charged with buying sterling to bolster it. The central bank couldn’t, however, hold back a tidal wave of speculative flows betting that the pound would eventually be allowed to fall. Inevitably, it eventually did.

In doing so, many argue, the markets caused a devaluation that enabled the UK economy to emerge from recession, which the government’s misguided exchange rate policy may have prevented.

The all-powerful market

The similarity between that event and Liz Truss and Kwasi Kwarteng’s mini-budget was that the market showed itself to be more powerful and influential than the government. This is something that motivated Bill Clinton’s political adviser James Carville’s famous quote: “I used to think that if there was reincarnation, I wanted to come back as the president or the pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.”

The bond market, in these instances, is sometimes referred to as a group of bond vigilantes; individuals who enforce the law despite having no authority to do so. They differ, of course, from true vigilantes, who would be motivated by civic duty. This is because bond vigilantes are motivated by self-interest alone, with occasional policy improvements being a happy consequence rather than an objective.

Is this a ‘Liz Truss moment’?

That was then, this is now. After the mini-budget, UK ten-year borrowing costs reached 4.5%; they are 4.8% now. So, is Chancellor Rachel Reeves now having her ‘Liz Truss moment’?

The most obvious similarities are the adjacency to a budget, and the unusual phenomenon of a falling currency more-or-less coinciding with rising bond yields (which would normally attract foreign bond buyers).

The last UK budget was the end of October. In it, the chancellor, who had criticised Truss for having crashed the economy with a debt-fuelled tax-cutting programme, announced a debt and tax-fuelled spending programme. It was poorly received by the market, although the dominant emotion was probably disappointment rather than shock.

Here was a former BoE economist, who had been the shadow chancellor of the exchequer for three years. Reeves came with the endorsement of former Bank of England Governor Mark Carney and had committed to not raise taxes on working people. So, a budget that delivered a big increase in borrowing, and a big increase in employment taxes was very underwhelming.

However, it was less shocking because Reeves had at least allowed scrutiny by the Office for Budget Responsibility (OBR), and there was some recognition that she was facing an almost impossible task (improving public services whilst maintaining any semblance of fiscal credibility).

Therefore, there wasn’t the same dramatic reaction as to the Truss budget, but borrowing costs have risen and now eclipse those seen during the crisis. A lot of that reflects rising yields globally, particularly since the U.S. election. In fact, the degree to which the UK stands out is small but significant.

Why is the UK in the crosshairs?

There are a few possible reasons. It could reflect the UK’s higher inflation during 2022/3, although in truth it wasn’t much worse than the Eurozone. The UK’s budget deficit is wide relative to many developed economies, but not the U.S. or France, whose bonds have been less weak. Wage growth has been more persistent in the UK than in the U.S., which makes it harder for the BoE to cut interest rates. 

It may partly reflect the political system and budget process in the UK. As the government has an enormous majority, it’s in a much stronger position to pursue a tax and spend policy if it desires. Other countries tend to see protracted periods of negotiation amongst different parties, allowing the markets to absorb and respond to proposed spending increases more gradually.

It could be argued that the Labour government is faced with relatively few institutional constraints due to its parliamentary majority. However, political and market constraints remain. Ensuring the market gains or regains confidence in the government is a function of maintaining the right rhetoric. The Treasury stated on Wednesday that, “no one should be under any doubt that meeting the fiscal rules is non-negotiable and the government will have an iron grip on the public finances”. Then it needs to ensure that actions follow that rhetoric.

The chancellor has set fiscal rules that, at current interest rates, she seems on course to break. Therefore, she may need to consider government spending cuts or tax increases if interest rates don’t drop by March when the next OBR forecasts are prepared. 

Will UK taxes be rising again?

Whether UK taxes will be raised depends on a few factors.

The most obvious is the outlook for the UK economy. If the economy remains strong, interest rates will remain high, and the government’s headroom will be diminished. If the economy were very weak, welfare payments would increase. Ideally, continued positive growth with an ebbing of inflation is needed.

In the UK, a rise in government bond yields has a fairly direct impact on the economy. It means that swap rates, and therefore mortgage rates, are likely to continue to increase, which is a headwind for housing market activity. The outlook for house prices has been quite strong in recent months, so it’s unlikely we’ll see price declines – but as mortgage rates creep up and affordability becomes more stretched, there must be some impact on housing market momentum.

Jobs growth is also expected to be weaker because of last year’s increase in employment taxes. If the current trend of weaker jobs growth continues, the BoE will be more willing to cut interest rates and bond yields will decline accordingly. A slowdown in wage growth would be particularly beneficial, as this has been the Achilles heel of the UK economy.

And beyond the UK?

There are external factors to consider here as well. If OPEC (the Organisation of the Petroleum Exporting Countries) countered the increase in U.S. oil production with a price war, inflationary concerns would ebb away quite quickly, but that doesn’t currently seem to be on the cards.

Another external factor would be a global economic slowdown.

Friday’s U.S. payroll growth figures suggest the world’s largest economy is still performing well, perhaps a bit too well. 256,000 new jobs were created during December, well above the forecast. These numbers could be revised but they indicate strength.

It was perhaps fortunate that there was little impact on wage growth, which has slowed over the last year. However, strong jobs growth raises concerns about how the labour market might react if the Trump administration is successful in taming immigration and thereby restricting labour supply.

As far as the balance of risks and opportunities is concerned, the most frequent challenge to the stock market, that of a recession, seems a distant prospect right now. Whether inflation continues to come down is increasingly in doubt.

We shall get a window into that this week, with inflation data for most major economies, including the UK and the U.S, due on Wednesday. Earnings season also begins this week. Earnings growth is expected to be strong over the next year.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

15/01/2025