Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, today’s Daily Investment Update from Brooks Macdonald which highlights the key factors currently affecting global investment markets.

What has happened?

Markets were relatively steady yesterday, with the S&P 500 (+0.28%) closing within 1% of its record high after the Federal Reserve left interest rates unchanged. European equities struggled for direction as higher energy prices added to inflation concerns, leaving the STOXX 600 (+0.07%) and FTSE 100 (+0.07%) broadly flat. Brent crude settled +1.26% higher at $115.32/bbl, although oil prices retreated overnight amid reports of renewed US-Iran outreach.

The Fed keeps its options open

The Federal Reserve kept interest rates unchanged at 3.75-4.00%, as expected, although two policymakers voted for a 25bp increase. The Fed upgraded its assessment of economic activity from “solid” to “strong”, while Chair Kevin Warsh emphasised the resilience of growth and stopped short of describing financial conditions as tight. The message was therefore one of patience rather than a clear shift away from further tightening. Markets nevertheless pared back expectations for rate rises following the press conference, contributing to a steepening of the US Treasury yield curve and some weakness in the dollar.

The Budget buys some breathing room

In the UK, Chancellor John Healey’s first Budget was comparatively measured, combining targeted support for households and businesses with tax increases and reduced near-term fiscal headroom. The OBR now expects UK growth of 1.2% this year but just 1.0% in 2027, while fiscal headroom falls to £15bn in 2029-30 before recovering to £22bn the following year. Overall, the Budget appears to have bought the government some breathing room without materially changing the longer-term fiscal challenge

Big tech faces a higher bar

Technology earnings provided a more cautious backdrop overnight. Alphabet shares fell almost -10% in after-hours trading after Google Services revenue disappointed expectations, with investors also questioning whether returns from AI investment can keep pace with rapidly rising capital expenditure. Samsung Electronics fell around -5% in Asian trading after profits in its chip business disappointed, while Microsoft provided a brighter spot, rising around +3% after cloud revenue exceeded expectations. The contrasting results have nevertheless weighed on the broader technology sector, with Nasdaq futures lower this morning.

What does Brooks Macdonald think?

Attention now turns to the ECB, which is widely expected to leave rates unchanged today, as well as another busy round of corporate earnings. More broadly, yesterday highlighted two themes likely to remain important for markets. First, resilient economic growth is being balanced against persistent inflation pressures, particularly from energy, leaving central banks with limited room to manoeuvre. Second, strong technology earnings alone may no longer be enough to satisfy investors, with greater scrutiny on whether heavy AI investment can translate into sustainable cash flows and profits.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

29th October 2026

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 27/10/2026

Is the AI boom running out of steam?

Technology stocks fell last week as rising bond yields, geopolitical concerns and higher oil prices put pressure on markets.

Key highlights

  • Is the AI bubble bursting? While AI investment has been a major driver of U.S. growth and corporate profits, investor sentiment is weakening – but doubts are focused on money rather than the machines.
  • Earnings season: With a quarter of the U.S. season done, 80% of companies have been surprisingly positive on earnings. However, some still saw shares slip as guidance was either held or trimmed.
  • UK inflation: Consumer prices rose 3.5% in the year to September, well above the 2% target, driven mainly by utility bills.

When fast is not fast enough

Amara’s Law states that we tend to overestimate the effect of a technology in the short run and underestimate the effect in the long run. It’s a paradox that’s reconciled by the idea of technological innovations tracking an S curve – slow at first, then accelerating, then levelling off.

That idea is also captured by the Gartner Hype Cycle, which begins with an innovation trigger, reaches a peak of inflated expectations, suffers a trough of disillusionment, before finding a slope of enlightenment as productivity gains eventually start to arrive.

There are clear fears that the cycle that began with the release of ChatGPT at the end of 2022 may now be approaching its peak of inflated expectations. The equity bull market has just entered its fifth year, but by age alone it isn’t especially long in the tooth. It’s younger than the median rallies we’ve seen since 1949, which tend to last about five years. Alongside these immutable cyclical fears is the secular trend of increasingly rapid technological deployment.

So, could it be possible that the Gartner Hype Cycle’s slope of enlightenment is able to arrive ahead of the trough of disillusionment? Or can disillusionment over the lack of profitability of AI chatbots be weathered by new peaks of expectations for enterprise, agentic and physical AI solutions? Going from inflated expectations to disillusionment is obviously painful but skipping that stage and getting straight to enlightenment (when technology goes from being interesting to becoming profitable) would be more benign. AI technology keeps advancing faster than most investors expected, and that’s what makes the market’s mood hard to read.

Investment in AI has become a major driver of U.S. growth and corporate profits, well beyond the technology sector itself. It’s based on leaps forward in capabilities. AI agents can now carry out multi-step business tasks on their own, and OpenAI says it has produced proof that resolves a 90-year-old mathematical problem. These aren’t incremental gains. But while the fundamentals seem positive, sentiment is weakening.

The doubts are about money rather than machines. A bullish set of earnings from Meta was badly received, probably because the firm intends to fund future capital expenditure into AI through more equity issuance. South Korea hosted its largest IPO of the year, neocloud Elice, which was nearly 400 times over-subscribed on retail demand and fell sharply on its debut.

Stock market listings have been meeting challenges with doubts over when the leading AI labs can tap the market. The cost of insuring the debt of some newer cloud computing providers has jumped, and investors are asking whether markets can absorb the sums being mooted.

So, what’s next?

We see this as a reset rather than a rupture: expectations had run ahead of even good numbers, and some companies’ spending plans, along with the prospect of issuing shares to fund them, may have unsettled investors.

Sentiment hands out labels and takes them back with little warning. A company can move from AI winner to AI loser, and back again, long before anything changes in its results. The launch of Meta’s new AI agent Muse sparked just such a scare. It hit hardest at businesses thought to depend on customer inertia, from banks to online travel platforms.

With a quarter of the U.S. earnings season gone already, the headline statistics are eerily familiar, with 80% of companies surprising positively on earnings, 50% positive on sales.

But the size of those surprises has slowed significantly so far. A good quarter is no longer enough to lift a share price; the outlook is more important, and it needs to be unequivocally good. Several companies reporting solid numbers last week saw their shares slip because guidance was either held rather than raised or trimmed in one corner of the business. When valuations rest on an expectation of steady upgrades, cautious management teams tend to be marked down, even when the caution looks sensible. That provides some opportunities to build resilience into portfolios.

The market isn’t treating every sector alike. Some previous weak spots, such as consumer staples, have caught a bid over the past month. Healthcare has been helped by an early start to the cold and flu season and by investors looking beyond the AI trade. The consumer looks resilient. How long that lasts depends partly on prices, and there the news was less comforting.

That’s why betting it all on semiconductors and AI labs isn’t the right path. There are different kinds of AI winners, and even some stocks which win despite AI, and these perform at different times too.

Source: LSEG Datastream

Stubborn costs and expensive money

Inflation is proving stubborn in the UK. Consumer prices rose 3.5% in the year to September, well above the 2% target and up from August. This was driven mainly by utility bills. The figure was slightly above forecasts, but the reaction in gilts was muted.

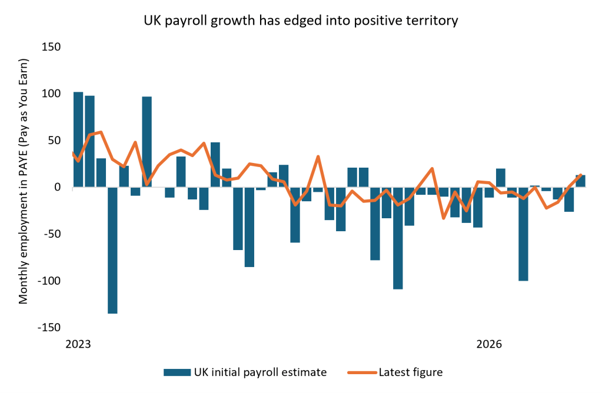
The jobs market and public finances give a mixed backdrop to this week’s Autumn Budget. Unemployment fell 0.2 percentage points in the three months to August, with around 100,000 jobs added. The early payroll figure for September was firmer than in recent months, though that measure is volatile. Borrowing came in slightly above expectations, but August’s figure was revised substantially lower.

Source: LSEG Datastream

Across the Channel, politics is setting the tone. French government bonds have been under pressure, with the extra yield over German government bonds (bunds) stretching to its widest amid uncertainty about elections in France. It has made for a testing autumn for bond investors, as our fund updates show.

Borrowing costs matter well beyond government bonds. The AI build-out is financed in capital markets, which is why the funding doubts we described earlier matter at least as much as any single earnings beat. For the story to keep rewarding investors, it has to keep paying its way in a world where money isn’t cheap.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

28/10/2026

Team No Comments

The Daily Update | Protectionism on the Rise

Please see the below article from WH Ireland discussing how the EU is seeking to protect its automotive industry as competitively priced Chinese vehicles rapidly gain European market share, while carefully avoiding trade retaliation from China, received this morning – 27/10/2026

The European Union is increasingly reacting to surging Chinese imports.  The trade deficit with China hit $404bn in 2025. Automobiles are a particularly sensitive area but an agreement to restrict the flow of Chinese hybrid vehicles into the EU to 350,000 per annum has been deemed acceptable to both parties.

Registrations of Chinese-branded cars in the third quarter of 2026 more or less doubled year on year to take a 12.7% market share. That compares to the 11.9% share of Japanese auto manufactures. The EU is walking a very fine line in trying to support its auto industry without risking trade retaliation from Beijing.

In 2021 Chinese brands accounted for just 1% of European sales while Japan’s automakers have spent decades building their position in Europe. Toyota has sold cars to the EU since the early 1960s and operates plants across the continent, while Nissan Motor Co has built vehicles at its Sunderland plant in the UK since 1986.

Chery, BYD and Geely announced a range of new models at the recent Paris car show. These are competitively priced cars and the temptation to purchase an EV over petrol or diesel, given the stubbornly high oil prices, should not be underestimated.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alexander James Roberts

27/10/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing market sentiment, AI adoption and China’s economic outlook, received this morning – 26/10/2026.

The sentiment gap

Global stocks sold off last Thursday, as AI optimism waned. Despite strong earnings, Meta’s investment plan ramp up renewed fears about unsustainable debt-fuelled growth. The timing is strange, though; underneath the noise, equity fundamentals are still improving.

The media’s AI bubble-burst narrative feels to have reached fever pitch. The question is whether that’s more about commentators catching up with market stories than anything new? Tech firms’ credit default swaps (CDS) have spiked in recent weeks, with the highly leveraged datacentre firm CoreWeave at the centre.

CDS evokes memories of the 2008/2009 Global Financial Crisis, but we’re a long way from the days of interwoven and opaque bank debts. Barclays’ Ajay Rajadhyaksha points out that even for CoreWeave itself, the distressed unsecured bonds are only a small part of its funding pile. And CoreWeave is only a small part of the AI investment boom. If the company went bust, it could knock some companies with stakes in it (Nvidia and OpenAI) but there would be no immediate domino effect.

Our usual rebuke of the AI bubble narrative is that equity valuations have fallen this year (as share prices have outpaced earnings) so it’s not a classic bubble. Now, bond yields have fallen, credit spreads (in the last week) have stayed stable and share prices have dropped. So, even on a relative basis, stocks have cheapened.

Most yields have fallen anyway; French yields broke above 5% on fiscal anxiety, and gilt traders seem to be waiting for a tough UK autumn budget to be over with, before making any moves.

Falling yields and ever-stronger earnings (Q3 is on course to beat Q2) should support shares, but investors don’t feel supported. Perhaps the scare stories – like the PHP website code vulnerability or oil above $110pb – are sapping sentiment. They heighten the sense that double-digit earnings growth can’t last. But as long as earnings keep pace – and especially if yields keep falling – we should expect sentiment to rebound eventually.

Who’s using AI?

The AI sell-off earlier this month was primarily about perceived weakness in demand growth for AI computing power. The metrics for this are opaque, so it’s worth looking at a broader picture of who’s actually using AI.

According to GenAI Adoption Tracker, 60.8% of US working-age adults used AI tools in August, up from 44.6% a year earlier but slightly down from May’s 61.8%. Reported work usage fell even more: 40.5% in August from May’s 45.2%. Short-term data is inevitably noisy, but it’s interesting how closely the adoption rate follows the so-called S-curve: a quick increase, followed by plateau or decline.

Meanwhile, 19.8% of US businesses reported using AI in May 2026, while 20% of EU companies did so in late 2025. The crude survey figures don’t distinguish between the intensities of AI usage they suggest that adoption hasn’t been as rapid as fervent optimists predicted.

What of slower demand for AI ‘compute’? The story that knocked AI stocks was a drop in the LLM Token Expenditure Index, but industry insiders pointed out that individual tokens getting cheaper doesn’t mean people are using less. The latest models use vastly more tokens, and Ramp reported that aggregate business AI spending rose 60% in the nine months to July. Still, demand looks concentrated: just 1% of firms drive 80% of OpenAI and Anthropic’s demand.

There’s some evidence that businesses are switching from the latest token-intensive models to older but sufficient models. Perhaps that’s why AI leaders are advocating a government-enforced slowdown: they cannot unilaterally slow investment for fear of falling behind, but there’s a feeling that existing models already meet many businesses’ AI needs.

Such an interpretation might be cynical but, with so much opaque data, it’s no surprise narratives are moving AI stocks more than cold hard facts.

China’s Japanification is a monetary problem

Is China undergoing ‘Japanification’? The world’s second-largest economy had decades of remarkable growth, but a busted property market and aging population have created deflation. That description of 2020s China applies word-for-word to 1990s Japan.

The comparison might sound strange given China reported 4.5% year-on-year growth in Q3 2026. But, even if you take China’s GDP numbers at face value, the economy is heavily concentrated on industrial production. Persistently weak retail sales data shows the dearth of consumer demand and price deflation hurts company profits. Beijing keeps announcing stimulus measures but, two years on from the initial stimulus pivot and with little to show for it, these measures no longer excite investors.

The struggles of Chinese companies are reflected in share prices. Price wars have kept producer prices low and profits weak. Profits are actually growing by more than stock market falls would suggest – but investors doubt the outlook. Given the government’s history of interventions (such as a recent tax clawback), that’s reasonable. There’s two layers to the problem: Does Xi Jinping’s government actually want to boost company profits and, even if it does, can Beijing’s production-led centralised economic policy model really stimulate demand?

Japan-style ‘lost decades’ aren’t inevitable but, just like Japan in the 1990s, China’s government is either unwilling or unable to boost short-term consumption and investment. The biggest spur would be getting people to borrow again, but the PBoC’s tight monetary policy disincentivises debt-led investment. Chinese bond yields are low compared to the rest of the world, but are still so much higher than expected economic returns that there’s little incentive to invest anywhere other than bonds. If the PBoC injected more liquidity, that could change. Japan learnt the same lesson much too late, when ‘Abenomics’ finally changed the monetary and fiscal landscape. There’s been suggestions that the PBoC might loosen, but we won’t hold our breath.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

26th October 2026

Team No Comments

WH Ireland – The Daily Update | The Cash Cost of Compute

23 October 2026

Please see below, today’s Daily Investment Update from WH Ireland which highlights the key factors currently affecting global investment markets.

Last week, we argued that the private economy’s response to expensive credit could eventually strengthen the case for long-dated government bonds. Washington might keep borrowing, but companies would have to adjust. The strain in AI financing offers an early test.


Artificial intelligence does not have to disappoint its customers to disappoint its creditors. Demand can keep growing while the companies building capacity run short of cash. Data centres and chips must be financed before customer payments arrive. The technology can succeed while some of the businesses supplying it struggle to repay their debts.


Thursday brought renewed pressure. High-yield credit default swap spreads widened by about nine basis points as technology shares sold off, even as government bonds attracted buyers seeking safety. This was no general seizure of credit markets. It was a reminder that investors can become more confident about owning government debt while growing less comfortable lending to companies.


AI infrastructure makes the financing problem unusually visible. Even Meta’s capital spending exceeded its operating cash generation last quarter. Its advertising business and substantial reserves provide a cushion. Smaller operators dependent on borrowed money have less freedom to wait for their investments to pay off.


Oracle has drawn on customer advances and new equity to finance its expansion. Both provide useful cash and reduce its immediate dependence on lenders. But customers paying early still expect services later. A growing order book can require more construction spending before it produces the income available to creditors.


CoreWeave provides the sharper warning. It rents out computing power used to train and run AI models, financing rapid expansion with substantial borrowing. Its unsecured bonds are yielding around 15 per cent. Investors are questioning how much protection a promising business offers when its financing needs remain so large.


Yet lenders have continued to finance particular CoreWeave projects. One secured facility achieved investment-grade ratings because it was backed by specified infrastructure and a customer contract. Its unsecured bonds remain below investment grade. The difference is the lender’s claim on assets and cash flows if something goes wrong.


That distinction matters beyond AI. A company may still obtain funding by pledging its best assets, while investors lending without those protections demand much higher returns. If more assets and revenues are committed to secured lenders, unsecured creditors must examine what remains available to support their claims.


Higher interest rates make these choices harder. Fixed-rate borrowing protects a company only until it needs to refinance. Floating-rate debt transmits the pressure sooner. Management can respond well before maturity by conserving cash, cancelling investment and slowing recruitment. Suppliers then lose orders, spreading the adjustment beyond the original borrower.


The Federal Reserve’s return to raising rates weakens the assumption that relief will arrive in time. With inflation still elevated, falling asset prices may not justify cuts. Emergency support could keep markets functioning without restoring cheap funding to companies whose debts have become unaffordable.


The cracks do not yet establish a broader high-yield crisis. They do challenge the idea that strong demand and an eventual Fed rescue are sufficient protection for creditors. Cash generation, refinancing needs and the claims of competing lenders deserve more attention than the size of an order book.


For government bond investors, the consequence may be different. Expensive credit forces private businesses to retrench, weakening demand and eventually inflation. That is how corporate distress can strengthen the case for long-dated government bonds even while public borrowing remains heavy. The highest yield and the best bond investment are often not the same thing.


Have a great weekend.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Cameron Owen

23 October 2026

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, today’s Daily Investment Update from Brooks Macdonald which highlights the key factors currently affecting global investment markets.

What has happened?

US equities extended their recent recovery yesterday, with the S&P 500 (+0.58%) posting a third consecutive gain and finishing within 1% of its record high. Technology stocks led the advance, helped by encouraging signals from the previous evening’s SpaceX earnings release, which reassured investors about the durability of AI-related spending. The Philadelphia Semiconductor Index (+1.97%) continued its rebound, while the Nasdaq (+1.05%) delivered another strong performance. The positive mood was also reflected in Europe, where the STOXX 600 (+0.92%) and other major indices moved higher, again led by tech stocks.

A more challenging backdrop for UK consumers

Yesterday’s UK inflation data came in slightly above expectations, with headline CPI rising to 3.5% in September and core inflation remaining elevated at 2.8%. Combined with this week’s strong labour market data, the figures reinforced expectations that the Bank of England will raise interest rates again in November, with markets pricing a near-certain probability of a move by yesterday’s close. At the same time, consumer confidence weakened. The latest British Retail Consortium survey showed households becoming more pessimistic about both the economic outlook and their personal finances. Although spending intentions improved as consumers looked ahead to the holiday season, the survey suggested that some households may increasingly rely on savings to support spending amid ongoing cost-of-living pressures.

The mood soured overnight

The tone became more cautious after the US close. While Meta delivered results that exceeded expectations, Tesla disappointed investors by cutting its 2026 capital expenditure target, raising questions about the pace of its ambitions in AI and robotics. As a result, futures on the Nasdaq 100 were down -1.32% this morning. Meanwhile, France’s fiscal position remained under scrutiny, with the country’s 10-year government bond yield closing above 5% for the first time since 2002. Geopolitical tensions in the Middle East also intensified overnight, adding further uncertainty. Reports of potential future strikes involving Iran, alongside continued attacks on energy infrastructure in Saudi Arabia, reinforced concerns about global energy supplies and lifted Brent crude (+1.73%) to $110.70/bbl, a five-month high.

What does Brooks Macdonald think?

The combination of persistent inflation pressures, higher-for-longer interest rate expectations and rising energy prices could create a more challenging backdrop for markets. From an investment perspective, the recent rise in oil prices warrants close attention. If sustained, higher energy costs could complicate the inflation outlook and reduce central banks’ flexibility to adjust monetary policy. For now, markets can take comfort from resilient economic growth and generally supportive corporate earnings. However, investors are likely to remain sensitive to any signs that higher energy prices begin to feed through into inflation expectations or weigh on economic activity. The key question in the months ahead will be whether the global economy can continue to absorb higher energy costs without a meaningful deterioration in growth.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Andrew Lloyd

22nd October 2026

Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 20/10/2026

Earnings season: what’s next for markets

Semiconductors are getting cheaper despite record profits – what does earnings season reveal about the road ahead?

Key highlights

  • AI trade: The semiconductor index fell by 10% as Broadcom’s chief executive questioned AI investment returns.
  • U.S. inflation: Core CPI overshot for a second month, driven by the owners’ equivalent rent category.
  • UK interest rates: Markets are pricing in one rate hike before the end of the year and three more in 2027, which strikes us as aggressive.

No crying in the casino

The biggest controversy in finance at the moment relates to the strength of the AI trade. The latest chapter in that story has centred around the longevity of the so-called ‘picks and shovels’ plays – investment strategies that target the companies providing the tools, equipment, infrastructure or services an industry needs to operate. In this case, that means semiconductors and the associated ecosystem.

AI models could establish monopolies – or they could be highly competitive.

If it’s the former, the benefits of AI will accrue to them. If it’s the latter, prices will fall and the benefits will accrue to their users. Regardless, there’ll be a lot of infrastructure built to serve these masters.

Now, there are constraints to that build-out. Political opposition to data centres has been growing due to their impact on local electricity prices. The funding available for new data centres has also been dwindling. This is due to the available cashflow of hyperscalers (large cloud computing firms) being fully deployed, and technology and consumer services becoming the second and third largest sectors in the investment-grade bond universe (and amidst the highest yielders).

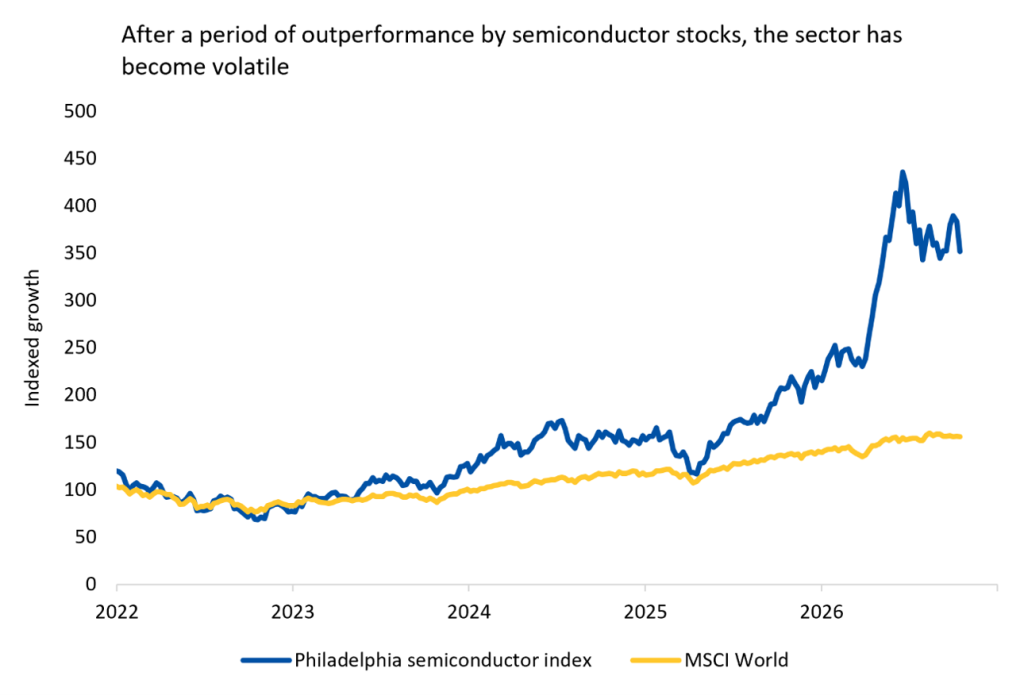
The argument about AI spending was conducted at unusual volume last week and it began with an unlikely critic. Broadcom’s Chief Executive, Hock Tan, likened some AI investment to betting in a casino, questioned whether the developers of frontier models can make money and observed that genuine productivity leaps remain scarce, while most companies are still experimenting. That’s candid talk from a business whose own order book depends on exactly that spending. As a chief executive with a track record of colourful commentary, this probably wasn’t the driver of the semiconductor correction, but the remarks certainly capture the mood.

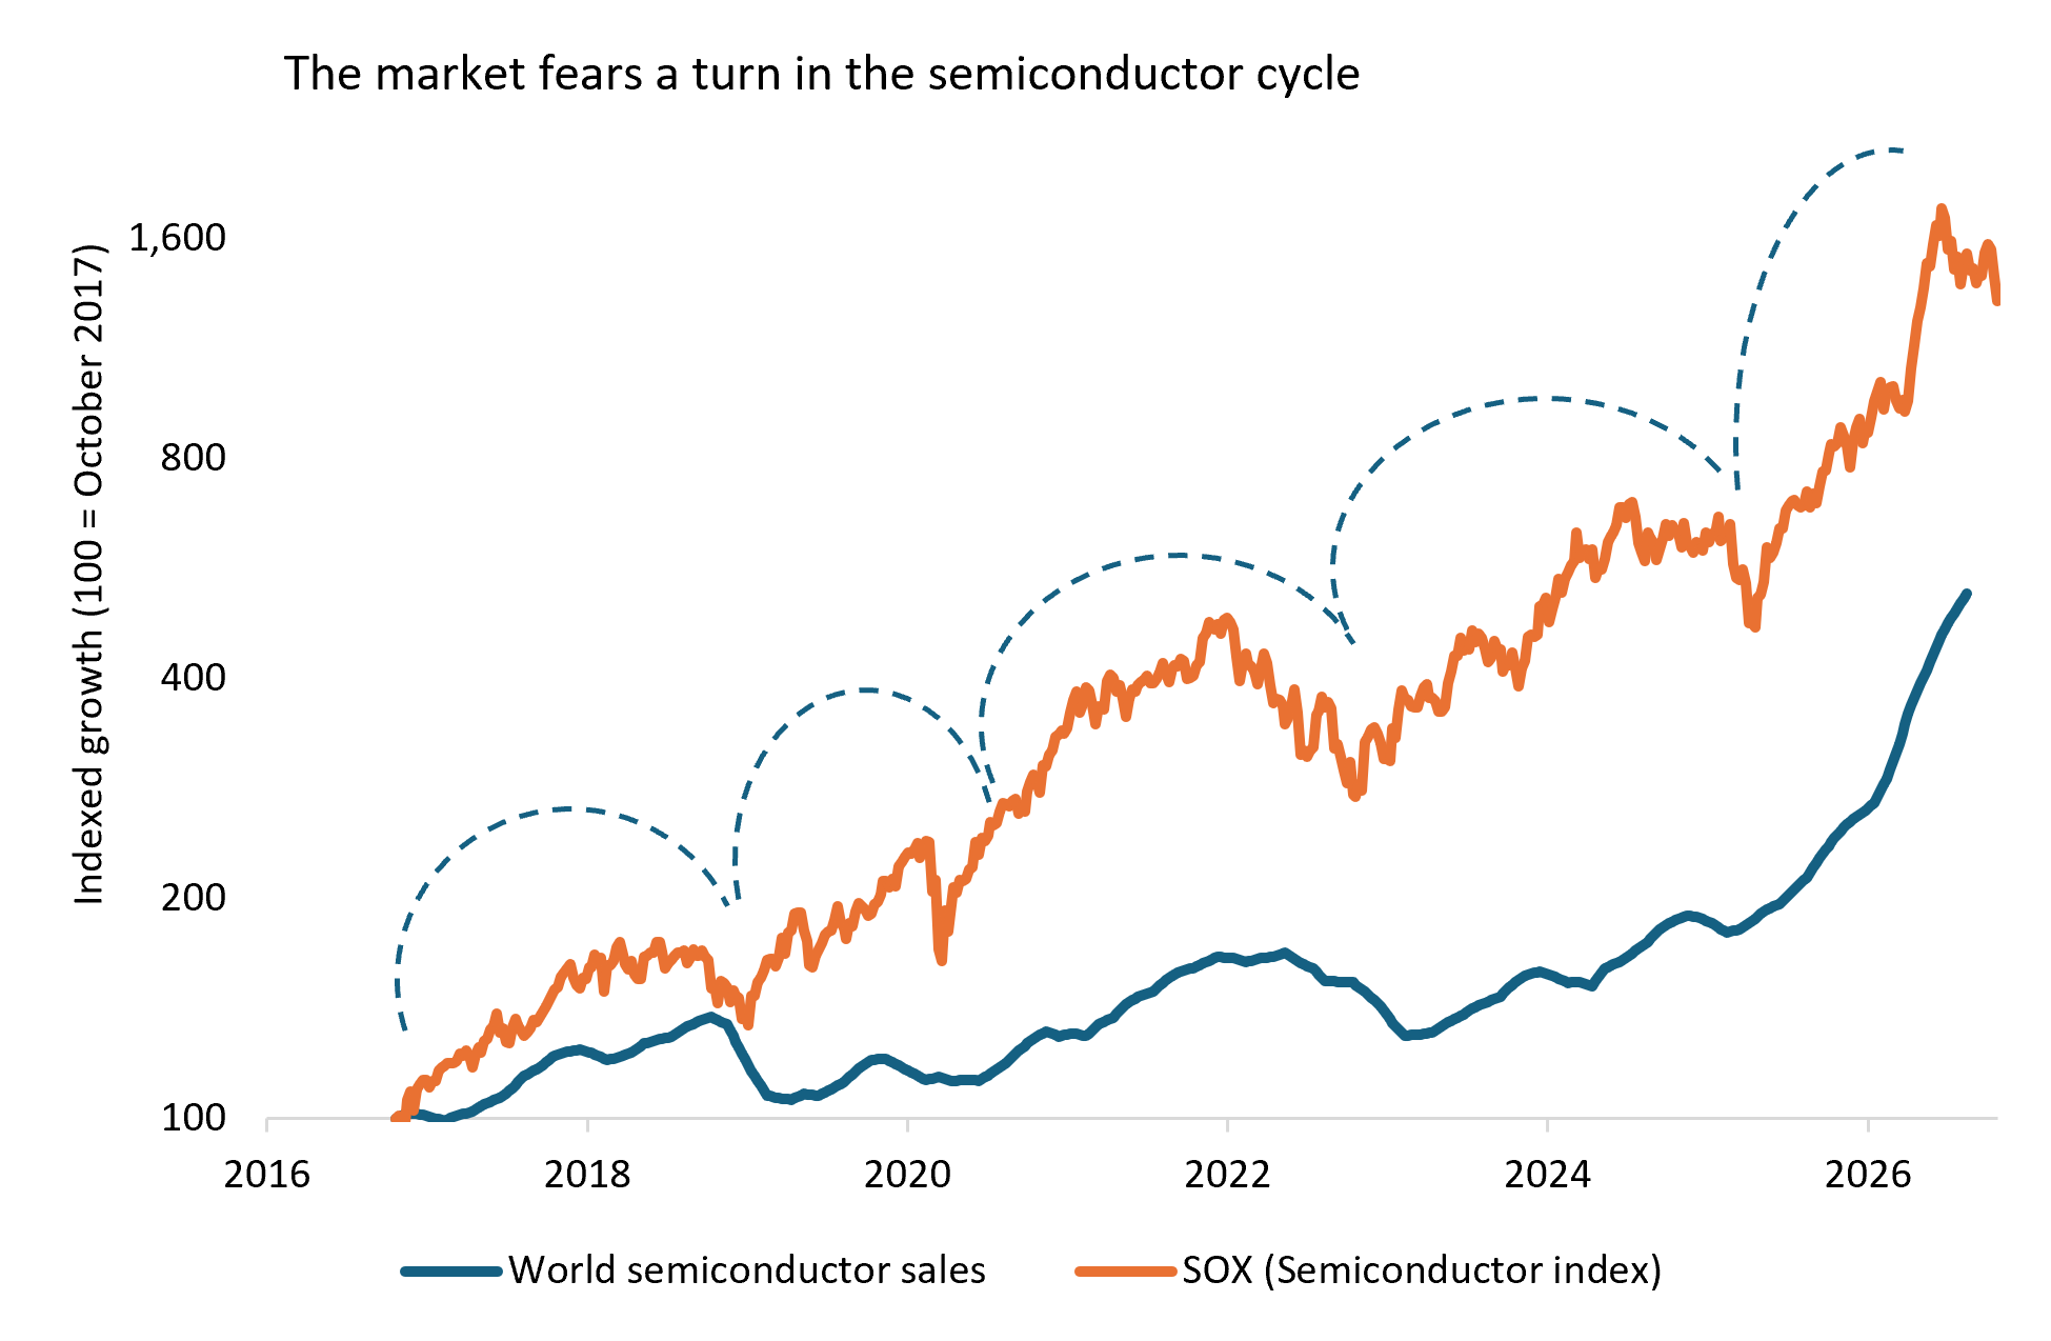
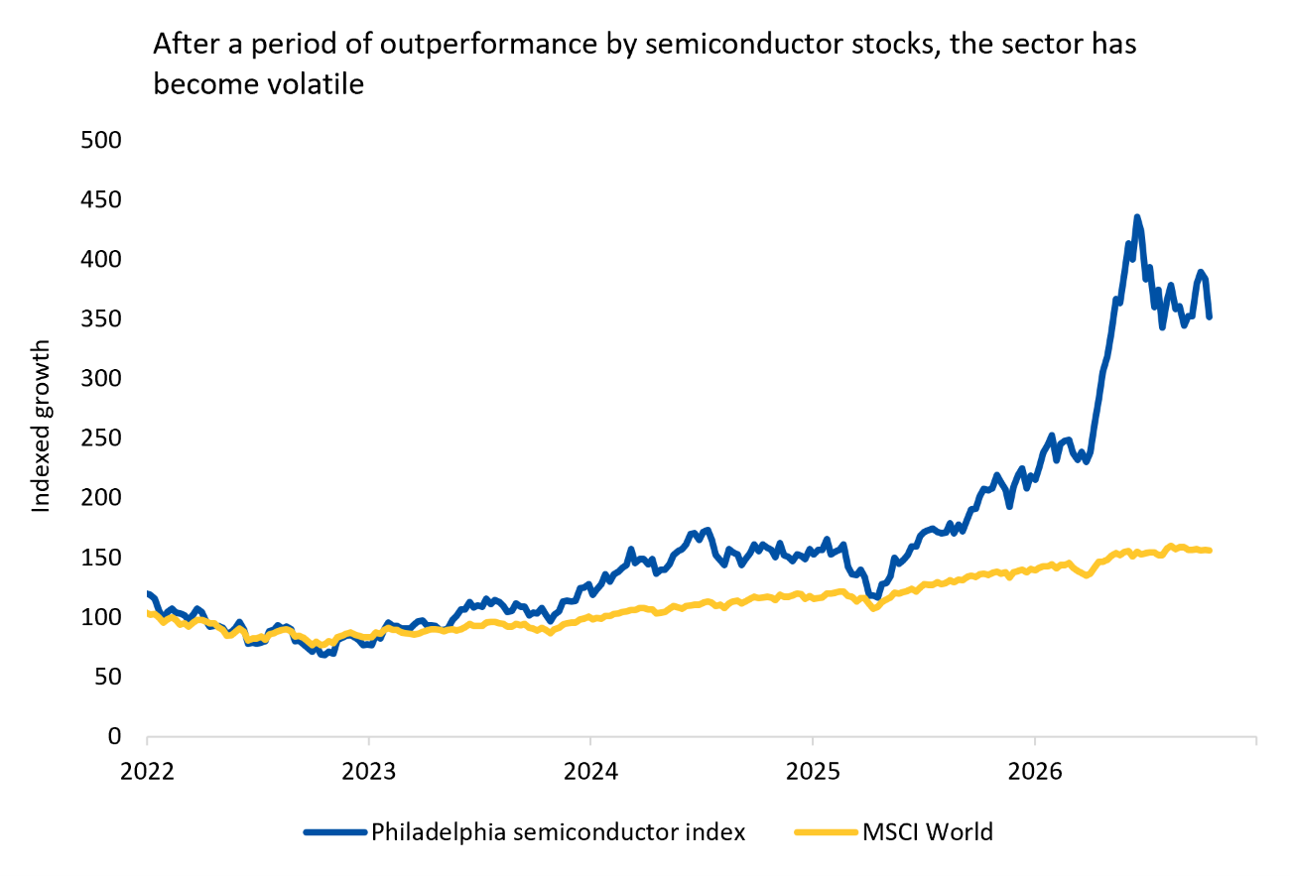
The Philadelphia Stock Exchange Semiconductor Index, the SOX index, which has become the bellwether for the theme, fell more than 10% in just over a week. Meanwhile, SK Hynix, the Korean memory giant, has fallen 30% in a fortnight.
Source: LSEG Datastream

The counterevidence came from the companies that sell the equipment and make the chips. ASML is supply-constrained rather than demand-constrained: tool supply for 2027 is unchanged and 2028 offers limited upside, which disappointed some. Yet, its installed-base business, which maintains machines and provides recurring revenue, grew 70% over the year.

TSMC raised its revenue growth guidance from 40% to 44% in dollar terms for 2026. Third-quarter revenue rose 40%, which was driven more by the richer mix of AI wafers than by volume. Capital spending of $60 billion to $64 billion looks likely to land at the upper end, with roughly 20 fabrication plants (fabs) under construction worldwide, as well as a possible new cluster in Texas. Discussions with Elon Musk’s TeraFab venture are also underway.

We’re also interested in what this implies about the shape of the cycle. Semiconductors have historically been violently cyclical, with upswings traditionally driven by a single product category – first the PC and then the smartphone. The demand base is broader now and the fabs being built today take years to arrive, which argues for a longer and smoother cycle.

TSMC has typically been conservative with capital. Its commitment speaks louder than its commentary.

So, industry fundamentals look solid and valuations have fallen, mostly by companies growing into them, but over the past couple of weeks, share price falls improved them even further.

AI’s claim on real resources is also starting to show up where investors feel it most directly: in prices.

Dwindling disinflation

Underlying U.S. price pressure is proving stubborn. Core consumer price index (CPI) data surprised to the upside for a second consecutive month, the first back-to-back overshoot since 2024, and the heavily weighted owners’ equivalent rent category did most of the work. That’s significant because new property lease rates have been rising.

High mortgage rates are keeping would-be first-time buyers in rented accommodation and high new-build costs are restricting supply. Slow net migration should limit demand, but a reliable source of disinflation has gone.

Core goods posted their biggest rise since the start of President Donald Trump’s second term and did so despite a continued large fall in prescription drug prices. This could reflect a delayed impact from tariffs or second-round effects from the rise in energy prices.

Core services excluding shelter is the better gauge of home-grown, persistent inflation, and it has been running near 3% for a year and a half. This is the indicator suggesting that underlying domestic economic strength is a source of inflationary pressure and that interest rates should rise as a result. The reassurance, though, is that wages have decelerated markedly, suggesting there’s limited benefit to weakening the labour market further.

Food prices were quiet in this month’s CPI report, but pressures are building in wholesale markets, which will find their way through to consumer markets in the coming months. A strengthening El Niño is likely to disrupt global food supply through a dispersed pattern of drought, flooding and erratic monsoons – even if it warms the European winter and marginally eases pressure on gas reserves.

The Federal Reserve (the Fed) restarted its hiking cycle last month and last week’s data makes a further increase before the year-end rather likely. Its next meeting falls less than a week before the midterm elections, which sets a high bar for acting then.

One hike, not four

Policymakers here face a gentler version of the same problem. Bank of England (BoE) Governor Andrew Bailey noted that the second-round effects of higher energy prices have been more subdued in the UK than feared, and while he remains cautious about what follows, that’s an encouraging message for now. Gilts (UK government bonds) outperformed on the back of it.

Markets treat a November rise as a near certainty and price in three more over 2027, which strikes us as aggressive. Our expectation, and that of most economists, is a single precautionary increase, one the BoE would be keen to unwind if the energy consequences of the war in the Strait of Hormuz begin to resolve.

A similar situation is true in the U.S., where Federal Reserve Chairman Kevin Warsh refused to offer forward guidance but still managed to downplay the chances of a rate hike in the last meeting before the midterms.

Steady customers, nervous shareholders

The start of earnings season offered another opportunity to check in on the banks. The sector has been weak in recent weeks and the reaction to the volley of results was mixed. Beyond that, the trends were good.
Source: LSEG Datastream

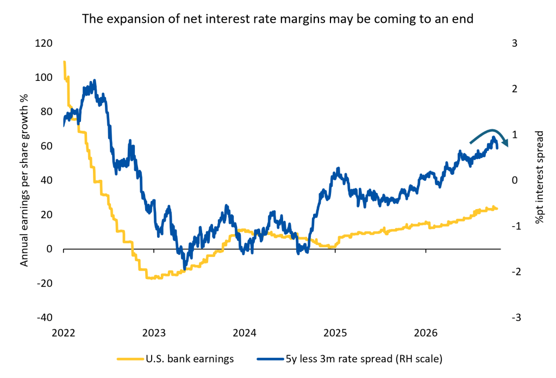
Balance sheets are growing healthily rather than recklessly, credit quality is sound and payment spending across debit and credit cards rose 5%, with no visible increase in delinquencies. The concern doesn’t appear to be deteriorating credit quality but rather net interest margins. As interest rate expectations have risen, the yield curve has flattened, making banks’ ‘borrow short and lend long’ business model less profitable.

Fixed-income trading was weaker and corporate activity merely fine, held back by the absence of the jumbo listings anticipated earlier in the year. Equities and equity financing were strong, which is usually a late-cycle signal and much of that strength sits in the prime broking businesses that fund the multi-manager hedge funds.

In other words, it’s another limb of the same AI trade now seeping into every corner of markets.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

21/10/2026
Team No Comments

WH Ireland – The Daily Update | Shelf Control

Please see the below article from WH Ireland discussing electronic shelf labels, operational efficiencies and a potential shift in pricing power, received this morning – 20/10/2026

Electronic shelf labels (ESLs) have been gaining ground in US supermarkets for several years, with Walmart rolling out the technology across thousands of stores. The trend is now gathering pace in the UK, Waitrose and Morrisons, for example, have introduced ESLs in more than 200 stores and Tesco plans to deploy them across around 3,000 locations. These small digital displays allow prices to be updated centrally within minutes, replacing the labour-intensive process of manually changing paper labels. For supermarkets operating on thin margins, the benefits include lower administrative costs, fewer pricing errors and improved inventory management. Yet beyond these operational efficiencies lies a bigger question: what happens when the cost of changing prices falls and retailers can respond to market conditions almost instantaneously?

Historically, the labour involved in replacing paper labels created a small but meaningful “menu cost”, discouraging frequent repricing. ESLs remove much of this friction, allowing retailers to respond more quickly to wholesale costs, inventory levels and competitors. This is not inherently inflationary: faster markdowns can reduce food waste, while better stock management can support profitability. Research suggests the benefits may extend beyond labour savings to improved inventory decisions and gross margins. For investors, the question is how much of these efficiency gains accrue to shareholders rather than being passed on through lower prices.

Concerns remain, however, about how the technology could be used in the future. Walmart has firmly defended its position that ESLs are an operational tool, not a means of charging different customers different prices. It maintains that all shoppers see the same instore price and that its labels do not collect personal data.

The wider concern is how ESLs could eventually interact with consumer data collected through loyalty schemes, mobile apps and online purchases. Shopping histories can reveal brand preferences, price sensitivity and how readily customers switch products or stores. Combined with sophisticated analytics and frictionless price updates, such information could, in principle, enable retailers to tailor prices or promotions to an individual’s predicted willingness to pay. The US Federal Trade Commission has raised concerns about “surveillance pricing”, including the use of personal data to personalise prices or offers. The risk is not that ESLs are necessarily tracking shoppers today, but that they could become part of a broader infrastructure in which consumer behaviour increasingly influences the price each shopper ultimately pays.

This creates an asymmetry between retailer and consumer. Supermarkets can adjust prices in minutes; households cannot switch off their need to eat. Grocery demand is relatively inelastic, and switching stores carries costs in time and convenience. Competition remains an important constraint, but consumers have limited ability to opt out.

ESLs represent both an efficiency opportunity and a potential shift in pricing power. They may improve margins without raising inflation, but they also remove friction from retail pricing while leaving the consumer’s underlying need unchanged. The retailer gains flexibility; the consumer remains bound to the basket.


Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alexander James Roberts

20/10/2026

Team No Comments

Tatton Investment Management – The Monday Digest

Please see the below article from Tatton Investment Management detailing their discussions on markets over the past week. Received this morning 19/10/2026.

Bonds cracking the AI trade

Bond yields had been climbing but then the remarkable happened last week: demand for bonds jumped, and stocks sold off. Yields at attractive levels, or waning tech optimism – which was the stronger motivation?

Meanwhile, France suffered destruction through social unrest not witnessed since 1911’s “Vie chère” or – just like today – high cost of living riots. The debate about reducing the relentless growth of the government deficit has seen disaffected urbanites being goaded into acts of violence. Over the weekend, Macron’s speech to the nation was met by a lot of political opportunism, with opposition politicians failing to seek restraint clearly. Remarkably, the Euro has remained stable and European equities are opening unchanged. Investors may be viewing the events as signalling a growing political will to deal with the debt issues, as nation heads into the Presidential election on 18th April next year.

The sharp fall in US (and other developed world) yields was, counterintuitively, prompted by surprisingly strong US inflation. The initial yield reaction was up – as you’d expect – but that rapidly reversed once investors realised that the Fed will likely raise rates this month, rather than in December. Long-term inflation expectations stayed level, but growth expectations took a hit – reflected in the fall of the real yields component of total yields.

Corporate bond yields for big tech companies went the other way, and share prices dropped. The UK was one of the few positives, buoyed by a stronger-than-expected GDP number – and the fact that some international investors (perhaps incorrectly) see the UK as a hedge against the AI trade.

The drop in tech stocks made global equities negative in aggregate. This tells us that the stocks-to-bonds shift was more about waning belief in AI’s seemingly never-ending profit growth, rather than yield attraction. Stories about slowing demand for AI ‘compute’ pushed up borrowing costs for datacentre firms – with bonds of CoreWeave – the data centre construction company – reaching distressed territory. It’s unclear how accurate the slowing compute story is, since the metrics for judging AI firms’ success are opaque. But the narrative is more important than reality in the short-term; and investors may well be looking for excuses to crystallise 2026 gains.

The dollar gave up recent gains, almost in lockstep with US real yields, reflecting waning optimism in US asset returns. Currency volatility hurts international investors and it could make foreign investors repatriate capital if it carries on. That could compound stock market volatility.

The antidote, as ever, is earnings. Q3 results already look strong and should renew faith in the AI theme. The only concern is if AI firms reveal even larger debts than investors realised. That would temper, rather than destroy, investor sentiment.

Budget suffers from the government’s own gilts

Chancellor John Healey faces a difficult Autumn budget. UK government debt is higher than it has ever been during peacetime, and the Institute for Fiscal Studies (IFS) thinks fulfilling his previous defence commitments would create a £35bn fiscal hole. Its report this week also highlighted a policy that hurts both the budget and UK bonds: the government’s accounting rules on quantitative tightening (QT).

While most central banks have stopped QT, the BoE has kept selling bonds. That’s one of the reasons gilts have underperformed other bonds. But QT doesn’t just raise the government’s debt costs by pushing up gilt yields; it also costs the treasury directly, through the way they are accounted for. The BoE’s gilts are held on a separate Asset Purchase Facility (APF), which the government indemnifies against value fluctuations. This goes both ways – gains are paid to the treasury, but losses have to be covered too. Other governments apply similar accounting terms, but the UK is unique in that losses on its own debt impact actual cashflow. It looked like a blessing during QE but now it is certainly a curse: the treasury has paid about £30bn a year since 2022.

We shouldn’t overstate the yield impact. Gilts’ main issue is structural imbalance (i.e. too many long-term and inflation-linked bonds), compounded by QT. But at least those don’t impact day-to-day spending.

You could argue the APF payments deter fiscal profligacy, but that’s a fairly weak argument. In the short-term it just makes the fiscal position worse, which increases volatility and makes international investors squeamish. Changing the policy could therefore help more than hinder gilts.

There’s no sign Chancellor Healey will change this in his budget. But with the government wanting extra spending and reluctant to cut, tax or borrow, technical adjustments like aligning gilt accounting with global standards might be all that’s left. Commentators typically scoff at such fiddling, but it can be more important than you think.

The global diesel pressure point

Nowhere is 2026’s global energy shortage more apparent than in diesel prices. Wholesale diesel has more than doubled in price since the start of the US-Iran war, and the Trump administration has made it a geopolitical priority. Why are politicians, and markets, so focussed on diesel?

Diesel didn’t use to be more expensive than regular gasoline; it was often cheaper before 2004. Environmental  requirements made it costlier to produce, while its fuel efficiency and the rapid expansion of global supply chains pushed demand steadily higher. Diesel’s role in transportation and industry made it a truly global market with a consistent premium. That premium widened after Russia invaded Ukraine, and the Strait of Hormuz crisis has destabilised it again. Demand is sticky, which is why the IEA expect prices to rise further.

Diesel’s global economic importance makes the shortage a geopolitical issue. Trump threatened to ban US exports, likely to force the EU to release emergency supplies – which it did, with the G7 agreeing to draw down 100mn barrels of crude and diesel. Trump also announced a sanction relief deal releasing 300,000 tonnes from Russia (less than a single day’s US consumption, ~530,000). The president talks tough on an export ban but it would be politically difficult: the biggest diesel consuming US states are also the biggest oil producers, so any relief a ban provides on prices, also takes away revenue from producers.

We wouldn’t count on reserve releases to fix the market. JP Morgan suggests the 100mn figure includes barrels already promised, and Europe is reluctant to release more. Reserves are designed for acute shortages, not price emergencies. The upshot is that we expect diesel to remain a pressure point for the global economy until the Strait of Hormuz blockades are lifted. Nations can’t keep releasing reserves forever.

Please continue to check our blog content for advice, planning issues and the latest investment, market and economic updates from leading investment houses.

Alex Clare

19/10/2026

Team No Comments

Brooks Macdonald: Daily Investment Bulletin

Please see below, an article from Brooks Macdonald which highlights the key factors currently affecting global investment markets. Received today – 16/10/2026

What has happened?

After a period of pressure, tech stocks found their footing yesterday as Nvidia CEO Jensen Huang publicly defended the long-term AI investment story. The improved sentiment helped the S&P 500 rise +0.33%, leaving the index within 1% of its record high. Market gains were also broader than recent sessions, with the equal-weighted S&P 500 outperforming the cap-weighted one by around one percentage point. Semiconductor stocks remained under pressure, although the Philadelphia Semiconductor Index recovered from losses of more than -4% early in the day to finish down a more modest -0.88%. The improvement in risk appetite also supported bonds, with the 10-year Treasury yield falling -12.7bps to 5.06%. Earlier in the day, European markets were relatively resilient, having been less exposed to the recent AI-related volatility. The STOXX 600 rose +0.38% for a second consecutive session, reaching its highest level in three weeks.

A resilient US economy keeps inflation concerns alive

The latest US economic data continued to paint a picture of resilient growth and persistent inflationary pressure. September retail sales rose +0.8% m-o-m, comfortably ahead of expectations, while producer prices also surprised to the upside. Headline PPI increased +1.3% m-o-m, boosted by higher energy prices, while core PPI rose +0.7%, more than double consensus forecasts. The release followed Wednesday’s firmer-than-expected core CPI reading and reinforced concerns that inflation may prove more persistent than policymakers had hoped. Although higher energy prices played a role, strength in services prices and consumer spending suggests underlying demand remains healthy.

What does Brooks Macdonald think?

Overnight, Fed Chair Kevin Warsh struck a notably constructive tone at the IMF conference. Despite a string of stronger-than-expected inflation releases this week, Warsh declined to push back against market expectations for the upcoming Federal Reserve meeting, noting that he does not “prejudge meetings” ahead of the Fed’s blackout period. Instead, his comments focused on the strength of the US economy, highlighting a substantial investment cycle and the potential productivity benefits of artificial intelligence. Markets interpreted the absence of a more hawkish message as reassuring, with expectations for an October rate rise falling materially during his remarks. While it remains too early to draw firm conclusions, markets currently appear more willing to focus on the growth opportunity than the inflation risk.

Bloomberg as at 16/10/2026.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Alex Kitteringham

16th October 2026