Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below, todays daily update article from Brooks Macdonald, received this morning – 02/09/2026:

What has happened?

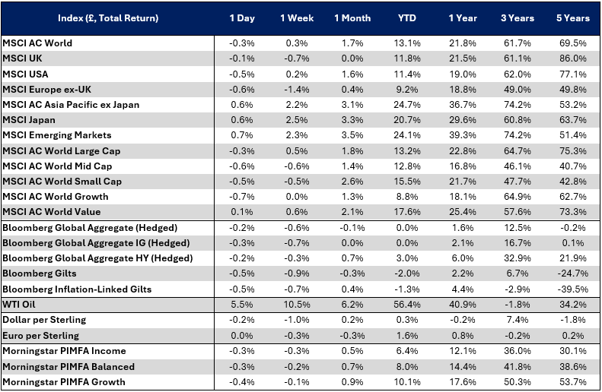
September has begun with a clear risk-off tone as escalating tensions between the US and Iran, rising energy prices and a sharp global bond sell-off weighed on investor sentiment. US air strikes on Iranian targets around the Strait of Hormuz and subsequent Iranian retaliation pushed Brent crude above $95 per barrel, reigniting concerns over inflation and global supply disruptions. At the same time, government bond yields reached multi-year highs across major markets, with UK gilts, US Treasuries and Japanese government bonds all under pressure as investors priced a greater likelihood of further central bank tightening. Equity markets declined across the US, Europe and Asia, with technology shares among the weaker performers, while attention now turns to US labour market data and Broadcom’s earnings later this week.

Markets Confront a Stagflation Shock

The standout theme is the re-emergence of stagflation concerns. Higher oil prices are arriving at a time when inflation has already proven more persistent than expected, prompting increasingly hawkish rhetoric from central banks. Markets are now pricing a much higher probability of a September Federal Reserve rate hike, while the ECB and Bank of England also face renewed pressure from energy-driven inflation risks. The combination of rising commodity prices and higher yields is challenging both equity and bond markets simultaneously, creating a difficult backdrop for traditional diversification. Unlike earlier geopolitical shocks, investors are increasingly focused on whether sustained energy price strength could delay the global easing cycle and prolong restrictive monetary policy.

Both Sides of the Yield Equation Turn Against Markets

A nominal bond yield comprises a real yield, which represents the return after expected inflation, and a breakeven inflation rate, which reflects both inflation expectations and the compensation investors demand for inflation uncertainty. Until recently, rising government bond yields had largely been driven by higher real yields, reflecting tighter policy expectations and an increase in term premia. The latest move is more concerning because both real yields and breakeven inflation rates have risen. Central banks continue to signal that policy may need to remain restrictive, while higher oil prices are adding to inflationary pressures and supply-related risk premia. The rise in breakevens suggests investors are not only pricing a higher near-term inflation path but are also demanding greater compensation for inflation risk. More importantly, it may indicate growing concerns about how quickly central banks can return inflation to target if supply shocks persist and inflation expectations become less firmly anchored. This combination increases the discount rate applied to future corporate cash flows while also threatening profit margins, consumer purchasing power and earnings growth. The result is a less favourable backdrop for equities, particularly long-duration growth stocks, and a reduction in the diversification benefits of government bonds, as inflation shocks can cause both asset classes to fall simultaneously.

What does Brooks Macdonald think?

While the geopolitical backdrop has clearly deteriorated, the market reaction reflects more than just Middle East tensions. The recent rise in yields also highlights the resilience of global growth and the reassessment of how much policy tightening may still be required to contain inflation. We believe investors should distinguish between short-term volatility and longer-term fundamentals. Strong economic activity, robust corporate earnings and structural growth themes such as AI remain important supports for risk assets, but higher oil prices and bond yields are likely to keep market volatility elevated in the near term. For now, markets appear to be transitioning from a growth-focused narrative to one increasingly dominated by inflation and policy expectations, making diversification particularly important.
Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Andrew Lloyd

02/09/2026
Team No Comments

Tatton Investment Management: Tuesday Digest

Please see the below article from Tatton Investment Management discussing the latest market outlook, including resilient growth, strong earnings, geopolitical and inflation risks, bond yields and AI-related investment, received this morning – 01/09/2026

Tantrums and other 21st century resolution mechanisms

Last week saw little movement in the main asset classes, with equities a touch higher and the dollar recouping much of last week’s losses. Bond yields rose, mostly in shorter maturities. We open this week with higher energy prices (again) following a resumption of “kinetic” war in the Gulf and another push up in yields, enough to impair equity market confidence slightly.

Kevin Warsh’s Jackson Hole address emphasised returning inflation to target with “speed”, while unwinding some of the “debasement” talk that followed Bessent’s bond market intervention last week. Investors welcomed his apparent preference for the inflation mandate over the employment mandate. Short yields ticked up on the prospect of a September hike; large caps rose while small caps, more exposed to interest costs, fell — not what President Trump wanted after “firing” Jerome Powell. Warsh said nothing on the Fed’s bond holdings; a task force’s recommendations will “come later” and won’t affect the September or November FOMC meetings.

Growth remains resilient while inflation edges back from levels that might force further hikes. Headline inflation is still elevated by the Iran conflict’s fuel price jump — in the UK, regulated energy prices rise 4% from October, softened only by a temporary VAT cut. But secondary effects are milder than feared: developed-world core inflation is now around 2.4%, a “miss” versus the 2% target no worse than the 1997-2019 average.

Given the past decade’s shocks, this resilience is remarkable. One reason: household and corporate debt has fallen substantially relative to economic size, even as government debt rose to fill the demand gap. That balance is now shifting — the private sector has stopped saving and is spending heavily on AI- and defence-related investment, a drive likely to be long-lived if bumpy. Growth keeps surprising to the upside: Germany’s Q2 GDP was revised up to 1% year-on-year, with confidence measures beating forecasts too.

So what could go wrong? Governments could lose faith in the system, try to protect weaker areas, or simply make mistakes. Bessent has promised a fiscal plan to cut the deficit and intervened in bond markets, warning of a US “Doom Loop”. Monday’s “Project Outcast” tariffs on Iran’s trading partners are not that plan — they will be smaller and, by design, less sustainable than 2025’s “Liberation Day” tariffs. The real risk is that Republicans facing the mid-terms resist the squeeze needed to make any plan work.

Elsewhere, Trump’s trade belligerence towards Canada — encouraged by Commerce Secretary Lutnick — looks resolvable despite unsettling swing-state voters on both sides of the border. Putin-aligned voices have floated “tactical nuclear” rhetoric over Ukraine, but such threats have surfaced before without escalation; brinkmanship raises both the perceived risk and the incentive to de-escalate. Geopolitics rarely moves markets as much as headlines suggest, and stated intentions rarely match outcomes.

Back to School Outlook 2026 – overview

Economic conditions remain supportive heading into autumn. Despite geopolitical noise, global growth and corporate profits have been strong in 2026, powering investment returns, and we expect that strength to continue into 2027, driven mainly by private sector investment.

Clients remain worried — about a tech bubble, an inflation surge, and UK wealth taxes. These concerns are reasonable but have persisted for most of the year without derailing markets, which have stayed resilient on the back of strong corporate profit growth.

Middle East tensions are a continuing risk to the medium-term outlook, with markets oscillating between calm and concern over oil and gas supplies through the Strait of Hormuz. Tighter supply has been offset by weaker global oil demand, particularly from China, and both sides retain strong incentives for a lasting ceasefire. Investors have grown somewhat numb to the back-and-forth, though continued disruption into winter would hurt more, especially in Europe.

Business sentiment is strong almost everywhere, with manufacturing rebounding as AI infrastructure spending offsets higher energy costs. Government and defence spending, particularly in Europe, add further support. Households — especially lower earners — remain squeezed and confidence is subdued, though employment has held up and feared AI-related job losses haven’t materialised.

Core inflation remains well contained, easing pressure on central banks to raise rates and supporting markets. AI infrastructure spending, fuelled by intense hyperscaler capital raising, should keep powering growth and earnings. But strong hyperscaler bond issuance is crowding out other borrowers, pushing up yields for lower-rated credit and government debt — a dynamic that, usefully, keeps the broader economy from overheating even as capital demand stays high.

Investment may be concentrated in a handful of large tech firms, but corporate profits are much more broadly spread and look healthy, suggesting growth is well founded and likely to continue, all else being equal.

Regional outlook summary


US

US corporate earnings remain strong, driven by AI infrastructure spending, though gains are skewed — non-tech firms face rising borrowing costs from hyperscaler demand. Consumers have stayed resilient to oil prices. Tariffs have eased, though a combative stance towards Canada may resurface ahead of midterms. Fed policy remains the bigger driver; a cut looks more likely than a hike, though Warsh’s plan to reduce central bank liquidity is a bigger risk.

UK
UK growth has surprised positively, led by strong private investment despite gloomy sentiment surveys. Valuations remain cheap versus the US, attracting private equity interest. Persistently high gilt yields — a structural issue — limit fiscal room, constraining PM Burnham’s spending plans. Contained core inflation helps, but gilts stay vulnerable to volatile international flows.

Europe
Growth expectations have eased slightly as the defence-spending boost matures, though earnings, especially banks’, have surprised positively. Low gas storage leaves Europe exposed if the Iran conflict disrupts supply into winter. Domestic politics, notably France’s 2027 election, is a bigger threat than tension with Washington.

Japan
The investment case remains strong on low labour costs and improved corporate governance, but persistent yen weakness — despite a large current account surplus — is a growing concern. Coordinated intervention has had limited lasting effect. A stronger yen could trigger self-reinforcing capital repatriation by Japanese investors.

China
China remains the outlier, with deflationary pressure from overproduction and weak consumer demand. Fiscal policy has tightened rather than eased, hurting profits. Late-August hints of easing offer hope, though seasonal spending patterns may explain much of it. US trade tensions add risk ahead of midterms.

Emerging Markets
EM equity performance has been dominated by AI-linked chip stocks (TSMC, Samsung, SK Hynix), masking weakness in China and India. Broader EM performance hinges on easing energy prices and a genuine Chinese policy pivot.

Asset classes


Equities

Strong corporate earnings should keep supporting stock prices into next year, with margins especially strong in US tech names driving the AI buildout. Earnings growth has outpaced share prices for AI firms this year, so valuations have fallen despite healthy returns — arguing against a classic bubble, even if some gains (like Amazon’s and Alphabet’s from AI investment stakes) look somewhat circular. Fundamentals remain strong, and downside looks limited while that continues.

One risk is currency volatility: growing foreign ownership of equities means exchange-rate swings could raise perceived risk and prompt selling, though we see this as unlikely.

The bigger risk is bonds. Historically high real yields make equities look less attractive by comparison — valuations aren’t cheap once adjusted for that. Capital hasn’t yet rotated out of stocks, as holders remain entrenched, but rising yields could change that. The equity outlook ultimately hinges on the bond outlook.

Bonds
Shorter-dated yields broadly match the medium-term growth and inflation outlook, but longer-dated yields have risen further than expected. Investors are effectively paid more than the economy’s likely return just for holding government debt, even as growth stays decent and inflation falls.

The problem is capital demand: indebted governments compete with AI firms racing to raise debt, and supply keeps outrunning demand. Yields likely won’t fall until investment returns drop below borrowing costs.

The UK is a concern, but France and the US worry us more — both have high debt and rising deficits with little will to fix them, risking a vicious fiscal-premium cycle. Bond vigilantes could emerge anywhere given ample supply; a US “Liz Truss moment” would hit markets harder than the UK’s in 2022.

That isn’t our base case — selling bonds amid falling inflation looks unattractive. The outlook stays mixed, with pockets of attractive return for diversified portfolios.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

1st September 2026

Team No Comments

Can Mr Burnham boost UK growth?

Please see below an article from WH Ireland, received this week, discussing the new Burnham government’s policy agenda and its potential impact on UK economic growth, housing, defence, taxation and public sector reform.

The new government led by Mr Burnham has raised Labour’s poll ratings a little and has revived media interest in what changes it might put through. Both the voters and the markets are keen to see if the new team will make a difference to the growth rate and will find ways to boost living standards. There was general disappointment with the tax rises, the increase in unemployment and the often sluggish growth under the Starmer administration, which led to higher long-term interest rates and a fall in housebuilding.

Mr Burnham has been flexible in his views over his political career. He has been a loyal Blairite as a Minister, a supporter of the party when Jememy Corbyn won the leadership, then developing his own approach as Mayor of Greater Manchester.

He has provided us with more up to date evidence of his views in speeches to win the Makerfield by election and in his subsequent talks as Prime Minister. He told his electors that he would apply a Makerfield test to everything he and the government do. This test is to bring fairness to places Whitehall has neglected.  He set out five principles of “unity, honest politics, distinctively Labour direction, all place government and devolution of power from Whitehall.”

He has said “We will make this moment a circuit breaker for Britain, bringing forward the biggest changes in the last forty years”.  He proposes a new political and economic model to be defined, and a 10 Year Plan to be drafted.  “In the 1980s Britain took some wrong turns. Political power was centralised, economic power privatised, large parts of the country de-industrialised, and they still haven’t recovered”. He wishes to “carry power to every postcode in the land”. He wants “to put life’s essentials back under stronger public control”.

Burham plans to “re industrialise Britain, using public procurement to back British industry”; to build more Council houses, refusing to revise down the very stretching 1.5 m new homes target for this Parliament. He promised to “honour our commitments on defence to our international partners”, “to meet our fiscal rules” and “to end rough sleeping”. A new National care service has been mooted, with a caveat for further study and cross party involvement. Previous governments have tried to get a consensus on social care reform without success. It would be expensive with Reform and the Conservatives ruling out a dedicated tax.

He has backed a “duty of candour” in public life after criticising the failure of the Establishment to tell the truth about the Hillsborough disaster in 1989.He has promised to be “relentless” in tackling illegal migration, whilst also saying he wants more to enter by safe routes. He often sounds as if he is campaigning against Margaret Thatcher, a Prime Minister in office four decades ago.

Increased defence spending with the promise of more work for UK factories and shipyards is part of the Growth plan which he inherited. The PM has been careful not to commit to large additional spending on defence this Parliament. The Chancellor, John Healey, resigned from the last government because he judged the budget increase in defence to be insufficient to defend the country and to meet NATO commitments. Both men agree that defence buying should be used to provide more orders and jobs for businesses to be based in the UK, though there were always more permissive rules for defence spending to allow more home content.

They have highlighted the work at UK shipyards already underway to provide new ships and new submarines for the navy.

The last government agreed to increase defence spending to 2.7% of GDP by 2027/8 and to keep it there until 2030. Mr Healey wanted more rapid progress to 3% by 2030 requiring £13 bn more. The 3.5% NATO target for 2035 would be achieved by a successor government nearer the target date.

The extra spending of £15bn put into budgets relies on £10.3bn of cuts in other departments, £1bn of identified savings in the Ministry of Defence budget and a further £3.7bn of unidentified MOD cuts. There remain big issues to be agreed between PM and Chancellor before the budget.

Housing too was an important component of the inherited Growth plan.

The 1.5m target for new homes 2024-9 looks unachievable. In the first two years they have witnessed the construction of under half the number of homes needed to hit this rate. The PM’s idea of more Council homes probably means more social homes, as directly financed Council houses will be part of public spending subject to the budgets and decisions of local Councils. The aim will more likely be to get the Housing Associations to raise private finance to let them build and rent out more.

The government has stated a spend of £39 bn over ten years to 2036 without yet translating that into specified annual budgets. With subsidy on a socially rented home in London extending to £170,000 per unit, around £4bn a year will not add sufficient to achieve a target of 300,000 new homes in total each year.  There is both a financial and a building industry capacity constraint on how many more homes can be built. Private sector housebuilding for sale which is usually the dominant part of residential construction is limited by dear mortgages, high prices and low levels of confidence amongst potential homebuyers. The pressures on the UK government bond market keeps the interest rates for mortgages relatively high.

Further tax rises would be unhelpful, as it is widely observed that the increases in National Insurance and IHT under the last government reduced employment and hit small businesses and family farms. The PM has promised to observe the Manifesto by avoiding Income tax, National Insurance and VAT hikes on working people as he seeks more money to spend. It is difficult to see he has any scope to raise Income tax thresholds for which he has shown some support, and which would increase spending power for employees. There may well be other tax rises, with rumours about capital gains tax which could be unhelpful to business growth.

The government wish to spend more of its cash on buying British needs to tackle three issues to bring this about. The first is the need to obey international trade rules. The second is that the UK has missing capacity in various cases making it difficult to find suppliers who can deliver what is needed. The third is the state is often a bad customer, as we see in MOD procurement with large cost overruns and cancellations of expensive programmes, with the customer often changing their mind over what is wanted. This can lead to excessive public spending and more pressure on interest rates.

The government may be able to impose a so called ” social weighting” under World Trade rules on contract bids and has already said it will do so. This means that it can consider the benefits in tax and social outcomes of having more of the work done at home. This needs to be proportionate, and foreign companies must be free to bid with carve outs in their proposal for some additional UK based work.

All governments claim they will learn the lessons of bad procurement, visible in the Post office computer, NHS computerisation, the Ajax armoured vehicle and others. Mistakes have so far continued.

Mr Burnham wants to reverse some privatisations, seeing nationalised businesses as a source of growth he can direct. Labour inherited the policy of full rail nationalisation from the outgoing Conservative government. Labour in office from 1997 nationalised the track, signals and stations of the railways, forming state owned Network Rail. They are now adding the train operating companies as their licences expire.  They have a target of increasing rail freight substantially, but it is unlikely there will be much extra growth from a nationalised railway.

Labour decided to intervene to take operating responsibility for British Steel (Scunthorpe) over a year ago. They have just completed its nationalisation. The business owns two very old blast furnaces, is losing £1.3 m a day and is considering an expensive plan to build a replacement electric arc works. It would then shut down the blast furnaces and shed a substantial amount of the workforce. Meanwhile, because the Government did not reach agreement with the Chinese owners in the first place, they now face a claim for £1 bn of compensation for a heavily loss-making business with many liabilities. The Steel Plan when it emerges is likely to mean fewer employees and little or no net additional steelmaking capacity.

The nationalised Post office runs the counters businesses we see on some High Streets. It has been losing around £500m a year, now disguised by payment of a large grant. The Post office does not yet have a convincing growth plan.

The government would like to privatise water, but the costs of buying out the current owners who in some cases include UK pension funds and small savers would be very high. Thames Water which has got into serious financial difficulty could be put into administration if they cannot sort out their refinancing. This might provide an opportunity for state ownership but given the size of Thames and the need for major investment in new pipes, new reservoirs and treatment works it would be a big increase to   the public spending figures. There are inherited plans to build more reservoirs, but these are all proceeding very slowly to letting contracts to build.

Growth will largely be determined by the success of the private sector economy. As yet, there are no new policies that could get interest rates or taxes down to provide more stimulus. It is true the Burnham opinion poll bounce may help with confidence. The PM needs to avoid plunging the country into weeks of fears of new and higher taxes in the run up the budget which hit confidence and activity under the previous Chancellor.

The government will struggle to find a way to hit their housing targets which was scored favourably for growth when first devised. Increases in defence over and above the £15bn accepted by the last PM will be modest, with the main increases put off into the next Parliament. There is limited scope to get more defence work done in the UK given industrial weakness and the substantial use of UK main contractors already for much of the programme.

The government is likely to give the much delayed go ahead to the Jackdaw and maybe Rosebank fields in the North Sea but will not unleash more activity by licencing more drilling for prospects. This will give a small boost to UK GDP. General de industrialisation which has been proceeding rapidly in recent years thanks to very high energy prices is likely to continue in the absence of big moves to cut energy taxes and renewable subsidies. Government spending will increase a little. More effort will be made to direct public investment into infrastructure, energy and water but it will prove difficult as these large projects are very delayed by UK planning and regulation.

It is doubtful that Mr Burnham will pull off the large revolution he envisages over his first year in office. As he wants growth to be public sector led and to be spread into every postcode he will find there are many delays and obstacles in the way of getting things done which have frustrated previous governments. Tax cuts on enterprise, investment and savings do not seem to be part of his thinking, and substantially lower energy taxes and prices seem ruled out. These might be more helpful in boosting growth.

While  the’ jury is out’, there are some positives in that UK services will continue to grow, and services trade remains a UK strength. Inflation should stay under reasonable control as money and credit are not excessive and wage increases in the private sector relatively restrained. Where there is less time to reflect is in an attractively valued UK stock market, quite cheap by international standards, which is, as a result, attracting a significant number of bids for important companies. Others are moving their listings to the US seeking a higher rating. The engine for Mr Burnham’s growth plans is under duress.


Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Alexander James Roberts

28/08/2026


Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 25/08/2026.

Are governments engineering bond demand?

Discover why debt keeps climbing, but the political will to cut has gone.

Key highlights

  • Washington and the yield curve: The U.S. Treasury doubling its buybacks of outstanding debt adds evidence of financial repression.
  • UK inflation rises: UK inflation data for July came in at an annual rate of 2.9% on Wednesday. The first rise in four months suggests inflationary pressures remain.
  • Bank of England to hold interest rates: Decidedly mixed economic data out of the UK has left markets expecting the Bank of England to hold interest rates at its September meeting.

Is Washington quietly taking control of the yield curve?

Source: LSEG

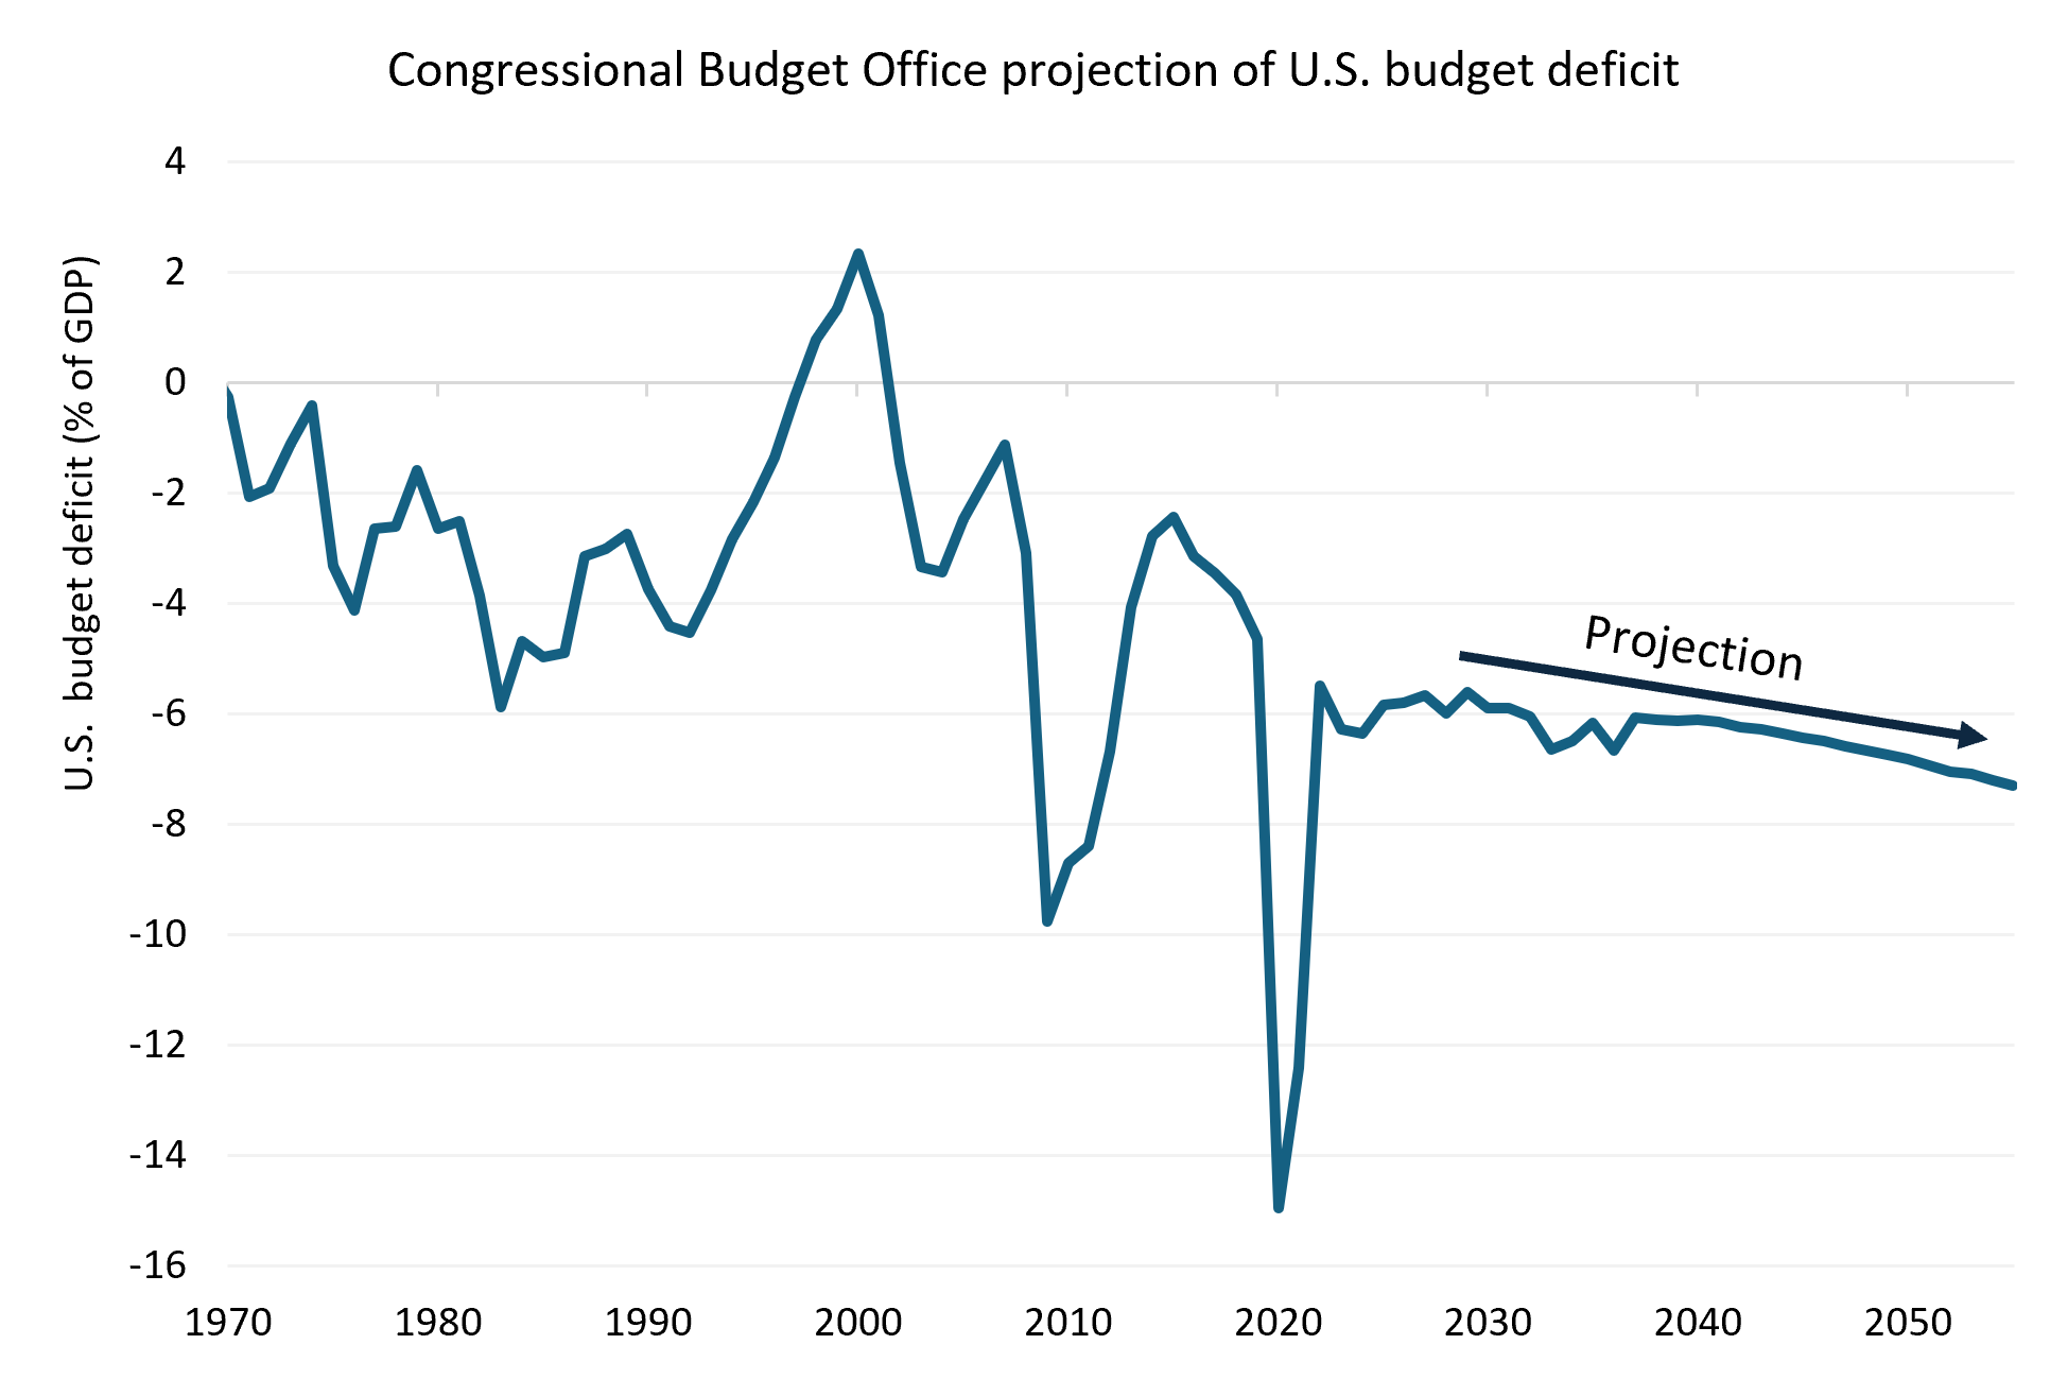
A recurring concern for investors during extraordinary periods of expansion has been the sustainability of debt. How can the good times continue when the debt-to-GDP (gross domestic product) ratio keeps increasing and with it the share of tax revenue being spent on interest payments alone?

The maths is straightforward, if uncomfortable. The most obvious way a government can improve its debt position is by cutting spending or raising taxes, but these are both politically thankless, whether you lean left or right. And while there was a brief period following the Great Financial Crisis in which fiscal repair was not completely rejected by voters, those halcyon days have passed.

For example, my colleague Atul Bhatia from our U.S. fixed income team describes U.S. policymakers as “one-way Keynesians” – they ramp up spending during economic shocks (such as a global pandemic), but neglect to run a corresponding budgetary surplus during better times.

If spending cuts and tax rises are politically untouchable, the only remaining route to lowering debt is by widening the gap between growth and borrowing costs. An optimistic scenario is that an AI miracle results in high growth and lowers inflation and therefore interest rates, allowing countries to outgrow their debt. While this is possible, it’s but one possibility. A particularly vigorous AI revolution could, for example, result in lower employment and higher benefits payments, which would have quite a different impact on public finances.

What does seem likely though, partly because it’s already happening, is that governments can achieve the same result with nominal growth (which includes inflation) rather than real growth. It’s quite customary for nominal growth to exceed interest rates, allowing countries to either pay down debt or, more commonly, run fiscal deficits. Widening that gap would give policymakers more palatable options.

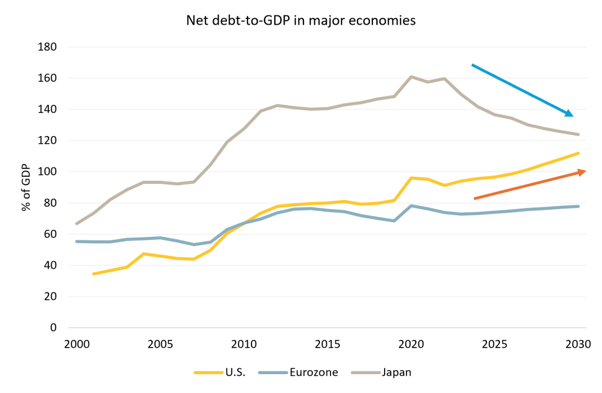
To see this in action, Japan – the most indebted major economy in the world – has trimmed its debt-to-GDP ratio since 2020 by precisely this route: inflation has risen faster than interest rates even as the country continued to run a budget deficit.

Source: LSEG

With that in mind, U.S. Secretary to the Treasury, Scott Bessent, confirmed it would at least double its buybacks of outstanding 10-year to 30-year debt, lifting operations from $2 billion to $4 billion. That saw a rally in the bond market. It was short-lived, but the buybacks announced won’t start until September, so this doesn’t mean it’s been futile.

When long-dated Treasury bond buybacks first began under former Secretary to the Treasury, Janet Yellen in 2024, ostensibly to manage liquidity, they were considered controversial by some. But last week’s events seem to connect the policy to the management of bond yields (interest rates).

It comes shortly after the U.S. sold euros to buy yen to spare Japan from selling its U.S. Treasury holdings. Demand for Treasuries is also being supported in other ways, such as making it easier for banks to hold them and potentially creating demand as collateral for stablecoins.

Now it seems possible to join the dots and see steps being taken towards a regime in which above-target inflation is tolerated and low interest rates are targeted to ease the servicing, or even reduction, of debt. Over the long term, this creates opportunities in the form of a steeper yield curve. This would weigh on the dollar relative to less repressive currencies and would highlight the attractions of real assets with limited supply, such as gold.

The implication for portfolios is one we’ve been building towards for some time. If governments lean on inflation to manage their debts, longer-dated bonds look vulnerable – there’s overwhelming pressure to cap yields, but little natural limit on how much debt can be issued. Assets, whose supply is genuinely constrained (gold being chief among them), become more appealing by contrast. Last week’s news doesn’t change our thinking so much as confirm it.

UK ‘stagflationary’ pressure remains

Source: LSEG

Closer to home, UK inflation data for July came in at an annual rate of 2.9%. It’s the first rise in four months and a touch above expectations on the core measure.

These figures were the first to reflect higher household utility bills due to the U.S.-Iran conflict and because of the lagged impact of the regulatory price cap. Fortunately, that landed during a month when fuel costs fell.

Beneath the surface, the signals are mixed: services inflation eased to 3.4%, but that was largely airfares and the Bank of England’s (BoE) preferred underlying measure – the Consumer Price Index – actually rose to an annualised 2.9% in July, up from 2.6% in June.

Another way of gauging underlying pressure is the median category price change, which reached its highest level since mid-2025, suggesting inflationary pressure remains.

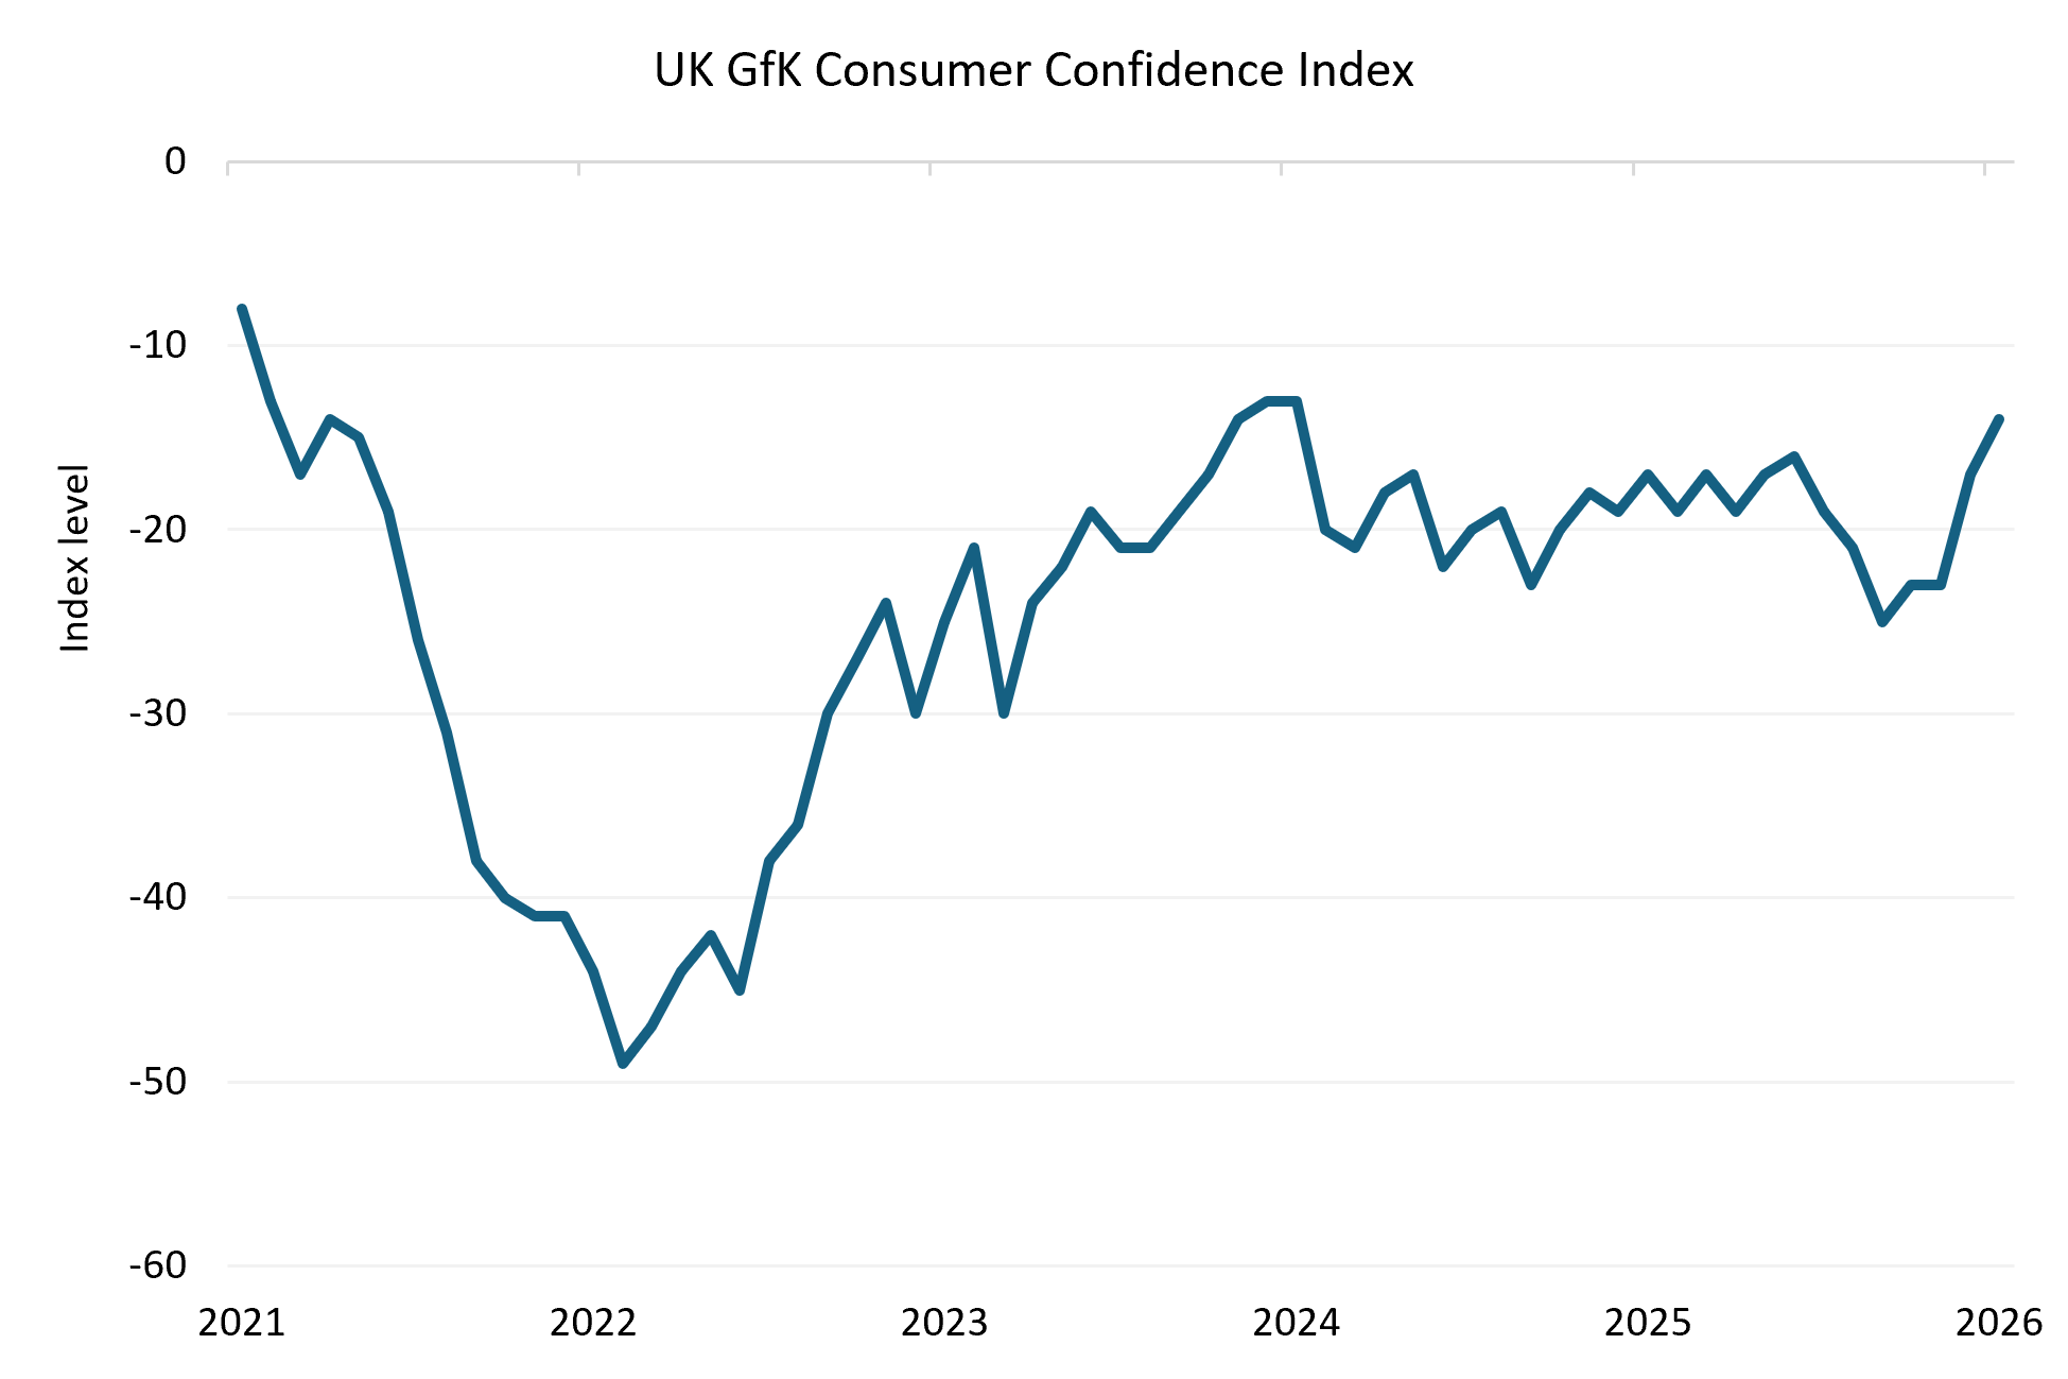
Despite this, there’s definitely a better mood in the UK at the moment, which seems to have coincided with new Prime Minister Andy Burnham having a more optimistic tone. Consumer confidence rebounded to its highest since 2024 – notably, the strongest reading under the current government. Yet retail sales slipped slightly, flattered only by a World Cup boost to food and drink. Public finances continued to show how difficult the new chancellor’s job will be ahead of October’s budget.

Employment data released last week told a similar tale of tension: payrolls fell for a second month, and vacancies hit a five-year low, yet wage growth held firm at 3.5%. That awkward combination – slack in jobs, stickiness in pay – has left markets expecting the BoE to hold interest rates at its next meeting in September.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

26/08/2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, suggesting that markets were cautious as rising energy costs and trade tensions continued to create uncertainty for investors, received this morning – 25/08/2026

What has happened?

Markets began the final week of August on a cautious footing. US equities moved lower as semiconductor stocks remained under pressure ahead of Nvidia’s results, with the S&P 500 and Nasdaq retreating while broader market performance was more resilient. Bond markets found support as Brent crude fell back from last week’s sharp gains after the US outlined further pressure on Iran but stopped short of announcing major new measures. Treasury yields moved lower, although European bond markets were less responsive as natural gas prices rose to their highest level since early 2023 amid concerns over low European storage levels. Trade tensions also remained in focus after the US announced higher tariffs on Canadian automotive imports.


Trade wars and energy risks re-emerge

The key theme remains the interaction between energy prices, inflation expectations and interest rates. While oil prices eased yesterday, European natural gas prices continued to rise, highlighting that energy supply risks have not disappeared. European gas storage levels are currently at their lowest seasonal level since the data series began in 2009, raising concerns about energy availability heading into winter. At the same time, ongoing tensions involving Iran and continued disruption to grain exports from the Black Sea region underline how geopolitical developments can quickly feed through to commodity markets and inflation expectations. These pressures are being closely watched by central banks, with markets continuing to price further policy tightening in several regions.


What does Brooks Macdonald think?

Recent market moves reinforce the view that investors remain highly sensitive to any developments that could influence inflation, growth expectations and bond yields. The decline in oil prices provided short-term relief for fixed income markets, but higher natural gas prices and broader commodity uncertainty suggest inflation risks have not fully faded. At the same time, the breakdown in US-Canada trade talks serves as a reminder that tariffs and trade disputes remain an important market risk, with the potential to weigh on growth while adding to price pressures. Against this backdrop, semiconductor weakness shows that highly valued growth sectors continue to face scrutiny as investors assess whether earnings can justify elevated expectations. We remain constructive on the economic backdrop, with markets to be driven by the balance between resilient growth, inflation risks and policy uncertainty in the short term.


Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Alexander James Roberts

25/08/2026

Team No Comments

Tatton Investment Management: Monday Digest

Please see the below article from Tatton Investment Management discussing the renewed influence of bond markets, rising long-dated government yields, fiscal discipline returning to focus in the US and UK, and the rapid growth of China’s Unitree Robotics — received this morning – 24/08/2026.

The might of the bond markets returns

We start the week in a quiet frame despite Friday’s resumption of a US-Canada trade war. Last week, the underlying narratives were largely unchanged: strong tech earnings and simmering energy fears. However, for the first time this summer, the seasonally low trading liquidity and its role in the rise in government bond yields became a real issue for wider markets.

Government bond yields finally reached levels too high for equity investors to ignore, moving higher on Monday and Tuesday despite tame inflation data – probably because reduced summer liquidity limited the market’s ability to absorb supportive news. Global 10-year yields reached a new post-pandemic high, close to a 20-year peak; the global average real yield is now essentially at 2%. Equities sold off broadly from Monday, most sharply in the US and Japan; Europe held up better.

The US Treasury was less sanguine than bond traders. Scott Bessent announced on Wednesday that the US would at least double buybacks in the 10-to-30-year range, to at least $74bn from the $38bn programme flagged two weeks earlier. Yields fell 0.12% initially, before rising back 0.06% on Thursday; equities bounced. The dollar weakened against most currencies – a move which may prove more persistent than others. Coupled with rising gold and a surging Bitcoin, it suggests the seasonal summer liquidity drought may be ending.

Trump backed this intervention although his suggestion that the next bout may involve the military was perhaps not entirely thought through.

Had this been purely about bond liquidity, the implications might be ephemeral. But on Thursday Bessent told CNBC of “an increased focus on fiscal consolidation,” tasked by President Trump alongside Budget Director Russ Vought. His original “3-3-3” pledge – 3% growth, 3 million extra barrels of oil, a 3% deficit – has landed two out of three: the deficit has failed, never below 5%, with US debt passing $40 trillion this week.

Republicans seeking election in the mid-terms are likely to welcome a big focus on deficit reduction, especially if it delivers lower mortgage rates – the 30-year is back above 6.75% – given a housing market that has been dire since 2022.

For the UK, June’s positive balance data was followed by a disappointing £1.8bn monthly deficit, despite buoyant July receipts. Fiscal discipline is back in fashion in the West, though falling US yields should pull UK yields down too. Flash PMIs stayed expansionary, and consumer confidence improved.

Next week brings Nvidia’s results and the Fed’s Jackson Hole symposium of global central bankers, where balance sheet signals will be watched.

What’s gone wrong with bond yields?

Since the start of the year, yields of longer-maturity bonds have risen sharply – and not just in the UK. This summer has seen the developed world aggregate at levels not seen in 25 years.

What is driving this move?

Many commentators point to rising government deficits, corporate borrowing to fund AI investment, and inflation concerns coupled with less Federal Reserve guidance.

For example:

On August 18th, Jonas Goltermann of Capital Economics told Reuters: “Bond yields’ recent surge suggests investors are losing patience with fiscal profligacy.”

But there is no consensus on the most decisive driver. We think the shift has less to do with increased risk than with how bond investors and issuers are behaving as buyers and sellers this year.

Bond yields split into inflation expectations, a real “risk-free” return, credit risk, and a term premium – compensation for locking into a long- rather than short-term rate.

The inflation component has moved little (outside Japan), arguably vindicating Fed Chair Warsh’s inflation-fighting stance.

Fiscal concerns, measured against risk-free swap rates, rose 0.4-0.8% between 2022 and 2025, but are barely changed this year despite deficits still rising – a worry, but no worse than other components.

Where moves have been significant is in inflation-adjusted “real” yields, especially in Japan.
We note that substantial issuance of AI infrastructure bonds by hyperscalers is affecting supply and demand. Bloomberg reports investment-grade companies have sold nearly $1.5 trillion of bonds this year, a 36% jump, with big tech borrowing alone equivalent to 25% of the Treasury’s net issuance.

That keeps equity investors positive on profit growth, so few are swapping equities for bonds, despite the most tempting yields this millennium. The bond investor cohort is therefore static at best, with Chinese investors increasingly favouring domestic bonds over foreign ones.

Japanese bond holders are now suffering what Western holders endured four years ago, with the term premium at highs there and rising in the US too, as fewer long-bond investors face rising issuance – leaving more sellers than buyers and stressing liquidity.

Scott Bessent’s aforementioned announcement that the Treasury would increase its buying of long-maturity Treasuries, was therefore as notable as it was unusual, given its main job is issuing them.

Investors currently happy holding equities may need convincing that bonds are worth having again. But some of the illiquidity may be seasonal, with buyers tending to return as autumn begins.

Unitree: The $50 Billion Robot

On Wednesday last week, a ten-year-old company from China’s Hangzhou that makes robot dogs and dancing humanoids became one of the most valuable robotics businesses on earth. Unitree Robotics listed about 10% of itself on Shanghai’s STAR Market, valuing it at about $9bn – double its original target.

Demand was remarkable: 9.78m subscribers cut the retail allocation rate to 1 in 5,500. Shares closed the first day at CNY 845, up 460%, with a market cap above $50bn – one of the most oversubscribed IPOs in STAR Market history.

Unitree was founded in 2016 by Wang Xingxing, then 26, and grew in Hangzhou, the tech hub that also produced Alibaba and DeepSeek.

It sells robot components as well as complete quadruped and humanoid robots, claiming over 60% of the global quadruped market, with humanoids undercutting Western rivals’ pricing by an order of magnitude.

DeepSeek has taken a stake to collaborate on foundation models and “embodied AI” – the field on which Tesla’s valuation, via Optimus, increasingly rests too.

Unusually for an early tech company, Unitree is profitable: on the back of revenues of CNY 1.699bn last year, it generated a net profit of CNY 278m, through gross margins of near 60%.

China’s state is deeply invested – several state-owned enterprises hold stakes, and the company enjoys tax incentives under China’s SME support scheme.

Security concerns have followed it abroad: flaws have let robots transmit data to Chinese servers, prompting the Pentagon to add Unitree to its Chinese military companies list and the FCC to block new equipment approvals.

Britain and Europe favour a lighter, context-based approach – restricting use in policing, defence and infrastructure rather than banning Unitree outright – while European demand outstrips supply. The result is a bifurcating market: a protected domestic base plus Europe and the Global South, against a shrinking US position.

Unitree has proven humanoid robots can be built cheaply and profitably, but margins may be harder to hold: it is not even the biggest producer by volume across robot categories – that is AgiBot, with over 43% of global shipments in H1 2026 (according to Counterpoint Research), with rivals like Dexmal and Chery’s AiMOGA also emerging.

What remains open is whether they can be deployed usefully at scale — and how much of the world will be permitted to buy them.

Please continue to check our blog content for the latest advice and planning issues from leading investment management firms.

Marcus Blenkinsop

24th August 2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, received this morning – 21/08/2026:

What has happened?

Global bond markets came under renewed pressure yesterday as Wednesday’s rally, triggered by the US Treasury’s plans to expand its buyback operations, quickly faded. US 10-year Treasury yields rose +5.8bps to 4.71%, while a further rise in oil prices added to inflation concerns. Brent crude climbed +2.4% to $93.78/bbl, extending its winning streak to five sessions. The combination of higher yields and rising energy prices weighed on sentiment, with the S&P 500 falling -0.9%, its largest decline of August so far. European markets also softened. French 10-year government bond yields reached a fresh post-2008 high, while UK gilt yields moved higher following stronger-than-expected CBI survey data. Equity performance was mixed, with modest declines across most major continental European indices, while the FTSE 100 edged slightly higher.


Markets seek reassurance but yields edged higher

Treasury yields rose despite efforts from US Treasury Secretary Scott Bessent to reassure markets. Speaking to CNBC, Bessent suggested that Treasury buybacks could be expanded and said policymakers still had a broad toolkit to support market functioning. He also indicated that greater emphasis would soon be placed on fiscal consolidation, although few details were provided. Despite some stabilisation later in the day, Treasury yields ultimately reversed most of Wednesday’s decline.


Oil surge fuels inflation concerns

Geopolitical tensions in the Middle East remained a key market focus, helping to push Brent crude above $93/bbl. The move higher in oil prices drove a sharp rise in inflation expectations, with the US one-year inflation swap recording its largest daily increase since March. Markets consequently nudged up expectations for further Federal Reserve tightening this year. Comments from St. Louis Fed President Musalem also reinforced the view that inflation remains elevated and that underlying demand pressures persist.


What does Brooks Macdonald think?

Importantly, yesterday’s economic data offered little evidence that higher yields are beginning to meaningfully slow the US economy. The Philadelphia Fed Business Outlook rose to its strongest level since 2021, while the survey’s capital expenditure expectations reached levels not seen for decades. Initial jobless claims also remained low, pointing to a labour market that continues to show resilience. Taken together, the combination of firm growth data, a stable labour market and rising energy prices helps explain why bond markets remain reluctant to price in a more benign inflation outlook.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Cherise Lancaster

21/08/2026

Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, suggesting that markets recovered after the US Treasury unexpectedly announced an increase in its buyback operations, while investors remain cautious about the longer-term inflation outlook, received this morning – 20/08/2026

What has happened?

Markets recovered yesterday, led by a sharp rally in long-dated US government bonds after the US Treasury unexpectedly announced an increase in its buyback operations. The move pushed the 30-year Treasury yield down 9.2bps to 5.19%, marking its largest daily decline since June. Equities also benefited, with the S&P 500 rising +0.21%. Healthcare stocks outperformed after Moderna (+176.97%) and Merck (+12.60%) reported positive skin cancer vaccine trial results, although weakness in semiconductor shares continued to weigh on broader gains, with the Philadelphia Semiconductor Index falling -2.12%. Elsewhere, gold rose +4.18%, its strongest gain since March, while Brent crude climbed for a fourth consecutive session to $91.62/bbl.


A signal of support for long-term bonds

The Treasury announcement dominated market attention. Officials said they would at least double the size of buyback operations for longer-dated Treasuries, covering maturities from 10 to 30 years, beginning on 9 September. Although the increase is small relative to the overall Treasury market, it surprised investors given that the Treasury had published its provisional buyback schedule only two weeks earlier. More importantly, it signalled a willingness to support the long end of the market after 30-year Treasury yields reached their highest level since 2007 earlier this week. The result was a strong rally in longer-dated bonds and a notable flattening of the yield curve.


Fed minutes offer little urgency

Investors also reviewed the Fed’s July meeting minutes, which showed that “many participants” believed further tightening could be needed if inflation remained elevated. However, the language stopped short of signalling an imminent rate hike. As a result, expectations for further tightening eased slightly, with 2-year Treasury yields ending the session 0.8bps lower at 4.16%. The move was modest compared with the larger rally in longer-dated bonds.


What does Brooks Macdonald think?

The Treasury’s intervention provided immediate relief for long-dated bond markets, but it does not fundamentally change the underlying backdrop of resilient inflation pressures, elevated energy prices and large government borrowing requirements. The reaction across asset classes was particularly telling. While bond yields fell sharply, gold prices rallied strongly, suggesting investors remain cautious about the longer-term inflation outlook. At the same time, the modest decline in expectations for further Fed tightening indicates markets are becoming more confident, even if central banks remain reluctant to declare victory over inflation.


Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Alexander James Roberts

20/08/2026


Team No Comments

Brewin Dolphin – Markets in a Minute

Please see this week’s Markets in a Minute update below from Brewin Dolphin, received yesterday afternoon – 18/08/2026.

What’s driving U.S. stock record highs?

Discover why U.S. stocks continue to outperform despite ongoing tensions in the Middle East and softened economic data.

Key highlights

  • Cooling data provides breathing room: Signs of slower economic momentum reduced pressure on the Federal Reserve to immediately raise interest rates.
  • Markets are learning to live with geopolitical risk: Despite continuous tension between the U.S. and Iran and disruption to The Strait of Hormuz, the S&P 500 reached fresh highs.
  • Strong profits are supporting the bull market: An exceptional U.S. earnings season and growing evidence of AI monetisation are helping broaden the equity rally beyond a handful of technology leaders.

Cooling data, hotter market

U.S. data gave markets something close to a Goldilocks combination last week. U.S. inflation cooled following weaker jobs data, but there is still little evidence of a broader downturn.

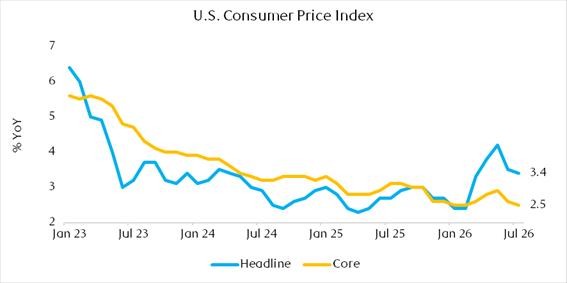
The July headline Consumer Price Index (CPI) rose just 0.1% over the month, taking annual inflation down to 3.4% from 3.5%. More importantly, core inflation rose 0.2%, with the annual rate easing to 2.5%. This was reassuring after surging oil prices raised fears that inflation could reaccelerate.

Source: Bloomberg

There were some yellow flags beneath the surface. Core goods prices accelerated and services inflation also remains sticky.

But producer prices provided relief. The headline Producer Price Index (PPI) was unchanged in July, contradicting expectations for an increase, while the annual rate slowed to 4.7% from 5.5%. This suggests the pipeline inflation pressure is weaker than feared.

Taken together, CPI and PPI have reduced the urgency for the Federal Reserve (the Fed) to immediately raise interest rates again.

This comes after last week’s surprisingly weak jobs report, which showed the U.S. economy lost 23,000 jobs in July. Retail sales also contracted in July, which provided another important test of consumer momentum.

Interestingly, markets currently seem comfortable with a little weakness in U.S. data as investors still see resilience rather than recession.

That distinction is important. The broader economy remains resilient and crucially, corporate profits are exceptionally strong. Some moderation in employment and consumer spending can be helpful for markets if it takes pressure off the Fed.

Markets sharply reduced the probability of a September rate hike following the inflation data, although an increase later this year remains possible.

For equities, that is a relatively favourable combination: growth is cooling enough to give the Fed room to wait, but not enough to derail corporate profits.

However, oil continues to be the obvious challenge to this Goldilocks scenario.

Markets learn to live with Hormuz

Developments surrounding the Strait of Hormuz remain one of the biggest macro risks facing markets given the unprecedented supply shock, but investors have become noticeably less reactive to each new headline.

The conflict remains unresolved and the Strait continues to face severe disruption. The U.S. has intensified its threats towards Iran, while Washington is preparing what Treasury Secretary Scott Bessent has described as “unprecedented additional economic measures” against Tehran.

President Donald Trump has alternated between a more conciliatory tone and renewed threats of pressure, creating occasional flare-ups in oil prices. Brent crude oil has nevertheless remained around the high-$80s per barrel, well below its earlier wartime peaks.

A renewed surge in oil would of course be a concern. It could push inflation higher again and potentially force the Fed back towards tightening.

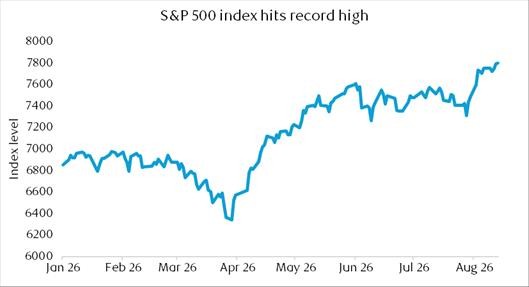
Despite this uncertainty, the S&P 500 reached record highs.

Source: Bloomberg

There is an element of geopolitical fatigue here. After months of U.S.-Iran tensions, markets are becoming more immune to individual headlines. Unless an escalation materially changes the outlook for energy supply, inflation or economic growth, investors appear increasingly willing to look through it.

Ultimately, fundamentals matter more. And right now, those fundamentals remain supportive.

Earnings give the bull market firmer foundations

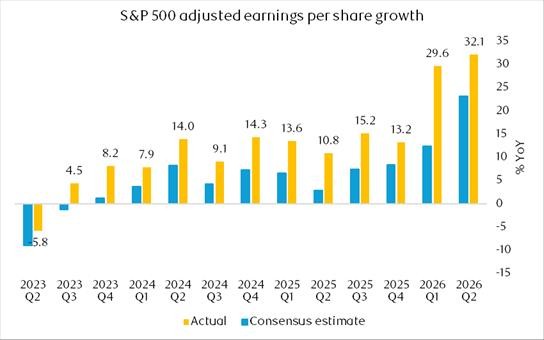
The second-quarter U.S. earnings season has been extraordinary.

With almost 90% of the S&P 500 having reported by the end of last week, blended earnings growth stood at 50.4% year-on-year. That headline earnings growth number is inflated by hyperscalers’ investment gains from SpaceX, Anthropic and Open AI. Adjusting for those exceptional items that are not related to underlying business operations, S&P 500 earnings growth was still around 32%.

The strength of corporate America is not simply an accounting effect or an AI story.

Source: Bloomberg

At the same time, we are seeing more evidence that enormous investment in AI is translating into revenue and profit. Cloud demand specifically tied to AI has boomed, semiconductor earnings have surged and AI-related infrastructure spending continues to feed through the broader economy.

Perhaps even more encouraging is the broadening of the rally. Technology remains a major earnings engine, but profit growth is becoming less concentrated. That gives the bull market a healthier foundation than one driven purely by a handful of mega-cap stocks and rising valuations.

There are still risks. Expectations for AI are extremely high, valuations leave less room for disappointment, capital expenditure continues to rise rapidly, and free cash flow from hyperscalers have deteriorated.

But for now, the combination of strong earnings, improving AI monetisation and broader participation in profit growth gives investors a fundamental reason to remain constructive.

That also explains why markets have been able to absorb softer economic data and persistent geopolitical uncertainty. The macro backdrop may be cooling, but corporate America is not.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Charlotte Clarke

19/08/2026


Team No Comments

Brooks Macdonald – The Daily Investment Update

Please see below the daily update article from Brooks Macdonald, received this morning – 18/08/2026:

What has happened?

With little sign of a breakthrough between the US and Iran, investors increasingly priced in a prolonged disruption to oil supplies through the Strait of Hormuz. As a result, Brent crude oil rose +2.65% to close above $90/bbl for the first time in two weeks. The rise in oil prices weighed on risk assets on both sides of the Atlantic, as investors considered the potential inflationary impact of higher energy costs. The S&P 500 fell -0.52%, marking its weakest session of August so far, although a rebound in semiconductor stocks helped limit the decline, with the Philadelphia Semiconductor Index gaining +1.64%. Market weakness was broad-based, with the equal-weighted S&P 500 falling -0.92%, its largest decline in more than a month. European markets closed before the sell-off fully gathered pace, but the STOXX 600 still fell -0.22%, extending its losing streak to four consecutive sessions.

Markets brace for a longer standoff

Yesterday’s headlines suggested that both sides remain far apart from an agreement. President Trump said he had no interest in extending the 60-day memorandum of understanding agreed in June, while also reiterating that he was in no hurry to secure a deal. Although Trump referenced a potential back channel with members of Iran’s Revolutionary Guard, Iranian officials rejected the claim, stating that no talks were taking place. Comments from US Energy Secretary Chris Wright also pointed to a patient approach, with the administration focused on playing the “long game” with Iran.

What does Brooks Macdonald think?

Markets are responding not just to higher oil prices, but to what they could mean for inflation and interest rates. A sustained period of elevated energy costs would make it harder for inflation to continue moderating, potentially turning central banks more hawkish. This helps explain why bond markets also came under pressure yesterday, particularly at the longer end of the yield curve. 30-year government bond yields reached multi-year highs across several major markets, reflecting not only higher inflationary pressure but also lingering concerns over fiscal sustainability.

Please continue to check our blog content for advice, planning issues and the latest investment market and economic updates from leading investment houses.

Andrew Lloyd

18/08/2026